
 Bamboo Panels Market | 2026-2036
Bamboo Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Bamboo Panels Market Insights
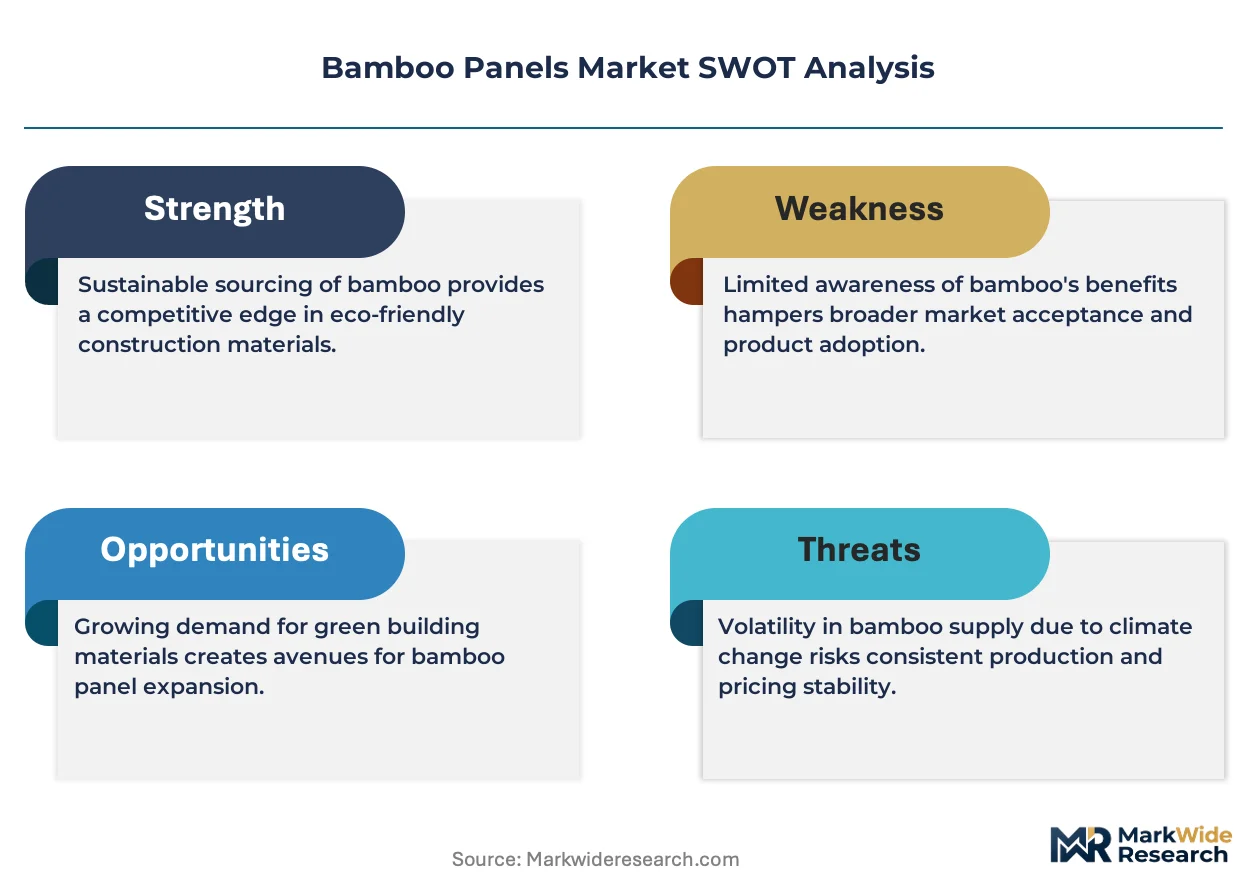
Skilled bamboo laminators and adhesive specialists is reorganizing output capacity across Southeast Asian mills. Moso International B.V. leverages its European distribution network to supply certified panels for commercial interiors. Smith & Fong Co., Inc. sustains a North American foothold through FSC-certified product lines. Cali Bamboo, Inc. differentiates via direct-to-contractor channels that bypass traditional lumber yards.
Bamboo panels are engineered or solid-pressed sheet materials manufactured from moso or guadua bamboo culms, typically bonded with phenol-formaldehyde or isocyanate resins under heat and pressure to achieve density ratings between 0.6 and 1.1 g/cm³. These panels serve structural and decorative functions where dimensional stability, rapid renewability, and carbon sequestration credentials outweigh conventional hardwood or steel alternatives. Laminated panels dominate value capture in furniture manufacturing due to their uniform grain appearance and machinability on CNC routers. Engineered panels are gaining share in construction frameworks where cross-laminated configurations meet seismic load requirements. Decorative veneers occupy a premium niche among exhibition designers seeking lightweight, visually distinctive surfacing.
China's SAMR enforces GB standards that limit formaldehyde release in bamboo-based panels bound for residential applications. The EU Green Deal and REACH compliance obligations restrict certain adhesive chemistries imported into European markets, redirecting procurement toward low-emission European producers. Indonesia's national standards body mandates SNI certification for structural bamboo products used in government-backed housing programs. Stakeholders must track evolving bio-based adhesive certifications and regional procurement preferences for mass-timber-compatible bamboo systems.
Market Dynamics
China's GB standards for formaldehyde emissions are forcing adhesive reformulation across Southeast Asian mills, compressing margins for phenol-formaldehyde dependent producers while creating certification premiums for low-emission alternatives.
Growth Catalysts
- EU Green Deal compliance obligations:REACH restrictions on certain adhesive chemistries redirect European procurement toward certified low-emission bamboo panel producers, tightening supply access for compliant mills.
- Mid-rise residential construction:Developers in Vietnam and Indonesia specify cross-laminated bamboo for seismic frameworks in government-backed housing programs.
- Carbon sequestration credentials:Lifecycle assessment protocols favor bamboo's rapid renewability over tropical hardwoods in furniture manufacturing specifications.
Market Restraints
- Phenol-formaldehyde cost volatility:Petrochemical feedstock fluctuations compress margins for mills without backward integration into adhesive production.
- Supply concentration in China:Moso culm processing dominates Anhui and Sichuan provinces, creating single-source vulnerability for European distributors.
- Steel substitution in structural frames:Engineered timber and mass timber systems compete for the same mid-rise construction specifications.
Strategic Opportunities
- Indonesia's SNI certification mandate:Government-backed housing programs create captive demand for structurally certified bamboo panel suppliers.
- Direct-to-contractor channels:Bypassing traditional lumber yards captures margin compression currently absorbed by distribution intermediaries.
- Isocyanate-bio-based hybrid adhesives:Convergence of low-emission chemistry with structural performance opens premium positioning against conventional phenolic systems.
Industry Challenges
- Skilled laminator scarcity:Bamboo-specific adhesive application and press calibration expertise concentrates in aging workforces across Vietnamese and Chinese mills.
- FSC-GB dual certification timelines:Parallel forest stewardship and Chinese national standard compliance extends product launch cycles by months.
- CNC machinability standardization:Inconsistent density ratings between 0.6 and 1.1 g/cm³ complicate automated furniture production workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bamboo Panels Market |
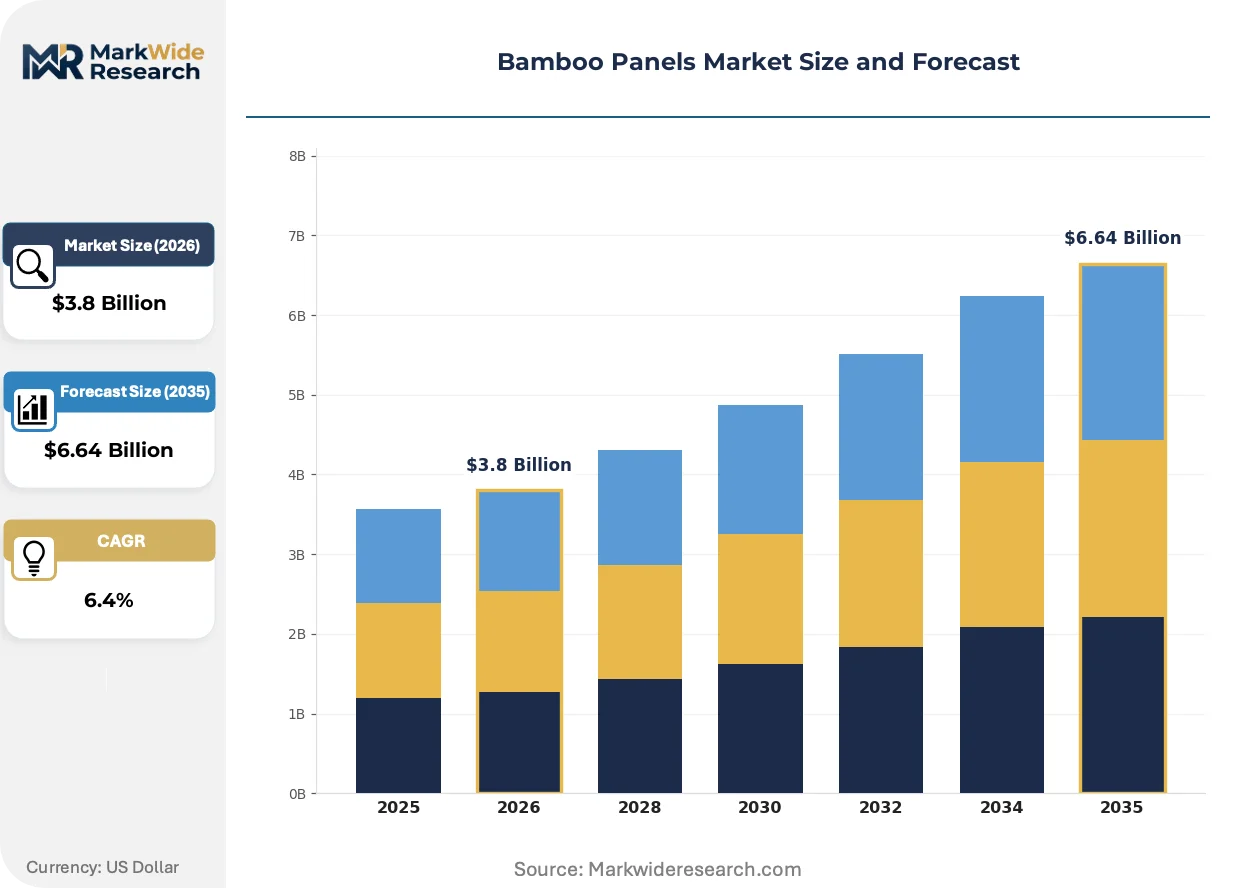
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panels, Laminated Panels, Engineered Panels, Solid Panels, Decorative Veneers Application: Furniture Manufacturing, Interior Wall Cladding, Flooring Solutions, Construction Frameworks, Packaging Materials End User: Residential Developers, Commercial Builders, Furniture Artisans, Packaging Manufacturers, Exhibition Designers Distribution Channel: Direct Sales, Wholesale Distributors, Online Retailers, Specialty Lumber Stores, Trade Shows |
| Companies Covered | Cali Bamboo, Inc., Bamboo Australia Pty Ltd., Smith & Fong Co., Inc., Zhejiang Yongyu Bamboo, Anji Tianzhen Bamboo Flooring, Moso International B.V., Teragren LLC, Xiamen Yusheng Bamboo Products Co., Ltd., Dasso Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bamboo Panels Market Trends and Innovations
Adhesive chemistry innovation and procurement channel restructuring are compressing traditional value chain positions while creating new certification premiums.
Cross-laminated bamboo configurations are decomposing the structural steel dominance in mid-rise seismic frameworks. Japanese developers specify these panels for five-to-twelve story residential projects, compressing installation timelines versus conventional concrete forming. The technology is decomposing established procurement relationships between general contractors and steel fabricators.
China's SAMR enforces progressively stricter GB formaldehyde emission thresholds for residential-bound panels. Mills serving European markets face divergent compliance obligations against REACH adhesive restrictions, forcing dual-formulation production lines. Vietnamese exporters absorb the highest certification burden as they simultaneously satisfy EU Green Deal procurement preferences and domestic SNI structural mandates.
Contractors in North American commercial interiors now specify certified panels directly, disintermediating traditional lumber yard distribution. This channel compression rewards mills with in-house logistics and specification support capabilities. The shift concentrates in California and Pacific Northwest markets where green building codes drive material transparency requirements.
Bamboo Panels Market Segmentation
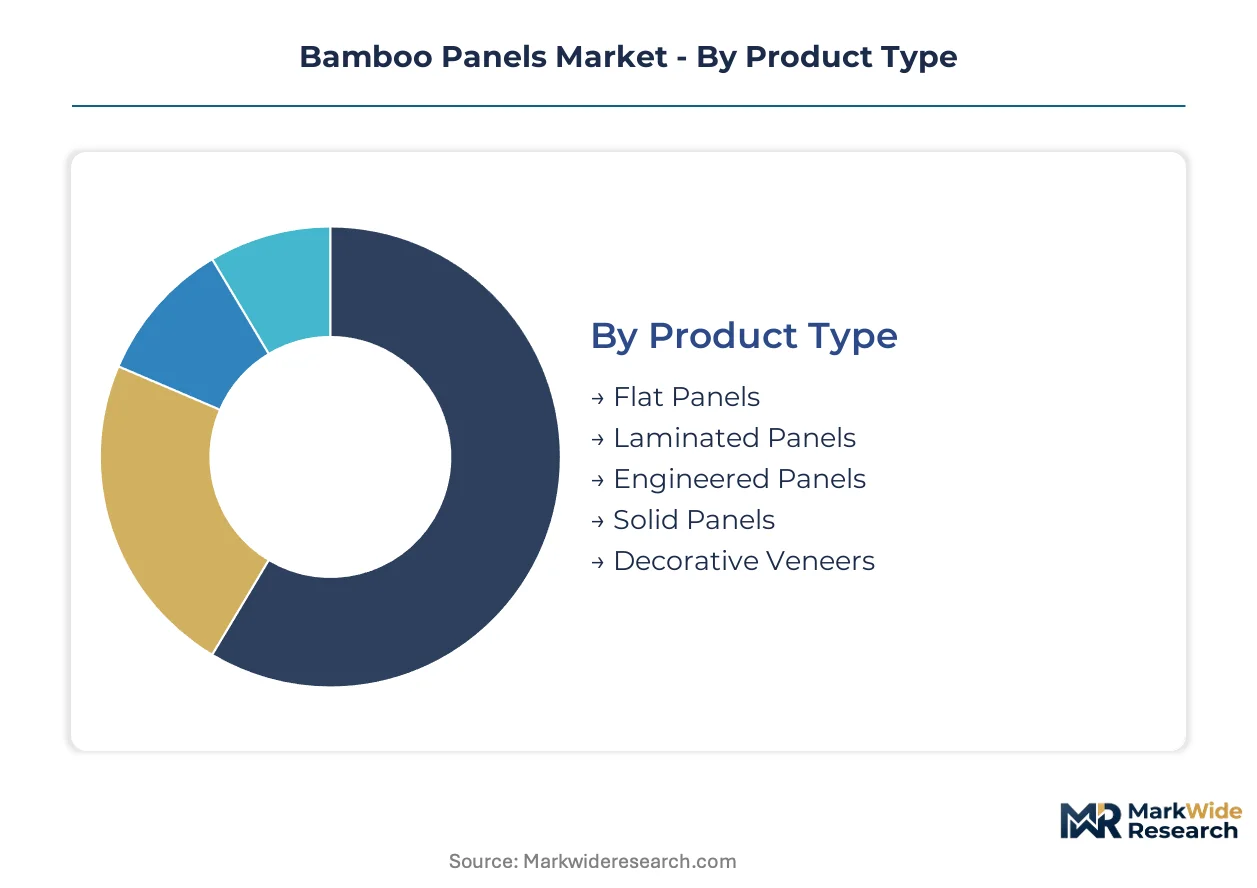
Bamboo panel demand fragments across multiple value capture points. Product type determines manufacturing complexity and certification burden. Application and end-user specifications drive adhesive chemistry and density requirements.
Product Type:
Margin pools concentrate in engineered configurations where cross-lamination commands structural premiums over commodity flat panels.
- Flat Panels:Single-layer pressed sheets with density ratings between 0.6 and 0.8 g/cm³ serve basic surfacing applications. Vietnamese furniture manufacturers in the Ho Chi Minh City corridor absorb volume for cabinet backing and drawer bottoms where cost minimization outweighs structural demands.
- Laminated Panels:Cross-directional layer bonding achieves dimensional stability for CNC machining. Residential developers across Southeast Asia specify these for mid-rise housing interiors where seismic performance requirements intersect with aesthetic uniformity.
- Engineered Panels:High-density configurations between 0.9 and 1.1 g/cm³ meet load-bearing specifications. China's GB standards enforcement drives adhesive reformulation costs into this tier.
- Solid Panels:Single-culm construction preserves natural grain variation for premium decorative applications. Limited machinability restricts adoption in automated production workflows.
- Decorative Veneers:Thin-sliced surface layers provide visual distinction at reduced material intensity. Exhibition designers specify these for temporary installations requiring lightweight transport.
The dominant share belongs to Laminated Panels, while Engineered Panels is closing the gap fastest.
Application:
Volume concentrates where material substitution economics favor bamboo over tropical hardwoods or steel alternatives.
- Furniture Manufacturing:CNC-compatible panels with uniform grain appearance dominate production of tables, cabinetry, and seating. Indonesia's furniture export sector absorbs capacity from mills seeking FSC certification for European market access.
- Interior Wall Cladding:Moisture-resistant panels with low formaldehyde emissions serve commercial interiors. California's green building codes drive specification transparency requirements in this segment.
- Flooring Solutions:High-density engineered configurations withstand abrasion in high-traffic environments. REACH compliance obligations restrict adhesive options for European-bound product.
- Construction Frameworks:Cross-laminated bamboo meets seismic load requirements in Japan's five-to-twelve story residential projects. Installation timeline compression versus concrete forming accelerates adoption.
- Packaging Materials:Lower-density flat panels substitute for plywood in export crating. Cost volatility in phenol-formaldehyde resins compresses margins for producers without captive adhesive supply.
Furniture Manufacturing retains the largest volume position, though Construction Frameworks is expanding most quickly.
End User:
Procurement sophistication varies sharply between specification-driven commercial builders and price-sensitive packaging manufacturers.
- Residential Developers:Mid-rise housing projects in Vietnam and Indonesia specify certified structural panels for government-backed programs. Dual GB-SNI compliance timelines extend supplier qualification periods.
- Commercial Builders:Green building mandates in the Pacific Northwest drive demand for lifecycle assessment documentation. Direct-to-contractor channels bypass traditional lumber yard markups in this segment.
- Furniture Artisans:Small-batch producers prioritize aesthetic grain consistency over structural certification. Specialty lumber stores serve this fragmented demand base.
- Packaging Manufacturers:Volume purchasers prioritize unit cost over emission credentials. Wholesale distributors capture this commoditized flow.
- Exhibition Designers:Temporary installation requirements favor lightweight decorative veneers. Trade show procurement cycles concentrate demand seasonally.
Residential Developers command the deepest specification requirements, while Commercial Builders are gaining procurement sophistication fastest.
Distribution Channel:
Channel compression rewards mills with in-house logistics capabilities against traditional intermediary structures.
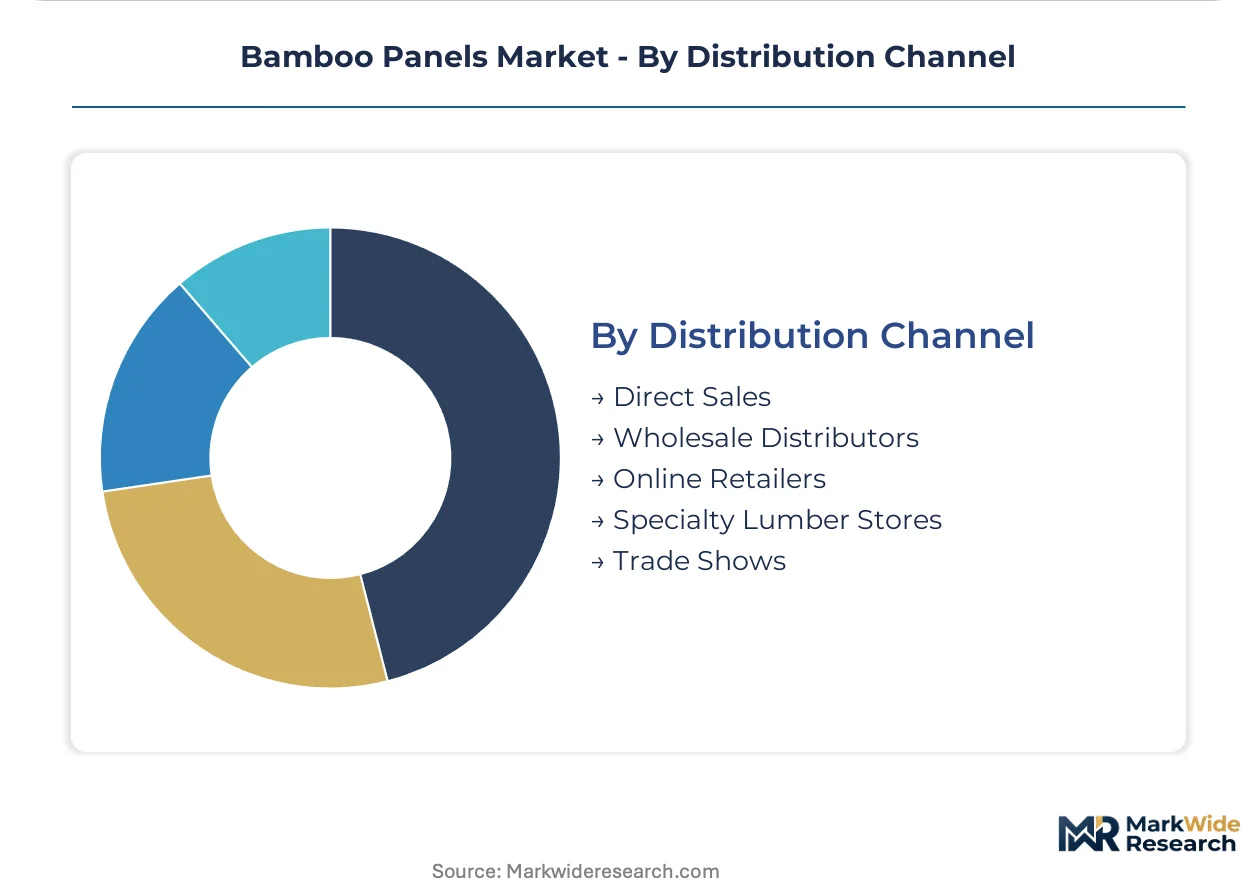
- Direct Sales:Mills with specification support staff capture margin compression from disintermediated procurement. California contractors increasingly specify certified panels through this channel.
- Wholesale Distributors:Inventory aggregation serves fragmented furniture artisan and packaging manufacturer demand. Margin absorption by intermediaries pressures producer pricing.
- Online Retailers:Digital specification tools penetrate small-scale residential renovation projects. Limited tactile evaluation capability restricts adoption for premium decorative applications.
- Specialty Lumber Stores:Local technical consultation supports furniture artisan selection. Geographic concentration limits scale in this channel.
- Trade Shows:Specification-intensive segments consolidate annual procurement decisions at industry exhibitions. Exhibition designers and commercial builders dominate this channel's transaction value.
Direct Sales holds the steepest expansion trajectory, while Wholesale Distributors retain volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European distribution networks while Chinese mills absorb margin compression from dual-formulation compliance costs. Vietnamese exporters face the steepest certification burden as they navigate overlapping EU and domestic mandates. Japanese developers are accelerating structural panel procurement for mid-rise seismic frameworks.
China
Anhui and Sichuan provinces dominate moso culm processing for global supply. SAMR enforces progressively stricter GB formaldehyde emission thresholds for residential-bound panels, forcing adhesive reformulation across mills. Mills in the Yangtze River Delta region maintain captive phenol-formaldehyde production to hedge petrochemical feedstock volatility.
Vietnam
Furniture manufacturers in the Ho Chi Minh City corridor absorb flat panel volume for cost-sensitive cabinetry applications. Exporters simultaneously satisfy EU Green Deal procurement preferences and domestic SNI structural mandates, extending qualification timelines. Binh Duong province hosts the densest concentration of laminator workforce training programs.
Indonesia
Government-backed housing programs in Java and Sumatra specify certified structural panels for mid-rise seismic frameworks. The national standards body mandates SNI certification for structural bamboo products used in subsidized construction. Surabaya's manufacturing belt is scaling cross-laminated panel capacity to meet program deadlines.
Japan
Developers in Tokyo and Osaka specify cross-laminated bamboo for five-to-twelve story residential projects, compressing installation timelines versus concrete forming. METI guidelines incentivize carbon-sequestering materials in public construction procurement. The Kansai region hosts specification engineering firms translating seismic load requirements into panel fabrication standards.
United States
California contractors specify certified panels directly, disintermediating traditional lumber yard distribution channels. The state's green building codes drive material transparency requirements in commercial interior applications. Pacific Northwest specification engineers are translating European REACH compliance documentation into domestic procurement templates.
Bamboo Panels Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with European-certified mills capturing premium positioning while Chinese producers dominate volume throughput. The vendor base stratifies across three tiers: integrated culm processors with captive adhesive production, regional laminators serving single export markets, and specification-focused distributors with in-house logistics. Two dominant competitive moves are reshaping positioning: mills are acquiring backward integration into phenol-formaldehyde resin production to hedge feedstock volatility, and distributors are building direct-to-contractor specification support capabilities to capture margin compression from disintermediated procurement.
Among Netherlands-based distributors, Moso International B.V. exemplifies the certification-premium archetype through European network control. Smith & Fong Co., Inc. and Cali Bamboo, Inc. occupy positions on opposite coasts of North American market development, with the former representing FSC-certified specialty positioning and the latter anchoring direct-channel margin capture. These three entities collectively illustrate how geographic origin and distribution architecture determine competitive positioning more than manufacturing scale alone.
| Leading Market Players |
|---|
| Cali Bamboo, Inc. |
| Bamboo Australia Pty Ltd. |
| Smith & Fong Co., Inc. |
| Zhejiang Yongyu Bamboo |
| Anji Tianzhen Bamboo Flooring |
| Moso International B.V. |
| Teragren LLC |
| Xiamen Yusheng Bamboo Products Co., Ltd. |
| Dasso Group |
| Others |
Pricing and Supply Chain Analysis
China's GB formaldehyde emission standards simultaneously gate supplier qualification and stratify price tiers across residential-bound panel markets, compressing margins for phenol-formaldehyde dependent mills while awarding certification premiums to low-emission alternatives.
Pricing Analysis
European markets command price spreads exceeding Asian benchmarks due to REACH compliance documentation and FSC dual-certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates engineered cross-laminated panels from commodity flat sheets and decorative veneers. Cost compression in standard-tier flat panels intensifies because Vietnamese furniture manufacturers absorb volume at minimal emission thresholds. Packaging manufacturers exhibit highest price sensitivity, while Japanese seismic-framework contractors accept structural premiums for certified engineered configurations.
Supply Chain Analysis
Container availability fluctuations on the Shanghai-Rotterdam trade lane compress European distributor margins during peak procurement cycles. Supply concentrates in China's Anhui and Sichuan provinces, with Vietnamese Binh Duong province and Indonesian Surabaya belt serving secondary processing hubs. Raw material dependencies center on moso culm supply, phenol-formaldehyde resin formulations, and isocyanate adhesive chemistries. Single-source vulnerability in Chinese culm processing creates structural risk for European distributors. Distribution runs through direct-to-contractor channels in North America and certified wholesale networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-laminated bamboo configurations are approaching platform-economics inflection as Japanese seismic standards and European REACH protocols create interoperability requirements that favor certified ecosystem participants over commodity suppliers.
For Market Incumbents: Compound certification advantages by acquiring captive phenol-formaldehyde production in Yangtze River Delta mills to hedge petrochemical feedstock volatility against phenol-formaldehyde cost fluctuations. Extend backward integration into adhesive chemistry to defend margin position against isocyanate-bio-based hybrid entrants. For New Entrants and Emerging Players: Anchor in Indonesia's SNI-certified structural segment where government-backed housing programs create captive demand with extended qualification timelines that favor patient capital. Target cross-laminated panel fabrication for Java and Sumatra mid-rise projects, leveraging Surabaya's scaling manufacturing belt for regional logistics advantage. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across engineered panel sub-segments as adhesive reformulation costs concentrate in compliant tier-one mills. Prioritize acquisition targets with dual GB-SNI certification capabilities and in-house logistics infrastructure over pure manufacturing scale. Watch Japanese METI guideline revisions as signal for public procurement inflection toward carbon-sequestering materials.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Production | Mills with captive phenol-formaldehyde supply hedge GB standard compliance costs against petrochemical volatility. |
| Dual Certification Investment | Simultaneous FSC and GB standard attainment opens premium European and Chinese residential channels. |
| Direct-to-Contractor Channel Buildout | California commercial builders increasingly specify certified panels through disintermediated procurement pathways. |
| Cross-Laminated Capacity Expansion | Surabaya manufacturing belt scales output to meet Indonesian government-backed housing program deadlines. |
| Isocyanate-Bio-Based Hybrid R&D | Convergence of low-emission chemistry with structural performance opens premium positioning against phenolic systems. |
Research Methodology
A spread of perspectives from adhesive formulation chemists, Vietnamese laminator workforce trainers, European distribution network managers, and Indonesian SNI certification auditors converged on the working assumptions. Primary fieldwork with these stakeholders combined with secondary validation against China's SAMR regulatory filings, EU ECHA REACH substance databases, Indonesian BSN SNI documentation, and Japanese METI construction material guidelines. Bottom-up mill capacity estimates and top-down regional demand projections underwent triangulation.
Segmentation dimensions modeled include product type hierarchy, application intensity tiers, end-user procurement sophistication levels, and distribution channel architecture across the projection horizon. CAGRs derived from volume trajectory analysis incorporating adhesive reformulation cost curves, certification timeline distributions, and seismic framework adoption patterns in Japanese residential construction.
Decision-makers should treat outputs as directional under base assumptions of sustained GB standard enforcement and Indonesian housing program continuity; material deviation would warrant model refresh. Specific risk factors include phenol-formaldehyde feedstock volatility, skilled laminator workforce attrition, and steel substitution acceleration in mid-rise frameworks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
North America Sustainable Home Decor Market
Homecare and Decor
Curtains and Window Blinds Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
India Decorative Laminates Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
US Wallpaper Market
Homecare and Decor
Flush Door Market
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
Digital Printed Wallpaper Market
Homecare and Decor
Pillow Cases Market
Homecare and Decor
Europe Commercial Blinds and Shades Market