
 UK Facade Market | 2026-2036
UK Facade Market Size, Share, and Industry Trends Forecast 2026-2036
UK Facade Market Analytics
Modular unitized panel bundling is restructuring procurement patterns across major UK developments. Saint-Gobain Glass UK leverages its Pilkington heritage to dominate high-performance coated glass supply for curtain walling. Schüco UK anchors its position through systems-level control over aluminium profiles, thermal breaks, and integrated hardware. Reynaers Aluminium UK competes on specification flexibility across commercial and residential facade programmes.
A facade constitutes the external envelope system of a building, comprising cladding, glazing, insulation, and structural support elements engineered to manage thermal transmittance, air permeability, weather resistance, and structural load transfer. Its primary commercial purpose is to protect interior spaces while maximizing daylight penetration and minimizing operational energy consumption. Metal facade systems lead volume in commercial towers due to speed of installation and recyclability credentials. Glass segments command premium positioning in prestige developments where solar control coatings and triple-glazing specifications drive specification value. Unitized systems represent the fastest-growing facade system category as offsite manufacturing quality and crane-lift efficiency reduce site labour dependency.
The Building Safety Regulator enforces gateway compliance and higher-risk building certification, compelling facade manufacturers to document fire performance of insulation cores and cavity barriers. BSI Kitemark and UKCA marking requirements shape product access, with third-party certification now mandatory for external wall system components used above 18 metres. BREEAM and the Future Homes Standard tighten operational carbon thresholds, pushing specification toward thermally broken aluminium and vacuum-insulated panels. Stakeholders must monitor how the regulator's evolving technical guidance on combustible materials redirects R&D investment and procurement qualification timelines.
Market Dynamics
The UK facade market is restructuring around offsite manufacturing economics as unitized panel systems compress installation schedules and reduce skilled labour dependency on congested urban sites. This shift is amplifying procurement consolidation toward systems-level suppliers capable of end-to-end envelope performance warranties.
Growth Catalysts
- Future Homes Standard thermal mandates:The 2025 uplift in U-value requirements for new residential construction is accelerating specification of thermally broken aluminium and vacuum-insulated panels across housebuilder portfolios.
- High-rise residential clustering in Greater London:Tower development pipelines in Nine Elms, Canary Wharf, and Stratford are generating concentrated demand for fire-rated curtain walling with integrated cavity barriers.
- Modular construction adoption:Offsite manufacturing of complete facade modules is reducing site programme risk for commercial office developers facing compressed completion deadlines.
Market Restraints
- Aluminium billet price volatility:Input cost swings for extrusion feedstock are compressing margin visibility for systems houses and specialist fabricators.
- Third-party certification bottlenecks:UKCA marking and BSI Kitemark testing queues for external wall systems above 18 metres are extending qualification timelines by 4-8 months.
- Thin-film photovoltaic glazing:Building-integrated photovoltaics with improving cost curves threaten to capture premium facade spend in prestige commercial schemes.
Strategic Opportunities
- Retrofit envelope programmes:The Social Housing Decarbonisation Fund and MEES compliance deadlines are opening large-scale overcladding contracts across England's 1950s-1980s tower stock.
- Digital twin integration:Convergence of BIM Level 2 mandates with IoT sensor embedding is creating recurring revenue streams through performance monitoring contracts.
- Scottish high-rise pipeline:Edinburgh and Glasgow city centre residential towers remain undersupplied by unitized specialists relative to English markets.
Industry Challenges
- Fire engineering skill scarcity:Qualified facade fire engineers capable of Gateway 2 compliance documentation are concentrated among a handful of consultancies, creating recruitment bottlenecks.
- Legacy system integration:Heritage building retrofits require bespoke interface detailing with existing masonry structures, complicating standardised panel design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Facade Market |
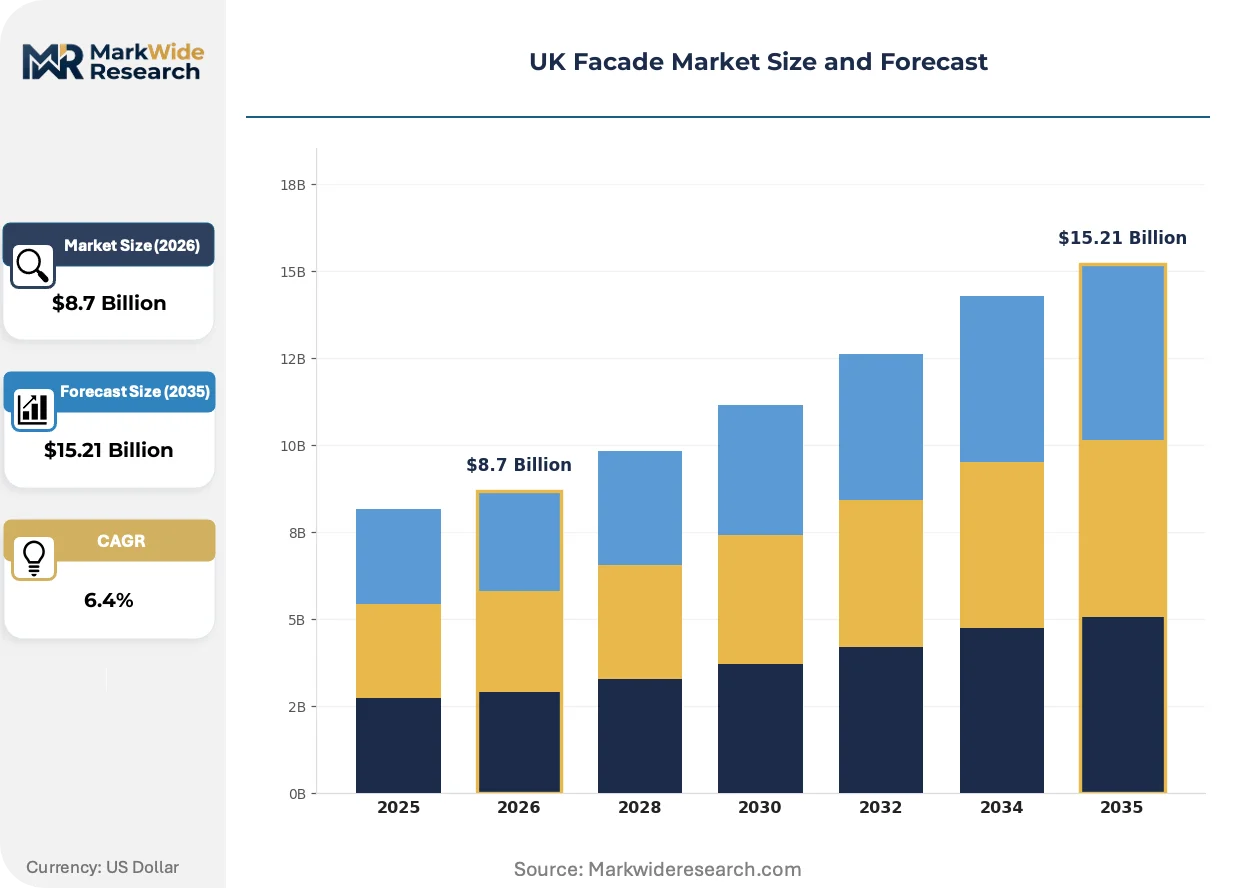
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Metal, Wood, Concrete Installation Type: New Construction, Renovation, Retrofit, Modular Building Type: Residential, Commercial, Institutional, Industrial Facade System: Ventilated, Unitized, Stick-built, Double-skin |
| Companies Covered | Saint-Gobain Glass UK, AluK (GB) Ltd, Permasteelisa, Senior Architectural Systems, Yuanda Europe (UK), Schüco UK, Lindner Exteriors, Reynaers Aluminium UK, Kingspan Insulated Panels UK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Facade Market Evolving Landscape
Digital fabrication and performance monitoring technologies are compressing the traditional separation between design, manufacture, and operational optimisation in UK envelope procurement. These shifts are redistributing value capture toward data-integrated supply chains.
Electrochromic glazing with real-time solar modulation is rewriting specification norms for commercial office towers. Landlords targeting EPC A ratings and WELL certification are specifying these systems despite 40-60% cost premiums over static high-performance glass. The technology is compressing the trade-off between daylight autonomy and cooling load reduction that has dominated facade engineering for two decades.
The Building Safety Regulator's evolving technical guidance on combustible materials is forcing recertification of established insulation core products. Manufacturers with early third-party fire performance data are securing preferred supplier status on Gateway 1-registered projects. Residential high-rises above 18 metres face the steepest compliance cost escalation as cavity barrier integration becomes mandatory.
Developer procurement teams are consolidating envelope packages under single-point responsibility contracts rather than fragmented cladding-plus-glazing splits. Main contractors with design capability are capturing facade risk that specialist subcontractors previously held. This concentration is most visible in Manchester and Birmingham mixed-use schemes where programme certainty outweighs unit cost optimisation.
UK Facade Market Segmentation
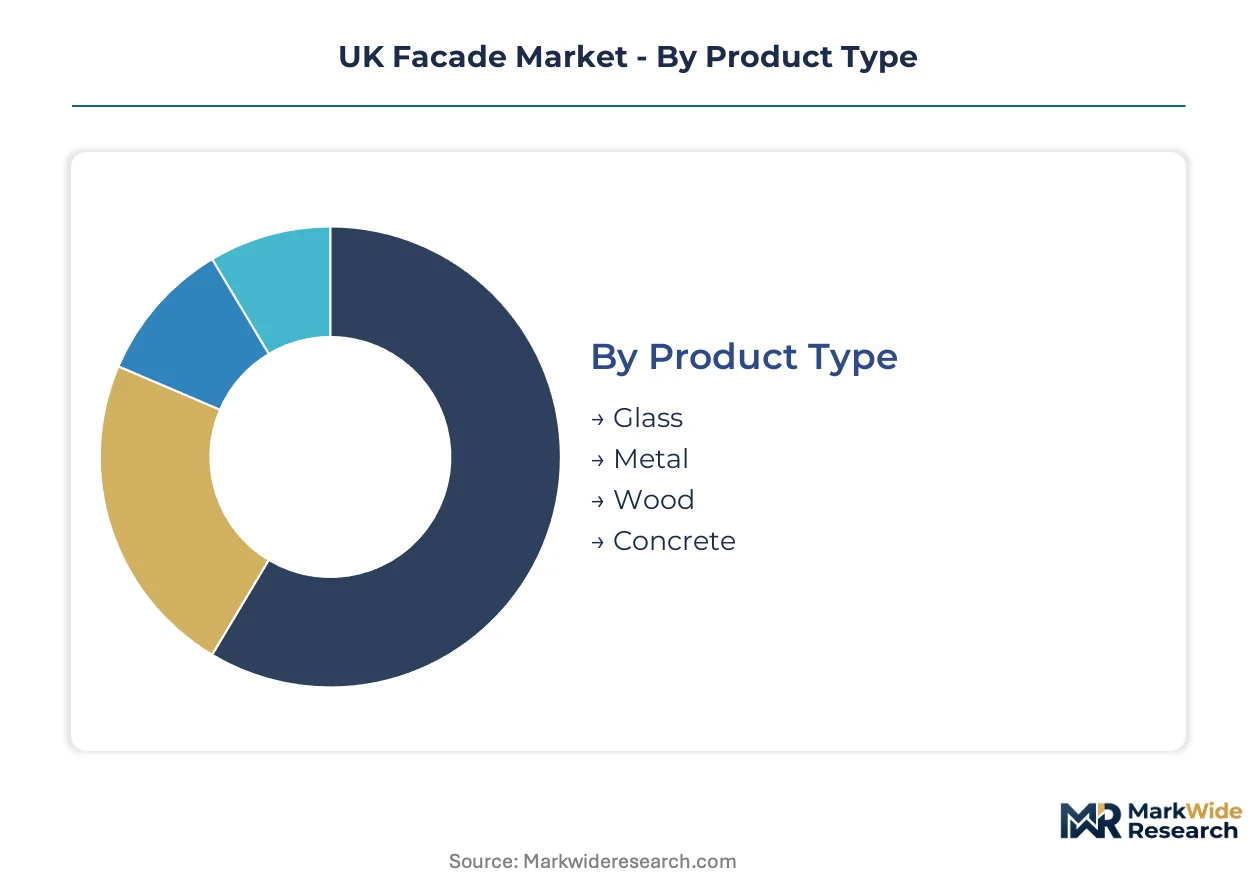
Facade procurement in the UK fragments across four structural dimensions. Each dimension carries distinct certification burdens under the Building Safety Regulator and BSI Kitemark frameworks. Specification teams must map these overlaps to qualify envelope systems for projects above 18 metres.
Product Type:
UKCA marking requirements diverge sharply across material classes, with fire performance documentation driving qualification timelines.
- Glass:Triple-glazed units with solar control coatings dominate prestige commercial towers in Canary Wharf and the City of London. Landlords targeting EPC A ratings absorb 40-60% cost premiums for electrochromic variants that modulate solar gain in real time.
- Metal:Aluminium composite panels and solid metal rainscreen systems lead volume in Manchester and Birmingham mixed-use schemes. Thermally broken extrusions are displacing standard profiles as Future Homes Standard U-value mandates tighten.
- Wood:Timber cladding with fire-retardant treatment occupies niche positioning in low-rise residential and heritage-sensitive institutional projects.
- Concrete:Precast concrete facade panels anchor industrial logistics facilities and data centres across the Midlands where impact resistance outweighs thermal performance priorities.
Metal sits at the top of the volume ranking, with Glass climbing the fastest.
Installation Type:
Cost tiers separate site-based labour intensity from factory-controlled quality premiums.
- New Construction:Greenfield commercial towers in Nine Elms and Stratford generate concentrated demand for integrated envelope packages with single-point warranty coverage.
- Renovation:Partial facade replacement on 1990s office stock in central London faces interface complexity with existing curtain walling systems.
- Retrofit:Overcladding programmes under the Social Housing Decarbonisation Fund are opening large-scale contracts across England's 1950s-1980s tower stock. MEES compliance deadlines compress procurement timelines.
- Modular:Complete facade modules manufactured offsite reduce site programme risk for developers facing compressed completion deadlines. Crane-lift efficiency cuts skilled labour dependency on congested urban sites.
Retrofit commands the steepest expansion trajectory as regulatory deadlines force action on existing stock.
Building Type:
Customer type determines performance specification thresholds and procurement consolidation patterns.
- Residential:High-rise towers above 18 metres face mandatory cavity barrier integration and Gateway 2 compliance documentation. Housebuilder portfolios are accelerating thermally broken aluminium specification.
- Commercial:Office developers in London and Manchester are consolidating envelope packages under design-build contracts. WELL certification and EPC targets drive electrochromic glazing uptake.
- Institutional:NHS estates and university campuses balance heritage constraints with operational carbon reduction. Bespoke interface detailing with existing masonry complicates standardised panel design.
- Industrial:Logistics sheds and data centres prioritise speed of enclosure over thermal performance. Metal panel systems dominate with minimal glazing ratios.
Commercial leads absolute spend, with Residential gaining share fastest through high-rise clustering.
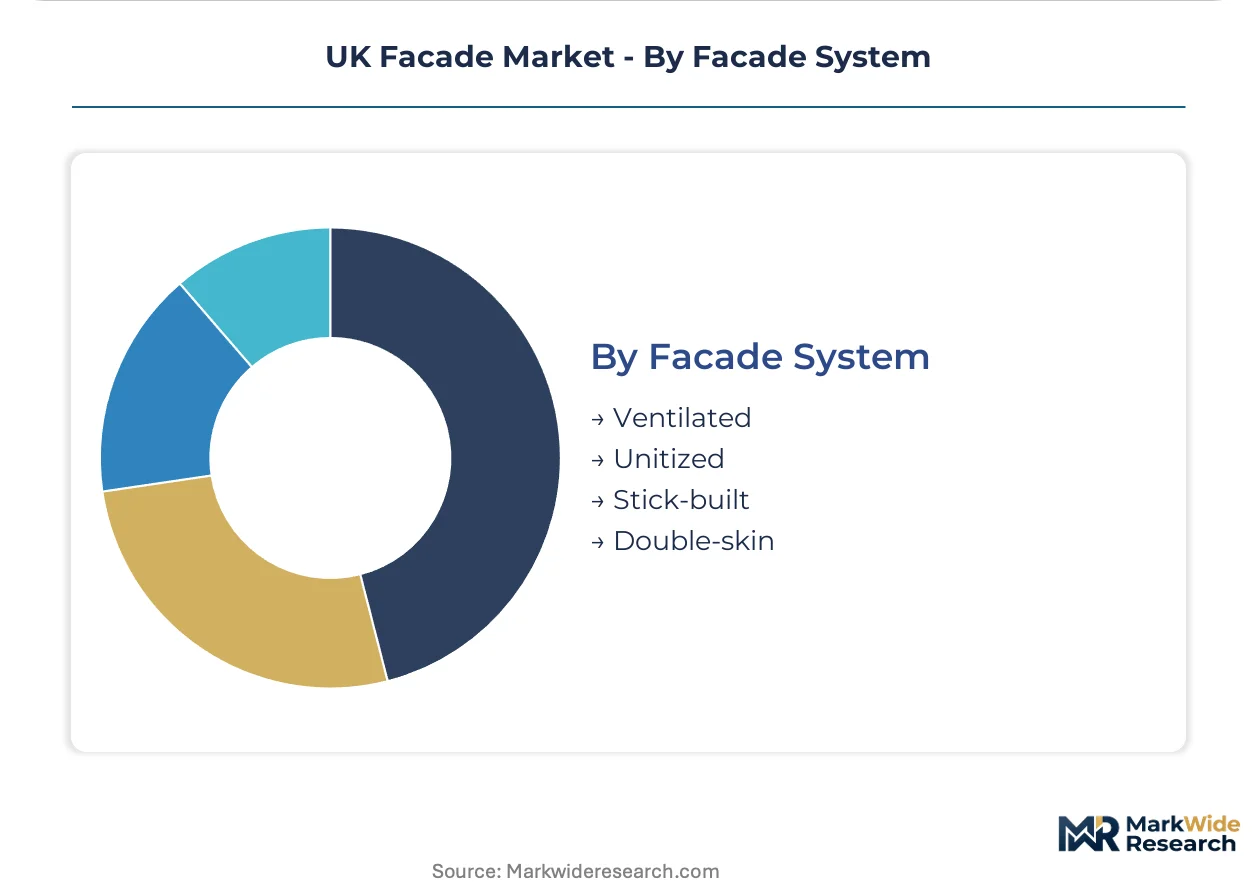
Facade System:
Supply concentration favours systems houses with end-to-end envelope performance warranties.
- Ventilated:Rainscreen systems with drained and back-ventilated cavities dominate mid-rise commercial and residential applications. Fire engineering scrutiny concentrates on insulation core classification.
- Unitized:Factory-assembled panels with integrated glazing and thermal breaks are displacing site-built alternatives. Offsite manufacturing quality and crane-lift efficiency reduce labour dependency.
- Stick-built:Site-assembled mullion-and-transom systems retain share in low-rise commercial where programme pressure is lower and design flexibility higher.
- Double-skin:Active cavity facades with integrated shading and natural ventilation command premium positioning in prestige headquarters targeting BREEAM Outstanding ratings.
Unitized systems sit at the top of the volume ranking, with Double-skin climbing the fastest among prestige schemes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK facade industry traces its modern lineage to the post-war reconstruction era, when Pilkington's float glass innovation and Birmingham's metalworking clusters established the foundation for today's envelope engineering capabilities. This heritage continues to shape regional specialisation across the nation's construction economy.
London and the Southeast
Canary Wharf and Nine Elms generate concentrated demand for fire-rated curtain walling in towers exceeding 18 metres. The Building Safety Regulator's Gateway 2 compliance documentation compels developers to source cavity barrier-integrated systems. Specialist fabricators cluster around the Thames Gateway to service compressed completion schedules on mixed-use schemes.
Midlands
Birmingham's commercial office pipeline and Coventry's logistics expansion drive specification of thermally broken aluminium rainscreen systems. The Future Homes Standard's U-value mandates are accelerating vacuum-insulated panel uptake across housebuilder portfolios. Metal fabrication heritage in the West Midlands sustains capacity for rapid-turnaround envelope packages.
North England
Manchester city centre's residential tower clustering creates procurement concentration for unitized facade modules. The Social Housing Decarbonisation Fund is opening overcladding contracts across 1950s-1980s tower stock in Liverpool and Leeds. Local authorities compress timelines to meet MEES compliance deadlines.
Scotland
Edinburgh and Glasgow city centre residential towers remain undersupplied by unitized specialists relative to English markets. Scottish building standards exceed UK baseline thermal performance requirements, favouring triple-glazed specifications. The Edinburgh-Glasgow corridor presents strategic whitespace for systems houses with Gateway 1 registration capabilities.
Wales
Cardiff's commercial regeneration and Swansea's waterfront development generate mid-rise envelope demand below the 18-metre regulatory threshold. Welsh procurement frameworks emphasise whole-life carbon assessment, shifting specification toward recyclable metal systems. Regional fabricators compete on speed rather than certified fire performance complexity.
UK Facade Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and warranty scope. Systems houses with end-to-end envelope performance guarantees capture procurement consolidation from risk-averse developers. Three archetypes dominate: integrated systems suppliers controlling aluminium extrusion and thermal break technology; specialist fabricators competing on installation speed; and glass processors leveraging coating heritage for solar control specification. Competitive moves concentrate on design-build contract capture and third-party fire performance data accumulation.
Within the heritage-anchored tier, Saint-Gobain Glass UK and Schüco UK exemplify divergent paths to specification influence. Saint-Gobain occupies a position tied to Pilkington's float glass lineage and high-performance coating capabilities. Schüco represents systems-level control over profile engineering and integrated hardware. Reynaers Aluminium UK sits within the flexibility-focused segment, competing across commercial and residential programme diversity. These three demonstrate how geographic origin and structural suffix—UK-limited companies and German GmbH heritage—map to distinct competitive positioning without requiring operational detail.
| Leading Market Players |
|---|
| Saint-Gobain Glass UK |
| AluK (GB) Ltd |
| Permasteelisa |
| Senior Architectural Systems |
| Yuanda Europe (UK) |
| Schüco UK |
| Lindner Exteriors |
| Reynaers Aluminium UK |
| Kingspan Insulated Panels UK |
| Others |
Value Network & Pricing Analysis
Aluminium billet price volatility cascades through UK facade supply chains, compressing margin visibility for systems houses as extrusion feedstock swings propagate from LME trading floors to project tenders across Manchester and Birmingham commercial towers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies facade procurement by certification grade and thermal performance tier. Premium positioning commands 40-60% cost absorption for electrochromic glazing and Gateway 2-compliant cavity barrier integration. Cost compression in standard metal rainscreen systems is intensifying because housebuilders face Future Homes Standard U-value mandate deadlines. Social housing retrofit programmes exhibit highest price sensitivity, while prestige commercial landlords in Canary Wharf demonstrate lowest sensitivity.
Supply Chain Analysis
Regional distribution centers across the West Midlands and Thames Gateway operate hub-and-spoke patterns to service compressed completion schedules on urban mixed-use schemes. Supply concentrates in Germany for thermal break technology and aluminium profile systems, in Belgium for float glass and solar control coatings, and in China for hardware components and standard extrusions. Raw material dependencies rest on primary aluminium billets, polyamide thermal break strips, and low-E coating chemicals. Single-source vulnerability in qualified fire engineering consultancy creates bottleneck risk. Distribution runs through main contractor consolidation rather than fragmented specialist subcontractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK facade market functions as a stable compounder anchored by regulatory ratcheting on building safety and thermal performance that mandates envelope replacement cycles across England's tower stock.
For Market Incumbents: Anticipate thin-film photovoltaic glazing substitution threat by accelerating electrochromic specification partnerships with London commercial landlords targeting WELL certification. Prioritize backward integration into vacuum-insulated panel core manufacturing to defend margin position against commodity aluminium volatility. Lock in preferred supplier status on Gateway 1-registered projects through early third-party fire performance data accumulation. For New Entrants and Emerging Players: Digital specification platforms offer route to bypass established systems house relationships by delivering real-time U-value compliance calculators to housebuilder procurement teams. Scottish high-rise residential towers present most penetrable geography given relative undersupply by unitized specialists. Target overcladding programme aggregation through local authority framework contracting to capture Social Housing Decarbonisation Fund deployment. For Investors and Strategic Acquirers: Roll-up economics work for regional facade fabricators because Building Safety Regulator certification requirements create scale advantages in third-party testing cost absorption. Five-to-ten year viability hinges on retrofit envelope exposure versus new-build cyclicality. Monitor Edinburgh-Glasgow corridor planning permission pipelines as inflection indicator for Scottish market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Gateway 2 Certification Investment | Early fire performance data accumulation secures preferred supplier status on high-rise projects. |
| Retrofit Overcladding Specialization | Social Housing Decarbonisation Fund deployment creates recurring revenue from England's tower stock. |
| Digital Twin Integration | BIM Level 2 convergence with IoT sensor embedding generates performance monitoring contract streams. |
| Scottish Market Entry | Edinburgh and Glasgow undersupply offers whitespace for unitized systems with Gateway 1 registration. |
| Electrochromic Partnership Program | WELL certification demand from Canary Wharf landlords drives premium specification capture. |
Research Methodology
Coverage spans Greater London, the Midlands, North England, Scotland, and Wales, with primary inputs from each region combined with secondary validation across regulatory databases. Primary interviews incorporated facade system procurement directors, main contractor envelope package leads, Building Safety Regulator compliance consultants, and local authority housing decarbonisation officers. Secondary sources included UKCA marking registers, BSI Kitemark certification databases, MHCLG technical guidance releases, and planning permission pipelines from local authority portals. Bottom-up project pipeline aggregation triangulated against top-down construction output forecasts.
Granularity-level modeling operated at product type, installation type, building type, and facade system dimensions, with thermal performance tier and regulatory height threshold as cross-cutting variables. CAGRs derived from segment-level volume projections weighted by regional construction pipeline density and mandate implementation schedules. Forecast inputs incorporated aluminium price elasticity coefficients and fire engineering capacity constraints across the analysis window.
The model assumes a particular technology adoption path for electrochromic glazing; alternative pathways for building-integrated photovoltaics would alter the outlook for premium glass specification. Forecasts reflect assumptions on regulatory enforcement intensity and retrofit funding continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
Prestressed High Strength Concrete Pipe Pile Market
Structural Engineering
Europe Insulated Concrete Form (ICF) Market
Structural Engineering
Translucent Concrete Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
Global Structural Health Monitoring Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Concrete Slabs Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
Bridge Bearing Pad Market