
 Freeze-Dried Pea Isolates Market | 2026-2036
Freeze-Dried Pea Isolates Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze-Dried Pea Isolates Market Analytics
Buyer concentration among sports nutrition and dairy-alternative brands is repositioning procurement power toward mid-sized clean-label formulators. Roquette Frères leverages its European extraction infrastructure to supply major food manufacturers. Burcon Nutrascience Corporation anchors North American pea-protein innovation through its Winnipeg R&D campus. Cosucra Groupe Warcoing specializes in Belgian-sourced organic isolates for premium European brands.
Freeze-dried pea isolates are concentrated protein powders, typically containing 80-90% protein by dry weight, produced through aqueous extraction followed by lyophilization to preserve functional properties including emulsification and gelation. The organic product type segment commands premium positioning as clean-label certifications tighten across European retail. Protein supplements lead application demand, while dairy alternatives represent the fastest-growing end-use channel as lactose-free formulations multiply.
The FDA regulates pea isolate labeling under Food Allergen Labeling and Consumer Protection Act provisions, while EFSA governs novel food authorizations across European markets. REACH compliance shapes solvent residues in extraction processes, directly affecting import eligibility for Asian suppliers. Stakeholders must monitor evolving protein-content thresholds in organic certification standards and freeze-drying energy regulations.
Market Dynamics
Sports nutrition procurement consolidation and EU Green Deal energy standards are compressing margins for freeze-drying operators while elevating clean-label certification requirements across European retail channels.
Growth Catalysts
- EU F-Gas Regulation:Equipment manufacturers are accelerating R-404A refrigerant phase-outs, driving replacement demand for energy-efficient lyophilization systems that reduce processing costs per kilogram of isolate.
- Clean-label protein powders:Formulators in Germany's ingredient startup corridor are specifying organic pea isolates for sports nutrition applications, tightening protein-content thresholds above 85% dry weight.
- Lactose-free dairy alternatives:Beverage brands across Western Europe are reformulating with pea isolates to achieve gelation properties matching casein, expanding the addressable application base beyond supplements.
Market Restraints
- Natural gas price volatility:Freeze-drying consumes 0.8-1.2 kWh per kilogram of water removed; European energy costs have compressed operating margins for contract manufacturers in Belgium and the Netherlands.
- Extraction solvent residues:REACH compliance for hexane and ethanol traces creates import friction for Asian suppliers lacking ECHA-registered processing documentation.
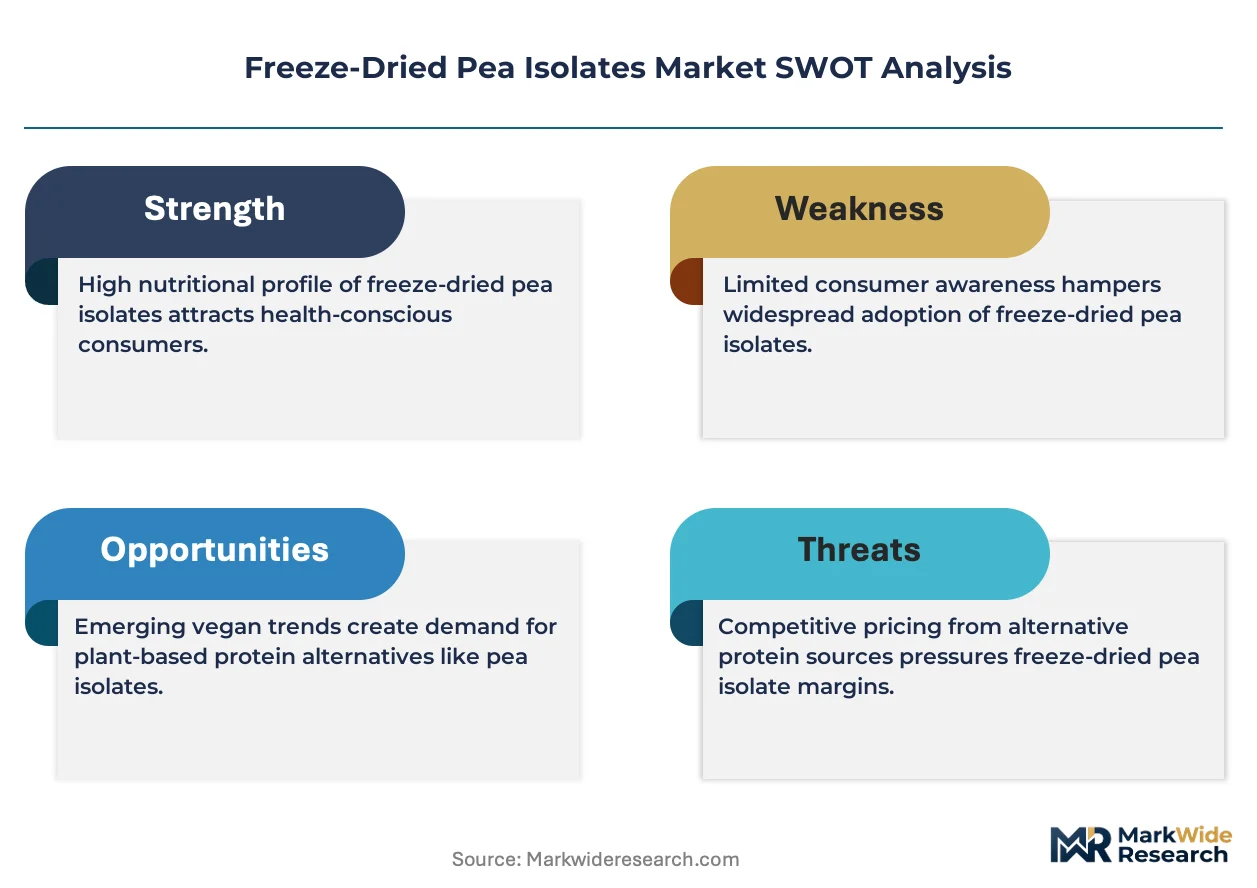
- Soy-whey protein substitution:Established dairy and commodity soy supply chains maintain cost advantages in mass-market formulations, limiting pea isolate penetration in price-sensitive segments.
Strategic Opportunities
- Organic certification tiering:Premium European brands are differentiating through Bio-Siegel and EU organic logos, creating margin expansion for isolates meeting 95% organic ingredient thresholds.
- Cell-cultured meat hybridization:Alternative protein startups are blending pea isolates with cultivated fats to achieve texture benchmarks, opening a nascent high-value application channel.
- Direct-to-brand procurement platforms:Digital ingredient marketplaces are disintermediating traditional distributors, enabling mid-sized German formulators to source isolates with full batch traceability.
Industry Challenges
- Lyophilization technician scarcity:Specialized knowledge of vacuum chamber optimization and sublimation curve management is concentrated among aging European equipment operators.
- Organic certification timeline compression:Three-year conversion periods for conventional pea farming are constraining supply elasticity for brands launching clean-label product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze-Dried Pea Isolates Market |
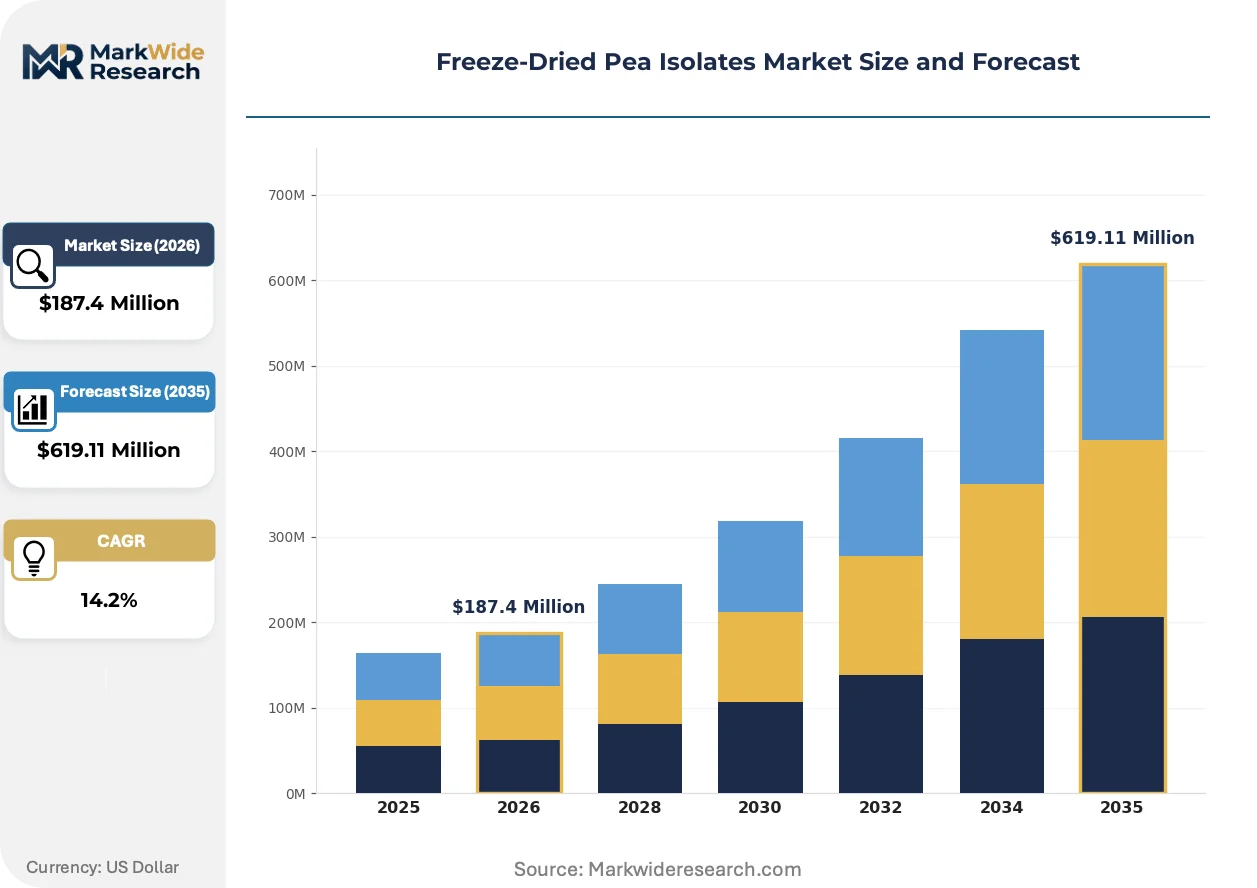
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Non-GMO, High-Protein End User: Food Industry, Beverage Industry, Nutraceuticals, Sports Nutrition Application: Protein Supplements, Snack Foods, Bakery Products, Dairy Alternatives Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Roquette Frères, Burcon Nutrascience Corporation, Cosucra Groupe Warcoing, Nutri-Pea Limited, Sotexpro, Axiom Foods, Ingredion Incorporated, Cargill, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze-Dried Pea Isolates Market Evolving Landscape
Automation of extraction and drying workflows is compressing batch-to-batch variability while regulatory pressure on refrigerants and clean-label claims is reshaping capital allocation across European processing facilities.
Membrane filtration systems integrated with AI-driven process control are automating protein fractionation precision. Mid-sized German ingredient startups are adopting these systems to reduce isolate variability below 2% coefficient of variation. This automation is compressing quality-control labor costs while enabling real-time adjustment of extraction pH and temperature parameters.
The EU F-Gas Regulation mandates 79% phasedown of hydrofluorocarbon refrigerants by 2030, forcing lyophilization equipment retrofits. Processing facilities in Hamburg and Berlin are piloting CO2-based cascade refrigeration to maintain -40°C shelf temperatures. Organic-certified isolates face the steepest compliance costs as energy-intensive certification audits compound refrigerant transition capex.
Ingredient buyers are consolidating supplier relationships around single-source traceability requirements. Sports nutrition brands in Germany are displacing multi-origin procurement with direct partnerships covering farm-to-isolate documentation. This concentration is most visible in Berlin's startup cluster, where formulators specify individual Belgian or French organic pea fields for batch-level provenance marketing.
Freeze-Dried Pea Isolates Market Segmentation
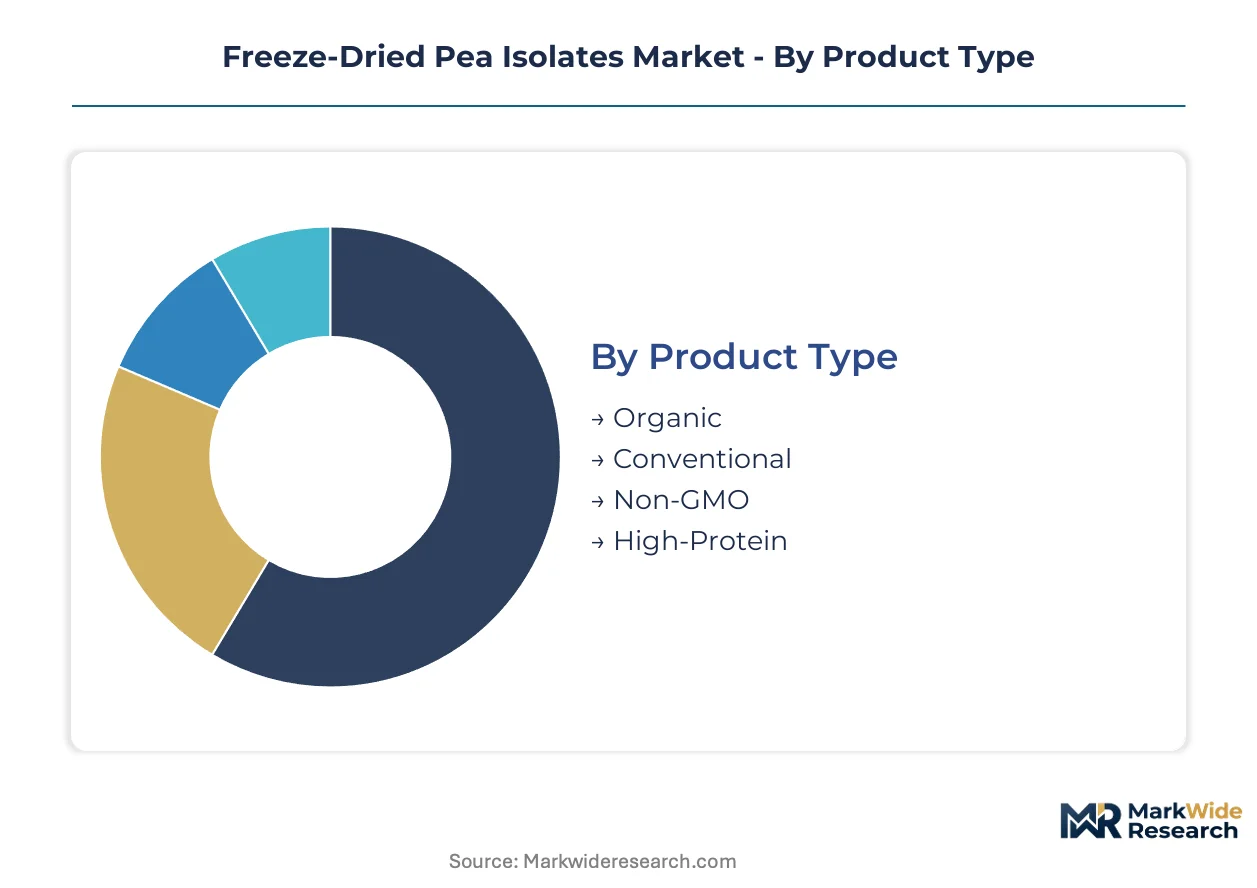
Freeze-dried pea isolates command divergent price premiums across certification tiers while end-use applications impose distinct functional specifications on protein content and solubility. Buyers in sports nutrition and dairy alternatives are driving segmentation fragmentation through clean-label procurement mandates.
Product Type:
Certification tier determines procurement priority for European formulators facing tightening retail labeling standards.
- Organic:Requires 95% organic ingredient content under EU regulation, commanding premium positioning in German and Belgian clean-label formulations. Bio-Siegel certification audits compound energy costs for lyophilization facilities, constraining supply elasticity from French and Italian organic pea fields.
- High-Protein:Specifications exceed 85% protein by dry weight, targeting sports nutrition brands in Berlin's startup corridor demanding batch-to-batch consistency below 2% coefficient of variation. Membrane filtration automation enables this precision tier.
- Non-GMO:IP traceability systems track seed-to-isolate provenance for retail chains enforcing transparency protocols.
- Conventional:Standard extraction processes serve cost-sensitive mass-market applications without certification overhead.
Conventional isolates lead on scale; organic isolates lead on momentum.
End User:
Functional requirements vary sharply across customer categories, with protein-content thresholds and gelation properties dictating isolate selection.
- Sports Nutrition:Formulators specify 80-90% protein isolates with rapid dispersibility for powder applications, sourcing through direct-to-brand procurement platforms that disintermediate traditional distributors. Hamburg ingredient startups cluster around this demand.
- Dairy Alternatives:Beverage brands reformulate with pea isolates to achieve casein-matching gelation properties, expanding the addressable application base beyond supplements into lactose-free milk and yogurt alternatives.
- Food Industry:Bakery and snack manufacturers utilize isolates for emulsification and texture modification in clean-label reformulations.
- Nutraceuticals:Capsule and tablet applications require micronized particle specifications for compressibility.
Sports nutrition leads on scale; dairy alternatives expand most quickly.
Application:
Processing conditions and finished-product matrices determine isolate functional requirements across consumption occasions.
- Protein Supplements:Powder formats dominate procurement volumes, with German brands specifying organic isolates for clean-label positioning in retail and e-commerce channels.
- Dairy Alternatives:Beverage applications require heat-stable emulsification properties for UHT processing, driving R&D partnerships between isolate suppliers and Dutch and Belgian beverage formulators.
- Snack Foods:Extruded and puffed applications utilize isolates for protein fortification with minimal flavor impact.
- Bakery Products:Dough conditioning and crumb structure modification employ isolates at lower inclusion rates than supplement applications.
Protein supplements lead on scale; dairy alternatives gain share fastest.
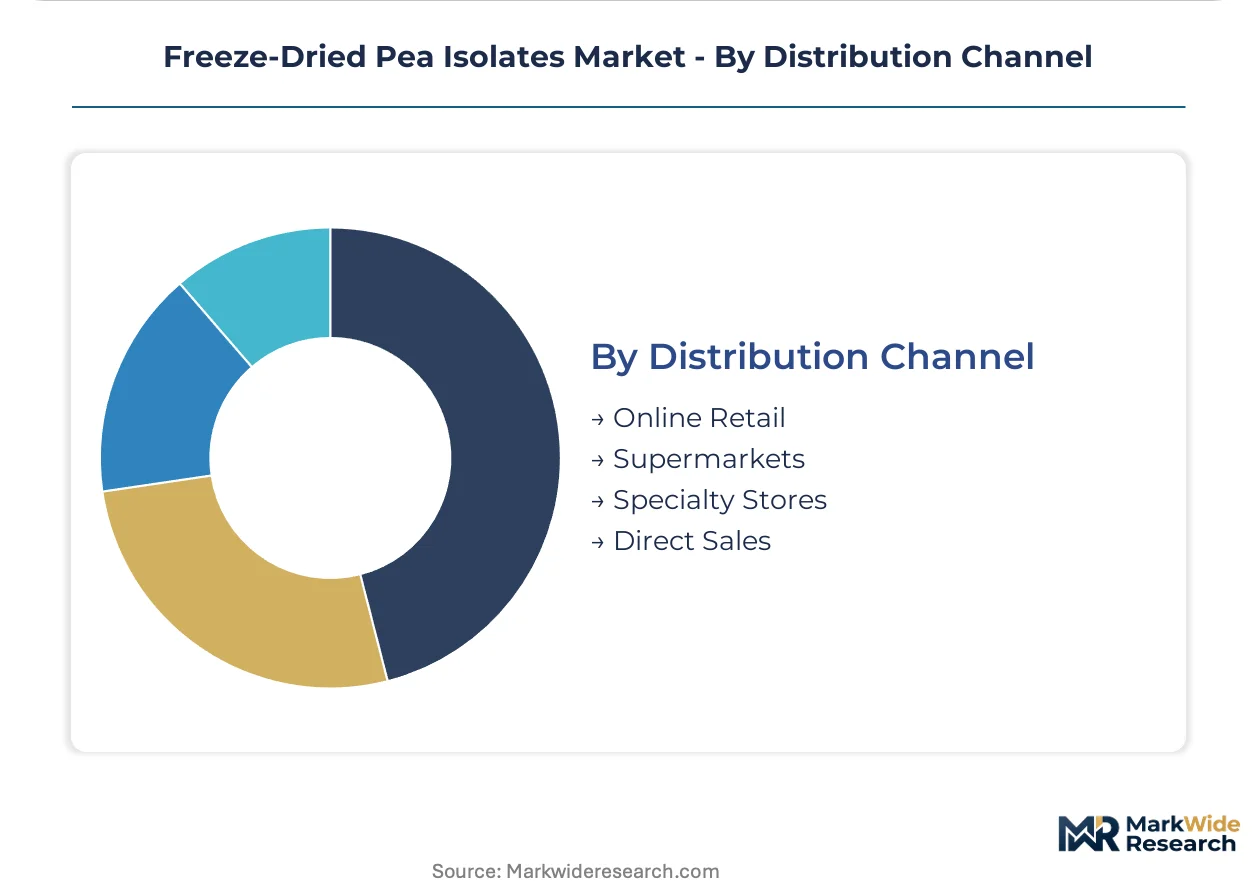
Distribution Channel:
Traceability requirements and order fragmentation reshape channel economics for isolate suppliers.
- Direct Sales:Single-source partnerships with full farm-to-isolate documentation displace multi-origin procurement among Berlin formulators specifying individual Belgian or French organic pea fields for batch-level provenance marketing.
- Online Retail:Digital ingredient marketplaces enable mid-sized German formulators to source isolates with full batch traceability, compressing distributor margins.
- Specialty Stores:Regional ingredient distributors serve smaller formulators lacking direct supplier relationships.
- Supermarkets:Mass retail channels move packaged finished goods rather than bulk isolates, limiting relevance for B2B procurement.
Direct sales leads on scale; online retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium procurement volumes while the United States anchors North American innovation infrastructure, creating divergent competitive dynamics across Atlantic markets.
Germany
Sports nutrition brands in Berlin and Hamburg are consolidating supplier relationships around single-source organic traceability. The EU F-Gas Regulation mandates 79% hydrofluorocarbon phasedown by 2030, forcing lyophilization retrofits in northern processing corridors. Ingredient startups cluster around Hamburg's port logistics and Berlin's formulation R&D hubs.
United States
Clean-label protein powder brands are accelerating procurement of high-protein isolates exceeding 85% dry weight specifications. The FDA governs allergen labeling under FALCPA provisions while USDA organic certification audits tighten supply chain documentation. Mid-sized formulators in the Pacific Northwest and Northeast Corridor are piloting direct-to-farm procurement platforms.
Belgium
Dairy alternative beverage manufacturers are reformulating with pea isolates to match casein gelation properties in lactose-free applications. REACH compliance requirements for solvent residue documentation create import friction for non-European suppliers. Organic processing facilities concentrate in Wallonia's agricultural belt near French border organic pea fields.
France
Retail chains are enforcing Bio-Siegel certification thresholds above 95% organic ingredients for premium positioning. The EU Green Deal energy standards are compressing operating margins for freeze-drying operators dependent on natural gas. Ingredient innovation clusters in the Hauts-de-France region leverage proximity to Belgian extraction infrastructure.
Canada
Alternative protein startups are blending pea isolates with cultivated fats for hybrid texture applications in cell-cultured meat. Health Canada regulates novel food authorizations while provincial agricultural programs support organic pea farming conversion. Winnipeg anchors North American pea-protein R&D through university-industry partnerships.
Freeze-Dried Pea Isolates Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers and application segments. The vendor base stratifies between scale-driven commodity suppliers and premium organic specialists serving clean-label formulators. Three archetypes dominate: European extraction infrastructure owners, North American innovation-focused pure-plays, and diversified global ingredient conglomerates. Capacity expansion in low-energy lyophilization and backward integration into organic pea farming represent the dominant competitive vectors.
Among European infrastructure owners, Roquette Frères and Cosucra Groupe Warcoing exemplify the premium organic specialist archetype, while Burcon Nutrascience Corporation anchors the North American pure-play innovation tier. These three occupy positions spanning extraction scale, certification depth, and geographic coverage without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Roquette Frères |
| Burcon Nutrascience Corporation |
| Cosucra Groupe Warcoing |
| Nutri-Pea Limited |
| Sotexpro |
| Axiom Foods |
| Ingredion Incorporated |
| Cargill |
| ADM |
| Others |
Value Network & Pricing Analysis
Natural gas costs for lyophilization facilities in Belgium and the Netherlands cascade through organic certification tiers to German sports nutrition brands, compressing margins at each processing stage while elevating price premiums for Bio-Siegel isolates.
Pricing Analysis
Capacity additions in France and Italy are reshaping price floors for conventional isolates while organic tiers hold firm. Three-tier pricing structure across premium organic, high-protein standard, and conventional economy levels dominates procurement contracts. Price differentiation centers on certification depth and protein-content precision above 85% dry weight. Pricing pressure stems from EU F-Gas Regulation compliance costs for refrigerant retrofits. Mass-market dairy alternatives exhibit highest price sensitivity; Berlin clean-label startups show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Belgian organic pea fields supplying Hamburg and Berlin formulators. Raw material flows concentrate in France, Belgium, and Italy for organic cultivation; extraction capacity clusters in Belgium and the Netherlands. Supply chains draw from hexane and ethanol solvents, natural gas feedstock for lyophilization, and specialized vacuum chamber components. Tariff exposure threatens Asian suppliers lacking ECHA-registered documentation. Distribution runs through direct-to-brand procurement platforms disintermediating traditional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between North American innovation infrastructure and European regulatory-premium capture, with EU Green Deal energy standards widening cost differentials against North American natural gas pricing.
For Market Incumbents: Deepen backward integration into organic pea farming in Wallonia and Hauts-de-France to secure three-year conversion timelines. Expand low-energy lyophilization capacity ahead of F-Gas Regulation deadlines. Soy-whey substitution threats in mass-market segments demand certification-tier defense through Bio-Siegel exclusivity. For New Entrants and Emerging Players: Capture white-space in cell-cultured meat hybridization applications blending pea isolates with cultivated fats. Target Pacific Northwest clean-label formulators seeking direct-to-farm procurement alternatives. Lead with single-field traceability documentation as the go-to-market wedge against established distributors. For Investors and Strategic Acquirers: Consolidation pressure builds where organic certification audits compound energy-intensive processing capex. Long-term viability favors specialists with captive organic supply and automated membrane filtration. Watch for F-Gas Regulation retrofit completion rates as inflection indicator for margin recovery timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Farming | Captures three-year conversion premiums and secures Bio-Siegel supply elasticity for German formulators. |
| Low-Energy Lyophilization Capacity Expansion | Reduces natural gas exposure while meeting EU F-Gas Regulation refrigerant phase-down mandates. |
| Direct-to-Brand Procurement Platform Launch | Disintermediates distributors for Hamburg and Berlin startups demanding batch-level field traceability. |
| Cell-Cultured Meat Hybrid R&D Partnership | Opens high-value application channel with alternative protein startups in Winnipeg and San Francisco. |
| Membrane Filtration Automation Deployment | Compresses isolate variability below 2% coefficient for 85%+ protein tier specifications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered extraction facility operators, sports nutrition procurement leads, organic certification auditors, and lyophilization equipment manufacturers. Secondary validation drew from ECHA REACH filings, EU F-Gas Regulation implementation reports, USDA organic certification databases, and customs trade records for pea isolate shipments. Bottom-up capacity modeling and top-down demand segmentation were triangulated for convergence.
Segment-weighting applied product type tiers, end-use application channels, and geographic regulatory clusters across the projection horizon. CAGRs were derived from installed lyophilization capacity trajectories and clean-label procurement elasticity indices. Forecast inputs included organic farming conversion timelines and EU energy standard compliance cost curves.
Energy price volatility, regulatory timeline slippage, and substitute protein technology breakthroughs are the dominant revision risks. Forecasts reflect documented assumptions on certification adoption rates and equipment replacement cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Fiber Rich Flours Market
Ingredients
Citrus Fiber Market
Ingredients
Quark Powder Market
Ingredients
Global Fruits and Vegetables Ingredients Market
Ingredients
North America Carrageenan Market
Ingredients
Global Distillers Grains Market
Ingredients
Starch-Derived Fiber Market
Ingredients
Agar Agar Flakes Market
Ingredients
South America Fats and Oil Market
Ingredients
Mulberry Leaf Extract Market
Ingredients
White Mulberry Leaves Extract Market
Ingredients
Lime Seed Oils Market
Ingredients
Alkalized Cocoa Powder Market
Ingredients
Low Calorie Olive Oil Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Global Apricot Oil Market