
 Birch Sap Market | 2026-2036
Birch Sap Market Size, Share, and Industry Trends Forecast 2026-2036
Birch Sap Market Analysis
Subscription-based seasonal delivery is repositioning birch sap from a niche forest product to a recurring wellness purchase. Nordic Koivu Ltd. leverages its Finnish supply base to anchor premium positioning in European markets. TreeVitalise competes through direct-to-consumer channels that bypass conventional retail markups. Sibberi specializes in pasteurized formats that extend shelf stability without chemical preservatives.
Birch sap consists of the clear, watery fluid harvested from Betula species during early spring dormancy break, typically containing glucose, fructose, malic acid, and trace minerals at concentrations between one and two percent dry matter; the primary commercial purpose centers on functional beverage production and cosmetic formulation bases. Filtered birch sap leads volume due to its balance of clarity and minimal processing cost, while carbonated variants represent the fastest-growing category as producers target the ready-to-drink segment. Pasteurized formats command margin pools in nutraceutical channels where microbial safety standards exceed conventional beverage thresholds.
The EU's EFSA governs health claim substantiation for birch sap products marketed with functional benefits, while the FDA regulates import classifications for non-alcoholic botanical beverages entering the United States. Organic certification under EU Regulation 2018/848 shapes harvest area eligibility and tapping method documentation. Stakeholders must monitor evolving novel food designations in key import jurisdictions before scaling distribution.
Market Dynamics
Subscription-based seasonal delivery models are restructuring birch sap from a sporadic forest commodity into a recurring wellness purchase, compressing traditional wholesale margins while expanding direct-to-consumer reach.
Growth Catalysts
- EU Farm to Fork Strategy:Tightened organic labeling requirements for forest-harvested products elevate entry barriers that favor established Finnish suppliers with documented tapping protocols.
- Carbonated ready-to-drink formats:Functional beverage producers are capturing shelf space previously held by coconut water and kombucha through effervescent birch sap variants.
- Finnish supply concentration:Traditional tapping practices in Karelia and Lapland regions anchor authenticity narratives that command premium positioning in German and French retail channels.
Market Restraints
- Input seasonality:Betula pendula and Betula pubescens sap flows concentrate in a 3-4 week window during dormancy break, constraining annual production volumes regardless of demand.
- Novel food designation uncertainty:EFSA classification pending for concentrated birch sap extracts limits expansion into fortified food applications across EU member states.
- Substitution by maple and coconut water:Established alternative beverages with year-round availability and lower per-unit logistics costs capture price-sensitive consumers in mass retail.
Strategic Opportunities
- Cosmetic formulation bases:Korean and French skincare manufacturers are incorporating birch sap into hyaluronic acid replacement formulations for sensitive-skin product lines.
- Pasteurized bulk supply to nutraceutical channels:Extended shelf-stable formats without chemical preservatives unlock B2B ingredient sales to supplement manufacturers.
- Direct-to-consumer subscription platforms:Monthly delivery models bypass conventional retail markups while capturing recurring revenue streams from health-conscious urban households.
Industry Challenges
- Harvest labor specialization:Traditional tree-tapping expertise concentrates among aging rural populations in Finland and Russia, constraining scalable workforce expansion.
- Cold chain integrity:Fresh unpasteurized sap requires continuous 2-4°C logistics from forest to consumer, elevating distribution costs for premium raw formats.
- EU Regulation 2018/848 documentation:Organic certification mandates detailed harvest area mapping and tapping method records that small-scale collectors struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Birch Sap Market |
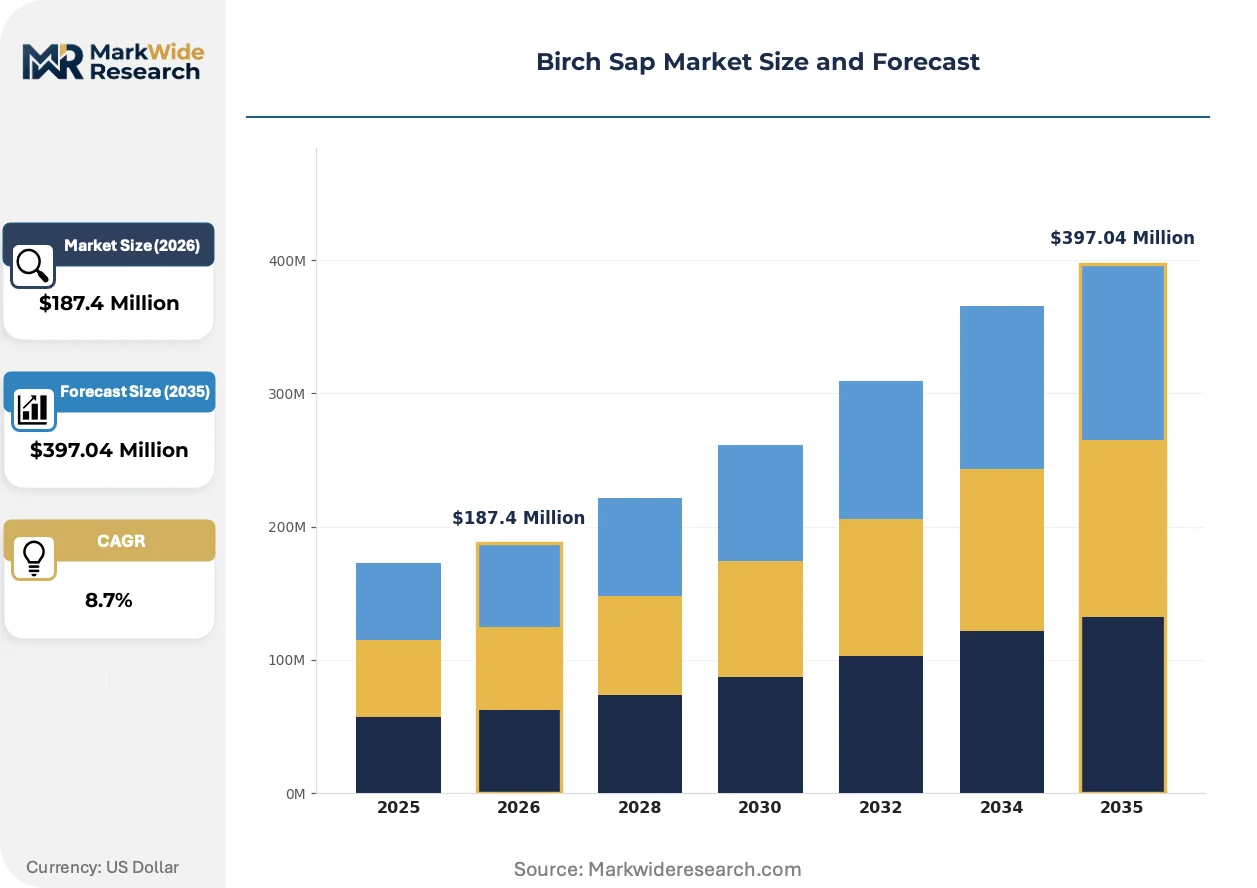
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Birch Sap, Filtered Birch Sap, Pasteurized Birch Sap, Carbonated Birch Sap End Use Application: Beverage Industry, Food Industry, Nutraceuticals, Cosmetics Industry Distribution Channel: Direct Sales, Online Retail, Supermarkets, Specialty Stores Packaging Type: Bottles, Tetra Packs, Cans, Bulk Containers |
| Companies Covered | TreeVitalise, Nordic Koivu Ltd., Sibberi, Sappy, Treo Brands, BelSeva, Sapp Inc., Birch Juice, Sealand Birk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Birch Sap Market Emerging Trajectories
Mobile-connected tapping monitoring systems and blockchain traceability protocols are reconfiguring how birch sap quality is verified and premiumized across fragmented supply networks.
Reverse osmosis concentration technology is decentralizing processing capacity from centralized Finnish facilities to regional collection hubs. Mid-scale producers in Estonia and Latvia are adopting skid-mounted membrane systems that reduce transport volumes by 80% while preserving heat-sensitive bioactive compounds. This distributed model compresses capital requirements for market entry and enables shorter harvest-to-bottle cycles.
EFSA's evolving stance on botanical health claims is tightening substantiation requirements for birch sap products marketed with renal support or detoxification benefits. Functional beverage brands must now commission human intervention studies to retain on-pack messaging, elevating R&D budgets for market incumbents. German and Austrian regulators are enforcing these standards most stringently, forcing reformulation of legacy product lines.
Health-conscious consumers are migrating from single-unit retail purchases toward curated seasonal boxes that bundle birch sap with complementary forest products like chaga and pine needle extracts. Nordic direct-to-consumer platforms capture this shift through subscription tiers that lock in harvest-period allocation. This behavioral pivot concentrates demand timing and intensifies fulfillment logistics compression during narrow spring windows.
Birch Sap Market Segmentation
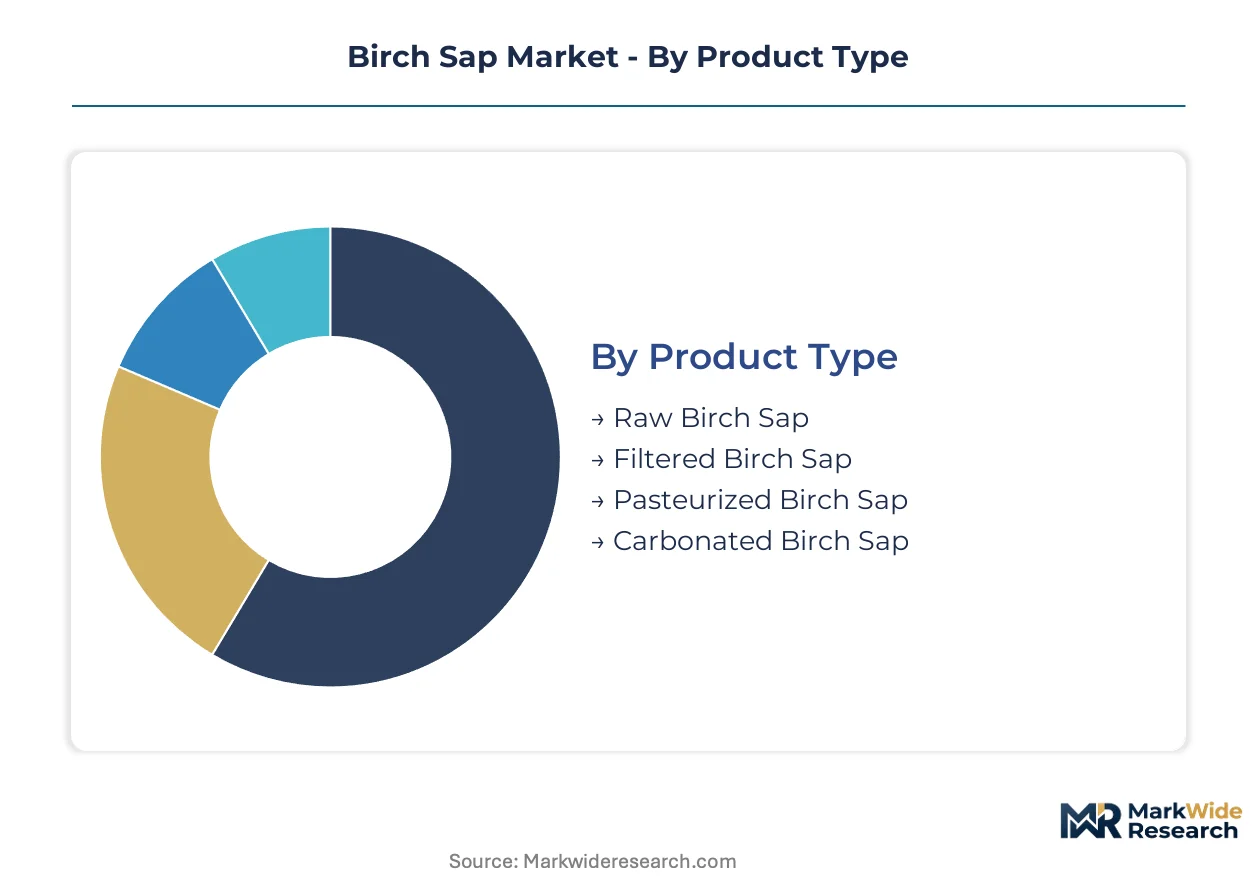
Finnish supply concentration shapes how birch sap segments command differentiated margin pools across processing intensities and channel access. Each category reflects distinct cold chain requirements, regulatory exposure, and consumer willingness-to-pay thresholds.
Product Type:
Supply concentration in Karelia and Lapland regions concentrates high-volume processing investments around formats that balance spoilage risk with bioactive preservation.
- Filtered Birch Sap:Mechanical clarification removes particulates while preserving glucose, fructose, and malic acid profiles. German and French retail channels absorb the majority of volume as this format meets conventional beverage shelf-life expectations without thermal degradation.
- Carbonated Birch Sap:Effervescent variants target ready-to-drink positioning against coconut water and kombucha. Functional beverage producers in Austria and Switzerland are capturing shelf space through carbonation that masks subtle tannic notes while extending perceived freshness.
- Raw Birch Sap:Unprocessed sap with 1-2% dry matter content requires continuous 2-4°C logistics from forest to consumer. Direct-to-consumer subscription platforms in Finnish urban centers dominate this ultra-premium tier.
- Pasteurized Birch Sap:Thermal treatment at 72-75°C eliminates microbial load for nutraceutical channels where EFSA safety standards exceed conventional beverage thresholds. B2B ingredient sales to supplement manufacturers concentrate demand here.
Filtered birch sap absorbs the bulk of installed capacity; carbonated birch sap is expanding most quickly.
End Use Application:
Cost tier differentiation separates commodity beverage feedstock from pharmaceutical-grade cosmetic bases requiring documented tapping provenance.
- Beverage Industry:Functional drink producers blend birch sap with botanical extracts for detoxification positioning. EFSA health claim substantiation requirements are tightening formulation standards across German-speaking markets.
- Cosmetics Industry:Korean and French skincare manufacturers incorporate birch sap into hyaluronic acid replacement formulations. Sensitive-skin product lines demand certified organic harvest documentation under EU Regulation 2018/848.
- Nutraceuticals:Pasteurized bulk supply serves supplement manufacturers requiring extended shelf stability without chemical preservatives. Novel food designation uncertainty for concentrated extracts limits fortified food applications.
- Food Industry:Limited adoption in fermentation bases and natural sweetener applications due to seasonal supply constraints and higher per-unit costs versus maple syrup alternatives.
Beverage industry offtake dominates current volume; cosmetics industry applications are climbing the fastest.
Distribution Channel:
Customer type fragmentation between health-conscious urban households and institutional buyers drives divergent fulfillment investments.
- Direct Sales:Producer-to-consumer relationships bypass retail markups while capturing recurring revenue through seasonal subscription tiers. Nordic platforms lock in harvest-period allocation during narrow spring windows.
- Online Retail:E-commerce penetration concentrates in metropolitan areas where cold chain last-mile capabilities justify premium positioning. Packaging innovation in insulated shippers absorbs logistics cost premiums.
- Specialty Stores:Organic and bio-focused retailers in France and Germany curate birch sap alongside complementary forest products like chaga and pine needle extracts.
- Supermarkets:Mass retail penetration remains constrained by input seasonality and substitution pressure from year-round alternatives.
Direct sales channels capture the steepest margin expansion; online retail is gaining share fastest.
Packaging Type:
Volume-to-weight economics and shelf-life extension requirements shape material selection across ambient versus chilled distribution networks.
- Bottles:Glass and PET formats dominate premium positioning in specialty retail where visual clarity signals minimal processing. Finnish producers favor amber glass for UV protection during extended supply chains.
- Tetra Packs:Aseptic carton technology enables ambient distribution for pasteurized formats targeting nutraceutical B2B channels. Estonian and Latvian regional hubs favor this format for export efficiency.
- Cans:Aluminum formats suit carbonated variants in ready-to-drink positioning. Austrian functional beverage brands are adopting cans for outdoor consumption occasions.
- Bulk Containers:Stainless steel totes and bag-in-box systems serve cosmetic and nutraceutical manufacturers requiring ingredient-scale supply with traceability documentation.
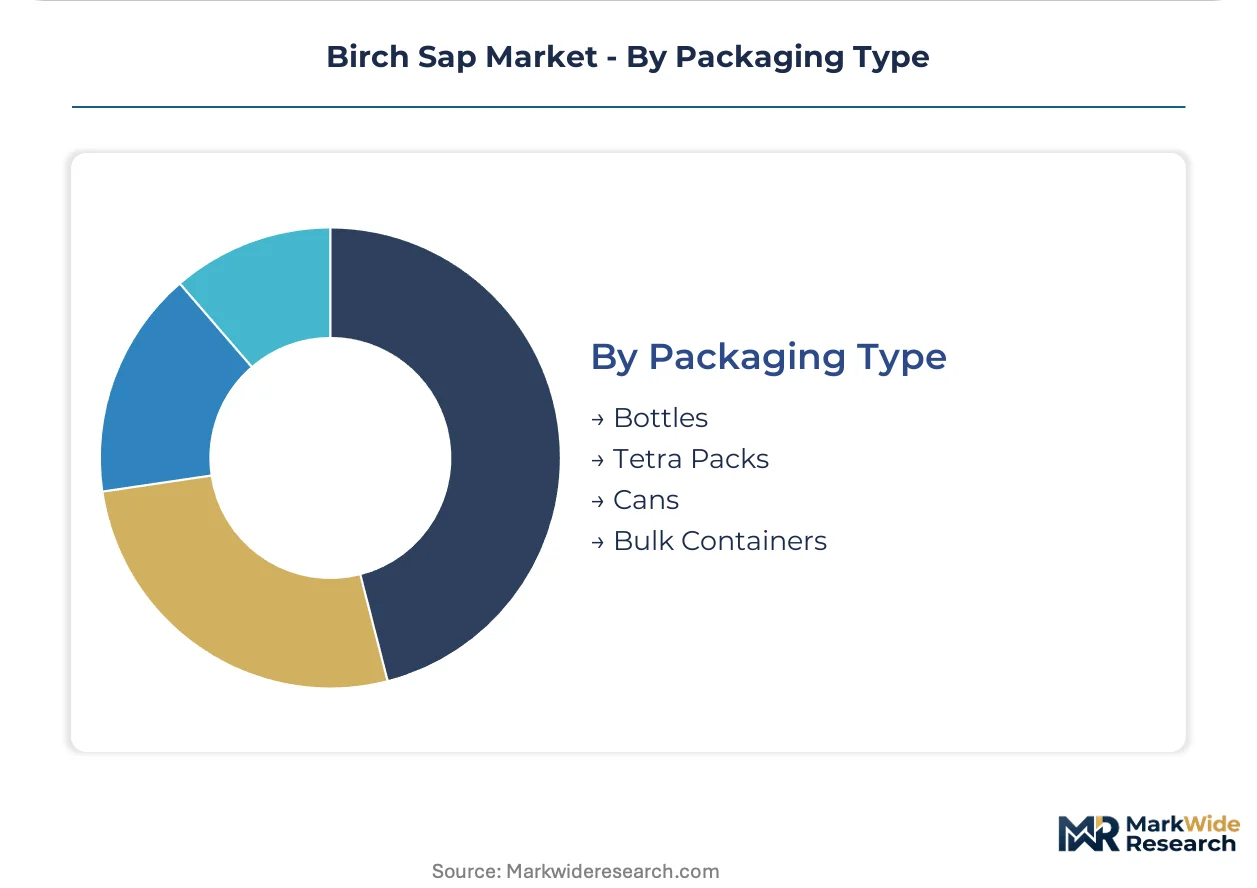
Bottles retain the largest share of premium positioning; Tetra Packs are expanding most quickly in B2B channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Karelia and Lapland anchor Finnish birch sap production, where traditional tapping expertise concentrates among forest cooperatives with documented organic protocols under EU Regulation 2018/848.
Finland
Domestic wellness subscriptions and German export demand drive volume. EFSA organic certification requirements shape harvest area eligibility. Karelia's forest cooperatives maintain tapping expertise that commands premium positioning in French retail channels.
Germany
Functional beverage brands and bio-focused retailers absorb filtered and carbonated imports. BfR enforces strict novel food assessments for concentrated extracts. Berlin's specialty retail clusters curate birch sap alongside chaga and pine needle products.
France
Cosmetic formulators and organic beverage distributors generate dual-channel demand. ANSM monitors botanical health claim substantiation for detoxification positioning. Parisian skincare manufacturers incorporate birch sap into sensitive-skin hyaluronic acid replacements.
Estonia
Regional processing hubs adopt reverse osmosis concentration to reduce transport volumes. The country's veterinary and food board aligns with EU organic documentation standards. Tartu-area membrane facilities shorten harvest-to-bottle cycles for Baltic export.
Latvia
Emerging collection networks serve pasteurized bulk supply to nutraceutical channels. Food and veterinary service regulations mirror EU 2018/848 harvest mapping requirements. Riga-region hubs leverage skid-mounted systems for B2B ingredient scale.
Birch Sap Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across birch sap value chains, with forest-integrated tappers facing off against direct-to-consumer platform operators. The market fragments across seasonal harvest constraints, compressing scale advantages toward processing technology and cold chain control. Three archetypes dominate: Finnish forest cooperatives with organic certification depth, Nordic direct-to-consumer specialists with subscription infrastructure, and private-label processors serving cosmetic and nutraceutical B2B channels. Capacity expansion and geographic diversification through Estonian and Latvian hub deployment represent the primary competitive vectors.
Within the Finnish-origin tier, Nordic Koivu Ltd. exemplifies forest-integrated supply authenticity, while TreeVitalise occupies a position in direct-to-consumer channel development. Sibberi represents pasteurized format specialization for extended shelf stability. These three anchors illustrate how competitive positioning splits between provenance documentation, platform control, and processing technology.
| Leading Market Players |
|---|
| TreeVitalise |
| Nordic Koivu Ltd. |
| Sibberi |
| Sappy |
| Treo Brands |
| BelSeva |
| Sapp Inc. |
| Birch Juice |
| Sealand Birk |
| Others |
Supply Flow & Price Mechanics
Direct-to-consumer subscription platforms concentrate buyer power among health-conscious urban households, compressing wholesale margins while anchoring value-based pricing around harvest-period authenticity and cold chain integrity.
Pricing Analysis
Subscription-tier anchoring ties price to wellness outcome delivery rather than commodity volume. Three-tier pricing structure across premium raw, standard filtered, and economy pasteurized levels separates tiers by certification depth under EU Regulation 2018/848 and cold chain investment. Cost compression in standard filtered tiers is intensifying because Estonian and Latvian regional hubs are deploying reverse osmosis concentration to bypass Finnish supply premiums. Mass retail channels exhibit highest price sensitivity; nutraceutical B2B buyers show lowest elasticity due to formulation lock-in requirements.
Supply Chain Analysis
Betula pendula and Betula pubescens sap flows rest on Finnish forest cooperative networks with documented organic protocols. Raw inputs draw from Karelia and Lapland tapping zones; processing capacity feeds from Estonian and Latvian membrane concentration hubs. Single-source vulnerability concentrates in aging rural tappers with traditional expertise. Distribution runs through direct-to-consumer platforms for premium tiers and Tetra Pack bulk channels for B2B nutraceutical offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reverse osmosis concentration technology is displacing centralized Finnish processing, compressing capital barriers for regional entrants while fragmenting provenance-based competitive moats.
For Market Incumbents: Deepen backward integration into forest cooperative tapping networks to secure harvest-period allocation against subscription platform competition. Fortify organic certification documentation under EU Regulation 2018/848 to defend margin position against Estonian and Latvian regional hub cost advantages. Lock in long-term supply agreements with German and French cosmetic formulators before novel food designation clarity opens ingredient competition.
For New Entrants and Emerging Players: The gap between ultra-premium raw subscription pricing and mass retail filtered economy tiers offers white-space entry. Target pasteurized bulk supply to nutraceutical channels where EFSA safety standards exceed conventional beverage thresholds and incumbent capacity concentrates in seasonal windows. Deploy mobile-connected tapping monitoring systems to bypass traditional expertise bottlenecks and anchor traceability narratives.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Finnish forest cooperatives with stranded organic certification assets during regional hub expansion phases. Five-to-ten year viability hinges on provenance premium durability against distributed processing cost compression. Monitor EFSA novel food designation rulings for concentrated birch sap extracts as inflection signal for fortified food application expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Reverse Osmosis Hub Deployment | Estonian and Latvian regional facilities compress transport volumes while preserving heat-sensitive bioactive compounds. |
| Blockchain Traceability Integration | Mobile-connected tapping monitoring systems verify quality across fragmented forest cooperative networks. |
| Direct-to-Consumer Platform Launch | Seasonal subscription tiers lock in harvest-period allocation and bypass conventional retail markups. |
| Cosmetic Formulation Partnership | Korean and French skincare manufacturers incorporate birch sap into hyaluronic acid replacement lines. |
| Pasteurized Bulk Capacity Expansion | Thermal treatment at 72-75°C unlocks B2B ingredient sales to supplement manufacturers requiring extended shelf stability. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this birch sap market analysis. Primary interviews with forest cooperative managers, cosmetic formulation R&D directors, nutraceutical procurement leads, and cold chain logistics operators combined with EFSA guidance documents, EU organic certification registries, and Finnish forest industry association harvest statistics. Bottom-up volume modeling triangulated against top-down category spending estimates across beverage, cosmetic, and nutraceutical end uses.
Segment-level granularity modeled product type, end use application, distribution channel, and packaging format dimensions across the projection horizon. CAGRs derived from trend extrapolation of subscription platform penetration, regional hub capacity additions, and EFSA regulatory trajectory. Forecast inputs incorporated harvest labor availability curves, cold chain infrastructure investment pipelines, and novel food designation probability assessments.
Underlying measurement precision varies by segment; direct-to-consumer subscription volumes carry tighter precision than emerging cosmetic formulation offtake. Forecasts reflect assumptions around EFSA regulatory timelines, regional hub technology adoption rates, and harvest labor succession planning. Regulatory designation shifts, climate variability affecting dormancy break timing, and substitute beverage price movements warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Gelatin Market
Ingredients
Middle East and Africa Pea Starch Market
Ingredients
European Brewing Enzymes Market
Ingredients
Gum Arabic Market
Ingredients
US Vegetable Oil Market
Ingredients
Egg Yolk Powder Market
Ingredients
Casein Hydrolysate Market
Ingredients
Shortening Fats Market
Ingredients
Salad Oil Market
Ingredients
2'-Fucosyllactose (2'-FL) Market
Ingredients
South America Malt Ingredient Market
Ingredients
Starch Market
Ingredients
Ximenia Oil Market
Ingredients
Beverage Ingredients Market
Ingredients
US Ingredients Market
Ingredients
Soybean Oil Market