
 Valerian Root Oil Market | 2026-2036
Valerian Root Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Valerian Root Oil Market Analytics
Pharmaceuticals is restructuring its share of valerian root oil offtake as cosmetics and dietary supplements gain parallel traction. Robertet Group leverages its Grasse-based extraction infrastructure to dominate European pharmaceutical-grade supply. NOW Foods competes through vertically integrated botanical sourcing across North American health channels. Young Living Essential Oils anchors premium positioning via direct-to-consumer aromatherapy distribution.
Valerian root oil is a steam-distilled essential oil derived from Valeriana officinalis rhizomes, typically containing 0.5–2.0% essential oil by dry weight with valerenic acids as marker compounds; it functions primarily as a sedative and anxiolytic agent in therapeutic and cosmetic formulations. Essential oil commands the highest margin pool due to concentration-dependent efficacy requirements in pharmaceutical applications, while dietary supplements represents the fastest-growing end user channel as consumers self-direct sleep health management. Tincture formats occupy a mature niche within health shops, though online retail is displacing specialty stores as the dominant distribution channel for direct-to-consumer valerian products.
EMA botanical drug guidelines shape European market access by mandating standardized valerenic acid content for therapeutic claims, while FDA dietary supplement regulations govern U.S. labeling and Good Manufacturing Practice compliance for sleep aid positioning. Germany's Commission E monographs further constrain product composition for reimbursement eligibility. Stakeholders must monitor evolving pharmacovigilance requirements for botanical sedatives as regulators tighten post-market surveillance frameworks across multiple jurisdictions.
Market Dynamics
EMA botanical drug guidelines are compressing market access timelines while simultaneously elevating extract quality thresholds, forcing formulators to restructure supply relationships around certified European processors.
Growth Catalysts
- Commission E Monographs:Germany's reimbursement framework validates valerian-based therapeutics for anxiety and sleep disorders, expanding prescription-channel volumes for standardized extracts.
- Steam Distillation Advances:Supercritical CO2 extraction methods are improving valerenic acid recovery rates from rhizome biomass, reducing solvent residues in pharmaceutical-grade output.
- France:ANSM oversight of herbal sleep aids under the European Traditional Herbal Medicinal Products Directive is consolidating demand around traceable French supply chains.
Market Restraints
- Raw Material Volatility:Valeriana officinalis cultivation concentrates in Eastern European contract farms, exposing processors to weather-driven rhizome yield fluctuations and spot price spikes.
- Substitution Pressure:Synthetic melatonin and L-theanine formulations are capturing shelf space in mass-market sleep aid categories, compressing valerian's addressable consumer base.
- REACH Compliance Burden:ECHA registration requirements for essential oil importers are elevating documentation costs for non-European suppliers seeking European market entry.
Strategic Opportunities
- Cosmeceutical Expansion:Anti-stress skincare formulations incorporating valerian root oil are penetrating premium French and German beauty channels, opening non-therapeutic revenue streams.
- Direct-to-Consumer Platforms:Subscription-based wellness services are bypassing traditional pharmacy distribution, enabling margin capture for branded extract suppliers.
- Swissmedic Pathway:Switzerland's streamlined botanical drug approval process offers a regulatory arbitrage route for sponsors seeking faster European market validation.
Industry Challenges
- Analytical Chemist Scarcity:Qualified personnel for valerenic acid quantification and marker compound standardization are concentrated in Grasse and Frankfurt extraction clusters, creating hiring bottlenecks.
- Batch-to-Batch Variability:Wild-harvested rhizome sourcing generates inconsistent essential oil profiles, complicating GMP compliance for pharmaceutical clients demanding certificate of analysis alignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valerian Root Oil Market |
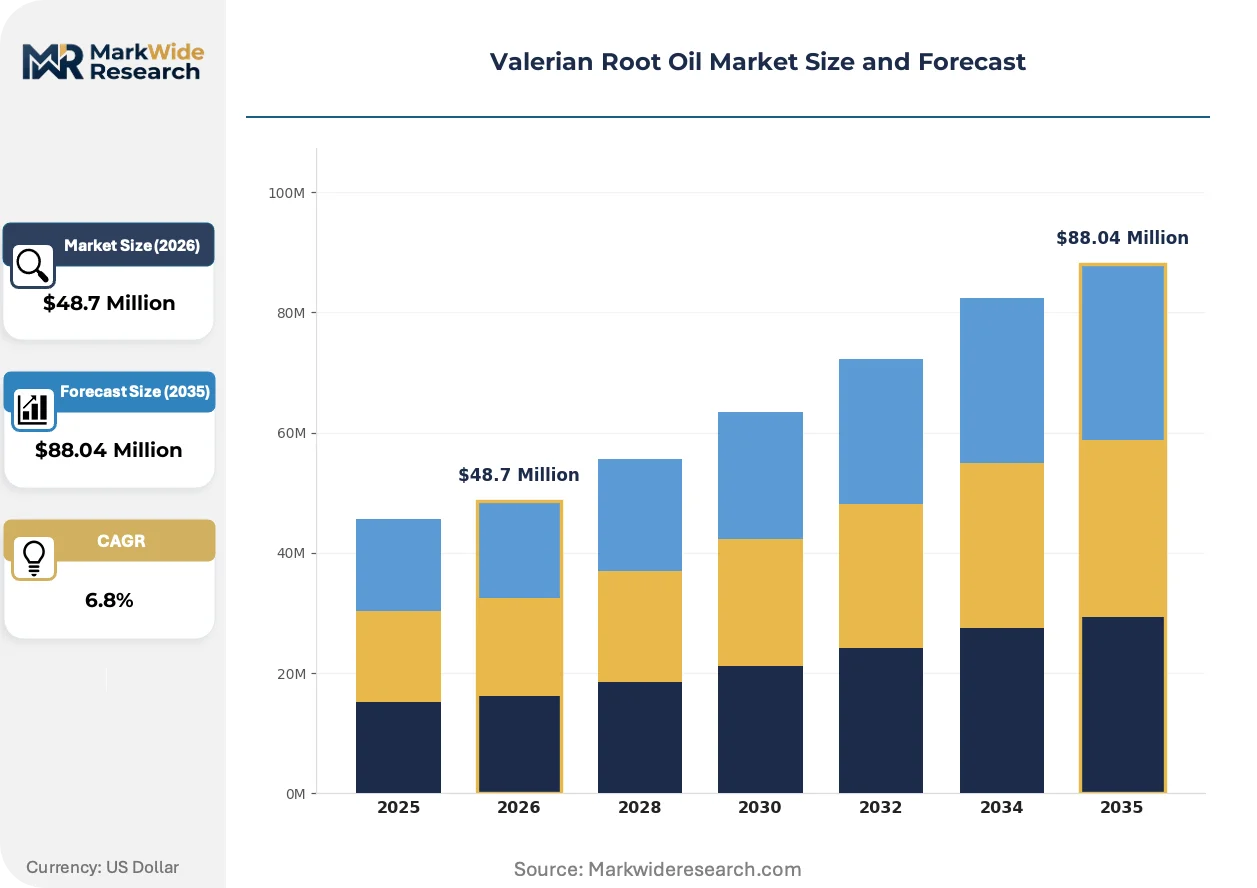
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oil, Extract, Powder, Tincture End User: Pharmaceuticals, Cosmetics, Food & Beverage, Dietary Supplements Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Shops Application: Aromatherapy, Medicinal, Skin Care, Sleep Aids |
| Companies Covered | Robertet Group, Young Living Essential Oils, doTERRA International LLC, NOW Foods, Mountain Rose Herbs, Albert Vieille, Berje, Oshadhi GmbH, Plant Therapy Essential Oils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valerian Root Oil Market Evolving Landscape
Supercritical extraction technologies are converging with digital supply chain traceability platforms, restructuring how pharmaceutical buyers verify botanical provenance and potency across multi-tier supplier networks.
CO2 extraction systems are replacing traditional steam distillation for high-potency valerian oil production. German pharmaceutical formulators are adopting these methods to meet EMA purity specifications for anxiolytic drug submissions. This technology shift is converging with blockchain-based batch tracking to compress qualification timelines for new raw material suppliers.
REACH Annex XVII restrictions on residual solvents in consumer products are tightening acceptable thresholds for hexane-extracted botanicals. French and German processors are retrofitting facilities to eliminate petrochemical solvents entirely. Essential oil grades destined for cosmetic applications face the steepest compliance burden, driving capital reallocation toward supercritical infrastructure.
Specialty retail displacement is accelerating as online wellness platforms capture sleep-aid purchasing decisions. Direct-to-consumer brands are unbundling professional consultation from product acquisition, reshaping how consumers discover and trial valerian-based solutions. This channel rotation is most pronounced in North American and Nordic markets where digital health engagement rates exceed European pharmacy loyalty.
Valerian Root Oil Market Segmentation
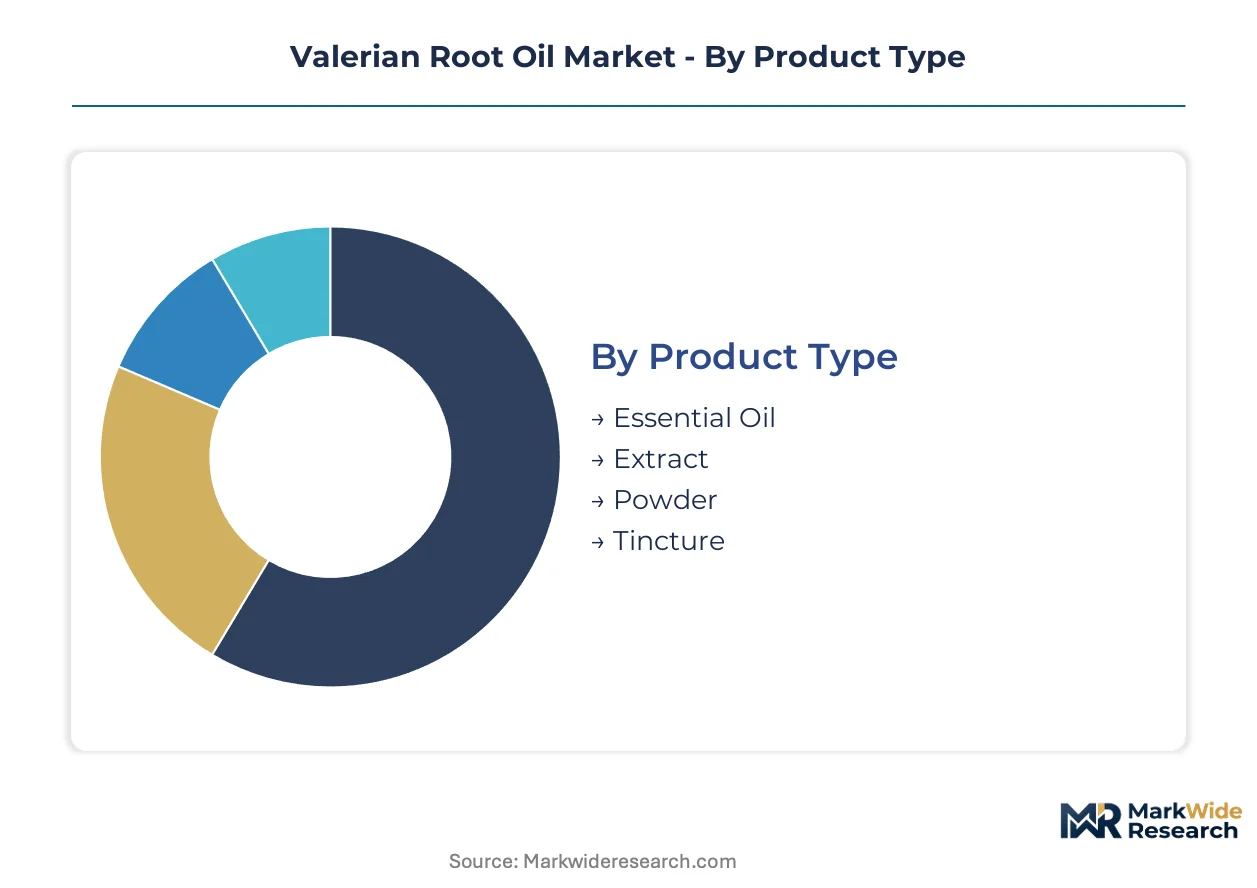
Valerian root oil segmentation reflects divergent capital requirements across extraction technologies and regulatory compliance tiers. Product type distinctions drive equipment investment decisions, while end-user channels determine certification spend and quality thresholds.
Product Type:
Essential oil extraction demands the heaviest fixed-capital commitment, with supercritical CO2 systems requiring seven-figure installation outlays versus conventional solvent infrastructure.
- Essential Oil:Steam-distilled or CO2-extracted concentrates containing 0.5–2.0% oil by dry weight with standardized valerenic acid markers. German pharmaceutical formulators under EMA botanical drug guidance command premium volumes for anxiolytic drug submissions, though REACH Annex XVII solvent restrictions are accelerating facility retrofit costs.
- Extract:Standardized preparations with defined valerenic acid content for therapeutic claims. French ANSM-registered traditional herbal medicines consolidate demand around traceable supply chains, with extraction yield variability compressing margin predictability for contract processors.
- Powder:Dried rhizome preparations for bulk supplement manufacturing. NOW Foods and comparable North American brands integrate powder into vertically controlled capsule production.
- Tincture:Alcohol-based liquid preparations occupying mature health shop distribution. German Commission E monographs validate specific tincture compositions for reimbursement eligibility.
Most installed capacity flows through Essential Oil. Expansion is steepest in Extract.
End User:
Customer-type segmentation reveals pharmaceuticals as the margin anchor, though cosmetics and dietary supplements are capturing volume growth through lower regulatory barriers.
- Pharmaceuticals:Prescription and OTC sedative formulations requiring GMP-certified production and batch-level certificate of analysis alignment. Robertet Group's Grasse infrastructure dominates European pharmaceutical-grade supply to German and French formulators.
- Dietary Supplements:Capsule, tablet, and softgel sleep aids for self-directed health management. North American direct-to-consumer platforms are displacing pharmacy channels as the primary volume driver, with subscription models capturing recurring revenue.
- Cosmetics:Anti-stress skincare and aromatherapy applications in premium French and German beauty channels. REACH compliance for residual solvents imposes steeper documentation burdens than food-grade requirements.
- Food & Beverage:Functional ingredient applications in relaxation-oriented beverages and fortified foods. Regulatory ambiguity around novel food status in Europe constrains formulation innovation.
Pharmaceuticals anchor value capture. Dietary supplements are expanding most quickly.
Distribution Channel:
Channel configuration determines working capital intensity, with online retail minimizing inventory carry versus specialty store shelf-space commitments.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capturing sleep-aid purchasing decisions. Young Living Essential Oils leverages proprietary e-commerce infrastructure for premium aromatherapy positioning.
- Specialty Stores:Dedicated herbal and natural product retailers with trained staff consultation. German health food chains maintain pharmacy-adjacent credibility for Commission E-validated products.
- Health Shops:Independent retailers with tincture and bulk herb focus. TGA-registered products in Australia concentrate in this channel alongside pharmacy distribution.
- Supermarkets:Mass-market placement for standardized supplement formats. Shelf-space economics favor high-velocity SKUs over specialty valerian preparations.
Transaction volume concentrates in Online Retail. Share gains are fastest in Health Shops.
Application:
Application segmentation tracks efficacy claim intensity, with medicinal positioning demanding the steepest evidentiary investment versus cosmetic wellness framing.
- Medicinal:Therapeutic claims for anxiety and sleep disorders requiring clinical substantiation and regulator pre-approval. Swissmedic's streamlined botanical drug pathway offers faster European validation than centralized EMA procedures.
- Sleep Aids:Dedicated insomnia and sleep quality positioning across supplement and pharmaceutical formats. Synthetic melatonin competition is compressing addressable market expansion in mass-market categories.
- Aromatherapy:Inhalation and diffusion applications for stress reduction without therapeutic claims. Direct-to-consumer essential oil brands capture margin through premium positioning and subscription replenishment.
- Skin Care:Topical anti-stress and soothing formulations in premium cosmetic channels. French formulators lead cosmeceutical incorporation of valerian root oil for sensory wellness positioning.
Regulatory investment flows through Medicinal. Commercial momentum is strongest in Sleep Aids.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting valerian root oil processing capacity toward jurisdictions with streamlined botanical drug pathways, as EMA compliance costs in core European markets pressure margin structures for extract suppliers.
Germany
Commission E monographs validate valerian-based therapeutics for anxiety and sleep disorder reimbursement, anchoring prescription-channel demand for standardized extracts. The country's national pharmaceutical regulator enforces GMP certification for botanical drug submissions. Frankfurt-Rhine-Main extraction clusters concentrate supercritical CO2 infrastructure serving EMA-compliant formulators.
France
ANSM oversight of herbal sleep aids under the Traditional Herbal Medicinal Products Directive consolidates demand around traceable domestic supply chains. REACH Annex XVII residual solvent restrictions are accelerating facility retrofits in Grasse-based processors. The Provence-Alpes-Côte d'Azur region hosts pharmaceutical-grade distillation capacity serving premium cosmetic and therapeutic channels.
Switzerland
Swissmedic's streamlined botanical drug approval process attracts sponsors seeking faster European market validation than centralized EMA procedures. The country's therapeutic goods regulator maintains mutual recognition agreements with EU member states. Basel-area formulation hubs leverage this regulatory arbitrage for anxiolytic product development.
United States
FDA dietary supplement regulations govern labeling and GMP compliance for sleep aid positioning across direct-to-consumer channels. The agency's botanical drug development guidance creates parallel compliance frameworks for therapeutic claims. Pacific Northwest cultivation zones supply raw rhizome biomass to vertically integrated North American brands.
India
CDSCO herbal drug regulations and FSSAI functional food standards shape export-oriented processing investments for European and North American buyers. The country's national pharmaceutical regulator mandates certificate of analysis alignment for botanical API shipments. Uttar Pradesh and Madhya Pradesh contract farming belts concentrate wild-harvested rhizome sourcing for international processors.
Valerian Root Oil Market Competitive Landscape
Capacity expansion dominates the current landscape as processors retrofit facilities to eliminate petrochemical solvents under REACH Annex XVII. The vendor base stratifies across three tiers: integrated fragrance houses with pharmaceutical-grade infrastructure, vertically controlled wellness brands, and specialist botanical extractors serving private-label channels. Strategic archetypes include Grasse-based extraction specialists, North American direct-to-consumer platforms, and Indian contract manufacturers. Competitive intensity concentrates on supercritical CO2 technology licensing and backward integration into rhizome cultivation.
Within the integrated fragrance house tier, Robertet Group exemplifies European pharmaceutical-grade supply positioning through its Grasse-based infrastructure. Among North American wellness platforms, NOW Foods occupies a scale-driven position through vertically controlled botanical sourcing. Young Living Essential Oils anchors premium-tier direct-to-consumer distribution via proprietary e-commerce infrastructure. These three archetypes represent divergent capital allocation strategies—fixed-asset intensity in European extraction, supply chain control in North American supplements, and brand equity capture in aromatherapy channels.
| Leading Market Players |
|---|
| Robertet Group |
| Young Living Essential Oils |
| doTERRA International LLC |
| NOW Foods |
| Mountain Rose Herbs |
| Albert Vieille |
| Berje |
| Oshadhi GmbH |
| Plant Therapy Essential Oils |
| Others |
Value Network & Pricing Analysis
Backward integration into Eastern European rhizome cultivation anchors supply security for German and French processors while compressing procurement cost volatility. This captive sourcing model concentrates pricing power among Grasse-based extraction houses that control both biomass procurement and pharmaceutical-grade distillation capacity.
Pricing Analysis
Direct-to-consumer subscription channels capture margin layers that traditional pharmacy distribution relinquishes to wholesale intermediaries. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and dietary supplement grades reflects REACH compliance burden and valerenic acid standardization intensity. Cost compression in mass-market supplement tiers intensifies because synthetic melatonin substitutes erode shelf-space economics. Direct-to-consumer wellness platforms exhibit lowest price sensitivity; contract manufacturers serving private-label supermarket brands face highest.
Supply Chain Analysis
Direct-to-OEM channels handle pharmaceutical formulator demand through certified Grasse and Frankfurt extraction clusters. Rhizome biomass concentrates in Poland, Bulgaria, and Ukraine contract farming belts. Essential oil production rests on wild-harvested rootstock, supercritical CO2 equipment, and GMP-certified distillation infrastructure. Single-source vulnerability runs through Eastern European cultivation zones exposed to climate-driven yield fluctuation. Distribution runs through pharmaceutical wholesalers, direct-to-consumer platforms, and specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Swissmedic's streamlined botanical drug pathway offers 12-18 month approval acceleration versus centralized EMA procedures, compressing time-to-revenue for sponsors willing to establish Basel-area formulation presence.
For Market Incumbents: Lock in rhizome supply through multi-year cultivation contracts in Poland and Bulgaria before climate volatility hardens procurement terms. Commission E monograph compliance investments defend German reimbursement eligibility against emerging synthetic anxiolytic substitutes. Prioritize supercritical CO2 capacity additions in Grasse to capture REACH Annex XVII-driven facility retrofit demand from solvent-dependent competitors. For New Entrants and Emerging Players: Swissmedic in Switzerland opens a window for faster European market validation than EMA centralized procedures permit. Target cosmeceutical anti-stress skincare formulations in French premium beauty channels where regulatory barriers sit below pharmaceutical tiers. Launch through subscription-based direct-to-consumer platforms to bypass pharmacy distribution margin extraction. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance capital requirements exceed standalone processor cash generation capacity. Five-to-ten year viability favors acquisition of Grasse-based extraction specialists with EMA-certified infrastructure and existing pharmaceutical customer relationships. Monitor synthetic melatonin formulation patent expirations as demand inflection signal for natural sleep aid substitution cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Grasse-based processors meet EMA purity specifications while eliminating REACH Annex XVII solvent liabilities. |
| Swissmedic Regulatory Pathway Entry | Basel-area sponsors compress botanical drug approval timelines versus centralized EMA procedures. |
| Eastern European Cultivation Integration | Polish and Bulgarian contract farming belts secure rhizome supply against climate-driven yield volatility. |
| Direct-to-Consumer Platform Launch | Subscription wellness services capture margin layers surrendered to pharmacy wholesale intermediaries. |
| Cosmeceutical Formulation Development | French anti-stress skincare channels open non-therapeutic revenue streams with lower regulatory burden. |
Research Methodology
Multiple input streams — extraction technology providers, pharmaceutical formulator procurement leads, regulatory affairs specialists at botanical drug sponsors, and specialty retail channel managers — were reconciled against secondary validation from EMA botanical drug guidance documents, ANSM traditional herbal medicine registrations, and REACH Annex XVII compliance filings. Bottom-up volume estimates from processor capacity utilization were triangulated with top-down demand projections from end-user segment analysis.
Segmentation-level outputs across essential oil, extract, powder, and tincture product types were modeled against pharmaceutical, dietary supplement, cosmetic, and food and beverage end-user channels throughout the forecast period. CAGRs were derived from annualized growth rate calculations applied to base-year value estimates. Industry-specific forecast inputs included valerenic acid standardization requirements, supercritical CO2 adoption curves, and synthetic melatonin substitution elasticities.
Revisions become necessary when EMA botanical drug guidance amendments, REACH solvent threshold modifications, or Eastern European agricultural disruption materialize. Forecasts reflect documented assumptions regarding regulatory stability, cultivation yield continuity, and substitution technology penetration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia Pacific Feed Yeast Market
Ingredients
Cold-Pressed Citrus Seed Oil Ingredients Market
Ingredients
Chicory Root Fiber Market
Ingredients
Global Fruits and Vegetables Ingredients Market
Ingredients
Cacao Extracts Market
Ingredients
Sesame Oil Market
Ingredients
Corn Oil Market
Ingredients
Soybean Meal Market
Ingredients
Agarwood Oil Market
Ingredients
Icing Shortening Market
Ingredients
Organic Edible Oil Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Oat Fiber Market
Ingredients
Macleaya Cordata Extract Market
Ingredients
Algae-Based Ingredients Market