
 Asia-Pacific Soy Protein Market | 2026-2036
Asia-Pacific Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Soy Protein Market Outlook
Chinese soy crushing and protein extraction capacity is restructuring as domestic processors expand higher-margin isolate and concentrate lines. COFCO Corporation leverages its state-backed grain origination network to secure non-GMO soybean supply chains across Heilongjiang and Inner Mongolia. Gushen Biotechnology Group anchors technical production of isolated soy protein with fermentation-derived processing advantages. Shandong Yuxin Bio-Tech competes on customized textured protein formulations for regional meat-alternative brands.
Soy protein comprises globulin and albumin fractions extracted from defatted soybean meal, typically achieving protein concentrations from fifty percent in flour to over ninety percent in isolate form through aqueous extraction and isoelectric precipitation. Its primary commercial purpose centers on emulsification, water binding, and nutritional fortification in formulated foods. Isolated soy protein commands the strongest margin pool due to premium pricing in sports nutrition and clinical applications, while textured soy protein extends fastest into plant-based meat alternatives across Southeast Asian foodservice channels. Powder form dominates industrial handling and bulk fortification workflows, though liquid concentrates gain traction in ready-to-drink dairy alternatives.
China's SAMR enforces GB standards for plant protein labeling and novel food ingredient approvals, while India's FSSAI mandates protein content disclosures and additive restrictions for soy-fortified packaged foods. Japan's MHLW through PMDA oversight influences pharmaceutical-grade protein specifications for medical nutrition products. Stakeholders must monitor how divergent national standards for genetically modified material traceability reshape cross-border ingredient sourcing and contract manufacturing arrangements.
Market Dynamics
China's tightening GB standards for plant-based food labeling are compressing product specifications across the soy protein value chain, forcing processors to upgrade extraction purity and traceability systems ahead of enforcement timelines.
Growth Catalysts
- Thailand's foodservice pivot:Plant-based meat manufacturers in Bangkok and Chiang Mai are expanding soy protein procurement as consumer diets shift away from animal products, creating dedicated supply contracts with regional crushers.
- GB standard alignment:China's SAMR enforcement of protein content disclosure rules is standardizing quality tiers, accelerating consolidation among processors capable of isolate-grade production.
- Fermentation-derived processing:Advanced enzymatic extraction methods are lowering energy costs for isolate production, enabling mid-scale facilities in Shandong to compete with integrated multinationals.
Market Restraints
- Non-GMO supply concentration:Premium identity-preserved soybean streams concentrate in Heilongjiang and Inner Mongolia, exposing processors to origination bottlenecks during harvest compression periods.
- Technical limitation in flavor masking:Residual beany off-notes in concentrate formulations persist above threshold levels for clean-label applications, restricting penetration into premium dairy alternatives.
- Regulatory friction from FSSAI:India's additive restrictions for soy-fortified packaged foods create formulation complexity for exporters targeting dual China-India product registrations.
Strategic Opportunities
- Vietnam's underpenetrated food manufacturing:Ho Chi Minh City-based meat-alternative startups lack domestic isolate supply, creating first-mover advantage for crushers establishing localized extraction capacity.
- Japan's pharmaceutical-grade specifications:PMDA oversight of medical nutrition products opens premium pricing tiers for isolate meeting injectable-grade purity standards.
- Dual carbon policy alignment:China's MEE carbon intensity targets for food processing create regulatory tailwind for fermentation-advantaged facilities with lower thermal energy footprints.
Industry Challenges
- Isoelectric precipitation expertise gap:Qualified process engineers capable of optimizing isolate yield curves remain concentrated among legacy state-owned enterprises, constraining technical talent mobility.
- Cross-border certification timelines:Simultaneous FSSAI and SAMR registration requirements for fortified food ingredients extend product launch cycles by 18-24 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Soy Protein Market |
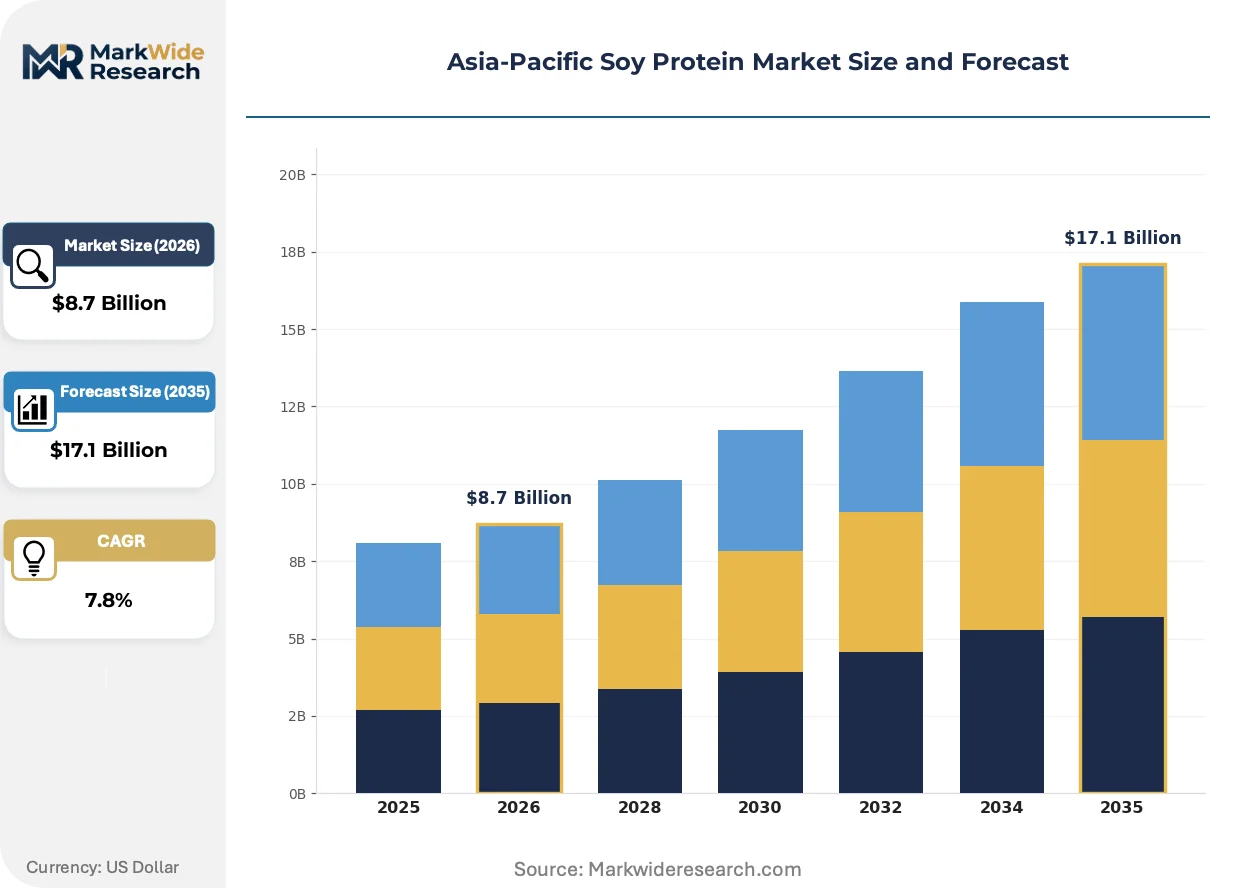
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolated Soy Protein, Soy Protein Concentrate, Textured Soy Protein, Hydrolyzed Soy Protein End User: Food & Beverage, Animal Feed, Pharmaceuticals, Nutritional Supplements Form: Dried, Liquid, Powder, Granule Application: Meat Alternatives, Dairy Alternatives, Protein Fortification, Bakery Products |
| Companies Covered | COFCO Corporation, Crown Soya Protein Group, Archer Daniels Midland Company, Gushen Biotechnology Group Co., Ltd., Shandong Yuxin Bio-Tech Co.,Ltd., Cargill, Incorporated, Bunge Limited, Sonic Biochem Extractions Pvt. Ltd., Wilmar International Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Soy Protein Market Strategic Shifts
Processing technology convergence and regulatory precision are reshaping competitive positioning across the Asia-Pacific soy protein landscape, with extraction efficiency and label compliance emerging as primary differentiation vectors.
Enzymatic debittering systems are expanding into commercial isolate production lines, replacing traditional alcohol-wash methods with targeted protease treatments that reduce solvent handling costs. Regional meat-alternative manufacturers in Vietnam and Thailand are adopting these systems at pilot scale to meet clean-label requirements from export buyers. The technology is expanding into mid-tier processor facilities previously excluded from premium isolate supply chains due to capital constraints.
China's SAMR is tightening enforcement of GB 28050 nutritional labeling standards for plant protein content claims, requiring third-party verification of protein digestibility-corrected amino acid scores. Industrial consequence includes mandatory laboratory accreditation for in-house testing facilities, raising fixed costs for smaller crushers. Sports nutrition brands targeting domestic e-commerce channels are most affected, accelerating partnerships with certified contract manufacturers in Shandong and Jiangsu.
Direct procurement relationships between foodservice chains and specialized crushers are displacing traditional distributor intermediaries in Southeast Asian plant-based meat supply chains. Bangkok-based QSR operators now contract directly with textured protein formulators for customized hydration specifications, compressing margin capture for regional trading houses. This pattern is most visible in Vietnam's expanding fast-casual segment, where end-to-end traceability requirements favor direct supplier accountability over layered distribution networks.
Asia-Pacific Soy Protein Market Segmentation
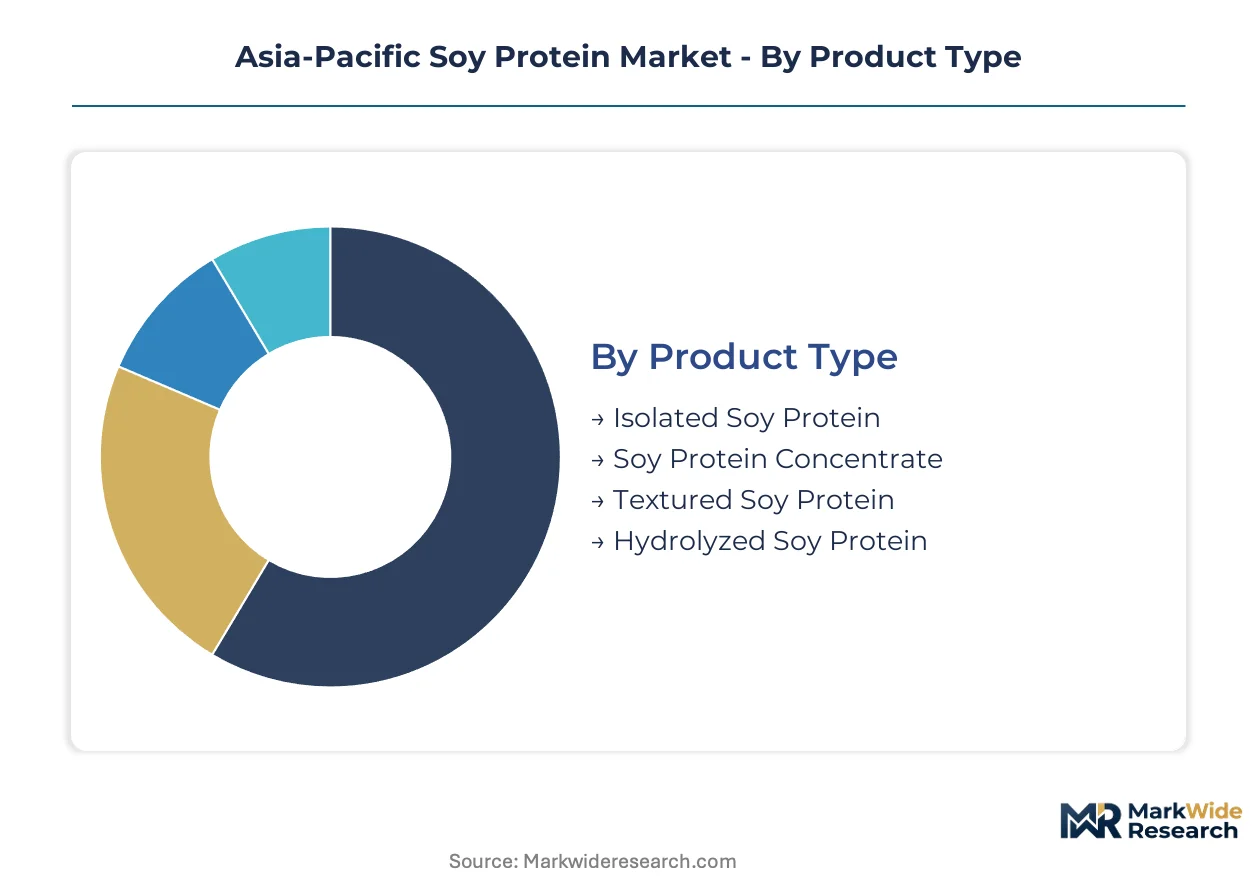
Soy protein value chains in Asia-Pacific fragment across extraction purity tiers, end-use performance requirements, and handling formats. Each segmentation axis carries distinct margin structures and regulatory compliance burdens that reshape processor investment priorities.
Product Type:
Purity thresholds and processing intensity separate buyers by margin tolerance and technical specification rigor.
- Isolated Soy Protein:Exceeds ninety percent protein concentration through isoelectric precipitation and membrane filtration. Demand concentrates in Japan's pharmaceutical-grade medical nutrition channels where PMDA purity standards command premium pricing tiers.
- Soy Protein Concentrate:Achieves sixty-five to ninety percent protein through aqueous alcohol washing. Thailand's expanding plant-based meat manufacturers in Bangkok and Chiang Mai source concentrate for cost-sensitive foodservice applications requiring emulsification stability.
- Textured Soy Protein:Extruded concentrate with fibrous structure for meat analogs. Vietnam's fast-casual chains specify customized hydration profiles from direct crusher contracts.
- Hydrolyzed Soy Protein:Enzymatically fragmented peptides for rapid absorption. Sports nutrition brands in eastern China's e-commerce channels specify hydrolyzed fractions for amino acid fortification claims.
Volume sits with Soy Protein Concentrate; growth tilts toward Isolated Soy Protein.
End User:
Formulation complexity and certification requirements stratify customers by technical service intensity.
- Food & Beverage:Dominates procurement volume across meat alternatives, dairy analogs, and bakery fortification. China's SAMR GB 28050 labeling enforcement is accelerating third-party laboratory accreditation requirements for protein content verification.
- Animal Feed:Absorbs lower-purity soy flour and concentrate fractions. Shandong and Jiangsu crushing clusters supply regional aquaculture and poultry operations with defatted meal streams.
- Pharmaceuticals:Demands injectable-grade isolate purity for medical nutrition. Japan's PMDA oversight creates specialized supply chains with extended certification timelines.
- Nutritional Supplements:Sports nutrition and clinical dietetic products require digestibility-corrected amino acid score documentation. Domestic Chinese brands partner with certified contract manufacturers to meet SAMR disclosure rules.
Food & Beverage captures current volume leadership; Nutritional Supplements demonstrates the steepest expansion trajectory.
Form:
Handling economics and shelf stability requirements drive format selection across manufacturing workflows.
- Dried:Reduced moisture content enables ambient storage and extended distribution radius. Southeast Asian trading houses favor dried concentrates for inventory flexibility across fragmented foodservice networks.
- Liquid:Ready-to-use concentrates reduce reconstitution labor in high-volume bakery and beverage operations. China's dairy alternative processors in Jiangsu province are expanding liquid handling capacity for oat-soy blend formulations.
- Powder:Standard industrial format for bulk fortification and dry blending. Dominates procurement workflows in nutritional supplements and animal feed compounding.
- Granule:Free-flowing particles for specific hydration kinetics in textured protein applications. Meat-alternative extrusion lines in Thailand specify granule geometry for consistent fiber alignment.
Powder maintains volume dominance; liquid concentrates are climbing the fastest on dairy alternative demand.
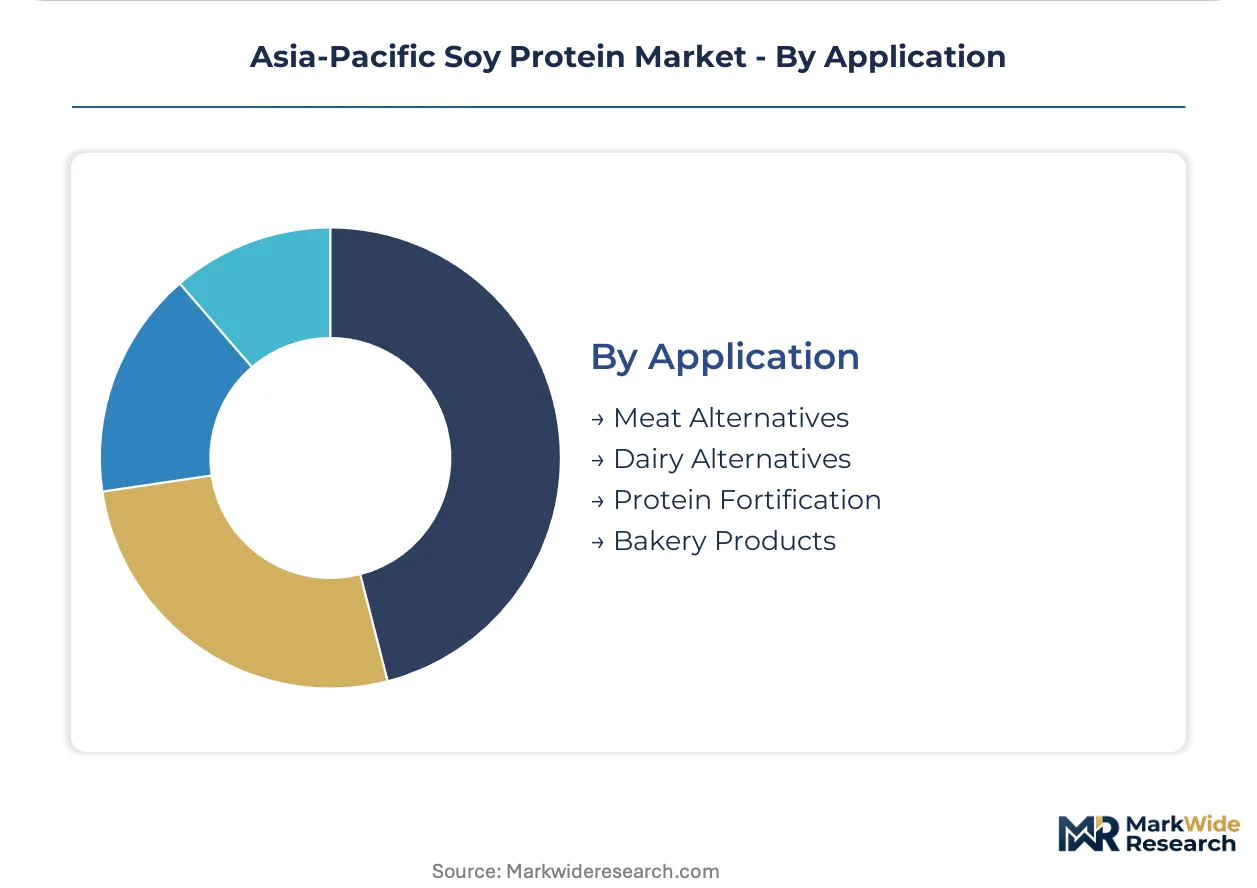
Application:
Consumer positioning and clean-label requirements differentiate end-use segments by ingredient cost tolerance.
- Meat Alternatives:Textured and isolate proteins provide fibrous structure and bite simulation. Vietnam's Ho Chi Minh City-based startups lack domestic isolate supply, creating procurement bottlenecks for premium positioning.
- Dairy Alternatives:Emulsification and protein stability requirements challenge flavor masking capabilities. Residual beany off-notes in concentrate formulations restrict penetration into premium positioning tiers.
- Protein Fortification:Powder isolates and hydrolysates fortify beverages, bars, and clinical foods. China's tightening GB standards for protein content claims are compressing specification ranges.
- Bakery Products:Water binding and dough conditioning functionality from concentrate fractions. Regional processors in Shandong supply customized hydration specifications for steamed bread applications.
Meat Alternatives holds current volume concentration; Dairy Alternatives is gaining share fastest on Southeast Asian foodservice expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heilongjiang and Inner Mongolia's non-GMO soybean belts anchor Asia-Pacific protein origination, funneling identity-preserved supply into Shandong and Jiangsu processing clusters while Southeast Asian food manufacturers build localized procurement channels.
China
Shandong and Jiangsu provinces concentrate crushing and isolate extraction capacity serving domestic sports nutrition brands and export-oriented contract manufacturers. SAMR's tightening GB 28050 protein content disclosure rules mandate third-party laboratory accreditation, raising compliance costs for smaller processors. COFCO Corporation leverages state-backed grain networks to secure Heilongjiang non-GMO streams for premium isolate production.
Japan
Pharmaceutical-grade isolate demand from medical nutrition channels commands premium pricing tiers under PMDA purity oversight. Tokyo and Osaka-based formulators specify injectable-grade specifications for clinical applications, creating specialized supply chains with extended certification timelines. Domestic processors partner with Chinese isolate producers for fermentation-advantaged technical supply.
Thailand
Bangkok and Chiang Mai plant-based meat manufacturers expand soy protein procurement as foodservice chains pivot from animal products. Direct procurement relationships with textured protein formulators displace traditional distributor intermediaries, compressing margin capture for regional trading houses. Clean-label requirements from export buyers accelerate enzymatic debittering system adoption.
Vietnam
Ho Chi Minh City-based meat-alternative startups lack domestic isolate supply, creating procurement bottlenecks for premium positioning. Fast-casual chains specify customized hydration profiles through direct crusher contracts, favoring end-to-end traceability over layered distribution networks. First-mover advantage exists for crushers establishing localized extraction capacity.
India
FSSAI additive restrictions for soy-fortified packaged foods create formulation complexity for exporters targeting dual China-India registrations. Maharashtra and Gujarat food processors navigate protein content disclosure mandates while sourcing concentrate fractions for bakery fortification. Extended registration timelines stretch product launch cycles by 18-24 months.
Asia-Pacific Soy Protein Market Competitive Environment
Global majors compete with regional champions across extraction technology tiers, with integrated agribusiness conglomerates holding origination advantages while specialized biotechnology groups capture premium isolate margins. The vendor base stratifies into three archetypes: state-backed grain processors with captive supply chains, fermentation-technical specialists commanding pharmaceutical-grade purity premiums, and customized formulators serving regional meat-alternative brands. Consolidation pressure intensifies as SAMR enforcement of GB standards accelerates among processors capable of isolate-grade production, while strategic partnerships between Southeast Asian foodservice chains and specialized crushers displace traditional distribution intermediaries.
Within the state-backed origination tier, COFCO Corporation exemplifies vertical control from Heilongjiang non-GMO belts through Shandong processing infrastructure. Gushen Biotechnology Group Co., Ltd. and Shandong Yuxin Bio-Tech Co.,Ltd. occupy positions on the technical-specialist vector, with the former representing fermentation-derived processing advantages and the latter anchoring customized textured protein formulation capabilities for regional brand supply. These three enterprises collectively illustrate how competitive positioning fragments across origination scale, extraction purity, and application-specific formulation service.
| Leading Market Players |
|---|
| COFCO Corporation |
| Crown Soya Protein Group |
| Archer Daniels Midland Company |
| Gushen Biotechnology Group Co., Ltd. |
| Shandong Yuxin Bio-Tech Co.,Ltd. |
| Cargill, Incorporated |
| Bunge Limited |
| Sonic Biochem Extractions Pvt. Ltd. |
| Wilmar International Limited |
| Others |
Value Chain & Pricing Dynamics
Captive origination from Heilongjiang non-GMO belts anchors both supply security and premium pricing power for Chinese isolate processors, creating tiered margin structures that reward upstream control over spot-market dependency. This integration pattern compresses procurement risk for SAMR-certified facilities while exposing non-integrated crushers to origination volatility during harvest windows.
Pricing Analysis
Service bundling separates certified contract manufacturers from commodity traders, with laboratory accreditation and third-party verification included in premium isolate contracts but unbundled in standard concentrate offtake. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade purity levels tracks certification intensity and PMDA alignment. Cost compression in standard concentrates is intensifying because enzymatic debittering capex requirements exclude mid-scale facilities. Regional meat-alternative manufacturers in Vietnam exhibit highest price sensitivity, while Japanese medical nutrition formulators tolerate premium tiers for injectable-grade specifications.
Supply Chain Analysis
Certification gating through SAMR laboratory accreditation and FSSAI additive compliance creates supply chain segmentation between certified contract manufacturers and uncertified commodity processors. Raw material flows concentrate in China, Thailand, and Vietnam, with Heilongjiang non-GMO streams feeding Shandong extraction clusters and Bangkok-Chiang Mai foodservice channels drawing from regional textured protein formulators. Processing draws from identity-preserved soybeans, fermentation-derived enzyme systems, and membrane filtration equipment. Single-source vulnerability concentrates in Heilongjiang origination during Q4 harvest compression. Distribution runs through direct procurement relationships displacing traditional trading house intermediaries in Southeast Asian plant-based meat supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic debittering systems are supplanting legacy alcohol-wash methods across commercial isolate production, compressing capital requirements and reshaping competitive entry barriers for mid-scale processors.
For Market Incumbents: Hedge against fermentation-technical disruption by securing captive enzyme supply partnerships or in-house protease development capabilities. COFCO Corporation's state-backed grain networks exemplify origination defense against Heilongjiang supply bottlenecks. Prioritize SAMR laboratory accreditation investment to maintain premium contract manufacturing positioning as third-party verification mandates tighten. For New Entrants and Emerging Players: Vietnam's Ho Chi Minh City-based meat-alternative startups represent an underserved buyer archetype lacking domestic isolate supply and willing to absorb technical service premiums for customized hydration specifications. First-mover advantage exists for crushers establishing localized extraction capacity with direct procurement relationships displacing layered distribution networks. Target enzymatic debittering pilot scale adoption to meet clean-label export requirements from Bangkok-based QSR operators. For Investors and Strategic Acquirers: Exit pathways concentrate in fermentation-advantaged technical specialists commanding pharmaceutical-grade purity premiums under PMDA oversight. Long-term viability over the projection horizon favors processors with dual China-Japan certification capabilities and carbon-intensity advantages aligned with MEE targets. The signal to watch is SAMR enforcement acceleration triggering consolidation among isolate-grade producers unable to absorb laboratory accreditation fixed costs.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Debittering Scale-Up | Lowers solvent handling costs for Shandong mid-tier facilities competing with integrated multinationals. |
| Non-GMO Origination Lock-In | COFCO leverages state-backed grain networks to secure Heilongjiang identity-preserved supply chains. |
| SAMR Laboratory Accreditation | Mandatory third-party verification capability raises barriers for uncertified commodity crushers. |
| Direct Procurement Relationships | Bangkok QSR operators contract specialized crushers for customized textured protein hydration profiles. |
| Fermentation-Derived Processing Investment | Gushen Biotechnology Group anchors technical production with lower thermal energy footprints. |
Study Parameters
Document review covered customs and trade data from China and Vietnam, SEC filings from listed agribusiness conglomerates, SAMR regulatory filings, and FSSAI additive restriction notices, complemented by interviews with plant managers at Shandong crushing facilities, procurement leads at Bangkok-based meat-alternative manufacturers, regulatory affairs specialists navigating dual China-India registrations, and sports nutrition brand managers in eastern China's e-commerce channels. Secondary validation drew from GB standards documentation, PMDA pharmaceutical-grade specifications, and MEE carbon intensity targets for food processing. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Output modeling produced segment-level protein volume and value trajectories across the projection horizon, with analytical frameworks tracking extraction purity tiers, end-use performance requirements, and handling format adoption curves. Segmentation dimensions included product type, end user, form, and application with regional regulatory cluster overlays. CAGRs derived from capacity expansion announcements, origination yield projections, and foodservice channel penetration rates. Industry-specific inputs encompassed enzymatic debittering adoption curves and SAMR enforcement timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Heilongjiang harvest variability, FSSAI-SAMR regulatory divergence, and fermentation technology cost curves. Forecasts reflect documented assumptions on origination yields, certification timeline standardization, and carbon policy implementation intensity. A model refresh is warranted upon material change in SAMR GB 28050 enforcement acceleration or PMDA pharmaceutical-grade specification revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Animal-Derived Ingredients Market
Ingredients
North America Whey Protein Ingredients Market
Ingredients
United States Protein Market
Ingredients
Volatile Fatty Acids Market
Ingredients
Konjac Flour Market
Ingredients
Asia-Pacific Soy Protein Concentrate Market
Ingredients
Middle East and Africa Lipids Market
Ingredients
Marine Ingredients Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
Seaweed Derivatives Market
Ingredients
Birch Sap Market
Ingredients
Synephrine Market
Ingredients
Blackcurrant Concentrate Market
Ingredients
Fermented Rennet Market
Ingredients
Grapeseed Oil Market
Ingredients
Pea Hull Fiber Market