
 India Big Data Analytics in Energy Market | 2026-2036
India Big Data Analytics in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
India Big Data Analytics in Energy Market Insights
Modular deployment of edge-computing nodes with centralized cloud dashboards is restructuring buyer choice across India's energy analytics sector. Tata Consultancy Services leverages its utility sector relationships to dominate implementation contracts for state discoms. IBM Corporation anchors its position through specialized offerings in predictive maintenance for thermal power assets. Wipro differentiates by focusing on IoT integration for renewable energy farms.
India Big Data Analytics in Energy encompasses the collection, processing, and algorithmic interpretation of high-velocity operational data from generation, transmission, and distribution systems, typically requiring latency below 100 milliseconds for grid-balancing applications and petabyte-scale storage for historical load pattern analysis. Its primary purpose is to optimize asset utilization, minimize downtime, and improve demand-supply matching across India's fragmented power network. Predictive Maintenance commands the largest service allocation as aging coal plants require failure-prevention analytics, while Load Forecasting represents the fastest-expanding application segment due to intermittent renewable injection. Machine Learning leads technology adoption, though Cloud Computing is displacing on-premise installations as discoms seek opex flexibility.
The Central Electricity Authority mandates data interoperability standards under the National Smart Grid Mission, compelling vendors to align with BIS-certified communication protocols. CEA guidelines on cyber security for power infrastructure shape product development roadmaps, while state-level renewable purchase obligations from regulators like MERC and GERC drive analytics spending in Maharashtra and Gujarat. Stakeholders must monitor how the proposed Electricity Amendment Bill alters data ownership between generators, discoms, and third-party analytics providers.
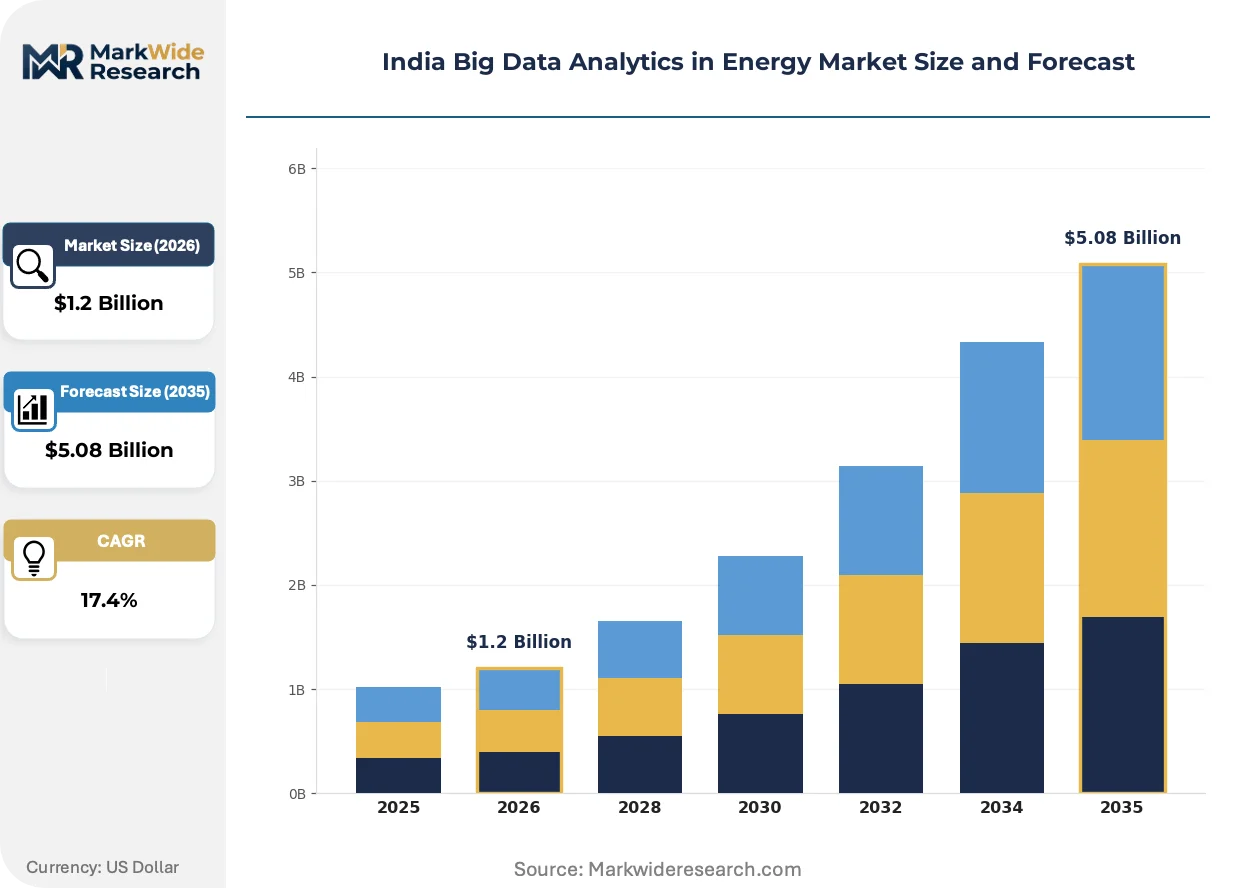
Market Dynamics
State discoms in Maharashtra, Gujarat, and Karnataka are accelerating edge-computing procurement to meet CEA-mandated latency thresholds for grid-balancing operations, compressing vendor selection cycles and reshaping deployment architectures.
Growth Catalysts
- CEA Interoperability Mandates:The Central Electricity Authority's data standards under the National Smart Grid Mission compel discoms to upgrade legacy systems, creating replacement demand for BIS-certified analytics platforms.
- Renewable Purchase Obligations:State regulators MERC and GERC enforce solar and wind integration targets that require real-time load forecasting algorithms to manage intermittency.
- Edge Computing Architectures:Modular node deployment with centralized cloud dashboards reduces transmission latency below 100 milliseconds for critical grid operations.
Market Restraints
- Legacy System Integration Costs:State-run utilities operate decades-old SCADA infrastructure that requires expensive middleware to interface with modern analytics platforms.
- Skilled Workforce Scarcity:Machine learning engineering talent concentrates in Bengaluru and Hyderabad, leaving tier-2 discom locations dependent on outsourced implementation.
- Data Sovereignty Friction:Cloud Computing adoption faces resistance from state governments wary of storing grid operational data on servers outside Indian jurisdiction.
Strategic Opportunities
- Rural Electrification Analytics:The Saubhagya scheme's last-mile connections in Bihar and Uttar Pradesh generate untapped demand for theft-detection algorithms and distribution transformer monitoring.
- Hydrogen Blending Pilots:NTPC's green hydrogen injection trials at thermal plants create demand for process analytics that optimize combustion efficiency with variable hydrogen ratios.
- Open Access Trading Platforms:The proposed Electricity Amendment Bill provisions for peer-to-peer energy trading will require blockchain-integrated settlement analytics for industrial consumers.
Industry Challenges
- Cybersecurity Certification Timelines:CEA guidelines on critical infrastructure protection require vendors to obtain multi-stage approvals that extend product launch cycles by 12-18 months.
- Interoperability Testing Complexity:Disparate communication protocols across state discoms force analytics providers to maintain multiple integration codebases, inflating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Big Data Analytics in Energy Market |
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Predictive Maintenance, Energy Management, Load Forecasting, Asset Optimization Technology: Machine Learning, Data Visualization, Cloud Computing, IoT End User: Utilities, Oil & Gas, Renewable Energy, Industrial Service Type: Consulting, Managed Services, Software Development, Training |
| Companies Covered | IBM Corporation, SAP SE, Microsoft Corporation, Siemens Aktiengesellschaft, Accenture, Infosys Limited, Tata Consultancy Services, Wipro, Oracle Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Big Data Analytics in Energy Market Trends and Innovations
Machine Learning architectures are fragmenting across deployment modes as buyers weigh latency requirements against capital constraints, while regulatory pressure on data localization accelerates domestic cloud infrastructure investment.
Edge computing for grid analytics is decentralizing data processing from centralized data centers to substation-level nodes. State discoms in Tamil Nadu and Rajasthan are deploying these architectures fastest to reduce bandwidth costs. This topology is decentralizing vendor competitive advantage toward hardware-software integration capabilities rather than pure algorithmic sophistication.
The Central Electricity Authority's cybersecurity framework for power infrastructure mandates air-gapped systems for critical generation assets. Thermal plant operators must now segment operational technology networks from enterprise IT, doubling deployment complexity. This regulation most affects predictive maintenance vendors serving NTPC and state gencos, who are reengineering products for offline model inference.
Industrial consumers in Gujarat's chemical clusters are unbundling analytics procurement from EPC contracts and contracting directly with specialized software vendors. This disintermediation bypasses traditional system integrators and shifts pricing power toward buyers with in-house data science teams. The pattern is most visible in Mundra and Dahej, where captive power plants seek granular load optimization independent of discom analytics platforms.
India Big Data Analytics in Energy Market Segmentation
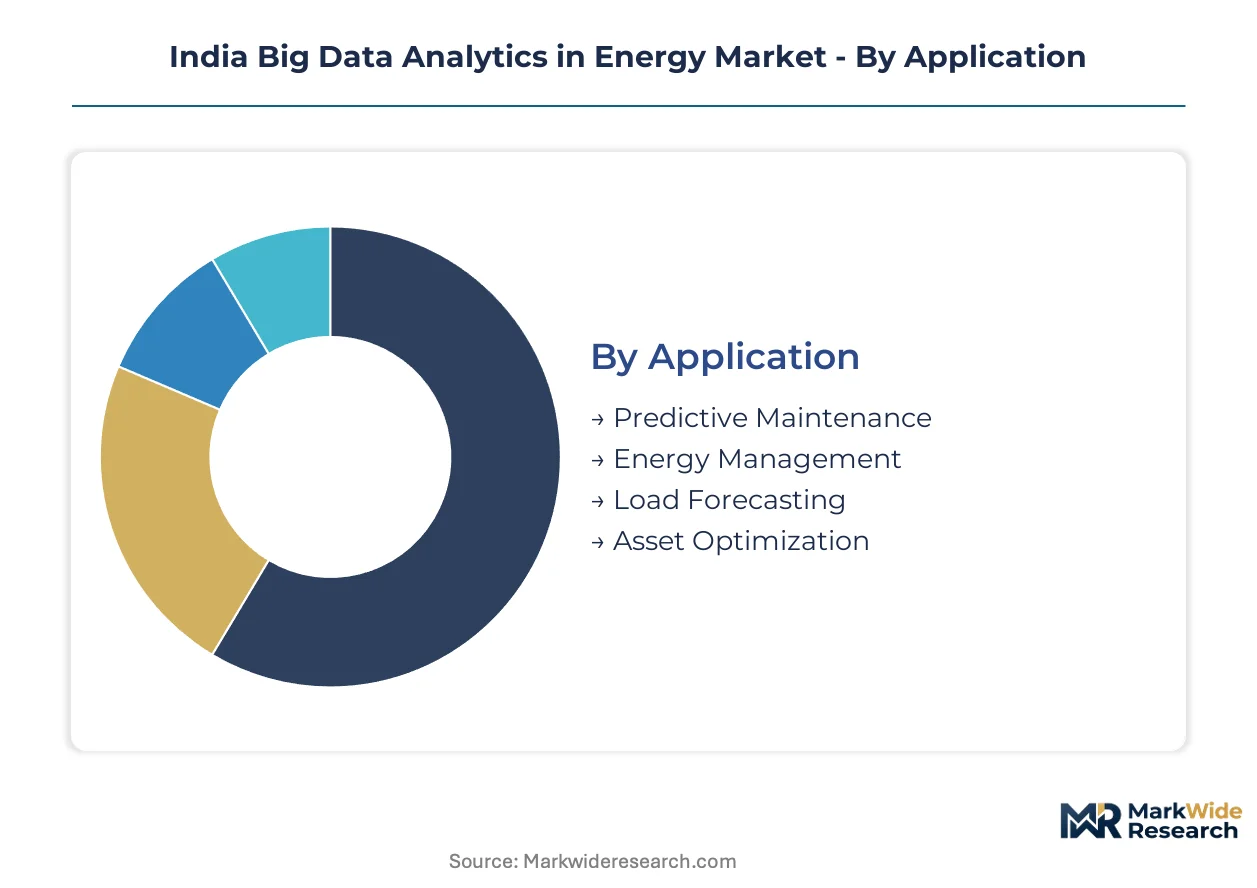
India's energy analytics market fragments across four distinct category axes. Each dimension reveals divergent procurement patterns between state-run utilities and private industrial consumers. Understanding these splits clarifies where vendor specialization creates pricing power versus where commoditization pressures compress margins.
Application:
Predictive Maintenance commands the largest revenue allocation while Load Forecasting climbs the fastest as renewable penetration accelerates intermittency management.
- Predictive Maintenance:Failure-prevention algorithms analyze vibration, thermal, and electrical signatures from aging coal plant turbines and transformers. NTPC and state gencos in Maharashtra concentrate procurement here due to CEA-mandated asset reliability targets for baseload thermal units. The segment absorbs the highest per-site deployment costs given air-gapped network requirements for critical infrastructure protection.
- Load Forecasting:Machine learning models ingest satellite weather data, historical consumption patterns, and real-time renewable generation to project demand-supply gaps. Discoms in Gujarat and Karnataka drive adoption as solar and wind variability strains grid balancing operations. MERC and GERC renewable purchase obligations mandate the forecasting accuracy improvements this segment delivers.
- Energy Management:Real-time monitoring dashboards optimize consumption across industrial microgrids and commercial complexes.
- Asset Optimization:Algorithms maximize utilization rates for transmission lines, substations, and distribution transformers.
Today's leader: Predictive Maintenance. Tomorrow's challenger: Load Forecasting.
Technology:
Machine Learning anchors current deployments while Cloud Computing displaces on-premise installations as opex flexibility outweighs data sovereignty concerns.
- Machine Learning:Supervised and unsupervised algorithms detect anomalies in SCADA streams and predict equipment degradation curves. The technology dominates R&D allocation across all major implementation vendors serving Indian utilities. BIS-certified communication protocols under the National Smart Grid Mission shape model deployment architectures.
- Cloud Computing:Scalable infrastructure-as-a-service eliminates capital-intensive server procurement for cash-constrained state discoms. Tamil Nadu and Rajasthan discoms pilot hybrid edge-cloud topologies to satisfy latency thresholds while reducing bandwidth expenditure. State government data localization requirements slow adoption in jurisdictions wary of offshore server locations.
- Data Visualization:Interactive dashboards translate complex operational metrics into actionable intelligence for control room operators.
- IoT:Sensor networks at substations and generation assets feed high-velocity data streams into centralized analytics platforms.
Machine Learning generates the deepest vendor moats. Cloud Computing opens the broadest addressable market.
End User:
Utilities dominate procurement volume while Industrial consumers unbundle analytics from EPC contracts and contract directly with specialized software vendors.
- Utilities:State discoms and generation companies constitute the foundational demand base with multi-year implementation timelines. Maharashtra State Electricity Distribution Company and Gujarat Urja Vikas Nigam anchor procurement through competitive bidding under public procurement rules. These buyers prioritize BIS-certified platforms with demonstrated interoperability across legacy SCADA infrastructure.
- Industrial:Captive power plants and energy-intensive manufacturing facilities in Mundra and Dahej chemical clusters seek granular optimization independent of discom platforms. This segment demands faster deployment cycles and outcome-based pricing models rather than perpetual license structures. In-house data science teams enable direct vendor relationships bypassing traditional system integrators.
- Renewable Energy:Solar park operators and wind farm developers require generation forecasting and grid integration analytics.
- Oil & Gas:Refineries and pipeline operators deploy process analytics for energy efficiency and predictive maintenance.
Utilities anchor volume commitments. Industrial buyers reset pricing benchmarks.
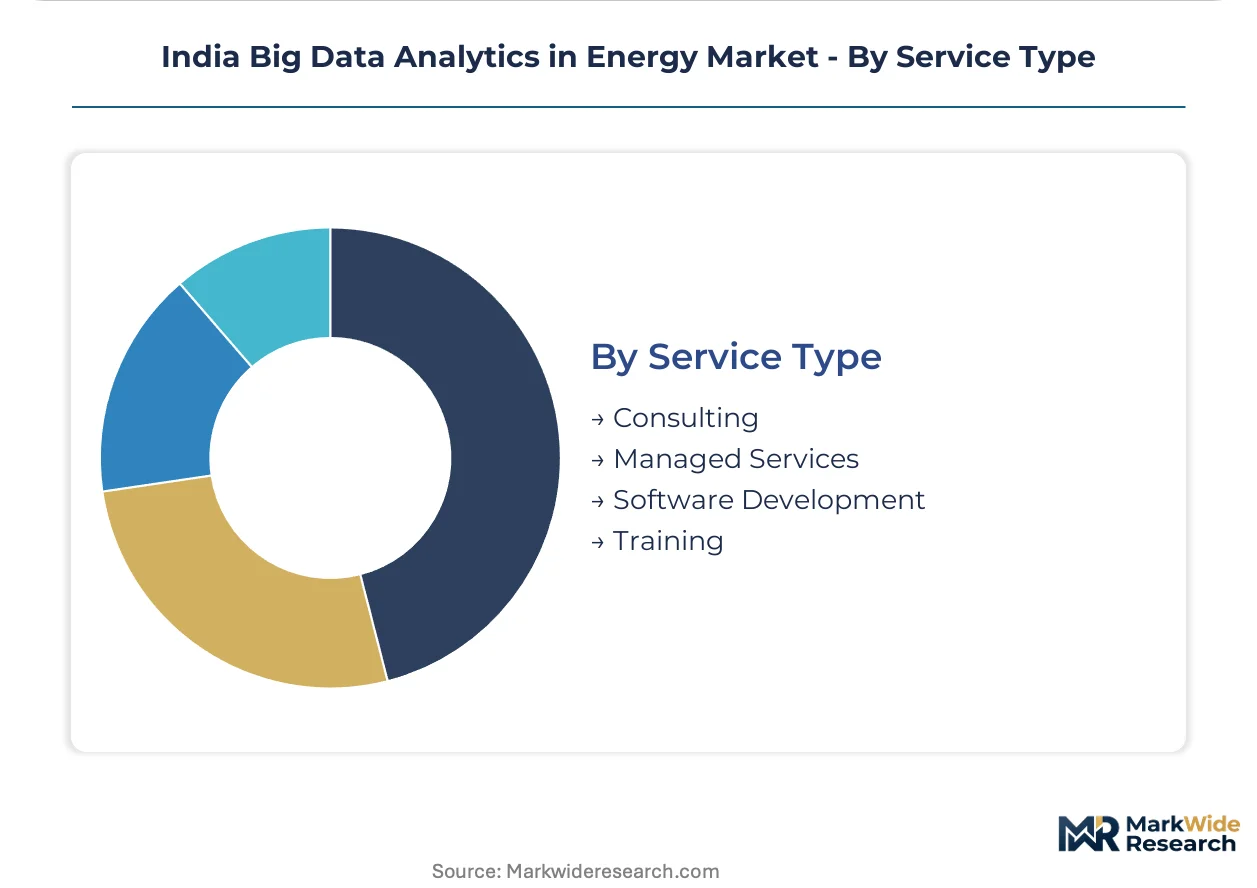
Service Type:
Software Development captures premium margins while Managed Services expands most quickly as discoms outsource operational complexity.
- Software Development:Custom platform engineering for utility-specific workflows commands the highest per-engagement value. Vendors embed proprietary algorithms into client infrastructure with multi-year maintenance contracts. The segment concentrates in Bengaluru and Hyderabad where machine learning engineering talent clusters.
- Managed Services:Outsourced platform operation and algorithm retraining relieves discoms of scarce technical workforce constraints. Tier-2 utility locations in Bihar and Uttar Pradesh drive adoption under the Saubhagya scheme's rural electrification analytics requirements. Predictable subscription revenue attracts private equity-backed vendor consolidation.
- Consulting:Advisory engagements assess analytics readiness and design implementation roadmaps for digital transformation initiatives.
- Training:Capability building programs address workforce scarcity in machine learning operations and data engineering disciplines.
Software Development extracts margin. Managed Services scales revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's energy analytics sector traces its commercial origins to the National Smart Grid Mission launched in 2015, which created the first standardized procurement frameworks for state discoms. This institutional foundation concentrated early deployment in states with the most advanced grid infrastructure.
Maharashtra
Maharashtra State Electricity Distribution Company operates India's most extensive AMI rollout, generating massive data streams from Mumbai's dense urban load centers. MERC's renewable purchase obligations mandate real-time forecasting capabilities that discoms must procure from certified vendors. The MIDC industrial corridors in Pune and Nashik anchor demand from captive power plants seeking independent optimization platforms.
Gujarat
Gujarat Urja Vikas Nigam manages the country's highest solar penetration rates, creating acute forecasting challenges for grid operators. GERC's early-mover regulations on open access trading forced discoms to deploy settlement analytics ahead of peer states. The Mundra and Dahej chemical clusters host industrial buyers unbundling analytics procurement from traditional EPC contracts.
Karnataka
Karnataka's Pavagada and Koppal solar parks generate terabyte-scale generation data requiring edge-computing architectures for latency compliance. The state's renewable-rich grid profile makes it the primary testbed for ML-based intermittency management algorithms. Bengaluru's technology workforce concentration enables direct vendor relationships bypassing system integrator markups.
Tamil Nadu
Tamil Nadu Generation and Distribution Corporation pilots hybrid edge-cloud topologies to reduce bandwidth costs across its sprawling rural network. The state's wind-solar hybrid zones create complex forecasting scenarios that demand specialized algorithmic solutions. Coimbatore's textile belt industrial consumers drive demand for microgrid optimization independent of utility platforms.
Rajasthan
Rajasthan Rajya Vidyut Prasaran Nigam manages the Bhadla solar park complex, where generation variability strains inter-state transmission scheduling. The state's desert geography enables high-capacity factor renewable assets that generate disproportionate data volumes relative to grid infrastructure maturity. Jodhpur and Bikaner industrial zones emerging as secondary demand centers for theft-detection analytics.
India Big Data Analytics in Energy Market Competitive Landscape
Premium-margin players sit above commodity-margin players across implementation complexity and regulatory certification depth. The vendor base stratifies between full-stack system integrators with utility relationships and specialized algorithm shops competing on technical differentiation. Three archetypes dominate: legacy IT conglomerates leveraging existing discom contracts, pure-play analytics specialists, and global technology platforms adapting foreign IP to Indian regulatory requirements. Consolidation pressure intensifies as CEA certification timelines favor scaled players with dedicated compliance teams.
Within the legacy IT tier, Tata Consultancy Services and Wipro occupy positions defined by decades of utility sector embeddedness. IBM Corporation anchors the global technology platform segment, adapting predictive maintenance frameworks to CEA air-gapping requirements. Among these, Infosys Limited exemplifies the mid-scale challenger archetype competing on renewable-specific IoT integration capabilities.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Microsoft Corporation |
| Siemens Aktiengesellschaft |
| Accenture |
| Infosys Limited |
| Tata Consultancy Services |
| Wipro |
| Oracle Corporation |
| Others |
Pricing and Supply Chain Analysis
CEA-mandated cybersecurity air-gapping for critical generation assets gates qualified supply to vendors capable of offline model inference, compressing the vendor pool and anchoring premium-tier pricing to certification depth rather than algorithmic sophistication alone.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales service bundling. Premium tiers command markup for BIS-certified platforms with demonstrated SCADA interoperability, while economy tiers serve cash-constrained state discoms through stripped-down SaaS modules. Cost compression in the standard tier is intensifying because global technology platforms are localizing IP to compete on implementation speed. Industrial buyers in Gujarat's chemical clusters exhibit lowest price sensitivity due to in-house data science capabilities, whereas tier-2 discoms in Bihar and Uttar Pradesh demand outcome-based pricing to bypass capital approval constraints.
Supply Chain Analysis
Domestic-content requirements under the National Smart Grid Mission are reshaping sourcing toward Indian cloud infrastructure providers and edge-computing hardware assemblers. Component supply draws from Taiwan for GPU accelerators, China for sensor assemblies, and domestic Bengaluru-Hyderabad corridors for machine learning engineering talent. Single-source vulnerability concentrates in specialized cybersecurity certification consultancies, where CEA approval timelines create 12-18 month bottlenecks. Distribution runs through state-level discom procurement portals governed by competitive bidding rules, with system integrators capturing margin on implementation complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in India's energy analytics sector rests on cloud infrastructure localization reducing offshore server dependency costs, while premium-tier buyers upgrade from perpetual licenses to managed service subscriptions.
For Market Incumbents: Anticipate disintermediation pressure from industrial buyers unbundling analytics procurement from EPC contracts by embedding proprietary algorithms deeper into utility operational workflows. Defensive consolidation should prioritize acquisition of BIS-certified niche vendors to compress CEA approval timelines. Vertical integration into edge-computing hardware assembly secures supply chain control against import dependency risks. For New Entrants and Emerging Players: CEA's National Smart Grid Mission data interoperability standards in India open a window for specialized algorithm shops to penetrate the load forecasting segment, where renewable intermittency management demands outpace incumbent capacity. White-space targets include theft-detection analytics for Saubhagya scheme rural connections and hydrogen blending process optimization for NTPC pilot plants. Direct contracting with industrial captive power plants in Mundra and Dahej bypasses system integrator markups and accelerates revenue recognition. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale implementation specialists because CEA certification timelines favor scaled players with dedicated compliance teams and recurring managed services revenue provides predictable cash flow visibility. Acquisition targets should display demonstrated interoperability across legacy SCADA infrastructure and established relationships with MERC or GERC regulators. The signal to watch as inflection indicator is passage of the Electricity Amendment Bill provisions on peer-to-peer energy trading, which would trigger demand for blockchain-integrated settlement analytics.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Hardware Localization | Domestic assembly of substation-level nodes satisfies CEA latency mandates while reducing import duty exposure. |
| Managed Services Subscription Conversion | Predictable revenue streams from tier-2 discoms in Bihar and Uttar Pradesh attract private equity consolidation capital. |
| Air-Gapped Predictive Maintenance Platform | Offline model inference capabilities meet CEA cybersecurity requirements for NTPC thermal plant contracts. |
| Renewable Forecasting Algorithm Licensing | Specialized intermittency management IP addresses GERC-mandated accuracy improvements for Gujarat solar penetration. |
| Industrial Direct Sales Channel | Bypassing EPC intermediaries in Mundra and Dahej chemical clusters captures margin from outcome-based pricing demand. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Karnataka, Tamil Nadu, and Rajasthan, with primary inputs from each state's regulatory environment and utility operational context. Primary interviews combined utility planning officers at state discoms, IPP project developers managing solar park operations, EPC contractors with analytics implementation experience, and grid operators facing renewable intermittency challenges. Secondary validation drew from CEA circulars on Smart Grid Mission standards, MERC and GERC regulatory filings on renewable purchase obligations, SEC filings of listed implementation vendors, and project development databases tracking edge-computing deployments. Bottom-up unit economics triangulated against top-down addressable market sizing across the analysis window.
Granularity-level modeling disaggregated revenue by application segment, technology deployment mode, end-user archetype, and service type, with additional dimensioning by state-level regulatory framework and grid infrastructure maturity. CAGRs were derived from logistic adoption curves fitted to historical procurement data and projected policy implementation timelines. Industry-specific forecast inputs incorporated CEA-mandated latency thresholds for grid-balancing operations and state renewable purchase obligation enforcement schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Electricity Amendment Bill passage delays or accelerated data localization enforcement. Forecasts reflect assumptions on CEA certification timeline stability, renewable capacity addition schedules, and cloud infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
Germany Big Data Analytics in Energy Market
Energy Analytics and Software
Italy Big Data Analytics in Energy Market
Energy Analytics and Software
Asia-Pacific Big Data Analytics in Energy Market
Energy Analytics and Software
Africa Big Data Analytics in Energy Market
Energy Analytics and Software
Digital Energy Platform Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market
Energy Analytics and Software
Utility Analytics and Energy Analytics Market
Energy Analytics and Software
Energy Intelligence Solutions Market
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
Power Monitoring and Control Software Market
Energy Analytics and Software
Solar Digitalization Platform Market
Energy Analytics and Software
US Big Data Analytics in Energy Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data in Oil and Gas Market