
 Canada Rigid Plastic Packaging Market | 2026-2036
Canada Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Rigid Plastic Packaging Market Insights
Canada's single-use plastics prohibition is recalibrating the cost-of-entry calculus for rigid format suppliers. Berry Global Inc. leverages its broad thermoforming footprint to serve converted food service demand under the new rules. Amcor Group GmbH anchors its position through integrated PET recycling infrastructure in Ontario. WINPAK Ltd. competes on pharmaceutical-grade barrier specifications that exceed baseline compliance thresholds.
Canada rigid plastic packaging comprises formed or molded polymer structures—typically polyethylene, polypropylene, PET, or PVC—engineered to 0.5-5 mm wall thickness for dimensional stability during filling, distribution, and retail display. These formats protect oxygen-sensitive contents through controlled permeability and enable high-speed line handling at dairy, beverage, and personal care filling plants. Bottles and containers dominate current volume given their penetration in Food & Beverage and Pharmaceuticals applications, while trays represent the fastest-expanding format as fresh protein and produce retailers shift from expanded polystyrene. PET material grades command premium positioning due to established collection and reprocessing infrastructure under provincial extended producer responsibility programs.
Health Canada, the Canadian Food Inspection Agency, and provincial extended producer responsibility frameworks collectively shape material approvals, food-contact safety thresholds, and post-consumer recovery mandates. The national plastics registry under Environment and Climate Change Canada will tighten traceability requirements for resin sourcing and recycled content claims. Stakeholders must monitor regulatory divergence between federal single-use bans and provincial packaging stewardship rules that affect format viability across Quebec, Ontario, and British Columbia distribution networks.
Market Dynamics
Health Canada's single-use plastics prohibition is compressing format viability windows while simultaneously accelerating investment in thermoformed alternatives and recycled content infrastructure across Ontario and Quebec converter networks.
Growth Catalysts
- Extended Producer Responsibility mandates:Provincial stewardship programs in Ontario, Quebec, and British Columbia create direct economic incentives for post-consumer resin integration in rigid food containers.
- Fresh protein retail format conversion:Major grocery banners are displacing expanded polystyrene trays with PET and PP alternatives to meet corporate sustainability commitments and provincial landfill diversion targets.
- Thermoforming equipment upgrades:Converters deploying next-generation thin-wall injection and pressure-forming lines achieve cycle time reductions that offset virgin resin cost premiums.
Market Restraints
- Post-consumer rPET supply scarcity:Collection infrastructure gaps in Prairie provinces limit national availability of food-grade recycled feedstock, forcing converters to import bales from US Great Lakes states.
- Regulatory fragmentation:Divergent provincial implementation timelines for plastic registry requirements under Environment and Climate Change Canada create compliance planning uncertainty for multi-provincial distributors.
- Competing substrate substitution:Fiber-based molded pulp formats are capturing prepared meal and limited-shelf-life produce applications where moisture resistance specifications permit.
Strategic Opportunities
- Pharmaceutical barrier packaging:Health Canada's evolving drug stability guidelines create specification gaps that domestic converters can fill with multi-layer PET and cyclic olefin copolymer structures.
- Atlantic Canada distribution penetration:Underdeveloped converter capacity in Nova Scotia and New Brunswick presents first-mover advantages for regional dairy and seafood packaging supply.
- National plastics registry alignment:Early compliance with traceability mandates positions suppliers for preferred procurement status with federal and provincial institutional buyers.
Industry Challenges
- Food-contact safety certification timelines:Health Canada and Canadian Food Inspection Agency review cycles for novel polymer additives extend product development schedules by 12-18 months.
- Multi-material separation infrastructure:Recovery facilities lack optical sorting capability for black PET and full-body sleeve labeled containers, contaminating bale quality and depressing rPET pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Rigid Plastic Packaging Market |
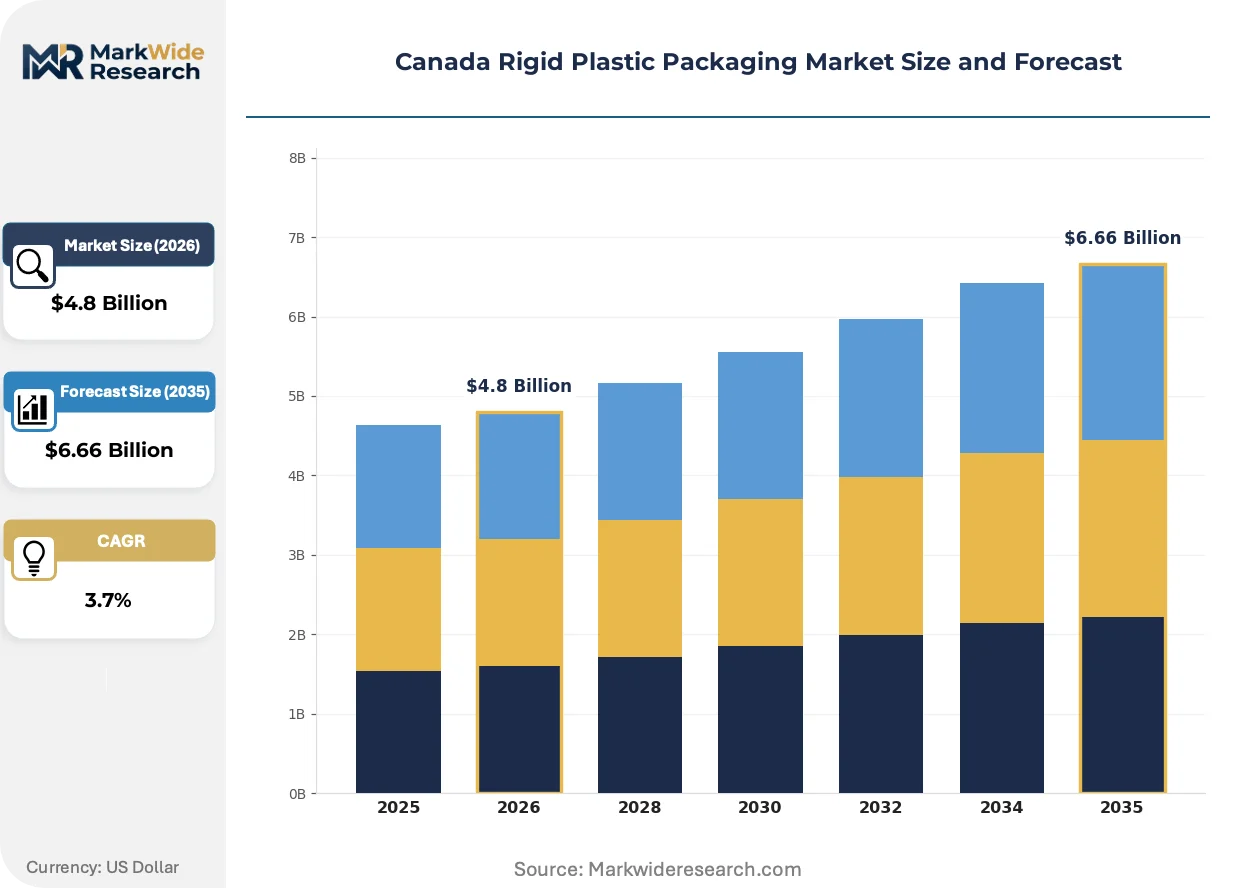
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Trays Application: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Material: Polyethylene, Polypropylene, PVC, PET End User: Manufacturers, Retailers, Wholesalers, Distributors |
| Companies Covered | Berry Global Inc., Amcor Group GmbH, Aptar Group Inc., Graham Packaging Company, Sonoco Products Company, Altium Packaging, Silgan Holdings Inc., CMG Plastics Canada, WINPAK Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Rigid Plastic Packaging Market Trends and Innovations
Digital manufacturing integration and material science advances are compressing development cycles while regulatory compliance requirements are expanding specification complexity across the Canadian converter base.
Lightweighting through finite element analysis-driven design is rewriting structural performance expectations for dairy and beverage bottles. Major processors in Ontario's Golden Horseshoe are adopting sub-20 gram PET formats for water and soft drink applications. The technology is rewriting capital allocation patterns as mold-makers and brand owners co-invest in simulation-validated tooling.
Health Canada's draft guidance on recycled plastics in food-contact applications is tightening contaminant screening protocols for mechanical recycling streams. The policy shift is elevating demand for advanced purification technologies and third-party certification. Dairy and ready-to-drink beverage categories are responding with accelerated trials of chemical recycling feedstocks.
Direct-store-delivery networks are consolidating procurement authority at regional distribution centers rather than individual plant level. This concentration is compressing supplier rosters and elevating technical service requirements. The shift is most visible in Quebec's dairy cooperative system and British Columbia's beverage bottling networks.
Canada Rigid Plastic Packaging Market Segmentation
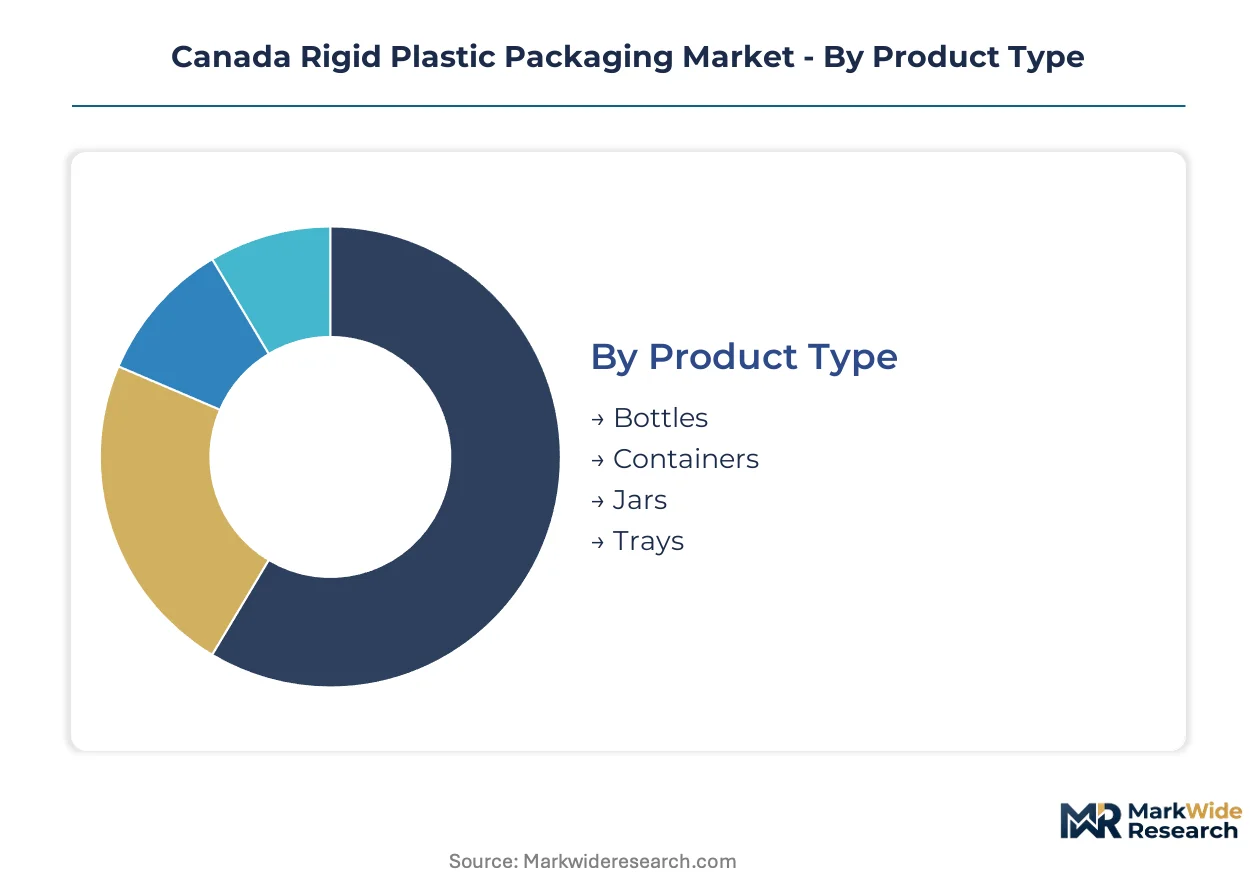
Converter investment patterns across Canada track closely to segment-specific margin profiles and regulatory exposure. Material and format choices determine compliance pathways under provincial extended producer responsibility frameworks and federal single-use restrictions.
Product Type:
Standardization dominates high-volume dairy and beverage formats while customization intensity rises in portion-controlled and specialty presentation applications.
- Bottles:Thin-wall PET constructions dominate water, soft drink, and dairy applications across Ontario's Golden Horseshoe processing corridor. Sub-20 gram formats are displacing heavier legacy designs as simulation-validated tooling spreads through converter networks. Health Canada's draft food-contact guidance for recycled content is accelerating trials of chemically recycled feedstocks in this segment.
- Trays:Thermoformed PET and polypropylene structures are capturing fresh protein and produce display applications as grocery banners abandon expanded polystyrene. Quebec and British Columbia landfill diversion targets are compressing adoption timelines for this format. The shift is rewriting procurement specifications at major retail distribution centers.
- Containers:Multi-layer barrier designs serve shelf-stable sauces, dressings, and ready-to-eat meals requiring oxygen and moisture protection.
- Jars:Wide-mouth formats concentrate in nut butter, spreads, and personal care segments where scooping access and reclosure durability matter.
Most installed capacity flows through bottles. Expansion is steepest in trays.
Application:
Volume concentration sits with shelf-stable consumables while specification complexity climbs in regulated health and personal care categories.
- Food & Beverage:Dairy processors in Ontario and Quebec drive demand for oxygen-scavenging multilayer bottles and portion-controlled formats. Direct-store-delivery consolidation at regional distribution centers is compressing supplier rosters and elevating technical service requirements for this segment.
- Pharmaceuticals:Cyclic olefin copolymer and multilayer PET structures address Health Canada's evolving drug stability guidelines for moisture and oxygen sensitivity. Domestic converters are filling specification gaps left by imported packaging in this high-margin category.
- Personal Care:Dispensing closures and decorative finishing capabilities differentiate suppliers serving shampoo, lotion, and cosmetic segments.
- Household Products:Chemical resistance and child-resistant closure compatibility dominate specification sheets for cleaning and automotive fluid containers.
Revenue concentration remains heaviest in food and beverage. Margin expansion is most pronounced in pharmaceuticals.
Material:
Collection infrastructure maturity creates tiered feedstock availability across provincial boundaries, shaping converter location decisions.
- PET:Established blue box and deposit-return systems in Ontario, Quebec, and British Columbia support food-grade mechanical recycling streams. Prairie province collection gaps force converters to import bales from US Great Lakes states, creating supply cost disparities.
- Polypropylene:Fresh protein tray conversion and dairy cup applications are expanding demand for clarified and impact-copolymer grades. Sorting infrastructure investments are improving post-consumer availability for this material.
- Polyethylene:HDPE and LDPE formats serve household chemical and personal care segments with established recycling pathways under provincial stewardship programs.
- PVC:Pharmaceutical blister and medical device packaging retains niche demand despite broader format displacement in consumer applications.
Processing volume concentrates in PET. Recycled content integration is advancing fastest in polypropylene.
End User:
Procurement authority is migrating upstream from plant-level buyers to centralized category managers, altering supplier engagement models.
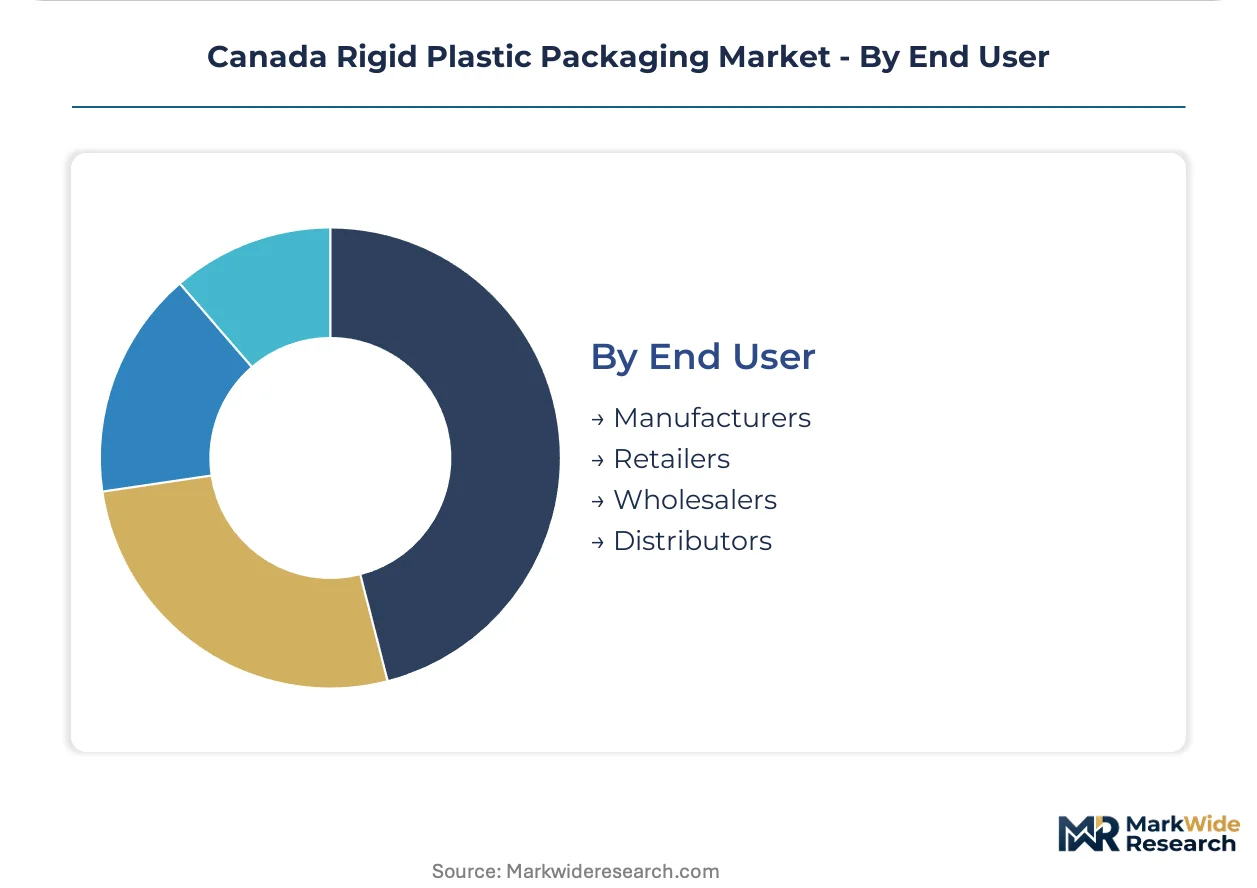
- Manufacturers:Dairy cooperatives in Quebec and beverage bottlers in British Columbia are consolidating packaging specifications across multiple production facilities. Technical service and line-speed optimization support have become table stakes for converter retention.
- Retailers:Grocery banners are imposing corporate sustainability commitments that mandate recycled content thresholds and format bans ahead of regulatory minimums. Private label development teams are engaging converters earlier in product design cycles.
- Wholesalers:Foodservice redistributors are adapting to single-use plastic prohibitions through format substitution programs and inventory consolidation.
- Distributors:Industrial and institutional channels are specifying compliance documentation for federal plastics registry alignment.
Contract value concentrates with manufacturers. Specification influence is shifting toward retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Canadian rigid plastic packaging industry traces its modern scale to post-war petrochemical expansion along the St. Lawrence Seaway, with converter networks consolidating in Southern Ontario during the 1970s to serve emerging CPG manufacturing clusters.
Ontario
Dairy processors and beverage bottlers in the Golden Horseshoe drive demand for thin-wall PET bottles and oxygen-scavenging multilayer formats. Ontario's extended producer responsibility framework mandates post-consumer recycled content thresholds that converters meet through established blue box collection infrastructure. Toronto and Hamilton anchor the densest converter concentration, where Berry Global Inc. and WINPAK Ltd. operate integrated thermoforming and injection molding facilities serving regional CPG customers.
Quebec
Fresh protein retail conversion from expanded polystyrene to PET and PP trays accelerates under provincial landfill diversion targets. The Canadian Food Inspection Agency coordinates with Quebec's environmental ministry on food-contact safety protocols for recycled content integration. Montreal and Quebec City host specialized converters supplying dairy cooperatives with portion-controlled formats and barrier specifications for shelf-stable applications.
British Columbia
Beverage bottling networks and seafood processors generate demand for high-barrier containers and modified atmosphere packaging. The province's deposit-return system for beverage containers supplies mechanical recycling feedstock that supports food-grade rPET production. Vancouver and the Lower Mainland concentrate thermoforming capacity serving Pacific Northwest export markets and domestic retail distribution.
Alberta
Petrochemical feedstock proximity attracts resin distribution and preform manufacturing operations rather than finished converter investment. Health Canada's evolving plastics regulatory framework shapes compliance planning for Alberta-based suppliers shipping into Ontario and Quebec markets. Calgary serves as a logistics hub connecting Prairie agricultural processors to packaging supply chains headquartered in Central Canada.
Atlantic Canada
Underdeveloped converter capacity in Nova Scotia and New Brunswick creates supply gaps for regional dairy and seafood packaging demand. Federal single-use plastics prohibitions compress format viability windows for foodservice distributors operating in Halifax and St. John's. First-mover investment in thermoforming infrastructure could capture procurement consolidation at regional distribution centers serving Maritime retail banners.
Canada Rigid Plastic Packaging Market Competitive Landscape
The competitive structure tilts toward integrated multinational suppliers with captive resin access and regional specialists with deep technical service capabilities. Three to five global packaging conglomerates anchor volume supply through Ontario-based manufacturing assets, while mid-tier Canadian converters compete on pharmaceutical-grade barrier specifications and rapid tooling turnaround. Strategic archetypes include resin-integrated volume players, barrier technology specialists, and regional service-focused converters. Dominant competitive moves encompass recycling infrastructure partnerships and thermoforming equipment upgrades that compress cycle times.
Within the multinational tier, Berry Global Inc. and Amcor Group GmbH exemplify resin-integrated positioning through broad thermoforming footprints and established collection infrastructure. WINPAK Ltd. occupies a specialist position among domestic converters, anchoring pharmaceutical barrier capabilities that exceed baseline regulatory thresholds. CMG Plastics Canada represents the mid-market regional archetype, serving food and beverage customers with shorter lead times and customized format development.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor Group GmbH |
| Aptar Group Inc. |
| Graham Packaging Company |
| Sonoco Products Company |
| Altium Packaging |
| Silgan Holdings Inc. |
| CMG Plastics Canada |
| WINPAK Ltd. |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade barrier certification and commodity food-service formats have diverged into distinct pricing ecosystems, with Health Canada's evolving food-contact safety protocols widening the premium gap while Ontario's EPR mandates compress margins on standardized containers. This bifurcation reshapes procurement patterns as converters choose between investing in cyclic olefin copolymer multilayer capacity or competing on thin-wall PET cycle-time efficiency.
Pricing Analysis
Bundled technical service contracts dominate dairy and beverage procurement in Quebec's cooperative networks, while unbundled transactional pricing prevails in Atlantic Canada's fragmented wholesaler base. Three-tier pricing structure across premium, standard, and economy levels tracks material purity grades and recycled content certification tiers. Pricing pressure stems from Prairie province rPET import dependencies that elevate feedstock costs above Ontario's blue-box-served converters. Foodservice distributors exhibit highest price sensitivity due to single-use prohibition compliance deadlines, while pharmaceutical contract manufacturers prioritize barrier performance over unit cost.
Supply Chain Analysis
Freight cost differentials between US Great Lakes rPET bale sources and Ontario converter clusters have elevated logistics to a primary site-selection factor, with Hamilton and Toronto maintaining density advantages. Supply concentrates in Ontario for finished thermoformed formats, in Alberta for resin distribution and preform manufacturing, and in British Columbia for Pacific Northwest export-oriented capacity. Raw material flows draw from Texas Gulf Coast virgin resin, Michigan mechanical recycling facilities, and emerging chemical recycling pilots. Single-source vulnerability sits with black PET and full-body sleeve labeled container streams that lack optical sorting infrastructure. Distribution runs through regional dairy cooperative distribution centers and grocery banner procurement consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Health Canada's draft recycled plastics guidance is forcing specification upgrades that favor converters with advanced purification capabilities and third-party certification infrastructure.
For Market Incumbents: To counter fiber-based molded pulp substitution in prepared meal applications, Berry Global Inc. and Amcor Group GmbH should deepen backward integration into chemical recycling feedstock partnerships that secure food-grade rPET supply independent of Prairie collection gaps. Thermoforming equipment upgrades that achieve sub-20 gram PET cycle times serve as the priority defensive lever against imported packaging from US Great Lakes competitors.
For New Entrants and Emerging Players: Regional distribution centers serving Maritime grocery banners present the most penetrable white-space target, as Nova Scotia and New Brunswick converter capacity remains underdeveloped relative to dairy and seafood packaging demand. First-mover investment in thermoforming infrastructure aligned with federal plastics registry traceability mandates secures preferred procurement status. A technical service-heavy engagement model compensates for scale disadvantages against Ontario-based incumbents.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier Canadian converters possessing pharmaceutical barrier specifications that exceed baseline Health Canada thresholds and shorter tooling turnaround capabilities than multinational volume players. Long-term viability hinges on positioning for chemical recycling feedstock adoption as mechanical recycling streams face tightening contaminant protocols. The signal to watch is provincial implementation timelines for plastic registry requirements that will accelerate supplier roster consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Feedstock Partnership | Secures food-grade rPET supply independent of Prairie collection infrastructure gaps. |
| Thermoforming Equipment Upgrade | Compresses cycle times for sub-20 gram PET formats serving Ontario dairy processors. |
| Pharmaceutical Barrier Certification Investment | Positions converters to fill specification gaps under Health Canada's evolving drug stability guidelines. |
| Atlantic Canada Distribution Center Partnership | Captures procurement consolidation at regional hubs serving Maritime retail banners. |
| Federal Plastics Registry Early Compliance | Elevates traceability documentation for preferred status with institutional buyers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with converter plant managers, dairy cooperative procurement leads, grocery banner category buyers, resin distribution specialists, and Health Canada regulatory affairs officers with secondary validation through provincial EPR program reports, Environment and Climate Change Canada plastics registry documentation, and customs trade data on US Great Lakes rPET bale movements. Bottom-up capacity assessments at Ontario and Quebec thermoforming facilities were triangulated against top-down demand modeling from food and beverage processing volumes.
Comparable-period anchoring tied projection assumptions to historical EPR mandate implementation patterns and single-use prohibition phase-out timelines across provincial jurisdictions. The analytical framework segmented by material grade, format type, application category, and end-user procurement authority structure across the modeling period. CAGRs were derived from elasticity-adjusted demand curves incorporating fresh protein retail format conversion rates and pharmaceutical packaging specification evolution. Industry-specific inputs included optical sorting infrastructure deployment schedules and chemical recycling pilot project announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Health Canada final guidance on recycled plastics in food-contact applications and Prairie province collection infrastructure investment decisions. Forecasts reflect documented assumptions about regulatory implementation timelines and feedstock availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Rigid Packaging Market
Rigid Packaging
Saudi Arabia Rigid Plastic Packaging Market
Rigid Packaging
Collapsible Rigid Containers Market
Rigid Packaging
GCC Rigid Packaging Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Rigid Food Packaging Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
US Rigid Thermoform Plastic Packaging Market
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
UAE Rigid Plastic Packaging Market