
 United States HVAC Equipment and Services Market | 2026-2036
United States HVAC Equipment and Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States HVAC Equipment and Services Market Analytics
Domestic heat pump manufacturing capacity is pivoting toward cold-climate variants as electrification mandates tighten across northern states. Carrier Global Corporation leverages its compressor technology leadership to anchor positions in commercial chiller replacement cycles. Trane Technologies competes through building automation integration that extends beyond hardware into energy-as-a-service contracts. Daikin Industries specializes in variable refrigerant flow systems that dominate high-rise multifamily installations in dense urban corridors.
United States HVAC equipment and services encompasses mechanical systems designed to regulate indoor temperature, humidity, and air quality through vapor-compression refrigeration cycles, forced-air distribution networks, and building management interfaces operating between 40°F and 450°F depending on application. These systems serve commercial offices, industrial process facilities, and residential structures where thermal comfort, ventilation compliance, and energy efficiency directly affect occupant productivity and operational cost structures. Heat pumps represent the fastest-expanding product category as cold-climate performance thresholds improve and electrification incentives flow through state energy offices. The service type dimension shows replacement and retrofit activity generating disproportionate margin pools compared to new construction installations, reflecting aging stock in the Northeast and Midwest building bases.
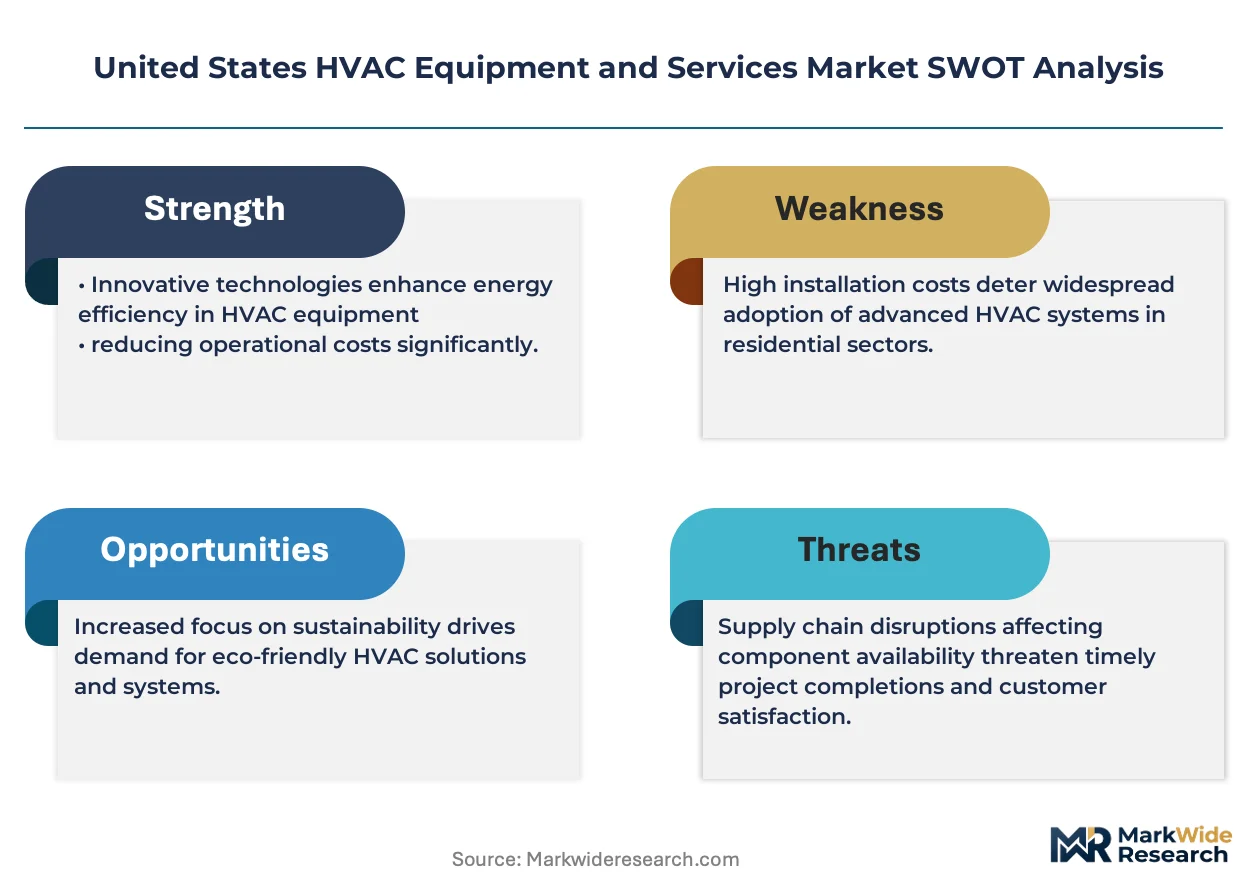
The EPA enforces refrigerant phaseout schedules under the AIM Act that force OEMs to redesign sealed systems around lower-GWP alternatives like R-454B and R-32. DOE appliance efficiency standards ratchet minimum performance coefficients upward on a regional basis, compelling manufacturers to maintain multiple product tiers for compliance across climate zones. Stakeholders must monitor state-level building electrification mandates and utility demand-response programs that will determine whether gas-fired furnaces retain share or cede ground to electric heat pumps in the residential replacement channel.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is forcing OEMs to redesign sealed systems around lower-GWP alternatives, compressing product development cycles and reshaping competitive positioning across equipment tiers.
Growth Catalysts
- Electrification mandates:State energy offices in New York, Massachusetts, and Washington are tightening building decarbonization timelines that accelerate heat pump deployment in residential replacement channels.
- Data center expansion:Virginia's Loudoun County and Texas's Dallas-Fort Worth corridor are adding hyperscale facilities that demand precision cooling systems matched to AI server density requirements.
- Sun Belt migration:Population inflow to Florida, Arizona, and Texas is outpacing national construction averages, concentrating new HVAC installation demand in high-cooling-load climate zones.
Market Restraints
- Copper and aluminum volatility:Raw material price swings in coil and tubing inputs compress margin visibility for equipment manufacturers and distributors holding inventory.
- Compressor supply concentration:Domestic production of high-efficiency rotary and scroll compressors depends on concentrated Asian component sourcing, exposing lead time risk.
- R-454B compatibility limits:Lower-flammability refrigerant transitions require redesigned heat exchangers and safety controls that extend equipment validation timelines.
Strategic Opportunities
- Cold-climate heat pump penetration:Minnesota, Maine, and Vermont represent underpenetrated northern markets where DOE Cold Climate Heat Pump Challenge winners are expanding rated capacity below 5°F.
- Utility demand-response integration:Grid-interactive water heaters and thermostats create recurring revenue streams through FERC Order 2222-enabled wholesale market participation.
- VRF system convergence:Variable refrigerant flow technology paired with building automation platforms is capturing high-rise multifamily installations in Chicago, Seattle, and Boston.
Industry Challenges
- Refrigerant handling certification:EPA Section 608 technician credentialing requirements are tightening as A2L refrigerants enter the market, constraining field workforce availability.
- Legacy BAS integration:BACnet and Modbus protocol fragmentation across installed building automation systems complicates unified energy management deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States HVAC Equipment and Services Market |
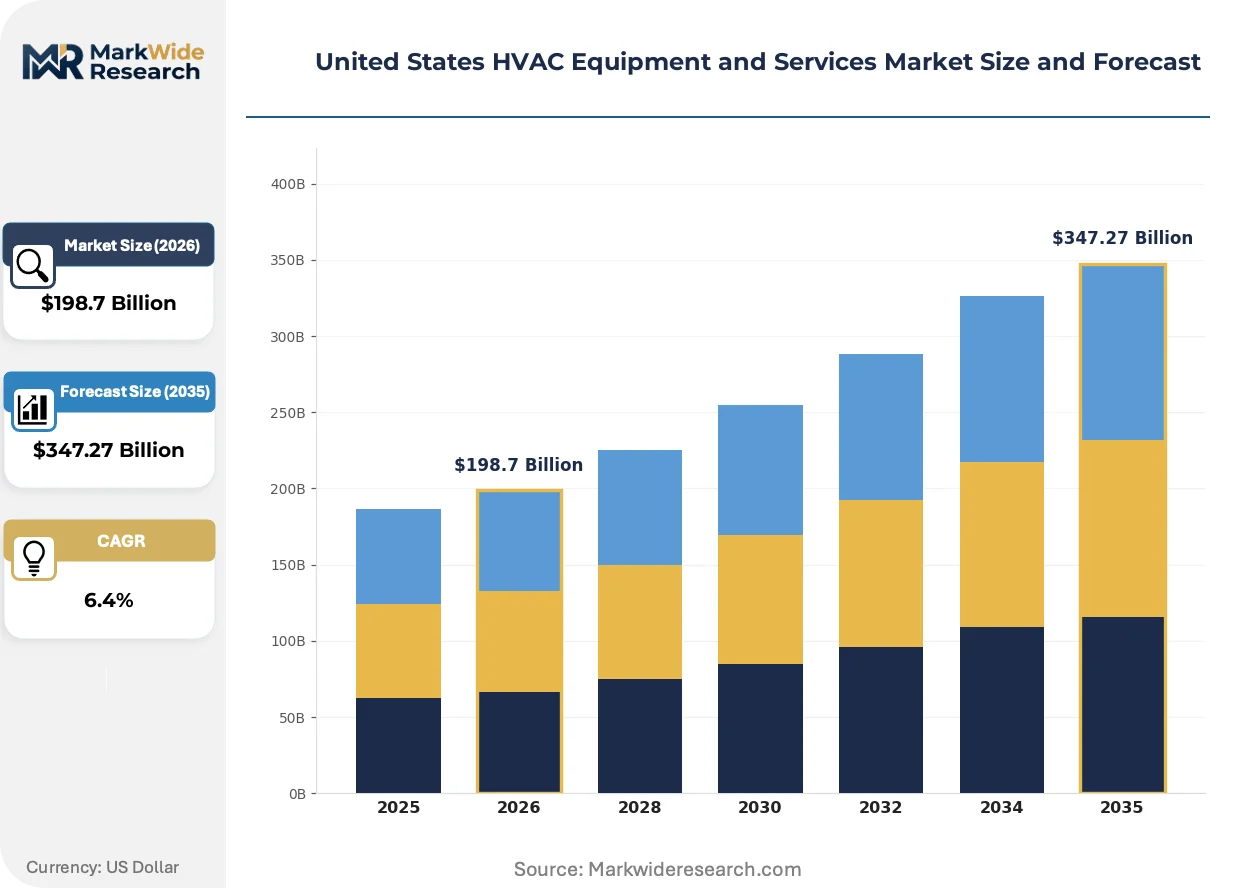
| Market Size in 2026 | $198.7 Billion |
| Market Size in 2035 | $347.27 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Conditioners, Furnaces, Heat Pumps, Thermostats Installation Type: Residential, Commercial, Industrial, New Construction Service Type: Maintenance, Repair, Replacement, Installation End User: Homeowners, Property Managers, Contractors, Facility Managers |
| Companies Covered | Trane Technologies, Daikin Industries, Carrier Global Corporation, Johnson Controls, Lennox International, Rheem Manufacturing Company, Mitsubishi Electric, Emcor Group, Comfort Systems USA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States HVAC Equipment and Services Market Evolving Landscape
Equipment intelligence and refrigerant chemistry are converging to redefine how thermal systems are specified, commissioned, and monetized across commercial and residential channels.
Magnetic bearing chiller technology is consolidating market share in large commercial and industrial applications by eliminating mechanical friction losses and enabling part-load efficiency above IPLV standards. Hospital campuses and university districts in California and Texas are specifying oil-free compression for critical cooling loads. The technology is consolidating supplier margins by compressing maintenance intervals and extending equipment life cycles beyond traditional centrifugal designs.
The EPA's phasedown schedule under the AIM Act is mandating transition to A2L refrigerants with GWP below 700, forcing redesign of safety systems and electrical enclosures. Equipment manufacturers are responding with dual-refrigerant product lines that maintain R-410A availability for legacy service while introducing R-454B variants for new construction. The commercial rooftop segment faces the steepest compliance curve due to high unit volumes and standardized platform architectures.
Energy-as-a-service contracting is displacing traditional equipment procurement in commercial real estate portfolios, transferring capital risk from building owners to HVAC OEMs and their financing partners. Blackstone and Prologis logistics facilities are piloting performance-guaranteed thermal contracts where providers retain equipment ownership. The model is most visible in California and New York where carbon disclosure requirements and Local Law 97-style mandates create preference for outsourced compliance accountability.
United States HVAC Equipment and Services Market Segmentation
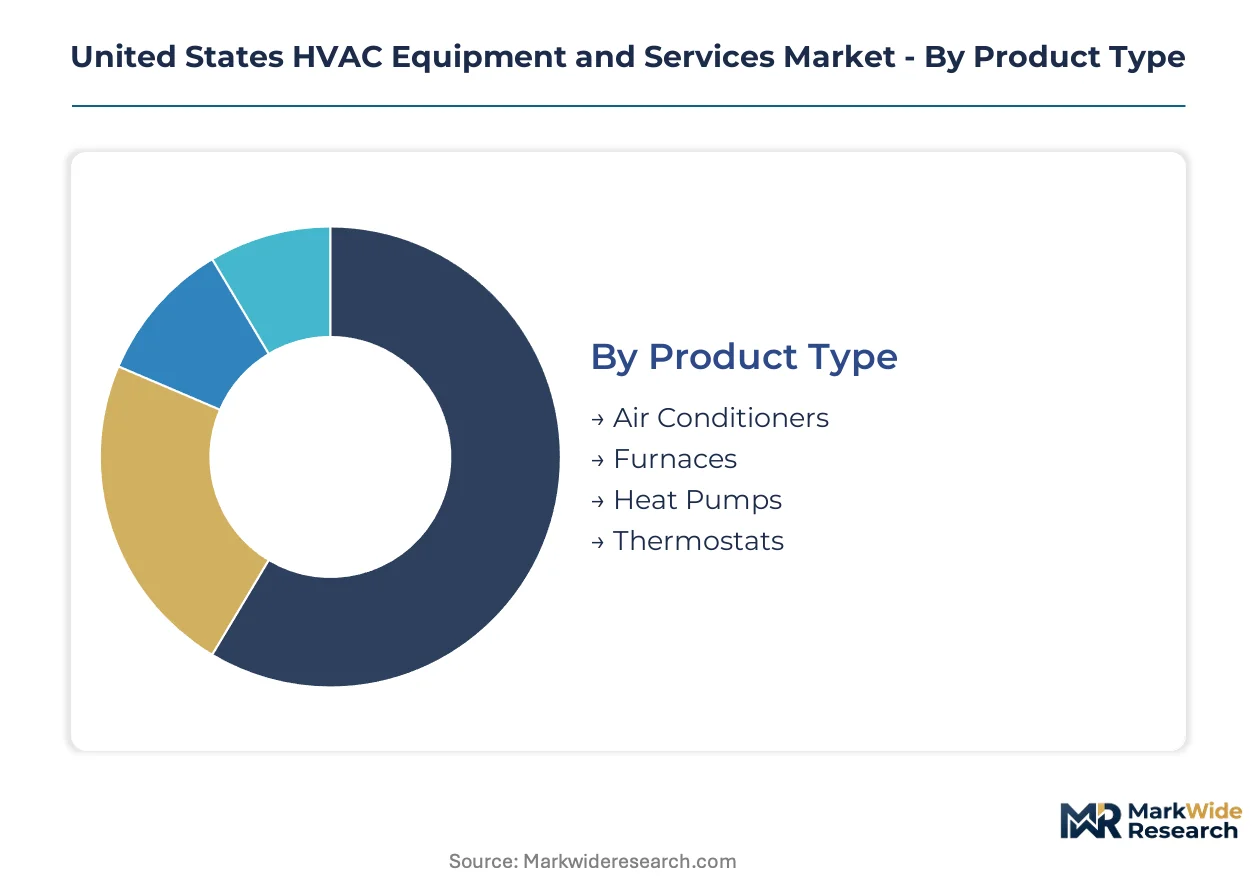
Capital allocation across the United States HVAC Equipment and Services Market diverges sharply by segment, with electrification mandates and refrigerant transitions concentrating investment in specific equipment categories. Understanding where upfront costs, regulatory complexity, and margin structures align reveals which segments command strategic priority.
Product Type:
Capital intensity peaks in sealed-system equipment requiring compressor manufacturing and refrigerant handling infrastructure, while controls and distribution components demand lighter fixed-asset deployment.
- Air Conditioners:Vapor-compression systems rated between 1.5 and 25 tons dominate residential and light-commercial cooling loads. Demand concentrates in Texas, Florida, and Arizona where cooling-degree-day accumulation drives replacement cycles and new construction specifications.
- Heat Pumps:Reversible refrigeration cycles providing both heating and cooling are capturing disproportionate investment as cold-climate performance thresholds improve and state energy offices in Massachusetts and Washington accelerate electrification timelines.
- Furnaces:Gas-fired forced-air heating systems retain installed base in the Northeast and Midwest where pipeline infrastructure and lower operating costs slow electric conversion.
- Thermostats:Programmable and connected climate controls represent the lowest capital barrier to entry, with utility demand-response programs in California and New York driving smart-device penetration.
Most installed capacity flows through Air Conditioners. Expansion is steepest in Heat Pumps.
Installation Type:
Project scale and regulatory exposure vary dramatically, from single-family residential permitting to industrial process cooling requiring EPA air quality compliance and OSHA safety coordination.
- Commercial:Rooftop units, chillers, and VRF systems serving offices, retail, and healthcare facilities carry the highest per-project capital requirements and longest sales cycles. Demand clusters in Sun Belt metropolitan areas where Class-A office construction and medical campus expansion outpace national averages.
- Industrial:Process cooling, cleanroom environmental control, and data center precision cooling demand engineered solutions with custom heat exchanger specifications. Virginia's Loudoun County and Dallas-Fort Worth hyperscale facilities are driving specification intensity.
- Residential:Single-family and multifamily unitary equipment represents the highest transaction volume with compressed margins and distributor-dominated procurement channels.
- New Construction:Greenfield installations tied to housing starts and commercial groundbreakings exhibit cyclical sensitivity to interest rate movements and regional migration patterns.
The largest revenue pools sit in Commercial. The steepest growth trajectory belongs to Industrial.
Service Type:
Margin structures invert across the service lifecycle, with reactive repair commanding premium pricing while planned maintenance generates recurring, contractually secured revenue streams.
- Replacement:End-of-life equipment swaps in aging Northeast and Midwest building stocks generate disproportionate margin capture compared to new construction, as existing infrastructure constraints demand customized solutions.
- Maintenance:Preventive service contracts and seasonal tune-ups produce predictable cash flows and create captive paths to replacement revenue when equipment nears failure thresholds.
- Installation:Greenfield equipment commissioning carries competitive pricing pressure and contractor bidding intensity, particularly in residential new construction channels.
- Repair:Emergency service calls command labor premiums and expedited parts logistics, though revenue unpredictability complicates workforce scheduling.
Replacement absorbs the majority of field technician hours. Maintenance contracts are expanding most quickly as building owners outsource operational accountability.
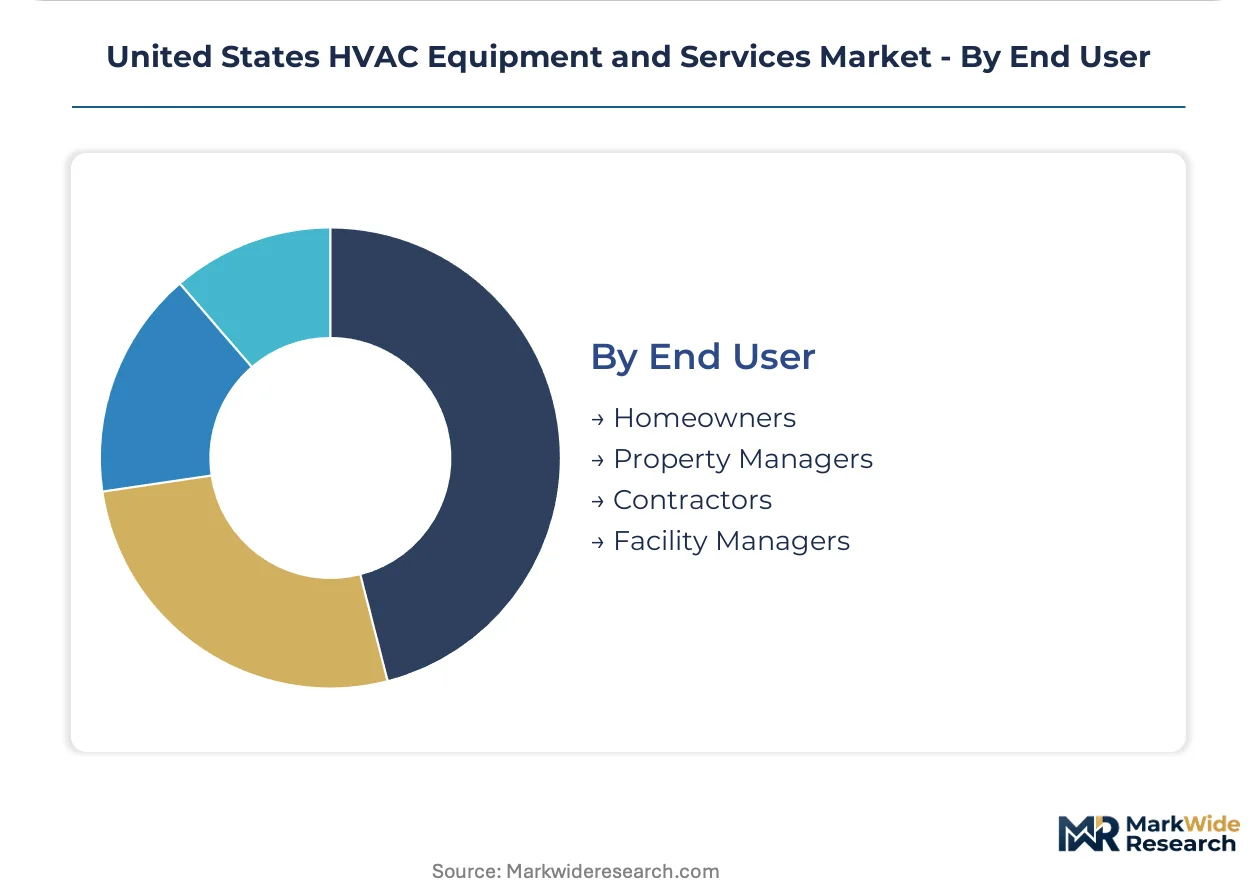
End User:
Procurement sophistication ranges from homeowner price sensitivity to facility manager energy-as-a-service contracting, reshaping how OEMs and distributors configure sales coverage.
- Facility Managers:Corporate and institutional operators with carbon disclosure mandates and Local Law 97-style compliance obligations are driving performance-contracting adoption and building automation integration.
- Property Managers:Multifamily portfolio operators prioritize equipment reliability and tenant comfort over efficiency optimization, favoring standardized platforms with national service networks.
- Contractors:HVAC installation and service firms act as intermediaries controlling brand specification in residential replacement and light-commercial channels through distributor relationships.
- Homeowners:Individual residential purchasers exhibit acute price sensitivity and seasonal purchasing patterns concentrated in equipment failure events.
Contractors intermediate the majority of equipment volume. Facility Managers are gaining share fastest as commercial electrification mandates deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping equipment sourcing patterns as OEMs relocate manufacturing to states with lighter environmental compliance burdens while maintaining distribution density in high-demand corridors. The Sun Belt's cost advantages in permitting and labor are attracting production capacity even as electrification mandates tighten in coastal markets.
Texas
Hyperscale data center construction in Dallas-Fort Worth and Austin is driving precision cooling demand matched to AI server density requirements. The Texas Commission on Environmental Quality administers air quality permits with timelines shorter than EPA regional offices in coastal states. Carrier Global Corporation and Rheem Manufacturing Company maintain major production facilities in the Dallas metro area serving southwestern distribution networks.
Virginia
Loudoun County's data center alley commands more cooling capacity per square mile than any US sub-region outside Phoenix. The Virginia Department of Environmental Quality implements refrigerant handling rules aligned with EPA Section 608 but with streamlined technician certification reciprocity. Northern Virginia's contractor base specializes in mission-critical cooling for financial services and government cloud infrastructure.
California
Building electrification mandates under Title 24 and Local Law 97-style ordinances in Los Angeles and San Francisco are accelerating heat pump specification in commercial retrofit channels. The California Air Resources Board enforces refrigerant GWP thresholds stricter than federal AIM Act minimums. The Central Valley's agricultural processing corridor sustains industrial chiller demand for cold chain logistics and food manufacturing.
Florida
Cooling-degree-day accumulation in Miami-Dade and Tampa Bay metro areas drives the nation's highest residential AC replacement velocity. The Florida Building Commission maintains statewide energy code compliance pathways that lag California and New York electrification timelines. Daikin Industries and Mitsubishi Electric anchor distribution networks in Orlando and Jacksonville serving southeastern installation contractors.
New York
Local Law 97 carbon intensity caps are forcing commercial building owners in Manhattan and Brooklyn toward electrified heating retrofits ahead of 2024 compliance deadlines. The New York State Energy Research and Development Authority channels IRA-funded incentives toward cold-climate heat pump deployment in upstate markets. Johnson Controls and Trane Technologies maintain service headquarters in the Hudson Valley corridor for northeastern institutional accounts.
United States HVAC Equipment and Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue building automation integration and energy-as-a-service contracting. The vendor base stratifies across three tiers: multinational OEMs with captive compressor technology, mid-scale specialists in variable refrigerant flow systems, and regional contractors controlling residential replacement channels. Strategic archetypes include technology licensors monetizing compressor IP, platform integrators bundling hardware with software, and asset-light service aggregators. Consolidation pressure concentrates in commercial service networks while product manufacturing faces capacity expansion in Mexico and southeastern US states.
Within the integrated OEM tier, Carrier Global Corporation and Trane Technologies occupy positions defined by scale and specification relationships with national account facility managers. Daikin Industries exemplifies the technology-specialist archetype through variable refrigerant flow system concentration. These three entities anchor competitive dynamics in commercial chiller and rooftop equipment segments where project scale and service network density determine specification outcomes.
| Leading Market Players |
|---|
| Trane Technologies |
| Daikin Industries |
| Carrier Global Corporation |
| Johnson Controls |
| Lennox International |
| Rheem Manufacturing Company |
| Mitsubishi Electric |
| Emcor Group |
| Comfort Systems USA |
| Others |
Value Network & Pricing Analysis
Copper coil and aluminum tubing costs cascade from commodity exchanges through distributor markups to landed equipment prices, compressing margin pools for manufacturers holding inventory against volatile LME pricing. Raw material swings force tiered pricing stratification across premium cold-climate heat pumps, standard efficiency air conditioners, and economy-grade furnaces serving price-sensitive residential replacement channels.
Pricing Analysis
Distributor margin layers separate OEM factory gates from contractor procurement, with 25-40 point spreads common in residential unitary equipment flowing through Lennox and Rheem distribution networks. Price differentiation rests on SEER rating certification tiers and cold-climate performance thresholds rather than brand premium alone. Cost compression in economy-tier gas furnaces is intensifying because steel sheet and burner component inputs face tariff exposure from concentrated Asian sourcing. Homeowners in Florida and Arizona exhibit acute price sensitivity during emergency replacement events, while facility managers in Manhattan and San Francisco prioritize performance contracting over capital cost.
Supply Chain Analysis
Workforce availability constraints in Texas and Mexico manufacturing corridors are extending lead times for scroll compressor production and coil fabrication lines. Geographic supply concentration centers on China for rare-earth magnet materials in high-efficiency motors, Mexico for sheet metal stamping and cabinet assembly, and domestic facilities in Arkansas and Tennessee for final system integration. Raw material dependencies draw from Chilean copper cathode, Chinese aluminum billet, and Korean steel coil. Single-source vulnerability in rotary compressor castings from concentrated Asian component houses exposes OEMs to port congestion risk. Distribution runs through manufacturer-authorized distributors controlling local contractor relationships and service parts logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through refrigerant transition premiums and cold-climate heat pump tier upgrades, with equipment makers capturing value from EPA-mandated system redesigns and electrification incentive flows.
For Market Incumbents: Anticipate R-454B compatibility requirements by accelerating heat exchanger and safety control validation ahead of AIM Act phaseout deadlines. Secure backward integration into compressor manufacturing through captive production lines or long-term offtake agreements with Korean and Japanese component suppliers. Defend against emerging building-automation integrators by bundling hardware with FERC Order 2222-enabled demand-response software layers. For New Entrants and Emerging Players: Enter via cold-climate heat pump white space in Minnesota, Maine, and Vermont where DOE Challenge winners have proven rated capacity below 5°F but local contractor networks remain fragmented. Target utility demand-response program administration as a service-light entry point requiring minimal manufacturing capital. Pursue grid-interactive water heater and thermostat deployment through direct partnerships with municipal utilities bypassing traditional distributor channels. For Investors and Strategic Acquirers: Roll-up economics work for regional commercial service contractors because Local Law 97-style compliance mandates in New York and California are forcing building owners toward outsourced performance accountability and long-term maintenance contracts. Platform consolidation across Sun Belt metropolitan service networks offers 5-10 year viability given replacement cycle concentration in Texas and Florida. Monitor EPA refrigerant handling certification bottlenecks as an inflection signal—technician scarcity constraining A2L system deployment would accelerate acquisition premiums for credentialed service networks.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Climate Heat Pump Certification Investment | DOE Challenge validation unlocks Massachusetts and Washington electrification incentive flows. |
| A2L Refrigerant Safety System Redesign | EPA AIM Act compliance separates compliant OEMs from legacy R-410A-dependent competitors. |
| Utility Demand-Response Platform Integration | FERC Order 2222 market participation creates recurring revenue beyond equipment margins. |
| Regional Service Contractor Acquisition | Local Law 97 compliance deadlines concentrate outsourced maintenance demand in coastal markets. |
| Mexico Manufacturing Footprint Expansion | Texas Commission on Environmental Quality permitting advantages reduce time-to-market for southwestern distribution. |
Research Methodology
Coverage spans the Northeast, Southeast, Midwest, and Southwest, with primary inputs from each region's contractor networks and utility program administrators. The approach combines structured interviews with HVAC distributor principals, facility managers at Class-A commercial portfolios, state energy office electrification leads, and EPA-certified refrigerant technicians with secondary validation through DOE appliance standards filings, EPA Section 608 enforcement data, FERC Order 2222 implementation dockets, and utility demand-response program filings. Bottom-up equipment shipment analysis and top-down construction spending triangulation anchor volume estimates.
Rate-of-change decomposition separates replacement cycle velocity from new construction sensitivity and electrification policy acceleration across the projection horizon. Segmentation dimensions modeled include equipment product type, installation channel, service lifecycle stage, and end-user procurement sophistication. CAGRs derive from equipment stock aging curves, refrigerant transition timelines, and regional cooling-degree-day accumulation patterns. Forecast inputs incorporate IRA incentive allocation trajectories through state energy offices and data center power density specifications from hyperscale facility disclosures.
The model holds under steady electrification policy implementation and AIM Act phaseout adherence; deviation in federal incentive continuity or refrigerant supply disruption would shift equipment replacement timelines and OEM margin structures. Forecasts reflect assumptions about technician certification pipeline expansion and copper price volatility bands. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
Middle-East and Africa Compressor Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
Compressor Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
Air Volume Controllers Market
HVAC Equipment
Helical Screw Blowers Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
Compressor Controllers Market