
 Europe Oil Filled Distribution Transformer Market | 2026-2036
Europe Oil Filled Distribution Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Oil Filled Distribution Transformer Market Analysis
CE marking under the EU's Low Voltage Directive and harmonized EN standards is redrawing competitive entry barriers for transformer suppliers across Europe. ABB Ltd. leverages its integrated manufacturing footprint in Sweden and Poland to sustain cost-efficient production of three-phase units. Siemens Energy AG anchors its position through deep R&D investment in ester-based insulating fluids. Schneider Electric SE competes via channel control across French and Iberian utility procurement frameworks.
Europe oil filled distribution transformers are static electromagnetic devices rated typically from 10 kVA to several MVA, using mineral oil or synthetic ester as both coolant and dielectric medium to step down medium-voltage grid power for end-user consumption. Three-phase configurations dominate utility-scale deployments, while pole-mounted designs retain structural importance in rural Spain and Eastern European territories with dispersed load profiles. The 101-250 kVA power rating band captures concentrated margin pools as commercial building electrification and light industrial expansion accelerate replacement cycles across Italy and the Netherlands.
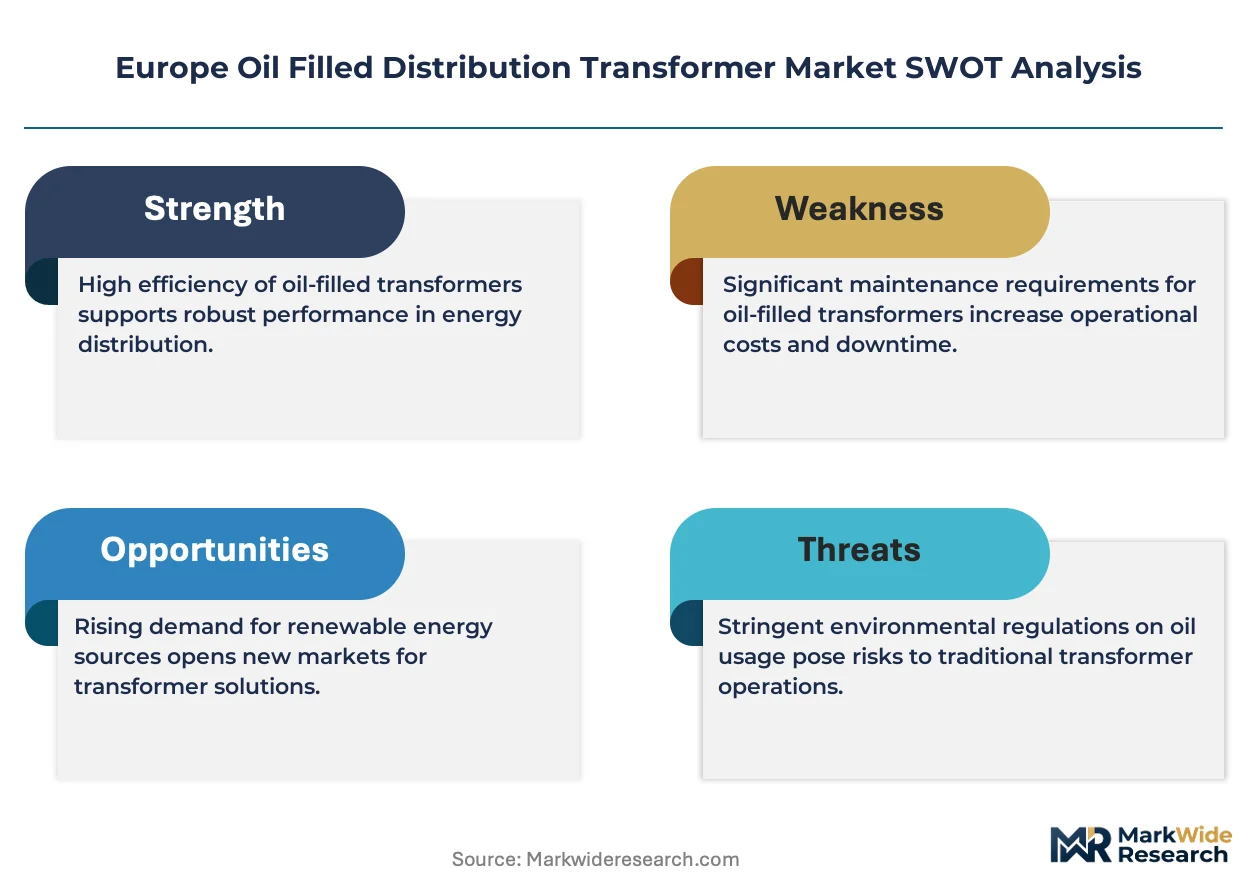
EMA's environmental risk assessments and REACH compliance requirements for mineral oil formulations shape material selection and recycling obligations for manufacturers operating within EU member states. The EU Green Deal's 2030 efficiency targets and F-Gas Regulation restrictions on synthetic dielectrics are forcing accelerated reformulation toward natural and synthetic ester alternatives. Stakeholders must monitor how ECHA's evolving substance restrictions and national transpositions of the Ecodesign Directive reshape total cost of ownership calculations for utility procurement teams.
Market Dynamics
EU Green Deal efficiency mandates and F-Gas Regulation restrictions on synthetic dielectrics are forcing transformer manufacturers toward bio-based insulating oil reformulation, reshaping material sourcing and certification timelines across continental supply chains.
Growth Catalysts
- Offshore wind interconnection:German and Polish utilities are deploying three-phase units to integrate North Sea and Baltic renewable capacity into medium-voltage distribution networks.
- REACH compliance deadlines:ECHA substance restrictions on mineral oil formulations are accelerating replacement cycles as utilities preempt regulatory obsolescence.
- Ester fluid technology:Natural and synthetic ester dielectrics are capturing procurement preference due to enhanced fire safety and biodegradability profiles.
Market Restraints
- Copper and grain-oriented electrical steel volatility:Input cost swings compress margin predictability for manufacturers with fixed-price utility contracts.
- Core lamination supply concentration:Dependency on limited European specialty steel producers creates vulnerability to production disruptions.
- Mineral oil substitution timeline:Legacy fleet compatibility constraints slow full ester adoption despite regulatory pressure.
Strategic Opportunities
- Eastern European grid modernization:Romanian and Bulgarian distribution operators present underpenetrated demand for pole-mounted rural configurations.
- Digital twin integration:IoT-enabled thermal monitoring converges with transformer hardware to unlock predictive maintenance revenue streams.
- EU Ecodesign Directive transposition:National efficiency procurement mandates create first-mover advantage for Tier 2 loss-certified units.
Industry Challenges
- High-voltage testing technician scarcity:Specialized dielectric testing expertise shortages extend factory acceptance timelines.
- Legacy fleet interoperability:Retrofit compatibility with 1970s-1990s installed base complicates standardized product platform rollout.
- CE marking documentation burden:EN 50541-1 conformity assessment delays stretch commercialization cycles for new product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Oil Filled Distribution Transformer Market |
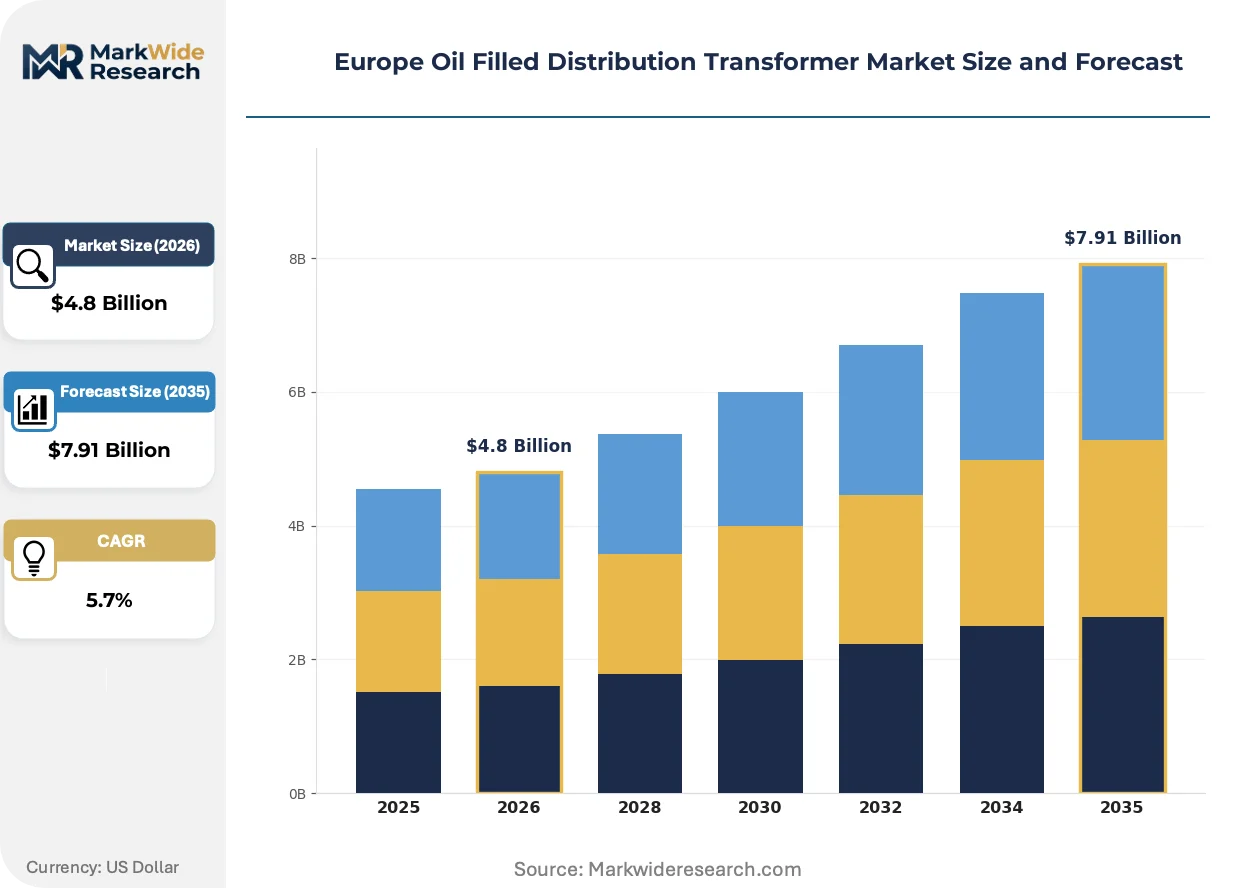
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Floor-Mounted, Pole-Mounted End User: Utilities, Industrial Plants, Commercial Buildings, Residential Sector Installation: Indoor, Outdoor, On-Site, Off-Site Power Rating: Up to 50 kVA, 51-100 kVA, 101-250 kVA, Above 250 kVA |
| Companies Covered | GE Vernova, ABB Ltd., Hitachi Energy Ltd., SGB-SMIT, CG Power & Industrial Solutions, Siemens Energy AG, Eaton Corporation plc, ORM AZABAL, Schneider Electric SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Oil Filled Distribution Transformer Market Emerging Trajectories
Synthetic ester fluids and digital monitoring systems are converging to redefine transformer lifecycle economics, while procurement frameworks increasingly weight total cost of ownership over upfront capital expenditure.
Natural ester dielectrics derived from vegetable oil feedstocks are displacing mineral oil in fire-sensitive installations. Data centers and urban underground substations in the Netherlands and Belgium are specifying these fluids for reduced environmental liability. This chemistry shift is displacing conventional fire mitigation infrastructure requirements and enabling compact indoor installations previously restricted by safety codes.
F-Gas Regulation restrictions on synthetic fluorinated dielectrics are eliminating certain high-performance alternatives from transformer applications. Manufacturers must reformulate product lines around non-fluorinated ester options or absorb compliance penalties. German and French utilities are responding by embedding bio-based fluid mandates into technical specifications ahead of statutory deadlines.
Performance-based service agreements are replacing traditional equipment-only procurement across Nordic distribution operators. Maintenance responsibility shifts to manufacturers while utilities pay per guaranteed availability. This contracting evolution is most visible in Sweden and Finland where grid digitalization enables real-time condition monitoring and remote diagnostics.
Europe Oil Filled Distribution Transformer Market Segmentation
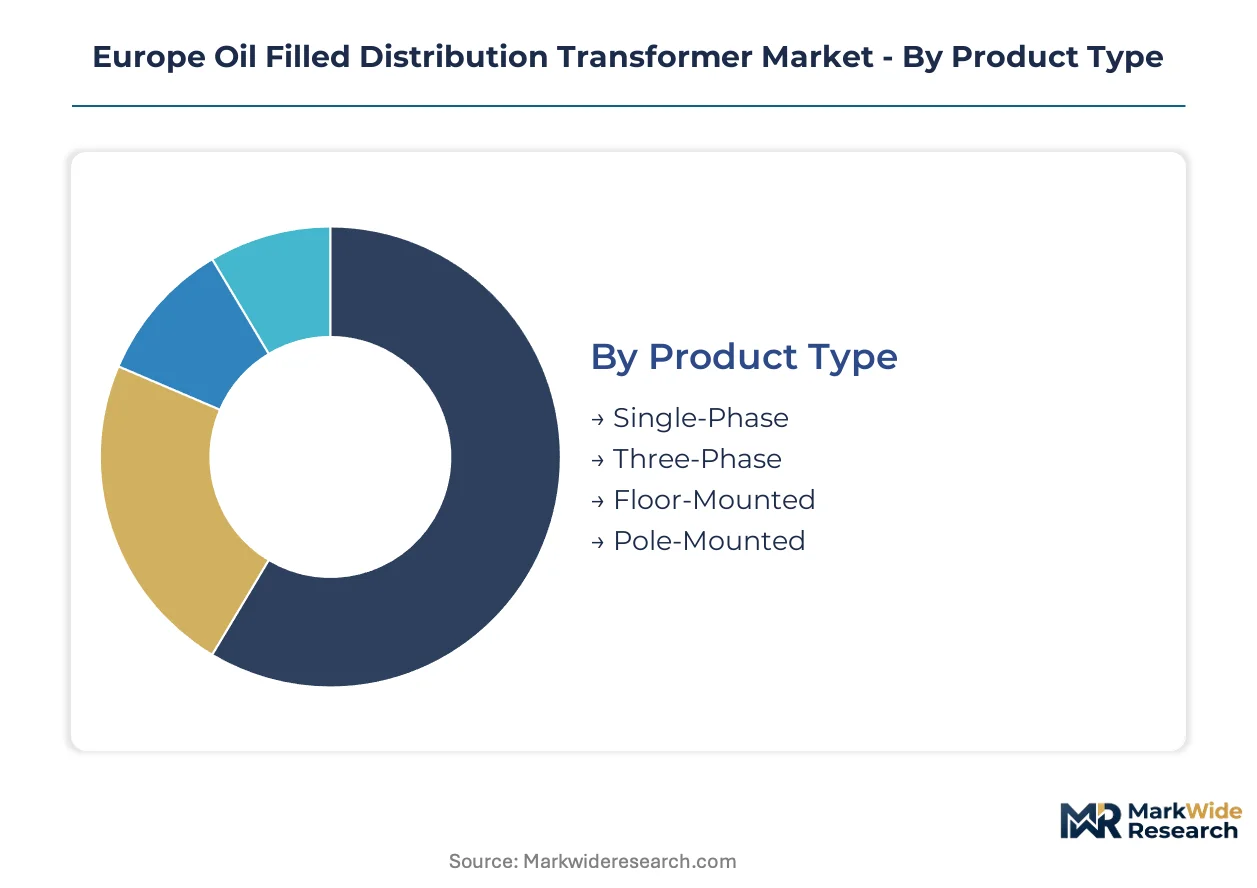
Transformer procurement across Europe fragments across voltage configurations, mounting topologies, and end-use requirements. Each segment carries distinct certification burdens, fluid compatibility constraints, and utility specification patterns that reshape supplier economics.
Product Type:
Domestic demand concentrates in three-phase and floor-mounted configurations serving German and French grid modernization, while pole-mounted exports sustain Polish and Romanian manufacturing scale.
- Three-Phase:These units handle medium-voltage distribution from 10 kVA to several MVA using mineral oil or synthetic ester dielectrics. German utilities deploying North Sea offshore wind interconnectors specify three-phase designs for substation density. REACH compliance deadlines on mineral oil formulations are compressing procurement cycles as operators preempt regulatory obsolescence.
- Pole-Mounted:Elevated installations serve rural Spain and Eastern European territories with dispersed load profiles and limited substation footprint. Bulgarian and Romanian distribution operators present underpenetrated demand as EU cohesion funds accelerate grid extension into agricultural zones.
- Single-Phase:Compact units address isolated residential connections and remote agricultural pumping stations across Mediterranean islands.
- Floor-Mounted:Pad-mounted configurations dominate urban Netherlands and Belgian underground substations where fire codes restrict pole installations.
Three-Phase commands the established base. The steepest expansion runs through Pole-Mounted.
End User:
Volume concentration tilts toward utility procurement frameworks, though commercial electrification and data center buildouts are diversifying customer mix.
- Utilities:State-backed distribution operators across Germany, France, and Poland drive standardized tender volumes with multi-year framework agreements. EU Green Deal efficiency mandates are embedding bio-based fluid requirements into technical specifications ahead of statutory deadlines.
- Commercial Buildings:Electrification retrofits and light industrial expansion accelerate replacement cycles across Italy and the Netherlands. The 101-250 kVA band captures concentrated margin pools as building codes tighten energy performance standards.
- Industrial Plants:Heavy manufacturing clusters in the Ruhr and northern Italy specify robust thermal profiles for continuous operation.
- Residential Sector:Single-family housing stock renewal and multi-unit development sustain baseline demand for smaller kVA ratings.
Utilities anchor volume procurement. Commercial Buildings are climbing the fastest.
Installation:
Site constraints and fire safety codes determine indoor versus outdoor specification, with prefabricated off-site assembly gaining traction for accelerated deployment.
- Outdoor:Open-air pad and pole installations dominate utility-scale deployment across continental climates. Natural ester fluids are displacing mineral oil in fire-sensitive locations to reduce environmental liability and enable compact configurations.
- Indoor:Underground substations in Dutch and Belgian urban cores specify these units where space constraints and safety codes restrict conventional designs. Synthetic ester dielectrics eliminate separate fire suppression infrastructure.
- On-Site:Conventional assembly at substation locations persists for bespoke configurations and legacy compatibility requirements.
- Off-Site:Factory-integrated substations reduce field construction timelines for Polish and Baltic renewable interconnection projects.
Outdoor retains the installed base. Indoor is gaining share fastest.
Power Rating:
Rating bands align with distinct end-use thermal profiles and replacement economics, with mid-range units capturing efficiency-upgrade premiums.
- 101-250 kVA:This band serves commercial building electrification and light industrial expansion where Tier 2 loss certification unlocks procurement preference. Italian and Dutch utilities specify these ratings for urban distribution density.
- Above 250 kVA:Heavy industrial and utility substation applications demand these units for renewable integration and grid reinforcement. German offshore wind interconnectors deploy large three-phase configurations for medium-voltage aggregation.
- Up to 50 kVA:Rural residential and agricultural pumping applications sustain baseline production across Mediterranean and Eastern European markets.
- 51-100 kVA:Small commercial and multi-family housing stock fills intermediate demand with standardized platform economics.
101-250 kVA commands margin concentration. Above 250 kVA shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal efficiency mandates and F-Gas Regulation restrictions on synthetic dielectrics are accelerating transformer procurement cycles across continental utilities. Member states are transposing Ecodesign Directive requirements into national procurement frameworks ahead of 2030 deadlines.
Germany
North Sea offshore wind interconnection projects are driving demand for three-phase units rated above 250 kVA. The Bundesnetzagentur is enforcing stricter loss certification under transposed EU Ecodesign rules. Manufacturing clusters in North Rhine-Westphalia and Bavaria are expanding production capacity for ester-fluid configurations serving TenneT and 50Hertz grid operators.
France
Réseau de Transport d'Électricité and Enedis are modernizing urban distribution networks with pad-mounted floor configurations. The Agence de l'Environnement et de la Maîtrise de l'Énergie is promoting natural ester adoption through fire safety code amendments. Industrial corridors around Lyon and Grenoble are specializing in compact indoor substation designs for data center electrification.
Poland
Baltic Sea renewable integration and rural grid extension are sustaining pole-mounted and three-phase deployment. The Energy Regulatory Office is aligning technical codes with REACH compliance deadlines for mineral oil phase-out. Manufacturing facilities in Lower Silesia and Greater Poland are scaling output for PGE and Tauron distribution framework agreements.
Netherlands
Underground urban substations in Amsterdam and Rotterdam are specifying synthetic ester units to eliminate separate fire suppression infrastructure. The Netherlands Enterprise Agency is subsidizing Tier 2 loss-certified replacements under national climate agreements. Randstad logistics hubs are accelerating 101-250 kVA procurement for commercial building electrification.
Italy
Terna and Enel Distribuzione are replacing aging mineral oil fleets in northern industrial zones. The Ministry of Ecological Transition is accelerating Ecodesign transposition with 2027 efficiency benchmarks. Manufacturing concentration in Lombardy and Emilia-Romagna is pivoting toward bio-based fluid platforms for fire-sensitive alpine installations.
Europe Oil Filled Distribution Transformer Market Vendor Landscape
Player mix skews toward integrated electrical equipment conglomerates with captive transformer divisions. Tier-1 suppliers with integrated manufacturing footprints in Poland and Sweden command utility-scale procurement preference. Strategic archetypes include: (1) full-grid-solution providers bundling transformers with switchgear and digital monitoring, (2) specialized fluid-technology innovators reformulating around ester chemistry, and (3) regional fabricators serving Eastern European price-sensitive tenders. Dominant competitive moves center on backward integration into core lamination supply and technology licensing partnerships for ester fluid formulations.
Among diversified industrial conglomerates, ABB Ltd., Siemens Energy AG, and Schneider Electric SE occupy anchor positions across European procurement frameworks. ABB Ltd. exemplifies the integrated manufacturing archetype with production presence in Sweden and Poland. Siemens Energy AG represents the fluid-technology specialization vector through R&D concentration in ester-based dielectrics. Schneider Electric SE sits within the channel-control tier leveraging French and Iberian utility relationships. These three entities collectively shape competitive dynamics without exclusive segment dominance.
| Leading Market Players |
|---|
| GE Vernova |
| ABB Ltd. |
| Hitachi Energy Ltd. |
| SGB-SMIT |
| CG Power & Industrial Solutions |
| Siemens Energy AG |
| Eaton Corporation plc |
| ORM AZABAL |
| Schneider Electric SE |
| Others |
Supply Flow & Price Mechanics
Ester fluid substitution for mineral oil dielectrics is simultaneously redrawing supply geography toward Polish and Swedish manufacturing clusters and compressing pricing premiums for bio-based formulations as REACH compliance deadlines accelerate procurement cycles.
Pricing Analysis
CE marking tier under EN 50541-1 creates the primary spread between premium-certified and standard-grade units. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden, fluid chemistry, and loss-grade efficiency. Cost compression in standard mineral oil segments is intensifying because utilities are front-loading ester conversions ahead of ECHA substance restrictions. Commercial building electrification buyers exhibit highest price sensitivity, while German offshore wind interconnectors prioritize performance over unit economics.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg container terminals are elevating landed costs for Asian-sourced core laminations and copper feedstock. Manufacturing gravity centers on Poland, Sweden, and Germany for finished transformer assembly, with grain-oriented electrical steel drawing from limited European specialty mills. Single-source vulnerability concentrates in Austrian and Slovak electrical steel production. Distribution runs through utility procurement frameworks and EPC contractor channels serving TenneT, Enedis, and PGE grid operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics around interoperable digital monitoring systems and standardized ester-fluid specifications are creating winner-take-most dynamics as EU Ecodesign transpositions harden technical barriers to entry.
For Market Incumbents: Compound manufacturing scale in Lower Silesia and Greater Poland to capture Baltic renewable interconnection volumes. Deepen backward integration into core lamination supply through captive electrical steel partnerships. Accelerate ester-fluid R&D to preempt REACH-driven mineral oil obsolescence. Lock multi-year framework agreements with TenneT and 50Hertz before efficiency mandates tighten.
For New Entrants and Emerging Players: Differentiate on synthetic ester formulation chemistry for fire-sensitive indoor installations in Dutch and Belgian urban substations. Target Romanian and Bulgarian pole-mounted rural configurations where EU cohesion funds are accelerating grid extension. Pursue white-label manufacturing partnerships with Polish fabricators to bypass CE marking documentation burdens.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabricators in Eastern Europe lacking ester-fluid capabilities. Five-to-ten year viability hinges on successful chemistry transition and digital twin integration. Watch for Baltic Sea renewable project award announcements as inflection indicators for manufacturing capacity utilization.
| Strategic Initiative | Industry Significance |
|---|---|
| Ester Fluid Manufacturing Scale-Up | Captures procurement preference as ECHA mineral oil restrictions harden across German and French utilities. |
| Backward Integration into Core Lamination Supply | Reduces dependency on Austrian and Slovak electrical steel producers amid supply concentration risks. |
| Digital Twin Platform Integration | Enables predictive maintenance revenue streams through IoT-enabled thermal monitoring convergence. |
| Long-Term Utility Framework Agreements | Locks volume commitments with TenneT, Enedis, and PGE ahead of EU Ecodesign transposition deadlines. |
| Joint Venture for Eastern European Grid Extension | Accesses Romanian and Bulgarian pole-mounted demand through EU cohesion fund-backed projects. |
Methodological Framework
A standing panel of utility planning officers, transformer procurement managers, EPC contractors, and ester-fluid R&D directors provided ongoing calibration against secondary validation from EU Ecodesign Directive filings, ECHA substance restriction databases, Bundesnetzagentur loss certification records, and utility tender documentation. Bottom-up unit shipment estimates triangulated with top-down grid investment forecasts across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including IEA grid infrastructure reports, ENTSO-E ten-year network development plans, and national regulatory office procurement disclosures. Segmentation modeling spanned product type, power rating band, end-use sector, installation configuration, and fluid chemistry platform. CAGRs derived from regression analysis of historical replacement cycles and forward policy mandate trajectories, with specific inputs for offshore wind interconnection timelines and REACH compliance phase-out schedules.
The analysis sits within stated boundaries; outcomes outside EU Green Deal implementation pace or electrical steel supply stability assumptions would require recalibration. Forecasts reflect documented assumptions regarding ester fluid adoption curves and utility procurement framework renewal patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
United States Dry-Type Transformer Market
Transformers
Transformer Steel Market
Transformers
Uninhibited Transformer Oil Market
Transformers
United Arab Emirates Transformer Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
United States Large Power Transformer Market
Transformers
Canada Transformer Market
Transformers
Green Power Transformers Market
Transformers
Distribution Transformer Market
Transformers
Industrial Control Transformers Market
Transformers
Three Phase Transformer Market
Transformers
Renewable Energy Transformer Market
Transformers
Rail Traction Transformers Market
Transformers
India Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market