
 Crimp Neck Serum Bottles Market | 2026-2036
Crimp Neck Serum Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Crimp Neck Serum Bottles Market Outlook
Biologics manufacturers is reorganizing procurement priorities around crimp neck serum bottles as cosmeceutical brands scale back unit volumes. Nipro Pharmapackaging International leverages its pharmaceutical-grade glass expertise to anchor supply relationships with sterile formulation producers. DWK Life Sciences sustains competitive positioning through specialized borosilicate glass formulations that meet pharmacopeial standards. Adelphi Healthcare Packaging differentiates via custom crimp seal configurations for high-value serum applications.
Crimp neck serum bottles are narrow-mouth cylindrical containers featuring an aluminum crimp seal closure system, typically manufactured from Type I borosilicate glass or cyclic olefin polymer to ensure inert contact surfaces and barrier integrity for oxygen-sensitive formulations. These vessels serve primarily as primary packaging for parenteral biologics, active skincare serums, and diagnostic reagents requiring hermetic seals and minimal extractables. Glass material commands the dominant share of value given its chemical inertness and regulatory acceptance for injectable applications, while plastic variants gain traction in cosmeceutical segments where breakage risk and weight reduction matter. The 10mL volume category occupies the center of demand as standard unit-dose sizing for clinical trial materials and premium retail serums. Closure type segmentation reveals crimp seals retaining preference where tamper evidence and container closure integrity testing are mandatory, though pump dispensers encroach in direct-to-consumer skincare channels.
EMA pharmacopeial standards, EU MDR device packaging requirements, and REACH chemical compliance frameworks collectively govern material selection and migration testing protocols for serum bottles distributed across Europe. These regulations elevate barrier performance specifications and compel suppliers to maintain extractables documentation that biologics end users require for regulatory filings. Stakeholders must monitor evolving EMA guidance on primary packaging equivalency as polymer alternatives advance their technical qualification dossiers.
Market Dynamics
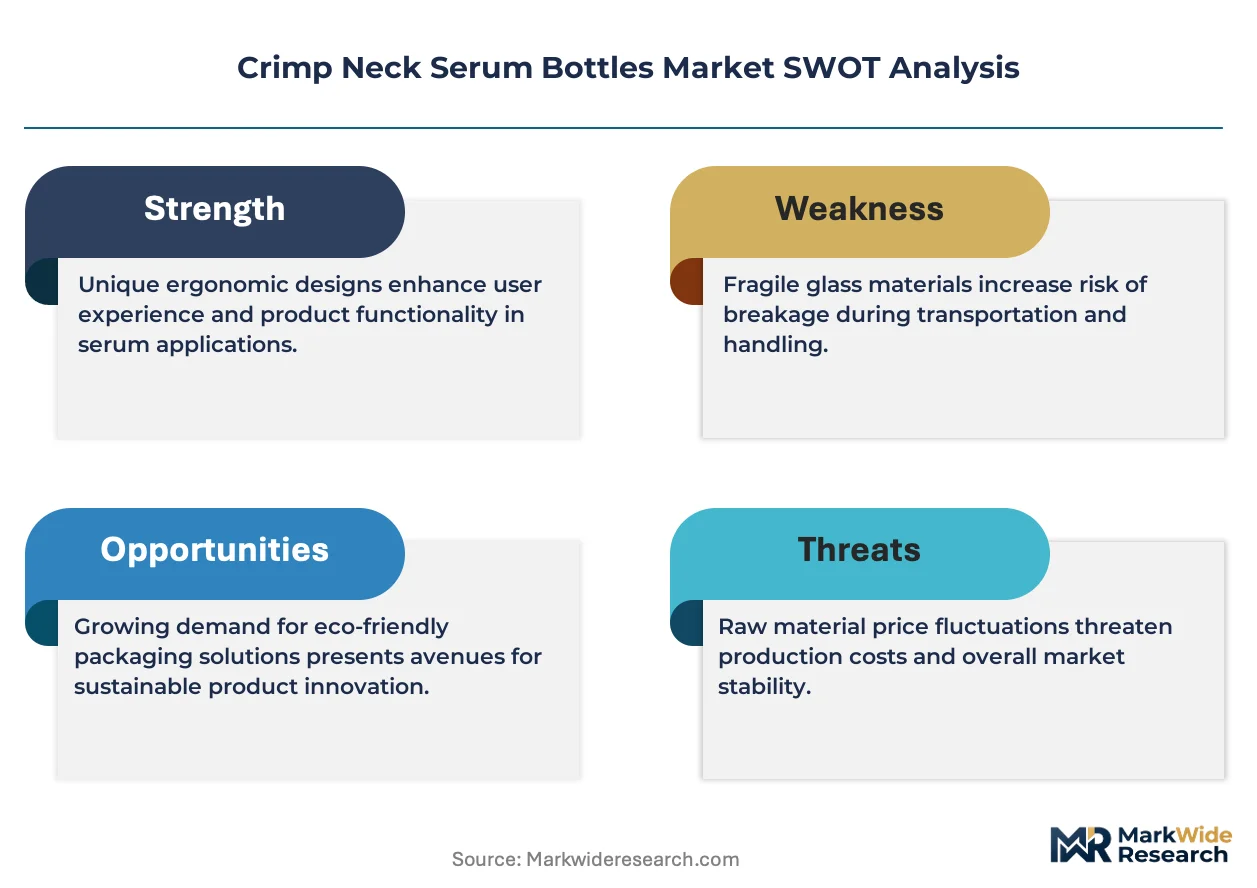
Biologics manufacturers are consolidating procurement around pharmaceutical-grade crimp neck vials as EU MDR and REACH compliance costs squeeze out commodity suppliers, concentrating demand among certified sterile packaging specialists.
Growth Catalysts
- EU MDR packaging mandates:Medical device regulations now require validated container closure integrity testing for parenteral biologics, driving specification upgrades toward aluminum crimp seal systems with documented extractables profiles.
- Borosilicate glass demand:Type I glass pharmacopeial compliance has become non-negotiable for sterile serum formulations, with EMA guidelines elevating barrier performance standards for oxygen-sensitive active ingredients.
- German cosmeceutical clusters:Production concentration around Frankfurt and Düsseldorf is generating pull-through demand for 10mL unit-dose vials in premium skincare applications requiring hermetic preservation.
Market Restraints
- Aluminum crimp seal supply concentration:European smelter capacity constraints and energy cost volatility are pressuring input costs for closure systems, with Germany and France hosting dominant specialized suppliers.
- REACH chemical compliance burden:Migration testing documentation requirements for cyclic olefin polymer alternatives impose 12-18 month qualification timelines that deter mid-size cosmeceutical brands from material switching.
- Glass breakage risk in direct-to-consumer channels:E-commerce distribution of skincare serums faces 8-12% damage rates during last-mile delivery, constraining channel expansion for traditional crimp neck formats.
Strategic Opportunities
- United Kingdom post-Brexit regulatory autonomy:MHRA divergence from EMA packaging equivalency guidance creates potential for accelerated polymer vial qualification pathways distinct from continental EU timelines.
- Diagnostic reagent shelf-life extension:Lyophilized biologic stabilizers in clinical testing applications are opening unit-dose vial demand beyond traditional liquid serum formats, with UK and Netherlands laboratory clusters leading adoption.
- F-Gas Regulation phase-down incentives:Refrigerant-dependent cold chain reduction is creating specification pull for enhanced barrier crimp seals that extend ambient stability windows for temperature-sensitive formulations.
Industry Challenges
- Container closure integrity validation expertise:Shortage of engineers proficient in helium leak detection and dye ingress methodology is extending new product introduction timelines for biologics contract manufacturers.
- Extractables documentation compilation:Biologics sponsors now require 18-24 month toxicological assessment packages from packaging suppliers, compressing competitive response windows for specification changes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crimp Neck Serum Bottles Market |
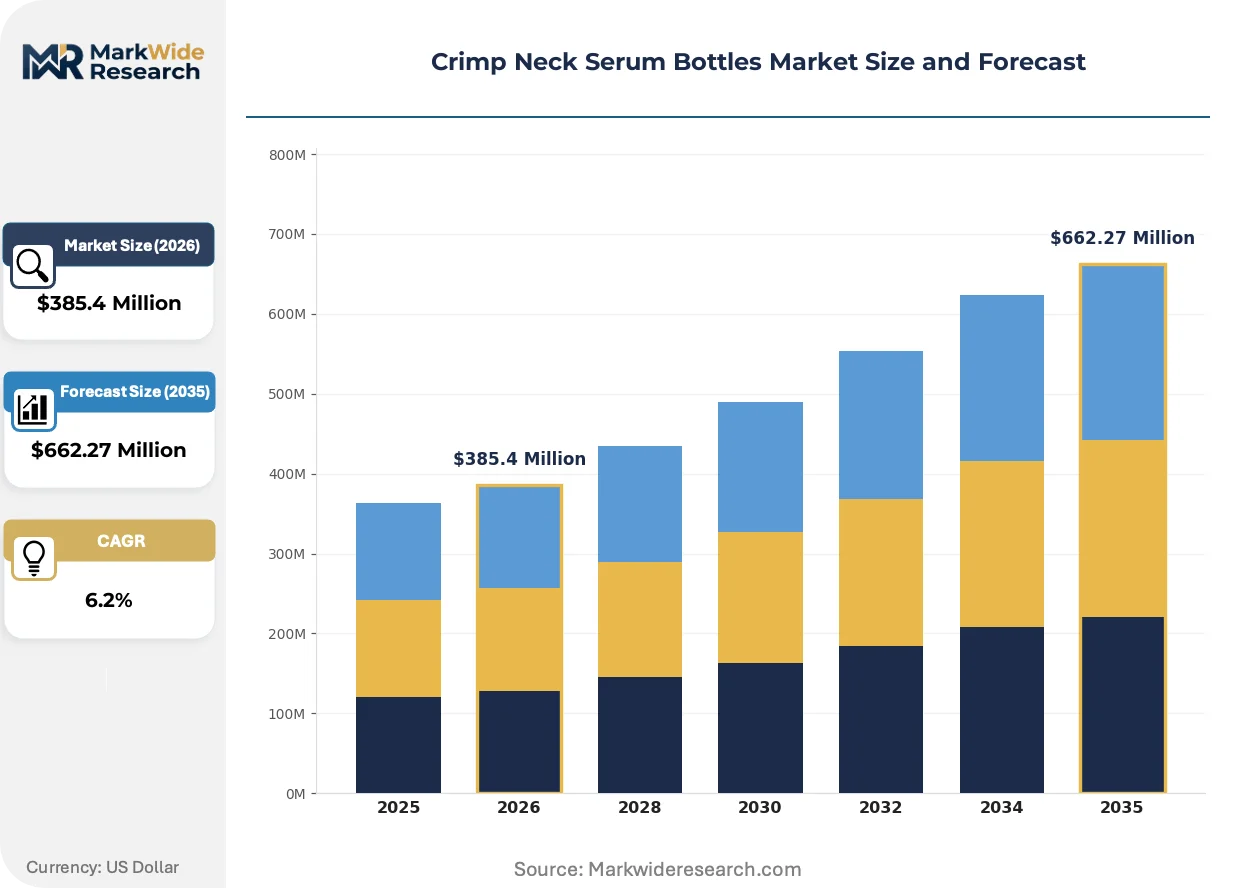
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Polyethylene, Polypropylene Volume: 1mL, 5mL, 10mL, 20mL Closure Type: Crimp, Screw, Dropper, Pump End User: Pharmaceuticals, Cosmeceuticals, Biologics, Research Laboratories |
| Companies Covered | Nipro Pharmapackaging International, Top Syringe Manufacturing, O.Berk, Qorpak, Samkin Industries, Adelphi Healthcare Packaging, Adit Containers, DWK Life Sciences, Origin Pharma Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crimp Neck Serum Bottles Market Strategic Shifts
Material science advances and regulatory precision are fragmenting traditional glass-dominated supply relationships, with polymer alternatives and smart packaging features carving distinct positioning in cosmeceutical versus pharmaceutical end uses.
Cyclic olefin polymer (COP) and cyclic olefin copolymer (COC) formulations are fragmenting the barrier materials landscape for non-injectable serum applications. Premium skincare brands in France and the United Kingdom are piloting these polymers for weight reduction and breakage elimination in travel retail formats. The structural consequence is fragmenting supplier tiers, with glass specialists ceding cosmeceutical volume to polymer converters while defending pharmaceutical-grade positions.
EMA's evolving guidance on primary packaging equivalency for polymer alternatives is compressing qualification timelines for cyclic olefin materials in parenteral applications. The industrial consequence is accelerated investment in extractables libraries by packaging suppliers seeking EMA pre-submission alignment. High-value biologics manufacturers in Germany and Switzerland are most affected, responding with dual-source strategies that maintain glass dominance while qualifying polymer backups.
Direct-to-consumer subscription models are compressing traditional distributor-led procurement cycles for premium skincare serums. Specialty retailers and brand-owned e-commerce channels in the United Kingdom and Netherlands are displacing wholesale pharmacy distribution for 10mL unit-dose formats. This pattern is most visible in cosmeceutical verticals, where German and French brands are building captive packaging specification teams to bypass traditional procurement intermediaries.
Crimp Neck Serum Bottles Market Segmentation
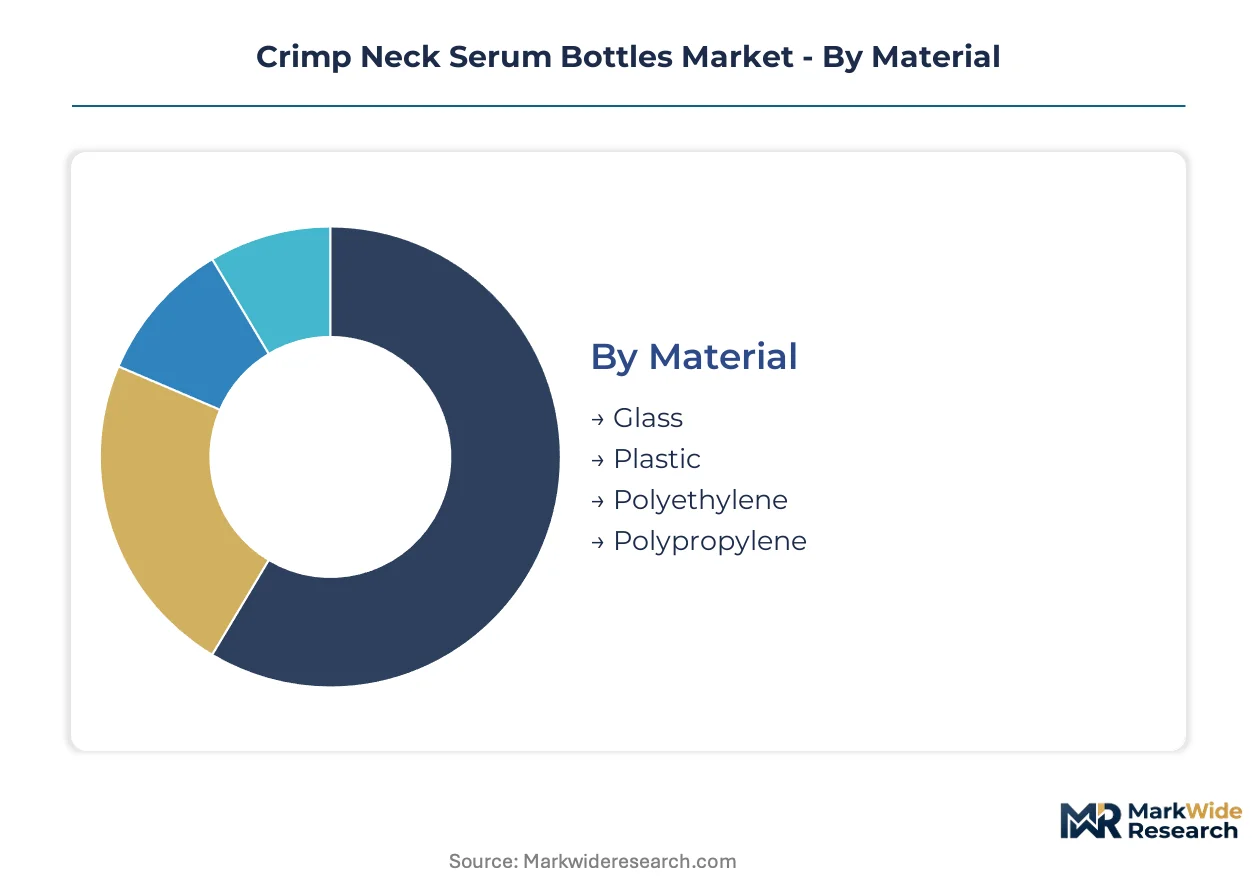
Material selection and volume configuration determine channel viability for crimp neck serum bottles, with pharmaceutical-grade specifications commanding premium distribution networks while cosmeceutical formats penetrate direct-to-consumer routes. Closure type and end-use segmentation further stratify procurement patterns, separating validated sterile supply chains from retail-oriented logistics.
Material:
Glass formulations dominate pharmaceutical procurement channels, while polymer alternatives fragment cosmeceutical sourcing through specialty converters and brand-direct arrangements.
- Glass:Type I borosilicate formulations deliver pharmacopeial compliance for parenteral biologics. Demand concentrates in German and Swiss sterile manufacturing clusters where EMA extractables documentation is mandatory for regulatory filings.
- Plastic:Polymer variants reduce breakage risk in e-commerce skincare distribution. French premium brands are piloting these materials for travel retail formats, though REACH migration testing imposes 12-18 month qualification barriers.
- Polyethylene:Lightweight barrier properties suit diagnostic reagent applications with moderate chemical resistance requirements.
- Polypropylene:Thermal stability supports autoclave sterilization protocols in research laboratory supply chains.
By volume, Glass leads. By growth pace, Plastic is expanding most quickly as cosmeceutical brands seek breakage elimination.
Volume:
Unit-dose sizing aligns with end-use economics, with smaller formats commanding per-milliliter premiums in clinical applications while larger vessels serve cost-sensitive bulk segments.
- 10mL:Standard unit-dose configuration for clinical trial materials and premium retail serums. German cosmeceutical production clusters around Frankfurt and Düsseldorf generate concentrated pull-through demand for this mid-range format.
- 1mL:Micro-dose specification for high-potency biologics and pediatric formulations. Swiss biopharma manufacturers favor this format for lyophilized stabilizers requiring precise reconstitution.
- 5mL:Compact sizing for sample programs and travel retail distribution in United Kingdom premium skincare channels.
- 20mL:Bulk format for research laboratory reagents and institutional diagnostic supply with lower per-unit handling costs.
By shipment frequency, 10mL dominates. By margin expansion, 1mL shows the steepest trajectory.
Closure Type:
Seal integrity requirements separate pharmaceutical and cosmeceutical procurement specifications, with tamper-evidence mandates driving aluminum crimp adoption in regulated channels.
- Crimp:Aluminum seal systems provide validated container closure integrity for parenteral applications. EMA MDR compliance documentation elevates this format in German and French biologics manufacturing where helium leak detection is mandatory.
- Pump:Metered dispensing suits direct-to-consumer skincare subscription models. United Kingdom e-commerce channels are displacing wholesale pharmacy distribution for this user-friendly format.
- Screw:Reclosable convenience dominates over-the-counter cosmeceutical retail in Netherlands pharmacy chains.
- Dropper:Pipette integration serves precision dosing in clinical testing and compounding pharmacy applications.
By regulatory acceptance, Crimp holds position. By channel expansion, Pump is gaining share fastest.
End User:
Validation depth and procurement scale diverge sharply across end-use segments, with biologics manufacturers consolidating supplier relationships while research laboratories fragment purchasing.
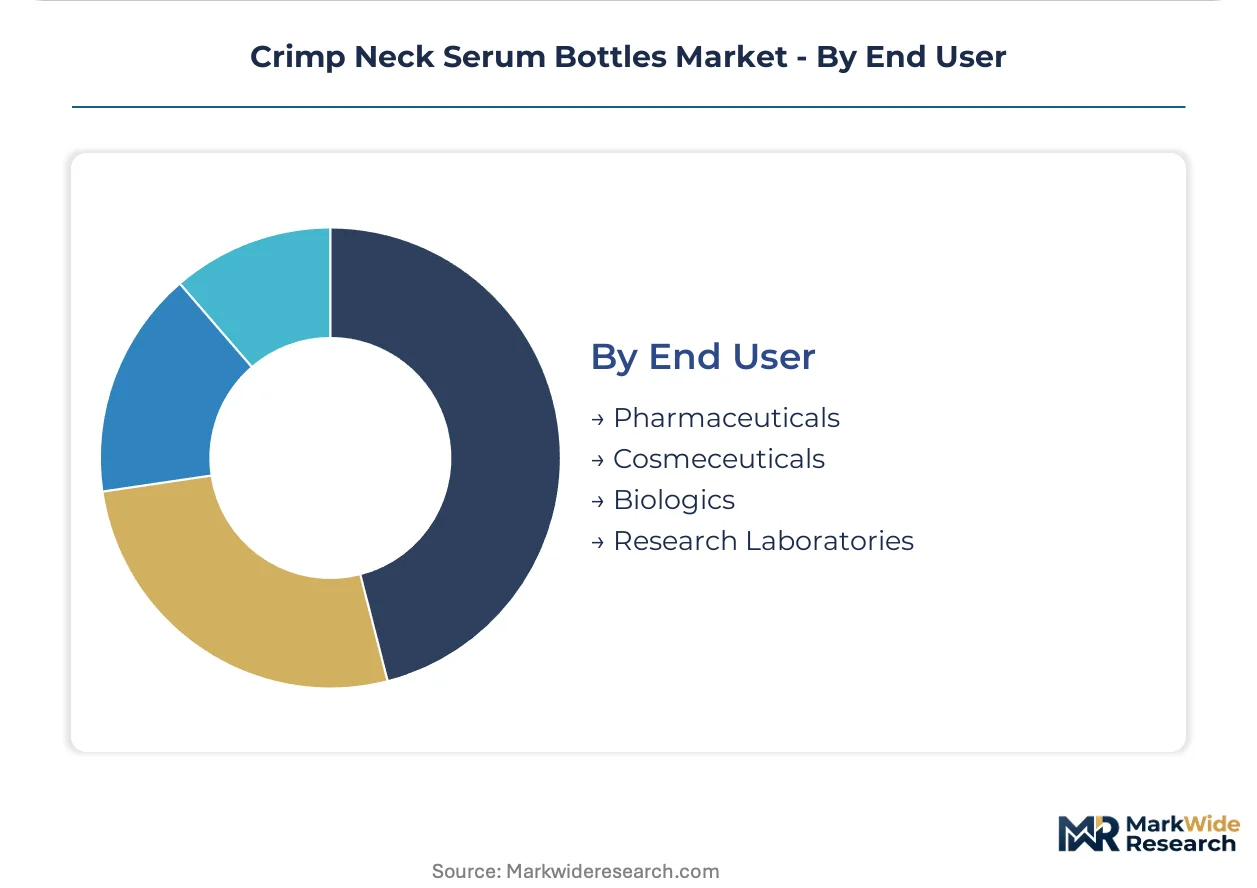
- Biologics:Sterile formulation producers demand exhaustive extractables libraries and dual-source glass strategies. German and Swiss manufacturers are consolidating procurement around certified specialists with documented CCIT capabilities.
- Cosmeceuticals:Premium skincare brands are building captive specification teams to bypass traditional distributors. French and United Kingdom direct-to-consumer channels favor polymer alternatives for weight reduction.
- Pharmaceuticals:Generic injectable manufacturers prioritize cost-optimized borosilicate sourcing with pharmacopeial minimums.
- Research Laboratories:Academic and clinical testing facilities in Netherlands clusters drive unit-dose demand for lyophilized diagnostic reagents.
By specification intensity, Biologics sets standards. By volume elasticity, Cosmeceuticals is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports pharmaceutical-grade crimp neck vials to Swiss biologics manufacturers and French cosmeceutical brands, establishing a north-south trade corridor across Continental Europe.
Germany
Frankfurt and Düsseldorf cosmeceutical clusters drive 10mL unit-dose demand for premium skincare applications. EMA pharmacopeial standards mandate Type I borosilicate compliance for sterile formulations. North Rhine-Westphalia hosts specialized aluminum crimp seal fabricators supplying validated container closure integrity systems to biologics contract manufacturers.
France
Paris-based luxury skincare houses are piloting cyclic olefin polymer alternatives for travel retail formats to eliminate breakage risk. REACH chemical compliance frameworks impose 12-18 month migration testing timelines for material switching. Île-de-France pharmaceutical packaging converters are building extractables documentation libraries to accelerate EMA pre-submission alignment.
United Kingdom
London and Southeast England direct-to-consumer subscription channels are displacing wholesale pharmacy distribution for pump-dispenser formats. MHRA post-Brexit regulatory autonomy creates potential for accelerated polymer vial qualification pathways distinct from continental EU timelines. Cambridge laboratory clusters drive unit-dose demand for lyophilized diagnostic reagents.
Switzerland
Swissmedic guidelines elevate barrier performance specifications for oxygen-sensitive biologic stabilizers. Basel and Zurich biopharma manufacturers favor 1mL micro-dose formats for high-potency parenteral applications requiring precise reconstitution. Swiss sterile formulation producers are consolidating procurement around certified packaging specialists with documented helium leak detection capabilities.
Netherlands
Amsterdam and Rotterdam diagnostic reagent manufacturers are opening unit-dose vial demand beyond traditional liquid serum formats for clinical testing applications. ECHA chemical compliance frameworks govern cyclic olefin polymer migration testing protocols. Randstad logistics hubs enable just-in-time delivery to German and French pharmaceutical manufacturing sites.
Crimp Neck Serum Bottles Market Competitive Environment
Listed leaders compete with private specialists across regulatory documentation depth, with public companies leveraging capital market access for extractables library investment while family-owned fabricators defend niche qualification relationships. The supplier base concentrates around three strategic tiers: pharmaceutical-grade glass specialists with EMA-certified sterile capabilities, polymer converters targeting cosmeceutical weight reduction, and diversified packaging conglomerates spanning multiple closure formats. Capacity expansion and strategic partnerships represent the dominant competitive moves, with firms securing dual-source arrangements to mitigate aluminum crimp seal supply concentration risks.
Among pharmaceutical-grade specialists, Nipro Pharmapackaging International exemplifies the regulatory-intensive archetype through its documented sterile formulation expertise, while DWK Life Sciences occupies a position within borosilicate glass pharmacopeial compliance. Adelphi Healthcare Packaging represents the custom configuration tier, anchoring supply relationships through specialized crimp seal geometries for high-value serum preservation applications.
| Leading Market Players |
|---|
| Nipro Pharmapackaging International |
| Top Syringe Manufacturing |
| O.Berk |
| Qorpak |
| Samkin Industries |
| Adelphi Healthcare Packaging |
| Adit Containers |
| DWK Life Sciences |
| Origin Pharma Packaging |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month extractables documentation timelines for polymer alternatives concentrate procurement leverage among German and French glass specialists with pre-validated EMA dossiers, compressing margin capture for mid-tier converters lacking pharmacopeial certification depth.
Pricing Analysis
Current-generation aluminum crimp seal systems command substantial premiums over legacy rubber-stopper configurations, while next-generation polymer vial formats remain in pre-qualification pricing limbo. Three-tier pricing structure across EMA-certified premium, standard pharmacopeial, and economy cosmetic grades separates biologics manufacturers from cosmeceutical brands. Cost compression in mid-tier borosilicate sourcing is intensifying because REACH migration testing burdens deter material switching. Generic injectable manufacturers exhibit highest price sensitivity, while Swiss biopharma sponsors accept substantial premiums for documented helium leak detection capabilities.
Supply Chain Analysis
Aluminum smelter capacity constraints in Germany and France constitute the primary chokepoint for closure system availability, with energy cost volatility transmitting directly into input pricing. Raw material flows draw from Belgian soda ash processors, Italian specialty glass furnaces, and Austrian aluminum rolling mills. Single-source vulnerability concentrates around North Rhine-Westphalia seal fabricators serving validated sterile supply chains. Distribution runs through Randstad logistics hubs enabling just-in-time delivery to Frankfurt and Düsseldorf manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR container closure integrity mandates are disrupting legacy procurement relationships, creating accelerated consolidation windows for suppliers with pre-built extractables libraries.
For Market Incumbents: Fortify EMA-certified sterile capabilities through dedicated borosilicate furnace investments in Germany, while securing dual-source aluminum crimp seal arrangements to mitigate energy-driven supply interruptions from French smelter concentration. Cyclic olefin polymer qualification acceleration by specialized converters threatens mid-tier glass positions in cosmeceutical channels. For New Entrants and Emerging Players: MHRA fast-track polymer equivalency pathways offer the most penetrable regulatory entry point for UK-based diagnostic reagent packaging. Target Cambridge laboratory clusters with 1mL lyophilized vial formats, leveraging post-Brexit divergence from continental EU migration testing timelines. Direct-to-consumer subscription channel partnerships provide immediate revenue traction without wholesale pharmacy distribution barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EMA documentation depth functions as a moat that compounds with each biologics sponsor relationship. Packaging specialists with 18-24 month toxicological assessment capabilities represent the priority acquisition archetype. Watch for Swissmedic guidance updates on oxygen-sensitive biologic barrier specifications as the inflection signal for next-generation material qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Pre-Submission Alignment Investment | Extractables library development accelerates polymer vial qualification timelines for German biologics sponsors. |
| Dual-Source Crimp Seal Fabrication | Geographic diversification mitigates aluminum smelter concentration risk across German and French suppliers. |
| MHRA Equivalency Pathway Exploitation | UK regulatory autonomy enables faster cyclic olefin polymer market entry versus continental EU timelines. |
| Direct-to-Consumer Channel Integration | Bypassing wholesale pharmacy distribution captures margin from London subscription skincare models. |
| Helium Leak Detection Capability Buildout | Validated CCIT expertise anchors supply relationships with Swiss high-potency biologics manufacturers. |
Study Parameters
The analysis maps borosilicate glass pharmacopeial compliance, cyclic olefin polymer migration testing, aluminum crimp seal fabrication, and diagnostic reagent packaging configurations, each validated through packaging procurement directors at biologics contract manufacturers, regulatory affairs leads at EMA-notified bodies, and sterile formulation engineers at German manufacturing clusters. Primary interview insights triangulate against EMA submission databases, REACH chemical compliance registries, Swissmedic guidance documents, and customs trade flow records. Bottom-up volume modeling from individual facility capacities reconciles with top-down segment value allocations.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions include material grade tier, volume configuration, closure type, and end-use regulatory intensity. CAGRs derive from facility expansion announcements, sponsor pipeline disclosures, and channel shift trajectories. Forecast inputs incorporate EMA equivalency guidance evolution and F-Gas Regulation phase-down incentives for ambient stability packaging.
Underlying assumptions cover sustained EMA pharmacopeial standard adherence, stable aluminum smelter energy cost structures, and gradual MHRA-EMA regulatory divergence, with deviation risk concentrated in REACH chemical compliance timeline extensions and polymer extractables documentation delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Cosmetic and Toiletry Containers Market
Cosmetic Packaging
Beauty Supplements Packaging Market
Cosmetic Packaging
Hair Care Packaging Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
Global Perfume Packaging Market
Cosmetic Packaging
Latin America Cosmetic Packaging Market
Cosmetic Packaging
Lip Care Packaging Market
Cosmetic Packaging
Lotion Tubes Market
Cosmetic Packaging
Cosmetic Pump Bottle Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Tubes Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market
Cosmetic Packaging
Latin America Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Bottles Packaging Market
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Global Cosmetic Packaging Market