
 China Personal Care Packaging Market | 2026-2036
China Personal Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Personal Care Packaging Market Outlook
Premium-grade mono-material and refillable specification tiers is unwinding legacy multilayer formats across China's personal care sector. HCP Packaging Co Ltd leverages its Guangzhou manufacturing base to dominate high-end skincare dispensing systems. Amcor PLC sustains technology leadership in recyclable flexible films for sachet and pouch formats. Silgan Holdings Inc anchors North American expertise into Chinese fragrance and aerosol metal packaging through specialized joint ventures.
China personal care packaging encompasses primary and secondary containment systems—ranging from polyethylene terephthalate bottles and polypropylene jars to aluminum tubes and folding cartons—engineered to protect formulation integrity, enable precise dosing, and convey brand identity at retail and digital touchpoints. Skincare and cosmetics segments command the deepest margin pools as domestic brands elevate unit economics through airless pump and double-wall jar architectures. Plastic retains volume dominance but faces structural displacement from glass in premium fragrance and from paperboard in e-commerce secondary packaging as SAMR intensifies post-consumer recycled content audits.
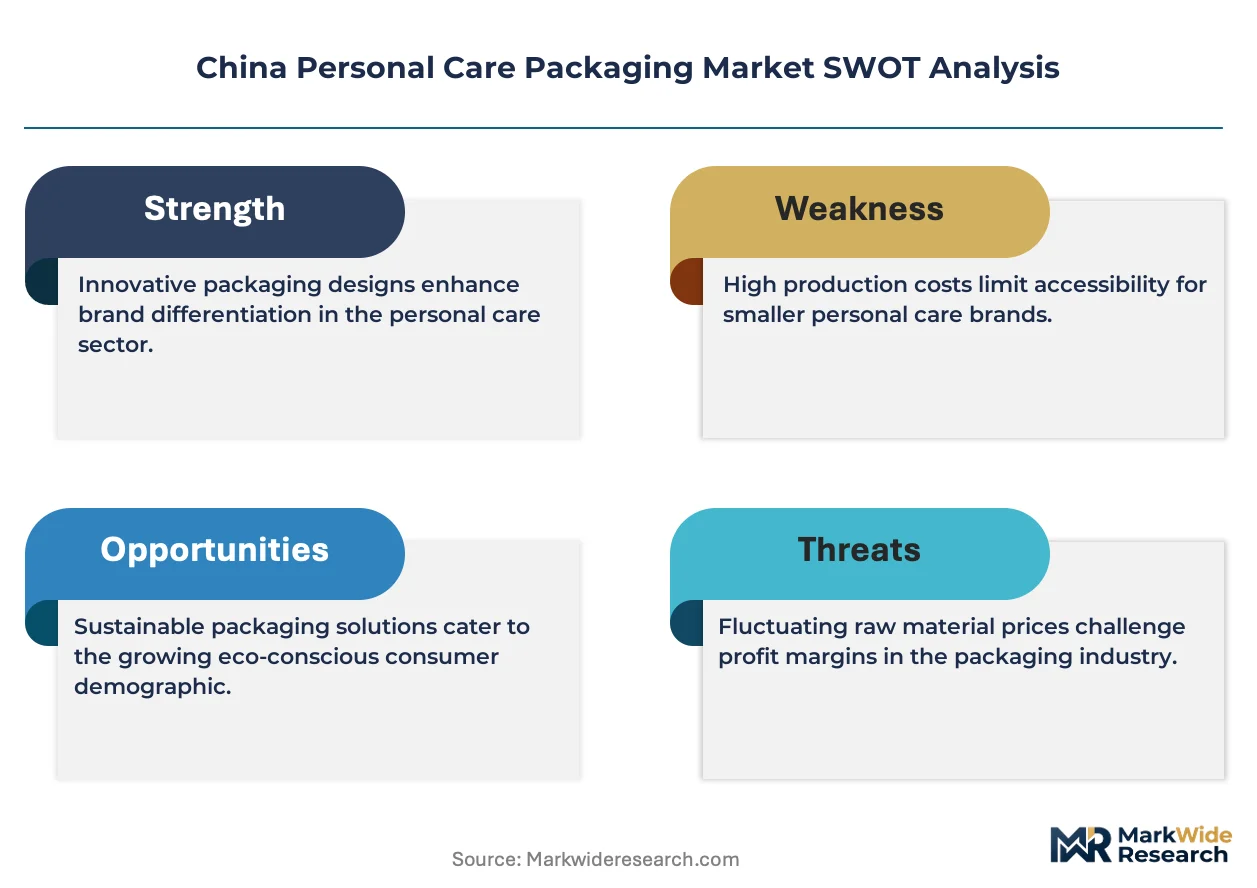
MIIT's GB standards for packaging recyclability and MEE enforcement of plastic pollution reduction timelines compel converters to revalidate material streams and submit compositional disclosures. NMPA cosmetic registration requirements further tighten primary packaging compatibility testing for active-ingredient stability. Stakeholders must weigh capital allocation between compliant mono-material conversion and emerging bio-based feedstock partnerships before regulatory phase-ins harden supply chain requirements.
Market Dynamics
MIIT's GB standards for packaging recyclability are forcing converters to revalidate entire material streams and submit compositional disclosures ahead of enforcement timelines, compressing legacy multilayer formats.
Growth Catalysts
- Dual carbon policy framework:China's national emissions targets compel brands to adopt refillable and mono-material architectures, accelerating specification upgrades across skincare and cosmetics segments.
- Yangtze River Delta concentration:Shanghai and Jiangsu province host dense clusters of cosmetic packaging converters and brand headquarters, enabling rapid prototype-to-production cycles for premium dispensing systems.
- Airless pump technology:Domestic brands elevate unit economics through double-wall jar and airless pump adoption, deepening margin pools in high-end skincare applications.
Market Restraints
- Post-consumer recycled content audits:SAMR intensifies compliance verification, creating documentation burdens and testing costs that squeeze mid-tier converters.
- Petrochemical feedstock volatility:Polypropylene and polyethylene terephthalate resin prices fluctuate with crude oil movements, compressing margin predictability for volume producers.
- Glass substitution in premium fragrance:Aesthetic and sustainability preferences displace plastic in high-end perfume packaging, eroding plastic's share in the deepest margin tier.
Strategic Opportunities
- Guangzhou manufacturing base expansion:South China's packaging hub offers underutilized capacity for brands seeking geographic diversification beyond the Yangtze cluster.
- Bio-based feedstock partnerships:Early alliances with agricultural-derived polymer suppliers position converters ahead of MEE plastic pollution reduction phase-ins.
- E-commerce secondary packaging:Paperboard demand surges for unboxing experiences and shipping protection, opening new revenue streams beyond primary containment.
Industry Challenges
- NMPA registration compatibility testing:Cosmetic registration requirements tighten primary packaging validation timelines, forcing reformulation or redesign cycles that delay product launches.
- Mono-material conversion capex:Retooling extrusion and molding lines for recyclable single-stream formats demands capital allocation ahead of confirmed return thresholds.
- Active-ingredient stability expertise:Formulation chemistry knowledge gaps in packaging converter R&D teams complicate barrier property specification for sensitive skincare actives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Personal Care Packaging Market |
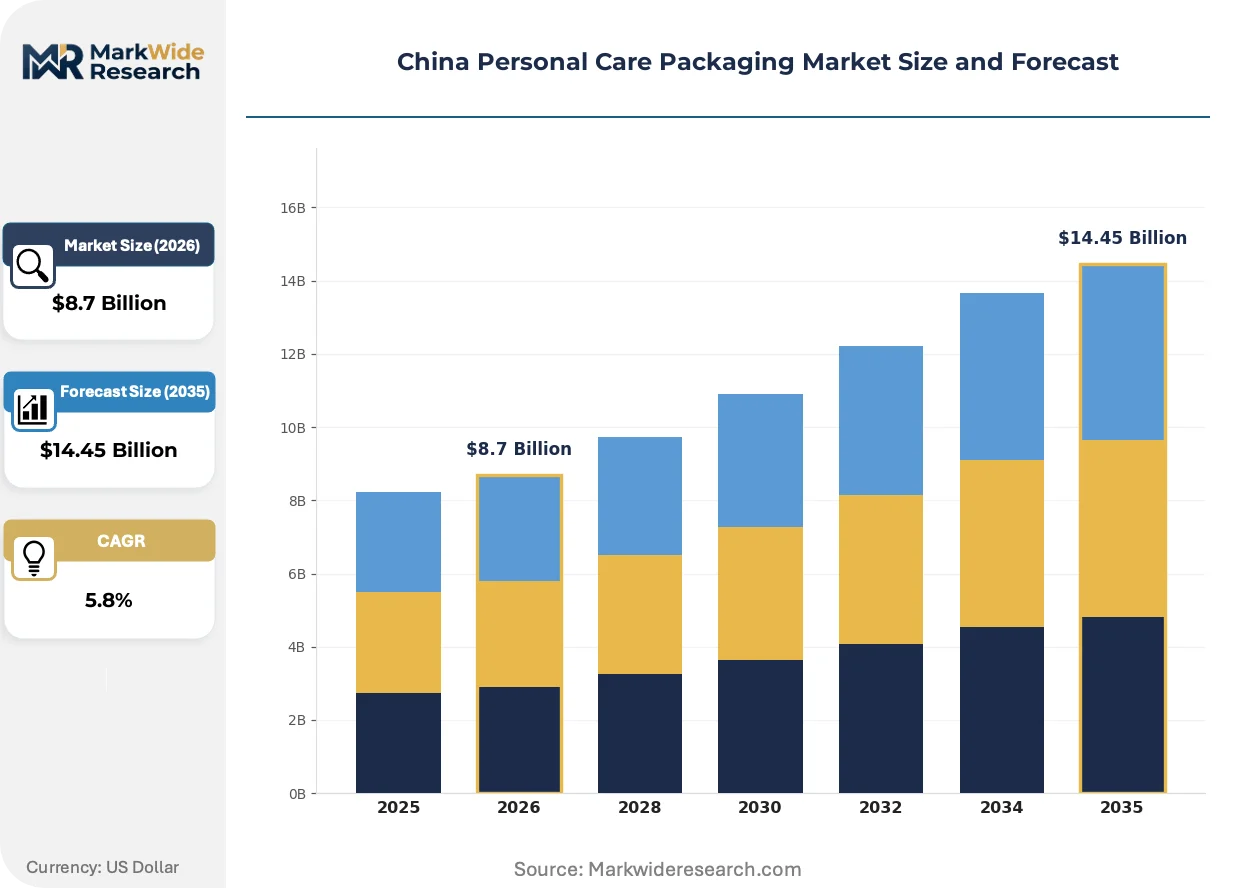
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Cosmetics, Fragrances Packaging Material: Plastic, Glass, Metal, Paper Closure Type: Screw Caps, Flip Tops, Pumps, Sprayers End User: Retailers, E-Commerce, Direct Sales, Wholesalers |
| Companies Covered | Albea SA, HCP Packaging Co Ltd, RPC Group Plc, Silgan Holdings Inc, DS Smith PLC, Amcor PLC, Bemis Company Inc, Quadpack Industries SA, Rieke Packaging Systems Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Personal Care Packaging Market Strategic Shifts
Material science advances and regulatory enforcement timelines are compressing legacy formats while opening specification territory for bio-derived and mechanically recyclable alternatives.
Mono-material flexible films are decomposing multilayer laminate dominance in sachet and pouch formats. Domestic skincare brands adopt these structures at accelerating pace to preempt SAMR audit requirements. This shift is decomposing incumbent converter relationships built on proprietary coextrusion expertise.
MEE enforcement of plastic pollution reduction timelines tightens operational windows for compliance. Industrial consequence includes mandatory compositional disclosure submissions and revalidated supply chain certifications. Small and mid-tier converters in Jiangsu province face the steepest adaptation costs.
Refillable architecture adoption concentrates in premium skincare as brands seek differentiation through sustainability credentials. Direct-to-consumer channels and flagship retail locations install bulk dispensing infrastructure to support repeat purchase models. Shanghai-based domestic brands lead this specification shift.
China Personal Care Packaging Market Segmentation
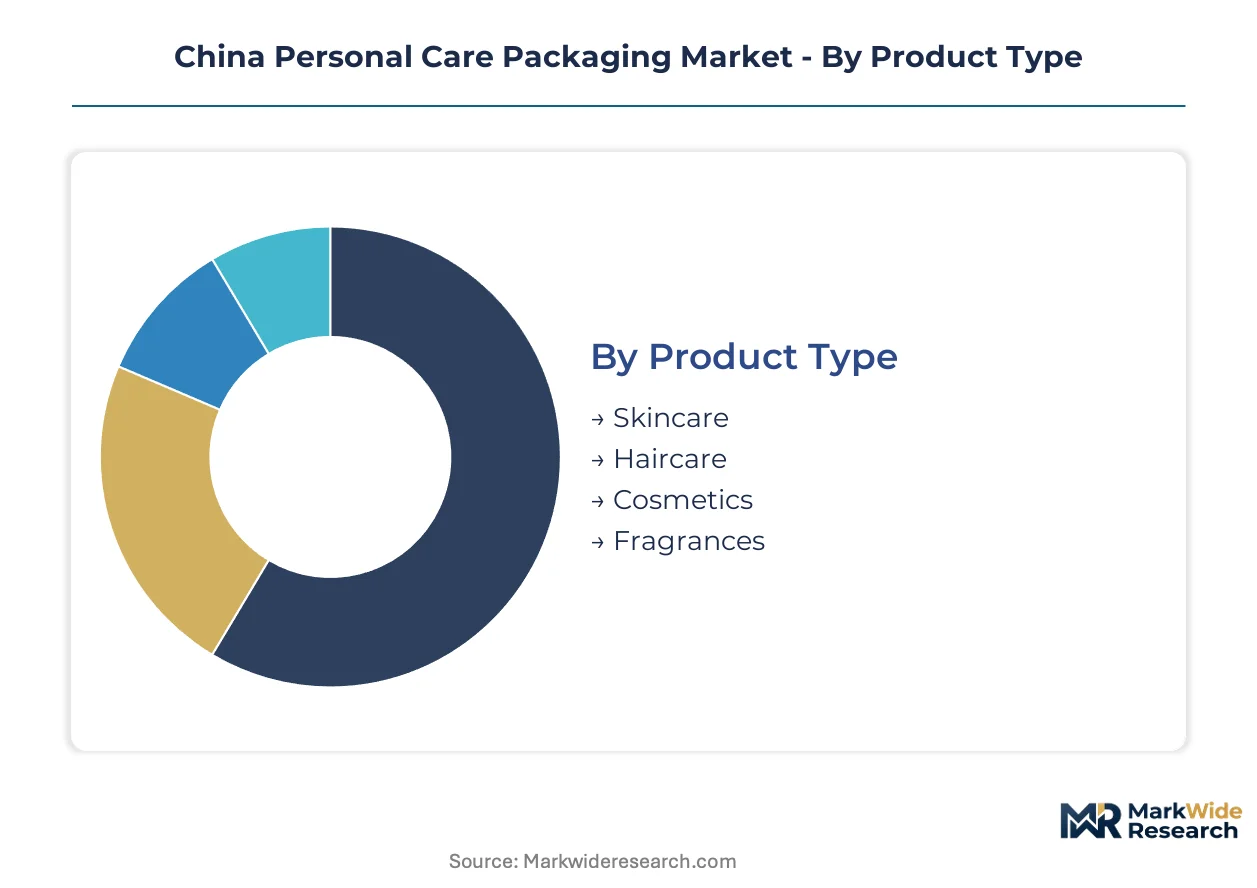
Segmentation reveals how regulatory pressure and channel migration are reallocating value across material and closure specifications in China's personal care packaging sector. Domestic consumption patterns diverge sharply from export-oriented production, with each segment responding to distinct compliance timelines and brand positioning strategies.
Product Type:
Domestic demand concentrates in skincare and cosmetics as Shanghai-based brands elevate premium positioning, while haircare and fragrances retain stronger export orientation toward Southeast Asian markets.
- Skincare:Airless pump bottles and double-wall jars dominate specification sheets as domestic brands pursue mono-material compliance ahead of MIIT enforcement timelines. Demand clusters in Jiangsu province converters serving Shanghai headquarters operations.
- Cosmetics:Refillable compact architectures and magnetic closure systems command premium positioning as brands differentiate through sustainability credentials. Yangtze River Delta manufacturing bases enable rapid prototype iteration for color cosmetics launches.
- Haircare:High-density polyethylene bottles and polypropylene flip-cap formats retain volume dominance in mass-market distribution. Export production concentrates in Guangzhou for Southeast Asian private label contracts.
- Fragrances:Glass bottle substitution accelerates in premium tiers as aesthetic and dual carbon considerations displace plastic. Metal aerosol systems anchor North American joint venture expertise in Jiangsu production facilities.
Skincare commands the established base. The steepest expansion runs through cosmetics as refillable architectures gain specification share.
Packaging Material:
Cost tier stratification separates commodity resin applications from glass and metal specifications serving margin-intensive premium segments.
- Plastic:Polyethylene terephthalate bottles and polypropylene jars retain volume leadership across mass-market skincare and haircare. SAMR post-consumer recycled content audits are forcing compositional revalidation and supply chain certification updates.
- Glass:Premium fragrance and high-end skincare adoption accelerates as brands respond to aesthetic preferences and GB recyclability standards. MEE plastic pollution reduction timelines tighten operational windows for converter qualification.
- Metal:Aluminum tubes and aerosol canisters serve fragrance and haircare applications with established barrier properties. Joint venture structures import North American technical expertise for precision forming operations.
- Paper:E-commerce secondary packaging and folding cartons expand as unboxing experiences drive brand differentiation. Demand concentrates in direct-to-consumer channel fulfillment operations.
Plastic retains volume dominance. Glass is gaining share fastest in premium tier displacement.
Closure Type:
Application-specific dispensing requirements separate precision pump systems for sensitive actives from commodity closure formats in mass haircare.
- Pumps:Airless dispensing systems command premium positioning in skincare as brands validate active-ingredient stability through NMPA registration protocols. Technical specification requires barrier property expertise concentrated in Guangzhou manufacturing bases.
- Screw Caps:Polypropylene and polyethylene closures serve haircare and basic skincare with established cost efficiency. Volume production concentrates in Jiangsu province for domestic brand supply contracts.
- Flip Tops:One-handed dispensing formats dominate shower and haircare applications with convenience-driven consumer preference. Specification standardization enables converter scale economies across mass-market production.
- Sprayers:Fine-mist and aerosol systems serve fragrance and haircare styling products with precision dosing requirements. Metal valve integration demands specialized joint venture technical partnerships.
Screw caps command the established base. Pumps are expanding most quickly as airless technology penetrates premium skincare.
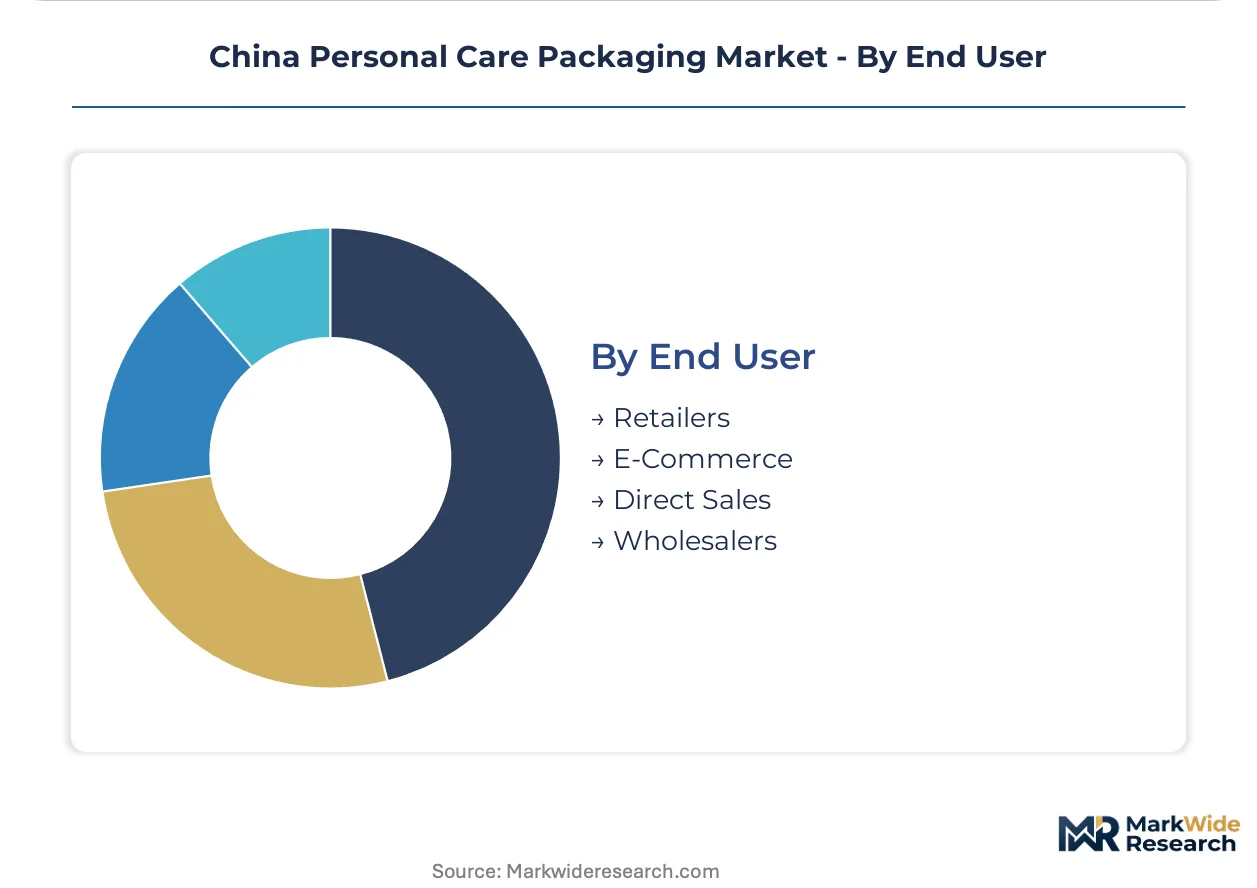
End User:
Channel configuration determines packaging specification complexity, with e-commerce driving secondary packaging innovation and direct sales enabling refillable infrastructure investment.
- E-Commerce:Shipping protection requirements and unboxing experience design drive paperboard secondary packaging specification. Shanghai-based brands lead investment in sustainable fulfillment packaging ahead of MEE enforcement timelines.
- Retailers:Shelf presence and dispensing ergonomics dominate primary packaging design for department store and specialty channel distribution. Counter display compatibility constrains dimensional specification ranges.
- Direct Sales:Bulk dispensing infrastructure and refillable architecture adoption concentrate in flagship locations and subscription models. Repeat purchase economics justify capital investment in durable primary container systems.
- Wholesalers:Standardized case packs and pallet efficiency drive secondary packaging specification for mass-market haircare and basic skincare. Cost minimization priorities favor established plastic bottle and closure formats.
Retailers command the established base. E-commerce shows the steepest expansion trajectory as channel share shifts accelerate specification change.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in mass-market haircare segments demonstrate acute price sensitivity, while premium skincare purchasers absorb specification premiums for mono-material compliance. This elasticity divergence concentrates converter investment in Yangtze River Delta clusters serving domestic brand headquarters.
Yangtze River Delta
Shanghai-based domestic brands drive airless pump and double-wall jar specifications for premium skincare positioning. MIIT's GB standards for packaging recyclability compel converters in Jiangsu province to revalidate material streams ahead of enforcement timelines. Suzhou and Wuxi host the densest concentration of cosmetic packaging converters serving rapid prototype-to-production cycles.
Pearl River Delta
Guangzhou manufacturing bases supply high-end skincare dispensing systems with technical barrier property expertise for sensitive actives. MEE enforcement of plastic pollution reduction timelines tightens operational windows for converter qualification. Dongguan and Shenzhen facilities specialize in precision molding for color cosmetics refillable architectures.
Beijing-Tianjin-Hebei
Direct-to-consumer channel fulfillment operations concentrate demand for paperboard secondary packaging and sustainable unboxing experiences. SAMR intensifies post-consumer recycled content audits, creating documentation burdens for e-commerce packaging suppliers. Tianjin port infrastructure supports import of specialized resin grades for compliant mono-material conversion.
Sichuan-Chongqing
Western China markets exhibit growing specification sophistication as domestic brands expand beyond coastal headquarters. NMPA cosmetic registration requirements tighten primary packaging compatibility testing timelines for brands entering this consumer base. Chengdu converter facilities serve as secondary supply nodes for brands seeking geographic diversification from Yangtze concentration.
Shandong Peninsula
Mass-market haircare production for Southeast Asian export contracts concentrates in Qingdao and Yantai facilities. Petrochemical feedstock volatility in polypropylene and polyethylene terephthalate resin compresses margin predictability for volume producers. Local converters optimize standardized case pack efficiency for wholesaler distribution channels.
China Personal Care Packaging Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Market concentration splits between multinational converters with proprietary dispensing system expertise and domestic fabricators optimized for scale production of standardized formats. Three strategic archetypes dominate: premium dispensing system specialists, flexible film technology leaders, and diversified packaging conglomerates with cross-material portfolios. Competitive moves center on mono-material conversion capex deployment and bio-based feedstock partnership formation ahead of regulatory phase-ins.
Among the named players in this sector, HCP Packaging Co Ltd and Amcor PLC occupy positions as archetype anchors for premium dispensing and flexible film technologies respectively. Silgan Holdings Inc exemplifies the specialized joint venture model for metal packaging applications. These three companies represent distinct strategic postures within a market where converter relationships are decomposing as brands requalify supply chains for GB standard compliance.
| Leading Market Players |
|---|
| Albea SA |
| HCP Packaging Co Ltd |
| RPC Group Plc |
| Silgan Holdings Inc |
| DS Smith PLC |
| Amcor PLC |
| Bemis Company Inc |
| Quadpack Industries SA |
| Rieke Packaging Systems Ltd |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day prototype-to-production cycles in the Yangtze River Delta concentrate converter capacity and pricing power among Jiangsu province fabricators serving Shanghai brand headquarters, while Guangzhou facilities command premiums for airless pump technical expertise. This geographic asymmetry shapes how domestic brands negotiate specification tiers and how mid-tier converters absorb cost compression from SAMR compliance audits.
Pricing Analysis
Refillable architecture service revenue and repeat-purchase subscription models drive lifetime value for premium skincare brands investing in bulk dispensing infrastructure. Three-tier pricing structure across premium mono-material specifications, standard multilayer formats, and economy polyethylene terephthalate bottles separates compliance-grade offerings from commodity resin applications. Pricing pressure stems from petrochemical feedstock volatility compressing margin predictability for volume producers in haircare segments. Mass-market haircare purchasers demonstrate acute price sensitivity, while premium skincare buyers absorb specification premiums for NMPA-compatible airless pump systems.
Supply Chain Analysis
Port congestion at Shanghai and Ningbo-Zhoushan tightens inbound logistics for specialized polypropylene and polyethylene terephthalate resin grades imported for compliant mono-material conversion. Raw material supply draws from Saudi Arabia for virgin resin feedstocks, South Korea for specialty polymer additives, and domestic Sinopec facilities for commodity-grade volumes. Single-source vulnerability concentrates in Guangzhou-based airless pump valve components requiring North American joint venture technical partnerships. Distribution runs through direct-to-consumer fulfillment centers in Beijing-Tianjin-Hebei for e-commerce secondary packaging, with wholesale channels in Shandong Peninsula serving Southeast Asian export contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's personal care packaging sector sits in early-cycle expansion as domestic brands accelerate refillable architecture adoption ahead of MEE plastic pollution reduction enforcement timelines. Dual carbon policy compliance creates sustained specification upgrade demand across the projection horizon.
For Market Incumbents: Compound technology leadership in airless pump barrier properties through captive R&D investment in Guangzhou manufacturing bases, defending against emerging domestic converter entrants acquiring European dispensing system licenses. Prioritize backward integration into post-consumer recycled resin streams to preempt SAMR audit documentation burdens squeezing mid-tier competitors. For New Entrants and Emerging Players: Anchor in Sichuan-Chongqing secondary supply nodes where NMPA registration requirements tighten validation timelines but converter capacity remains underdeveloped relative to coastal clusters. Target wholesale distribution channels for standardized haircare formats where specification complexity remains lowest and private label contract opportunities concentrate in Qingdao export facilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underperforming China personal care divisions lacking mono-material conversion capex deployment. Long-term viability hinges on regulatory compliance technology rather than commodity resin scale. Watch for MIIT enforcement timeline acceleration as the inflection signal compressing operational windows for non-compliant legacy multilayer inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Conversion Capex Deployment | Retooling extrusion lines for GB standard compliance ahead of MIIT enforcement hardens supply chain positioning. |
| Bio-Based Feedstock Partnership Formation | Early alliances with agricultural-derived polymer suppliers position converters ahead of MEE plastic reduction phase-ins. |
| Refillable Architecture Infrastructure Investment | Bulk dispensing systems in flagship retail locations enable repeat-purchase economics for domestic skincare brands. |
| E-Commerce Secondary Packaging Expansion | Paperboard unboxing experiences drive brand differentiation in Shanghai-based direct-to-consumer fulfillment operations. |
| Airless Pump Technical Licensing Acquisition | European dispensing system expertise transfers strengthen barrier property specifications for NMPA-active-ingredient stability testing. |
Study Parameters
A spread of perspectives from packaging converter operations directors, cosmetic brand supply chain managers, NMPA regulatory affairs consultants, and resin procurement leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through MIIT GB standard documentation, SAMR compliance bulletins, customs trade data for polymer imports, and SEC filings from multinational packaging conglomerates. Bottom-up segment sizing triangulated against top-down market value estimates from industrial association disclosures.
Segmentation dimensions modeled include product type tier, packaging material grade, closure system complexity, and end-user channel configuration across the projection horizon. CAGRs derived from historical volume trajectories adjusted for regulatory enforcement timeline impacts and brand specification shift velocities. Forecast inputs incorporated dual carbon policy adoption curves and e-commerce channel penetration rates for secondary packaging demand.
Underlying assumptions cover sustained MIIT enforcement timelines and stable petrochemical feedstock pricing bands, with deviation risk concentrated in MEE acceleration of plastic pollution reduction schedules or NMPA registration protocol revisions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Lotion Tubes Market
Cosmetic Packaging
Anti-Counterfeit Cosmetic Packaging Market
Cosmetic Packaging
Make-Up Products Packaging Market
Cosmetic Packaging
India Personal Care Packaging Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
Beauty Supplements Packaging Market
Cosmetic Packaging
Europe Personal Care Packaging Market
Cosmetic Packaging
Latin America Cosmetic Packaging Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Hair Care Packaging Market
Cosmetic Packaging
Beauty and Personal Care Packaging Market
Cosmetic Packaging
Skin Care Packaging Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
Cosmetic Bottles Packaging Market