
 Plastic Cosmetic Packaging Market | 2026-2036
Plastic Cosmetic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Cosmetic Packaging Market Analytics
Prestige skincare is hardening as the dominant demand vertical for plastic cosmetic packaging, eclipsing traditional fragrance and color cosmetics in volume commitment. AptarGroup Inc. leverages its airless pump technology leadership to capture premium formulation accounts. Berry Global Inc. sustains massive blow-molding capacity across North American personal care corridors. Albea Group anchors European supply through its dedicated beauty packaging division.
Plastic cosmetic packaging encompasses engineered polymer containers, closures, and dispensing systems designed to protect, preserve, and present topical formulations through controlled barrier properties and precise dosage delivery. These systems typically incorporate multi-layer co-injection or injection-stretch blow molding to achieve oxygen transmission rates below 0.1 cc per day for oxidation-sensitive actives. Jars retain dominance in prestige creams and balms where wide-mouth access supports tactile application rituals. Tubes are displacing bottles in travel-size and masstige segments due to collapsible efficiency and lower material intensity per milliliter dispensed. PET bottles command the largest material share in haircare and body care, though polypropylene is gaining in hot-fill and chemical-resistant applications.
The U.S. FDA maintains cosmetic packaging safety standards under the Federal Food, Drug, and Cosmetic Act, while the EPA regulates resin manufacturing emissions and recycled content claims. The EU's REACH framework restricts phthalate plasticizers and mandates substance-of-very-high-concern disclosure across cosmetic contact materials. China's SAMR enforces GB standards for plastic food-contact materials that extend to cosmetic packaging through cross-referenced hygiene requirements. Stakeholders must monitor how extended producer responsibility schemes in California, France, and Japan will reshape resin selection and post-consumer collection infrastructure without assuming uniform global compliance timelines.
Market Dynamics
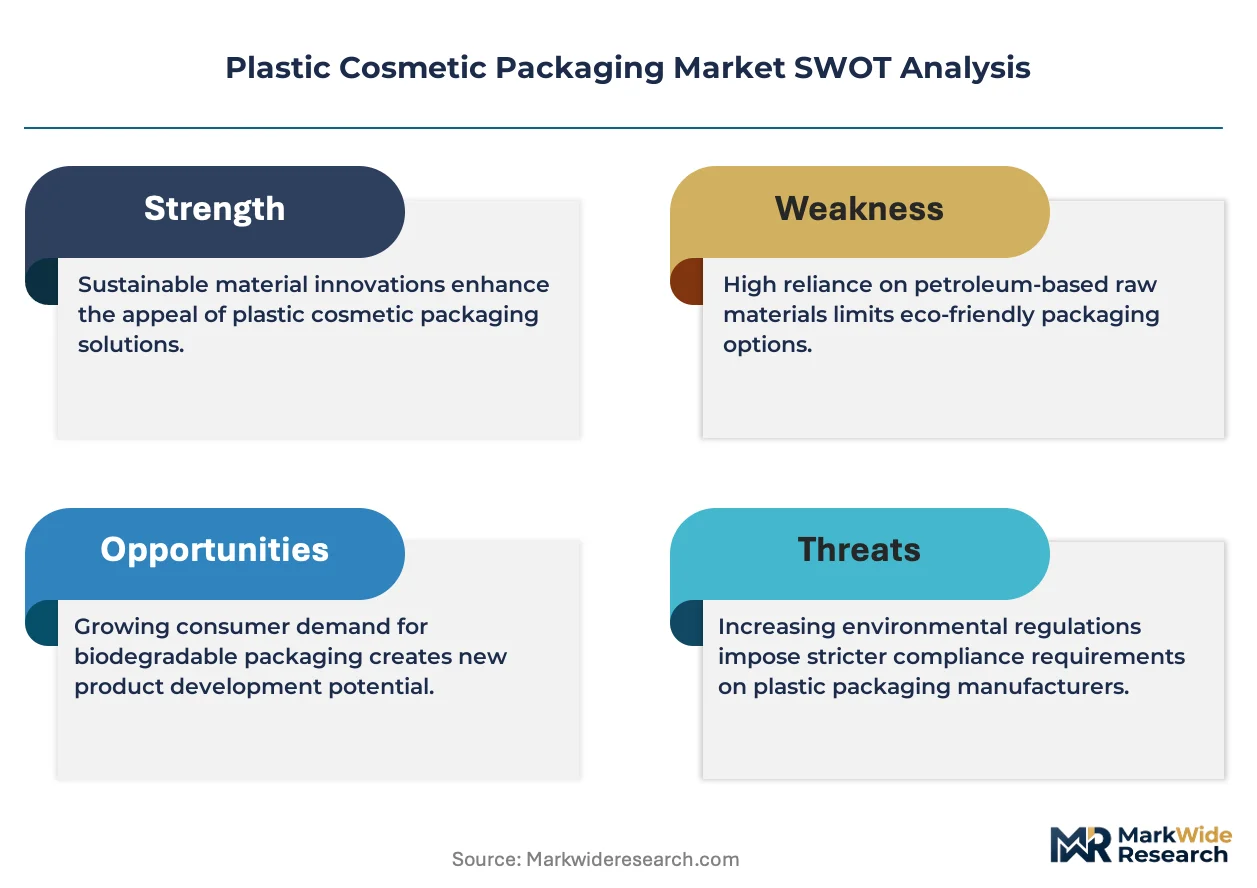
EU Packaging and Packaging Waste Regulation mandates are compressing material choices toward mono-material formats, forcing converters to re-engineer multi-layer barrier systems without sacrificing oxygen transmission performance.
Growth Catalysts
- REACH substance restrictions:Phthalate plasticizer bans under ECHA frameworks accelerate bio-based polymer R&D investment across European formulation houses.
- Airless pump technology:Retinol and vitamin C preservation requirements drive skincare brands toward piston-based dispensing systems with sub-0.1 cc daily oxygen permeability.
- German manufacturing clusters:Hamburg and Düsseldorf concentration of premium beauty houses creates dense supplier ecosystems for rapid prototyping and short-run customization.
Market Restraints
- Recycled PET feedstock volatility:Post-consumer rPET flake availability fluctuates with collection infrastructure gaps in Southern and Eastern European markets.
- Hot-fill polypropylene technical ceiling:Temperature resistance limitations above 85°C restrict material substitution in autoclave-sterilized pharmaceutical-cosmetic hybrids.
- Chinese GB standard cross-referencing:SAMR hygiene requirements extending food-contact rules to cosmetic packaging create compliance friction for imported formats.
Strategic Opportunities
- Indian masstige expansion:Tier-2 and Tier-3 city consumption growth creates demand for collapsible tube formats at price points below rigid bottle alternatives.
- Japan METI circular economy roadmaps:Design-for-recycling incentives reward mono-material pump systems with streamlined post-consumer sorting.
- Direct-to-consumer channel maturation:Subscription box fulfillment requirements favor lightweight, shatter-resistant polymer formats over glass for shipping economics.
Industry Challenges
- Multi-layer delamination expertise:Co-injection molding technicians capable of maintaining barrier layer adhesion across temperature cycling remain scarce in North American converter workforces.
- Extended producer responsibility integration:California, France, and Japan divergent collection infrastructure timelines force parallel compliance system maintenance without harmonized data reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Cosmetic Packaging Market |
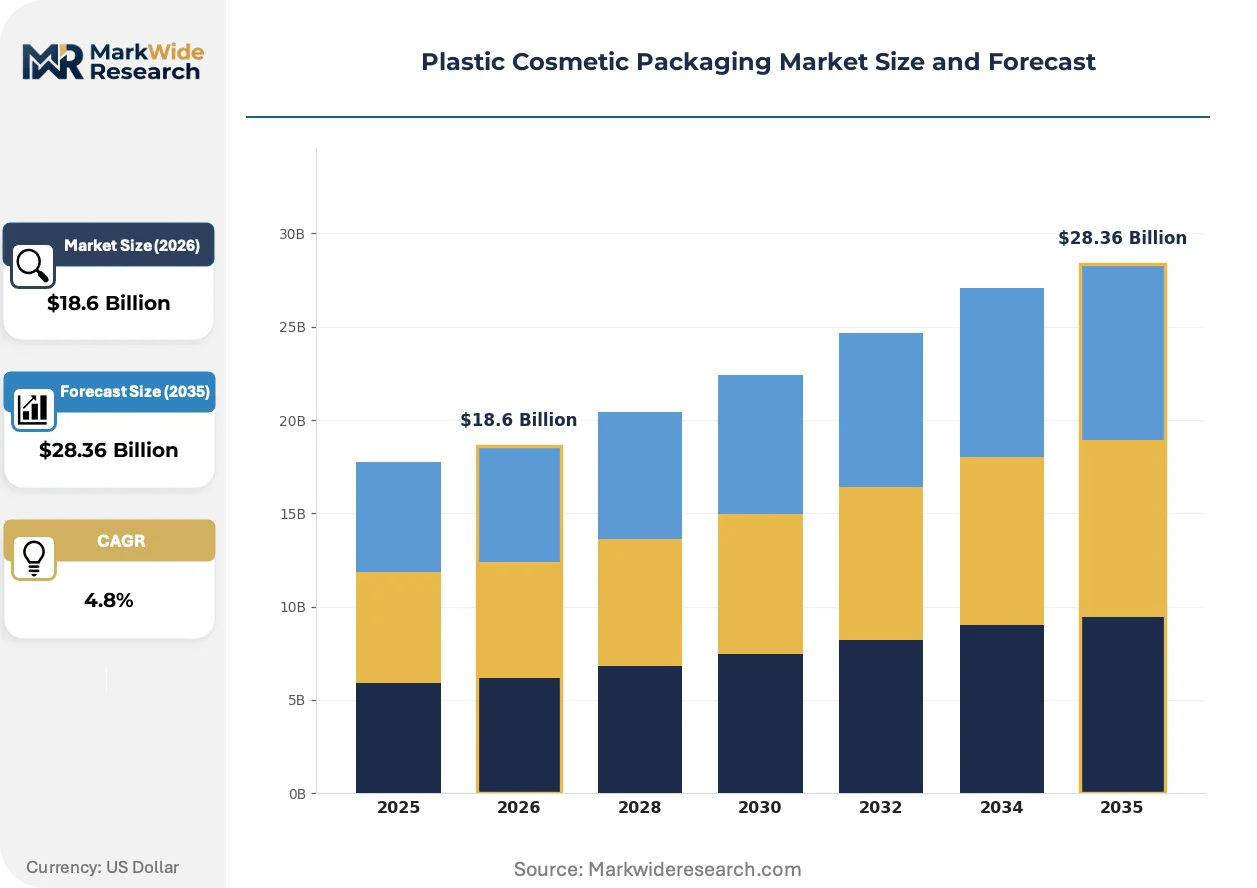
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $28.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jars, Bottles, Tubes, Dispensers Material: Polyethylene, Polypropylene, PET, PVC Closure Type: Screw Caps, Flip Tops, Pumps, Spray Caps End User: Skincare, Makeup, Haircare, Fragrance |
| Companies Covered | Amcor plc, AptarGroup Inc., Berry Global Inc., Albea Group, Silgan Holdings Inc., Gerresheimer AG, DS Smith PLC, HCP Packaging, Quadpack Industries SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Cosmetic Packaging Market Evolving Landscape
Material science convergence with regulatory design mandates is collapsing traditional packaging hierarchies, replacing heritage format preferences with performance-specified polymer selection.
Mono-material polyethylene pump systems are modularizing formerly complex multi-component assemblies into single-resin dispensers compatible with existing HDPE recycling streams. Prestige skincare houses in Germany and France are piloting these formats for serum and eye cream applications. The technology is modularizing supply chains by eliminating separate spring and glass ball procurement while simplifying post-consumer sortation.
REACH substance-of-very-high-concern disclosure expansion is compelling raw material inventory overhauls across European cosmetic packaging converters. ECHA candidate list updates now capture previously exempt polymer additives used in clarity-enhancing masterbatches. Color cosmetics and sun care segments face compressed reformulation timelines as downstream brands demand full supply chain transparency documentation.
Refill and reuse system adoption is restructuring primary packaging economics toward durable outer shells with standardized inner cartridges. Prestige fragrance and skincare houses in France and the United Kingdom are deploying deposit-return schemes for heavy-wall polypropylene jars and compacts. German retail partnerships with dm-drogerie markt and Douglas are accelerating consumer habit formation for return-and-refill models in masstige segments.
Plastic Cosmetic Packaging Market Segmentation
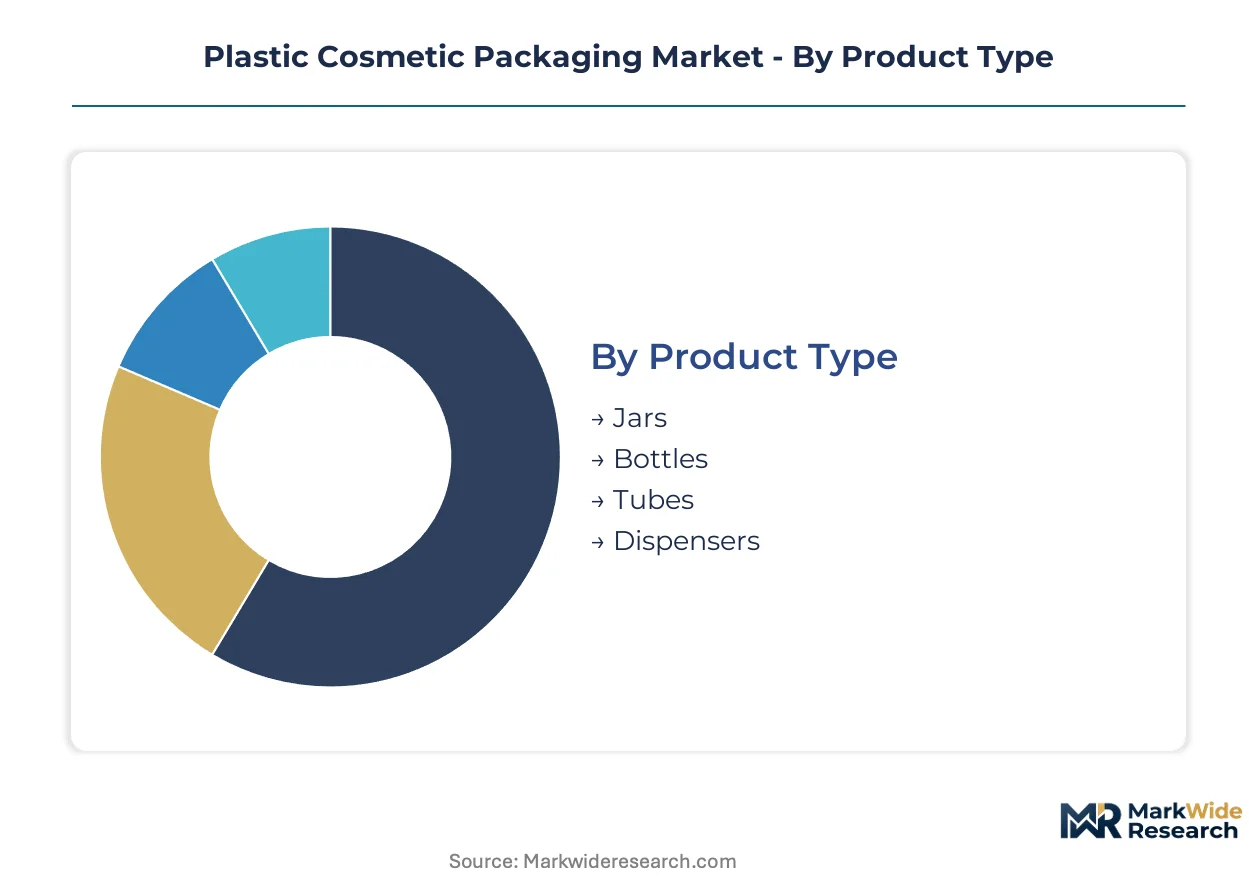
Segmentation in plastic cosmetic packaging reveals how formulation chemistry, dispensing mechanics, and retail channel requirements create divergent specification clusters. Each dimension carries distinct regulatory burdens and resin selection constraints that shape converter capabilities and brand procurement strategies.
Product Type:
REACH substance restrictions and FDA cosmetic safety standards impose varying testing protocols across container geometries, with wide-mouth formats facing heightened migration risk assessments.
- Jars:Wide-mouth polypropylene or polyethylene containers engineered for 50-500ml cream and balm formulations. Demand concentrates in German prestige skincare houses where tactile application rituals support premium positioning, though ECHA scrutiny of antioxidant additives in jar walls complicates formulation compatibility testing.
- Dispensers:Airless pump systems incorporating piston mechanisms and sub-0.1 cc daily oxygen transmission barriers for retinol and vitamin C preservation. Skincare brands in Hamburg and Düsseldorf drive specification intensity as contract manufacturers prototype mono-material alternatives to satisfy EU Packaging and Packaging Waste Regulation mandates.
- Bottles:Injection-stretch blow molded PET or HDPE containers for 100-1000ml liquid formulations.
- Tubes:Collapsible laminated or mono-material extrusions for viscous and semi-solid products.
Leading the category by volume: Bottles. Growing fastest: Dispensers.
Material:
Cost tier stratification separates commodity resins from engineered polymers with enhanced barrier or aesthetic properties.
- PET:Crystalline polyester with clarity and oxygen barrier performance dominating haircare and body care bottle applications. North American converters leverage massive blow-molding capacity along personal care manufacturing corridors, though rPET flake availability volatility in Southern and Eastern European collection markets constrains recycled content claims.
- Polypropylene:Semi-crystalline olefin with hot-fill tolerance to 85°C and chemical resistance for autoclave-sterilized pharmaceutical-cosmetic hybrids. Japanese METI circular economy roadmaps reward mono-material PP pump systems with streamlined post-consumer sorting economics.
- Polyethylene:Flexible and rigid grades for tubes, jars, and closure components.
- PVC:Chlorinated polymer with clarity and barrier properties in declining use due to ECHA substance-of-very-high-concern disclosure requirements.
PET commands the largest volume position. Polypropylene gains share fastest in hot-fill and airless applications.
Closure Type:
Application-specific dispensing precision determines closure selection, with skincare actives demanding engineered pump mechanisms over simple threaded seals.
- Pumps:Piston or pre-compression dispensers delivering 0.1-2.0ml doses with oxygen exclusion for oxidation-sensitive formulations. German premium beauty houses specify mono-material PE pump systems compatible with existing HDPE recycling streams, eliminating separate metal spring procurement.
- Screw Caps:Threaded polyethylene or polypropylene closures for standard bottles and jars.
- Flip Tops:Hinged polypropylene lids for single-handed dispensing in shower and travel environments.
- Spray Caps:Aerosol or finger-pump atomizers for fragrance and haircare fine-mist delivery.
Screw caps dominate unit volume. Pumps exhibit the steepest expansion trajectory on skincare premiumization.
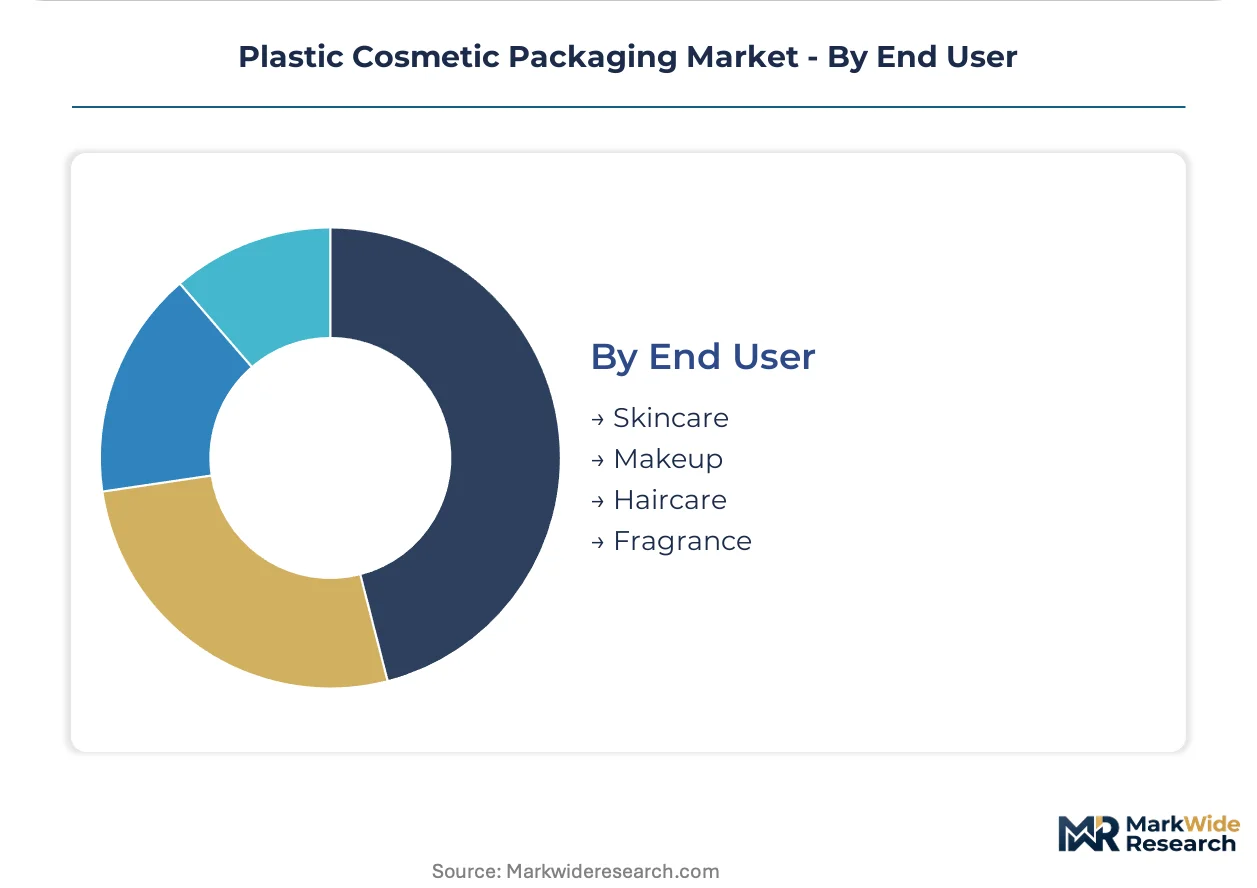
End User:
Customer type segmentation maps formulation chemistry complexity to packaging barrier requirements and regulatory exposure.
- Skincare:Retinol, vitamin C, and peptide formulations demanding sub-0.1 cc daily oxygen permeability through airless pump or multi-layer jar systems. French and German prestige houses pilot refillable outer shells with standardized inner cartridges, restructuring primary packaging economics toward durable polypropylene bases.
- Makeup:Color cosmetics requiring clarity-enhancing masterbatches now subject to expanded ECHA candidate list disclosure for polymer additives.
- Haircare:Shampoo and conditioner bottles in PET or HDPE with standard screw cap or flip top closure.
- Fragrance:Premium and masstige perfume packaging with atomizer pumps and decorative overcaps.
Haircare generates the highest unit volumes. Skincare commands the fastest value expansion on airless technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Hamburg and Düsseldorf anchor European plastic cosmetic packaging concentration. German manufacturing clusters attract premium beauty houses seeking rapid prototyping capabilities. Asia-Pacific converters scale mono-material production to serve expanding masstige demand.
United States
Massive blow-molding capacity stretches across personal care manufacturing corridors serving haircare and body care brands. The EPA regulates resin manufacturing emissions and recycled content claims under evolving extended producer responsibility frameworks. New Jersey and Ohio host dense converter networks supplying direct-to-consumer subscription channels with lightweight polymer formats.
Germany
Prestige skincare houses demand airless pump systems with sub-0.1 cc daily oxygen permeability for retinol preservation. REACH substance-of-very-high-concern disclosure mandates compel raw material inventory overhauls across converters. Hamburg and Düsseldorf clusters enable short-run customization for contract manufacturers prototyping mono-material alternatives.
France
Refill and reuse system adoption restructures primary packaging economics toward durable outer shells. ECHA phthalate plasticizer bans accelerate bio-based polymer R&D investment across formulation houses. Paris and Lyon prestige fragrance houses pilot deposit-return schemes for heavy-wall polypropylene jars through retail partnerships with dm-drogerie markt and Douglas.
China
SAMR enforces GB standards for plastic food-contact materials extending to cosmetic packaging through cross-referenced hygiene requirements. Dual carbon goals pressure converters toward recycled content integration despite rPET flake availability gaps. Yangtze River Delta manufacturing bases supply domestic masstige expansion while navigating compliance friction for imported formats.
Japan
METI circular economy roadmaps reward mono-material pump systems with streamlined post-consumer sorting economics. Design-for-recycling incentives concentrate converter investment in single-resin dispensers compatible with existing HDPE streams. Osaka and Nagoya industrial zones develop standardized inner cartridges for refillable outer shells in prestige skincare applications.
Plastic Cosmetic Packaging Market Competitive Landscape
Top-tier vendors anchor premium technology tiers, while mid-scale converters occupy regional supply positions. The market exhibits moderate consolidation around airless pump specialists and massive blow-molding operators. Three archetypes dominate: integrated dispensing system innovators, high-volume commodity resin molders, and niche sustainable format developers. Competitive moves concentrate on mono-material R&D partnerships and backward integration into recycled resin sourcing.
Within the integrated dispensing tier, AptarGroup Inc. and Berry Global Inc. occupy positions exemplifying technology-scale hybridization. AptarGroup represents airless pump system leadership through piston-based dispensing expertise. Berry Global anchors high-volume blow-molding capacity across North American personal care corridors. Albea Group sits within the European supply anchor archetype, sustaining dedicated beauty packaging operations. These three structures illustrate how geographic clustering and format specialization stratify competitive positioning without requiring uniform global scale.
| Leading Market Players |
|---|
| Amcor plc |
| AptarGroup Inc. |
| Berry Global Inc. |
| Albea Group |
| Silgan Holdings Inc. |
| Gerresheimer AG |
| DS Smith PLC |
| HCP Packaging |
| Quadpack Industries SA |
| Others |
Value Network & Pricing Analysis
EU Packaging and Packaging Waste Regulation compliance gates both qualified supplier rosters and premium-tier pricing access, as converters investing in mono-material R&D and ECHA-certified resin inventories command 15-20% price premiums over commodity molders lacking barrier-layer re-engineering capabilities.
Pricing Analysis
Short lead-time premiums separate agile German and French converters prototyping mono-material airless systems for prestige skincare houses from spot-market suppliers holding excess PET and polypropylene inventory at discounted clearing rates. Pricing stratifies across premium, standard, and economy tiers based on oxygen barrier certification grade and customization depth. Cost compression in masstige tube segments is intensifying because Indian and Southeast Asian converters are scaling collapsible format capacity. Mass haircare brands exhibit the highest price sensitivity due to PET commoditization, while German prestige skincare houses remain least sensitive given retinol preservation requirements.
Supply Chain Analysis
Co-injection molding technician scarcity in North American converter workforces constrains multi-layer barrier production expansion despite brand demand for sub-0.1 cc oxygen transmission systems. Supply concentrates in Germany, China, and the United States, with Hamburg-Düsseldorf clusters anchoring European premium prototyping and Yangtze River Delta bases serving Asian masstige scaling. Raw material flows draw from Saudi and Qatari virgin resin feedstocks, South Korean engineered polymer additives, and fragmented European rPET flake collection. Single-source vulnerability runs through German piston-pump mechanism suppliers serving airless system assemblers. Distribution runs through contract manufacturer networks linking converters to L'Oréal, Estée Lauder, and Unilever procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material conversion capacity scarcity props pricing premiums, as qualified suppliers capable of ECHA-compliant barrier re-engineering remain fewer than brand procurement slots demanding EU Packaging and Packaging Waste Regulation compliance.
For Market Incumbents: Lock in backward integration into rPET flake sourcing and captive piston-pump mechanism production to defend against Chinese converters scaling mono-material assembly. Prioritize Hamburg and Düsseldorf capacity expansion to capture prestige skincare prototyping demand before mid-tier European molders achieve ECHA substance disclosure certification. Certification investment in REACH SVHC documentation systems represents the critical defensive lever against regulatory audit exposure. For New Entrants and Emerging Players: Enter via India's Tier-2 and Tier-3 city masstige expansion, where collapsible tube demand outstrips rigid bottle converter capacity at price points 30-40% below European benchmarks. Target white-space in Japanese METI circular economy roadmap compliance, where design-for-recycling incentives reward mono-material PE pump systems with streamlined post-consumer sorting economics. Direct-to-consumer subscription channel fulfillment offers the most penetrable go-to-market angle, as lightweight polymer formats displace glass for shipping economics. For Investors and Strategic Acquirers: First-mover mono-material pump system deployment by AptarGroup or Albea is the leading indicator that premium-tier pricing power is consolidating around barrier-technology specialists rather than commodity molders. Long-term viability across the analysis window favors converters with captive R&D in co-injection delamination prevention and ECHA-certified resin inventories. Acquisition targets should profile mid-scale European beauty packaging specialists with Hamburg-Düsseldorf geographic positioning and pending mono-material patent portfolios. Watch for rPET flake price volatility spikes as the inflection signal for vertical integration premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material R&D Partnership | ECHA compliance timelines force joint development of single-resin barrier systems with German polymer institutes. |
| Backward Integration into rPET Sourcing | Post-consumer flake volatility in Southern Europe rewards captive collection infrastructure investment. |
| Airless Pump Technology Licensing | Piston mechanism IP transfers enable mid-tier converters to access prestige skincare procurement slots. |
| Direct-to-Consumer Channel Expansion | Subscription box fulfillment requirements favor lightweight polymer formats over glass for shipping economics. |
| Refill System Infrastructure Partnership | Douglas and dm-drogerie markt retail partnerships accelerate deposit-return scheme adoption in masstige segments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving converter plant managers, prestige beauty house procurement directors, ECHA regulatory affairs specialists, and German contract manufacturing executives. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, ECHA SVHC candidate list updates, SAMR GB standard cross-references, and METI circular economy roadmap disclosures. Bottom-up resin consumption modeling triangulated against top-down beauty industry production forecasts.
Granularity-level modeling operated at product-type, material-grade, and closure-mechanism dimensions, with additional layering by oxygen barrier performance tier and ECHA compliance certification status across the projection horizon. CAGRs derived from weighted-average growth contributions across German prestige skincare, Indian masstige expansion, and Japanese refill system adoption trajectories. Industry-specific inputs incorporated rPET flake availability indices, airless pump technology penetration curves, and mono-material patent filing velocities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA substance restriction acceleration or rPET collection infrastructure collapse scenarios. Forecasts reflect assumptions regarding REACH disclosure timeline adherence and Hamburg-Düsseldorf cluster capacity expansion rates. Material deviation in EU Packaging and Packaging Waste Regulation enforcement intensity or Chinese dual carbon goal acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
North America Cosmetic Packaging Market
Cosmetic Packaging
Latin America Personal Care Packaging Market
Cosmetic Packaging
Asia Pacific Cosmetic Packaging Market
Cosmetic Packaging
Anti-Counterfeit Cosmetic Packaging Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
Crimp Neck Serum Bottles Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
India Personal Care Packaging Market
Cosmetic Packaging
Europe Plastic Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Bottles Packaging Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Lotion Tubes Market
Cosmetic Packaging
Middle East and Africa Personal Care Packaging Market
Cosmetic Packaging
Europe Cosmetic Packaging Market
Cosmetic Packaging
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market