
 Cosmetic Spray Bottles Market | 2026-2036
Cosmetic Spray Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Spray Bottles Market Outlook
China is tilting toward expanded PET and aluminum conversion capacity for cosmetic packaging. AptarGroup leverages its pump technology leadership across fragrance and skincare dispensing systems. Albéa Group anchors European production through specialized fine mist and foam actuator platforms. Berry Global competes on polymer formulation scale, supplying recyclable resin grades to multinational beauty brands.
Cosmetic spray bottles are precision dispensing vessels engineered with actuator mechanisms delivering controlled particle sizes between 20–100 microns, typically constructed from PET, glass, or aluminum with polypropylene or polyethylene closure components; they serve the primary commercial purpose of preserving product integrity while enabling hygienic, metered application of liquids, gels, and foams. Fine mist formats lead volume demand due to their penetration in facial toners and setting sprays, while aluminum substrates represent the fastest-growing material category as brands pursue refillable and mono-material circular packaging targets. Pump closures concentrate margin pools given their mechanical complexity and brand-customization requirements.
The FDA regulates cosmetic packaging contact materials under the Federal Food, Drug, and Cosmetic Act, while the EU REACH framework restricts substance migration from plastic and coated metal containers; China's SAMR enforces GB standards for cosmetic packaging safety and labeling compliance. These layered requirements compel manufacturers to maintain multi-jurisdictional testing protocols and documentation systems. Stakeholders must monitor evolving extended producer responsibility schemes and material-specific recycling mandates to anticipate compliance-driven sourcing shifts.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is accelerating material transitions across cosmetic spray bottle supply chains, forcing converters to redesign actuator systems around mono-material recyclability targets.
Growth Catalysts
- Fine mist actuator demand:Premium skincare brands in Germany and the United States are specifying 20–40 micron particle sizes for facial toner applications, pulling specialized pump capacity expansion.
- REACH substance restrictions:ECHA's evolving SVHC candidate list is eliminating certain plasticizers from polypropylene closure compounds, creating certified-alternative sourcing premiums.
- Aluminum substrate conversion:Refillable packaging mandates in France and refill-station retail expansion in South Korea are displacing single-use PET formats in fragrance and setting spray segments.
Market Restraints
- Propellant cost volatility:Compressed gas and hydrocarbon propellant prices fluctuate with petrochemical feedstock indices, squeezing margin on aerosol-compatible aluminum bottles.
- Mold fabrication concentration:Precision actuator mold manufacturing concentrates in southern Germany and northern Italy, creating 14–18 week lead time vulnerabilities for new product launches.
- Mono-material performance gaps:All-polypropylene fine mist pumps currently fail to match the spray consistency of POM-spring hybrid designs, limiting full regulatory compliance.
Strategic Opportunities
- Indian domestic brand supply:CDSCO's streamlined cosmetic packaging approval pathways and PLI scheme incentives for polymer processing equipment are opening local production partnerships.
- Airless spray convergence:Integration of bag-on-valve technology with fine mist actuators enables preservative-free formulation compatibility for sensitive skin applications.
- SAMR labeling digitization:China's mandatory QR-code traceability requirements for cosmetic packaging create service-revenue streams for serialized closure integration.
Industry Challenges
- Multi-jurisdictional testing protocols:FDA migration studies, REACH SVHC declarations, and GB standard compliance documentation must synchronize for multinational brand supply contracts.
- Recyclability certification timelines:APR and RecyClass design-for-recycling approvals require 8–12 month validation cycles that delay new mono-material actuator launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Spray Bottles Market |
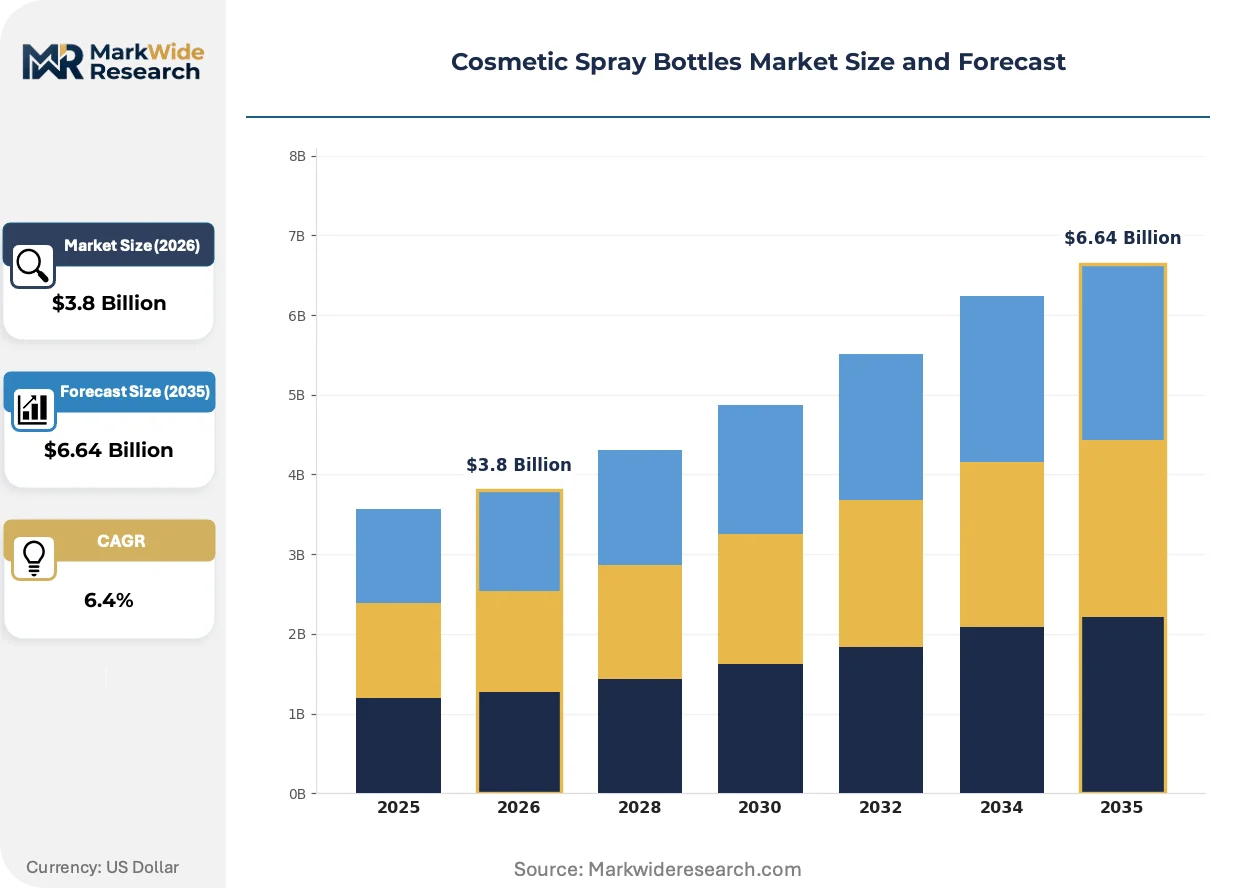
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fine Mist, Foam, Gel, Lotion Material: Glass, Plastic, Aluminum, PET Closure Type: Cap, Pump, Spray, Dropper End User: Manufacturers, Retailers, Wholesalers, Home Users |
| Companies Covered | AptarGroup, Albéa Group, Berry Global, Amcor, Silgan Holdings, Gerresheimer, HCP Packaging, Landmu, Qosmedix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Spray Bottles Market Strategic Shifts
Active materials science and digital integration are redefining cosmetic spray bottle value propositions beyond basic containment, with smart dispensing and circular design now baseline competitive requirements.
Smart actuator systems incorporating near-field communication chips and usage-tracking sensors are digitizing consumer engagement channels for prestige fragrance houses. L'Oréal and Estée Lauder supply chains are piloting these connected closures for loyalty-program integration and refill-triggering alerts. The technology is digitizing traditional point-of-sale relationships into direct brand-consumer data loops that bypass retailer intermediation.
REACH Article 33 disclosure obligations and the EU Green Deal's packaging waste reduction targets are forcing compound reformulation across polypropylene and polyethylene closure components. Manufacturers must now document full substance inventories to ECHA databases, with non-compliance blocking market access. Premium skincare segments in Germany and France are responding fastest, specifying certified-recycled resin grades ahead of regulatory deadlines.
Direct-to-consumer sampling programs and subscription box channels are fragmenting traditional bulk procurement patterns for cosmetic spray bottles. Indie beauty brands in the United States and United Kingdom now specify sub-10,000 unit production runs with rapid design iteration cycles. This channel rotation compresses mold amortization schedules and rewards digital-native converters with agile manufacturing platforms over legacy high-volume specialists.
Cosmetic Spray Bottles Market Segmentation
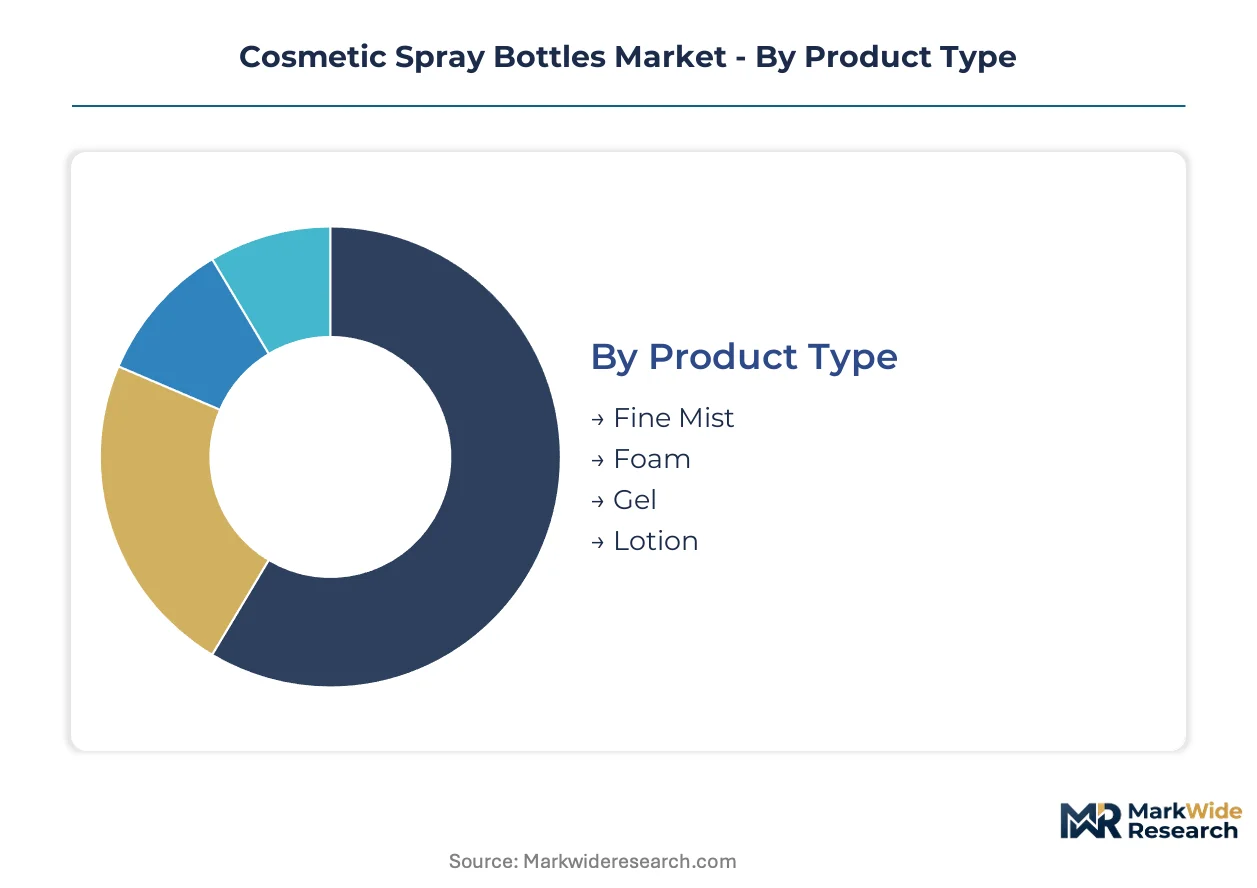
Segmentation in cosmetic spray bottles reveals how formulation physics, material compliance, and dispensing mechanics create distinct margin architectures. Each category demands specialized tooling, regulatory documentation, and aftermarket technical support intensity.
Product Type:
After-sales service intensity varies sharply across product types, with precision actuator mechanisms requiring field calibration support and replacement programs.
- Fine Mist:Engineered with 20–100 micron particle control through specialized swirl chamber geometries. Premium skincare brands in Germany specify sub-40 micron tolerances for facial toner applications, pulling dedicated technical service teams for actuator calibration.
- Foam:Combines liquid concentrate with air entrainment through mesh or screen systems. French refill-station networks and South Korean retail expansion are displacing single-use formats, creating demand for foam actuator refurbishment services.
- Gel:Viscosity-tolerant designs with wider orifice diameters and shear-resistant pump mechanisms. Hair care and body product lines in the United States favor this format.
- Lotion:Higher displacement pumps with dip tube extensions for medium-viscosity formulations. Mass-market personal care manufacturers in India specify this type for cost-optimized production runs.
Fine Mist holds the largest share; momentum sits with Foam.
Material:
Cost tier stratification separates premium substrate specifications from commodity resin procurement patterns.
- Glass:Borosilicate and soda-lime compositions with UV-blocking tints for photosensitive formulations. Prestige fragrance houses in France and Italy specify this substrate for olfactory preservation and shelf presence.
- Plastic:Polypropylene and polyethylene homopolymer grades with REACH-compliant additive packages. Volume concentration in Chinese manufacturing clusters serving domestic beauty brands.
- Aluminum:Drawn and ironed seamless construction with internal epoxy or polyester linings. Refillable packaging mandates in France and mono-material circular targets are accelerating this category fastest.
- PET:Stretch-blow molded clarity with acetaldehyde control for fragrance compatibility. Berry Global and Albéa Group supply chains dominate recyclable resin grade conversion.
Plastic holds the largest share; Aluminum is climbing the fastest.
Closure Type:
Application-driven specification splits between passive containment and active dispensing functionality.
- Cap:Screw-thread and snap-fit designs with tamper-evident bands. Lowest service intensity; standard inventory for bulk shampoo and conditioner formats.
- Pump:Reciprocating piston mechanisms with 0.5–2.0 mL dose consistency. Margin concentration here given mechanical complexity and brand-customization requirements.
- Spray:Trigger and finger-actuated systems with compression spring return. Fine mist skincare applications in North America and Germany anchor demand.
- Dropper:Bulb-squeeze or push-button pipette assemblies for serum precision. Indie beauty brands in the United Kingdom specify this for apothecary aesthetic positioning.
Pump holds the largest share; Spray gains share fastest.
End User:
Customer type determines order fragmentation, with direct-to-consumer channels compressing production run economics.
- Manufacturers:Multinational beauty houses with 100,000+ unit annual contracts and integrated quality audits. L'Oréal and Estée Lauder supply chains dominate this tier.
- Retailers:Private-label programs and exclusive brand partnerships with 10,000–50,000 unit runs. Sephora and Ulta Beauty specification teams drive regional sourcing.
- Wholesalers:Distributor-consolidated procurement for regional beauty supply chains. Inventory pooling reduces per-SKU tooling amortization.
- Home Users:Artisan and small-batch formulators sourcing through Alibaba and domestic B2B platforms. Sub-1,000 unit orders with digital design iteration cycles.
Manufacturers hold the largest share; momentum sits with Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized actuator mold fabrication concentrates in southern Germany and northern Italy, creating supply dependencies for converters worldwide. This geographic clustering shapes procurement patterns for premium skincare and fragrance brands seeking precision dispensing systems.
United States
Fine mist actuator demand from Estée Lauder and L'Oréal supply chains pulls dedicated technical service teams for calibration support. FDA migration studies under the Federal Food, Drug, and Cosmetic Act govern polypropylene closure compounds. New Jersey and Connecticut manufacturing corridors host precision pump assembly operations serving North American prestige beauty brands.
Germany
Cosmetic manufacturing clusters in Hamburg and Berlin anchor European supply chains for facial toner and setting spray formats. ECHA's REACH Article 33 disclosure obligations force full substance inventory documentation for PP and PE closure components. Baden-Württemberg precision engineering firms specialize in 20–40 micron swirl chamber geometries for premium skincare specifications.
France
Refillable packaging mandates displace single-use PET formats in fragrance segments, accelerating aluminum substrate conversion. ANSM enforces cosmetic packaging safety standards alongside EU Green Deal waste reduction targets. Grasse and Paris Basin production networks integrate refill-station retail expansion with mono-material circular design requirements.
China
SAMR's mandatory QR-code traceability requirements for cosmetic packaging create service-revenue streams for serialized closure integration. GB standards govern packaging safety and labeling compliance for domestic beauty brands. Yangtze River Delta PET and aluminum conversion capacity expansions serve both export and rapidly growing domestic skincare markets.
South Korea
Refill-station retail expansion in Seoul and Busan drives demand for foam actuator refurbishment services. MFDS cosmetic packaging regulations align with extended producer responsibility schemes. Gyeonggi-do manufacturing zones specialize in airless spray convergence technologies for preservative-free sensitive skin formulations.
Cosmetic Spray Bottles Market Competitive Environment
Technology-anchored specialists and polymer-scale suppliers split the market into distinct capability tiers. The vendor base organizes around precision actuator engineering versus commodity resin conversion competencies. Three archetypes dominate: pump mechanism innovators, material formulation platforms, and integrated dispensing system providers. Competitive moves concentrate on strategic partnerships for smart closure integration and capacity expansion for certified-recycled resin grades.
Within the precision actuator tier, AptarGroup and Albéa Group exemplify technology-anchored positioning through specialized fine mist and foam dispensing platforms. Berry Global represents the polymer-scale archetype, supplying recyclable resin formulations to multinational beauty houses. These three companies occupy the competitive center of gravity where mechanical complexity meets regulatory compliance documentation.
| Leading Market Players |
|---|
| AptarGroup |
| Albéa Group |
| Berry Global |
| Amcor |
| Silgan Holdings |
| Gerresheimer |
| HCP Packaging |
| Landmu |
| Qosmedix |
| Others |
Value Chain & Pricing Dynamics
Precision actuator mold fabrication in southern Germany and northern Italy concentrates upstream technical capacity, anchoring margin pools in pump closure tiers where mechanical complexity commands customization premiums downstream.
Pricing Analysis
EU REACH substance restrictions dictate the pricing tier structure across cosmetic spray bottle supply chains. Three-tier pricing stratifies across premium certified-recycled resin grades, standard REACH-compliant compounds, and economy virgin polymer specifications. Price differentiation centers on ECHA SVHC documentation depth and RecyClass certification status. Cost compression in standard-grade PP closures is intensifying because of propellant feedstock volatility and mold fabrication lead time bottlenecks. Indie beauty brands and home-user formulators exhibit highest price sensitivity, while prestige fragrance houses absorb premiums for calibrated fine mist tolerances.
Supply Chain Analysis
Contract manufacturing concentrates with AptarGroup, Albéa Group, and Berry Global holding dominant precision actuator and resin formulation capacity. Geographic supply concentration centers on Germany, Italy, and China, with Yangtze River Delta PET conversion and Baden-Württemberg precision engineering as critical nodes. Raw material dependencies draw from petrochemical feedstocks for polypropylene and polyethylene homopolymers, aluminum sheet stock for refillable formats, and specialized steel alloys for precision mold tooling. Single-source vulnerability in swirl chamber mold fabrication creates 14–18 week lead time exposure for new product launches. Distribution runs through multinational beauty house direct procurement, retailer private-label programs, and Alibaba-consolidated artisan formulator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cosmetic spray bottles market sits in a cyclical recovery phase, with EU Packaging and Packaging Waste Regulation compliance deadlines pulling forward material conversion investments ahead of mandatory implementation windows.
For Market Incumbents: Pre-empt aluminum substrate conversion capacity constraints by securing dedicated drawn-and-ironed seamless bottle lines before refillable mandate enforcement peaks. Anchor backward integration into certified-recycled resin compounding to defend margin position against virgin polymer price volatility. Prioritize RecyClass design-for-recycling pre-approval to compress 8–12 month validation cycles for mono-material actuator launches. For New Entrants and Emerging Players: Indian domestic brand supply represents the most penetrable entry point, with CDSCO streamlined approval pathways and PLI scheme polymer processing incentives lowering capital barriers. Airless spray convergence for preservative-free sensitive skin formulations offers technical differentiation in South Korean refill-station retail expansion. Pursue digital-native agile manufacturing platforms to capture sub-10,000 unit indie beauty brand production runs with rapid design iteration cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision actuator specialists holding southern German mold fabrication relationships. Five-to-ten year viability hinges on smart closure integration capabilities and serialized QR-code traceability service revenue streams. Monitor APR and RecyClass certification throughput rates as inflection indicators for regulatory-compliant sourcing pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Actuator Development | ECHA REACH compliance eliminates SVHC plasticizers from PP closure compounds ahead of regulatory deadlines. |
| Smart Closure Integration | NFC chip and sensor embedding digitizes L'Oréal and Estée Lauder loyalty-program engagement channels. |
| Aluminum Substrate Capacity Expansion | Refillable packaging mandates in France and South Korea displace single-use PET fragrance formats. |
| Certified-Recycled Resin Sourcing | Berry Global and Albéa Group supply chains dominate recyclable PET grade conversion for multinational beauty brands. |
| Airless Spray Convergence | Bag-on-valve technology integration enables preservative-free formulation compatibility for MFDS-regulated sensitive skin segments. |
Study Parameters
Cross-validation between primary interviews with packaging engineers, cosmetic brand procurement directors, regulatory compliance officers, and mold fabrication specialists anchors the qualitative findings. Secondary validation draws from ECHA SVHC candidate list updates, FDA Federal Food Drug and Cosmetic Act guidance documents, SAMR GB standards publications, and RecyClass design-for-recycling protocol documentation. Bottom-up segmentation modeling triangulates against top-down macro demand indicators across the analysis window.
Calibration against historical volume trajectories and regulatory implementation timelines shapes the analytical framework. Segmentation dimensions span product type, material substrate, closure mechanism, and end-user procurement scale across the projection horizon. CAGRs derive from weighted average growth assumptions by segment, with aluminum substrate conversion rates and fine mist actuator adoption curves as primary industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock indices, euro-dollar exchange rates, or EU EPR scheme enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on regulatory timeline adherence and brand sustainability commitment durability. Quarterly review of ECHA SVHC list expansions, APR certification approval rates, and refill-station retail network buildouts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market
Cosmetic Packaging
US Personal Care Packaging Market
Cosmetic Packaging
Crimp Neck Serum Bottles Market
Cosmetic Packaging
India Personal Care Packaging Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Asia Pacific Cosmetic Packaging Market
Cosmetic Packaging
Middle East and Africa Personal Care Packaging Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
Latin America Personal Care Packaging Market
Cosmetic Packaging
Lip Care Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
Cosmetic Pump Bottle Market
Cosmetic Packaging
Lotion Tubes Market