

Cream Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Cream Jars Market Insights
Buyer concentration among premium cosmetic houses is expanding as multinational skincare brands consolidate supplier rosters and demand shorter lead times. Aptar Group leverages its airless pump expertise to serve high-margin facial cream lines. Gerresheimer anchors European glass jar supply through specialized borosilicate and molded glass operations. Berry Global competes across PET and polypropylene formats with scale manufacturing in North America and Asia.
Cream jars are rigid primary packaging vessels, typically 15–100 milliliters in fill volume, designed to protect viscous emulsions from oxidation, contamination, and UV degradation through barrier walls and sealed closure systems. Glass dominates prestige facial cream applications where chemical inertness and recyclability command price premiums, while PET and polypropylene segments serve mass-market body lotions and hand creams where lightweighting and drop resistance drive purchasing criteria. Acrylic occupies a narrowing mid-tier as brands migrate toward either glass for sustainability credentials or bioplastic for emerging eco-positioning.
FDA cosmetic labeling rules, EU REACH substance restrictions, and China's GB standards for plastic food-contact materials all govern jar composition, decoration chemistry, and migration testing protocols. EMA and national health authorities indirectly shape demand through dermatology clinic procurement standards that favor single-use or airless formats. Stakeholders must monitor how extended producer responsibility schemes in Europe and state-level packaging laws in the US reshape material economics and closure technology roadmaps.
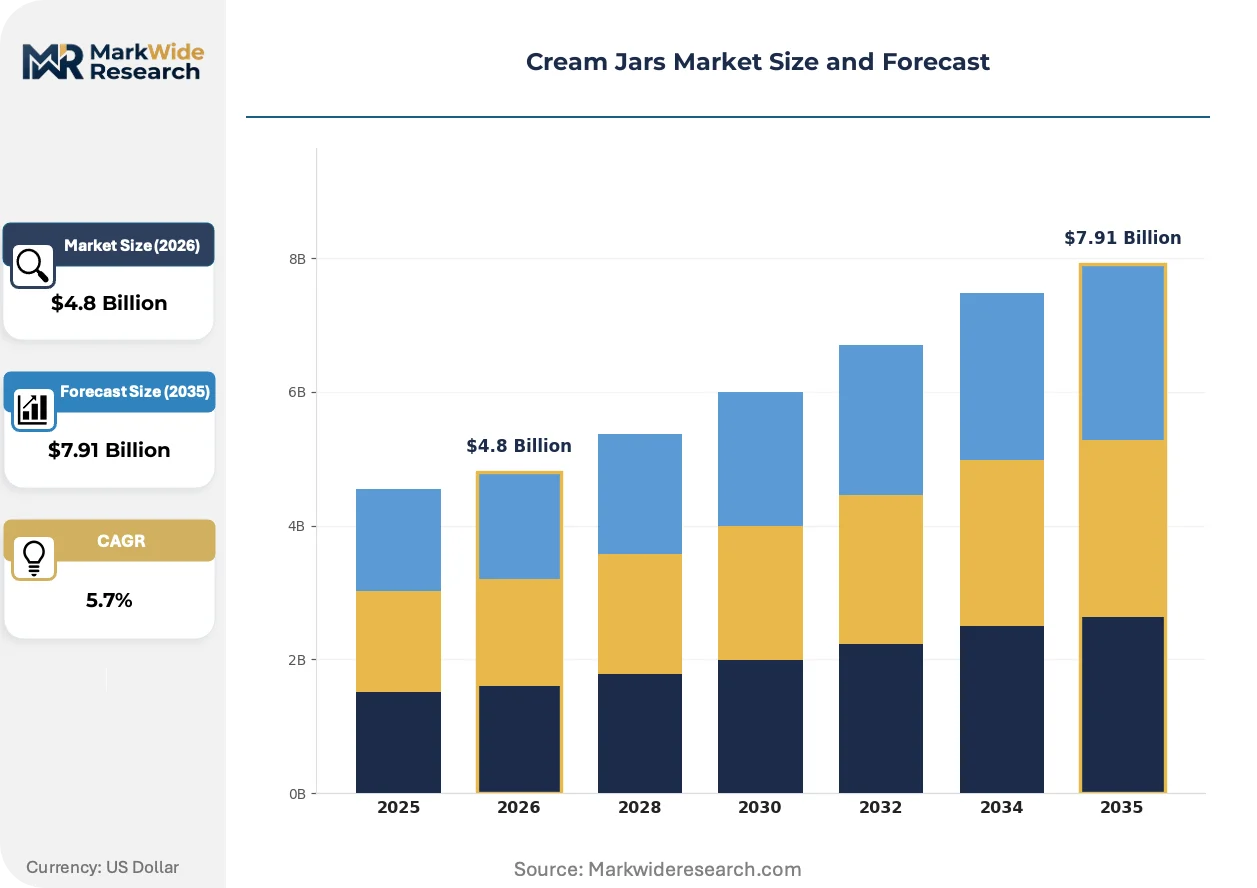
Market Dynamics
Premium cosmetic brands are consolidating supplier rosters and demanding shorter lead times, forcing packaging converters to regionalize manufacturing and invest in airless pump capabilities. This buyer concentration is compressing margins for mid-tier suppliers while rewarding scale players with dermatology clinic certifications.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are accelerating glass jar demand across prestige skincare lines in Germany and France.
- Airless pump technology:High-margin facial cream brands are specifying barrier closures that extend product shelf life and justify premium positioning.
- South Korea:K-beauty export growth is regionalizing supply chains, with local converters capturing demand from multinational skincare houses.
Market Restraints
- Borosilicate glass supply concentration:European furnace capacity limits are creating bottlenecks for heavy-wall prestige jar orders.
- Bioplastic cost structure:Polylactic acid and other bio-based resins trade at 40-60% premiums to conventional PET, constraining mass-market adoption.
- REACH substance restrictions:ECHA scrutiny of decorative coatings and UV stabilizers is lengthening formulation approval timelines for jar decorators.
Strategic Opportunities
- Refillable jar systems:Durable outer vessels with replaceable inner cartridges are penetrating premium skincare lines in France and Germany.
- China GB standards alignment:Converters certifying to plastic food-contact material rules can access cross-selling into dermocosmetic brands exporting to Asia.
- Monomaterial polypropylene jars:Full-PP constructions including closure and liner are qualifying for enhanced recycling streams under EU extended producer responsibility schemes.
Industry Challenges
- Decorative chemistry certification:Migration testing for heavy metals and photoinitiators requires 12-18 month validation cycles that delay new jar launches.
- Airless pump assembly integration:Precision tolerances between jar neck finish and pump actuator demand automated production lines that smaller converters cannot finance.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cream Jars Market Trends and Innovations
Material science advances and regulatory tightening are reshaping how cream jars protect formulations while signaling sustainability credentials to end consumers.
Post-consumer recycled glass is expanding into prestige facial cream applications as brands seek to maintain chemical inertness while meeting corporate circularity pledges. Luxury skincare houses in France and Germany are specifying 30-50% cullet content in borosilicate and soda-lime constructions. This material shift is compressing virgin glass demand while creating supply competition for high-quality recycled cullet streams.
REACH authorization requirements for certain phthalates and bisphenols are forcing reformulation of jar liners and closure seals across European supply chains. ECHA's candidate list expansion is accelerating migration to silicone and thermoplastic elastomer alternatives. Mass-market body cream segments are absorbing most compliance costs, as price-sensitive buyers cannot pass through material premiums.
Direct-to-consumer subscription models are shortening jar size standardization cycles, with brands requesting 15-milliliter trial formats and 75-milliliter refill sizes alongside traditional 50-milliliter SKUs. E-commerce fulfillment requirements are driving demand for drop-tested PET and polypropylene constructions that survive last-mile handling. South Korean beauty brands are most advanced in this channel evolution, with packaging specifications updated quarterly.
Cream Jars Market Segmentation
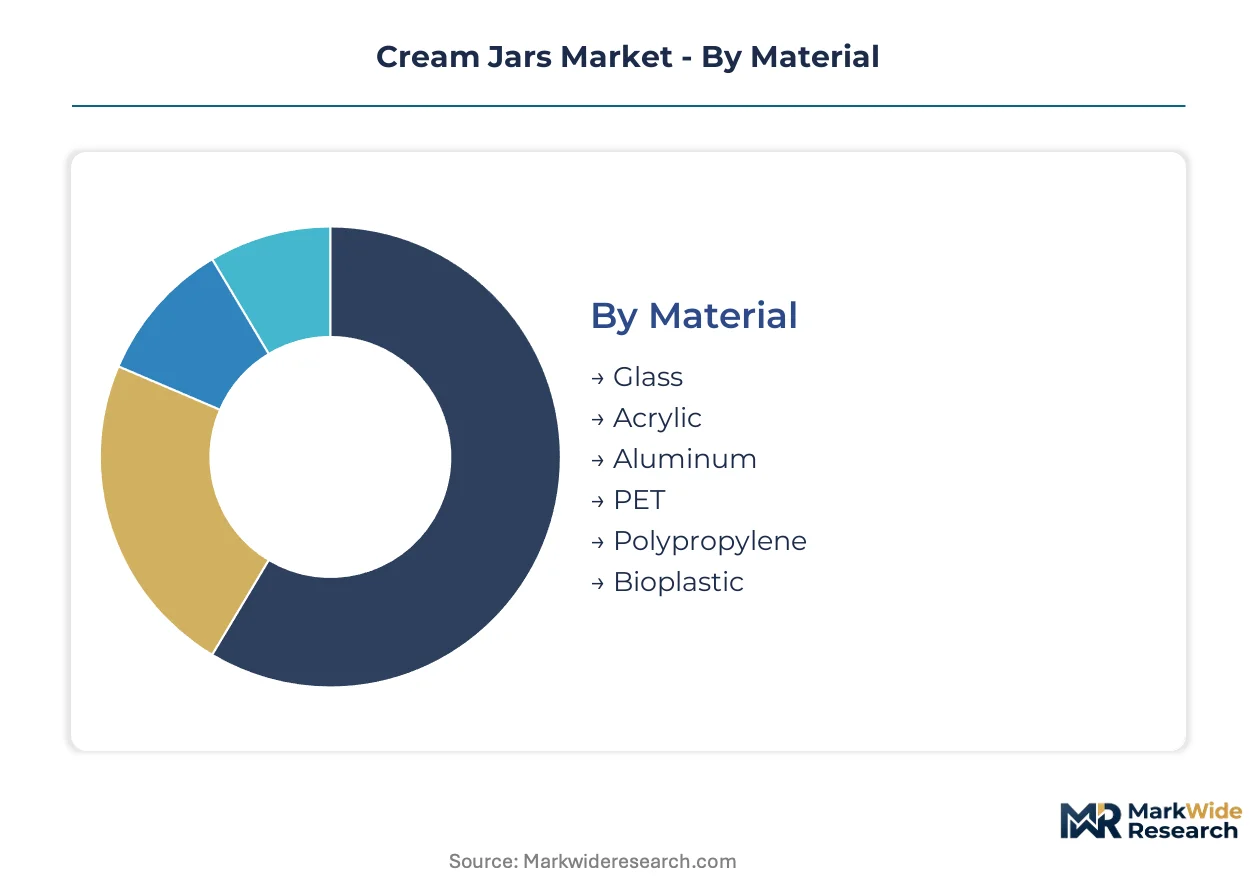
Cream jar specifications diverge sharply across material chemistry, closure engineering, and end-use performance requirements. Each segmentation axis carries distinct capital commitments and margin profiles that shape supplier specialization and buyer procurement strategies.
Material:
Glass and bioplastic segments demand the heaviest upfront furnace and polymerization investments, while commodity resin lines run on repurposed equipment.
- Glass:Borosilicate and soda-lime constructions deliver chemical inertness and infinite recyclability for prestige facial cream applications. German and French luxury skincare houses specify heavy-wall designs that command price premiums and require dedicated furnace capacity.
- Bioplastic:Polylactic acid and bio-based polyethylene formulations trade at substantial premiums to conventional resins but qualify for EU Green Deal procurement preferences. Mass-market adoption remains constrained by feedstock scale and composting infrastructure gaps.
- Acrylic:Thermoplastic clarity mimics glass aesthetics at reduced weight, though brands are migrating toward either glass for sustainability credentials or bioplastic for emerging eco-positioning.
- Aluminum:Lightweight metal shells serve premium body cream lines seeking differentiation through cold-touch aesthetics and infinite recyclability.
- PET:Drop-resistant clarity dominates e-commerce fulfillment channels where last-mile handling durability outweighs thermal resistance requirements.
- Polypropylene:Chemical resistance and monomaterial recyclability position this resin for enhanced sorting streams under extended producer responsibility schemes.
Glass absorbs the bulk of installed capacity; bioplastic is expanding most quickly.
Closure Type:
Premium positioning now hinges on barrier performance rather than mere containment, elevating airless pump specifications across facial cream portfolios.
- Airless Pump:Precision piston mechanisms eliminate oxygen ingress and extend shelf life for high-margin antioxidant formulations. South Korean K-beauty exporters specify quarterly specification updates that favor converters with automated assembly lines.
- Screw Cap:Universal threading compatibility minimizes tooling changeover costs across mass-market body lotion and hand cream SKUs.
- Flip Top:Single-handed dispensing suits gym bag and travel formats where convenience overrides premium aesthetics.
- Snap Lid:Audible closure confirmation serves ophthalmic and pediatric cream applications where tamper evidence is paramount.
- Disc Cap:Controlled flow orifices reduce over-dispensing waste for thick emulsions in professional salon environments.
Airless pump captures the steepest margin expansion; screw cap retains the broadest SKU coverage.
Application:
Facial cream specifications concentrate innovation investment, while body care lines absorb volume throughput.
- Facial Creams:Airless barrier closures and UV-opaque glass dominate antioxidant and retinol formulations where oxidation sensitivity commands packaging premiums. German dermatology clinic procurement standards favor single-use or airless formats.
- Eye Creams:Precision dispensing and micro-dose formats require specialized 15-milliliter constructions with narrow neck finishes.
- Body Lotions:Lightweight PET and polypropylene serve high-volume mass-market channels where per-unit packaging cost minimization drives specification.
- Sunscreens:UV-stabilized resins and opaque constructions protect photosensitive active ingredients from degradation during retail display.
- Hand Creams:Portable 30-50 milliliter formats with flip-top closures dominate purse and desk drawer occasions.
- Night Creams:Thicker viscosity formulations require wider mouth jars and heavier-wall constructions to prevent deformation.
Facial creams anchor R&D expenditure; body lotions generate the highest unit volumes.
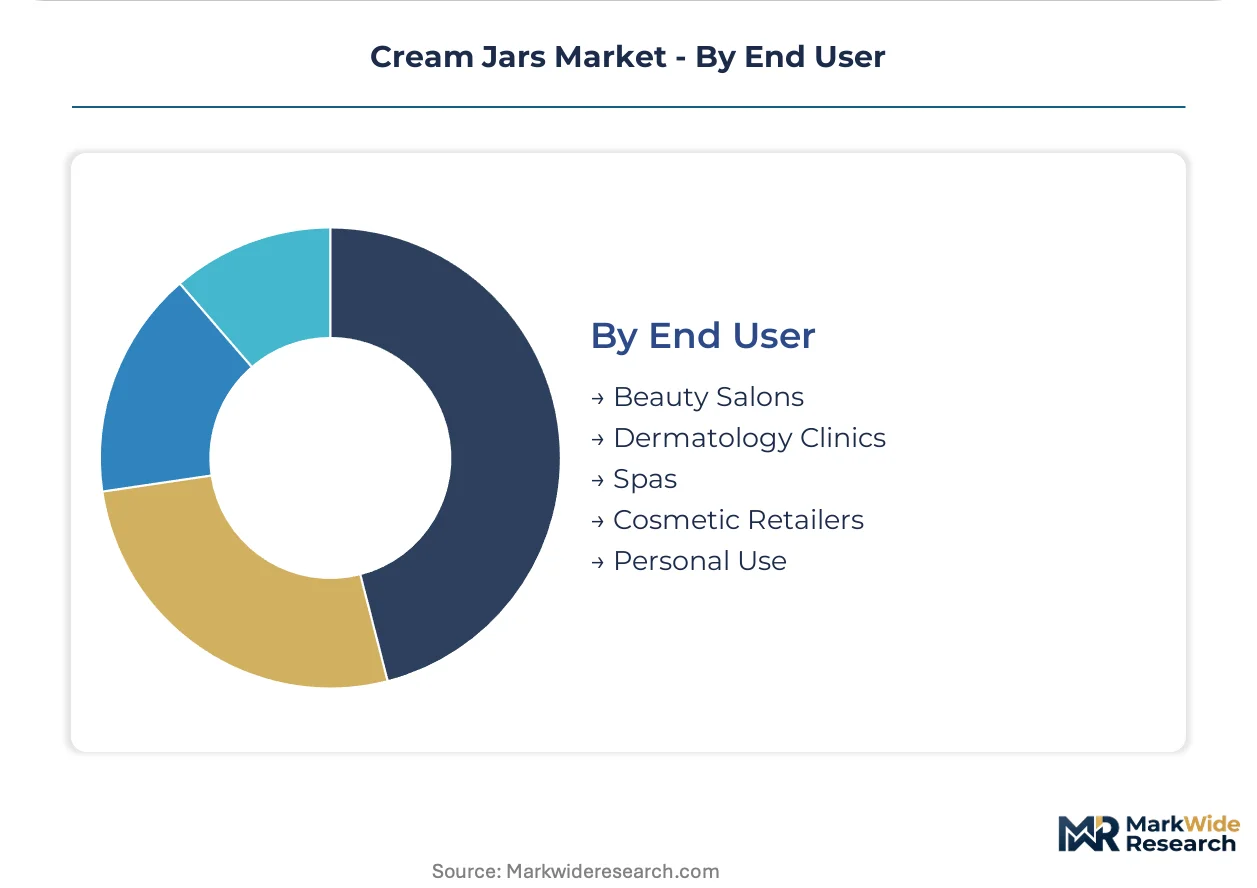
End User:
Professional channel certification requirements fragment supplier bases, with dermatology clinics imposing the most stringent validation protocols.
- Dermatology Clinics:EMA-influenced procurement standards mandate single-use or airless formats with full migration testing documentation. Certification cycles span 12-18 months and favor established converters with dedicated regulatory affairs teams.
- Cosmetic Retailers:Shelf-ready aesthetics and standardized case counts drive demand for decorated glass and premium acrylic constructions.
- Beauty Salons:Professional back-bar sizes in 100-250 milliliter formats prioritize durability over premium finishing.
- Spas:Coordinated amenity lines require custom color matching and logo embossing on mid-volume orders.
- Personal Use:Direct-to-consumer subscription models are fragmenting size standardization with quarterly specification churn.
Dermatology clinics absorb the most compliance overhead; cosmetic retailers offer the broadest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium cosmetic brands concentrate procurement in Germany, France, and South Korea, where specialized converters serve regionalized supply chains with shorter lead times. These three markets anchor demand for heavy-wall glass and airless pump closures. Each geography imposes distinct regulatory and infrastructure constraints on jar specification.
Germany
Luxury skincare houses in Bavaria and North Rhine-Westphalia specify heavy-wall borosilicate jars for prestige facial cream lines. The EU Packaging and Packaging Waste Regulation mandates recyclability targets that accelerate post-consumer recycled glass adoption. Stuttgart-area converters invest in dedicated furnace capacity to serve dermatology clinic certification requirements.
France
Paris-based beauty brands drive demand for refillable jar systems with replaceable inner cartridges. REACH authorization requirements for phthalates and bisphenols force reformulation of closure seals and jar liners. Cosmetic packaging clusters in Île-de-France and Provence-Alpes-Côte d'Azur specialize in decorated glass for shelf-ready aesthetics.
South Korea
K-beauty exporters in the Seoul Capital Area specify quarterly packaging specification updates for direct-to-consumer subscription models. MFDS cosmetic safety standards govern migration testing for jar materials and decorative coatings. Busan-Ulsan converters capture regionalized supply chain demand with automated airless pump assembly lines.
United States
Mass-market body lotion brands in California and New York Metro prioritize drop-resistant PET and polypropylene for e-commerce fulfillment. FDA cosmetic labeling rules govern jar composition and decoration chemistry validation. Midwest converters in Illinois and Ohio scale polypropylene production for monomaterial recycling streams.
China
Dermocosmetic brands exporting to Asia require GB standards certification for plastic food-contact materials in jar construction. NMPA cosmetic registration rules extend to packaging migration documentation. Pearl River Delta converters in Guangdong province supply lightweight formats for hand cream and sunscreen applications.
Cream Jars Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bioplastic and refillable system niches. The supplier base concentrates among scale converters with dermatology clinic certifications and regional furnace or polymerization assets. Three archetypes dominate: glass specialists with borosilicate expertise, multi-material scale players with North American and Asian manufacturing footprints, and precision closure engineers with airless pump capabilities. Competitive moves center on capacity regionalization and automated assembly line investment to meet quarterly specification churn.
Among European glass specialists, Gerresheimer and Verescence exemplify the heavy-wall prestige jar archetype with dedicated furnace operations. Aptar Group anchors the precision closure tier. Berry Global sits within the multi-material scale category with commodity resin manufacturing breadth. These three represent distinct capability vectors—chemical inertness, barrier engineering, and volume throughput—that buyers weigh against specification requirements and lead time constraints.
| Leading Market Players |
|---|
| Aptar Group |
| Albea Group |
| Berry Global |
| Gerresheimer |
| Verescence |
| HCP Packaging |
| Silgan Holdings |
| Amcor |
| Quadpack Industries |
| Others |
Pricing and Supply Chain Analysis
Borosilicate glass furnace energy costs cascade through three distinct pricing tiers, with German and French heavy-wall prestige jars absorbing premium fuel surcharges while mass-market PET formats in North America and Asia compete on resin spot pricing. EU Packaging and Packaging Waste Regulation compliance costs stratify buyer procurement power, concentrating margin capture among scale converters with certified dermatology clinic supply lines.
Pricing Analysis
Volume throughput concentrates in mass-market body lotion PET and polypropylene formats where per-unit cost minimization dominates procurement, while facial cream glass and airless pump closures command margin premiums through barrier performance certification. Price differentiation hinges on EMA-influenced dermatology clinic validation tiers and regional furnace proximity to German and French luxury skincare clusters. Cost compression in bioplastic feedstocks is intensifying because polylactic acid supply lags brand circularity pledges. Mass-market body care buyers exhibit highest price sensitivity; prestige facial cream houses tolerate material premiums for sustainability credentials.
Supply Chain Analysis
EU domestic-content mandates under extended producer responsibility schemes are reshaping sourcing patterns, requiring European converters to qualify monomaterial polypropylene streams and post-consumer recycled glass cullet within regional boundaries. Manufacturing gravity centers on Germany, France, and South Korea, with Busan-Ulsan airless pump assembly and Stuttgart-area borosilicate furnace operations anchoring supply. Raw material flows draw from soda-lime silica sand deposits, petroleum-based resin feedstocks, and imported bio-based polymer precursors. Single-source vulnerability concentrates in European borosilicate furnace capacity for heavy-wall prestige orders. Distribution runs through regionalized beauty supply clusters serving K-beauty export channels and German dermatology clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer consolidation among multinational skincare brands is compressing supplier margins and forcing mid-tier converters toward exit or acquisition, with REACH authorization timelines and airless pump automation costs accelerating attrition.
For Market Incumbents: Acquire automated airless pump assembly lines to defend against South Korean converter encroachment in K-beauty supply chains. Secure dedicated borosilicate furnace capacity in Germany or France to lock in dermatology clinic certification workflows. Backward integration into post-consumer recycled glass cullet sorting protects against virgin material cost volatility under EU circularity mandates. For New Entrants and Emerging Players: Direct-to-consumer subscription channel managers represent the most accessible entry point, with quarterly specification churn favoring agile converters over legacy scale players. Target refillable jar system white space in French and German premium skincare lines where replaceable inner cartridge designs remain underpenetrated. Lead with rapid prototyping capabilities for 15-milliliter trial formats and 75-milliliter refill sizes bypassing standardized SKU constraints. For Investors and Strategic Acquirers: Quarterly packaging specification updates from Seoul Capital Area K-beauty exporters are the leading indicator that automated assembly capability is overtaking furnace scale as the scarce production input. Five-to-ten year viability favors precision closure engineers with airless pump patents over commodity resin volume players. Monitor ECHA candidate list expansions for phthalate and bisphenol restrictions as the signal that silicone and thermoplastic elastomer alternative suppliers will command acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Airless Pump Assembly Automation | Precision tolerance capabilities unlock K-beauty export contracts with quarterly specification cycles. |
| Post-Consumer Recycled Glass Integration | 30-50% cullet content qualifies prestige jars for EU Green Deal procurement preferences. |
| Monomaterial Polypropylene Certification | Full-PP constructions including closure and liner access enhanced EPR recycling stream premiums. |
| Dermatology Clinic Validation Investment | EMA-influenced certification cycles spanning 12-18 months lock out unqualified competitors. |
| Regional Furnace Capacity Expansion | Stuttgart and Île-de-France proximity shortens lead times for German and French luxury houses. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving packaging procurement managers at multinational skincare brands, regulatory affairs leads at glass and resin converters, dermatology clinic supply chain coordinators, and airless pump assembly automation engineers. Bottom-up volume modeling triangulated against top-down category spend estimates derived from EU Packaging and Packaging Waste Regulation compliance disclosures and MFDS cosmetic safety standard certification databases.
Granularity-level modeling operated at material chemistry, closure engineering, and end-use performance intersections, with separate trajectory builds for borosilicate glass, bioplastic, PET, and polypropylene segments across the projection horizon. CAGRs derived from installed capacity utilization rates, furnace and polymerization asset expansion pipelines, and brand sustainability pledge implementation timelines. Migration testing protocol duration and ECHA substance restriction candidate list evolution served as forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including abrupt EU furnace energy cost shocks, bioplastic feedstock crop failure scenarios, and K-beauty export demand collapse. Forecasts reflect documented assumptions regarding REACH authorization timeline stability and airless pump assembly automation diffusion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.