
 Global Perfume Packaging Market | 2026-2036
Global Perfume Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Perfume Packaging Market Outlook
Post-consumer recycled glass is rebalancing cost structures across premium perfume packaging as brands absorb higher unit costs to meet sustainability pledges. Gerresheimer AG leverages its European furnace network to supply flacon-grade cullet at scale. AptarGroup sustains pump-mechanism innovation that reduces metal content without sacrificing spray precision. Albea differentiates through integrated decoration capabilities that compress lead times for limited-edition launches.
Perfume packaging encompasses primary containers, closures, applicators, and secondary cartons engineered to preserve fragrance integrity, prevent oxidation, and convey brand positioning through tactile and visual cues. Glass dominates material type due to chemical inertness and premium perception, though metal and wood segments gain traction in refillable systems. Spray bottles lead packaging type by volume while sample packs represent the fastest-growing category as digital discovery channels expand. Luxury brands anchor end-user demand and capture the deepest margin pools, whereas online retailers are forcing format miniaturization and shipping-durable construction.
EU REACH restrictions on certain plasticizers and the EU Green Deal carbon-border adjustments are redirecting supplier qualification criteria toward audited recyclate streams and renewable energy certificates. FDA cosmetic packaging guidelines in the United States and China's GB standards for fragrance product containers add compliance layers that favor multinational converters with cross-border certification infrastructure. Stakeholders must weigh captive recycling investments against outsourced sustainable material premiums as regulatory thresholds tighten unevenly across jurisdictions.
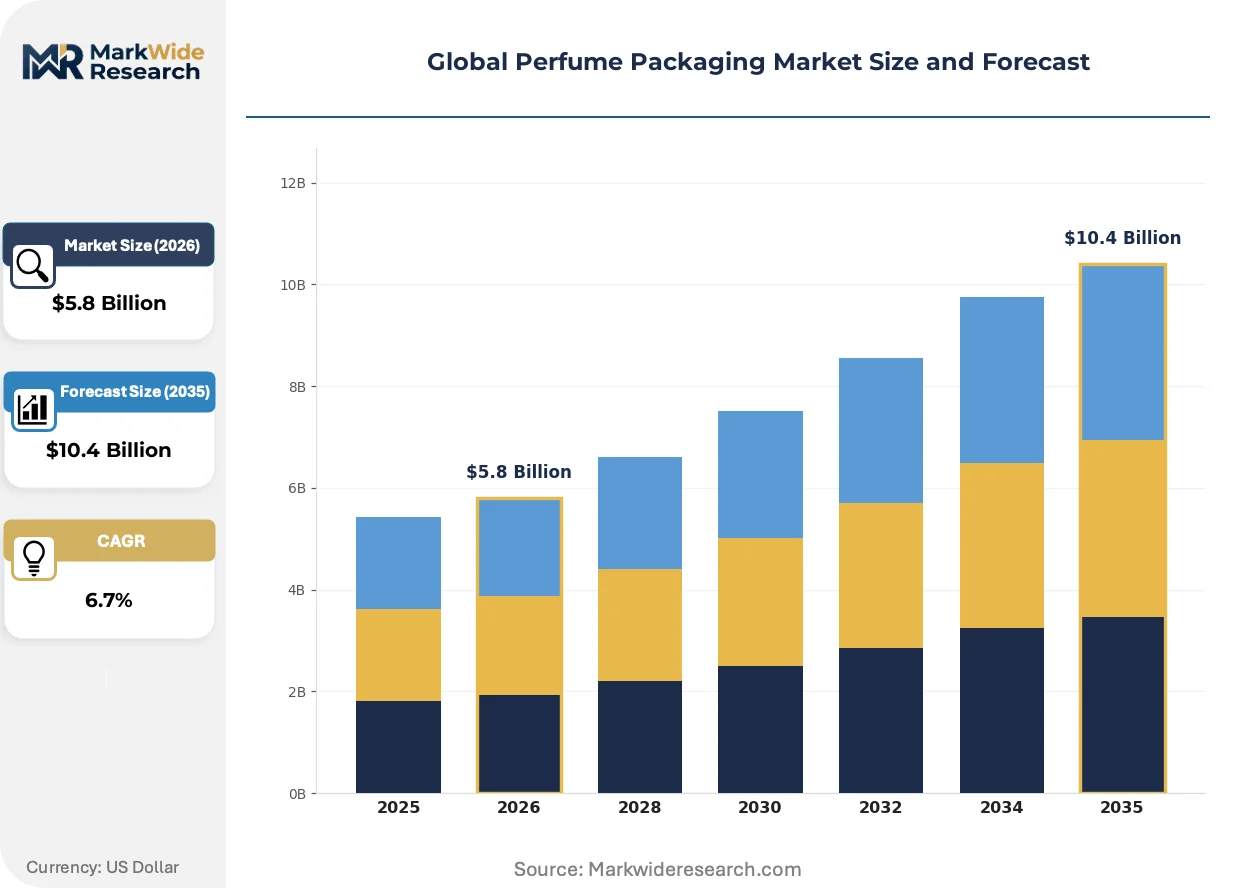
Market Dynamics
EU REACH restrictions on plasticizers and the EU Green Deal carbon-border adjustments are forcing material substitution from virgin polymers to post-consumer recycled glass and aluminum across flacon and closure production.
Growth Catalysts
- Refillable flacon systems:Heritage fragrance houses in France and the United Arab Emirates are mandating aluminum-cased refill mechanisms to extend customer lifetime value and reduce per-unit material intensity.
- REACH compliance deadlines:ECHA substance restrictions on phthalate-based plasticizers are accelerating converter qualification of bio-based polypropylene for pump housings and overcaps.
- Digital discovery channels:Social commerce platforms are expanding procurement of sample-sized formats, compressing minimum order quantities and rewarding converters with rapid tooling turnaround.
Market Restraints
- Post-consumer cullet scarcity:Flacon-grade recycled glass supply concentrates in Germany and Italy, creating input bottlenecks for converters lacking captive furnace access or long-term offtake agreements.
- Aluminum alloy price volatility:LME price swings for 6061 and 3003 series alloys are compressing margin stability on refillable metal sleeves and magnetic closure systems.
- Decorative process limitations:Water-based coating technologies for glass still fail to match solvent-based alternatives in abrasion resistance, constraining premium brand adoption.
Strategic Opportunities
- India fragrance market expansion:Domestic perfume consumption in Mumbai and Delhi is outpacing local packaging supply, creating openings for converters with BIS-certified glass and pump assembly capabilities.
- Monomaterial pump design:Convergence of all-PE spring mechanisms with rPET flacon bodies enables single-stream recycling without disassembly, aligning with EU Green Deal circularity targets.
- Blockchain traceability integration:Luxury houses are piloting QR-linked supply chain verification for mined crystal stoppers and conflict-free gold plating, differentiating at point of sale.
Industry Challenges
- Decorative artisan scarcity:Hand-finishing techniques for lacquering and gilding face generational skill gaps in Murano and Bohemia glassworking clusters.
- Multi-jurisdiction certification lag:Simultaneous compliance with EU REACH, FDA cosmetic packaging guidelines, and China's GB standards extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Perfume Packaging Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Plastic, Metal, Wood Packaging Type: Spray Bottles, Roll-Ons, Testers, Sample Packs End User: Luxury Brands, Mass Market, Independent Perfumeries, Online Retailers Design Style: Modern, Vintage, Minimalist, Artistic |
| Companies Covered | Gerresheimer AG, AptarGroup, Albea, Ball Corporation, Saverglass, Piramal Glass, Verescence France SASU, Quadpack, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Perfume Packaging Market Strategic Shifts
Smart packaging integration and material traceability systems are redefining how fragrance houses authenticate provenance and engage post-purchase. These shifts compress traditional decoration cycles while elevating regulatory documentation requirements.
Near-field communication chips embedded in secondary cartons are converging with blockchain-verified supply chain data to enable authentication and reordering via smartphone tap. Niche and indie fragrance brands in South Korea and Japan are piloting these systems for limited-edition releases. The technology is converging with customer relationship management platforms to capture consumption patterns and trigger replenishment before stock depletion.
EU Green Deal carbon-border adjustments are redirecting supplier audits toward renewable energy certificates and Scope 3 emissions disclosure for glass furnace operations. ECHA is expanding SVHC candidate list screening to cover imported decorated components, not just raw materials. Mid-sized converters in Italy and Spain are consolidating to share certification costs and maintain access to LVMH and Kering supply rosters.
Direct-to-consumer sampling subscriptions are fragmenting bulk procurement into micro-lot orders of 2-5ml vials with customized outer sleeves. Online retailers including Sephora and regional platforms in Southeast Asia are demanding ship-flat secondary packaging that reduces dimensional weight. This pattern is most visible in Singapore and Australia, where last-mile delivery costs dominate unit economics and unboxing video shareability drives repeat purchase rates.
Global Perfume Packaging Market Segmentation
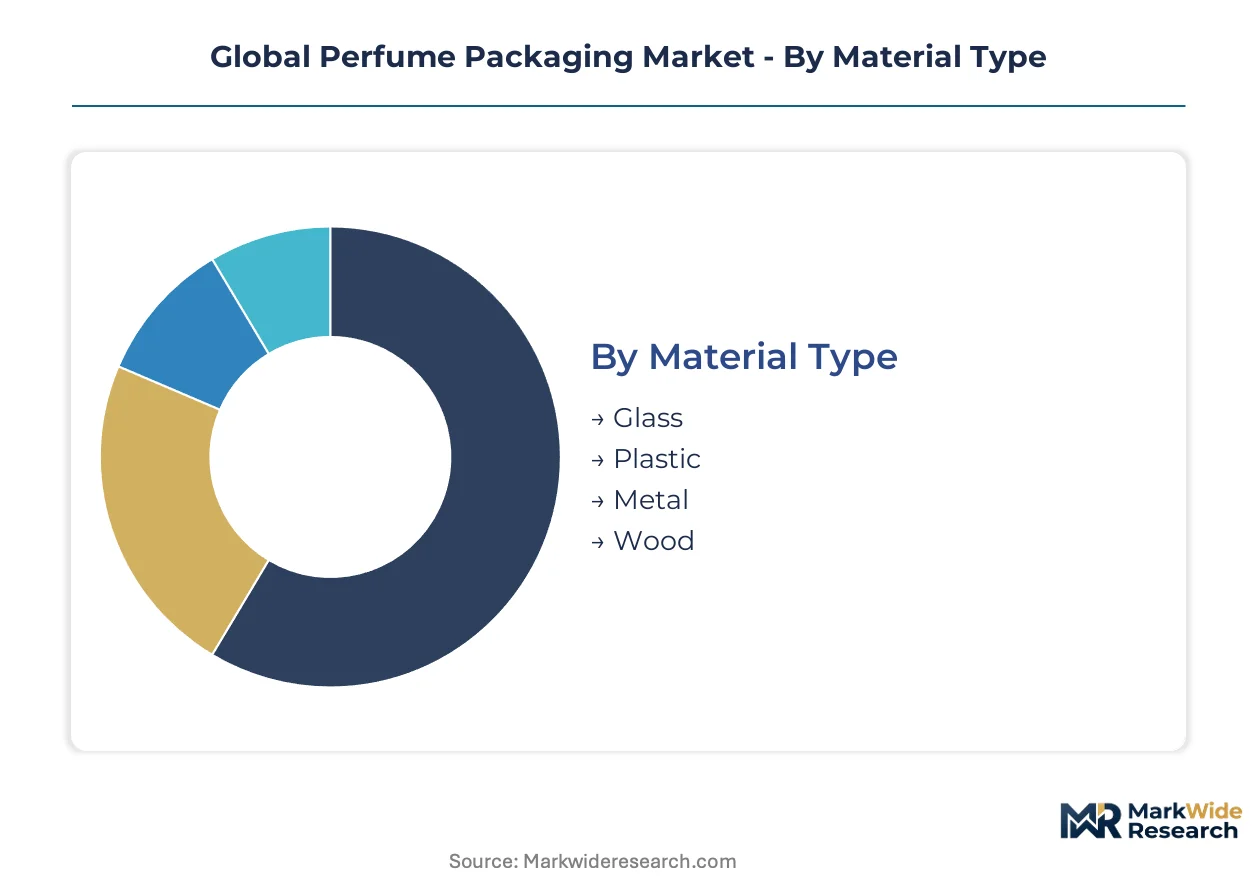
Material chemistry and closure mechanics determine preservation integrity, while decoration protocols signal price positioning. Each segmentation axis carries distinct procurement patterns and regulatory exposure that converters must navigate.
Material Type:
Chemical inertness and recyclability credentials define competitive positioning across substrate selection.
- Glass:Borosilicate and soda-lime formulations dominate flacon production due to zero gas permeability and UV-blocking tints. Heritage houses in France specify flacon-grade cullet from German and Italian furnace networks to satisfy EU Green Deal circularity audits.
- Plastic:Bio-based polypropylene and rPET are displacing virgin polymers in pump housings as ECHA REACH restrictions tighten on phthalate plasticizers. Mass-market procurement in the United States favors these materials for cost compression alongside FDA cosmetic packaging compliance.
- Metal:Aluminum 6061 and 3003 alloys form refillable sleeve systems and magnetic closures. LME price volatility constrains margin stability for converters serving Middle Eastern heritage brands.
- Wood:Certified hardwood caps and base inserts target artisanal positioning. Supply concentrates in sustainably managed European forests with FSC chain-of-custody documentation.
Mature deployment sits with glass. Newer deployment is concentrated in metal refillable systems.
Packaging Type:
Volume throughput and format miniaturization are diverging procurement specifications.
- Spray Bottles:Crimp-neck glass flacons with metered-dose pumps remain the volume anchor. Demand concentrates in French and Italian luxury houses requiring precision spray patterns across viscosity ranges.
- Sample Packs:2-5ml vials with heat-sealed or snap-fit closures are climbing the fastest as Sephora and Southeast Asian digital platforms fragment orders into micro-lots for subscription discovery models.
- Roll-Ons:Glass or plastic spheres in cylindrical housings target travel and pulse-point application. Mass-market brands in India specify these for price-accessible formats.
- Testers:Unboxed, often pump-less presentation formats for retail counter display. Procurement runs through duty-free operators in Dubai and Singapore.
High-volume contracts cluster around spray bottles. Format experimentation is expanding most quickly in sample packs.
End User:
Margin structure and order cadence vary sharply across customer archetypes.
- Luxury Brands:LVMH, Kering, and independent heritage houses command bespoke tooling and hand-finishing. These buyers absorb premium pricing for audited recyclate streams and renewable energy certificates.
- Mass Market:Coty and Inter Parfums scale procurement across standardized SKUs with compressed lead times. Specifications prioritize ship-flat secondary packaging for e-commerce durability.
- Independent Perfumeries:Niche creators in South Korea and Japan order limited runs with rapid decoration turnaround. These buyers pilot NFC-enabled authentication before mainstream adoption.
- Online Retailers:Amazon, Sephora, and regional platforms in Australia demand dimensional-weight-optimized formats with unboxing-optimized presentation. Minimum order quantities have collapsed to micro-lot thresholds.
Revenue concentration rests with luxury brands. Customer acquisition investment is expanding most quickly through online retailers.
Design Style:
Visual semiotics and tactile finish protocols segment converter capabilities.
- Modern:Clean lines, monochromatic coatings, and sans-serif typography dominate contemporary launches. Italian converters lead in water-based coating application for abrasion resistance.
- Vintage:Ornate stoppers, gilded accents, and serif logotypes reference heritage archives. Murano and Bohemia clusters face generational skill gaps in hand-lacquering techniques.
- Minimalist:Unadorned glass with raw material exposure and debossed rather than printed branding. Japanese fragrance houses specify these for shelf differentiation.
- Artistic:Collaborations with contemporary artists or crystal houses for limited editions. Blockchain traceability pilots verify provenance for conflict-free gold plating and mined crystal.
Established production capacity serves modern and vintage aesthetics. Capability investment is concentrating in artistic collaborations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France concentrates heritage fragrance house procurement and drives premium flacon specifications. Italy, Germany, the United Arab Emirates, the United States, and India anchor distinct demand clusters with diverging regulatory and supply chain configurations.
France
LVMH and Kering supply rosters mandate audited recyclate streams and renewable energy certificates for glass furnace operations. EU REACH restrictions on phthalate plasticizers accelerate converter qualification timelines. Paris and Grasse clusters dominate bespoke tooling and hand-finishing for limited-edition launches.
Italy
Murano glassworking heritage supports artisanal lacquering and gilding for luxury positioning. ECHA SVHC candidate list screening extends to imported decorated components under EU Green Deal compliance protocols. Mid-sized converters in Veneto and Tuscany consolidate to share certification costs and maintain access to major brand supply chains.
Germany
Gerresheimer AG leverages its European furnace network to supply flacon-grade cullet at scale for premium brands. EU Green Deal carbon-border adjustments redirect supplier audits toward Scope 3 emissions disclosure. Glassworking clusters in Bavaria and North Rhine-Westphalia face post-consumer cullet scarcity constraints.
United Arab Emirates
Heritage fragrance houses mandate aluminum-cased refill mechanisms to extend customer lifetime value. MOHAP cosmetic packaging standards add compliance layers for imported components. Dubai duty-free operators drive procurement of unboxed tester formats for retail counter display.
United States
FDA cosmetic packaging guidelines favor multinational converters with cross-border certification infrastructure. Mass-market brands prioritize ship-flat secondary packaging for e-commerce durability. Digital discovery channels through Sephora and Amazon fragment orders into micro-lot sample formats.
Global Perfume Packaging Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with heritage glasshouses commanding premium positioning and volume converters serving mass-market scale. The structure consolidates around furnace network control and pump-mechanism intellectual property. Three archetypes dominate: European heritage glass specialists with captive cullet supply, North American diversified packaging conglomerates with cross-regional certification infrastructure, and Asian integrated converters with cost-optimized standard formats. Competitive moves center on M&A for furnace access and strategic partnerships for decoration capability.
Among European heritage specialists, Gerresheimer AG and Verescence France SASU exemplify the furnace-network archetype with cullet supply integration. AptarGroup occupies a position representing pump-mechanism innovation capabilities that reduce metal content. These three anchors illustrate how geographic clustering and capability specialization stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| Gerresheimer AG |
| AptarGroup |
| Albea |
| Ball Corporation |
| Saverglass |
| Piramal Glass |
| Verescence France SASU |
| Quadpack |
| Berry Global |
| Others |
Value Chain & Pricing Dynamics
Hand-finishing artisans in Murano and Bohemia command wage premiums that widen spreads between heritage luxury flacons and mass-market formats. Labor-cost differentials between European glassworking clusters and Asian standard-format converters stratify pricing tiers across refillable systems and single-use bottles.
Pricing Analysis
Volume anchors at mass-market spray bottles while margins concentrate in limited-edition artistic collaborations. Three-tier pricing structure across premium, standard, and economy levels separates audited recyclate streams from virgin materials and uncertified inputs. Cost compression in mass-market tiers stems from micro-lot fragmentation via digital discovery channels. Online retailers exhibit highest price sensitivity; heritage houses absorb premium pricing for renewable energy certificates and hand-finished decoration.
Supply Chain Analysis
Workforce availability constraints in Murano lacquering and Bohemian gilding tether output expansion to generational skill transfer timelines. Supply concentrates in Germany, Italy, and France for flacon-grade cullet and furnace networks. Raw material dependencies include post-consumer recycled glass, aluminum 6061 alloys, and bio-based polypropylene for pump housings. Single-source vulnerability runs through German furnace networks for premium cullet supply. Distribution runs through duty-free operators in Dubai and Singapore for tester formats, direct-to-consumer platforms for sample packs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU REACH substance restrictions and EU Green Deal carbon-border adjustments erect barrier-to-entry moats favoring converters with cross-border certification infrastructure.
For Market Incumbents: Hedge against post-consumer cullet scarcity by securing long-term offtake agreements with German and Italian furnace networks. Deepen captive recycling investments to offset outsourced sustainable material premiums as ECHA expands SVHC screening to decorated components.
For New Entrants and Emerging Players: Capture whitespace in India's fragrance packaging supply gap by establishing BIS-certified glass and pump assembly capabilities in Mumbai and Delhi corridors. Prioritize rapid tooling turnaround for micro-lot sample formats demanded by Southeast Asian digital platforms.
For Investors and Strategic Acquirers: The window for entry favors mid-sized European converters with decoration capabilities and shared certification cost structures. Long-term viability hinges on furnace network control and pump-mechanism intellectual property. Watch for consolidation waves triggered by EU Green Deal compliance deadline acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cullet Supply | Gerresheimer AG's European furnace network secures flacon-grade recycled glass at scale for heritage brands. |
| Monomaterial Pump Design Development | All-PE spring mechanisms with rPET flacon bodies enable single-stream recycling aligned with EU circularity targets. |
| Blockchain Traceability Pilot Expansion | QR-linked supply chain verification differentiates luxury houses at point of sale for conflict-free gold plating. |
| Shared Certification Cost Consolidation | Mid-sized Italian and Spanish converters pool EU REACH, FDA, and China GB compliance expenses to maintain LVMH access. |
| Rapid Tooling Turnaround Investment | Compressed lead times for 2-5ml sample formats capture procurement from Sephora and Southeast Asian subscription platforms. |
Study Parameters
Independent corroboration across packaging procurement directors at heritage fragrance houses, sustainability officers at glass converters, and regulatory compliance leads at multinational OEMs underwrites the qualitative findings. Primary fieldwork encompassed supply chain managers at furnace networks, decoration specialists in Murano and Bohemia clusters, and e-commerce operations heads at online retailers. Secondary validation drew from ECHA substance restriction databases, EU Green Deal implementation guidelines, customs records for glass and aluminum trade flows, and SEC filings from listed packaging conglomerates. Bottom-up demand modeling triangulated against top-down market sizing across material type, packaging format, and end-user archetype.
Rate-of-change decomposition isolated volume drivers from price-mix effects across the projection horizon. Segmentation dimensions encompassed material chemistry tiers, closure mechanism complexity, decoration protocol intensity, and regional regulatory cluster stringency. CAGRs were derived from trend extrapolation of refillable system adoption curves, digital channel penetration rates, and compliance cost pass-through elasticity. Industry-specific inputs included aluminum LME price volatility coefficients and post-consumer cullet availability indices by furnace network.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA SVHC list expansion timing and EU carbon-border adjustment implementation pace. Assumptions reflect current regulatory trajectories and disclosed sustainability commitments from major fragrance houses. Material deviation in REACH restriction scopes or renewable energy certificate verification standards warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Lotion Tubes Market
Cosmetic Packaging
Latin America Cosmetic Packaging Market
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Lip Gloss Tube Market
Cosmetic Packaging
Hair Care Packaging Market
Cosmetic Packaging
India Personal Care Packaging Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Tubes Market
Cosmetic Packaging
Europe Cosmetic Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
US Personal Care Packaging Market
Cosmetic Packaging
Beauty Supplements Packaging Market
Cosmetic Packaging
North America Cosmetic Packaging Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market