
 Injection Moulding Cosmetic Packaging Market | 2026-2036
Injection Moulding Cosmetic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Injection Moulding Cosmetic Packaging Market Foresight
Buyer concentration among multinational beauty houses is pivoting as indie skincare labels and direct-to-consumer fragrance startups fragment procurement across smaller batch orders. Berry Global leverages its North American blow-moulding footprint to compete for high-volume tube contracts with mass-market haircare brands. HCP Packaging anchors Asian supply through dedicated facilities serving colour cosmetics houses with complex multi-component jar assemblies. Silgan Holdings sustains European relationships via in-house decoration and metallization capabilities that reduce supplier touchpoints for premium fragrance bottles.
Injection moulding cosmetic packaging denotes rigid containers, closures, and dispensers formed by forcing thermoplastic or thermoset polymers into precision-engineered steel moulds under controlled temperature and pressure cycles, typically achieving wall thickness tolerances of ±0.05 mm for dimensional stability across million-unit production runs. This process serves the beauty industry by delivering repeatable aesthetic quality, tamper-evident functionality, and compatibility with automated filling lines at speeds exceeding 300 units per minute. Tubes and jars command the largest volume positions as established formats for skincare and makeup applications, while pump and flip-top closures are gaining structural share as brands eliminate secondary cartoning and shift toward single-unit dispensing solutions. Polypropylene occupies the dominant material position for its chemical resistance and living-hinge durability in snap-on cap designs, though polyethylene competes aggressively in squeezable tube segments where flexibility and stress-crack resistance determine shelf performance.
The European Chemicals Agency enforces REACH compliance for substance restrictions in coloured masterbatches, while the FDA regulates cosmetic packaging contact materials under the Federal Food, Drug, and Cosmetic Act in the United States. China's SAMR mandates GB standards for plastic food-contact materials that also govern cosmetic packaging produced in shared converter facilities, creating cross-jurisdictional testing burdens for exporters. Stakeholders must monitor evolving extended producer responsibility schemes and material-specific recycling targets that will determine which resin platforms and mono-material designs retain market access across major economies.
Market Dynamics
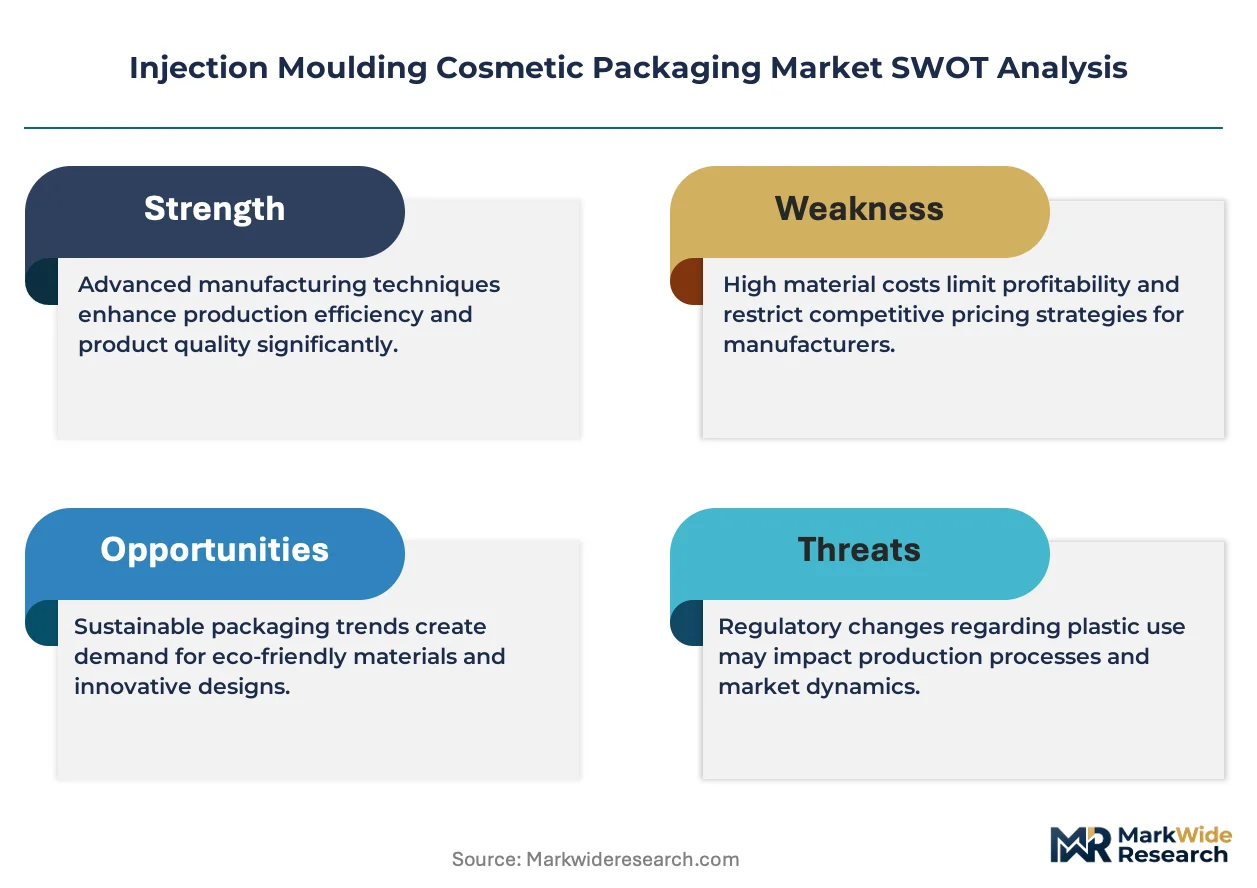
EU Green Deal mandates and the Packaging and Packaging Waste Regulation are forcing converters to abandon multi-material laminates for mono-material formats, compressing design cycles and supplier qualification timelines across beauty packaging procurement.
Growth Catalysts
- REACH substance restrictions:ECHA enforcement on coloured masterbatches is accelerating investment in compliant pigment systems, opening contract windows for certified compounders serving premium fragrance houses.
- Airless pump adoption:Skincare brands are specifying precision-moulded piston chambers to extend product shelf life, driving demand for tight-tolerance polypropylene processing.
- Nearshoring concentration:Beauty houses are consolidating injection moulding procurement in Germany, France, and Italy to reduce lead times and customs exposure.
Market Restraints
- Resin price volatility:Polypropylene and polyethylene feedstock costs swing with naphtha and natural gas indices, squeezing converter margins on fixed-price annual contracts.
- Mould fabrication bottlenecks:Precision steel tooling for ±0.05 mm wall tolerance requires 12-16 week lead times from specialised German and Japanese suppliers.
- Cross-jurisdictional testing:China's SAMR GB standards for food-contact plastics create parallel certification burdens for cosmetic packaging produced in shared converter facilities.
Strategic Opportunities
- Extended Producer Responsibility schemes:France's Citeo and Italy's CONAI eco-modulation fees reward mono-material designs with lower contribution rates, incentivising format simplification.
- Direct-to-consumer fragrance startups:Indie brands are fragmenting procurement into smaller batch orders, creating entry points for mid-cap moulders with quick-change tooling systems.
- Digital printing convergence:In-mould labelling combined with UV-cured inkjet decoration enables mass customisation without separate silk-screening steps.
Industry Challenges
- Tooling engineer scarcity:The specialised skill set for hot-runner manifold design and cavity flow simulation is concentrating among ageing workforces in Stuttgart and Milan industrial clusters.
- Recyclability certification timelines:Obtaining RecyClass or How2Recycle approval for novel mono-material pump mechanisms requires 8-14 months of third-party testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injection Moulding Cosmetic Packaging Market |
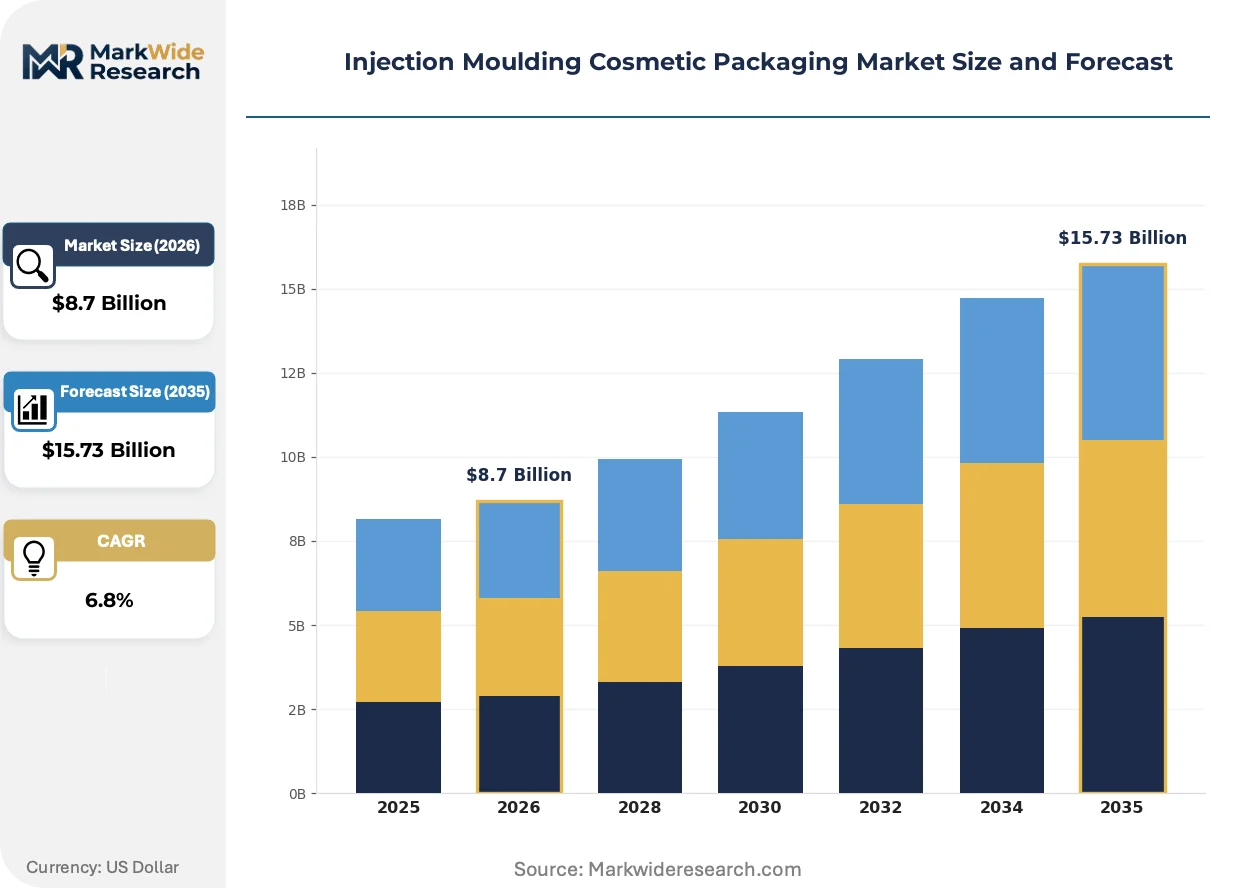
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tubes, Jars, Bottles, Containers Material: Polyethylene, Polypropylene, Glass, Aluminum Closure Type: Screwed, Snap-on, Pump, Flip-top End User: Skincare, Makeup, Haircare, Fragrance |
| Companies Covered | Silgan Holdings, Quadpack, RPC Group, Graham Packaging, Berry Global, Albea, HCP Packaging, Amcor, AptarGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injection Moulding Cosmetic Packaging Market Shifts & Advancements
Active redesign of cosmetic packaging formats is compressing material palettes and consolidating decoration steps, with sustainability compliance now dictating structural engineering decisions ahead of aesthetic considerations.
Mono-material polypropylene pump systems are modularizing the traditional multi-component dispenser architecture. Premium skincare houses are specifying all-PP assemblies with living-hinge flip-tops to eliminate metal springs and glass windows. This technology is modularizing supplier relationships by allowing converters to source entire pump mechanisms from single-resin platforms rather than coordinating five-plus material vendors.
EU Green Deal packaging recyclability targets are mandating design-for-recycling protocols by 2030. The industrial consequence is a ban on dark carbon-black masterbatches that contaminate near-infrared sorting streams. Colour cosmetics houses in France and Germany are responding fastest, reformulating to detectable grey and blue tints while retaining shelf appeal through surface metallization.
Beauty brand procurement teams are consolidating supplier panels and demanding integrated decoration capabilities. Mass-market haircare labels are bypassing standalone decorators by awarding tube contracts to moulders with in-house silk-screening and hot-stamping. This concentration is most visible in North American supply chains, where Berry Global and similar converters are capturing volume through decoration-capable facilities.
Injection Moulding Cosmetic Packaging Market Segmentation
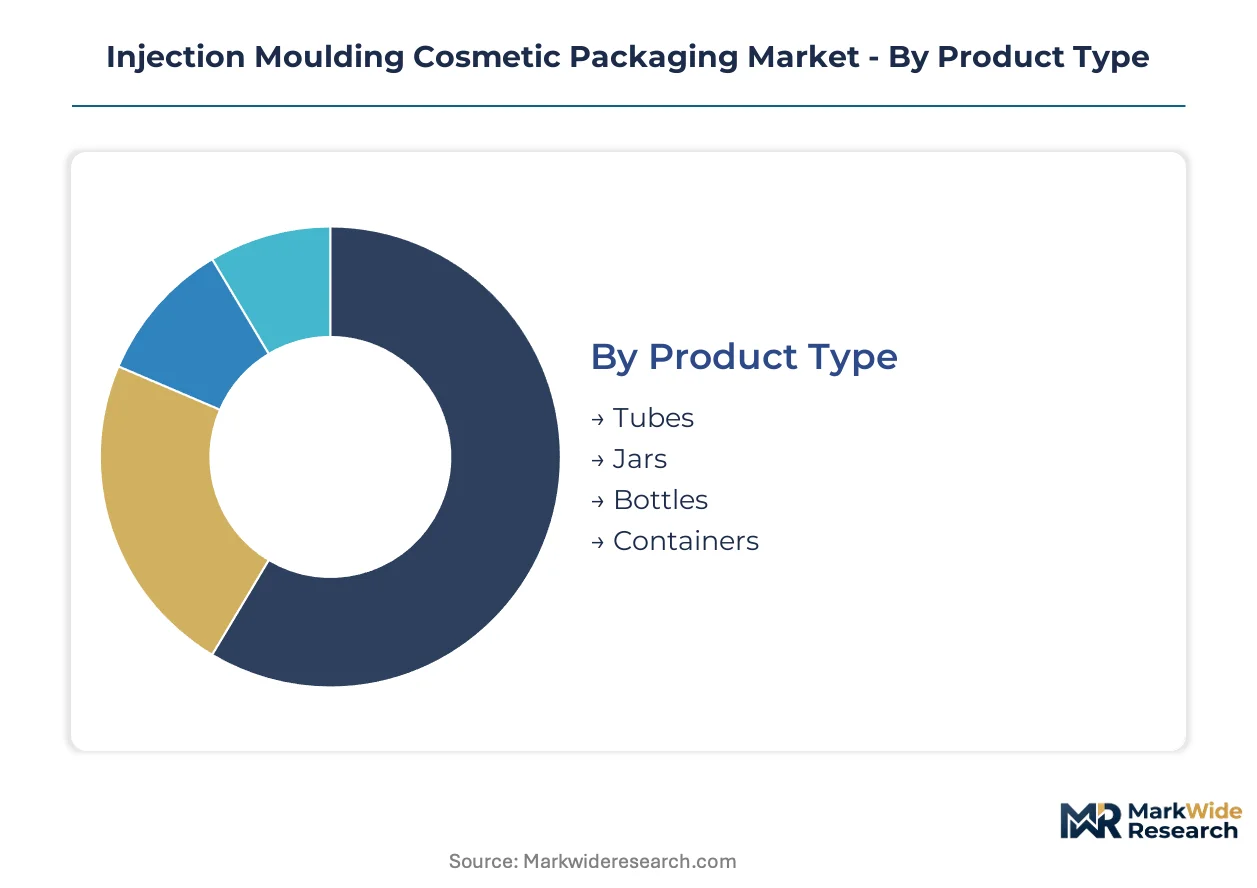
Segmentation in injection moulding cosmetic packaging reveals how procurement priorities diverge across format requirements, material compliance burdens, and dispensing functionality. Each category exposes distinct technical constraints that reshape supplier qualification criteria and mould investment decisions.
Product Type:
Brand procurement teams select formats based on viscosity compatibility, shelf presence requirements, and filling line integration needs.
- Tubes:Multi-layer extrusions with injection-moulded shoulders and caps dominate haircare and sunscreen applications. Mass-market brands in Germany and France are consolidating tube procurement with moulders offering in-house silk-screening to eliminate secondary decoration steps.
- Jars:Thick-walled polypropylene or glass-filled assemblies serve premium skincare creams requiring wide-mouth access. Demand concentrates with colour cosmetics houses specifying complex multi-component assemblies with metallized finishes.
- Bottles:Blow-moulded or injection-stretch bodies with separate closure systems accommodate liquid foundations and serums. E-commerce-ready designs prioritize leak-resistant neck finishes over traditional aesthetic differentiation.
- Containers:Rigid rectangular formats for solid balms and powder compacts leverage living-hinge integration in single-shot moulding. Indie fragrance startups are fragmenting orders into smaller batch runs with quick-change tooling requirements.
Volume sits with tubes; growth tilts toward jars as premium skincare expands airless and wide-mouth formats.
Material:
Resin selection determines chemical compatibility, recycling pathway eligibility, and regulatory compliance burden across jurisdictions.
- Polyethylene:Linear low-density grades dominate squeezable tube bodies where stress-crack resistance determines shelf performance. REACH-compliant masterbatch reformulation is accelerating investment in detectable pigment systems for French and German converters.
- Polypropylene:Homopolymer and random copolymer grades command rigid container and closure applications with living-hinge durability. EU Green Deal recyclability mandates are pushing premium houses toward all-PP pump assemblies that eliminate multi-material contamination.
- Glass:Borosilicate and soda-lime formats persist in premium fragrance bottles where weight signals luxury positioning. Decoration-capable converters with in-house metallization are capturing volume as brands consolidate supplier panels.
- Aluminum:Impact-extruded or drawn canisters serve aerosol and solid perfume formats with barrier properties. Mono-material aluminum designs qualify for favorable eco-modulation fees under France's Citeo extended producer responsibility scheme.
Polypropylene holds the largest installed base; polyethylene is climbing the fastest as tube formats expand in mass-market haircare.
Closure Type:
Dispensing mechanism selection reflects brand priorities around product preservation, consumer convenience, and single-unit packaging elimination.
- Screwed:Threaded polypropylene or polyethylene caps with induction seals serve standard skincare and haircare bottles. Procurement is shifting toward moulders with integrated liner insertion and torque testing capabilities.
- Snap-on:Living-hinge designs with audible engagement feedback dominate travel-size and sample formats. Tight-tolerance processing requirements are concentrating supply among Stuttgart and Milan tooling clusters with hot-runner expertise.
- Pump:Precision-moulded piston chambers with metal or all-plastic spring mechanisms extend shelf life for airless skincare systems. Extended producer responsibility schemes are rewarding mono-material PP pump designs with lower contribution rates.
- Flip-top:One-handed dispensing formats with integrated orifice reducers eliminate secondary cartoning for on-the-go applications. Direct-to-consumer brands are specifying quick-turn tooling for seasonal variant launches.
Screwed closures dominate current volume; pump mechanisms show the steepest expansion trajectory as airless systems displace traditional formats.
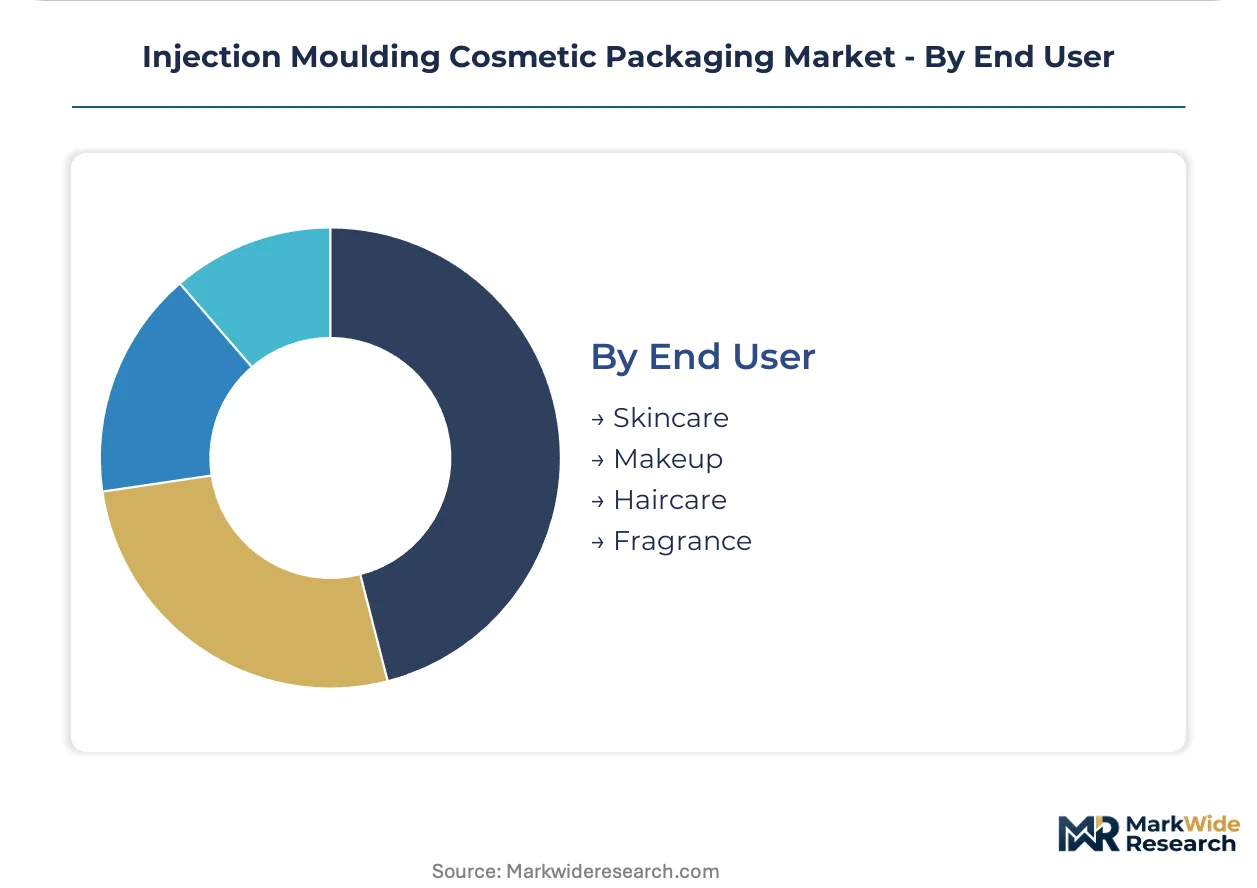
End User:
Category-specific performance requirements drive divergent specifications for barrier properties, decoration complexity, and batch size flexibility.
- Skincare:Airless pump jars and tubes with oxygen and UV barrier layers protect active ingredient stability. Nearshoring concentration in Germany, France, and Italy is compressing lead times for premium brand procurement teams.
- Makeup:Multi-component compact assemblies with magnetic closure and mirror integration demand high-cavity tooling with tight tolerances. Asian supply chains through dedicated facilities are serving colour cosmetics houses with complex jar requirements.
- Haircare:Large-volume tubes and bottles with flip-top or pump dispensers prioritize filling line speed over decoration complexity. Mass-market labels are awarding contracts to converters with blow-moulding footprints and high-volume throughput.
- Fragrance:Heavy-walled bottles with metallized or lacquered finishes require integrated decoration capabilities to reduce supplier touchpoints. Indie and direct-to-consumer startups are fragmenting procurement into smaller batch orders with digital printing requirements.
Haircare commands the greatest unit volume; skincare is gaining share fastest as premium airless formats expand across serum and cream applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beauty houses in Germany, France, and Italy are consolidating procurement to compress lead times and reduce customs exposure. Nearshoring concentration is reshaping converter capacity allocation across Western Europe. Asian supply chains retain dominance for complex multi-component assemblies serving colour cosmetics.
Germany
Mass-market haircare labels are awarding tube contracts to moulders with integrated blow-moulding and silk-screening capabilities. The EU Green Deal mandates mono-material formats by 2030, forcing reformulation of dark carbon-black masterbatches. Stuttgart industrial clusters concentrate hot-runner tooling expertise for ±0.05 mm tolerance pump mechanisms.
France
Premium fragrance houses are demanding metallized finishes with reduced supplier touchpoints. Citeo eco-modulation fees reward mono-material designs with lower contribution rates under extended producer responsibility. Paris-region converters are capturing volume through in-house decoration capabilities that bypass standalone decorators.
Italy
Colour cosmetics houses specify complex multi-component jar assemblies with magnetic closures and mirror integration. CONAI packaging consortium fees incentivize format simplification and detectable pigment systems. Milan tooling clusters specialize in high-cavity moulds for tight-tolerance living-hinge flip-tops.
China
Shared converter facilities face cross-jurisdictional testing burdens from SAMR GB standards for food-contact plastics. Yangtze River Delta and Pearl River Delta industrial zones anchor supply for Asian beauty markets. Domestic brands are fragmenting procurement into smaller batch orders with quick-change tooling requirements.
United States
Direct-to-consumer fragrance startups are bypassing traditional procurement channels for digital-print-enabled seasonal launches. FDA regulation of cosmetic packaging contact materials under the Federal Food, Drug, and Cosmetic Act shapes compliance investment. Berry Global leverages North American blow-moulding footprints to compete for high-volume haircare contracts.
Injection Moulding Cosmetic Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue quick-turn digital printing and mono-material specialization. The vendor base stratifies across three tiers: multinational converters with integrated decoration, regional specialists with hot-runner expertise, and agile mid-cap moulders serving indie brand fragmentation. Two dominant competitive moves are reshaping positioning: backward integration into in-house metallization and silk-screening to reduce supplier touchpoints, and geographic expansion through dedicated Asian facilities to serve colour cosmetics procurement.
Among North American-based converters, Berry Global and Silgan Holdings exemplify scale-driven archetypes with decoration-capable footprints. HCP Packaging occupies a position within the Asian-specialist tier, anchoring supply for complex jar assemblies. These three entities represent distinct strategic postures: continental-scale integrated production, European relationship sustainment through in-house finishing, and Asia-dedicated capacity for premium colour cosmetics.
| Leading Market Players |
|---|
| Silgan Holdings |
| Quadpack |
| RPC Group |
| Graham Packaging |
| Berry Global |
| Albea |
| HCP Packaging |
| Amcor |
| AptarGroup |
| Others |
Supply & Pricing Matrix
Multinational beauty houses consolidating procurement in Germany, France, and Italy command volume-based contract structures that compress converter margins on fixed-price annual commitments. This buyer concentration tilts pricing power toward mass-market haircare labels while squeezing mid-cap moulders serving fragmented indie brand orders.
Pricing Analysis
Volume sits with mass-market haircare labels negotiating fixed-price annual contracts, while premium fragrance houses tolerate higher per-unit costs for integrated metallization and decoration capabilities. Three-tier pricing structure across premium, standard, and economy levels separates all-PP mono-material pump assemblies from multi-component legacy formats and basic snap-on closures. Cost compression in standard-tier tube contracts is intensifying because resin price volatility tracks naphtha and natural gas indices. Mass-market haircare labels exhibit highest price sensitivity; premium skincare houses with airless pump specifications show least.
Supply Chain Analysis
Tooling engineer scarcity in Stuttgart and Milan industrial clusters constrains capacity expansion for hot-runner manifold design and cavity flow simulation. Supply concentrates in Germany, France, and Italy for European beauty house procurement, with Asian capacity anchored in Yangtze River Delta and Pearl River Delta zones for colour cosmetics. Precision steel tooling for tight-tolerance pump mechanisms draws from specialized German and Japanese suppliers, while polypropylene and polyethylene feedstock hinges on petrochemical complexes in Belgium and the Netherlands. Single-source vulnerability in precision mould fabrication creates bottleneck risk. Distribution runs through converter-direct relationships with beauty house procurement teams, bypassing traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained precision tooling capacity props pricing power for converters with captive hot-runner expertise, as 12-16 week mould fabrication lead times limit rapid competitor entry.
For Market Incumbents: Cement relationships with premium fragrance houses by deepening in-house metallization and silk-screening capabilities that eliminate standalone decorator touchpoints. Add dedicated quick-change tooling capacity in Milan or Stuttgart clusters to capture fragmented indie brand orders before mid-cap specialists establish footholds. Threat of digital-print-enabled new entrants eroding decoration-margin pools demands preemptive channel control through integrated finishing investments. For New Entrants and Emerging Players: E-commerce direct-to-consumer channels offer the lowest barrier entry point for seasonal fragrance launches with UV-cured inkjet decoration and mass-customization capabilities. Target white-space in mono-material PP pump assemblies for indie skincare labels seeking RecyClass certification without legacy multi-material conversion burdens. Go-to-market angle: quick-turn tooling partnerships with Milan-based mould fabricators serving sub-100k unit batch runs. For Investors and Strategic Acquirers: The window for entry favors converters with established hot-runner expertise and existing RecyClass-approved mono-material formats. Long-term viability rests on backward integration into masterbatch compounding to control pigment compliance costs under REACH enforcement. Acquisition target archetype: mid-cap Italian or German moulders with living-hinge specialization and open capacity. Signal to watch: Citeo and CONAI eco-modulation fee revisions accelerating format simplification mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Pump Assembly Development | Eliminates multi-material contamination for EU Green Deal recyclability targets by 2030. |
| In-House Metallization Capability Expansion | Reduces supplier touchpoints for premium fragrance houses consolidating procurement panels. |
| Quick-Change Tooling System Investment | Captures fragmented indie brand orders with seasonal variant launch requirements. |
| REACH-Compliant Masterbatch Backward Integration | Controls pigment system costs as ECHA enforcement tightens on coloured compounds. |
| RecyClass Certification Acceleration | Secures market access under France's Citeo and Italy's CONAI extended producer responsibility schemes. |
Research Methodology
Independent corroboration across converter procurement directors, beauty house packaging engineers, and hot-runner tooling specialists underwrites the qualitative findings in this study. Primary interviews with mould fabrication plant managers, resin compounder technical leads, and extended producer responsibility scheme administrators combined with secondary validation. Secondary sources include EU Packaging and Packaging Waste Regulation impact assessments, ECHA REACH substance restriction databases, RecyClass technical approval records, and customs trade data for polymer imports. Bottom-up unit economics triangulated against top-down market sizing across product type, material, closure mechanism, and end-use category dimensions.
Rate-of-change decomposition across the analysis window separates volume growth from value expansion driven by premium format mix shift. Segmentation dimensions modeled include product format, resin platform, dispensing mechanism, end-use vertical, and regional procurement cluster. CAGRs derived from logistic curve fitting to historical shipment data adjusted for regulatory inflection points. Industry-specific forecast inputs incorporate EU Green Deal packaging recyclability target timelines and REACH substance restriction phase-in schedules.
The model holds under stable regulatory enforcement timelines and resin price volatility within historical bands; deviation in PPWR implementation acceleration or naphtha feedstock disruption would shift capacity allocation assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
Middle East and Africa Cosmetic Packaging Market
Cosmetic Packaging
North America Cosmetic Packaging Market
Cosmetic Packaging
Lotion Tubes Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Cosmetic Pump Bottle Market
Cosmetic Packaging
Global Perfume Packaging Market
Cosmetic Packaging
US Personal Care Packaging Market
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Latin America Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Beauty Supplements Packaging Market
Cosmetic Packaging
Cosmetic Bottles Packaging Market
Cosmetic Packaging
India Personal Care Packaging Market
Cosmetic Packaging
Europe Plastic Cosmetic Packaging Market
Cosmetic Packaging
Hair Care Packaging Market