
 Latin America Cosmetic Packaging Market | 2026-2036
Latin America Cosmetic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Cosmetic Packaging Market Foresight
Multi-sourced component procurement is rebalancing toward consolidated supplier relationships as brand owners seek quality assurance across Latin American operations. Albéa Group leverages its regional manufacturing footprint to serve skincare and fragrance houses with turnkey dispensing solutions. Aptar Group sustains technology leadership in precision pump mechanisms for high-viscosity formulations. HCP Packaging Co., Ltd. anchors its competitive position through specialized decoration capabilities that differentiate premium cosmetic lines across Brazilian and Mexican markets.
Latin America cosmetic packaging encompasses primary and secondary containment systems engineered from polymers, glass, aluminum, and cellulose-based substrates, designed to protect product integrity, enable controlled dispensing, and convey brand identity through surface graphics and structural form. Plastic bottles and tubes dominate volume throughput across the region, though glass jars command disproportionate margin pools in prestige skincare segments where tactile weight and chemical inertness justify premium positioning. Pump closures are displacing traditional screw caps in facial treatment and serum categories, reflecting formulation trends toward airless protection and precise dosing.
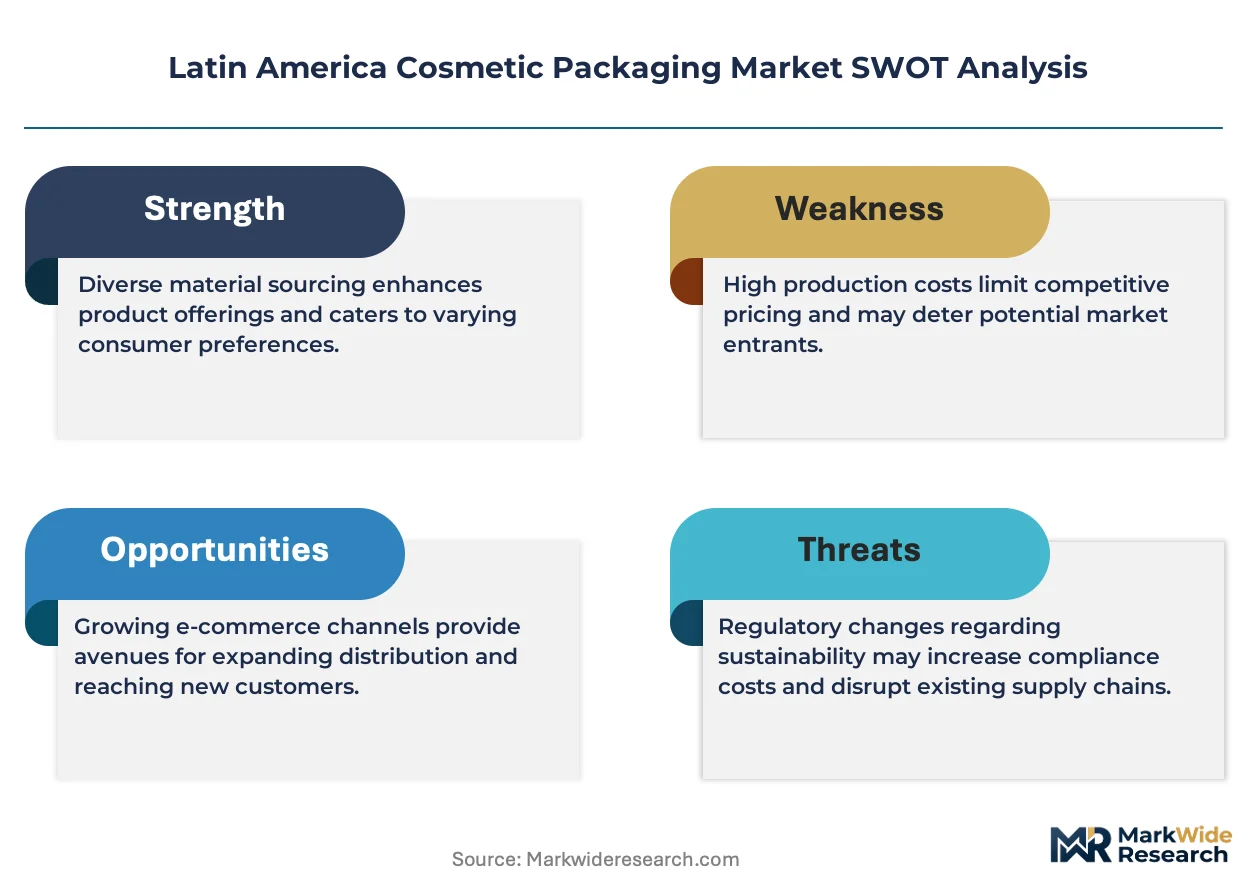
Brazil's ANVISA governs cosmetic packaging safety through residue and migration standards, while Mexico's PROFECO enforces net-content labeling accuracy that shapes primary container dimensioning and secondary pack configuration. These frameworks elevate compliance costs for imported components but simultaneously create protected demand for locally certified converters. Stakeholders must monitor evolving extended producer responsibility proposals across Mercosur jurisdictions, as pending packaging waste regulations threaten to restructure material selection criteria and reverse logistics obligations without grandfathering existing inventory positions.
Market Dynamics
Airless pump systems are consolidating procurement relationships across Brazilian and Mexican operations as skincare brands demand formulation stability and precise dosing control. This technology shift concentrates supplier selection around converters with validated cleanroom capabilities and regional certification portfolios.
Growth Catalysts
- ANVISA Residue Standards:Brazil's migration testing protocols for polymer-based primary containers elevate demand for certified local converters with in-house laboratory validation.
- High-Viscosity Serum Formulations:Skincare houses in São Paulo state are specifying precision pump mechanisms that protect active ingredient integrity through oxygen exclusion.
- São Paulo Converter Cluster:Proximity between formulation laboratories and packaging converters compresses development cycles for prestige skincare launches.
Market Restraints
- Aluminum Input Volatility:Premium glass jar lid assemblies depend on aluminum closure components exposed to commodity price swings.
- PROFECO Labeling Friction:Mexico's net-content accuracy enforcement creates dimensional constraints that limit design flexibility for primary containers.
- Cellulose Substrate Substitution:Secondary folding cartons face displacement pressure from polymer-based alternatives with superior moisture resistance.
Strategic Opportunities
- Colombian Market Underpenetration:Andean skincare brands currently import secondary packaging from Miami converters, creating captive demand for regional production.
- Extended Producer Responsibility Tailwinds:Pending Mercosur packaging waste mandates will favor mono-material pump systems with established reverse logistics pathways.
- Digital Printing-Conventional Decoration Convergence:Hybrid finishing lines enable short-run personalization for influencer-driven cosmetic launches without cylinder changeover delays.
Industry Challenges
- Cleanroom Technician Scarcity:Airless pump assembly requires controlled environment expertise that outpaces vocational training output in Brazilian interior states.
- ANVISA Certification Timelines:Migration study documentation for novel polymer grades extends qualification cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Cosmetic Packaging Market |
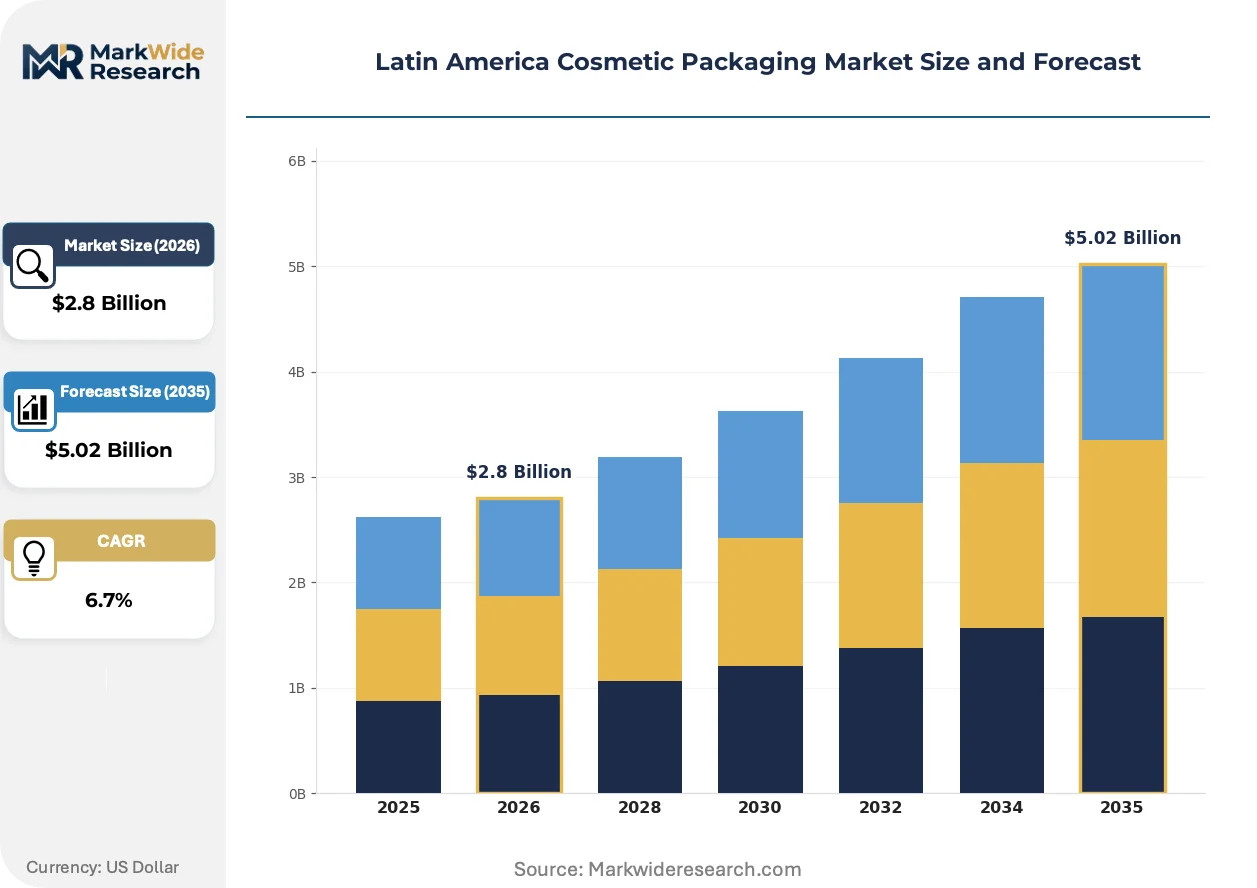
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Tubes, Sachets Material: Plastic, Glass, Metal, Paperboard Closure Type: Screw Caps, Pumps, Sprayers, Flip Tops End User: Skincare, Makeup, Haircare, Fragrance |
| Companies Covered | Albéa Group, Aptar Group, HCP Packaging Co., Ltd., Silgan Holdings Inc., Amcor PLC, Berry Global, Gerresheimer AG, DS Smith PLC, Sonoco Products Company, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Cosmetic Packaging Market Shifts & Advancements
Material science advances and regulatory tightening are compressing traditional packaging development cycles while elevating performance specifications for barrier properties and dispensing precision across Latin American cosmetic operations.
Mono-material airless pump assemblies are unifying previously separate component streams into single-resin systems that simplify recycling pathways. Prestige skincare brands in Mexico City and São Paulo are piloting these configurations for Q4 product refreshes. This unification is compressing supplier qualification requirements around converters with dedicated polypropylene processing lines and decoration capabilities.
PROFECO's evolving net-content verification protocols are forcing dimensional recalibration of primary containers to accommodate label real estate for expanded disclosure requirements. Secondary pack configurations must now integrate tamper-evident features that satisfy both Mexican enforcement and brand aesthetic standards. Fragrance houses operating near Guadalajara are responding with reduced-height bottle designs that preserve volume while expanding label surface area.
Brand owners are consolidating supplier relationships from fragmented regional sourcing toward single-source accountability for multi-country cosmetic portfolios. This concentration disrupts traditional procurement patterns that relied on Miami-based trading companies for component aggregation. Brazilian operations are most visibly affected, with São Paulo-based skincare houses now requiring direct technical service agreements with pump mechanism specialists rather than distributor intermediaries.
Latin America Cosmetic Packaging Market Segmentation
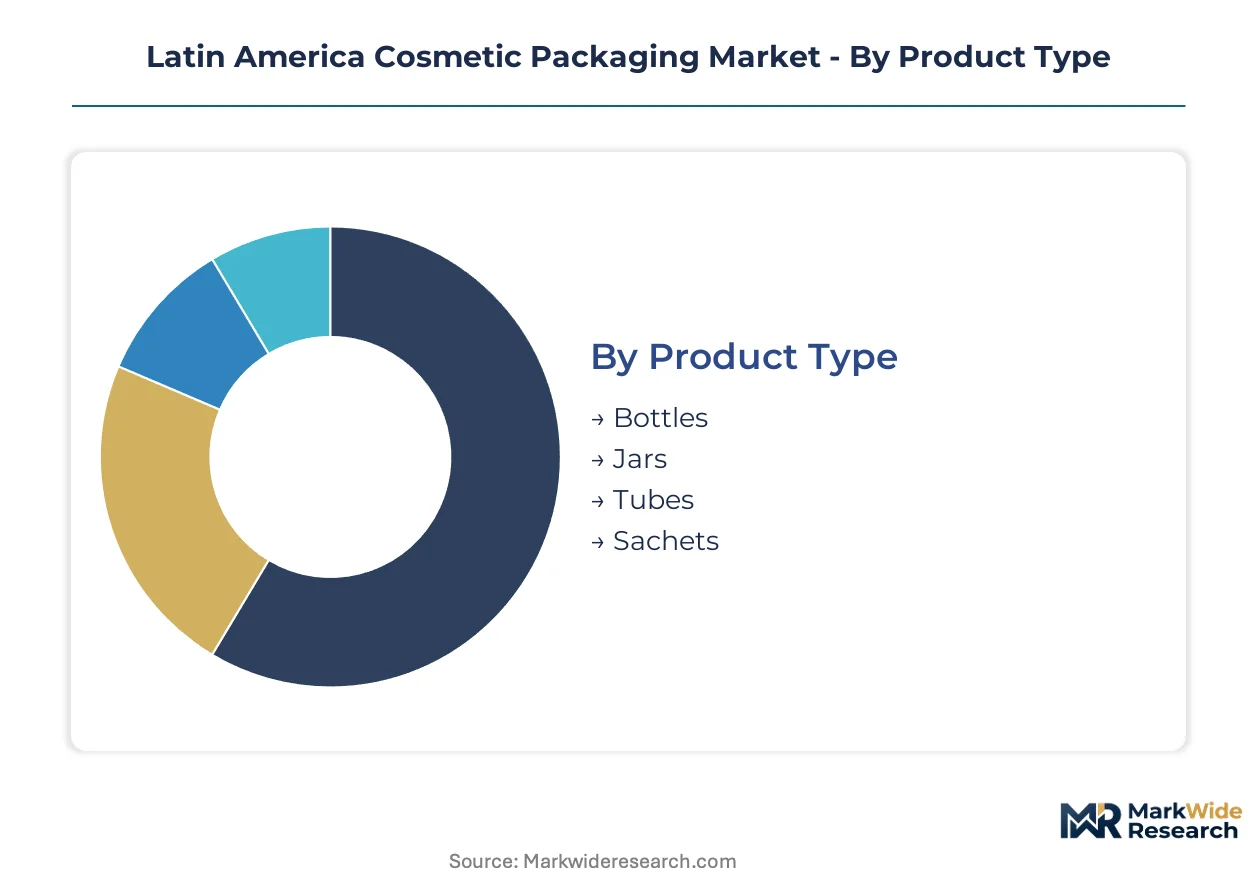
Latin American cosmetic packaging procurement varies sharply by product format, with skincare brands demanding precision-engineered dispensing systems while mass-market haircare tolerates standardized closures. Material selection and closure mechanics determine compliance pathways across ANVISA and PROFECO jurisdictions, creating divergent supplier qualification requirements.
Product Type:
Standardized formats dominate volume throughput, though customization intensity escalates toward premium skincare applications where dimensional tolerances tighten.
- Bottles:Polymer and glass configurations serve liquid formulations across body care and fragrance categories. São Paulo-based converters supply PET and HDPE variants with silk-screen decoration for Brazilian skincare houses seeking ANVISA-certified migration compliance. Most installed capacity flows through bottles. Expansion is steepest in airless pump-integrated bottle systems.
- Jars:Wide-mouth glass and polypropylene containers accommodate creams and balms requiring finger-access application. Mexican prestige brands near Guadalajara specify thick-walled glass with aluminum closures to satisfy PROFECO net-content labeling surface requirements. Jars gain share in premium skincare where tactile weight signals quality.
- Tubes:Laminated and extruded plastic formats deliver squeeze-dispensed products for haircare and body wash segments. Brazilian converters in São Paulo state produce multi-layer EVOH-barrier tubes for oxidation-sensitive formulations.
- Sachets:Single-use foil and polymer pouches sample fragrances and serums at point-of-sale. Colombian brands import these from Miami converters, though regional production interest is rising.
Tube capacity concentrates in São Paulo's industrial corridor. Sachet production is gaining share fastest among local converters.
Material:
Cost-positioning and regulatory migration limits split procurement between commodity polymers and certified barrier substrates.
- Plastic:PET, HDPE, and polypropylene constitute volume leadership across primary containers and closures. ANVISA residue testing protocols elevate demand for certified polymer grades with documented migration profiles from Brazilian converters. Plastic commands the greatest installed base. Glass is climbing the fastest in prestige skincare.
- Glass:Soda-lime and borosilicate formats serve fragrance and premium skincare where chemical inertness and heft justify unit cost premiums. Mexican fragrance houses near Guadalajara source decorated glass with aluminum closures to balance PROFECO compliance and aesthetic differentiation.
- Metal:Aluminum components form jar lids, fragrance caps, and aerosol canisters. Commodity price volatility constrains long-term contracting for these assemblies.
- Paperboard:Secondary folding cartons and rigid boxes provide surface graphics real estate for brand storytelling. Moisture sensitivity limits primary containment applications.
Polymer processing lines absorb the heaviest capital deployment. Glass furnace investments are expanding most quickly near São Paulo and Mexico City.
Closure Type:
Dispensing precision requirements separate commodity screw caps from engineered pump mechanisms with cleanroom assembly protocols.
- Screw Caps:Injection-molded polypropylene and polyethylene closures seal jars and bottles across mass-market haircare and body care. Brazilian converters produce these at scale with lower certification burdens than pump systems. Screw caps retain the broadest installed base. Pumps are gaining share fastest in facial treatment categories.
- Pumps:Airless and standard dispensing mechanisms protect serum formulations from oxidation while enabling precise dosing. São Paulo skincare brands specify these for ANVISA-compliant cleanroom assembly with validated migration documentation. Pump procurement is consolidating around converters with regional certification portfolios.
- Sprayers:Fine-mist and continuous-spray mechanisms serve fragrance and haircare applications. Mexican fragrance operations near Guadalajara demand these for alcohol-based formulations requiring compatibility testing.
- Flip Tops:Hinged polypropylene closures enable one-handed dispensing for shower and travel formats. These balance convenience with cost constraints in Brazilian mass-market body care.
Flip top molding capacity saturates São Paulo's commodity converters. Airless pump assembly is expanding most steeply among certified cleanroom facilities.
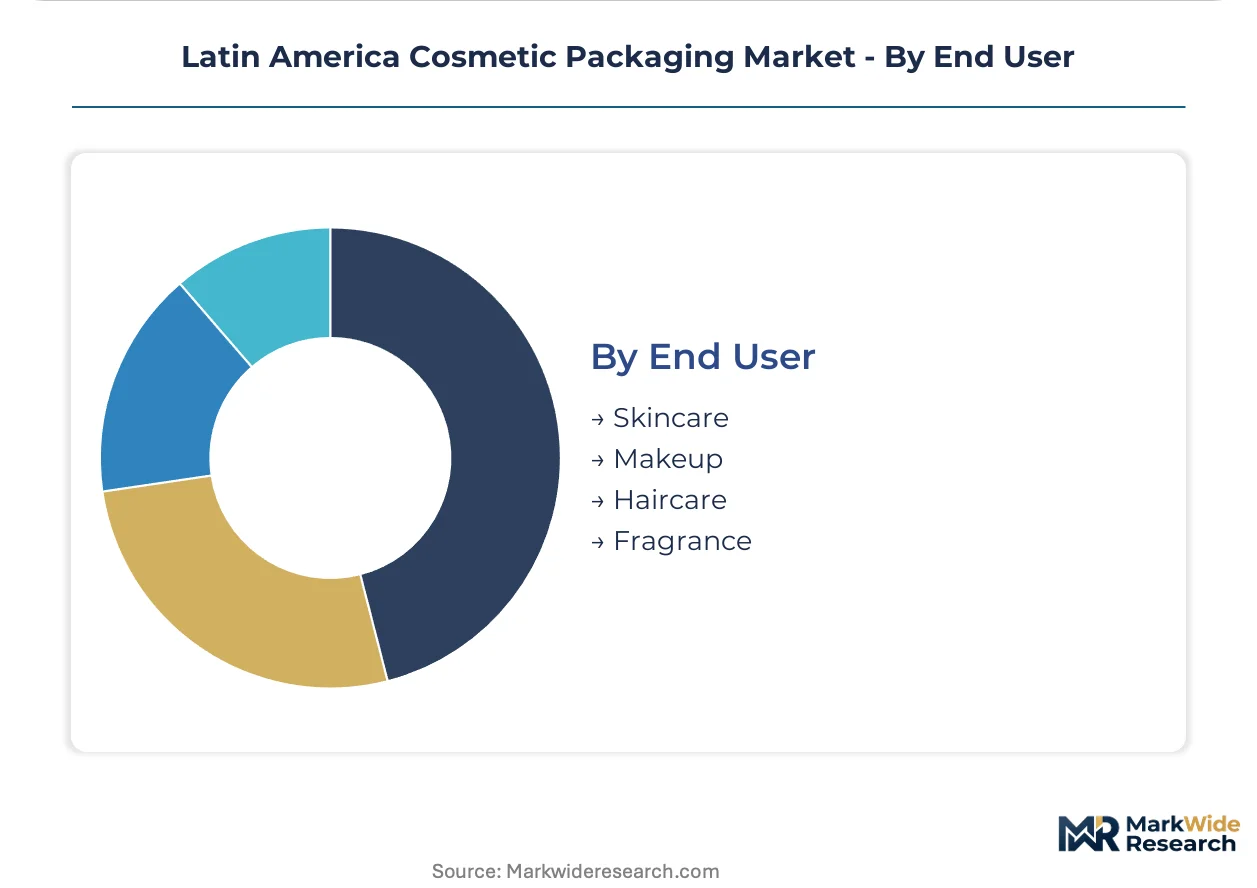
End User:
Formulation complexity and price positioning determine packaging performance specifications across cosmetic categories.
- Skincare:Facial treatments, serums, and creams demand barrier protection and precise dispensing to preserve active ingredient integrity. Brazilian brands in São Paulo state drive airless pump adoption with ANVISA-certified local converters. Skincare absorbs the most specialized packaging investment. Makeup is expanding most quickly in airless and precision-dose formats.
- Makeup:Liquid foundations, concealers, and lip products require compatibility with pigments and solvents while enabling controlled application. Mexican brands specify these with PROFECO-compliant labeling surfaces.
- Haircare:Shampoos, conditioners, and styling products tolerate standardized bottles and tubes with screw or flip-top closures. Volume scale supports commodity procurement from regional converters.
- Fragrance:Prestige and mass-market scents demand glass bottle integrity with decorated aluminum or zamac closures. Guadalajara-area fragrance houses balance PROFECO dimensional constraints with premium aesthetic requirements.
Haircare packaging flows through the highest volume throughput. Skincare specification intensity is climbing the fastest as active ingredient complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's industrial corridor anchors Latin American cosmetic packaging demand through dense clustering of formulation laboratories and converter facilities. Brazilian skincare houses drive specification intensity for airless pump systems and ANVISA-certified polymer grades. Mexican fragrance operations near Guadalajara balance PROFECO compliance mandates with premium aesthetic requirements.
Brazil
ANVISA residue testing protocols for polymer-based primary containers elevate procurement toward certified local converters with in-house laboratory validation. São Paulo state absorbs the densest concentration of airless pump assembly capacity, where skincare brands specify cleanroom-manufactured dispensing systems. Formulation labs in Osasco and Barueri compress development cycles through proximity to regional packaging converters.
Mexico
PROFECO net-content labeling accuracy enforcement shapes primary container dimensioning and secondary pack configuration for fragrance and skincare exports. Jalisco-based fragrance houses near Guadalajara specify reduced-height bottle designs that preserve volume while expanding label surface area. The Bajío Region's emerging converter investments target underpenetrated Andean supply chains currently served through Miami intermediaries.
Colombia
Andean skincare brands currently import secondary packaging from Miami converters, creating captive demand for regional production capacity. Bogotá-based distributors face extended lead times for airless pump components lacking local assembly infrastructure. Medellín's industrial zone attracts preliminary converter interest targeting Andean cosmetic brand procurement consolidation.
Argentina
Macroeconomic volatility compresses packaging procurement cycles toward shorter-term contracting with regional trading partners. Buenos Aires-based cosmetic houses prioritize ANVISA-compatible polymer grades to maintain cross-border supply flexibility with Brazilian converters. The Greater Buenos Aires industrial belt retains specialized decoration capabilities for prestige fragrance secondary packaging.
Chile
Santiago's cosmetic distribution hub serves as a consolidation point for Pacific-facing brand operations requiring ANVISA and PROFECO dual compliance. Local converters specialize in secondary folding cartons with moisture-resistant coatings for skincare export packaging. The Valparaíso port corridor facilitates component importation for brands lacking direct Brazilian or Mexican supplier relationships.
Latin America Cosmetic Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized dispensing technology and decoration capabilities. The market structure reflects moderate consolidation around converters with multi-country certification portfolios and cleanroom assembly infrastructure. Three archetypes dominate: integrated multinationals with regional manufacturing footprints, mid-scale specialists in precision pump mechanisms, and decoration-focused converters serving premium skincare lines. Competitive positioning depends on backward integration into polymer processing and geographic expansion through direct technical service agreements.
Among the integrated multinational tier, Albéa Group and Aptar Group occupy positions exemplifying turnkey dispensing solutions and precision pump technology respectively. HCP Packaging Co., Ltd. represents the decoration-specialist archetype, anchoring competitive positioning through surface graphics capabilities that differentiate premium cosmetic lines. These three entities collectively illustrate the supplier consolidation trajectory as brand owners migrate from fragmented regional sourcing toward single-source accountability for multi-country portfolios.
| Leading Market Players |
|---|
| Albéa Group |
| Aptar Group |
| HCP Packaging Co., Ltd. |
| Silgan Holdings Inc. |
| Amcor PLC |
| Berry Global |
| Gerresheimer AG |
| DS Smith PLC |
| Sonoco Products Company |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap converters across São Paulo state anchor regional supply discipline, translating backward integration into polymer processing into pricing power over skincare brands seeking ANVISA-certified airless pump assemblies. Their captive resin compounding capabilities compress cost pass-through volatility while enabling margin defense against aluminum closure commodity swings.
Pricing Analysis
Aluminum input cost pass-through dominates pricing volatility for premium glass jar lid assemblies, with São Paulo converters indexing quarterly adjustments to LME spot movements. Pricing stratifies across ANVISA-certified cleanroom grades, standard polymer bottles, and commodity screw caps, with certification tier commanding the widest spreads. Cost compression in standard closures is intensifying because Brazilian mass-market haircare brands consolidate volume procurement around fewer suppliers. Mass-market haircare packaging buyers exhibit highest price sensitivity, while prestige skincare houses in São Paulo state absorb premiums for validated migration documentation.
Supply Chain Analysis
Specialty polymer resin supply rests on petrochemical complexes in Brazil, Mexico, and imported grades from US Gulf Coast producers. Airless pump mechanism components draw from precision molding operations in São Paulo state, while aluminum closure stampings feed from Mexican and Argentine metalworking clusters. Single-source vulnerability concentrates in certified cleanroom assembly capacity for ANVISA-compliant pump systems. Distribution runs through direct technical service agreements between São Paulo converters and skincare brand formulation labs, bypassing Miami-based trading intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American cosmetic packaging operates as a regulatory compounder, with ANVISA migration study documentation timelines and PROFECO net-content enforcement together elevating compliance costs that filter through to certified converter premiums.
For Market Incumbents: Hedge aluminum price exposure through long-term offtake agreements with Mexican metal suppliers rather than spot market exposure. Deepen cleanroom technician training pipelines in Brazilian interior states to preempt capability scarcity threatening airless pump assembly expansion. Consolidate supplier qualification relationships around single-source accountability for multi-country brand portfolios to capture procurement concentration tailwinds. For New Entrants and Emerging Players: Launch via direct technical service agreements with Andean skincare brands currently importing secondary packaging from Miami converters. Target Colombian airless pump component demand where Bogotá distributors face extended lead times lacking local assembly infrastructure. Prioritize PROFECO-compliant label surface optimization as entry wedge against established Mexican fragrance converters. For Investors and Strategic Acquirers: Valuations sit cheapest among decoration-focused mid-caps with specialized finishing capabilities serving premium skincare lines across Brazilian and Mexican markets. Long-term viability over the coming decade hinges on mono-material pump system positioning ahead of pending Mercosur extended producer responsibility mandates. Watch ANVISA certification timeline compression as signal for converter capacity utilization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | São Paulo converters capture margin pools from resin formulation through captive ANVISA-grade production. |
| Cleanroom Capacity Expansion | Certified airless pump assembly infrastructure addresses technician scarcity threatening Brazilian skincare brand procurement. |
| PROFECO Compliance Design Services | Dimensional recalibration expertise preserves volume while expanding label surface area for Jalisco fragrance houses. |
| Andean Distribution Partnership | Bogotá technical service agreements displace Miami intermediaries for Colombian skincare packaging demand. |
| Mono-Material Pump Development | Single-resin airless systems align with pending Mercosur reverse logistics obligations for recycling pathway simplification. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging procurement managers at São Paulo skincare houses, cleanroom operations directors at Brazilian converters, Mexican fragrance brand supply chain leads, and Andean distributor principals with secondary validation. Trade flow data from Brazilian customs authorities, ANVISA certification registries, PROFECO enforcement disclosures, and polymer processor capacity filings anchored bottom-up volume estimates against top-down market sizing.
Segment-weighting across product type, material substrate, closure mechanism, and end-use category shaped analytical framework construction throughout the projection horizon. CAGRs derived from installed capacity expansion schedules, brand launch pipelines, and regulatory compliance cost trajectories across the modeling period. Airless pump adoption curves and ANVISA certification queue lengths served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended ANVISA documentation delays or abrupt PROFECO dimensional mandate changes. Forecasts reflect documented assumptions regarding cleanroom technician training output and aluminum price trajectory stability. Regulatory acceleration in Mercosur extended producer responsibility implementation and Colombian converter investment commitments warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market
Cosmetic Packaging
Europe Cosmetic Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Latin America Personal Care Packaging Market
Cosmetic Packaging
Plastic Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Europe Plastic Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Bottles Packaging Market
Cosmetic Packaging
Cosmetic and Toiletry Containers Market
Cosmetic Packaging
Skin Care Packaging Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Make-Up Products Packaging Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
Crimp Neck Serum Bottles Market