
 Beauty and Personal Care Packaging Market | 2026-2036
Beauty and Personal Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Beauty and Personal Care Packaging Market Analysis
Clean beauty and masstige consumers is bifurcating the demand base that legacy brands once monopolized. Amcor Plc leverages its global film and laminate portfolio to serve both premium and value tiers simultaneously. AptarGroup Inc. differentiates through dispensing technology leadership in airless pumps and precision droppers. Quadpack Industries specializes in wood-based and recycled plastic solutions that align with indie brand sustainability narratives.
Beauty and personal care packaging encompasses primary and secondary containment systems engineered from plastics, glass, metals, and paper substrates to protect, dispense, and merchandise cosmetic formulations with specified barrier properties against oxygen, UV, and moisture ingress. The category serves industrial purposes spanning shelf-life extension, dosage control, brand differentiation, and regulatory compliance for consumer chemical safety. Plastic bottles retain volume leadership across skincare and haircare applications due to cost efficiency and design flexibility, though glass jars command premium positioning in facial creams and serums where perceived quality and chemical inertness justify higher unit economics. Pouches are gaining fastest in travel-size and refill segments as brands reduce material intensity and logistics costs.
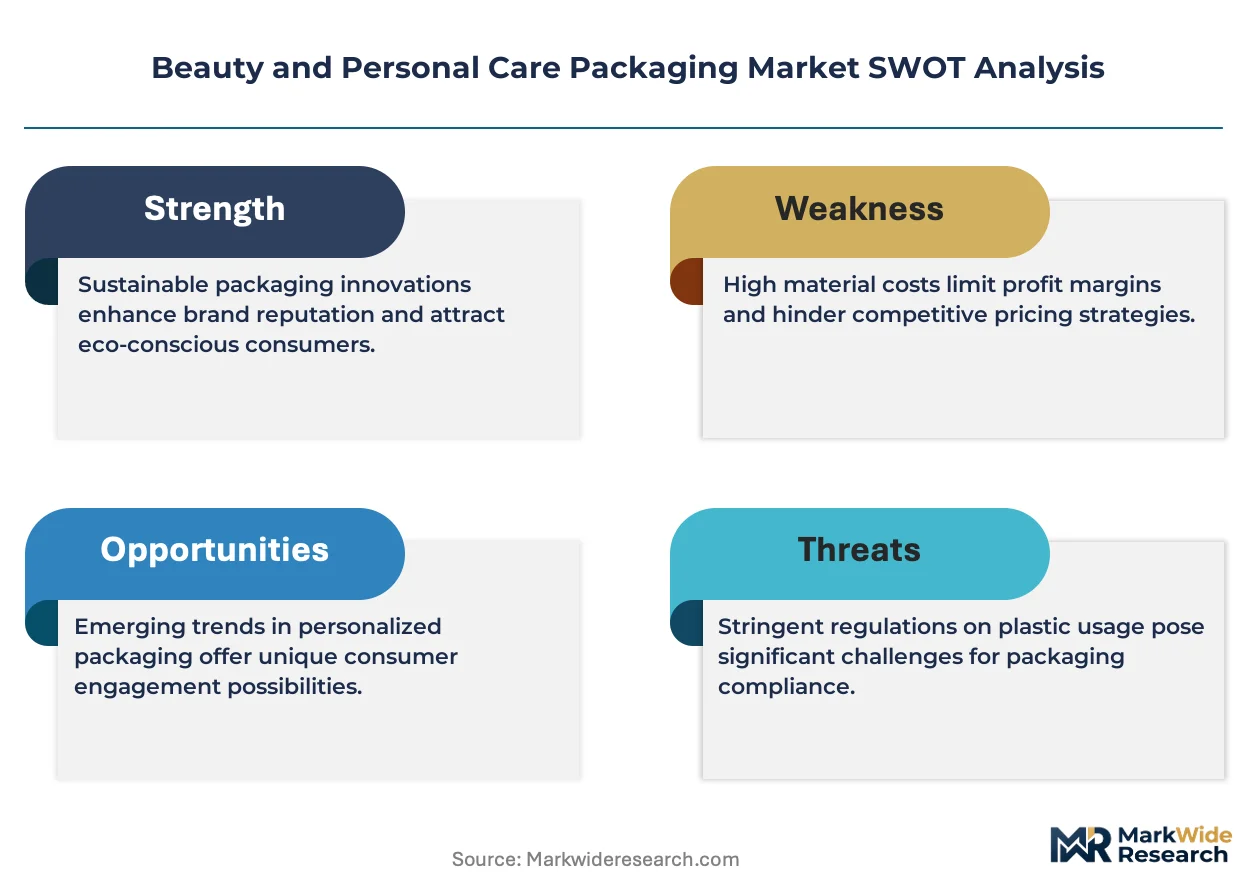
The EU Packaging and Packaging Waste Regulation and REACH chemical compliance frameworks are mandating recyclability thresholds and restricted substance lists that reshape material selection across European supply chains. FDA cosmetic labeling requirements and state-level extended producer responsibility laws in California and New York impose parallel compliance burdens on products entering US distribution channels. Stakeholders must monitor evolving polymer traceability standards and bio-based content verification protocols to maintain market access and avoid reformulation delays.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material redesign across the value chain as brands face mandatory recyclability thresholds and extended producer responsibility obligations that compress formulation-to-shelf timelines.
Growth Catalysts
- Refillable format mandates:Retailers in Germany, France, and the United Kingdom are requiring brands to offer refill stations, driving demand for mono-material pumps and standardized neck finishes.
- REACH chemical compliance:Restricted substance lists under ECHA frameworks are accelerating substitution of polycarbonate and certain phthalates in cosmetic containers.
- Airless dispensing technology:Premium skincare brands are adopting piston-based and bag-in-bottle systems to extend shelf life without preservatives.
Market Restraints
- Post-consumer resin quality inconsistency:rPET and rPP feedstock from European mechanical recyclers exhibits batch-to-batch color and odor variation that complicates brand color-matching requirements.
- Aluminum supply concentration:Primary aluminum for cosmetic tubes and aerosols concentrates in smelter networks outside the EU, exposing converters to carbon border adjustment mechanism cost pass-through.
- Glass weight penalty:Transport costs for glass jars and bottles scale nonlinearly with distance, limiting viable sourcing radius for brands targeting carbon-neutral logistics claims.
Strategic Opportunities
- Indie brand ecosystem in France:Marseille and Paris-based clean beauty startups lack in-house packaging engineering, creating white space for turnkey sustainable packaging-as-a-service models.
- Digital watermarking integration:Combining invisible marker technologies with existing injection molding lines enables automated sortation compliance under emerging EU digital product passport requirements.
- Pharmacy channel expansion:Dermocosmetic brands are bypassing traditional prestige retail to access pharmacist recommendation networks in Italy and Spain.
Industry Challenges
- Polymer traceability certification:Mass balance accounting for bio-based and chemically recycled content requires third-party verification that extends procurement cycles by four to eight weeks.
- Decorative printing requalification:Switching from solvent-based to UV-curable or water-based inks on existing offset and screen lines demands color stability testing that delays seasonal launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beauty and Personal Care Packaging Market |
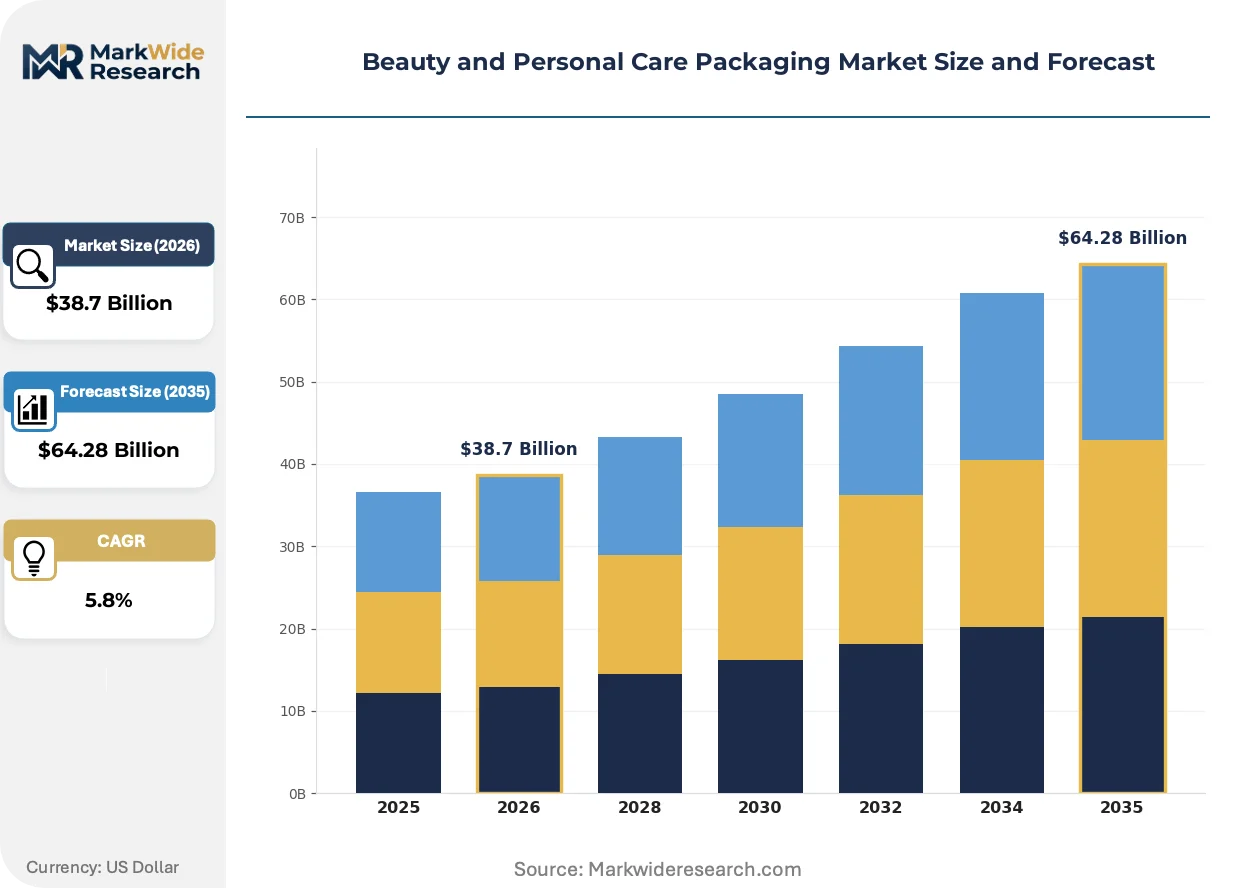
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Jars, Tubes, Pouches Material: Plastic, Glass, Metal, Paper Closure Type: Screw Tops, Pumps, Flip Tops, Droppers End User: Cosmetics, Skincare, Fragrances, Haircare |
| Companies Covered | Amcor Plc, Albea S.A., AptarGroup Inc., Gerresheimer AG, Berry Global Group Inc., Silgan Holdings Inc., Mondi Group, Ball Corporation, Quadpack Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beauty and Personal Care Packaging Market Emerging Trajectories
Material science breakthroughs and regulatory digitization are compressing traditional packaging development cycles while enabling new functional claims that previously required formulation changes.
Mono-material flexible pouches with integrated dispensing fitments are miniaturizing travel-size and sample formats previously dominated by rigid bottles. Masstige haircare brands in the United Kingdom are adopting these structures for conditioner and mask refills. The technology is miniaturizing unit economics to parity with conventional tubes while eliminating multi-component separation requirements at end-of-life.
REACH Annex XVII restrictions on microplastics in rinse-off cosmetics are compelling brands to reformulate exfoliants and shift toward cellulose-based or mineral alternatives. The industrial consequence extends to primary packaging as brands remove glitter and plastic-based decorative elements from labels and closures. Facial cleansers and body scrubs targeting German and French consumers are most affected, with suppliers accelerating paper-based labelstock qualification.
Direct-to-consumer subscription models are fragmenting order profiles from pallet-scale shipments to individual parcel fulfillment. Indie skincare brands operating through proprietary websites and specialized platforms are bypassing traditional wholesaler networks. This pattern concentrates in the United States and United Kingdom where last-mile logistics infrastructure supports cold-chain and fragile-goods handling at unit scale.
Beauty and Personal Care Packaging Market Segmentation
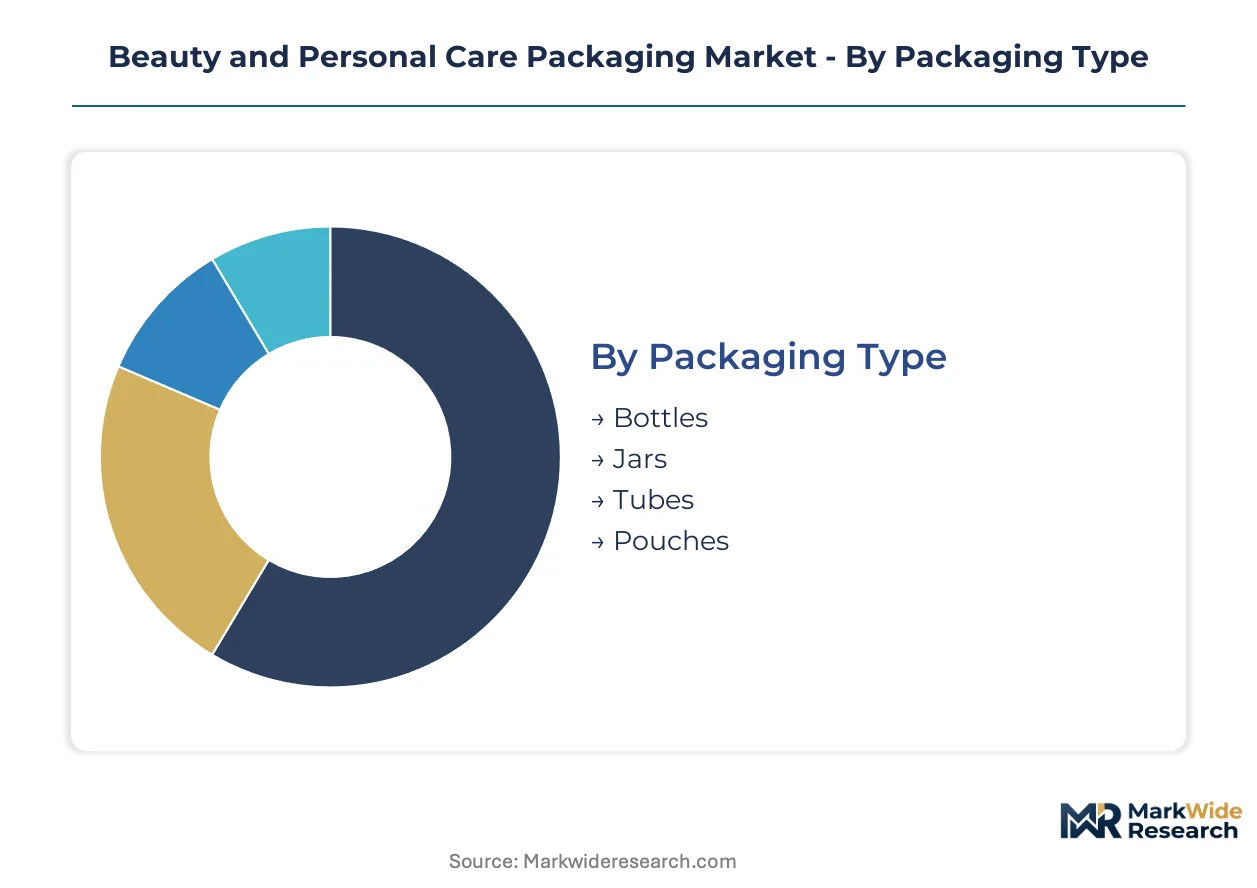
Packaging segmentation in beauty and personal care determines both compliance pathways and margin capture. Material and format choices increasingly lock brands into specific recycling infrastructure and extended producer responsibility obligations across European markets.
Packaging Type:
Margin pools concentrate in formats that balance unit economics with sustainability credentials and regulatory alignment.
- Bottles:HDPE and PET structures dominate shampoo and body wash applications. German retailers are mandating standardized neck finishes to enable refill station compatibility, compressing design flexibility for brands. Bottles hold installed capacity. Pouches is rotating up the share rankings.
- Jars:Thick-walled glass and polypropylene containers serve facial creams and masks where premium perception justifies higher unit costs. French dermocosmetic brands favor wide-mouth formats for spatula access and hygiene claims.
- Tubes:Laminate and mono-material extrusions target toothpaste-scale consumption in hair masks and sun care. Collapsible aluminum structures face carbon border adjustment exposure on primary metal sourcing.
- Pouches:Spouted and fitment-integrated flexible formats are displacing rigid miniatures in travel and sample segments. United Kingdom masstige haircare brands are adopting these for conditioner refills to cut material intensity.
Bottles retain volume leadership. Pouches is climbing the fastest on sustainability metrics.
Material:
Cost tiers separate commodity feedstocks from certified circular and bio-based alternatives with traceability premiums.
- Plastic:Virgin and mechanically recycled polymers remain cost-dominant across all format categories. ECHA restricted substance lists are accelerating substitution away from polycarbonate and certain phthalates in cosmetic containers.
- Glass:Borosilicate and soda-lime compositions command facial serum and fragrance applications where chemical inertness and perceived quality offset weight penalties. Transport costs scale nonlinearly with distance, constraining sourcing radius for carbon-neutral logistics claims.
- Metal:Aluminum tubes and aerosols concentrate primary smelting outside the EU, exposing converters to carbon border adjustment mechanism pass-through. Aerosol propellant regulations under F-Gas are adding compliance layers.
- Paper:Molded fiber and cartonboard formats are penetrating secondary packaging and primary containers for dry powders. REACH Annex XVII microplastic restrictions are accelerating paper-based labelstock qualification for rinse-off cosmetics.
Plastic holds installed capacity. Paper is rotating up the share rankings.
Closure Type:
Customer type stratification separates mass-market commodity closures from precision dispensing systems with formulation protection claims.
- Screw Tops:Standard threaded closures dominate value-tier skincare and haircare where cost minimization overrides dispensing sophistication. Batch-to-batch color consistency in post-consumer resin complicates brand matching requirements.
- Pumps:Piston-based airless systems extend shelf life without preservatives in premium skincare. Mono-material pump bodies are emerging to meet EU recyclability thresholds under Packaging and Packaging Waste Regulation mandates.
- Flip Tops:Hinged polypropylene closures serve shampoo and body wash convenience positioning. Travel-size format proliferation is driving miniaturization of hinge fatigue specifications.
- Droppers:Bulb and push-button precision dispensers target facial serums and active ingredient formulations. Glass pipette and bulb combinations face end-of-life separation challenges in mechanical recycling streams.
Pumps hold installed capacity. Droppers is rotating up the share rankings.
End User:
Application maturity determines whether segments compete on formulation innovation or packaging-led differentiation.
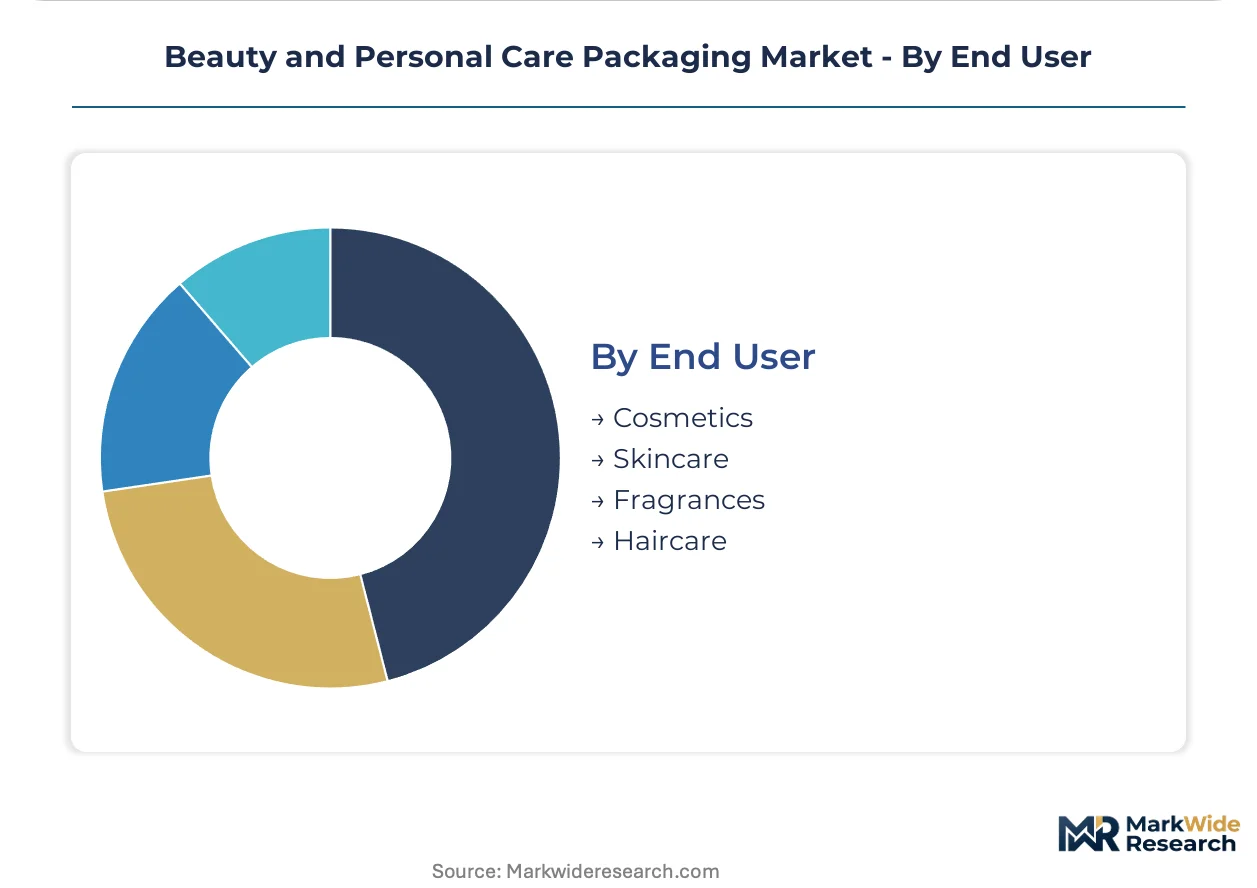
- Cosmetics:Color cosmetics and decorative products demand high-definition decoration and applicator integration. REACH microplastic restrictions are removing glitter and plastic decorative elements from primary packaging and labels.
- Skincare:Facial creams, serums, and treatments drive airless dispensing adoption and mono-material format redesign. Clean beauty startups in Marseille and Paris lack in-house packaging engineering, creating white space for turnkey sustainable packaging-as-a-service models.
- Fragrances:Premium positioning sustains heavy glass bottle economics despite logistics penalties. Direct-to-consumer subscription fragmentation is challenging traditional wholesaler distribution economics.
- Haircare:Shampoo and conditioner volumes sustain bottle and pouch format competition. Refill station mandates in German, French, and United Kingdom retail are standardizing neck finishes across masstige brands.
Skincare holds installed capacity. Haircare is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered dispensing components to French and UK beauty brands seeking refill-compatible packaging systems that comply with tightening EU sustainability mandates.
Germany
Refill station mandates at dm-drogerie markt and Douglas are standardizing neck finishes across masstige haircare brands. The national packaging regulator enforces extended producer responsibility obligations that compress supplier qualification timelines. Berlin-Brandenburg hosts converter clusters specializing in mono-material pump engineering for indie skincare labels.
France
Dermocosmetic brands leverage pharmacist recommendation networks in Marseille and Paris to bypass traditional prestige retail channels. ANSM oversees cosmetic container safety assessments that delay seasonal launches for non-compliant decorative elements. The Île-de-France corridor concentrates clean beauty startups lacking in-house packaging engineering capabilities.
United Kingdom
Masstige haircare brands adopt spouted pouches for conditioner refills to reduce material intensity against supermarket private-label competition. The Environment Agency implements packaging waste recovery targets that favor lightweight flexible formats over rigid alternatives. Greater Manchester hosts flexible packaging converters serving direct-to-consumer subscription brands.
United States
Indie skincare brands fragment order profiles through proprietary e-commerce platforms requiring unit-scale fulfillment infrastructure. FDA cosmetic labeling requirements and California SB 54 extended producer responsibility laws impose parallel compliance burdens on imported containers. New Jersey and Ohio host injection molding capacity serving fragrance and color cosmetics applications.
Italy
Pharmacy channel expansion for dermocosmetic brands concentrates demand in Milan and Rome metropolitan areas. The Ministry of Health enforces REACH-aligned restrictions on microplastic-containing rinse-off products that eliminate glitter from decorative packaging. Lombardy-based converters specialize in airless dispensing systems for premium facial serum applications.
Beauty and Personal Care Packaging Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and sustainability certification dimensions. The supplier base consolidates around three tiers: diversified materials conglomerates with global film portfolios, precision dispensing technology specialists, and regional sustainability-focused converters serving indie brand ecosystems. Strategic moves center on mono-material format R&D partnerships and mechanical recycling feedstock offtake agreements to secure post-consumer resin supply.
Among diversified packaging conglomerates, Amcor Plc and Berry Global Group Inc. represent scale-driven archetypes with integrated polymer supply chains spanning multiple substrate categories. AptarGroup Inc. occupies the precision dispensing tier, exemplifying technology leadership in airless pump engineering that extends formulation shelf life. Quadpack Industries sits within the sustainability-specialist segment, anchoring wood-based and recycled plastic solutions aligned with clean beauty brand narratives. These three archetypes capture distinct margin pools across premium standardization, functional performance, and environmental credentialing vectors.
| Leading Market Players |
|---|
| Amcor Plc |
| Albea S.A. |
| AptarGroup Inc. |
| Gerresheimer AG |
| Berry Global Group Inc. |
| Silgan Holdings Inc. |
| Mondi Group |
| Ball Corporation |
| Quadpack Industries |
| Others |
Supply Flow & Price Mechanics
EU Packaging and Packaging Waste Regulation recyclability thresholds gate supplier qualification and price differentiation simultaneously, forcing converters to absorb certification costs while brands tier offerings by sustainability credential tier. Mono-material format premiums compress as mechanical recycling feedstock scales, yet carbon border adjustment exposure on aluminum and virgin polymer volatility sustain cost dispersion across material categories.
Pricing Analysis
Next-generation mono-material pump systems command 15-25% premiums over legacy multi-component dispensers, while prior-generation polycarbonate containers face price erosion under ECHA restricted substance mandates. Pricing stratifies across premium airless systems, standard screw-cap bottles, and economy-tier flexible pouches. Cost compression in mid-tier formats intensifies as German retailers standardize neck finishes for refill station compatibility. Masstige haircare brands exhibit highest price sensitivity; premium dermocosmetic labels show lowest, prioritizing shelf-life extension claims.
Supply Chain Analysis
Inventory lead times for post-consumer resin feedstock extend procurement cycles by four to eight weeks as mass balance certification requirements compound. Supply concentrates in Germany for precision pump engineering, France for glass cosmetic containers, and China for primary aluminum extrusions. Raw material dependencies center on rPET flake, borosilicate glass cullet, and cosmetic-grade polypropylene. Single-source vulnerability concentrates in EU-external aluminum smelting networks. Distribution runs through converter-direct brand relationships for premium tiers, with pooled distribution serving masstige retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refill station infrastructure is creating platform-economics dynamics in European beauty retail, with standardized neck finishes and mono-material interoperability becoming the governing protocol layer for packaging procurement.
For Market Incumbents: Consolidate mechanical recycling feedstock offtake agreements in Germany and France to defend resin supply security against emerging converter competition. Deepen backward integration into post-consumer resin washing and pelletizing to capture margin pools threatened by quality inconsistency in third-party rPET supply. Prioritize digital watermarking R&D partnerships to pre-position for EU digital product passport mandates. For New Entrants and Emerging Players: Anchor in Marseille and Paris clean beauty startup ecosystems where packaging-as-a-service white space persists due to in-house engineering gaps. Target indie skincare brands seeking turnkey sustainable format development with subscription-model fulfillment integration. Pursue pharmacy channel bypass strategies for dermocosmetic labels in Italy and Spain. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mono-material format R&D and mechanical recycling infrastructure deployment. Acquisition focus should center on mid-cap converters with certified circular content capabilities and established brand relationships in German refill retail networks. Monitor carbon border adjustment mechanism implementation timelines as inflection signal for aluminum-dependent tube and aerosol exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Format R&D Partnership | Enables EU Packaging and Packaging Waste Regulation compliance while securing premium positioning with refill-mandated retailers. |
| Post-Consumer Resin Feedstock Agreement | Locks supply security against batch-to-batch quality variation that complicates brand color-matching requirements. |
| Digital Watermarking Integration | Positions converters for automated sortation compliance under emerging EU digital product passport frameworks. |
| Pharmacy Channel Distribution Partnership | Accesses pharmacist recommendation networks in Italy and Spain that bypass traditional prestige retail economics. |
| Direct-to-Consumer Fulfillment Infrastructure | Captures order profile fragmentation from indie brands operating through proprietary e-commerce platforms. |
Methodological Framework
Operator-level perspectives from packaging procurement managers at masstige and premium beauty brands, converter engineering directors, and retailer sustainability compliance officers anchored the qualitative base. Secondary validation drew from ECHA restricted substance filings, EU Packaging and Packaging Waste Regulation implementation guidance, and customs trade data for polymer and aluminum feedstock flows. Bottom-up segment sizing triangulated against top-down market envelope checks across material, format, and end-use dimensions.
Sensitivity analysis tested forecast robustness against carbon border adjustment pass-through scenarios and mechanical recycling feedstock availability constraints. The analytical framework modeled volume and value trajectories across packaging type, material substrate, closure system, and end-use application through the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic demand drivers and regulatory implementation timelines. Industry-specific inputs included refill station rollout schedules in Germany, France, and the United Kingdom, plus REACH Annex XVII microplastic restriction compliance patterns.
Material uncertainties — regulatory implementation delays, post-consumer resin quality degradation, and carbon border adjustment rate finalization — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding standardization timelines and retailer mandate enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Middle East and Africa Personal Care Packaging Market
Cosmetic Packaging
Plastic Cosmetic Packaging Market
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Eyeliner and Kajal Sculpting Pencil Packaging Market
Cosmetic Packaging
Latin America Cosmetic Packaging Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
Europe Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
Asia Pacific Cosmetic Packaging Market
Cosmetic Packaging
Lip Care Packaging Market
Cosmetic Packaging
Global Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic and Toiletry Containers Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Anti-Counterfeit Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Pump Bottle Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market