
 Lip Gloss Tube Market | 2026-2036
Lip Gloss Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Lip Gloss Tube Market Foresight
ISO 22716 Good Manufacturing Practices certification for cosmetic packaging is collapsing the supplier base as smaller molders exit. Albéa Group leverages integrated blow-fill-seal capabilities across European plants to sustain volume leadership in sustainable tube formats. HCP Packaging anchors Asia-Pacific supply through dedicated cosmetic packaging facilities in China and South Korea. AptarGroup differentiates via precision dispensing applicator technology that commands premium positioning among luxury beauty houses.
Lip gloss tubes are cylindrical or oval polymer containers, typically manufactured from polyethylene or polypropylene via extrusion blow molding, designed to store and dispense viscous lip color formulations through integrated wiper and applicator systems. Water-based formulations are gaining share as clean beauty brands reformulate away from petrochemical solvents, while oil-based tubes retain dominance in long-wear and conditioning product lines. Tube packaging controls the largest value pool due to portability and dosage precision, though wand formats are accelerating in prestige segments where applicator innovation drives repurchase rates.
FDA cosmetic labeling requirements and the EU Packaging and Packaging Waste Regulation (PPWR) are tightening material traceability and recyclability thresholds for all cosmetic primary packaging sold in the United States and European Union. REACH compliance on chemical additives in colorants and ECHA restrictions on microplastics in rinse-off cosmetics are redirecting R&D spending toward bio-based polymers and certified compostable tube structures. Stakeholders must monitor evolving extended producer responsibility schemes in California and France, as these jurisdictions are likely to set de facto North American and European standards for post-consumer tube collection and recycling infrastructure investment.
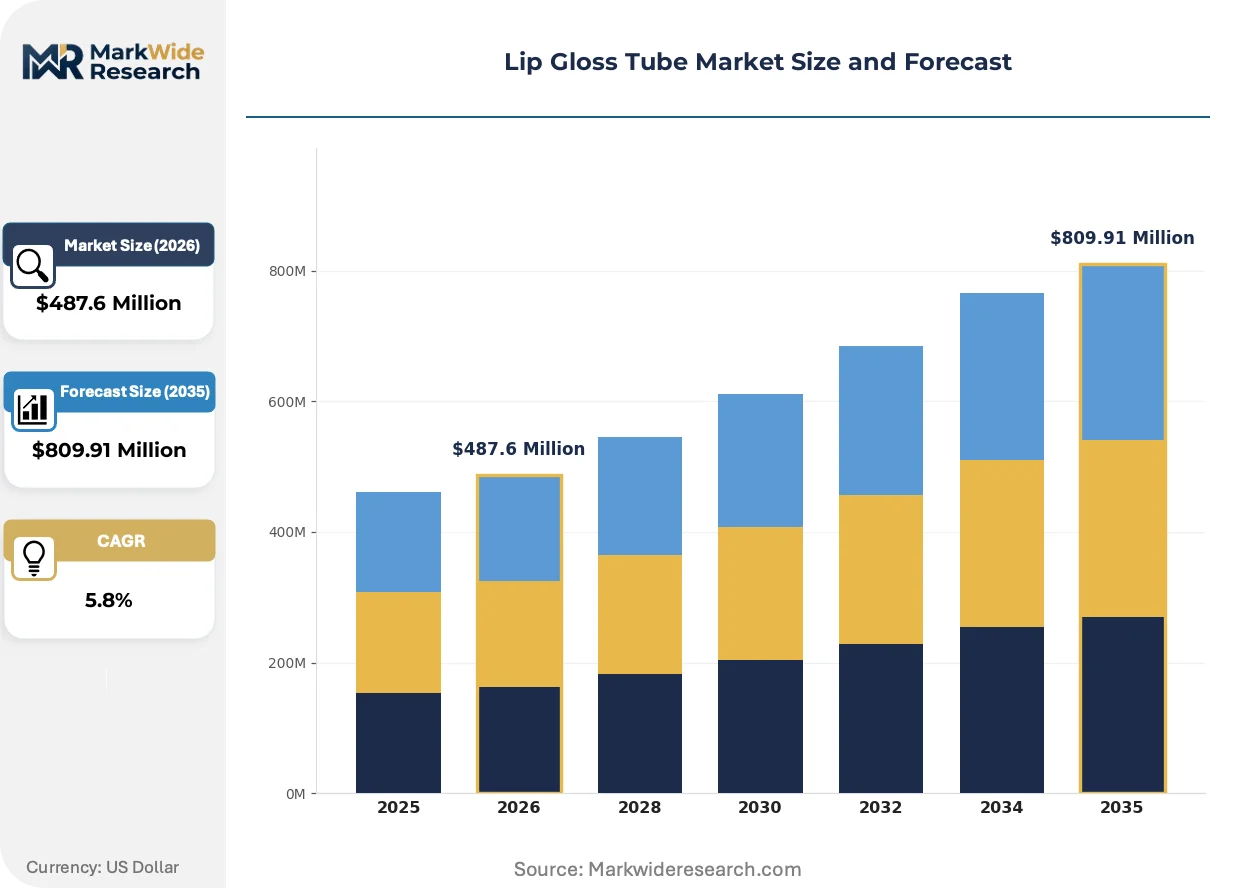
Market Dynamics
Sustainable packaging mandates across the European Union and North America are collapsing the supplier base for cosmetic primary packaging, as ISO 22716 Good Manufacturing Practices certification requirements force smaller molders to exit and concentrate production among integrated manufacturers with captive blow-fill-seal capabilities.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability thresholds for cosmetic tubes are redirecting R&D budgets toward mono-material polyethylene structures, pulling demand toward certified suppliers with established recycling partnerships.
- Water-based formulation chemistry:Clean beauty brands are reformulating away from petrochemical solvents, creating compatible tube specifications that require specialized barrier polymers and integrated wiper systems.
- Germany:Albéa Group and HCP Packaging anchor regional supply chains for recyclable tube formats, concentrating procurement decisions among beauty houses with sustainability commitments.
Market Restraints
- Polypropylene price volatility:Feedstock cost swings compress margins for extrusion blow molders lacking long-term resin contracts or backward integration into polymer production.
- REACH compliance on chemical additives:ECHA restrictions on colorants and microplastics in rinse-off cosmetics extend certification timelines and limit formulation flexibility for tube suppliers.
- Glass and aluminum substitution:Premium brands are testing rigid alternatives for prestige positioning, threatening polymer tube volume in the highest-margin cosmetic segments.
Strategic Opportunities
- Extended producer responsibility schemes:California and France are likely to set de facto standards for post-consumer tube collection, creating first-mover advantage for suppliers with established recycling infrastructure in these jurisdictions.
- Precision dispensing applicator convergence:Integration of micro-pump mechanisms with traditional tube formats opens premium positioning among luxury beauty houses seeking dosage precision.
- Direct-to-consumer channel expansion:E-commerce fulfillment requirements favor lightweight, damage-resistant tube formats over rigid alternatives, reshaping packaging specifications for digital-native cosmetic brands.
Industry Challenges
- ISO 22716 certification timeline:Smaller molders face 12-18 month compliance windows that strain working capital and technical staffing, accelerating consolidation among mid-cap suppliers.
- Legacy injection molding asset repositioning:Converting existing equipment for sustainable tube formats requires capex outlays that exceed internal hurdle rates for family-owned packaging firms.
- Cross-border material traceability:FDA cosmetic labeling requirements and EU PPWR create dual documentation burdens that complicate supply chain management for multinational beauty brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lip Gloss Tube Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glossy, Matte, Metallic, Sparkling Formulation: Water-based, Oil-based, Gel-based, Cream-based Packaging Type: Tube, Jar, Wand, Palette End User: Cosmetics Retailers, E-commerce Platforms, Beauty Salons, Direct Sellers |
| Companies Covered | Albéa Group, HCP Packaging, Amcor, AptarGroup, Lumson, World Wide Packaging, Quadpack, Raepak, Yonwoo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lip Gloss Tube Market Shifts & Advancements
Tube-based lip gloss packaging is undergoing material and functional transformation as regulatory pressure intersects with formulation chemistry shifts and direct-to-consumer distribution growth. Three developments are restructuring competitive positioning.
Mono-material polyethylene tube construction is fragmenting the supplier landscape by eliminating multi-layer barrier structures that previously required specialized coextrusion equipment. Clean beauty brands with sustainability commitments are specifying these formats for water-based formulations. The technology compresses margins for molders lacking integrated recycling partnerships or certified compostable polymer sourcing.
REACH restrictions on microplastics in rinse-off cosmetics are forcing reformulation of long-wear lip gloss products that historically relied on synthetic film-formers. ECHA enforcement timelines are compressing product development cycles for brands with significant European revenue exposure. Oil-based tube specifications retain dominance in conditioning segments, but water-compatible barrier polymers are capturing share in mass-market lines.
Beauty buyers are consolidating procurement decisions among suppliers with integrated blow-fill-seal capabilities and documented recycling infrastructure. Direct-to-consumer fulfillment requirements favor lightweight tube formats that withstand single-unit shipping stress. Germany and California represent the geographies where sustainability certification and extended producer responsibility schemes are most advanced, concentrating vendor selection criteria in these markets.
Lip Gloss Tube Market Segmentation
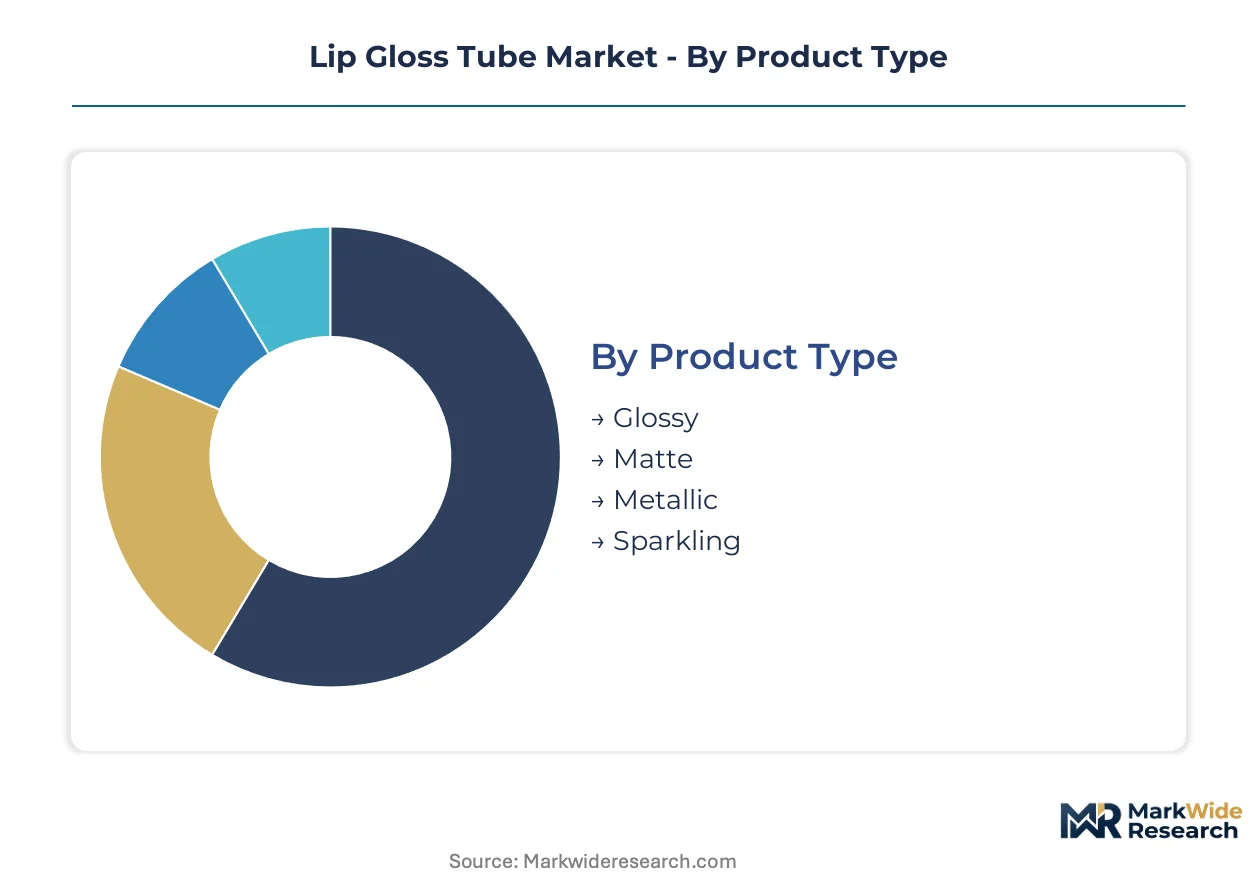
Lip gloss tube procurement diverges sharply across formulation chemistry and distribution channel, with clean beauty specifications and e-commerce fulfillment requirements rewriting supplier qualification criteria. Understanding segment boundaries reveals where mono-material tube investments concentrate versus where legacy formats retain pricing power.
Product Type:
Glossy and matte finishes dominate domestic production in Germany and France, while metallic and sparkling variants flow primarily through export-oriented facilities serving prestige beauty houses in the United States and Gulf states.
- Glossy:High-shine formulations require specialized wiper mechanisms to control viscosity flow and prevent leakage during temperature fluctuations. Demand clusters among mass-market retailers in Germany seeking recyclable mono-material compatibility.
- Matte:Drying agents in matte chemistry demand enhanced oxygen barrier properties in tube construction, pushing specification toward multi-layer structures that face recyclability scrutiny under EU PPWR. French beauty brands with sustainability commitments are driving specification shifts here.
- Metallic:Mica and metallic pigment suspensions require compatible polymer substrates to prevent separation; export-led demand from UAE luxury retailers.
- Sparkling:Glitter particle size distribution dictates applicator aperture engineering; constrained by ECHA microplastic restrictions in rinse-off applications.
Matte holds the largest share; momentum sits with Glossy as clean beauty brands reformulate toward water-based shine formulations.
Formulation:
Cost tier stratification separates commodity oil-based tubes from premium water-compatible barrier structures, with gel and cream formats occupying intermediate positioning based on viscosity engineering complexity.
- Water-based:Clean beauty specifications are eliminating petrochemical solvents, requiring specialized ethylene vinyl alcohol barrier layers or bio-based alternatives. German Albéa facilities and South Korean HCP plants are capturing volume as brands with European revenue exposure accelerate reformulation timelines.
- Oil-based:Long-wear and conditioning segments retain polymer tube dominance due to compatible rheology with standard polyethylene; California direct-to-consumer brands favor lightweight formats here.
- Gel-based:Intermediate viscosity demands precise wiper calibration; beauty salons in France specify professional-size tubes.
- Cream-based:Higher pigment loads require reinforced tube walls; e-commerce platforms prioritize damage-resistant specifications.
Oil-based retains volume leadership; water-based climbs the fastest as REACH enforcement compresses development cycles.
Packaging Type:
Tube and wand formats split along customer type lines, with palette and jar structures concentrated in professional channels where dosage precision matters less than visual merchandising.
- Tube:Extrusion blow-molded polyethylene or polypropylene containers with integrated applicators control the largest value pool due to portability and single-unit shipping resilience. E-commerce platforms in California and Germany are consolidating procurement around certified recyclable specifications.
- Wand:Precision dispensing applicators with micro-pump mechanisms command premium positioning among luxury beauty houses; South Korean manufacturing clusters lead technical development.
- Jar:Rigid formats retain niche in professional salon settings where scoop application is standard.
- Palette:Multi-pan configurations serve makeup artists and theatrical suppliers; limited tube substitution risk.
Tube captures the dominant revenue position; wand gains share fastest in prestige segments driven by applicator innovation.
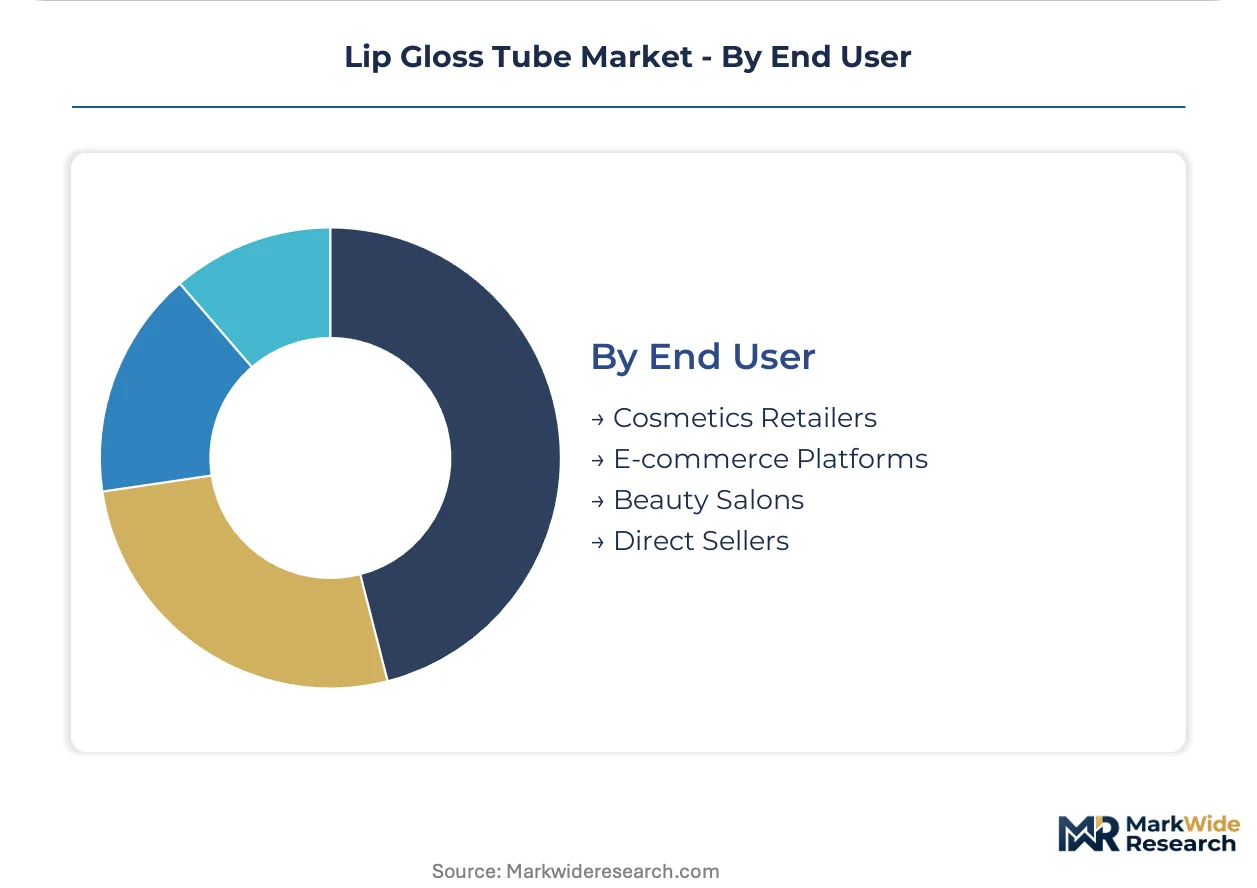
End User:
Volume concentration sits with cosmetics retailers and e-commerce platforms, while beauty salons and direct sellers operate on distinct specification cycles with longer replacement timelines.
- Cosmetics Retailers:Sephora, Douglas, and regional chains drive standardization around mono-material tube formats to meet corporate sustainability commitments. German retailers are advancing fastest on extended producer responsibility compliance.
- E-commerce Platforms:Amazon, Zalando, and direct-to-consumer beauty brands prioritize lightweight, damage-resistant tubes that withstand single-unit fulfillment stress; California regulatory developments on packaging waste are shaping procurement criteria.
- Beauty Salons:Professional channels favor larger-format tubes with bulk dispensing features; slower adoption of sustainable specifications.
- Direct Sellers:Avon and Oriflame networks emphasize portability and sampling compatibility; specifications lag retail channels on recyclability certification.
Cosmetics retailers command the largest procurement volume; e-commerce platforms show the steepest specification evolution as digital-native brands scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility schemes in California and France are establishing de facto procurement standards that ripple through supplier networks. Beauty brands with multinational revenue exposure now route volume through certified facilities in these jurisdictions.
United States
California's packaging waste regulations and Amazon's fulfillment specifications are reshaping tube procurement for direct-to-consumer brands. FDA cosmetic labeling requirements enforce material traceability documentation across all primary packaging. Los Angeles and New York Metro clusters host digital-native beauty brands specifying lightweight, damage-resistant mono-material formats.
Germany
EU Packaging and Packaging Waste Regulation enforcement is collapsing the supplier base as ISO 22716 certification requirements accelerate consolidation. REACH compliance on chemical additives redirects R&D spending toward bio-based polymers. Albéa Group anchors supply chains from facilities in the Rhine-Ruhr and Stuttgart regions.
France
Corporate sustainability commitments from LVMH and L'Oréal are standardizing mono-material tube specifications across prestige portfolios. ECHA microplastic restrictions in rinse-off cosmetics compress product development timelines for long-wear formulations. Paris and Lyon beauty houses concentrate procurement decisions among certified suppliers with documented recycling partnerships.
China
Domestic clean beauty brands are reformulating toward water-based chemistry compatible with specialized barrier polymers. SAMR cosmetic registration requirements and GB standards enforcement tighten material documentation burdens. HCP Packaging operates dedicated facilities in Guangdong and Jiangsu provinces serving both domestic and export demand.
South Korea
K-beauty export growth drives specification evolution for precision dispensing applicators with micro-pump mechanisms. MFDS cosmetic safety standards align with REACH-equivalent chemical restrictions. Seoul Capital Area manufacturing clusters lead technical development for luxury beauty house partnerships.
Lip Gloss Tube Market Competitive Landscape
Listed leaders compete with private specialists across certification capabilities and integrated manufacturing scale. The supplier base is consolidating as ISO 22716 compliance windows force smaller molders toward exit or acquisition. Three archetypes dominate: integrated blow-fill-seal operators with captive recycling infrastructure, precision applicator technology licensors, and regional packaging generalists pivoting toward cosmetic specialization. Competitive moves center on backward integration into polymer production and strategic partnerships with beauty houses for co-developed sustainable formats.
Among European integrated operators, Albéa Group and Lumson exemplify the certification-heavy tier where blow-fill-seal capabilities and documented recycling infrastructure determine vendor selection. HCP Packaging anchors Asia-Pacific positioning through dedicated cosmetic packaging facilities. These three entities represent the supplier archetype that is capturing volume as procurement decisions consolidate among beauty houses with binding sustainability commitments.
| Leading Market Players |
|---|
| Albéa Group |
| HCP Packaging |
| Amcor |
| AptarGroup |
| Lumson |
| World Wide Packaging |
| Quadpack |
| Raepak |
| Yonwoo |
| Others |
Supply & Pricing Matrix
Long-term resin offtake contracts between German extrusion molders and polypropylene producers lock in feedstock access and stabilize unit economics against petrochemical price swings. These arrangements concentrate procurement power among integrated operators with backward integration into polymer production, while smaller molders absorb spot market volatility.
Pricing Analysis
Certification level creates the primary spread between ISO 22716-compliant suppliers and uncertified competitors. Three-tier pricing structure across premium certified, standard industrial, and economy unverified levels reflects compliance investment recovery. Cost compression in the economy tier is intensifying because REACH additive restrictions extend certification timelines. Mass-market retailers exhibit highest price sensitivity, whereas luxury beauty houses prioritize applicator precision over unit cost.
Supply Chain Analysis
Rhine-Ruhr logistics corridors represent the dominant chokepoint for European tube distribution. Manufacturing concentrates in Germany, China, and South Korea, with raw material flows drawing from Saudi Arabian polyethylene producers and South Korean polypropylene specialists. Single-source vulnerability sits with specialized ethylene vinyl alcohol barrier polymer suppliers. Distribution runs through beauty house central procurement hubs in Paris, Stuttgart, and Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supplier fragmentation creates acquisition opportunities as ISO 22716 compliance windows force exits. Clean beauty reformulation toward water-based chemistry generates specification niches for barrier polymer specialists.
For Market Incumbents: Compound certification advantages by acquiring distressed mid-cap molders facing 12-18 month compliance deadlines. Deepen captive recycling infrastructure in California and France where extended producer responsibility schemes concentrate procurement decisions. Glass and aluminum substitution in prestige segments demands defensive R&D into hybrid tube formats. For New Entrants and Emerging Players: Anchor in water-compatible barrier polymer development for clean beauty brands accelerating reformulation timelines. Target German retailers advancing fastest on EU PPWR compliance as the most penetrable procurement channel. Pursue co-development partnerships with digital-native brands specifying e-commerce-optimized tube resilience. For Investors and Strategic Acquirers: Capital is best deployed toward integrated blow-fill-seal operators with documented recycling partnerships and ISO 22716 certification. The five-to-ten year viability window favors suppliers with established positions in California and Germany regulatory clusters. Monitor ECHA microplastic enforcement timelines as the critical inflection signal for formulation-driven tube specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive resin supply insulates Albéa Group and HCP Packaging from petrochemical price volatility. |
| ISO 22716 Certification Investment | Compliance collapse eliminates smaller molders and concentrates volume among certified European facilities. |
| Recycling Infrastructure Partnership | Documented post-consumer collection capabilities unlock procurement from LVMH and L'Oréal sustainability commitments. |
| Precision Applicator Technology Licensing | Micro-pump mechanisms command premium positioning among Seoul-based K-beauty export manufacturers. |
| Direct-to-Consumer Channel Specification | Lightweight mono-material formats meet Amazon and Zalando fulfillment damage-resistance requirements. |
Research Methodology
A spread of perspectives from packaging procurement managers at beauty houses, extrusion blow molding plant engineers, regulatory affairs specialists at cosmetic brands, and sustainability certification auditors converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA cosmetic labeling guidance documents, ECHA REACH restriction updates, EU PPWR regulatory texts, and customs trade data on polyethylene and polypropylene flows. Bottom-up volume modeling and top-down market sizing triangulated on segment-level outputs.
Segmentation dimensions modeled include formulation chemistry, packaging format, distribution channel, and regional regulatory cluster across the analysis window. CAGRs derived from regression analysis on historical shipment data and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporated REACH enforcement timelines for microplastic restrictions and California extended producer responsibility scheme implementation pace.
Material uncertainties — polypropylene feedstock price volatility, ECHA additive restriction scope expansion, and glass substitution rates in prestige segments — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EU PPWR recyclability threshold enforcement and clean beauty reformulation adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Europe Plastic Cosmetic Packaging Market
Cosmetic Packaging
Lotion Tubes Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Beauty and Personal Care Packaging Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Pump Bottle Market
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Latin America Cosmetic Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Middle East and Africa Cosmetic Packaging Market