
 Nail Polish Packaging Market | 2026-2036
Nail Polish Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Nail Polish Packaging Market Outlook
REACH is consolidating material compliance costs across European supply chains. Gerresheimer AG leverages its pharmaceutical-grade glass expertise to anchor premium bottle production for luxury nail brands. Amcor Ltd competes through sustainable plastic innovation, while Virospack specializes in droper and brush-assembly systems that integrate closure and applicator functions.
Nail polish packaging encompasses primary containers, closures, and applicator systems engineered to prevent solvent evaporation, ensure viscosity stability, and enable precise brush delivery of nitrocellulose-based lacquers. Glass bottles with brushed aluminum collars remain the dominant format in prestige segments, while plastic and aluminum alternatives gain traction in mass-market and travel-size categories. Decoration through screen printing and hot stamping commands premium positioning, whereas shrink sleeve labels offer cost-efficient brand differentiation for high-volume SKUs.
EMA cosmetic ingredient oversight, EU Green Deal sustainability mandates, and FDA color additive regulations in the United States collectively shape material selection, recyclability claims, and market access protocols across major demand centers. Stakeholders must monitor evolving extended producer responsibility frameworks and solvent-emission thresholds that will determine which material substrates and decoration technologies retain commercial viability.
Market Dynamics
EU Green Deal sustainability mandates are compressing material choices across nail polish packaging supply chains, forcing converters to requalify substrates and decoration processes ahead of tightening recyclability thresholds.
Growth Catalysts
- REACH compliance consolidation:Harmonized chemical safety standards across Europe reduce fragmentation in raw material sourcing, enabling economies of scale in glass and aluminum supply.
- Prestige brand sustainability commitments:Luxury cosmetics houses anchor demand for refillable bottle systems and mono-material closures that simplify end-of-life sorting.
- Solvent-recovery technologies:Closed-loop nitrocellulose handling systems in French and Italian manufacturing clusters cut volatile organic compound emissions while preserving lacquer viscosity stability.
Market Restraints
- Borosilicate glass supply concentration:Pharmaceutical-grade bottle production clusters in Germany and France face capacity constraints as cosmetic and drug packaging demands converge.
- Aluminum collar price volatility:Energy-intensive smelting operations in European foundries transmit electricity cost swings directly into component pricing.
- Decorative substrate incompatibility:Metallic hot-stamping foils and certain UV-cured inks complicate mechanical recycling streams, creating friction with EU Green Deal circularity targets.
Strategic Opportunities
- Refill station networks:French retail pharmacies and dedicated beauty chains pilot in-store dispensing systems that eliminate single-use primary packaging.
- Bio-based nitrocellulose alternatives:Biotechnology-derived film-forming polymers converge with conventional solvent systems to enable drop-in material substitution without brush-performance degradation.
- Post-consumer recycled glass expansion:Italian and Spanish container glass recovery infrastructure creates feedstock pools for cosmetic-grade bottle production with reduced virgin material intensity.
Industry Challenges
- Decorative certification timelines:ECHA substance-of-very-high-concern screening delays new pigment and effect-material approvals by 18-24 months.
- Brush-assembly automation gaps:Precision fiber alignment and crimping operations resist full robotic integration, constraining throughput scaling.
- Legacy mold amortization:Existing bottle cavity investments in proprietary shapes complicate rapid format transitions to lighter-weight or recycled-content designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nail Polish Packaging Market |
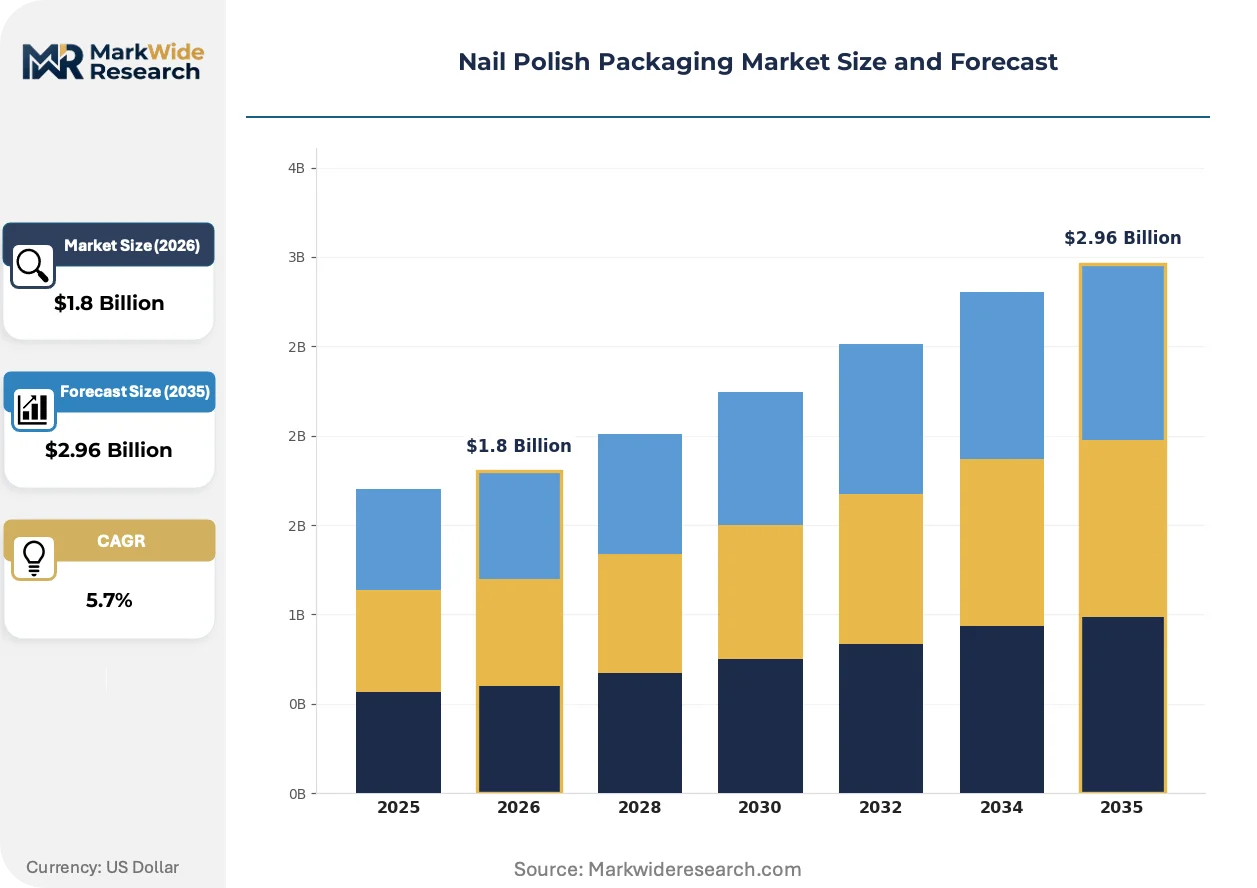
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Jars, Tubes, Pouches Material: Glass, Plastic, Aluminum, Cardboard Closure Type: Screw Caps, Pump Dispensers, Flip-Tops, Rolling Balls Decoration Type: Labels, Screen Printing, Hot Stamping, Shrink Sleeves |
| Companies Covered | GCC Packaging Group, Gerresheimer AG, Diamond Cosmetics, Silgan Holding, Amcor Ltd, Baralan USA, Virospack, Gidea Packaging, HCT Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nail Polish Packaging Market Strategic Shifts
Sustainability-driven material substitution is absorbing technical resources across formulation, decoration, and end-of-life design. Three converging developments are compressing conventional packaging paradigms.
Mono-material polypropylene bottles are absorbing decoration and barrier functions previously assigned to glass-aluminum assemblies. Mass-market brands in Germany and Poland adopt injection-molded opaque grades with in-mold labeling to bypass separate sleeve or print operations. The shift is compressing decoration supplier margins while expanding polymer converter volumes.
REACH authorization requirements for chromium-based pigments and certain phthalate plasticizers are forcing reformulation of color cosmetics packaging across European supply chains. Decorative coating houses in France and Italy accelerate water-based and UV-LED curing alternatives. Prestige segments absorb compliance costs through premium positioning, while mass-market SKUs face margin compression.
Direct-to-consumer sampling programs are displacing traditional counter-based distribution for trial-size nail polish. Subscription box operators in the United Kingdom and Netherlands consolidate micro-format procurement, concentrating buying power with specialized 3-5 milliliter bottle suppliers. The channel rotation is visible in travel-retail contraction and e-commerce fulfillment center expansion.
Nail Polish Packaging Market Segmentation
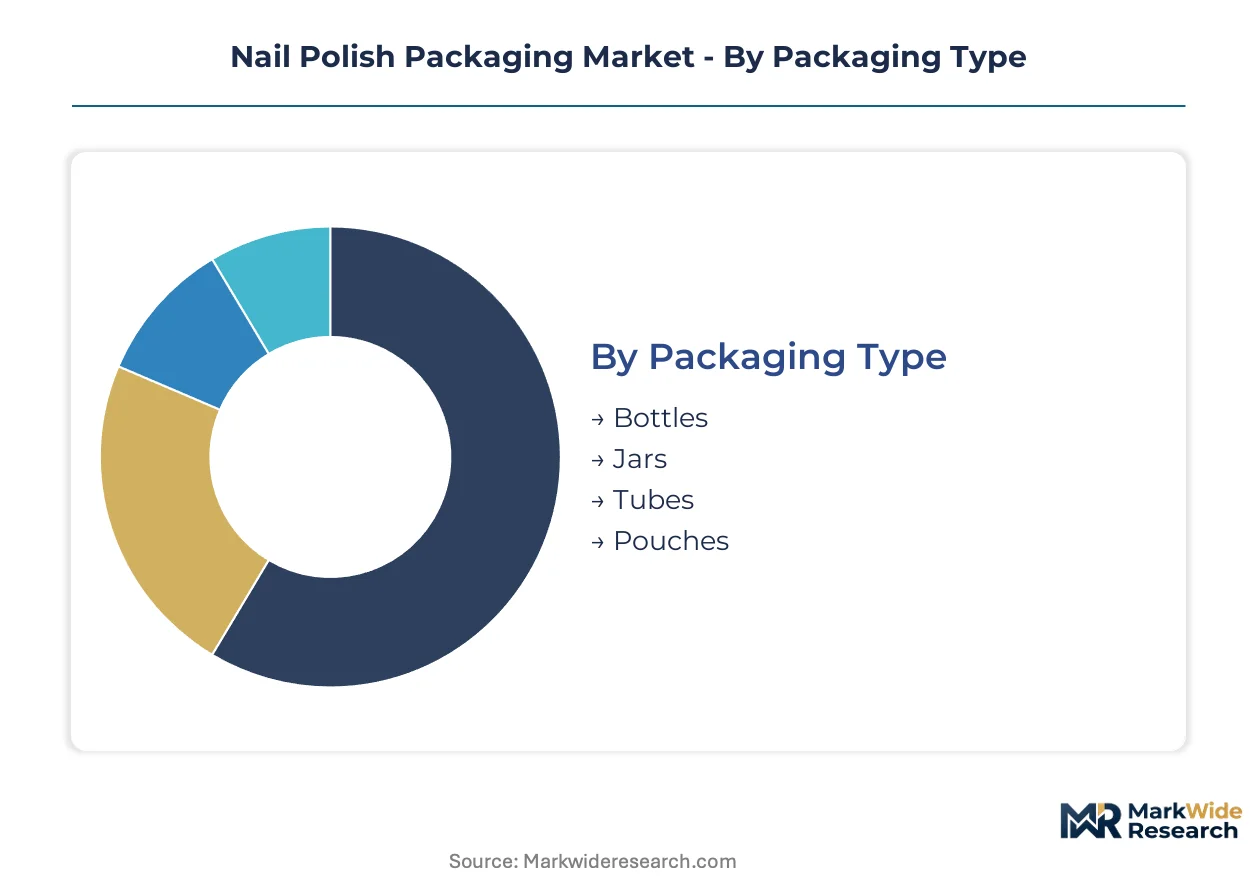
Packaging format selection in nail polish determines solvent retention, brush functionality, and shelf presence across prestige and mass-market channels. Material and decoration specifications must reconcile EU Green Deal recyclability mandates with brand differentiation requirements.
Packaging Type:
Format architecture governs viscosity stability, applicator integration, and retail display economics.
- Bottles:Cylindrical and square-profile glass or polymer vessels dominate prestige and mass-market lacquer presentation. French luxury houses anchor demand for heavy-wall flint glass with brushed aluminum collars, while German mass-market brands adopt injection-molded polypropylene for cost efficiency and breakage resistance.
- Jars:Wide-mouth containers accommodate dip-powder systems and gel polish pots requiring spatula access. Italian nail care specialists drive specification for double-wall polypropylene jars with integrated seal rings that prevent UV-cured product skinning.
- Tubes:Collapsible aluminum or laminated plastic formats serve travel-size and professional back-bar dispensing. Polish and Spanish converters specialize in 8-15 milliliter squeeze tubes with precision nozzles for art liner applications.
- Pouches:Flexible single-use sachets and refill pouches emerge in subscription sampling and salon bulk supply. Netherlands e-commerce operators consolidate procurement of 3-milliliter metallized film pouches for direct-to-consumer trial programs.
Mature deployment sits with bottles. Newer deployment is concentrated in pouches.
Material:
Substrate selection balances chemical resistance, decoration compatibility, and end-of-life sorting complexity.
- Glass:Soda-lime and borosilicate formulations provide impermeable barriers against nitrocellulose solvent evaporation. German pharmaceutical-grade glass converters supply French prestige brands with molded bottles achieving 0.5% weight tolerance for automated filling lines.
- Plastic:Polypropylene, PET, and acrylic polymers absorb decoration functions through in-mold labeling and direct UV printing. Mass-market penetration climbs fastest in Poland and Czechia where converters integrate recycled content streams.
- Aluminum:Lightweight, infinitely recyclable metal serves collapsible tubes, bottle collars, and mono-material closures. French and Italian foundries face electricity cost volatility that transmits into component pricing.
- Cardboard:Rigid and folding carton formats enclose primary containers for gift sets and retail multipacks. FSC-certified board gains traction in UK and Scandinavian markets with extended producer responsibility compliance requirements.
Glass commands premium positioning. Plastic delivers volume scale.
Closure Type:
Sealing mechanism determines shelf life, user experience, and brush-assembly integration.
- Screw Caps:Threaded aluminum or polymer closures with integrated brush stems constitute the dominant nail polish sealing format. French applicator specialists engineer crimped fiber bundles with 500-filament density for precision lacquer deposition.
- Pump Dispensers:Metered-dose systems serve professional salon back-bar and nail care treatment products. German packaging houses adapt pharmaceutical pump technologies for viscous gel polish formulations.
- Flip-Tops:Hinged polypropylene closures enable one-handed access for quick-dry top coat and treatment oils. Italian converters specialize in living-hinge designs with 10,000-cycle durability testing.
- Rolling Balls:Spherical applicator systems deliver cuticle oils and nail strengtheners with massage functionality. Spanish manufacturers supply roller-ball inserts with stainless steel or glass sphere options.
Screw caps anchor standard deployment. Pump dispensers expand in professional channels.
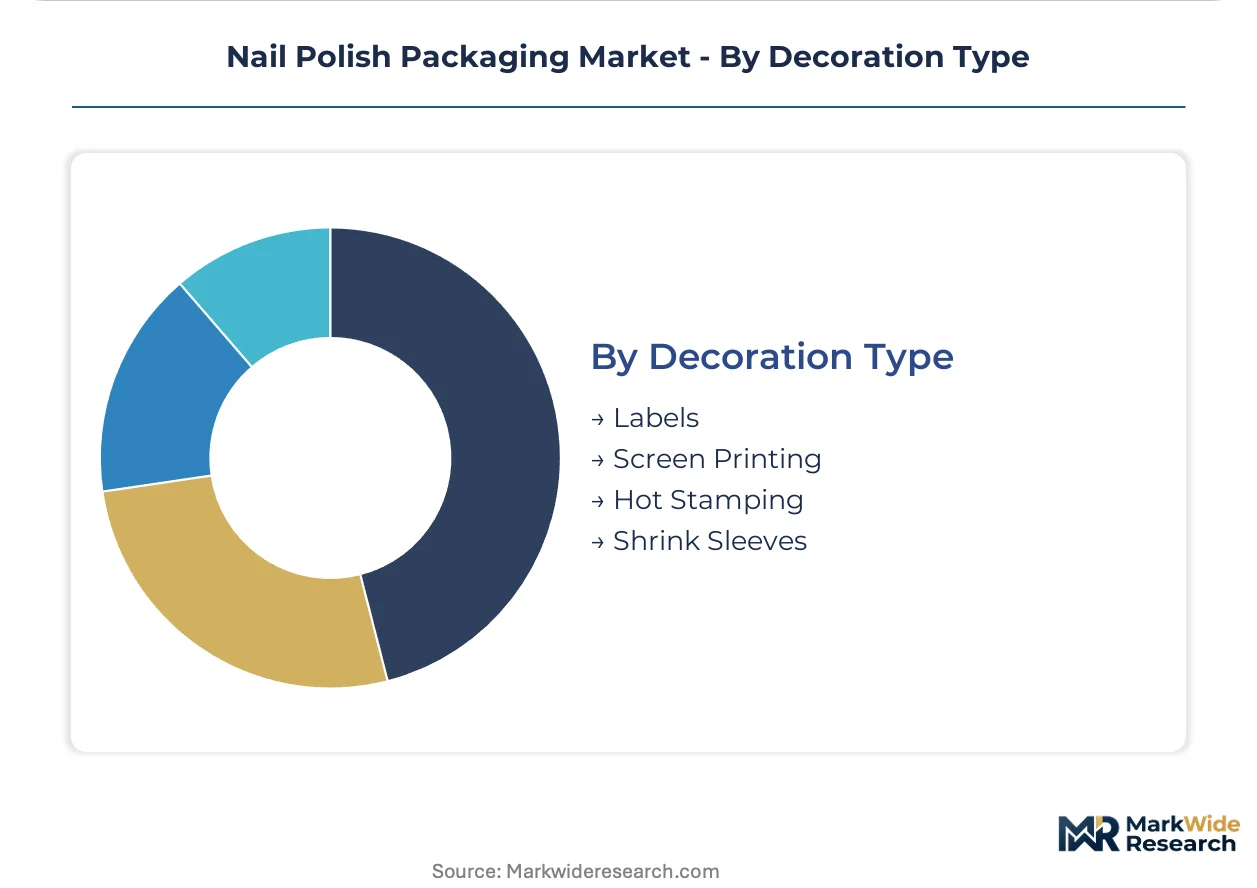
Decoration Type:
Surface treatment determines brand recognition, regulatory compliance, and recycling stream compatibility.
- Labels:Pressure-sensitive paper and synthetic facestocks enable complex graphics and variable data printing. UK converters specialize in clear-on-clear labels for no-label look applications on transparent glass.
- Screen Printing:Direct ceramic and UV-cured ink application delivers premium tactile quality and durability. Italian decoration houses command premium positioning for multi-color wet-on-wet printing on curved bottle surfaces.
- Hot Stamping:Metallic foil transfer creates reflective brand elements and luxury signaling. REACH authorization constraints on chromium-based pigments force reformulation of traditional gold and silver foil systems.
- Shrink Sleeves:Full-body polymer sleeves provide 360-degree graphics and tamper-evident sealing. German mass-market brands adopt PET-G and PLA sleeve materials to align with EU Green Deal recyclability targets.
Screen printing dominates prestige positioning. Shrink sleeves scale for high-volume SKUs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized industrial zones in northern France and western Germany concentrate glass manufacturing for prestige cosmetic packaging. Tax incentives for sustainable manufacturing in these regions accelerate converter investment in recycled-content production lines.
France
Luxury cosmetics houses in Paris and Grasse anchor demand for heavy-wall flint glass bottles with brushed aluminum collars. ANSM cosmetic packaging regulations enforce strict material safety documentation for primary containers. The Normandy glass corridor supplies pharmaceutical-grade borosilicate to prestige nail brands with automated filling compatibility.
Germany
Mass-market brands in North Rhine-Westphalia adopt injection-molded polypropylene bottles with in-mold labeling for cost efficiency. REACH compliance consolidation reduces raw material sourcing fragmentation across European supply chains. Gerresheimer AG leverages pharmaceutical-grade expertise from its Düsseldorf-area facilities to serve premium cosmetic segments.
Italy
Specialist decoration houses in Milan and Bologna command premium positioning for multi-color wet-on-wet screen printing. ECHA substance-of-very-high-concern screening delays new pigment approvals, forcing coating reformulation. The Veneto container glass recovery infrastructure creates feedstock pools for cosmetic-grade bottle production with reduced virgin material intensity.
United States
Direct-to-consumer subscription operators in New York and California consolidate procurement of micro-format bottles for sampling programs. FDA color additive regulations shape material selection and market access protocols for imported packaging. Baralan USA anchors West Coast distribution of brush-assembly systems for professional salon channels.
United Kingdom
E-commerce fulfillment centers in the Midlands expand warehousing for direct-to-consumer nail polish distribution. Extended producer responsibility frameworks under the UK Packaging Waste Regulations tighten recyclability claims and sorting requirements. UK converters specialize in clear-on-clear pressure-sensitive labels for no-label look applications on transparent glass bottles.
Nail Polish Packaging Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across material and component tiers. The market exhibits moderate consolidation with tiered competition between multinational packaging groups and regional decoration houses. Three archetypes dominate: pharmaceutical-grade glass specialists, sustainable polymer innovators, and integrated brush-assembly system providers. Capacity expansion in recycled-content glass and strategic partnerships for refill station infrastructure represent the dominant competitive moves.
Among Germany-based pharmaceutical packaging specialists, Gerresheimer AG exemplifies the premium glass archetype through its leveraged expertise in high-tolerance bottle manufacturing. Amcor Ltd and Silgan Holding represent diversified conglomerate positioning across material substrates and geographic markets. Virospack occupies a specialist position within the integrated applicator systems tier, anchoring droper and brush-assembly capabilities that converge closure and precision fiber functions.
| Leading Market Players |
|---|
| GCC Packaging Group |
| Gerresheimer AG |
| Diamond Cosmetics |
| Silgan Holding |
| Amcor Ltd |
| Baralan USA |
| Virospack |
| Gidea Packaging |
| HCT Packaging |
| Others |
Value Chain & Pricing Dynamics
Prestige brand procurement offices in Paris and Grasse concentrate demand for pharmaceutical-grade borosilicate bottles, anchoring a contract-based pricing model where long-term offtake agreements secure capacity allocation from German glass converters. This buyer concentration enables volume-tiered negotiations while spot purchases for short-lead-time orders command substantial premiums.
Pricing Analysis
Short-lead-time orders for heavy-wall flint glass bottles attract 15-25% premiums over standard contract pricing as French luxury houses compete for constrained German and French furnace capacity. Three-tier pricing structure across premium pharmaceutical-grade, standard cosmetic-grade, and economy polymer alternatives differentiates by certification level and automation compatibility. Cost compression in mass-market polypropylene segments is intensifying because Polish and Czech converters are expanding recycled-content capacity. Mass-market brands exhibit highest price sensitivity, while prestige houses absorb premiums for decoration complexity and material purity documentation.
Supply Chain Analysis
Direct-to-brand channels handle hyperscale prestige demand, while specialized distributors serve mid-tier cosmetic houses and private-label operators across European markets. Supply concentrates in Germany for pharmaceutical-grade glass, France for aluminum collars and decoration, and Italy for container glass recovery and screen-printing services. Raw material flows draw from German soda-lime sand deposits, French foundry-grade aluminum, and Italian post-consumer glass cullet streams. Single-source vulnerability sits with borosilicate furnace capacity in the Düsseldorf-Cologne corridor, where cosmetic and drug packaging demands converge. Distribution runs through integrated converter-direct relationships for premium tiers and regional packaging distributors for mass-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
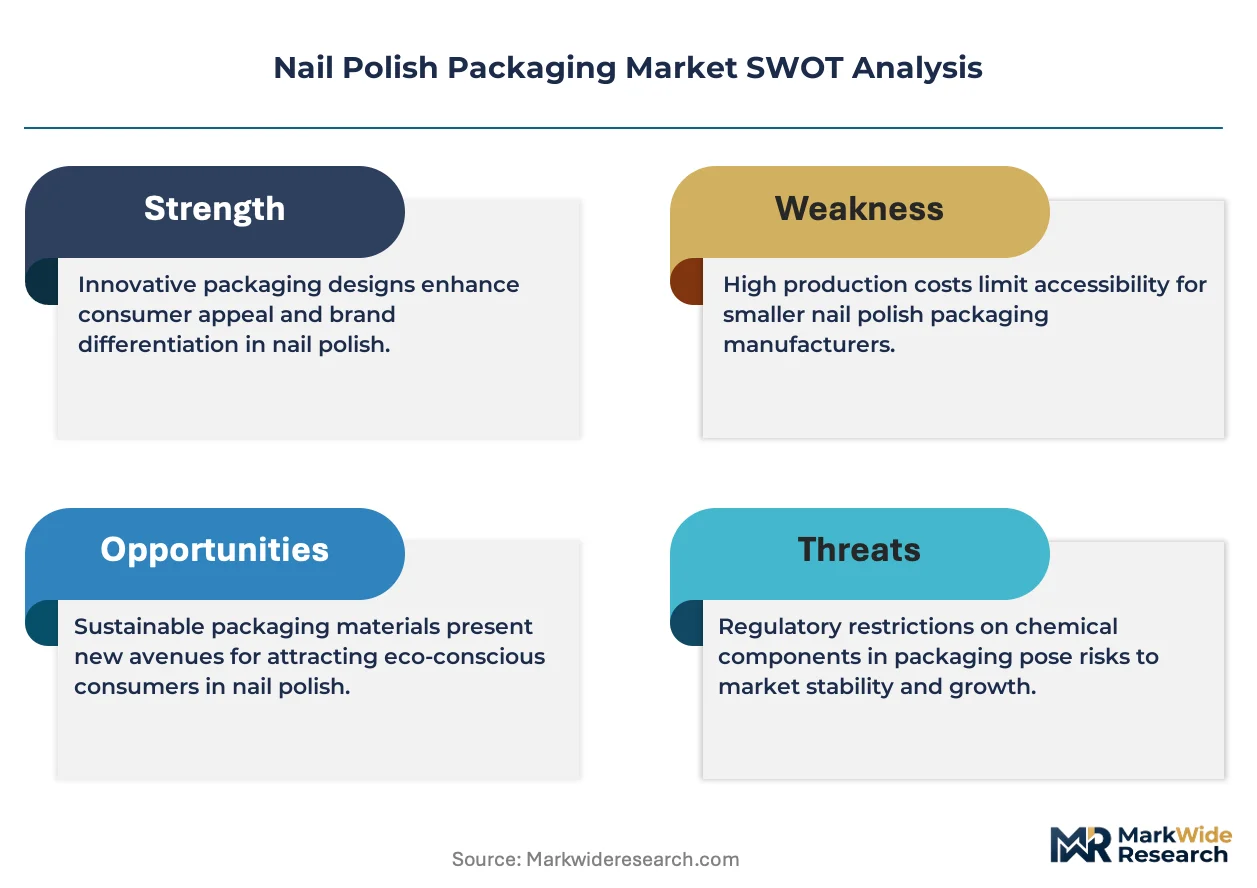
This market is becoming a vertical-integration race as converters pursue captive control over recycled glass feedstock and decoration capabilities to defend margin positions against regulatory compliance cost escalation.
For Market Incumbents: Hedge against aluminum price volatility through long-term electricity supply agreements with French and Italian foundries, or accelerate backward integration into post-consumer glass recovery infrastructure. Secure ECHA pre-registration for alternative pigments ahead of substance-of-very-high-concern screening delays that threaten decoration house partnerships. Capacity expansion in Spanish and Italian container glass recovery preserves feedstock optionality as EU Green Deal circularity mandates tighten. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable entry vector, consolidating procurement of 3-5 milliliter micro-format bottles for UK and Netherlands e-commerce operators. Target white-space in bio-based nitrocellulose alternative packaging compatibility testing, where biotechnology-derived film-forming polymers require new barrier validation. Pursue private-label partnerships with German mass-market brands seeking Polish and Czech recycled-content polymer converters as second sources. For Investors and Strategic Acquirers: The window for entry favors integrated brush-assembly specialists with pharmaceutical-grade crimping capabilities and established EMA compliance documentation. Long-term viability hinges on exposure to refill station infrastructure pilots in French retail pharmacies, which could displace single-use primary packaging volumes. Watch for ECHA authorization delays on chromium-based pigment alternatives as an inflection signal for decoration house consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Glass Recovery | Italian and Spanish cullet infrastructure secures EU Green Deal compliant feedstock pools for cosmetic-grade bottle production. |
| Refill Station Infrastructure Partnership | French retail pharmacy pilots eliminate single-use packaging for participating prestige and mass-market brand portfolios. |
| Water-Based Decoration Technology Transition | Italian coating houses accelerate UV-LED curing alternatives ahead of REACH authorization constraints on solvent systems. |
| Brush-Assembly Automation Investment | Precision fiber alignment robotics address throughput constraints that currently limit crimping operation scaling. |
| Mono-Material Polypropylene Expansion | German mass-market brands adopt injection-molded opaque grades with in-mold labeling to bypass separate decoration operations. |
Study Parameters
Document review covered ECHA substance registration databases, EU Green Deal implementation timelines, and FDA color additive guidance documents, complemented by interviews with packaging procurement directors at French luxury cosmetics houses, German glass converter operations managers, Italian decoration house technical directors, and Polish polymer converter sustainability leads. Secondary validation drew from ANSM packaging compliance bulletins, REACH authorization status reports, and extended producer responsibility framework documentation across UK, French, and German jurisdictions. Bottom-up volume modeling triangulated against top-down value estimates from trade flow analysis.
Segment-level projections across packaging format, material substrate, closure mechanism, and decoration technology dimensions were generated through driver-elasticity modeling over the projection horizon. CAGRs were derived from regression analysis against historical volume trajectories, incorporating EU regulatory phase-in schedules and prestige brand sustainability commitment timelines as structural break assumptions. Industry-specific inputs included solvent-recovery technology adoption curves in French and Italian manufacturing clusters and post-consumer recycled glass feedstock availability from Veneto and Catalonia recovery infrastructure.
The model holds under stable EU regulatory implementation schedules and continued furnace capacity utilization above 80%; deviation in energy cost volatility or ECHA screening timeline acceleration would shift volume trajectories toward polymer alternatives. Forecasts reflect assumptions regarding refill station network expansion rates and bio-based nitrocellulose substitution timelines. Periodic stress-testing of base assumptions against ANSM and EMA packaging guidance updates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market
Cosmetic Packaging
Skin Care Packaging Market
Cosmetic Packaging
Anti-Counterfeit Cosmetic Packaging Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
Cosmetic and Toiletry Containers Market
Cosmetic Packaging
Asia Pacific Cosmetic Packaging Market
Cosmetic Packaging
Beauty Supplements Packaging Market
Cosmetic Packaging
Europe Cosmetic Packaging Market
Cosmetic Packaging
Global Cosmetic Packaging Market
Cosmetic Packaging
Lotion Tubes Market
Cosmetic Packaging
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
Lip Care Packaging Market