
 Latin America Personal Care Packaging Market | 2026-2036
Latin America Personal Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Personal Care Packaging Market Foresight
Buyer fragmentation across indie beauty startups and direct-to-consumer skincare labels is recalibrating order economics for Latin American converters. Amcor Ltd leverages its regional film extrusion network to serve mid-sized brands with shorter runs. Mondi Group anchors its position through kraft paper solutions targeting fragrance houses seeking plastic reduction. AptarGroup differentiates via pump and dispensing systems that meet ANVISA's evolving child-resistance protocols.
Latin America personal care packaging encompasses primary and secondary containment systems—tubes, bottles, jars, and sprays—engineered from plastic, glass, metal, or paper substrates with functional barriers against moisture, oxidation, and UV degradation, produced through extrusion blow molding, injection stretch blow molding, or thermoforming processes designed to preserve product integrity while enabling consumer dispensing. Plastic dominates material selection due to cost efficiency and design flexibility, though paper-based alternatives are gaining traction among sustainability-focused cosmetics brands. Tube formats lead in skincare applications where controlled dosing and portability drive preference, while pump closures command premium positioning in haircare and premium fragrance segments where precise dispensing enhances user experience.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce cosmetic packaging safety standards that govern material migration limits, labeling accuracy, and recyclability claims across the region. REACH-aligned substance restrictions from European parent companies are cascading into Latin American supplier specifications, particularly for colorants and plasticizers in direct-contact layers. Stakeholders must monitor regulatory divergence between Mercosur and Pacific Alliance frameworks while building compliance capabilities that span multiple national approval pathways.
Market Dynamics
ANVISA's updated cosmetic labeling requirements are compressing converter lead times and forcing material specification changes across Brazil's personal care packaging corridor. This regulatory pressure is reshaping order economics as brands accelerate compliance timelines.
Growth Catalysts
- Sustainable material mandates:Brazil's National Solid Waste Policy is accelerating converter investment in post-consumer recycled content for skincare tubes. ANVISA's alignment with Mercosur packaging standards is streamlining cross-border approvals for compliant suppliers.
- Direct-to-consumer channel expansion:Indie beauty startups in São Paulo are demanding shorter-run, digitally-printed secondary packaging. This segment is absorbing capacity from traditional offset converters.
- Child-resistance protocol evolution:ANVISA's dispensing safety standards are creating specification pull for pump systems with torque-verified closures. Fragrance houses are retrofitting legacy bottle formats to meet these requirements.
Market Restraints
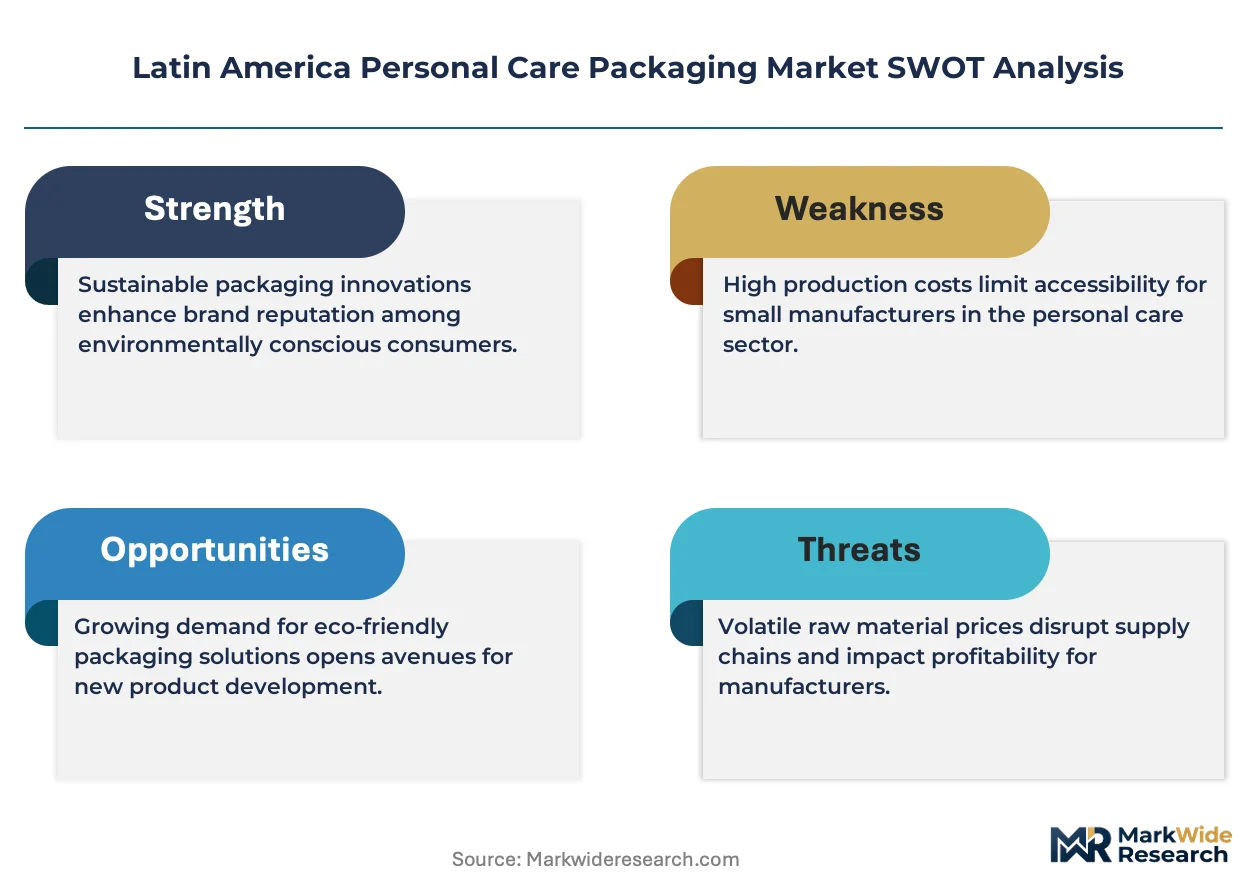
- Resin import dependency:Brazil's Southeast packaging cluster relies on imported polyethylene and polypropylene, exposing converters to petrochemical price volatility and currency fluctuation risk.
- Monomaterial technical ceiling:High-barrier skincare formulations currently require multi-layer structures that complicate mechanical recycling streams and limit circularity claims.
- Mercosur-Pacific Alliance regulatory divergence:Divergent cosmetic packaging approval pathways between Brazil and Chile are fragmenting converter compliance investments and extending product launch timelines.
Strategic Opportunities
- Colombia's underserved Andean corridor:INVIMA's streamlined cosmetic registration process is attracting brand manufacturing investment to Bogotá's emerging packaging hub. Converters with ANVISA-compliant systems can leverage existing certifications.
- Paper-based barrier convergence:Hydrophobic coating technologies are approaching performance parity with plastic laminates for dry personal care applications. Kraft paper tubes are penetrating deodorant and powder segments.
- Refill infrastructure development:Mexico's COFEPRIS is evaluating bulk dispensing regulations for professional salon channels. Pump and pouch systems designed for institutional refill are capturing specification interest from haircare brands.
Industry Challenges
- Digital printing skill scarcity:São Paulo's packaging cluster faces acute shortages of technicians trained in HP Indigo and Xeikon systems. Converters are competing with commercial print sectors for operational talent.
- Legacy injection molding asset stranding:Brazilian converters hold substantial PET preform capacity optimized for standard neck finishes. Lightweighting and custom closure trends are compressing utilization rates at these facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Personal Care Packaging Market |
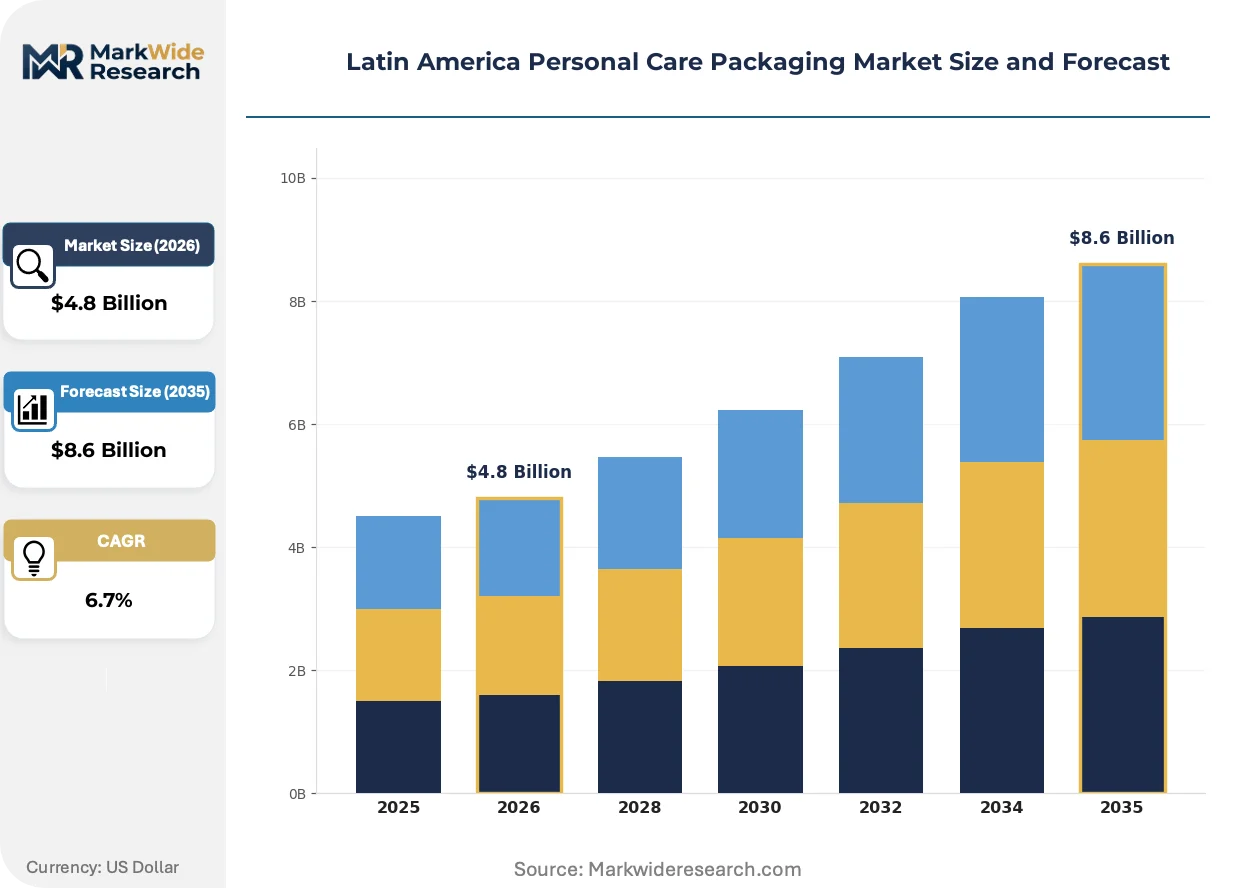
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Tube, Bottle, Jar, Spray Material: Plastic, Glass, Metal, Paper Closure Type: Screw Cap, Flip Top, Pump, Dropper End User: Cosmetics, Skincare, Haircare, Fragrance |
| Companies Covered | Amcor Ltd, Mondi Group, AptarGroup, Silgan Holdings, Sonoco, Albea, Gerresheimer AG, Berry Global Inc, Huhtamaki, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Personal Care Packaging Market Shifts & Advancements
Material science advances and regulatory alignment pressures are converging to reshape specification workflows across Latin America's personal care packaging value chain. Three developments are commanding converter R&D investment and brand procurement attention.
Mono-material polyethylene tubes with enhanced ethylene-vinyl alcohol barrier layers are absorbing technical validation cycles previously allocated to multi-layer structures. Brazilian skincare brands targeting European export markets are specifying these formats to preempt Extended Producer Responsibility compliance costs. The technology is absorbing capital from metallized film lamination lines as converters retool extrusion capacity.
ANVISA's 2023 cosmetic labeling resolution mandates QR-code traceability for allergen disclosure and ingredient sourcing. This policy is compressing artwork approval timelines and forcing brand-packaging converter data integration. Premium fragrance houses with complex multi-component packaging are experiencing the steepest workflow adaptation costs.
Beauty brands are consolidating supplier panels and shifting volume commitments toward converters with integrated pre-press, extrusion, and decoration capabilities. Mid-sized São Paulo packaging groups with captive tube printing are displacing fragmented procurement relationships. This concentration is most visible in haircare, where Unilever and L'Oréal procurement teams have reduced approved supplier counts by half since 2022.
Latin America Personal Care Packaging Market Segmentation
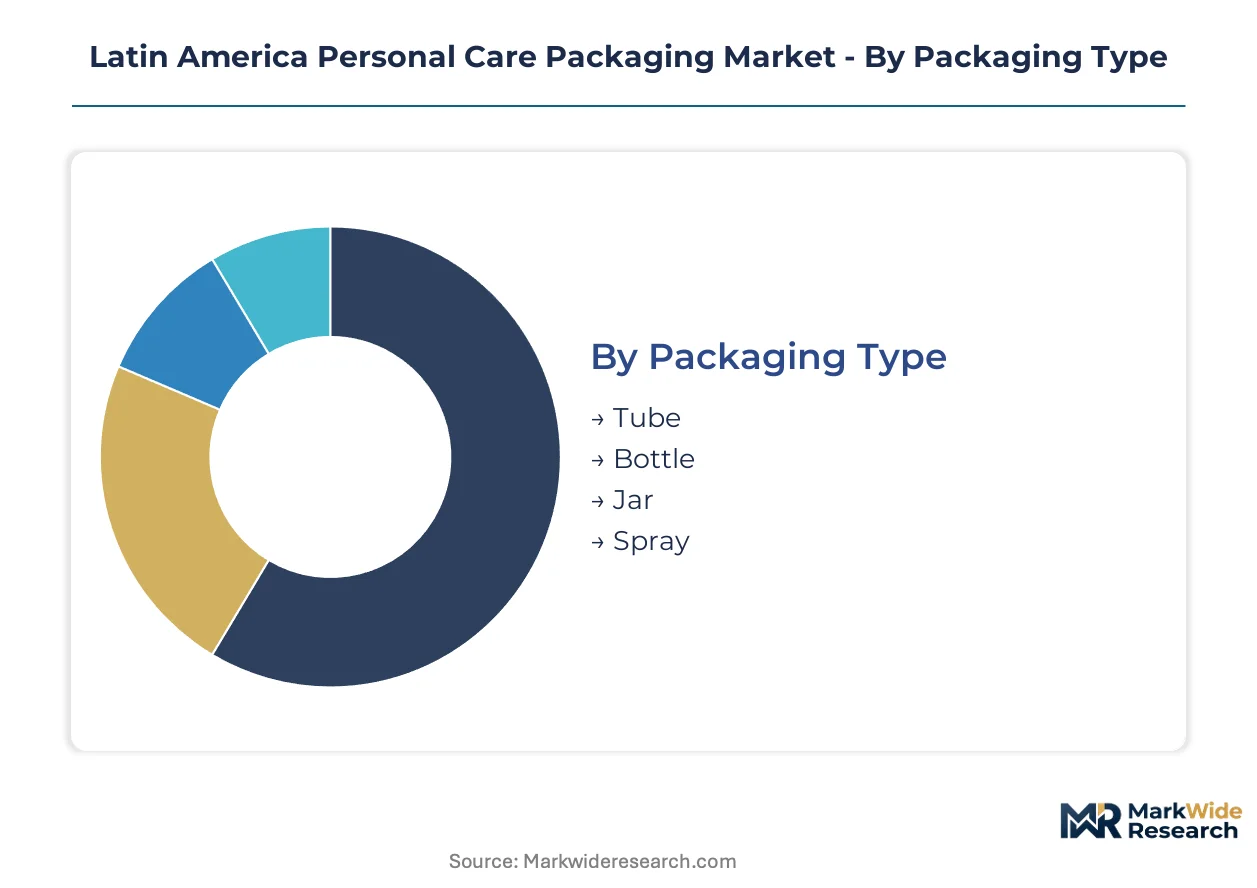
Personal care packaging in Latin America fragments across four distinct dimensions that determine converter equipment requirements and margin structures. Material selection and closure complexity drive the steepest capital intensity differences between segments.
Packaging Type:
Tube and bottle formats demand the highest upfront extrusion and blow molding investments, while jar and spray systems require more specialized but lower-capacity tooling configurations.
- Tube:Multi-layer co-extruded structures with ethylene-vinyl alcohol barriers dominate skincare applications where controlled dosing and portability matter. Brazilian converters in São Paulo's industrial corridor are retooling lamination lines to serve indie beauty startups demanding shorter runs with digital decoration.
- Bottle:Injection stretch blow molding and extrusion blow molding produce PET and HDPE containers for haircare and body care. ANVISA's child-resistance protocols are forcing specification changes for torque-verified closures in fragrance applications.
- Jar:Wide-mouth containers serve thick cream formulations across premium skincare segments. Thick-wall injection molding requires dedicated press capacity with extended cooling cycles.
- Spray:Aerosol and pump-actuated systems for deodorant and hair styling products. Propellant compatibility testing adds regulatory validation layers beyond standard cosmetic packaging.
Tube formats absorb the bulk of installed capacity across Brazil's Southeast packaging cluster; bottle segments are expanding most quickly as haircare brands consolidate supplier panels.
Material:
Substrate selection determines barrier performance, recyclability positioning, and exposure to petrochemical price volatility across converter operations.
- Plastic:Polyethylene and polypropylene dominate through cost efficiency and design flexibility. Brazil's import dependency for virgin resin exposes converters to currency fluctuation risk.
- Glass:Premium fragrance and skincare brands specify molded containers for tactile differentiation and chemical inertness. Furnace operations require continuous energy supply and represent the highest fixed-cost substrate category.
- Metal:Aluminum tubes and aerosol cans serve deodorant and hair spray applications. Monomaterial recyclability appeals to brands targeting post-consumer content mandates.
- Paper:Kraft-based tubes with hydrophobic coatings are penetrating dry personal care segments. Hydrophobic barrier technologies are approaching performance parity with plastic laminates for powder and solid formulations.
Plastic commands the majority of current volume throughput; paper-based alternatives are gaining specification share fastest among sustainability-focused cosmetics brands.
Closure Type:
Dispensing mechanism complexity separates premium positioning from mass-market applications, with torque verification and child-resistance features adding regulatory compliance costs.
- Screw Cap:Standard threaded closures for jars and bottles across mass-market skincare. Lowest unit cost but limited differentiation potential.
- Flip Top:Hinged lids for single-handed dispensing in shower and travel formats. Polypropylene living hinge durability determines product lifecycle performance.
- Pump:Precision dispensing systems for haircare and premium fragrance where dosage control enhances user experience. ANVISA's evolving safety standards are accelerating validation requirements for torque-verified designs.
- Dropper:Glass or plastic pipette systems for serum and oil formulations in premium skincare. Bulb material compatibility with active ingredients requires specialized testing protocols.
Pump closures capture the highest margin tier; droppers are climbing the fastest as facial serum penetration deepens across Mexico and Colombia.
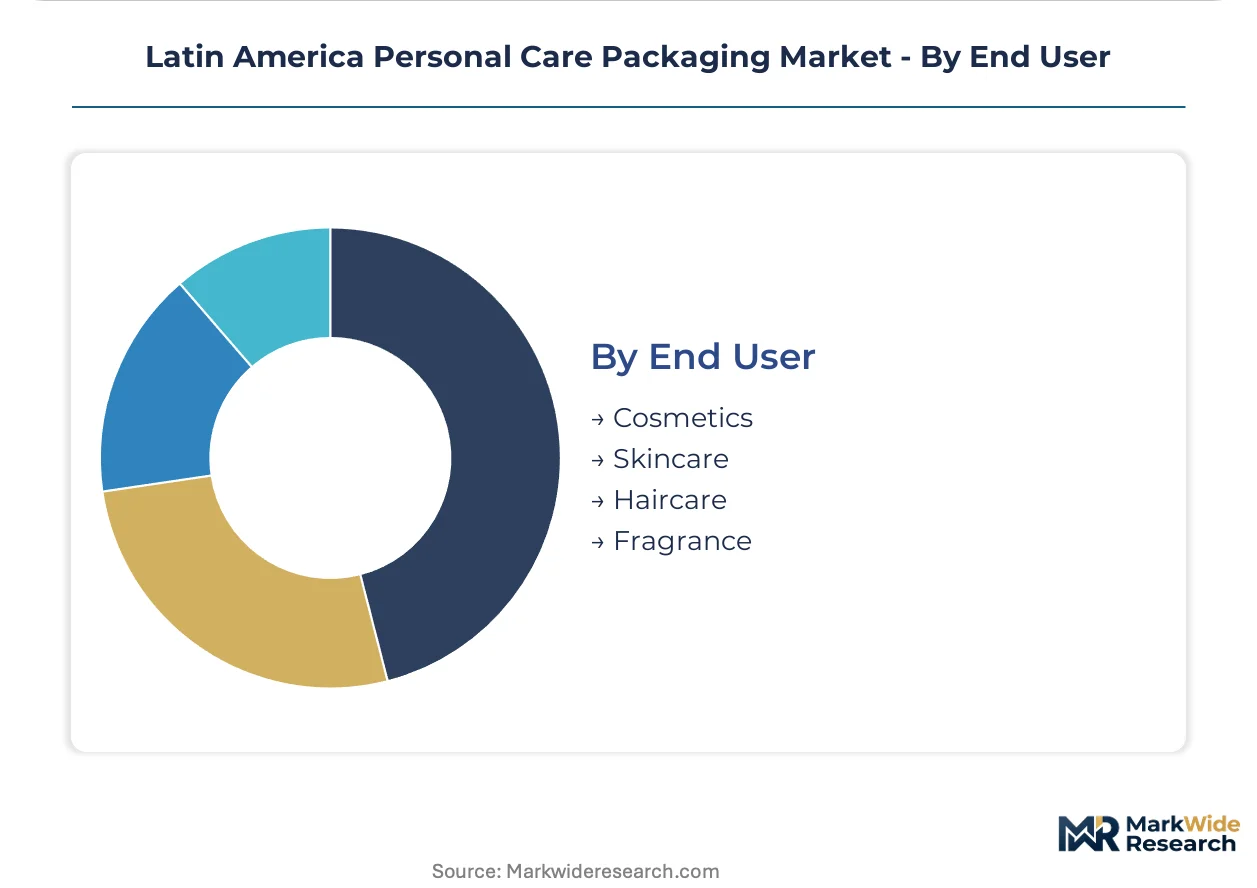
End User:
Brand procurement consolidation and channel mix create divergent order economics across personal care categories.
- Cosmetics:Color cosmetic packaging demands complex multi-component assemblies with precise shade matching. Shorter product lifecycles favor converters with digital printing and rapid tooling changeover.
- Skincare:Tube and jar formats with high-barrier requirements for active ingredient protection. Brazil's National Solid Waste Policy is accelerating post-consumer recycled content specifications.
- Haircare:Pump bottles and tubes for shampoo, conditioner, and styling products. Unilever and L'Oréal procurement teams have reduced approved supplier counts by half since 2022, concentrating volume with integrated converters.
- Fragrance:Premium glass bottles with custom closures and secondary packaging. ANVISA's QR-code traceability mandates are compressing artwork approval timelines for complex multi-component assemblies.
Skincare absorbs the dominant share of converter R&D investment; haircare is expanding most quickly as direct-to-consumer channel growth reshapes order economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil's Southeast industrial corridor, where São Paulo's packaging cluster processes orders for multinational personal care brands and indie beauty startups alike. Mexico's Central Plateau and Colombia's Andean corridor are absorbing secondary investment as regulatory alignment creates cross-border opportunities.
Brazil
Skincare brands are expanding sustainable packaging portfolios across São Paulo and Rio de Janeiro. ANVISA's updated cosmetic labeling requirements are pushing converters toward compliant material specifications with compressed lead times. The Southeast industrial corridor dominates converter capacity, with São Paulo's packaging cluster serving both multinational and direct-to-consumer labels.
Mexico
Haircare brands are consolidating supplier panels around integrated converters in Mexico City and Nuevo León. COFEPRIS maintains cosmetic packaging safety standards governing material migration limits and labeling accuracy. The Central Plateau region hosts expanding extrusion capacity as brands seek shorter-run digital printing for direct-to-consumer channels.
Colombia
INVIMA's streamlined cosmetic registration process is attracting brand manufacturing investment to Bogotá's emerging packaging hub. The national pharmaceutical regulator enforces safety standards that align with broader Andean region harmonization efforts. Converters with ANVISA-compliant systems leverage existing certifications to serve both domestic and export markets.
Chile
Pacific Alliance trade frameworks are creating specification divergence challenges for converters serving cross-border beauty brands. The national health authority maintains distinct cosmetic packaging approval pathways from Mercosur standards. Santiago's packaging sector specializes in premium fragrance secondary packaging with complex multi-component assemblies.
Argentina
Economic volatility is compressing converter margins while sustaining demand for cost-optimized plastic tube formats. Mercosur packaging standards alignment facilitates cross-border trade with Brazilian skincare brands. Buenos Aires maintains specialized capacity for color cosmetic packaging with precise shade matching requirements.
Latin America Personal Care Packaging Market Competitive Landscape
Brazilian producers anchor one tier of converter supply; European and North American specialists hold premium positioning through technology licensing and material science capabilities. The market structures around three tiers: integrated multinationals with captive extrusion networks, mid-sized regional groups with digital printing assets, and specialized closure manufacturers. Strategic consolidation and backward integration into resin compounding represent the dominant competitive moves as brands reduce approved supplier counts.
Within the integrated multinational tier, Amcor Ltd and Mondi Group exemplify scale-driven positioning across Latin American film and paper substrates. AptarGroup occupies a specialist position in pump and dispensing systems. These three companies represent divergent archetypes: Amcor leverages regional extrusion networks for mid-sized brand runs, Mondi anchors through kraft paper solutions targeting plastic reduction mandates, and AptarGroup differentiates via torque-verified closures meeting evolving child-resistance protocols.
| Leading Market Players |
|---|
| Amcor Ltd |
| Mondi Group |
| AptarGroup |
| Silgan Holdings |
| Sonoco |
| Albea |
| Gerresheimer AG |
| Berry Global Inc |
| Huhtamaki |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap converters across Brazil's Southeast corridor anchor regional supply, their consolidated ownership patterns enabling pricing discipline through captive extrusion networks and direct negotiations with petrochemical distributors. This ownership concentration insulates margin structures from the volatility that fragments pricing power among dispersed competitors in Mexico and Colombia.
Pricing Analysis
Volume-mass haircare contracts absorb converter capacity at compressed margins, while premium fragrance and skincare segments command substantial markups through torque-verified pump systems and custom closure engineering. Price differentiation hinges on ANVISA certification tiers and vertical integration depth, with resin import exposure driving cost compression across plastic-dependent tiers. Brand procurement consolidation since 2022 has intensified pricing pressure as Unilever and L'Oréal reduce approved supplier counts. Indie beauty startups exhibit highest price sensitivity; fragrance houses with complex multi-component assemblies show least.
Supply Chain Analysis
Brazil's National Solid Waste Policy and local-content preferences in government procurement channels are redirecting converter sourcing toward domestic post-consumer recycled resin streams and regional kraft paper suppliers. Raw material dependencies center on imported polyethylene and polypropylene from Gulf Coast petrochemical complexes, hydrophobic coating chemicals from European specialty producers, and EVOH barrier resins from Asian manufacturers. Single-source vulnerability runs through São Paulo's concentrated extrusion capacity, where furnace operations and continuous production requirements limit geographic diversification. Distribution feeds from converter clusters through brand-owned consolidation centers to retail and direct-to-consumer fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's personal care packaging sector sits at a materials-transition inflection, with mono-material polyethylene tubes displacing multi-layer metallized laminations as brands preempt Extended Producer Responsibility compliance costs.
For Market Incumbents: To counter stranded asset risk in legacy PET preform injection molding, accelerate retooling toward digital printing integration and captive tube extrusion capacity. Defensive consolidation of São Paulo's fragmented mid-cap converter base secures scale economies against procurement panel reductions by multinational beauty brands. Backward integration into resin compounding buffers currency-driven input volatility. For New Entrants and Emerging Players: Enter via Colombia's Andean corridor, where INVIMA's streamlined cosmetic registration process and underserved converter capacity create specification whitespace for ANVISA-certified systems. Target professional salon refill infrastructure in Mexico as COFEPRIS evaluates bulk dispensing regulations, capturing specification interest from institutional haircare brands. Go-to-market leverage rests on hydrophobic kraft paper barrier technologies approaching plastic laminate performance parity. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized São Paulo packaging groups with captive digital printing assets and established multinational brand relationships. Long-term viability over a five-to-ten year window depends on converter positioning within consolidated procurement panels and sustainable material certification depth. Signal to monitor: ANVISA's alignment with Mercosur packaging standards accelerating cross-border approval harmonization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply shields Brazilian converters from petrochemical currency volatility. |
| Digital Printing Asset Acquisition | HP Indigo and Xeikon capacity captures indie beauty startup demand for shorter-run secondary packaging. |
| ANVISA Certification Pre-Investment | Early compliance with evolving child-resistance protocols secures specification lock-in with fragrance houses. |
| Hydrophobic Coating R&D Partnership | Kraft paper barrier convergence opens deodorant and powder segments to plastic displacement. |
| Cross-Border Certification Leverage | ANVISA-compliant systems transfer to INVIMA-registered Colombian operations with minimal revalidation cost. |
Research Methodology
Trade association filings, petrochemical import records, and regulatory gazette publications formed the secondary backbone, cross-referenced against primary interviews with extrusion plant managers, brand procurement leads at multinational personal care companies, ANVISA regulatory affairs specialists, and digital printing operations directors. Bottom-up capacity assessments across São Paulo's packaging cluster were triangulated with top-down demand modeling from beauty brand manufacturing footprints.
Bottom-up modeling tracked installed extrusion and blow molding capacity by converter tier, while top-down approaches estimated category demand from brand volume disclosures and channel growth patterns. Segmentation dimensions spanned packaging type, material substrate, closure complexity, and end-use category across the analysis window. CAGRs were derived from regression analysis against macroeconomic drivers and regulatory event timelines, with input from resin price elasticity studies and procurement consolidation tracking.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical price shock scenarios and regulatory divergence between Mercosur and Pacific Alliance frameworks. Forecasts reflect documented assumptions on brand consolidation velocity and sustainable material substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Lip Gloss Tube Market
Cosmetic Packaging
Europe Plastic Cosmetic Packaging Market
Cosmetic Packaging
Anti-Counterfeit Cosmetic Packaging Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
India Personal Care Packaging Market
Cosmetic Packaging
Eyeliner and Kajal Sculpting Pencil Packaging Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
Europe Personal Care Packaging Market
Cosmetic Packaging
Skin Care Packaging Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
Cosmetic Bottles Packaging Market
Cosmetic Packaging
Beauty and Personal Care Packaging Market
Cosmetic Packaging
Beauty Supplements Packaging Market
Cosmetic Packaging
Global Cosmetic Packaging Market