
 Single Portion Cosmetic Packaging Market | 2026-2036
Single Portion Cosmetic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Single Portion Cosmetic Packaging Market Analytics
A capital-intensity divergence between integrated molders and outsourced decorators is reorganizing competitive tiers in single portion cosmetic packaging. Albéa Group leverages captive tube extrusion capacity across European and Asian plants to control unit economics at scale. HCP Packaging anchors its position through dedicated tooling investments for luxury brand sachet programs. TekniPlex competes via multi-layer barrier film technology that extends preservative-free formulation shelf life.
Single portion cosmetic packaging denotes primary containers engineered for one-time or limited-use cosmetic doses, typically constructed from multi-layer polyethylene or aluminum-laminate films with heat-sealed closure systems to prevent oxidation and microbial ingress. These formats serve sampling, travel retail, and subscription box channels where portability and hygiene override refillability. Sachets and tubes together occupy the dominant volume position, though biodegradable material variants are gaining fastest traction as beauty brands face Scope 3 emissions scrutiny. Plastic remains the baseline substrate for cost-sensitive blister and jar formats, while aluminum-laminate structures command premium positioning in high-actives skincare.
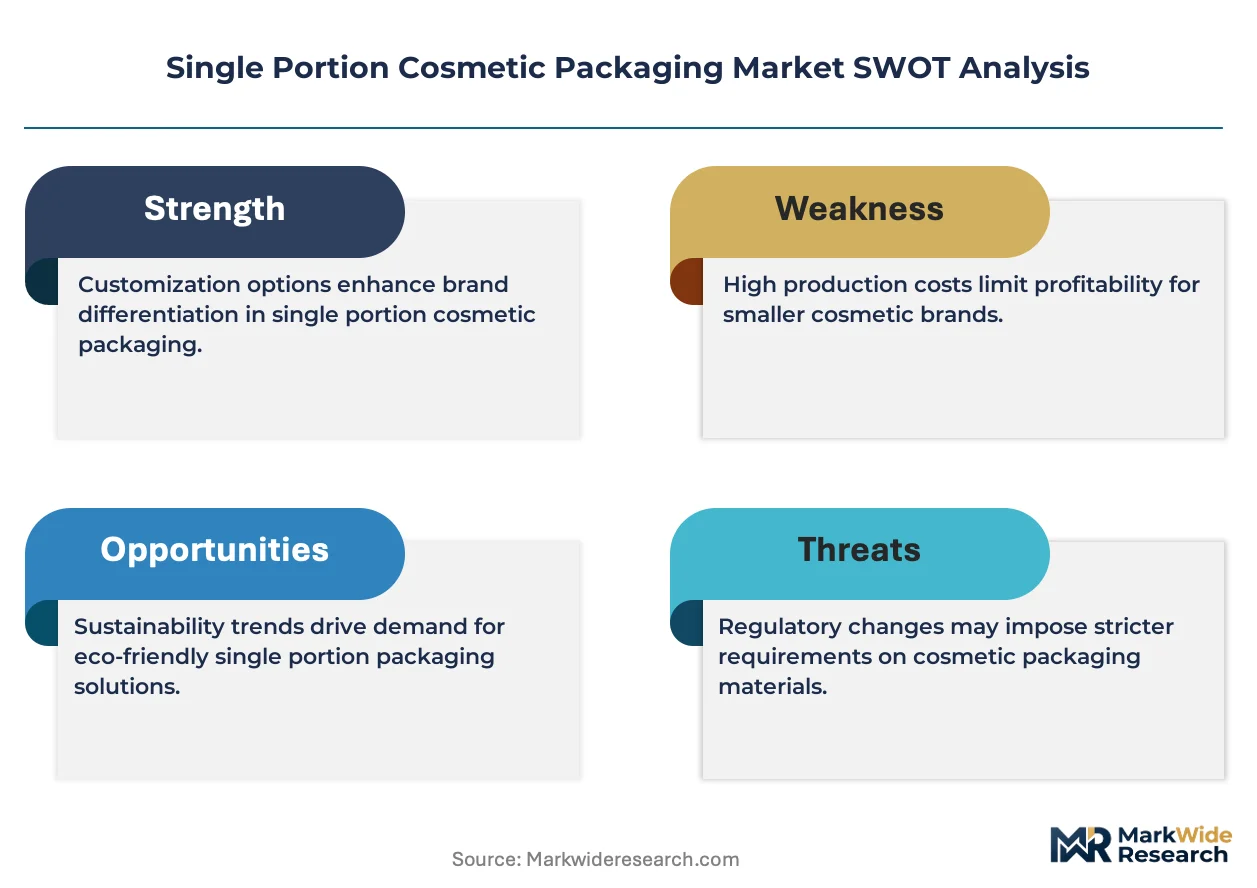
The EU's REACH chemicals framework and Single-Use Plastics Directive constrain material choices and end-of-life obligations for brands distributing across member states. China's SAMR enforces GB standards for cosmetic contact materials that foreign suppliers must certify before market entry. India's BIS marking requirements for imported plastic packaging add a compliance layer for brands targeting pharmacy and e-commerce channels. Stakeholders must monitor evolving extended producer responsibility schemes and substrate-specific recycling infrastructure gaps before committing to material transitions or geographic expansion.
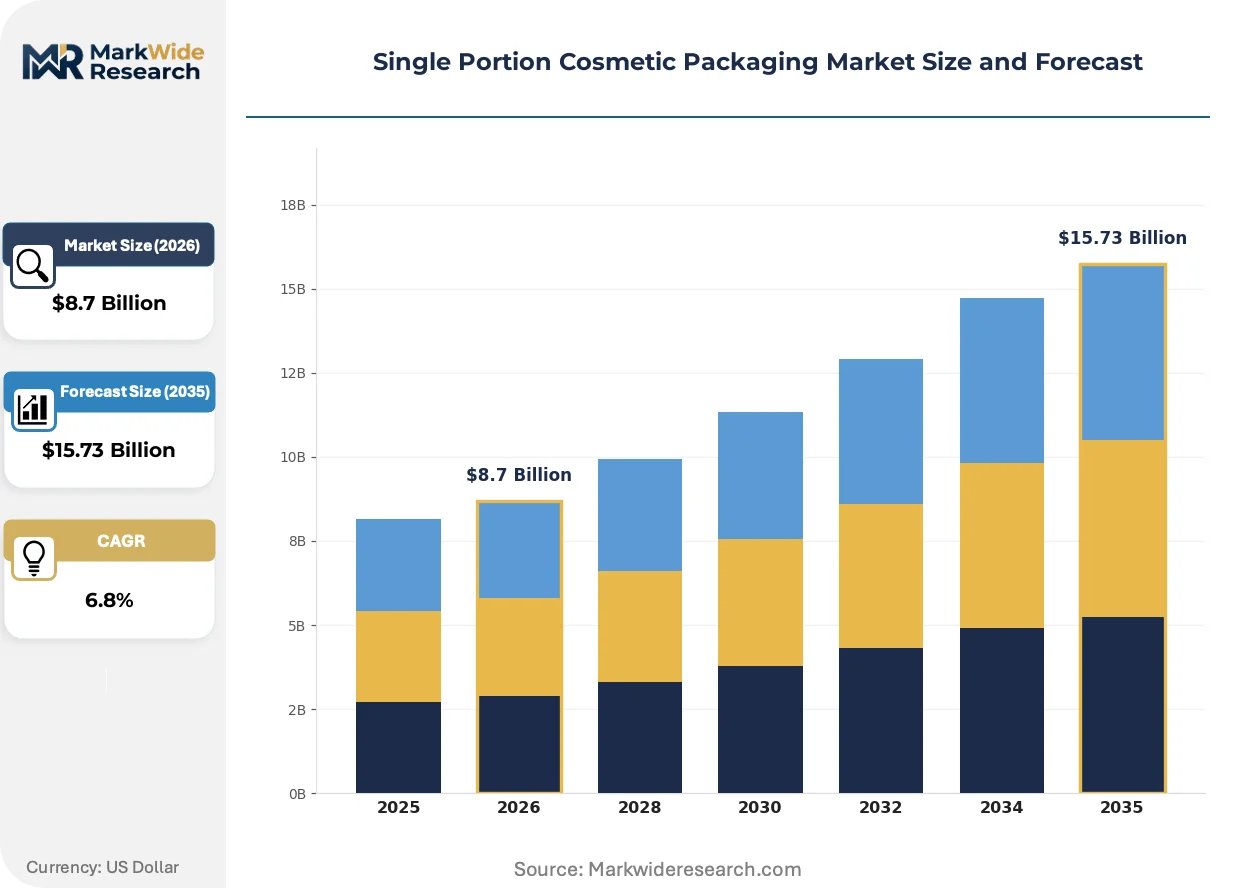
Market Dynamics
The EU's Single-Use Plastics Directive is forcing material transitions across European supply chains, while China's GB standards impose certification barriers on foreign entrants. These dual regulatory pressures are compressing margins for converters lacking captive R&D or regional compliance infrastructure.
Growth Catalysts
- Travel retail channel expansion:Premium beauty brands deploy single-dose formats for airport duty-free and hotel amenity programs, with South Korea's Incheon and Singapore's Changi hubs driving format standardization.
- REACH chemical compliance:EU restrictions on microplastics in rinse-off products push brands toward aluminum-laminate sachets as verified alternatives with established recycling pathways.
- K-beauty sampling economy:South Korean cosmetic houses distribute 8-12 unit sample kits through Olive Young and e-commerce platforms, normalizing single-portion as primary customer acquisition infrastructure.
Market Restraints
- Aluminum-laminate cost volatility:Multi-layer film structures carry 40-60% raw material premium over monolayer polyethylene, constraining adoption outside prestige skincare tiers.
- Recycling infrastructure gaps:Mixed-material sachets lack mechanical separation capacity in most municipal waste systems, exposing brands to extended producer liability under France's Citeo scheme and Germany's DSD.
- Biodegradable performance ceilings:PLA and PHA variants exhibit moisture barrier degradation within 90 days, disqualifying them from preservative-free and high-actives formulations.
Strategic Opportunities
- Pharmacy channel penetration:Germany's Apotheke network and France's parapharmacie segment underutilize single-dose formats for dermocosmetic trials, presenting white space against established blister pack conventions.
- Dual carbon alignment:China's MEE enforcement of carbon intensity targets creates procurement preference for domestic converters with verified renewable energy certificates.
- Subscription box integration:Personalized beauty services in the US and UK incorporate algorithm-selected single-portion samples, converting discovery into recurring revenue with lower return rates than full-size trials.
Industry Challenges
- Barrier film engineering talent scarcity:Coextrusion die design and adhesive lamination expertise concentrates among aging specialists in Italy's Bologna packaging cluster and Japan's Kansai region.
- SAMR certification timelines:China's GB standard testing for cosmetic contact materials extends 14-18 months for novel substrates, delaying product launches behind competitors with established approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Portion Cosmetic Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sachets, Tubes, Blisters, Jars Material Type: Plastic, Glass, Aluminum, Biodegradable Materials End User: Beauty Brands, Retail Chains, E-commerce Platforms, Subscription Services Distribution Channel: Online Retail, Drugstores, Specialty Stores, Supermarkets |
| Companies Covered | Albéa Group, Cosmogen, Amcor, Berry Global, TekniPlex, HCP Packaging, LF of America, PackingCosmetic, Aptar Beauty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Portion Cosmetic Packaging Market Evolving Landscape
Material science advances and regulatory stringency are bifurcating the competitive landscape between premium barrier solutions and cost-optimized formats. Three developments are restructuring investment priorities across the value chain.
Monolayer-to-multilayer film technology is bifurcating equipment requirements across converter tiers. High-barrier EVOH and nylon coextrusion lines demand €4-8 million capital commitments, accessible only to integrated groups with cosmetic-dedicated capacity. Mid-scale decorators face exclusion from preservative-free formulation contracts, compressing their addressable market to commodity shampoo and body wash sachets.
REACH microplastic restrictions are accelerating aluminum-laminate substitution in European rinse-off segments. France's ANSM guidance and Germany's BfR opinions converge on polymer film limitations for leave-on facial products. Prestige skincare houses are responding with foil-backed sachet specifications that command 25-35% unit price premiums over plastic equivalents.
Direct-to-consumer sampling programs are displacing traditional counter-based distribution in urban Chinese and Southeast Asian markets. Tmall and Lazada beauty verticals integrate single-portion SKUs into algorithmic recommendation engines, with Shanghai and Jakarta showing highest conversion rates from trial to full-size purchase. This channel compression is forcing contract packagers to install serialized printing and track-and-trace systems for anti-counterfeiting compliance.
Single Portion Cosmetic Packaging Market Segmentation
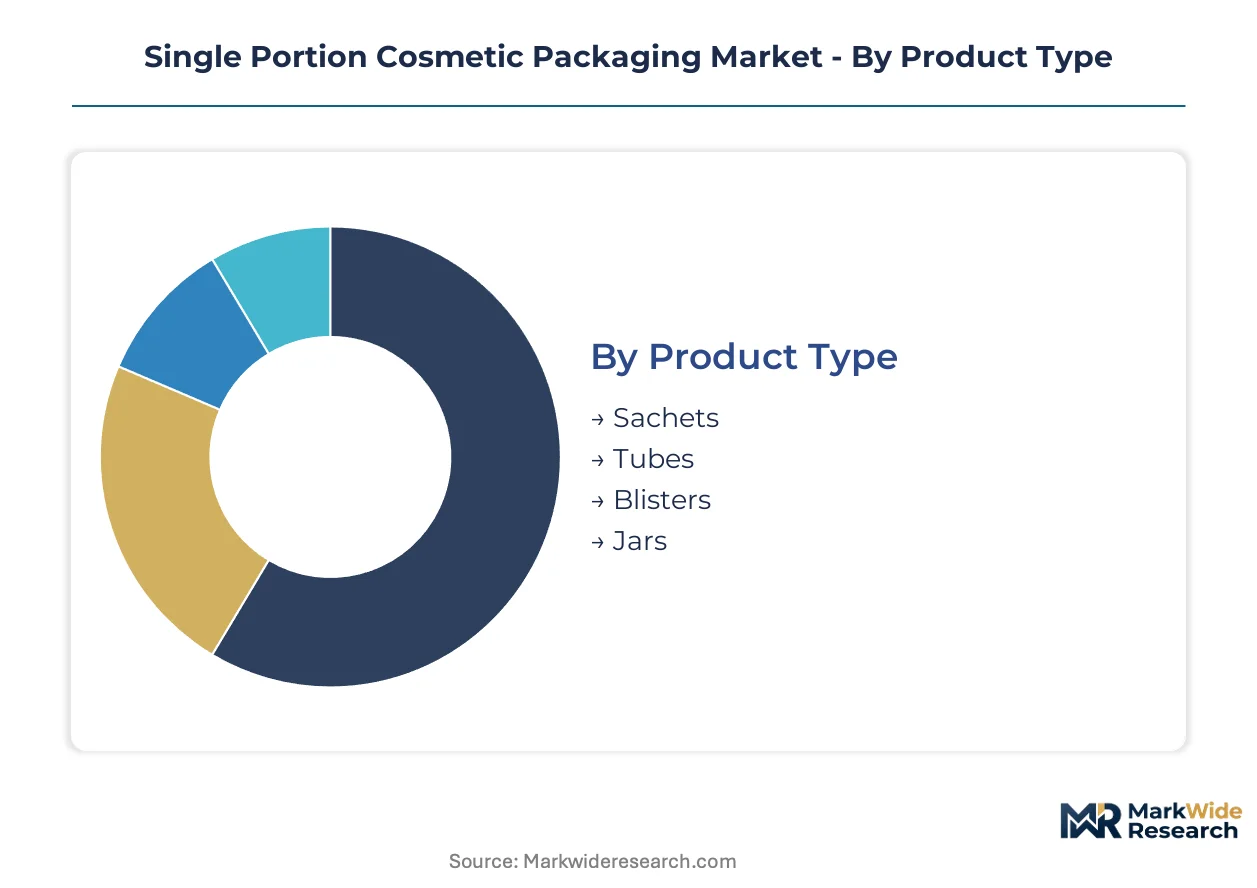
Single portion cosmetic packaging segments diverge sharply by barrier performance requirements and regulatory compliance burdens. Material choices and format specifications determine which converters can serve which end-use tiers, creating distinct competitive battlegrounds across the value chain.
Product Type:
REACH microplastic restrictions and ECHA guidance on rinse-off formulations are forcing format migrations across European supply chains.
- Sachets:Aluminum-laminate or multi-layer polyethylene films with heat-sealed edges dominate sampling and travel retail. South Korea's Olive Young and Tmall beauty verticals normalize 8-12 unit kits as customer acquisition infrastructure. Established volume favors sachets; emerging adoption favors biodegradable variants.
- Tubes:Extruded or laminated structures with crimp or flip-top seals serve premium skincare and dermocosmetic segments. Germany's Apotheke network and France's parapharmacie channel underutilize single-dose tubes against blister conventions.
- Blisters:Thermoformed PVC or PET cavities with lidding film target pharmacy and clinical trial applications. India's BIS marking requirements add compliance layers for imported plastic formats.
- Jars:Mono-material or dual-chamber pots accommodate thicker emulsions and mask formulations. China's SAMR enforces GB standard certification for cosmetic contact materials before market entry.
Tube and sachet formats command premium positioning; blister and jar segments compete on cost optimization.
Material Type:
Raw material cost spreads and end-of-life obligations are restructuring converter tier access by customer segment.
- Plastic:Monolayer polyethylene and polypropylene serve cost-sensitive shampoo and body wash sachets. Mixed-material plastic laminates face mechanical separation gaps in France's Citeo and Germany's DSD extended producer responsibility schemes.
- Glass:Borosilicate or soda-lime ampoules and vials target high-actives skincare and pharmaceutical-grade cosmetics. Specialty stores and prestige beauty houses specify glass for perceived purity and recyclability alignment.
- Aluminum:Foil laminates and pure aluminum pods deliver oxygen and light barrier performance for preservative-free formulations. EVOH coextrusion lines demand capital commitments accessible only to integrated groups with cosmetic-dedicated capacity.
- Biodegradable Materials:PLA and PHA variants exhibit moisture barrier degradation within 90 days, disqualifying them from high-actives and preservative-free applications. Subscription services and clean beauty brands pilot these formats despite performance ceilings.
Aluminum and glass anchor premium tier supply; plastic and biodegradable materials expand volume through cost accessibility.
End User:
Procurement sophistication and serialization requirements separate enterprise-grade from mid-market demand.
- Beauty Brands:L'Oréal, Estée Lauder, and K-beauty houses specify track-and-trace systems and serialized printing for anti-counterfeiting compliance. Direct-to-consumer sampling programs displace traditional counter-based distribution in urban Chinese and Southeast Asian markets.
- Retail Chains:Sephora, Ulta, and drugstore banners demand format standardization across SKU portfolios. Travel retail channel expansion at Incheon and Changi hubs drives sachet specification convergence.
- E-commerce Platforms:Tmall, Lazada, and Amazon beauty verticals integrate algorithm-selected single-portion samples with conversion tracking from trial to full-size purchase.
- Subscription Services:Birchbox, Ipsy, and regional equivalents incorporate personalized single-dose curation with lower return rates than full-size trials.
Beauty brands and e-commerce platforms concentrate technology investment; retail chains and subscription services prioritize format flexibility.
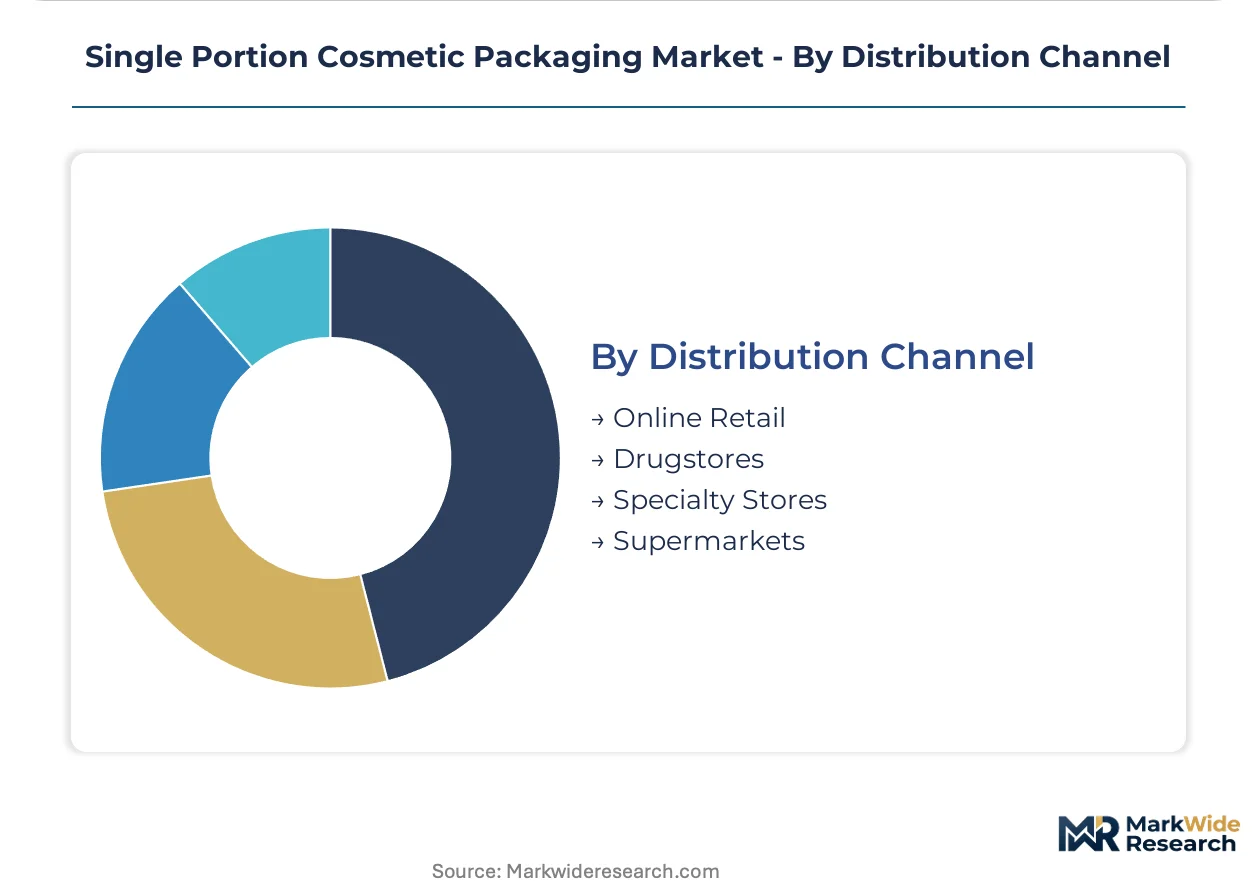
Distribution Channel:
Channel-specific compliance and logistics infrastructure determine regional packaging specifications.
- Online Retail:Direct-to-consumer shipments require damage-resistant formats with minimal dimensional weight. China's MEE carbon intensity targets create procurement preference for domestic converters with verified renewable energy certificates.
- Drugstores:CVS, Walgreens, and pharmacy banners favor blister and sachet formats for theft deterrence and shelf space efficiency. Germany's DSD packaging compliance shapes material specifications for multinational brands.
- Specialty Stores:Sephora and department store beauty halls emphasize premium unboxing experiences with foil-backed and glass formats. France's ANSM guidance on leave-on facial products accelerates aluminum-laminate substitution.
- Supermarkets:Mass-market grocery channels prioritize high-volume, low-unit-cost plastic sachets for shampoo and body wash trial sizes.
Online retail and specialty stores drive premium format adoption; drugstores and supermarkets anchor commodity volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. South Korean consumers absorb premium sachet pricing as customer acquisition cost, while Indian pharmacy channels demand sub-cent unit economics for mass-market trial formats.
South Korea
Olive Young and e-commerce platforms distribute 8-12 unit sample kits as primary customer acquisition infrastructure. MFDS cosmetic safety standards enforce rigorous stability testing for preservative-free formulations. Seoul's Gangnam district concentrates K-beauty headquarters where single-portion sampling budgets exceed traditional advertising spend.
Germany
Apotheke networks underutilize single-dose formats against established blister pack conventions for dermocosmetics. ECHA REACH microplastic restrictions accelerate aluminum-laminate substitution in rinse-off segments. Hamburg and Berlin host contract packagers serving French and Benelux beauty brands with DSD-compliant specifications.
China
Tmall beauty verticals integrate algorithm-selected single-portion samples with conversion tracking from trial to full-size purchase. SAMR GB standards for cosmetic contact materials impose 14-18 month certification timelines on novel substrates. Shanghai converters with MEE-verified renewable energy certificates secure procurement preference from carbon-conscious brands.
United States
Birchbox and Ipsy subscription services incorporate personalized single-dose curation with lower return rates than full-size trials. FDA cosmetic labeling requirements govern ingredient disclosure for interstate commerce. New Jersey and California packaging clusters install serialized printing systems for anti-counterfeiting compliance in direct-to-consumer channels.
India
E-commerce beauty platforms target pharmacy and tier-two city expansion with cost-optimized plastic sachets. BIS marking requirements for imported plastic packaging add compliance layers for multinational brands. Maharashtra and Gujarat converters scale mono-layer polyethylene capacity for shampoo and body wash trial formats.
Single Portion Cosmetic Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive extrusion capacity separating premium barrier suppliers from commodity decorators. Consolidation concentrates among European and Asian groups with cosmetic-dedicated molding assets. Three archetypes dominate: integrated film extruders with multi-layer coextrusion lines, precision toolers for luxury brand programs, and regional decorators serving mass-market sachet demand. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as mid-scale players seek technology licensing to bridge barrier film engineering gaps.
Among integrated packaging groups, Albéa Group exemplifies the extrusion-led archetype with European and Asian manufacturing presence. HCP Packaging occupies a position within the precision tooling tier, while TekniPlex represents multi-layer barrier technology specialization. These three anchors illustrate how capital intensity and regulatory compliance infrastructure stratify competitive access to preservative-free and high-actives formulation contracts.
| Leading Market Players |
|---|
| Albéa Group |
| Cosmogen |
| Amcor |
| Berry Global |
| TekniPlex |
| HCP Packaging |
| LF of America |
| PackingCosmetic |
| Aptar Beauty |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between K-beauty houses and European film converters lock in multi-year aluminum-laminate supply at fixed unit rates, insulating premium skincare brands from EVOH resin price swings while committing capital to dedicated coextrusion lines in South Korea and Germany.
Pricing Analysis
After-sales revenue from serialized printing and track-and-trace compliance services drives lifetime value for contract packagers serving direct-to-consumer channels. Three-tier pricing structure across premium aluminum-laminate, standard multi-layer plastic, and economy monolayer polyethylene segments reflects barrier performance and certification grade. Cost compression in standard-tier sachets is intensifying because India's BIS marking requirements add compliance overhead without commensurate price recovery. Mass-market shampoo and body wash trial formats show highest price sensitivity; preservative-free skincare commands lowest elasticity.
Supply Chain Analysis
Inventory lead times for EVOH coextrusion dies stretch 16-24 weeks, forcing converters to pre-position capacity before SAMR certification completion. Supply concentrates in South Korea, Germany, and China's Yangtze River Delta for high-barrier film production. Raw material dependencies include ethylene-vinyl alcohol copolymers, aluminum foil stock, and adhesive lamination chemistries. Single-source vulnerability in Italy's Bologna packaging cluster for die engineering expertise exposes European supply chains to specialist retirement waves. Distribution runs through brand-direct procurement for premium tiers and consolidated distributor networks for mass-market pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated K-beauty houses and algorithmic e-commerce platforms, fragmenting negotiating leverage among mid-scale converters lacking dedicated tooling investments or regional compliance infrastructure.
For Market Incumbents: Fortify barrier film engineering capabilities through captive R&D in South Korea's Seongnam cluster and Germany's Hamburg region to defend against emerging Chinese converters with MEE-verified renewable energy certificates. Deepen backward integration into aluminum foil lamination to capture margin compression from EVOH resin volatility. Prioritize SAMR pre-certification of novel substrates to compress 14-18 month approval timelines. For New Entrants and Emerging Players: Compliance-as-a-service gaps in India's BIS marking and China's GB standard navigation present white-space opportunities for regional specialists. Target Germany's Apotheke network for dermocosmetic tube formats where established blister conventions leave single-dose penetration below 15 percent. Pursue white-label serialization and track-and-trace bundling for Tmall and Lazada beauty verticals as primary go-to-market anchor. For Investors and Strategic Acquirers: Precision toolers with dedicated luxury brand sachet programs and established SAMR approval portfolios represent the most defensible acquisition archetype over the five-to-ten year horizon. Monitor ECHA guidance expansion from rinse-off to leave-on facial products as inflection signal for aluminum-laminate demand acceleration. Assess converter renewable energy certificate coverage before carbon intensity targets harden procurement preferences.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Foil Lamination | Captures 25-35% unit price premiums from prestige skincare houses specifying foil-backed sachets under France's ANSM guidance. |
| SAMR Pre-Certification Investment | Compresses 14-18 month GB standard timelines to outpace competitors launching preservative-free formulations in Shanghai. |
| Pharmacy Channel Expansion | Penetrates Germany's Apotheke and France's parapharmacie segments where single-dose dermocosmetic formats remain underutilized. |
| Renewable Energy Certificate Procurement | Secures MEE-verified preference from carbon-conscious brands enforcing dual carbon alignment across Chinese supply chains. |
| Serialized Printing Capability Installation | Enables anti-counterfeiting compliance for algorithmic Tmall and Lazada beauty verticals tracking trial-to-purchase conversion. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association reports through structured interviews with cosmetic packaging procurement directors, contract manufacturing executives, barrier film R&D specialists, and pharmacy channel category managers. Bottom-up demand modeling triangulates against top-down supply capacity assessments across South Korean, German, and Chinese production clusters.
Segmentation dimensions modeled include product type, material substrate, end-user archetype, and distribution channel across the analysis window. CAGRs derive from regression analysis of historical volume trajectories adjusted for regulatory inflection points and channel shift velocities. Forecast inputs incorporate EVOH resin price elasticity, SAMR certification pipeline data, and K-beauty sampling budget allocations.
Forecasts assume regulatory continuity in EU REACH, China's SAMR GB standards, and India's BIS marking regimes; material policy shifts would require re-modeling of substrate adoption curves and extended producer liability cost allocations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Make-Up Products Packaging Market
Cosmetic Packaging
Middle East and Africa Cosmetic Packaging Market
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Pump Bottle Market
Cosmetic Packaging
Europe Cosmetic Packaging Market
Cosmetic Packaging
Global Perfume Packaging Market
Cosmetic Packaging
Crimp Neck Serum Bottles Market
Cosmetic Packaging
Asia Pacific Cosmetic Packaging Market
Cosmetic Packaging
Eyeliner and Kajal Sculpting Pencil Packaging Market
Cosmetic Packaging
Middle East and Africa Personal Care Packaging Market
Cosmetic Packaging
Lip Gloss Tube Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market
Cosmetic Packaging
Global Cosmetic Packaging Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Skin Care Packaging Market
Cosmetic Packaging
Beauty Supplements Packaging Market