
 Beauty Supplements Packaging Market | 2026-2036
Beauty Supplements Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Beauty Supplements Packaging Market Insights
Asset-light contract manufacturing and third-party logistics leasing is rewriting competitive entry barriers for mid-tier beauty brands that previously lacked capital for proprietary packaging lines. Albéa Group leverages its integrated tube and bottle molding capacity to serve collagen and anti-aging supplement lines across European pharmacies. Amcor sustains global film and laminate supply for sachet formats that dominate hair health and detox applications in Asian wellness channels. AptarGroup differentiates through precision dispensing closures that protect active ingredients in skin-brightening capsules.
Beauty supplements packaging encompasses primary and secondary enclosures engineered to protect ingestible formulations from moisture, oxygen, and UV degradation through barrier specifications such as oxygen transmission rates below 0.1 cc per square meter per day and multilayer coextrusion processes. Blister packs and sachets lead unit volume due to their compatibility with single-serving collagen and detox regimens, though bottles and jars command higher margin pools in premium anti-aging segments where glass and aluminum reinforce perceived efficacy. Biodegradable materials represent the fastest-growing structural shift as regulatory deadlines in the European Union and California compel transitions from conventional plastic films to paperboard and metalized alternatives.
The FDA's dietary supplement labeling requirements and the EU Packaging and Packaging Waste Regulation shape material selection, barrier claims, and recyclability mandates across North American and European supply chains. China's SAMR and NMPA enforce stricter registration for imported beauty supplements, forcing packaging adaptations that accommodate Mandarin labeling and batch-traceability codes. Stakeholders must monitor diverging extended producer responsibility frameworks and decide whether to regionalize packaging specifications or pursue unified global formats that satisfy the most stringent jurisdiction.
Market Dynamics
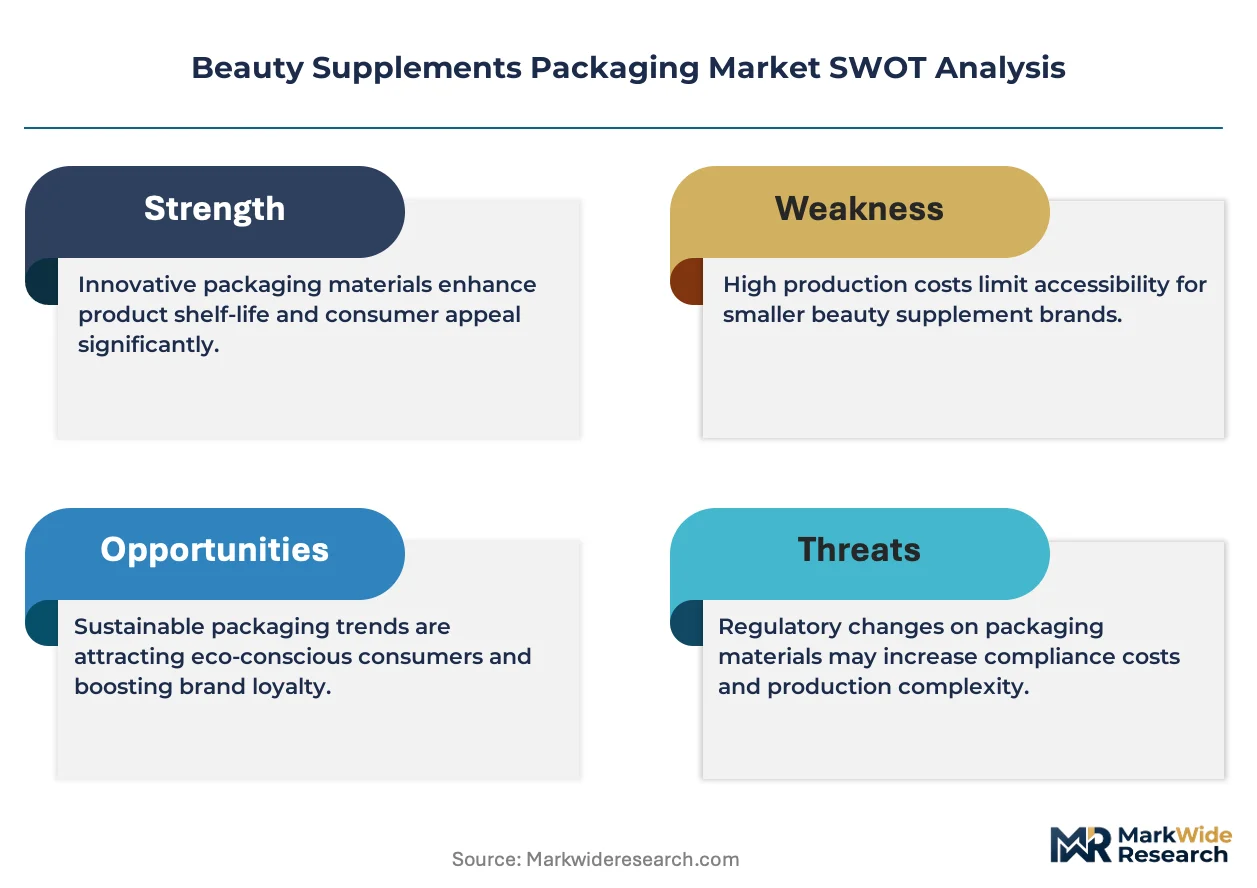
The EU Green Deal's packaging waste directives are compressing material choice sets and forcing rapid conversion from multilayer films to mono-material and fiber-based formats across European supply chains.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are pulling investment into paperboard and aluminum mono-material lines that simplify end-of-life processing for collagen sachets and capsule bottles.
- Single-serving wellness regimens:Daily-dose collagen and detox protocols are normalizing blister packs and stick packs as the default primary format for acquisition and retention programs.
- South Korea:Dense urban logistics and high supplement consumption per capita are accelerating demand for compact, shelf-stable unit-dose packaging with extended barrier protection.
Market Restraints
- Aluminum and bio-based resin input costs:Volatility in metal and agricultural feedstock markets is compressing margin on sustainable format transitions that brands have already committed to publicly.
- German converter concentration:Specialized mono-material coextrusion capacity for oxygen barrier below 0.1 cc/m²/day remains captive to a narrow supplier base in Central Europe.
- Technical limitation in paper barrier:Fiber-based alternatives struggle to match the moisture and UV protection of metallized films for hygroscopic ingredients like hyaluronic acid and certain probiotic strains.
Strategic Opportunities
- German pharmacy channel:Underpenetrated relative to direct-to-consumer, this regulated retail tier rewards compliant child-resistant and senior-friendly closure designs with preferential shelf placement.
- Digital printing convergence with track-and-trace:Variable data integration enables batch-level authentication and personalized regimen packaging without plate changeover costs.
- California SB 54 mandates:Extended producer responsibility frameworks create first-mover advantage for brands that regionalize recyclable formats ahead of 2032 compliance deadlines.
Industry Challenges
- Multilayer film decommissioning:Existing lamination assets require write-downs or retrofitting as brands exit non-recyclable structures, straining capital allocation for mid-tier players.
- SAMR registration timelines:China's batch-traceability and Mandarin labeling requirements extend product launch cycles by 12-18 months for imported beauty supplements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beauty Supplements Packaging Market |
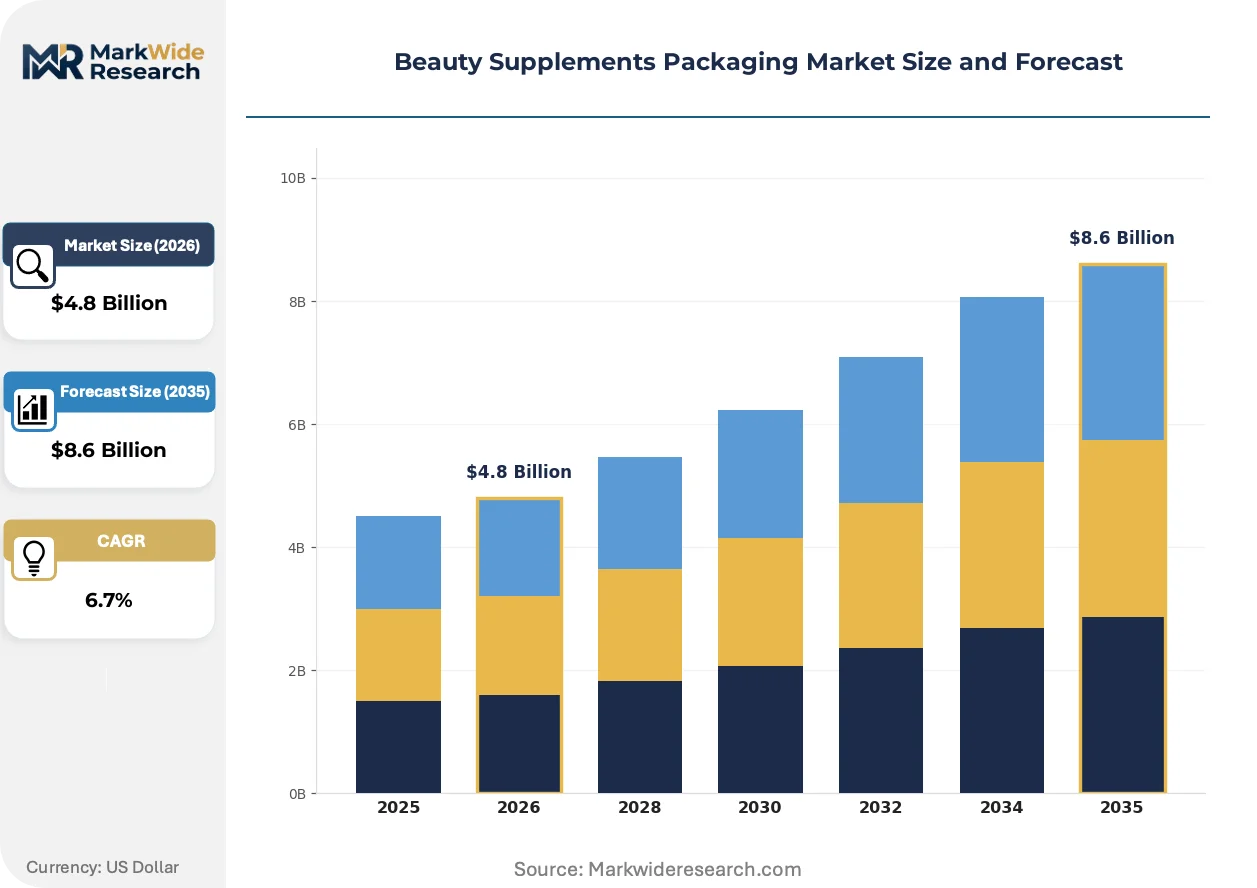
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottle, Blister, Sachet, Tube, Jar, Box Material: Plastic, Glass, Aluminum, Paperboard, Biodegradable, Metalized Film Application: Anti-Aging, Skin Brightening, Hair Health, Nail Strengthening, Collagen Boosting, Detox End User: Pharmacies, Wellness Centers, Cosmetic Clinics, Direct-to-Consumer Platforms, Specialty Stores |
| Companies Covered | Albéa Group, Amcor, AptarGroup, Berry Global, Gerresheimer, HCP Packaging, Huhtamaki, Quadpack Industries, Silgan Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beauty Supplements Packaging Market Trends and Innovations
Active packaging intelligence and substrate conversion are redrawing technical specifications as brands balance sensory premiumization against circularity mandates.
Near-field communication (NFC) tags embedded in secondary cartons are digitizing adherence monitoring and reorder triggers for subscription supplement programs. Premium anti-aging lines in South Korea and Germany are piloting these connected packs to capture consumption data and reduce churn. The technology is digitizing the traditional unidirectional supply chain into a feedback loop between patient, pharmacy, and brand.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) are eliminating grease-resistant coatings previously standard in paperboard supplement cartons. European converters are accelerating migration to clay-based and bio-wax barrier treatments that maintain oil resistance without fluorinated chemistry. Blister packs containing fish-derived collagen and omega formulations face the tightest reformulation timelines given direct food-contact exposure pathways.
Subscription bundling is consolidating individual SKUs into curated regimen kits that ship in consolidated outer packs rather than single-unit primary packaging. Direct-to-consumer brands in the United States are displacing pharmacy-centric bottle-and-carton conventions with pouch-based 30-day assortments. This pattern concentrates most visibly in hair health and skin-brightening verticals where trial-to-commitment cycles have compressed from quarterly to monthly.
Beauty Supplements Packaging Market Segmentation
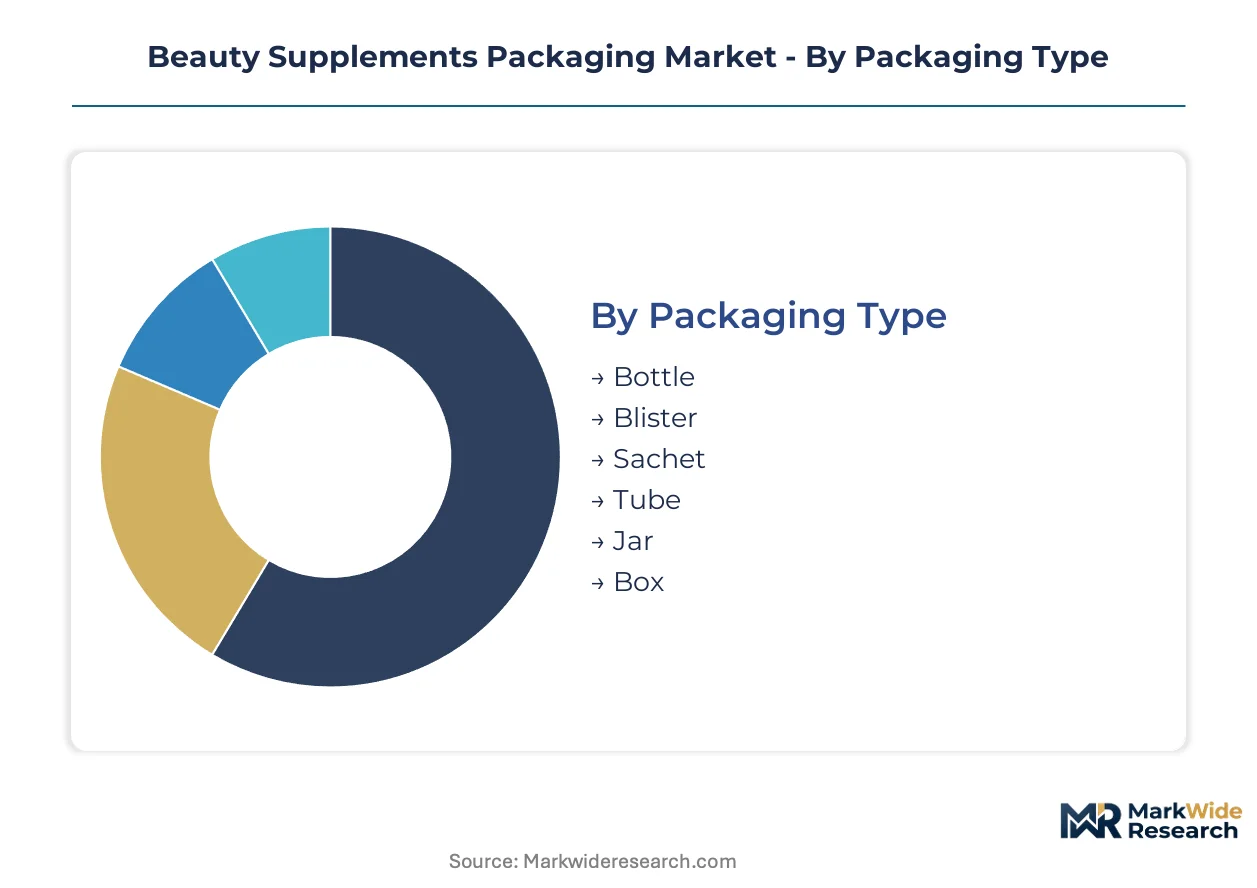
Segmentation in beauty supplements packaging reveals how formulation chemistry, distribution channel requirements, and regulatory exposure shape enclosure specifications. Each dimension carries distinct barrier, labeling, and handling mandates that determine material selection and unit economics.
Packaging Type:
Mature formats dominate unit volume while emerging structures capture premium positioning and compliance-driven conversions.
- Bottle:HDPE and PET containers with desiccant closures protect hygroscopic capsules and tablets through multi-year shelf lives. Demand clusters in United States pharmacies and German apothecens where child-resistant certification and batch-traceability codes are mandatory for collagen and anti-aging SKUs.
- Blister:Thermoformed PVC or aluminum lidding delivers unit-dose precision for probiotic and enzyme formulations requiring moisture barriers below 0.1 cc/m²/day. South Korean wellness channels and United States subscription services drive specification intensity for calendar-pack adherence programs.
- Sachet:Flexible stick packs dominate single-serving collagen and detox powders in Asian e-commerce logistics.
- Tube:Laminated squeeze formats serve liquid botanical extracts and oil-based serums in cosmetic clinic settings.
- Jar:Wide-mouth glass and aluminum enclosures command premium positioning for powder-based beauty supplements in specialty retail.
- Box:Secondary paperboard cartons carry regulatory labeling and NFC-enabled authentication layers for direct-to-consumer shipments.
Bottle and blister together handle the majority of throughput; sachet formats are expanding most quickly on share as single-serving regimens displace bulk purchasing.
Material:
Cost tiers separate commodity substrates from engineered barrier systems and emerging bio-based alternatives.
- Plastic:PET, HDPE, and PP resins provide cost-efficient formability for high-volume bottle and jar production across mass-market channels. United States direct-to-consumer brands and German pharmacy distributors specify recycled-content grades to satisfy California SB 54 and EU Packaging Waste Regulation mandates.
- Glass:Amber and cobalt silica containers deliver UV blocking and premium tactile properties for anti-aging and skin-brightening lines. South Korean cosmetic clinics and United States specialty retailers drive specification for perceived efficacy and shelf differentiation.
- Aluminum:Lightweight metal bottles and tubes offer complete oxygen and light barriers for oxidation-sensitive omega and antioxidant formulations.
- Paperboard:Fiber-based cartons and rigid boxes serve secondary and tertiary packaging with increasing substitution for plastic films under REACH PFAS restrictions.
- Biodegradable:PLA, PHA, and cellulose-derived structures represent the steepest expansion trajectory as EU Green Deal deadlines approach.
- Metalized Film:Metallized PET and OPP laminates retain dominance in sachet barriers despite recyclability challenges.
Plastic and glass absorb the bulk of current material spend; biodegradable alternatives are climbing the fastest as regulatory deadlines force format transitions.
Application:
Customer type and regimen duration determine packaging complexity, from trial-sized sachets to committed-use bottle systems.
- Anti-Aging:Premium glass bottles and aluminum jars with precision dispensing closures protect retinol, resveratrol, and peptide formulations from oxidation. German pharmacies and South Korean cosmetic clinics specify child-resistant and senior-friendly designs for regulated retail placement.
- Collagen Boosting:Single-serving sachets and blister calendars dominate powder and capsule formats for daily adherence protocols. United States subscription services and South Korean urban logistics channels drive compact, shelf-stable unit-dose demand.
- Skin Brightening:UV-protective amber glass and aluminum tubes serve glutathione and vitamin C derivatives sensitive to light degradation.
- Hair Health:Bottle formats with desiccant closures predominate for biotin and keratin tablet regimens in pharmacy and specialty retail.
- Nail Strengthening:Small-format blister packs and jars target trial-to-commitment conversion in wellness center sampling programs.
- Detox:Multi-compartment blister packs and sachet assortments support intermittent fasting and cleanse protocols in direct-to-consumer channels.
Anti-aging and collagen applications generate the highest packaging value per unit; skin brightening is gaining share fastest as pigmentation concerns expand across demographics.
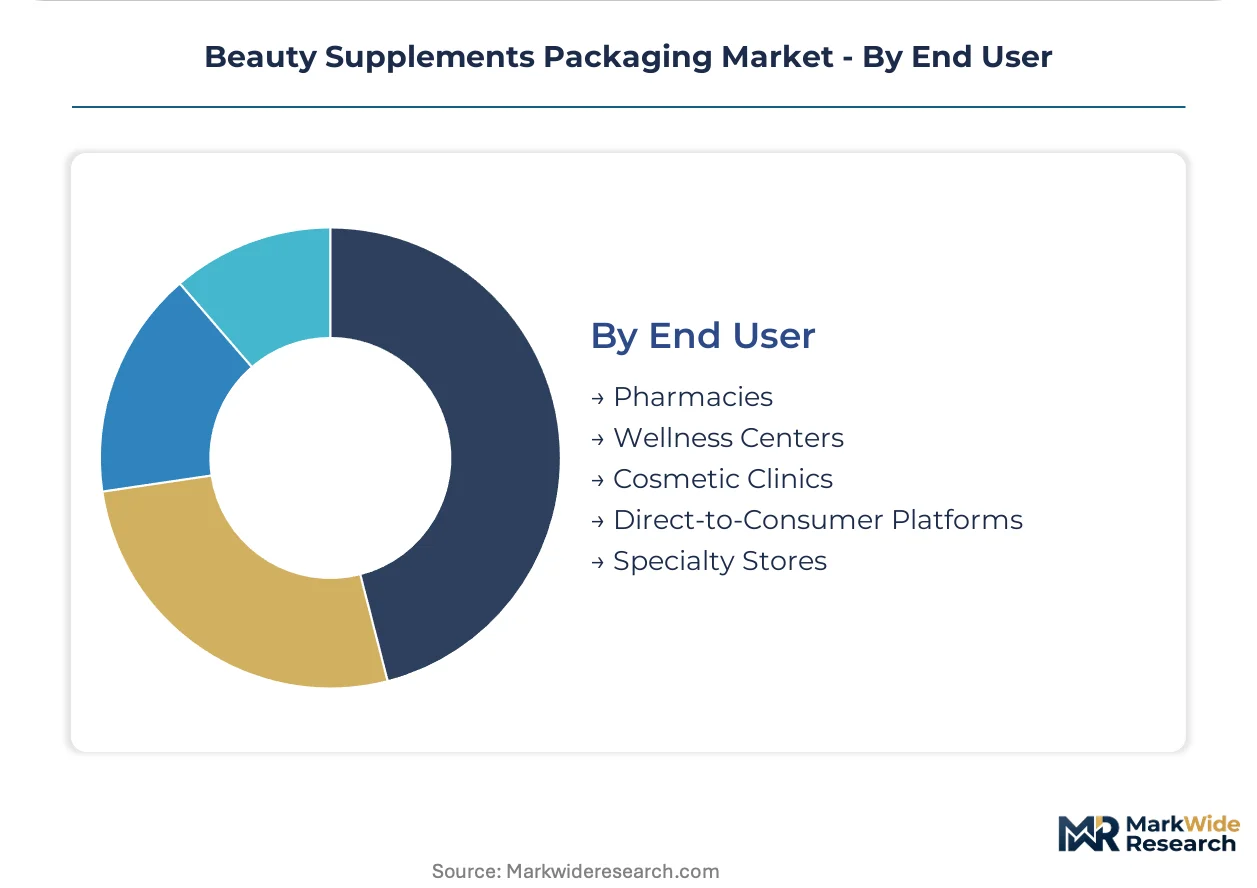
End User:
Channel-specific handling requirements and regulatory exposure create divergent specification paths for identical formulations.
- Direct-to-Consumer Platforms:Subscription-optimized pouch assortments and NFC-enabled cartons support automated replenishment and adherence tracking. United States e-commerce brands displace traditional bottle conventions with consolidated 30-day regimen kits for hair health and skin-brightening verticals.
- Pharmacies:Child-resistant bottles, tamper-evident seals, and batch-traceability labeling satisfy FDA and EU regulatory requirements for collagen and anti-aging SKUs. German apothecens reward compliant closure designs with preferential shelf placement.
- Wellness Centers:Sampling-sized sachets and single-blister units support trial conversion for detox and nail-strengthening protocols.
- Cosmetic Clinics:Premium glass and aluminum enclosures with precision dispensing reinforce clinical credibility for skin-brightening and anti-aging lines.
- Specialty Stores:Aesthetically differentiated jars and tubes with tactile finishes target gift-market and discovery purchasing in South Korean and United States urban retail.
Direct-to-consumer and pharmacy channels together account for the dominant packaging volume; wellness centers are expanding most quickly as sampling-driven acquisition models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in beauty supplements packaging favor net exporters with integrated converter ecosystems. Germany and the United States run structural surpluses in high-barrier mono-material formats. China and South Korea balance domestic consumption against regional re-export hubs.
United States
Direct-to-consumer subscription volumes drive specification intensity for pouch-based regimen kits and NFC-enabled cartons. California SB 54 mandates accelerate converter investment in recyclable mono-material lines ahead of 2032 deadlines. Los Angeles and New Jersey logistics corridors host third-party fulfillment centers that consolidate 30-day supplement assortments for hair health and skin-brightening verticals.
Germany
Pharmacy channel compliance requirements concentrate demand for child-resistant closures and batch-traceability labeling in collagen and anti-aging segments. EU Packaging and Packaging Waste Regulation recyclability targets pull capital into aluminum mono-material bottle lines. Bavarian and North Rhine-Westphalian converter clusters specialize in oxygen barrier below 0.1 cc per square meter per day for hygroscopic probiotic formulations.
South Korea
Dense urban logistics and high per-capita supplement consumption compress packaging formats toward compact, shelf-stable unit-dose designs. MFDS registration protocols enforce Mandarin-compatible labeling and traceability codes for cross-border e-commerce shipments. Seoul Capital Area contract manufacturers supply blister and sachet formats for regional re-export to Southeast Asian wellness channels.
China
SAMR and NMPA registration timelines extend launch cycles by 12-18 months for imported beauty supplements, forcing packaging adaptations for batch-traceability and localized labeling. Yangtze River Delta converters serve domestic collagen and detox powder brands with multilayer film capacity that faces pressure from EU Green Deal-linked export compliance requirements. Pearl River Delta logistics hubs handle cross-border e-commerce fulfillment for skin-brightening and anti-aging SKUs.
France
REACH restrictions on PFAS chemistry eliminate grease-resistant coatings from paperboard supplement cartons, accelerating migration to clay-based barrier treatments. Paris-region cosmetic clinics drive premium glass and aluminum enclosure specifications for clinical credibility in anti-aging lines. Auvergne-Rhône-Alpes packaging converters pilot bio-wax alternatives for fish-derived collagen blister formats facing direct food-contact exposure pathways.
Beauty Supplements Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in barrier films, precision closures, and substrate engineering. The vendor base organizes around three functional layers: integrated tube-and-bottle molders, global film-and-laminate suppliers, and dispensing closure engineers. Consolidation pressure concentrates at the mid-tier where contract manufacturing access lowers entry barriers for emerging beauty brands. Dominant competitive moves include geographic expansion into regulated pharmacy channels and portfolio diversification toward mono-material recyclable formats.
Among diversified packaging conglomerates, Albéa Group, Amcor, and AptarGroup exemplify distinct strategic archetypes. Albéa anchors the integrated molding tier with captive tube and bottle capacity serving European pharmacy collagen lines. Amcor occupies the global substrate tier with film and laminate supply networks spanning Asian wellness channels. AptarGroup sits within the precision dispensing tier, engineering active-ingredient protection for premium capsule formats. These three structures capture the competitive segmentation between form-factor integration, materials scale, and closure intelligence.
| Leading Market Players |
|---|
| Albéa Group |
| Amcor |
| AptarGroup |
| Berry Global |
| Gerresheimer |
| HCP Packaging |
| Huhtamaki |
| Quadpack Industries |
| Silgan Holdings |
| Others |
Pricing and Supply Chain Analysis
Bavarian and North Rhine-Westphalian converter clusters anchor European oxygen-barrier capacity below 0.1 cc per square meter per day, translating captive mono-material expertise into pricing power over collagen and probiotic packaging lines serving German pharmacies and direct-to-consumer brands.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that secures volume commitments against aluminum and bio-based resin volatility. Three-tier pricing structure across premium, standard, and economy levels separates glass-and-aluminum anti-aging enclosures from mass-market PET bottles and entry-level sachet films. Cost compression in biodegradable formats is intensifying because agricultural feedstock markets swing with climate volatility. Direct-to-consumer subscription services exhibit lowest price sensitivity, while mass-market pharmacy distributors negotiate hardest on per-unit resin costs.
Supply Chain Analysis
Upstream bio-resin cultivation and metallized film extrusion concentrate supply planning across Germany, China, and South Korea. Converter networks draw from aluminum smelter output in Bavaria, PET resin from Yangtze River Delta petrochemical complexes, and PLA feedstock from Midwestern agricultural processors. Single-source vulnerability in German mono-material coextrusion capacity threatens format conversion timelines for EU Green Deal compliance. Distribution runs through third-party logistics hubs in Los Angeles, New Jersey, and Seoul Capital Area that consolidate subscription regimen kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beauty supplements packaging functions as a service-attach opportunity where NFC-enabled adherence tracking and automated replenishment layers expand faster than primary enclosure hardware, embedding recurring revenue into physical product relationships.
For Market Incumbents: Build regulatory compliance moats by securing child-resistant closure certifications for German pharmacy placement and California SB 54 recyclable format approvals ahead of 2032 deadlines. Add captive mono-material coextrusion capacity in Central Europe to offset converter concentration risk. Defend against mid-tier contract manufacturers by controlling precision dispensing closure IP for oxidation-sensitive actives.
For New Entrants and Emerging Players: German pharmacy channels remain underpenetrated relative to direct-to-consumer saturation, offering preferential shelf access for compliant packaging designs. Target wellness center sampling programs with trial-sized sachet formats for detox and nail-strengthening verticals. Enter through digital printing partnerships that enable personalized regimen packaging without plate investment.
For Investors and Strategic Acquirers: Long-term, this sits as a circularity infrastructure play because EU Packaging and Packaging Waste Regulation recyclability mandates force sustained capital deployment into mono-material and fiber-based capacity. Acquisition candidates include mid-tier converters with German pharmacy channel relationships and bio-barrier R&D pipelines. Watch for aluminum price volatility spikes as inflection signals for bio-based substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Capacity Expansion | EU Green Deal deadlines force conversion from multilayer films to recyclable aluminum and paperboard formats. |
| Precision Dispensing Closure Development | AptarGroup-style active-ingredient protection commands premium positioning in skin-brightening capsule lines. |
| Digital Printing Integration | Variable data enables batch-level authentication and personalized regimen packaging without plate changeover costs. |
| Subscription Logistics Partnership | Third-party fulfillment consolidation of 30-day pouch kits displaces traditional bottle-and-carton conventions. |
| Bio-Barrier R&D Investment | REACH PFAS restrictions accelerate migration to clay-based and bio-wax treatments for paperboard cartons. |
Research Methodology
Operator-level perspectives from packaging procurement managers at direct-to-consumer brands, pharmacy category buyers, converter plant engineers, and logistics fulfillment directors anchored the qualitative base. Secondary validation drew from FDA dietary supplement labeling guidance, EU Packaging and Packaging Waste Regulation filings, SAMR registration databases, and customs trade data on aluminum and bio-resin flows. Bottom-up capacity assessments across German, Chinese, and South Korean converter clusters triangulated against top-down demand modeling from subscription service growth and pharmacy channel expansion.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning packaging type, material substrate, application vertical, and end-user channel. Modeled inputs included oxygen transmission rate specifications, desiccant closure adoption curves, and NFC-enabled carton penetration in premium anti-aging lines. CAGRs derived from regression analysis of historical format transitions and regulatory deadline impacts on capital deployment cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated beauty conglomerates or sudden bio-resin breakthroughs would shift outcomes. Cross-checking against EU extended producer responsibility compliance tracking and California SB 54 implementation timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Middle East and Africa Cosmetic Packaging Market
Cosmetic Packaging
Europe Cosmetic Packaging Market
Cosmetic Packaging
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic and Toiletry Containers Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market
Cosmetic Packaging
Latin America Personal Care Packaging Market
Cosmetic Packaging
Lotion Tubes Market
Cosmetic Packaging
North America Cosmetic Packaging Market
Cosmetic Packaging
Europe Personal Care Packaging Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Lip Gloss Tube Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
Hair Care Packaging Market
Cosmetic Packaging
Cream Jars Market