
 Asia Pacific Offshore Seismic Services Market | 2026-2036
Asia Pacific Offshore Seismic Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Offshore Seismic Services Market Outlook
The EU Green Deal's extraterritorial carbon border pressure is repositioning Asia Pacific offshore seismic contracting toward lower-emission survey fleets. BGP Inc. leverages its integrated land-sea processing network across the South China Sea. Shearwater GeoServices anchors its position through advanced streamer technology leadership. Fugro NV differentiates via geotechnical survey specialization in frontier basins.
Asia Pacific offshore seismic services encompass subsurface imaging through controlled acoustic energy propagation, typically employing air gun arrays generating 200-250 decibel impulses and ocean bottom seismometers recording reflected wavefields to map hydrocarbon reservoirs, carbon storage formations, and wind farm foundations. 3D seismic acquisition commands the largest revenue share due to complex pre-salt and deep-water prospects, while 4D seismic monitoring represents the fastest-expanding service category as field operators prioritize reservoir optimization over greenfield discovery. Streamer technology dominates offshore deployment for efficiency in open-water environments, though ocean bottom seismometers capture premium pricing in obstructed or shallow-water zones where towed arrays face operational constraints.
METI's offshore facility safety regulations in Japan, China's MEE marine environmental impact assessments, and Australia's NOPSEMA well integrity standards collectively elevate compliance costs while favoring contractors with certified quality management systems. These frameworks mandate real-time emissions monitoring, acoustic mitigation protocols, and decommissioning sureties that reshape procurement criteria across national oil companies and international majors. Stakeholders must weigh capital allocation between proprietary sensor R&D and fleet decarbonization partnerships as regulatory thresholds tighten across the region's most active licensing rounds.
Market Dynamics
Japan's METI vessel certification mandates and Australia's NOPSEMA well integrity standards are forcing contractors to reallocate capital from fleet expansion toward emissions monitoring systems and acoustic mitigation protocols.
Growth Catalysts
- Deep-water pre-salt exploration:Australia's North West Shelf and Timor Sea concessions drive demand for 3D seismic acquisition as operators target complex reservoir geometries below salt formations.
- Carbon storage site characterization:Japan's revised offshore safety standards under METI accelerate permitting for depleted gas field conversions, creating new survey requirements for CO2 injection integrity verification.
- Ocean bottom seismometer deployment:Obstructed shallow-water zones in Southeast Asian basins command premium pricing for stationary sensor arrays where towed streamer operations face operational constraints.
Market Restraints
- Air gun array cost volatility:Compressed air system maintenance and high-pressure component replacement cycles create unpredictable operational expenditure profiles for survey contractors.
- Specialized vessel supply concentration:Limited shipyard capacity in Singapore and South Korea for seismic-specific hull construction extends delivery timelines and concentrates bargaining power with regional lessors.
- Acoustic emission regulatory friction:China's MEE marine environmental impact assessments impose seasonal blackout periods that compress viable survey windows in the South China Sea.
Strategic Opportunities
- Philippines frontier basin opening:Unlicensed blocks in the Reed Bank and Sulu Sea offer first-mover positioning for contractors with pre-positioned equipment and established local agent networks.
- 4D reservoir monitoring services:Mature fields across Indonesia's Mahakam Delta and Malaysia's Sarawak waters create recurring revenue streams as operators prioritize production optimization over greenfield discovery.
- Wind farm foundation geophysics:Australia's offshore renewable energy zone declarations under the Offshore Electricity Infrastructure Act mandate subsurface imaging for turbine pile installation planning.
Industry Challenges
- Geophysicist talent scarcity:Specialized expertise in full-waveform inversion and depth migration processing concentrates among aging professionals in Perth and Kuala Lumpur, constraining crew rotation flexibility.
- Real-time emissions certification delays:METI's continuous monitoring system approval process extends vessel commissioning timelines by four to six months for Japan-flagged operations.
- Legacy data format integration:Proprietary seismic data structures from 1990s vintage surveys resist automated ingestion into modern cloud-based processing platforms, fragmenting interpretation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Offshore Seismic Services Market |
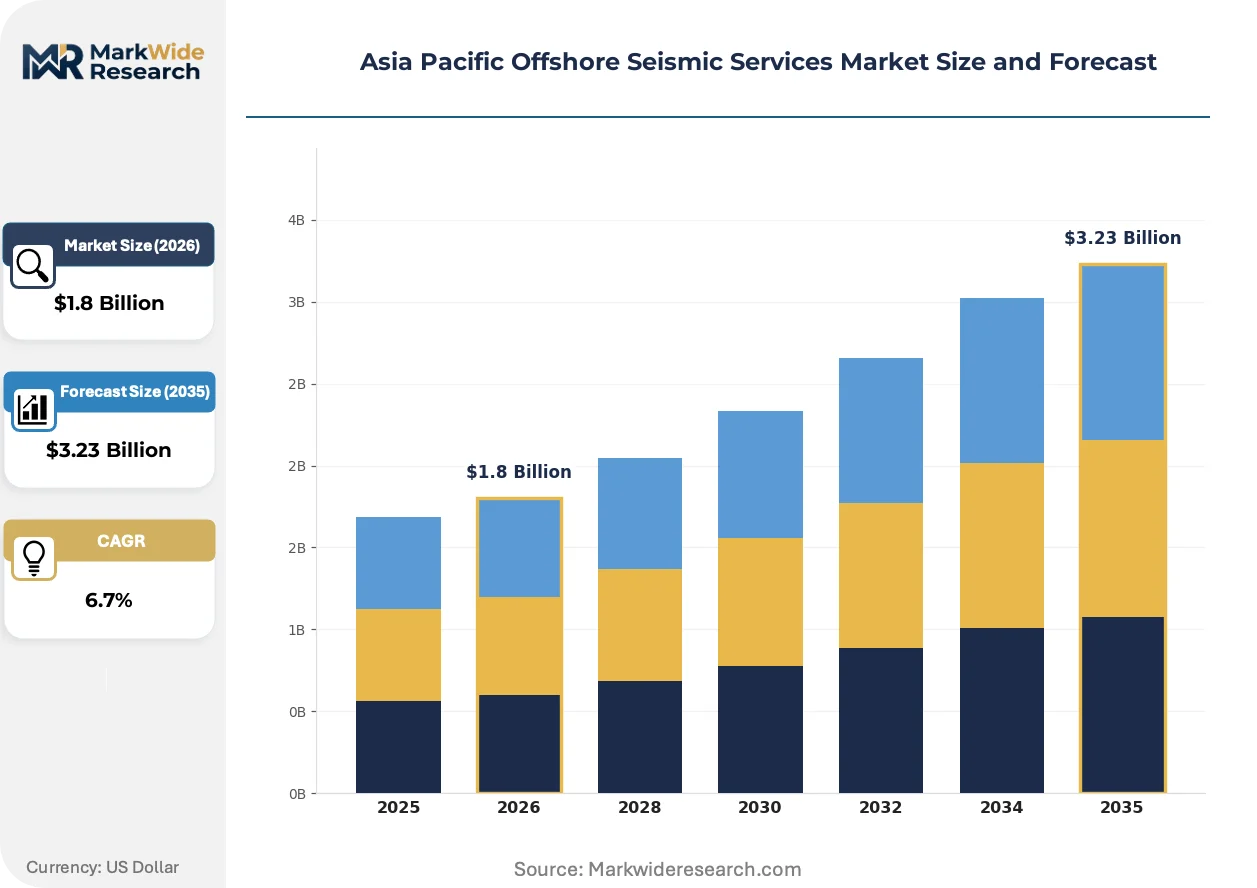
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: 2D Seismic, 3D Seismic, 4D Seismic, Data Processing Technology: Air Gun, Vibroseis, Ocean Bottom Seismometers, Streamer Technology End User: Oil & Gas, Renewable Energy, Geotechnical, Environmental Studies Deployment Model: Onshore, Offshore, Shallow Water, Deep Water |
| Companies Covered | PGS ASA, BGP Inc., Schlumberger Ltd, SAExploration Holdings Inc, Halliburton Company, China Oilfield Services Limited, CGG SA, Shearwater GeoServices, Fugro NV, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Offshore Seismic Services Market Strategic Shifts
Digital acquisition systems and regulatory compliance automation are compressing project timelines while elevating technical performance thresholds across Asia Pacific contracting.
Variable-depth streamer technology is unifying high-resolution shallow imaging with deep-target penetration in single-pass operations. National oil companies in Vietnam and Brunei are mandating these configurations for new licensing rounds. The technology is unifying previously separate survey campaigns into consolidated acquisition programs, reducing vessel days per block by approximately one-third.
METI's offshore facility safety regulations now require real-time acoustic source level monitoring with automated shutdown triggers. Japanese operators have responded by retrofitting legacy air gun controllers with integrated hydrophone feedback loops. Deep-water contractors face the steepest compliance costs, with some redirecting Japan-bound vessels to Australian NOPSEMA jurisdictions during regulatory gap periods.
Service unbundling now separates data acquisition from processing and interpretation. International majors in Australia's North West Shelf increasingly contract raw shot gathers to specialized processing boutiques in Singapore rather than integrated providers. This pattern is most visible among operators with captive geoscience teams, who prefer algorithmic control over proprietary velocity model building.
Asia Pacific Offshore Seismic Services Market Segmentation
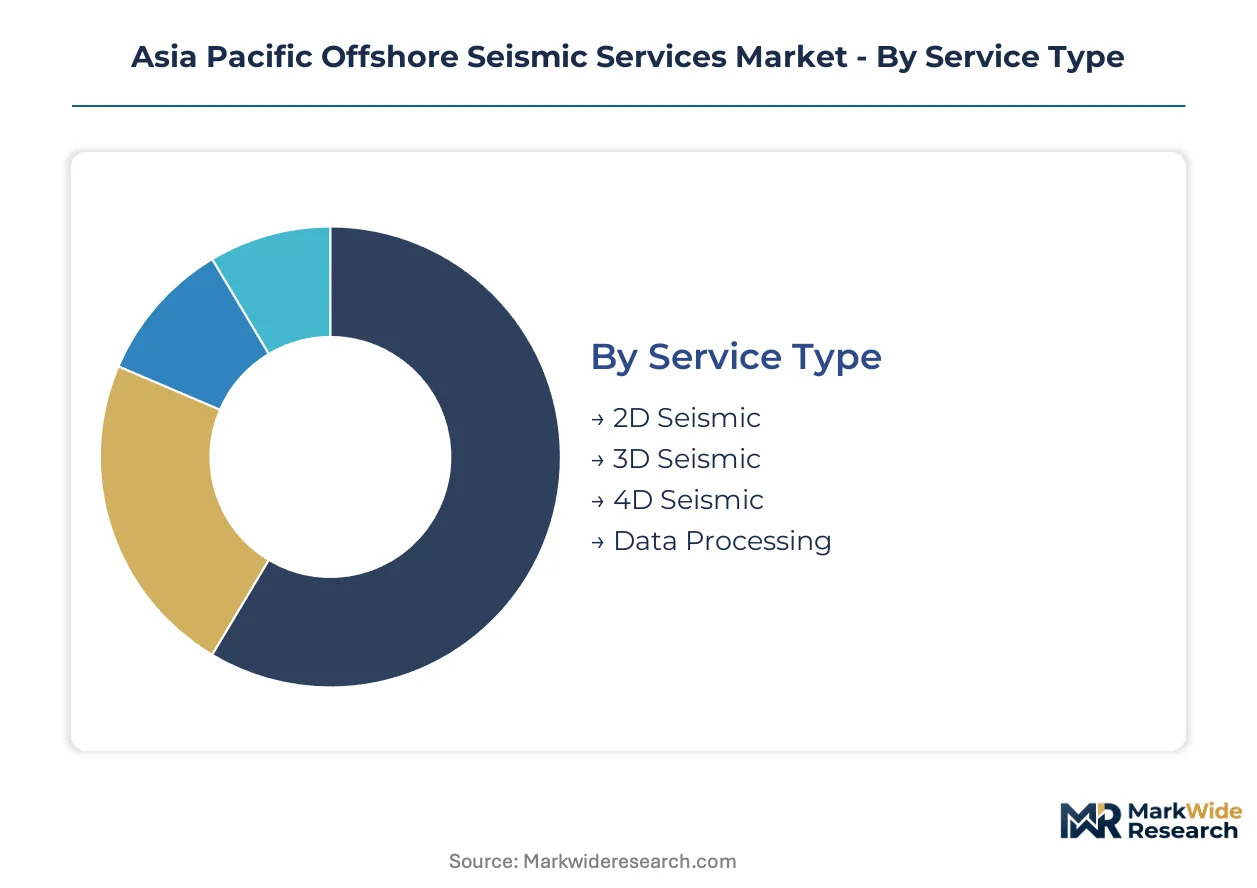
Segmentation in offshore seismic services determines contracting structures, equipment specifications, and regulatory compliance pathways. Each dimension carries distinct certification burdens that reshape procurement criteria across Asia Pacific licensing rounds.
Service Type:
NOPSEMA in Australia and METI in Japan impose tiered certification requirements that escalate from 2D reconnaissance through 4D monitoring, with data processing facing separate algorithmic audit standards.
- 3D Seismic:Multi-azimuth acquisition using overlapping source-receiver geometries generates high-fidelity subsurface volumes for pre-salt and deep-water prospect evaluation. Australia's North West Shelf operators mandate 3D coverage for all new block commitments, with contractors absorbing extended vessel mobilization costs to meet compressed seasonal windows.
- 4D Seismic:Time-lapse surveys repeat baseline 3D geometries to detect fluid displacement and pressure depletion in producing reservoirs. Indonesia's Mahakam Delta and Malaysia's Sarawak waters generate recurring demand as field operators prioritize production optimization over greenfield discovery.
- 2D Seismic:Reconnaissance line surveys for frontier basin screening require lighter vessel specifications and shorter permitting cycles.
- Data Processing:Velocity model building and depth migration services face unbundling pressure from operators with captive geoscience teams.
3D Seismic sits at the top of the volume ranking, with 4D Seismic climbing the fastest.
Technology:
Equipment selection drives capital intensity and operating cost structures, with ocean bottom installations commanding premium day rates against towed streamer efficiencies.
- Streamer Technology:Towed hydrophone arrays with variable-depth configurations unify shallow high-resolution imaging and deep-target penetration in single-pass operations. Vietnam and Brunei national oil companies now mandate these systems for new licensing rounds, consolidating previously separate survey campaigns.
- Ocean Bottom Seismometers:Stationary nodal arrays deploy in obstructed shallow-water zones where towed operations face operational constraints. Southeast Asian basins with complex seafloor topography generate premium pricing for these deployments.
- Air Gun:Compressed air impulse sources dominate deep-water operations despite maintenance volatility in high-pressure components.
- Vibroseis:Controlled vibratory sources see limited offshore application outside specific geotechnical survey niches.
Streamer Technology dominates contract volume, while Ocean Bottom Seismometers expand most quickly in shallow-water frontier zones.
End User:
Customer type determines project duration, technical specifications, and payment security structures across the contracting cycle.
- Oil & Gas:International majors and national oil companies drive multi-year framework agreements with integrated acquisition-processing commitments. Australia's North West Shelf and Timor Sea concessions concentrate exploration budgets from expanding national oil company portfolios.
- Renewable Energy:Offshore wind developers under Australia's Offshore Electricity Infrastructure Act mandate subsurface imaging for turbine pile installation planning across declared renewable energy zones.
- Geotechnical:Frontier basin site investigation contracts favor specialized contractors with combined geophysical and geotechnical survey capabilities.
- Environmental Studies:Carbon storage site characterization accelerates permitting requirements for depleted gas field conversions under Japan's revised METI safety standards.
Oil & Gas retains the largest share of contracted vessel days, with Renewable Energy gaining share fastest as offshore wind zoning advances.
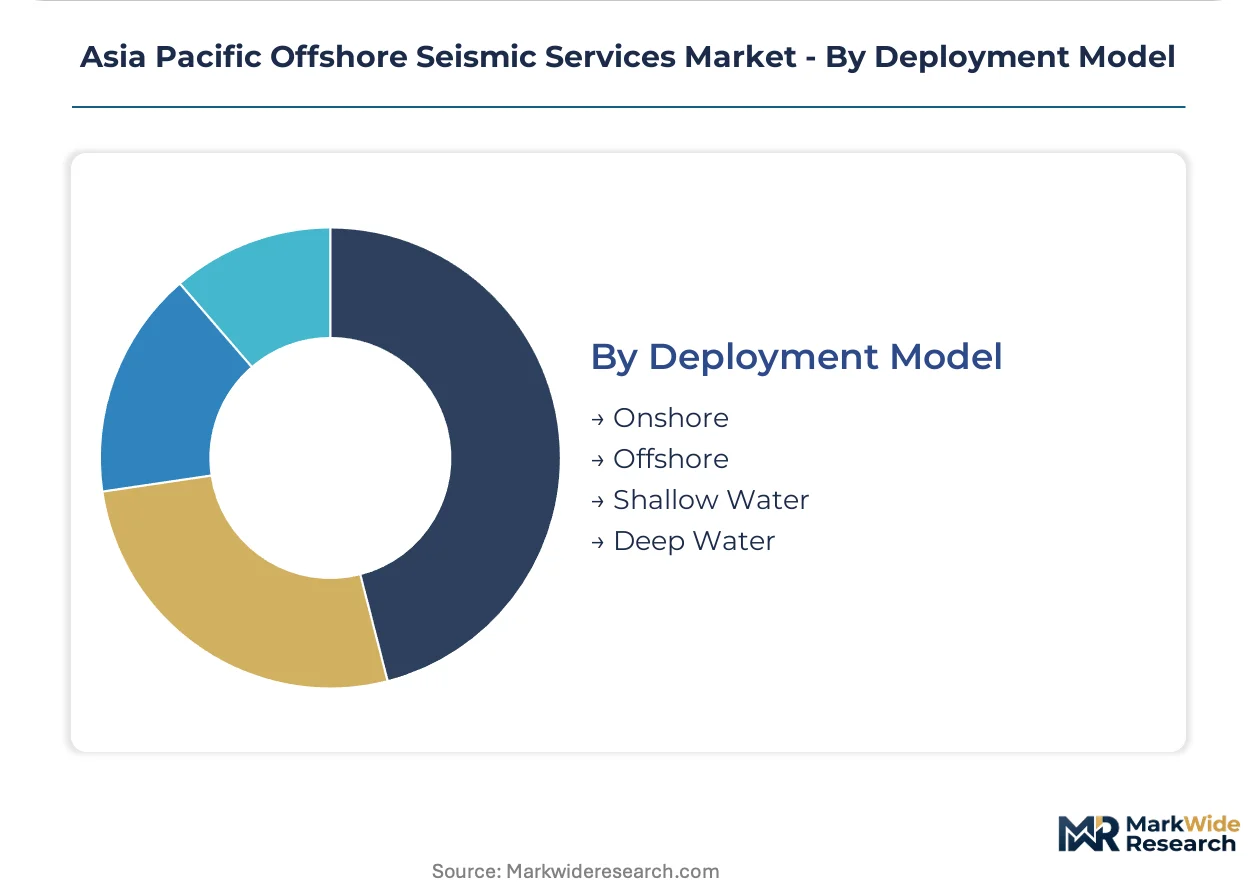
Deployment Model:
Water depth classification determines vessel specifications, regulatory jurisdiction, and acoustic mitigation protocol stringency.
- Deep Water:Operations below 400 meters require specialized vessel designs with extended streamer capacity and dynamic positioning systems. Pre-salt targets in Australia's North West Shelf and frontier Philippine basins concentrate contractor investment in deep-water capable fleets.
- Shallow Water:Deployments above 200 meters face obstructed zone constraints that favor ocean bottom seismometer configurations over towed arrays. Southeast Asian river deltas and coral-strewn shelf areas generate consistent demand.
- Offshore:General marine operations span the full water depth spectrum with jurisdiction-specific certification requirements.
- Onshore:Coastal transition zone surveys bridge marine and land acquisition with hybrid equipment configurations.
Deep Water commands the steepest expansion trajectory, while Shallow Water maintains stable demand in mature Southeast Asian production provinces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore seismic contracting in Asia Pacific traces its modern scale to North West Shelf development campaigns that established Australia's Perth basin as the region's technical services hub. Japanese METI safety protocols and Australian NOPSEMA standards now propagate across Southeast Asian licensing rounds. National oil companies from Vietnam to Brunei import these certification frameworks into their own procurement criteria.
Australia
North West Shelf pre-salt targets and Timor Sea concessions concentrate exploration expenditure from international majors and expanding national oil company portfolios. NOPSEMA well integrity standards mandate real-time emissions monitoring and acoustic mitigation protocols that extend vessel commissioning timelines. Perth anchors the regional technical services cluster, with processing boutiques and geophysicist talent pools supporting survey operations across the Indo-Pacific arc.
Japan
Depleted gas field conversions for carbon storage drive new survey requirements under METI's revised offshore facility safety regulations. Continuous monitoring system approvals extend vessel commissioning by four to six months for Japan-flagged operations. Tokyo Bay and surrounding industrial corridors host the engineering consultancies certifying automated shutdown triggers and integrated hydrophone feedback loops for air gun controllers.
China
South China Sea licensing rounds and frontier basin screening sustain demand for 3D seismic acquisition despite seasonal blackout periods imposed by MEE marine environmental impact assessments. Dual carbon goals redirect some contracting toward offshore wind foundation geophysics in declared renewable energy zones. Shenzhen and Guangzhou service clusters support both hydrocarbon exploration and emerging carbon storage site characterization mandates.
Indonesia
Mahakam Delta mature fields generate recurring 4D seismic monitoring contracts as operators prioritize reservoir optimization over greenfield discovery. Complex river delta topography obstructs towed streamer operations, elevating demand for ocean bottom seismometer deployments at premium day rates. Jakarta-based contractors coordinate equipment positioning across the archipelago's fragmented concession geography.
Vietnam
Frontier basin openings in unlicensed blocks attract first-mover positioning from contractors with pre-positioned equipment and established local agent networks. National oil company procurement now mandates variable-depth streamer configurations that unify shallow high-resolution imaging with deep-target penetration. Ho Chi Minh City serves as the operational coordination hub for South China Sea campaigns extending into Philippine waters.
Asia Pacific Offshore Seismic Services Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and sensor technology integration. The vendor base stratifies into three tiers: integrated acquisition-processing houses with proprietary fleet networks, specialized geotechnical surveyors with combined physical sampling capabilities, and regional contractors competing on mobilization speed and local regulatory relationships. Dominant competitive moves include fleet decarbonization partnerships with equipment financiers and unbundling of data processing from acquisition to capture algorithmic service contracts.
Among integrated service providers, BGP Inc. and Shearwater GeoServices occupy positions reflecting scale-driven streamer deployment capabilities, while Fugro NV anchors the geotechnical specialization tier with combined physical and acoustic survey competencies. These three entities exemplify contrasting strategic postures: the Chinese state-linked contractor leveraging integrated land-sea processing networks, the European technology leader advancing variable-depth acquisition systems, and the Dutch surveyor differentiating through frontier basin site investigation expertise. Each represents a distinct pathway for capital allocation between proprietary sensor research and regulatory compliance automation.
| Leading Market Players |
|---|
| PGS ASA |
| BGP Inc. |
| Schlumberger Ltd |
| SAExploration Holdings Inc |
| Halliburton Company |
| China Oilfield Services Limited |
| CGG SA |
| Shearwater GeoServices |
| Fugro NV |
| Others |
Value Chain & Pricing Dynamics
METI's real-time emissions certification mandates in Japan are forcing contractors to absorb four-to-six-month vessel commissioning delays, compressing pricing power for Japan-flagged operations and redirecting fleet capacity toward Australian NOPSEMA jurisdictions where compliance costs run lower.
Pricing Analysis
Project-based contracting with performance-linked milestone payments dominates Asia Pacific offshore seismic procurement, separating premium-tier integrated acquisition-processing providers from standard-tier acquisition-only contractors and economy-tier regional mobilization specialists. Price differentiation rests on certification depth and proprietary sensor integration, with NOPSEMA and METI compliance tiers commanding 15-25% day-rate premiums over uncertified competitors. Cost compression in the standard tier is intensifying as national oil companies unbundle processing from acquisition and award raw shot-gather contracts to Singapore-based processing boutiques. International majors with captive geoscience teams exhibit lowest price sensitivity, prioritizing algorithmic control over velocity model building, while frontier basin independents in Vietnam and the Philippines remain most price-constrained.
Supply Chain Analysis
Australia's local-content requirements for North West Shelf operations and Vietnam's domestic-agent mandates for South China Sea licensing rounds are reshaping sourcing toward Perth-based technical services clusters and Ho Chi Minh City coordination hubs. Vessel construction concentrates in Singapore and South Korea shipyards, while high-pressure air gun components and streamer sensor arrays draw from specialized manufacturing in Norway and the Netherlands. Single-source vulnerability runs through limited seismic-specific hull capacity, where regional lessors wield concentrated bargaining power over delivery timelines. Distribution runs through integrated service providers with proprietary fleet networks, specialized geotechnical surveyors with combined physical sampling capabilities, and regional contractors competing on regulatory relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific offshore seismic contracting functions as a regulatory-arbitrage play, with METI's extended commissioning timelines pushing vessel operators toward Australian waters where NOPSEMA standards offer faster deployment pathways at comparable compliance depth.
For Market Incumbents: To counter unbundling pressure from international majors with captive geoscience teams, deepen algorithmic service contracts through proprietary velocity model building partnerships and defend position by securing multi-year framework agreements with expanding national oil company portfolios across Indonesia and Vietnam. For New Entrants and Emerging Players: Begin with frontier basin positioning in Philippine Reed Bank and Sulu Sea unlicensed blocks, where pre-positioned equipment and established local agent networks create first-mover advantages. Target carbon storage site characterization under Japan's METI safety standards as the most penetrable service line, leveraging regulatory gap periods when incumbent vessels redirect to Australian jurisdictions. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized processing boutiques in Singapore capturing unbundled data interpretation contracts from operators seeking algorithmic control. Long-term viability hinges on 4D reservoir monitoring recurring revenue streams in mature Southeast Asian fields. Watch for inflection when METI approves continuous monitoring systems at scale, compressing Japan-flagged vessel commissioning timelines and normalizing regulatory arbitrage.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Decarbonization Partnership | Aligns vessel operators with equipment financiers to meet EU Green Deal extraterritorial carbon border pressure. |
| Variable-Depth Streamer Deployment | Consolidates shallow and deep imaging for Vietnam and Brunei national oil company licensing mandates. |
| Ocean Bottom Seismometer Expansion | Captures premium day rates in obstructed Southeast Asian river deltas where towed arrays face constraints. |
| Processing Boutique Acquisition | Secures algorithmic service contracts as international majors unbundle interpretation from acquisition. |
| Carbon Storage Survey Certification | Positions contractors for depleted gas field conversions under Japan's revised METI safety standards. |
Study Parameters
Coverage spans Australia, Japan, China, Indonesia, and Vietnam, with primary inputs from each market's contracting ecosystem. The approach combines structured interviews with fleet operations managers, national oil company procurement leads, geophysicist talent pools in Perth and Kuala Lumpur, and regulatory compliance officers at METI and NOPSEMA, validated against secondary sources including vessel charter databases, licensing round documentation, and environmental impact assessment filings. Bottom-up triangulation across contractor day-rate disclosures and top-down validation through exploration budget allocations from national oil companies anchor the analytical framework.
Granularity-level modeling distinguishes water depth classifications, service type tiers from 2D reconnaissance through 4D monitoring, technology configurations spanning streamer and ocean bottom deployments, and end-user segments across oil and gas majors, renewable energy developers, and carbon storage operators. CAGRs derive from segmented volume projections reconciled against aggregate exploration expenditure trends, with specific inputs including seasonal blackout period constraints from China's MEE assessments and vessel commissioning timeline extensions under METI continuous monitoring approval processes.
Several conditions sit outside the modeled scope, including commodity price volatility effects on exploration budget cycles, geopolitical disruption to South China Sea licensing rounds, and breakthrough displacement of air gun arrays by alternative acoustic source technologies. Forecasts reflect documented assumptions about regulatory stability and fleet capacity expansion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Rental Equipment Market
Offshore Oil and Gas
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
Offshore Oil and Gas Communications Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
Subsea Production and Processing System Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
Canada Oil and Gas Downstream Market
Offshore Oil and Gas
North America FLNG Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market