
 India Natural Gas Market | 2026-2036
India Natural Gas Market Size, Share, and Industry Trends Forecast 2026-2036
India Natural Gas Market Foresight
Liquefied natural gas regasification and small-scale LNG distribution is reconfiguring supply chain economics for remote industrial users. GAIL (India) Limited leverages its cross-country pipeline network to anchor bulk transmission across the Hazira-Vijaipur-Jagdishpur corridor. Adani Total Gas Limited competes aggressively in city gas distribution, while Gujarat State Petronet Limited controls last-mile connectivity in Gujarat's industrial belt.
Natural gas comprises methane-rich hydrocarbons extracted from conventional reservoirs, coal seams, or organic waste digestion, typically processed to 90-95 percent methane content for pipeline injection or cryogenic liquefaction at minus 162 degrees Celsius for transport. Its primary purpose spans baseload power generation, industrial process heat, and transport fuel substitution. Power Generation dominates volume offtake due to grid stability requirements, while Transportation through CNG stations represents the fastest-expanding margin pool as state transport utilities convert fleets. Conventional Gas maintains supply dominance, though Biogas is gaining policy traction under the SATAT initiative.
The Petroleum and Natural Gas Regulatory Board mandates unified tariffs and open access on common carrier pipelines, reshaping how traders contract for capacity. BIS standards for CNG dispensing and city gas infrastructure enforce safety and interoperability across state jurisdictions. The Ministry of Petroleum and Natural Gas compresses biogas blending targets into city gas networks. Stakeholders must monitor regulatory enforcement consistency across states and track pipeline tariff rationalization as the decisive variable for project returns.
Market Dynamics
The Petroleum and Natural Gas Regulatory Board's open access mandate is forcing pipeline operators to unbundle capacity contracts, compressing incumbent margins while enabling trader entry.
Growth Catalysts
- Compressed Biogas Blending:The Ministry of Petroleum and Natural Gas mandates biogas injection into city gas networks, creating feedstock demand for organic waste processors.
- Fertilizer Sector Expansion:Ammonia and urea manufacturers in Gujarat and Maharashtra are converting feedstock from naphtha to natural gas, anchoring baseload offtake.
- Hazira-Vijaipur-Jagdishpur Pipeline:This cross-country corridor extends into eastern industrial zones, unlocking stranded demand in Bihar and Uttar Pradesh.
Market Restraints
- LNG Import Dependency:Over half of supply arrives via long-term contracts tied to crude-linked pricing, exposing buyers to volatility when Brent fluctuates.
- Pipeline Tariff Fragmentation:The Petroleum and Natural Gas Regulatory Board's unified tariff implementation faces state-level resistance, delaying cost pass-through rationalization.
- Coal Subsidy Persistence:Power utilities retain regulated coal allocations, limiting gas-fired generation dispatch despite lower emissions profiles.
Strategic Opportunities
- Small-Scale LNG Distribution:Cryogenic trucking to remote industrial clusters bypasses pipeline coverage gaps, serving cement and steel plants in Rajasthan and Madhya Pradesh.
- SATAT Initiative Scale-Up:The compressed biogas program offers offtake guarantees to entrepreneurs setting up rural biogas plants, aggregating agricultural residue supply.
- CNG Fleet Conversion:State transport corporations in Maharashtra and Delhi are replacing diesel buses with CNG variants, expanding station throughput.
Industry Challenges
- Pipeline Construction Permits:Land acquisition and environmental clearances delay cross-state projects by 18-24 months, inflating project costs.
- Skilled Welder Shortage:High-pressure pipeline construction requires certified technicians that domestic training institutes cannot supply at required scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Natural Gas Market |
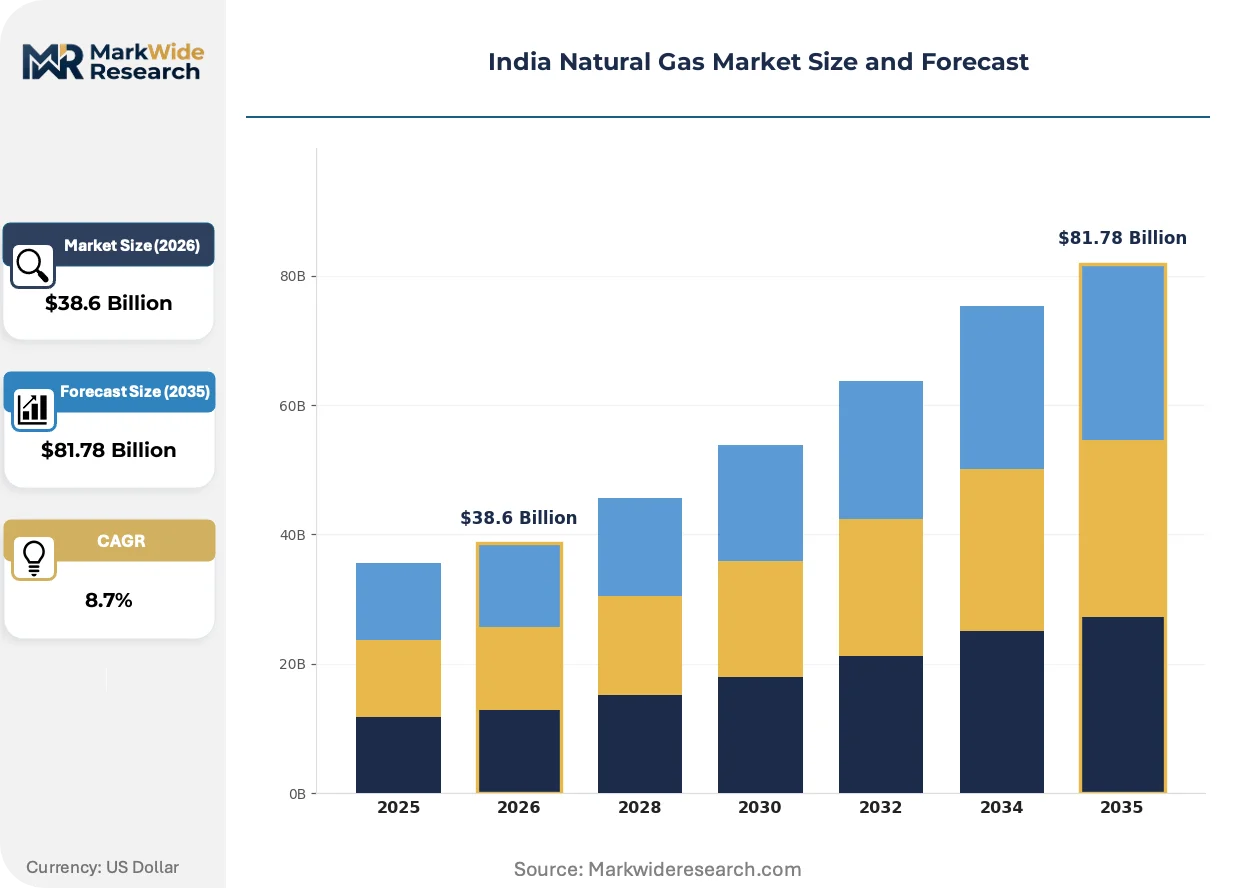
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Power Generation, Industrial Heating, Residential Cooking, Transportation Delivery Mode: Piped, LNG Trucks, CNG Stations, Storage Tanks End User: Utilities, Manufacturing, Households, Transportation Services Type: Conventional Gas, Shale Gas, Biogas, Others |
| Companies Covered | Indian Oil Corporation Limited, Indraprastha Gas Limited, GAIL (India) Limited, Gujarat State Petronet Limited, Gujarat Gas Limited, Oil and Natural Gas Corporation (ONGC), Adani Total Gas Limited, Reliance Industries Limited, Petronet LNG Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Natural Gas Market Shifts & Advancements
Modular liquefaction and virtual pipeline logistics are collapsing distance barriers between stranded gas sources and dispersed industrial demand.
Small-scale LNG regasification units mounted on skids are collapsing the capital threshold for remote industrial users to access pipeline-equivalent fuel quality. Cement manufacturers in Rajasthan and textile processors in Tamil Nadu now contract trucked LNG rather than waiting for grid extension. This distributed model compresses the effective reach of import terminals beyond their physical pipeline networks.
The Petroleum and Natural Gas Regulatory Board's open access tariff order is collapsing the exclusivity premium that integrated pipeline-city gas operators previously extracted. Third-party shippers now contract directly with GAIL and Gujarat State Petronet Limited for interruptible capacity. Traders are building position books around tariff arbitrage between high-pressure trunk lines and low-pressure distribution networks.
Industrial procurement of natural gas is consolidating around term contracts indexed to Henry Hub rather than traditional oil-linked formulas. Fertilizer manufacturers and glass producers with foreign exchange exposure prefer dollar-denominated pricing to hedge rupee volatility. This shift compresses the domestic spot market's liquidity, concentrating price discovery on exchange-traded platforms.
India Natural Gas Market Segmentation
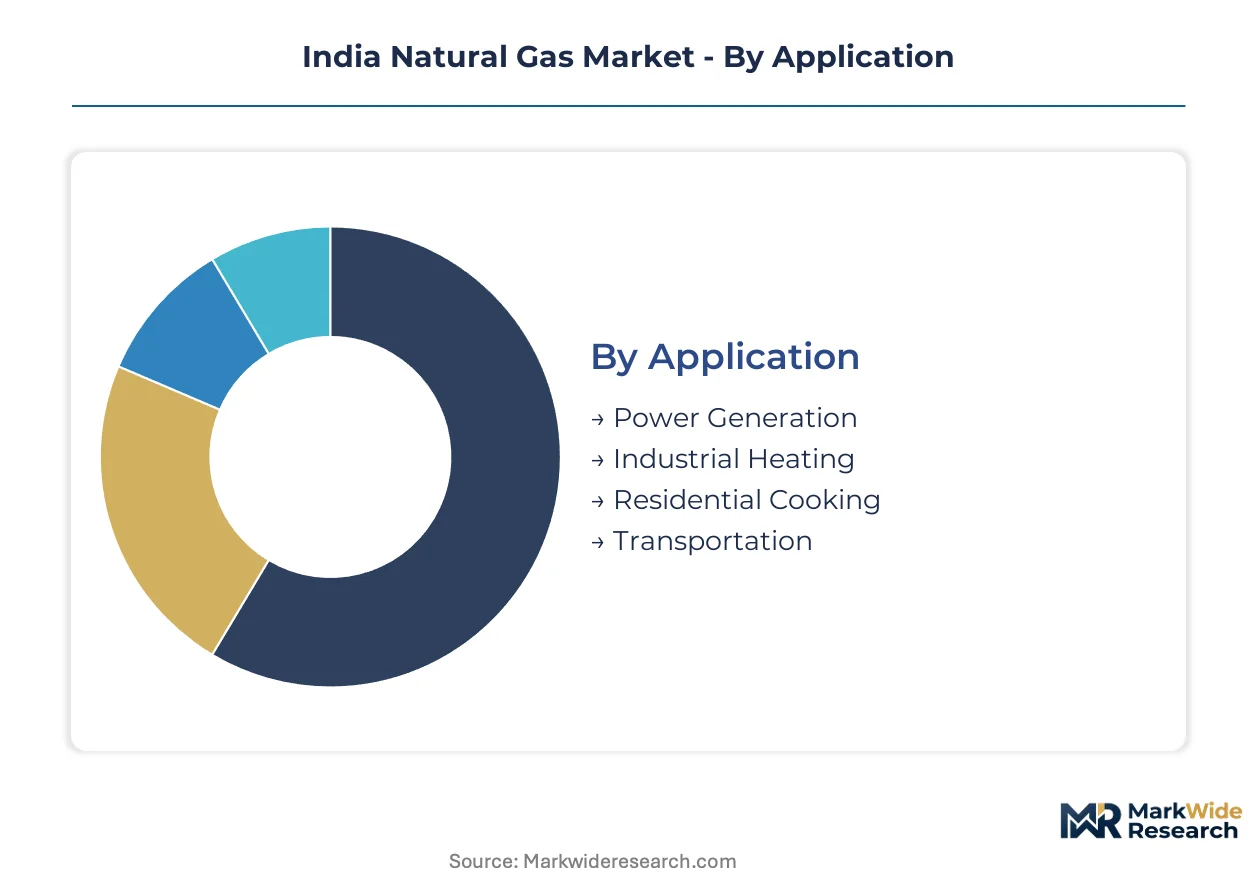
Natural gas consumption patterns across India diverge sharply by application cycle and infrastructure maturity. Segment-specific procurement behaviors determine contract structures, pricing benchmarks, and regulatory exposure for suppliers.
Application:
Power Generation turns fuel inventory weekly, while Residential Cooking stretches consumption across billing quarters.
- Power Generation:Combined-cycle turbines consume pipeline gas under take-or-pay contracts with grid dispatch priority. NTPC and state gencos in Gujarat anchor volume offtake, though coal linkage auctions constrain gas plant utilization rates.
- Transportation:CNG dispensing operates on intraday replenishment cycles with price-sensitive fleet operators. Maharashtra State Road Transport Corporation and Delhi Transport Corporation drive station throughput expansion along highway corridors.
- Industrial Heating:Glass, ceramic, and metal processors run continuous furnaces on monthly term contracts. Rajasthan cement kilns and Morbi ceramic clusters source trucked LNG where pipeline coverage lapses.
- Residential Cooking:PNG connections in urban households exhibit seasonal demand spikes during festival cooking cycles. City gas distribution networks in Mumbai and Ahmedabad prioritize metered domestic connections for tariff stability.
Power Generation dominates installed base. Transportation is where expansion concentrates.
Delivery Mode:
Capital intensity and geographic reach separate pipeline networks from distributed alternatives.
- Piped:High-pressure trunk lines and city gas distribution grids deliver standardized methane content under Petroleum and Natural Gas Regulatory Board tariff orders. The Hazira-Vijaipur-Jagdishpur corridor and Gujarat State Petronet Limited's intrastate network concentrate infrastructure ownership.
- LNG Trucks:Cryogenic road tankers bridge pipeline gaps to stranded industrial demand. Steel plants in Madhya Pradesh and textile processors in Tamil Nadu contract mobile regasification for fuel flexibility.
- CNG Stations:Daughter booster stations and mother stations compress pipeline gas for vehicular dispensing. Maharashtra and Gujarat host the densest station networks per kilometer of national highway.
- Storage Tanks:Above-ground bullet tanks and underground caverns buffer seasonal demand swings. Fertilizer manufacturers in Dahej and power utilities near LNG terminals maintain strategic inventory.
Piped infrastructure commands the deepest sunk cost base. LNG Trucks are climbing the fastest as last-mile arbitrage instruments.
End User:
Contract sophistication and credit risk profiles vary across institutional buyer categories.
- Utilities:State electricity boards and central gencos negotiate long-term supply agreements indexed to pooled gas prices. Grid stability mandates ensure dispatch priority during peak demand intervals.
- Manufacturing:Process industries hedge fuel costs through a mix of term contracts and spot LNG tenders. Fertilizer and petrochemical complexes in the western industrial corridor anchor baseload procurement.
- Households:Residential PNG subscribers pay regulated tariffs with slab-based pricing. Urban middle-class adoption in tier-1 cities drives connection growth for city gas distributors.
- Transportation Services:Fleet operators and individual vehicle owners purchase CNG at retail dispensing rates. State transport utilities negotiate bulk supply agreements with volume discounts.
Utilities lock in the longest contract tenors. Manufacturing offers the steepest expansion trajectory as industrial gasification accelerates.
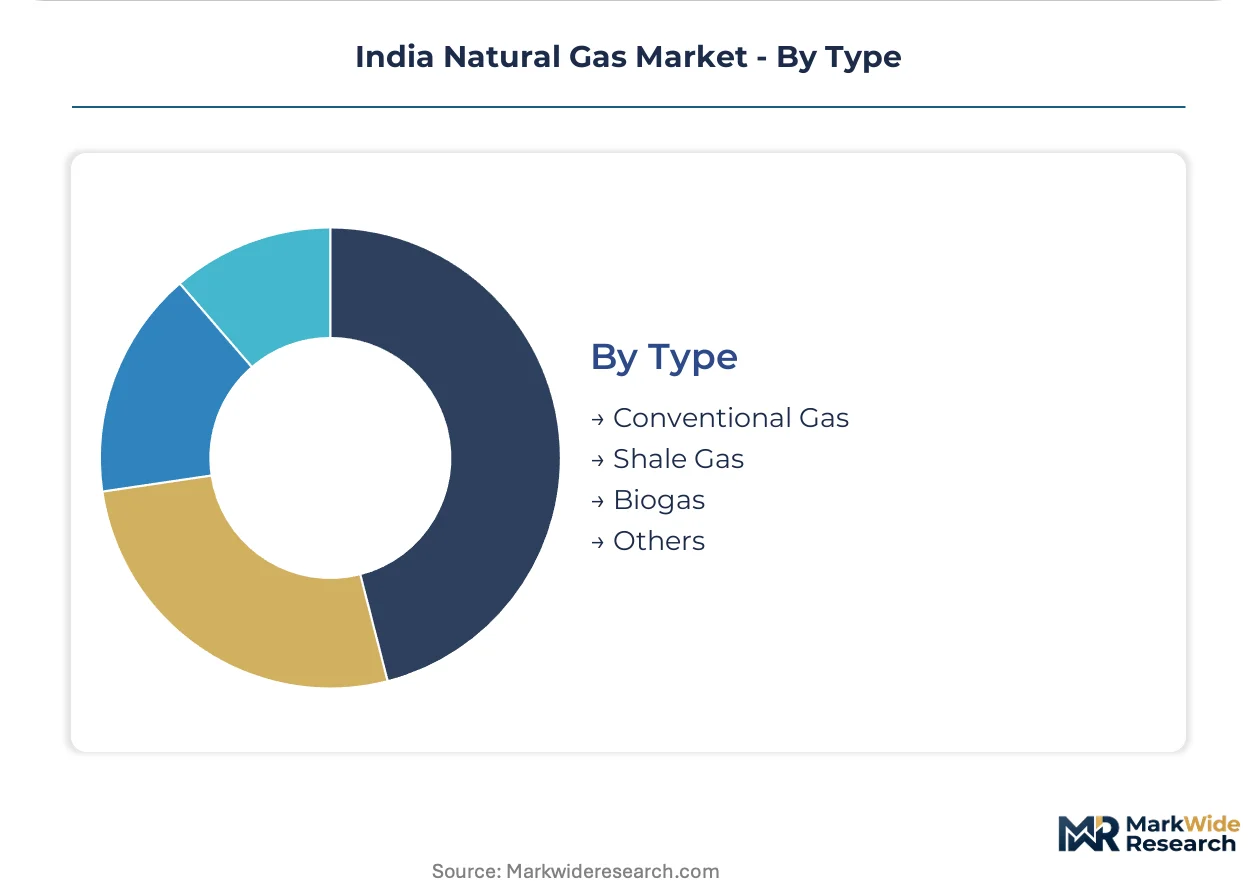
Type:
Feedstock origin determines carbon intensity credentials and regulatory treatment under national blending mandates.
- Conventional Gas:Depleted reservoir extraction from Bombay High and Krishna-Godavari basins supplies pipeline-grade methane. ONGC and Oil India Limited operate mature fields with declining production profiles.
- Biogas:Anaerobic digestion of agricultural residue and municipal organic waste yields compressed biomethane. The SATAT initiative guarantees offtake to entrepreneurs setting up rural biogas plants across Punjab and Haryana.
- Shale Gas:Tight formation extraction remains exploratory with limited commercial production. Cambay Basin test wells face water availability constraints for hydraulic fracturing operations.
- Others:Coal bed methane from Raniganj and Jharia coalfields and synthetic natural gas from biomass gasification pilot projects. Reliance Industries Limited operates the sole commercial coal bed methane block.
Conventional Gas dominates current supply volumes. Biogas is gaining share fastest under mandatory blending regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial consumers in western India anchor the bulk of natural gas procurement, while eastern states emerge as demand frontiers as pipeline networks extend. State-level regulatory enforcement and city gas distribution licensing determine effective market access across sub-regions.
Maharashtra
Fertilizer complexes and automotive manufacturing clusters in Mumbai-Pune corridor drive pipeline gas consumption. The Petroleum and Natural Gas Regulatory Board licenses city gas distribution networks in Nagpur and Nashik. Maharashtra State Road Transport Corporation converts diesel bus fleets to CNG along Mumbai-Pune Expressway.
Gujarat
Petrochemical refineries and ceramic processing hubs in Hazira-Mundra belt consume over one-third of national pipeline volumes. Gujarat State Petronet Limited controls intrastate transmission tariffs under state jurisdiction. Dahej LNG terminal anchors import regasification for western industrial corridor.
Uttar Pradesh
The Hazira-Vijaipur-Jagdishpur pipeline extension unlocks stranded demand in Kanpur-Lucknow industrial belt. GAIL (India) Limited operates the cross-country trunk line under Petroleum and Natural Gas Regulatory Board tariff orders. Fertilizer plants in Gorakhpur convert from naphtha to natural gas feedstock.
Tamil Nadu
Textile processors and glass manufacturers in Tiruppur and Sriperumbudur clusters source trucked LNG where pipeline coverage remains incomplete. Ennore LNG terminal supplies regasified volumes to southern industrial users. State industrial development corporations promote compressed biogas blending for captive power.
Delhi-NCR
Compressed natural gas dispensing for public transport and private vehicles concentrates demand in urban core. Indraprastha Gas Limited operates city gas distribution under exclusive licensing from Petroleum and Natural Gas Regulatory Board. Delhi Transport Corporation maintains the densest CNG bus fleet per route kilometer nationally.
India Natural Gas Market Competitive Landscape
Channel-controlling players compete with product-specialist players across transmission, distribution, and retail dispensing segments. The market structure consolidates around three tiers: national pipeline operators with cross-country infrastructure, state-level gas distribution utilities with geographic exclusivity, and import-terminal operators with regasification capacity. Strategic archetypes include integrated transmission-retail players, pure-play city gas distributors, and LNG terminal specialists. Competitive moves concentrate on pipeline capacity expansion and city gas distribution licensing rounds.
Among integrated transmission operators, GAIL (India) Limited anchors the national pipeline grid, while Gujarat State Petronet Limited exemplifies state-level infrastructure control. Adani Total Gas Limited occupies a position within city gas distribution expansion. These three represent distinct archetypes: cross-country trunk line ownership, intrastate network dominance, and retail dispensing growth.
| Leading Market Players |
|---|
| Indian Oil Corporation Limited |
| Indraprastha Gas Limited |
| GAIL (India) Limited |
| Gujarat State Petronet Limited |
| Gujarat Gas Limited |
| Oil and Natural Gas Corporation (ONGC) |
| Adani Total Gas Limited |
| Reliance Industries Limited |
| Petronet LNG Limited |
| Others |
Supply & Pricing Matrix
LNG import terminal concentration at Dahej, Hazira, and Kochi concentrates feedstock pricing power with Petronet LNG Limited and terminal operators, while downstream margin pools fragment across city gas distribution networks and industrial offtake contracts. This upstream bottleneck shapes how fertilizer manufacturers and power utilities negotiate term supply agreements.
Pricing Analysis
Cost-plus contracts indexed to Brent crude or Henry Hub dominate industrial procurement, with fertilizer manufacturers preferring dollar-denominated Henry Hub linkage to hedge rupee volatility. Price differentiation rests on volume scale and contract tenor, with baseload offtakers securing discounts against interruptible spot buyers. Pricing pressure intensifies as the Petroleum and Natural Gas Regulatory Board's unified tariff implementation compresses pipeline operator margins. State transport utilities exhibit highest price sensitivity in CNG procurement, while captive power users show lowest sensitivity due to grid stability mandates.
Supply Chain Analysis
Contract regasification capacity concentrates with Petronet LNG Limited at Dahej and Hazira terminals, while GAIL (India) Limited controls cross-country pipeline transmission. Geographic supply concentration centers on Qatar, Australia, and the United States as primary LNG contract sources. Raw material dependencies include cryogenic shipping vessels, nickel-alloy heat exchangers, and high-pressure pipeline steel. Supply chain risk hinges on single-source vulnerability for specialized LNG carriers and turbine maintenance services. Distribution runs through three-tier architecture: import terminals, high-pressure trunk lines, and city gas distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
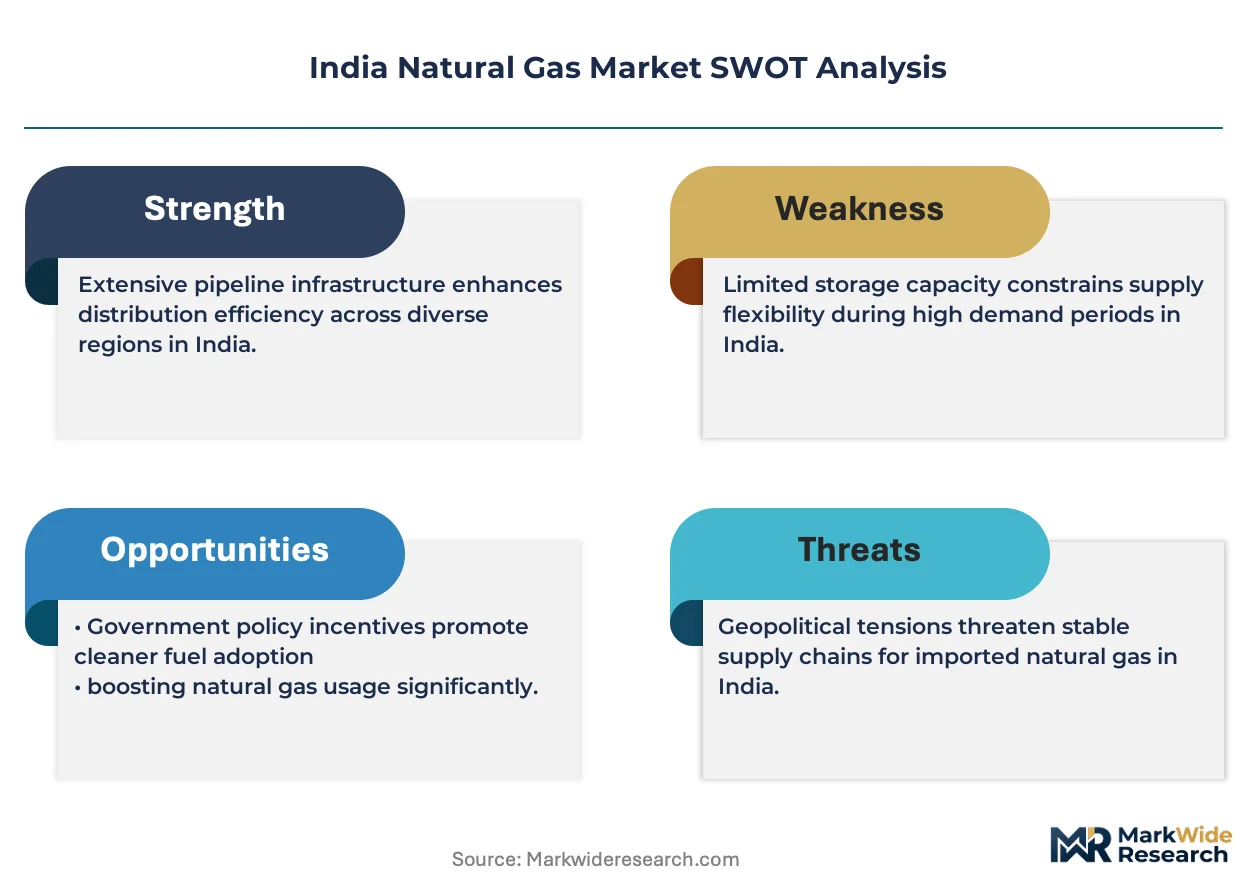
Pipeline welding certification scarcity and cross-state land acquisition expertise gaps constrain capacity expansion timelines, creating asymmetric returns for players who secure these capabilities early. Skilled technician availability determines project execution velocity more than capital access.
For Market Incumbents: Insulate transmission margins by securing preemptive city gas distribution licenses in Uttar Pradesh and Bihar before the Hazira-Vijaipur-Jagdishpur corridor extension completes. Accelerate backward integration into compressed biogas feedstock through SATAT initiative partnerships to offset conventional gas volume decline. The Petroleum and Natural Gas Regulatory Board's open access mandate threatens bundled service premiums, requiring tariff arbitrage capabilities between trunk and distribution networks. For New Entrants and Emerging Players: Pursue small-scale LNG distribution to Rajasthan cement kilns and Madhya Pradesh steel plants where pipeline coverage remains incomplete. Target biogas aggregation in Punjab and Haryana agricultural belts under SATAT offtake guarantees. Establish mobile regasification skids as the primary go-to-market vehicle, bypassing sunk-cost pipeline infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed city gas distribution operators holding licenses in tier-2 cities. Long-term viability hinges on pipeline density convergence with industrial demand corridors rather than retail dispensing scale. Monitor the Petroleum and Natural Gas Regulatory Board's unified tariff enforcement consistency as the decisive inflection signal for transmission asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Capacity Expansion | GAIL's Hazira-Vijaipur-Jagdishpur extension unlocks stranded demand in eastern industrial zones. |
| Compressed Biogas Backward Integration | SATAT offtake guarantees reduce feedstock risk for city gas distribution blending mandates. |
| Small-Scale LNG Distribution | Cryogenic trucking bypasses pipeline gaps to Rajasthan cement and Madhya Pradesh steel plants. |
| Unified Tariff Arbitrage | Third-party shippers exploit price spreads between high-pressure trunk and low-pressure networks. |
| CNG Fleet Conversion Partnerships | Maharashtra State Road Transport Corporation contracts anchor station throughput expansion. |
Research Methodology
A spread of perspectives from pipeline operations directors, city gas distribution licensing officers, fertilizer plant procurement heads, and LNG terminal logistics managers converged on the working assumptions. Primary interviews combined with secondary validation from Petroleum and Natural Gas Regulatory Board tariff orders, Ministry of Petroleum and Natural Gas policy circulars, and GAIL infrastructure disclosure filings. Bottom-up demand modeling from state-level industrial consumption data triangulated against top-down supply projections from LNG import terminal capacity schedules.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning application cycle, delivery mode, end user sophistication, and feedstock origin. CAGRs derived from weighted average of historical volume trajectories and project pipeline visibility. Industry-specific forecast inputs included city gas distribution license award timelines and compressed biogas plant commissioning schedules under SATAT.
Sensitivities concentrate around regulatory enforcement consistency for unified tariffs and LNG spot price volatility relative to long-term contract indices. Forecasts reflect documented assumptions on infrastructure completion timelines and blending mandate adherence. Quarterly review of Petroleum and Natural Gas Regulatory Board tariff orders and LNG import terminal utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
Global Oil and Chemical Spill Kits Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
Well Intervention Service Market
Oil & Gas
North America Hydraulic Fracturing Fluids Market
Oil & Gas
Libya Oil and Gas Midstream Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Blockchain in Oil and Gas Market
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Europe Well Intervention Market