
 North America Hydraulic Fracturing Fluids Market | 2026-2036
North America Hydraulic Fracturing Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hydraulic Fracturing Fluids Market Analytics
Fluid-recycling subscription services is hardening as a distinct revenue layer, shifting vendor relationships from one-time chemical sales to multi-year performance contracts. Halliburton Company leverages its integrated service model to bundle fluid chemistry with real-time downhole monitoring. Baker Hughes Company anchors its position through advanced polymer research facilities in Oklahoma. Calfrac Well Services Ltd. competes aggressively on price in the Canadian market while expanding its US fracturing fleet.
North America hydraulic fracturing fluids are engineered slurries combining base liquids, proppant, and chemical additives to create and maintain fractures in low-permeability rock formations, typically operating at pressures exceeding 10,000 psi and temperatures above 150°C to liberate hydrocarbons from shale and tight-gas reservoirs. Water-based fluids dominate the product-type mix due to lower cost and simpler disposal, though foam-based fluids command premium pricing in water-scarce formations where liquid loading threatens well productivity. Among end users, independent producers represent the fastest-growing demand pool as private-equity-backed drillers scale operations in the Permian and Eagle Ford, while oil companies retain the deepest technical specification authority over additive selection and sourcing.
The EPA regulates fluid disclosure and wastewater handling under the Safe Drinking Water Act and Clean Water Act, compelling operators to document chemical constituents and treat flowback before surface release. OSHA and state-level regulators in Texas and New Mexico enforce worker exposure limits during blending and pumping operations. State oil and gas commissions increasingly mandate closed-loop systems and recycled-water percentages. Stakeholders must monitor how evolving federal methane rules and state water-allocation policies reshape fluid formulation economics and sourcing geography.
Market Dynamics
The EPA's updated methane and wastewater standards are compressing formulation economics across the Permian and Eagle Ford, forcing operators to retire legacy chemistry stacks and requalify additive packages under tighter toxicity thresholds. This regulatory compression is redrawing vendor relationships and sourcing geography.
Growth Catalysts
- Horizontal Well Intensity:Operators in Texas and New Mexico are extending lateral lengths beyond 15,000 feet, multiplying fluid volumes per completion and sustaining demand for high-performance friction reducers and crosslinked gels.
- Closed-Loop Mandates:State oil and gas commissions in Texas now require recycled-water percentages in certain water-stressed counties, creating pull for treatment and reuse infrastructure that locks in fluid-service contracts.
- Tight-Gas Resurgence:The Haynesville Shale is absorbing renewed capital allocation as LNG export capacity expands, driving demand for foam-based fluids in high-pressure, high-temperature formations.
Market Restraints
- Guar Gum Price Volatility:Weather-driven harvest disruptions in India periodically spike costs for this essential viscosifier, squeezing margins on crosslinked fluid systems.
- Proppant Supply Concentration:Northern White sand deposits in Wisconsin and Minnesota face rail-capacity constraints and competing industrial demand, creating bottleneck risk for slickwater formulations.
- Flowback Treatment Costs:The Clean Water Act's NPDES permitting requirements for surface discharge impose capital-intensive pretreatment obligations that erode economics in low-oil-price environments.
Strategic Opportunities
- Canadian Montney Expansion:British Columbia and Alberta tight-gas development remains underpenetrated relative to US shale, offering white space for fluid vendors with cold-weather formulation expertise.
- Real-Time Downhole Monitoring Convergence:Integration of fiber-optic sensing with automated chemical injection systems enables precision dosing that cuts additive waste and differentiates service offerings.
- IRA-Aligned Methane Mitigation:Federal tax incentives for emissions reductions reward operators adopting low-methane-intensity fluid systems, creating regulatory tailwind for next-generation chemistry.
Industry Challenges
- Specialized Blending Technician Shortage:The complexity of multi-additive recipes at high throughput requires experienced personnel that the Permian labor pool cannot currently supply.
- Legacy ERP Integration:Field-level automation systems must interface with decades-old operator enterprise software, creating data-integrity risks and deployment delays.
- Additive Certification Timelines:EPA's updated disclosure requirements extend qualification cycles for new chemistries, compressing R&D payback windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hydraulic Fracturing Fluids Market |
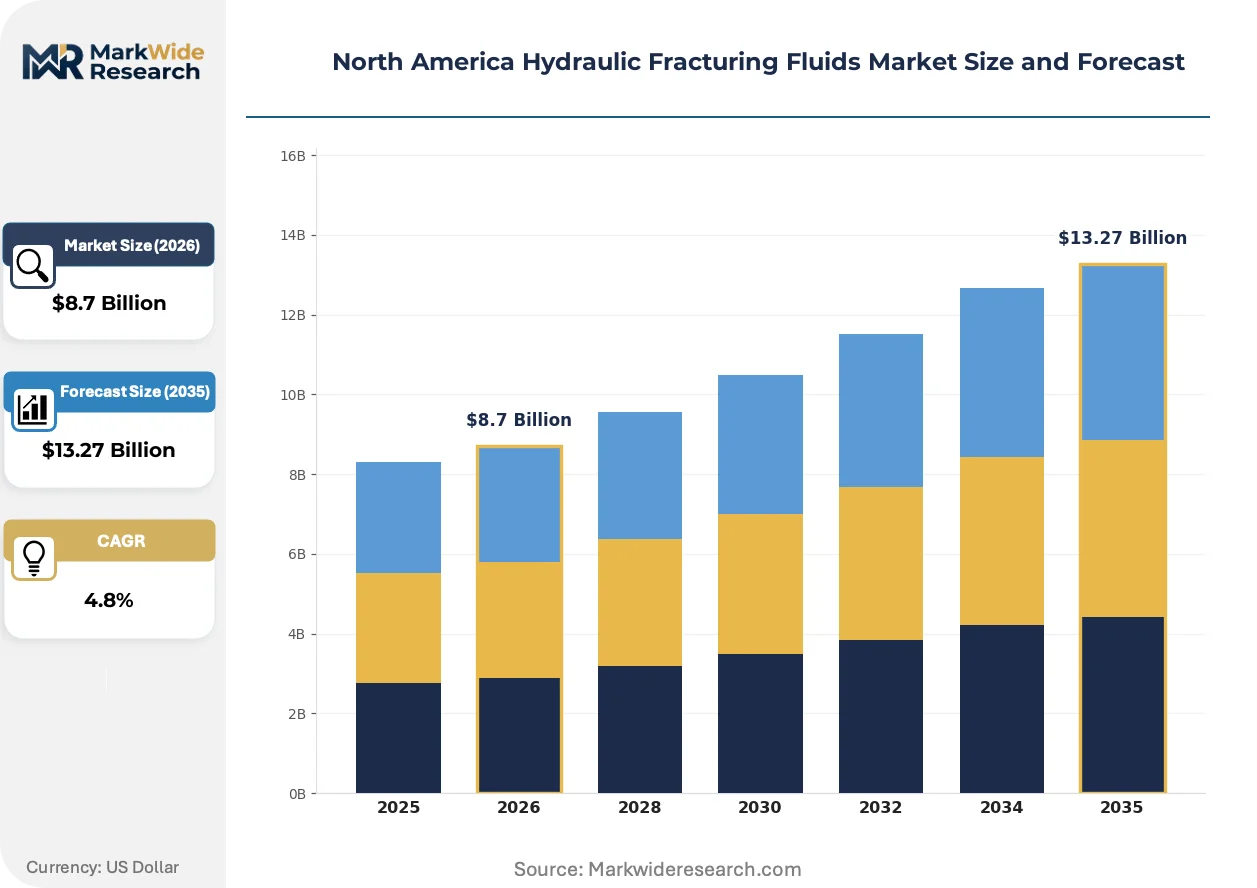
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Fluids, Oil-Based Fluids, Foam-Based Fluids, Additive-Based Fluids End User: Oil Companies, Gas Companies, Service Providers, Independent Producers Application: Onshore, Offshore, Tight Gas, Shale Gas Composition: Crosslinking Agents, Surfactants, Gelling Agents, Biocides |
| Companies Covered | Calfrac Well Services Ltd., Weatherford International, Baker Hughes Company, ProFrac Holding Corp., Liberty Oilfield Services LLC, Halliburton Company, BASF SE, National Oilwell Varco, Schlumberger Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hydraulic Fracturing Fluids Market Evolving Landscape
Formulation science is pivoting toward lower-toxicity chemistries that satisfy tightening federal and state standards without sacrificing proppant transport efficiency. This shift is compressing the competitive advantage of incumbent additive portfolios.
High-viscosity friction reducers (HVFRs) are absorbing market share from conventional polyacrylamide systems by delivering comparable drag reduction at lower polymer loadings. Independent producers in the Delaware Basin are adopting HVFRs aggressively to cut chemical costs per barrel. This displacement is absorbing volume from guar-based crosslinked systems in moderate-temperature formations.
The EPA's revised methane performance standards under the Clean Air Act are compelling operators to document and minimize fugitive emissions across the completions value chain. This regulatory pressure is accelerating substitution of diesel-based hydraulic horsepower with natural gas-fired electric fracturing fleets. Fluid vendors serving the Permian and DJ Basin are reformulating to align with electrified operations and lower-carbon intensity scoring.
Subscription-based fluid management is displacing spot chemical purchasing among private-equity-backed drillers seeking predictable unit economics. Performance contracts bundle chemistry, logistics, and recycling into per-barrel fees that transfer formulation risk to vendors. This model is concentrating most visibly in the Midland Basin where capital discipline favors operational simplicity over in-house blending expertise.
North America Hydraulic Fracturing Fluids Market Segmentation
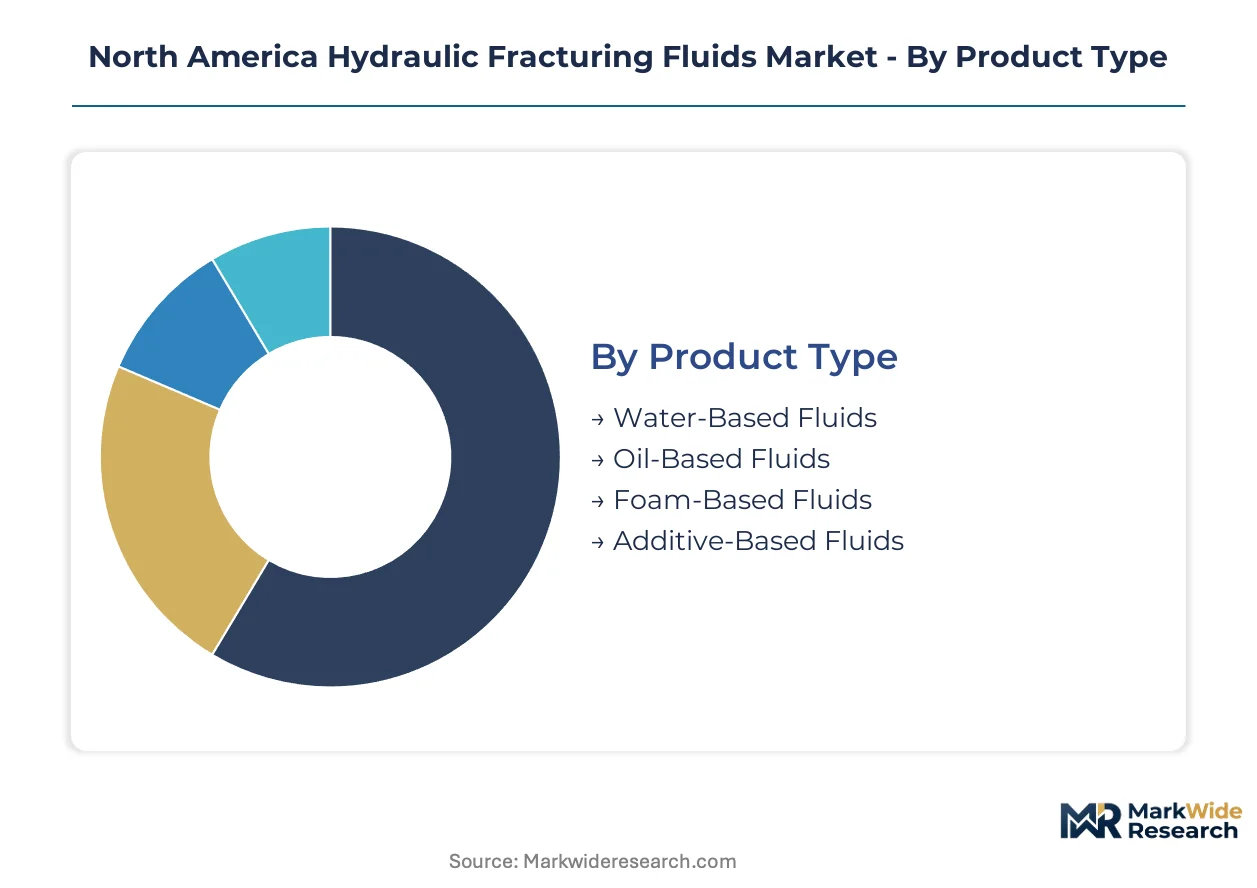
Fluid formulation economics vary sharply across segment boundaries. Capital deployment, regulatory exposure, and margin profiles diverge based on product chemistry, customer type, and reservoir application.
Product Type:
Water-based systems demand the heaviest upfront infrastructure for sourcing, storage, and recycling at scale.
- Water-Based Fluids:Slickwater and linear gel formulations dominate Permian and Eagle Ford completions. Independent producers in Texas favor these systems for cost efficiency in high-volume, multi-stage horizontal wells where fluid volumes exceed 100,000 barrels per completion.
- Foam-Based Fluids:Nitrogen or carbon dioxide energized systems reduce liquid loading in water-scarce formations. Haynesville Shale operators absorb premium pricing to sustain productivity in high-pressure, high-temperature gas wells where conventional fluids impair fracture conductivity.
- Oil-Based Fluids:Diesel or mineral oil carriers serve water-sensitive formations with reactive clay content. The EPA's toxicity disclosure requirements compress deployment in US shale plays.
- Additive-Based Fluids:Custom chemical packages target specific reservoir conditions. Oklahoma operators deploy these for complex geologies requiring precise rheology control.
Most installed capacity flows through water-based systems. Expansion is steepest in foam-based formulations.
End User:
Customer type determines procurement sophistication and contract structure across the value chain.
- Independent Producers:Private-equity-backed drillers in the Permian and Eagle Ford drive fastest volume growth. These operators favor subscription-based fluid management to transfer formulation risk and lock in predictable unit economics across multi-well pads.
- Oil Companies:Integrated majors retain deepest technical authority over additive selection, sourcing, and qualification protocols. Their capital budgets sustain long-term R&D partnerships with service providers for next-generation chemistry development.
- Gas Companies:LNG-focused producers in the Haynesville prioritize foam-based systems and closed-loop water handling to meet emissions intensity benchmarks for export markets.
- Service Providers:Halliburton, Baker Hughes, and Calfrac bundle fluid chemistry with pumping services, capturing margin through integrated execution rather than standalone chemical sales.
Procurement concentration sits with oil companies. Gaining share fastest are independent producers.
Application:
Reservoir setting dictates pressure, temperature, and fluid compatibility requirements.
- Shale Gas:Marcellus and Utica formations in Appalachia absorb water-based systems at extreme lateral lengths. EPA methane standards push operators toward electrified completions with lower-emission fluid handling.
- Tight Gas:Deep, overpressured zones in the Haynesville and Canadian Montney command foam-based fluids to minimize formation damage and accelerate cleanup.
- Onshore:Texas and New Mexico horizontal wells account for dominant fluid consumption. State water-allocation policies in New Mexico increasingly mandate recycled-water percentages.
- Offshore:Gulf of Mexico applications require compact, high-performance systems with minimal deck footprint and rapid mixing capabilities.
Volume concentrates in onshore shale gas. Tight gas applications are climbing the fastest.
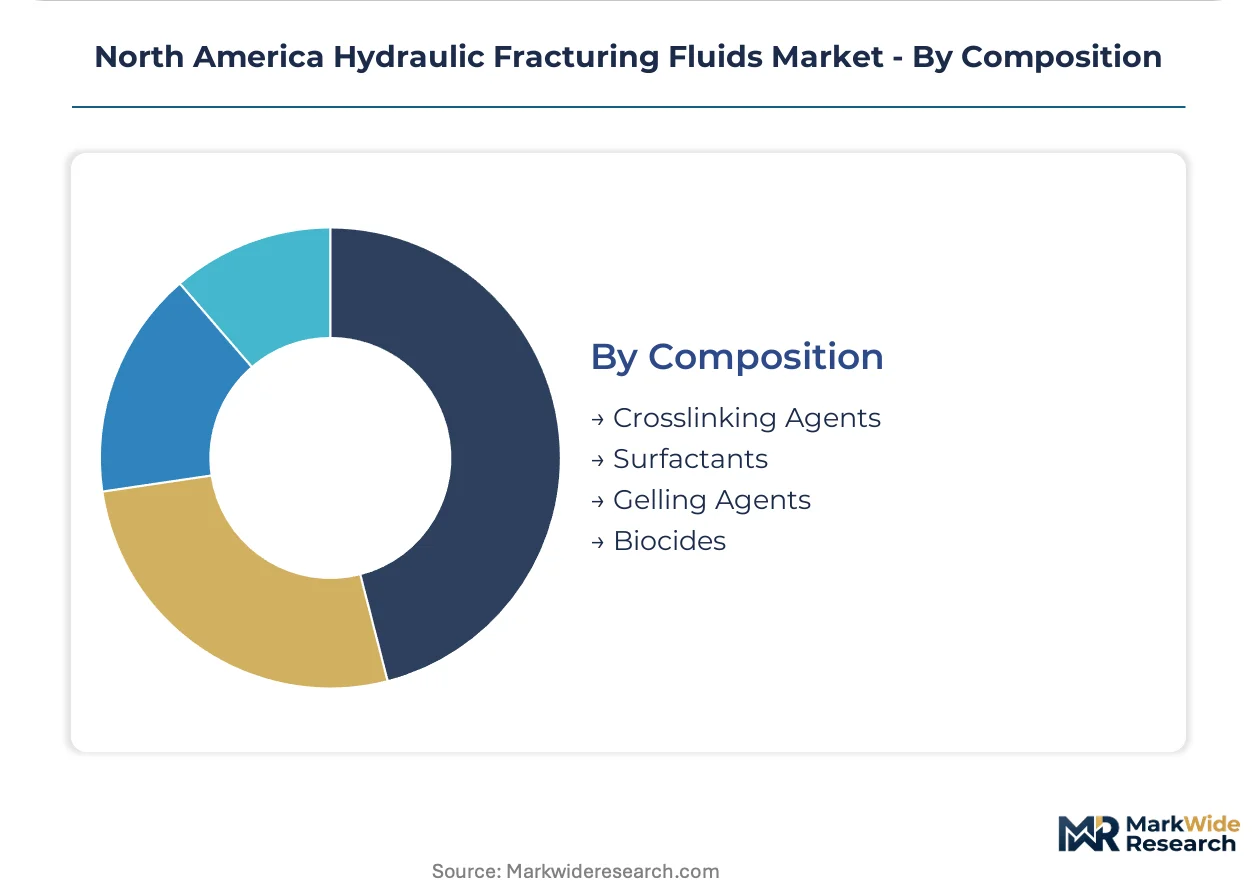
Composition:
Additive chemistry determines functional performance, environmental compliance, and supply chain risk.
- Gelling Agents:Guar gum and synthetic polymers build viscosity for proppant transport. Indian harvest volatility periodically disrupts supply and pricing for guar-based systems.
- Crosslinking Agents:Borate and zirconium compounds delay gel breaking for deeper, hotter formations. Delaware Basin operators specify these for wells exceeding 300°F bottom-hole temperatures.
- Surfactants:Reduce surface tension to improve fluid recovery and minimize formation damage. New Mexico regulators scrutinize these for aquatic toxicity.
- Biocides:Control bacterial growth in recycled water systems. Texas Railroad Commission guidelines limit certain chemistries in water-stressed counties.
Spend concentrates on gelling agents. Reformulation activity is most intense for crosslinking agents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States absorbs the dominant share of hydraulic fracturing fluid consumption, while Canada operates as a specialized secondary market with distinct cold-weather formulation requirements and tighter provincial environmental oversight.
United States
Texas and New Mexico horizontal wells drive fluid demand through extended lateral lengths exceeding 15,000 feet and multi-stage completion intensity. The EPA's updated methane performance standards under the Clean Air Act compel operators to document fugitive emissions across the completions chain. The Permian Basin in West Texas anchors North American consumption, where Delaware Basin operators specify high-temperature crosslinked systems for wells exceeding 300°F bottom-hole temperatures.
Canada
British Columbia and Alberta tight-gas development in the Montney formation creates demand for cold-weather formulations that maintain viscosity at sub-zero surface conditions. Health Canada and provincial regulators enforce stricter aquatic toxicity thresholds for surfactants and biocides than US counterparts. Calgary-based service providers anchor the Canadian market, with expansion focused on LNG export-linked projects in northeastern British Columbia.
Mexico
Burgos Basin shale gas potential remains largely undeveloped due to constitutional restrictions on private upstream investment and Pemex capital constraints. The country's national oil and gas regulator oversees limited hydraulic fracturing activity concentrated in conventional tight-gas fields. Northern border states including Tamaulipas and Nuevo León hold geological prospectivity but lack the water infrastructure and service company density of US shale plays.
North America Hydraulic Fracturing Fluids Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated oilfield service providers capturing margin through bundled execution while standalone chemical suppliers compete on formulation innovation. The vendor base concentrates around three strategic archetypes: integrated service companies bundling pumping and chemistry, specialized fluid technology developers, and diversified chemical majors leveraging polymer research platforms. Dominant competitive moves include strategic partnerships between operators and fluid vendors for multi-year performance contracts, and backward integration by service providers into captive additive manufacturing.
Within the integrated service tier, Halliburton Company and Baker Hughes Company exemplify the bundled chemistry-execution model that transfers formulation risk to vendors through subscription-based contracts. Calfrac Well Services Ltd. occupies a distinct position as a Canadian-founded service provider competing on fleet scale and price positioning in cross-border markets. These three companies anchor the competitive landscape through divergent geographic footprints and contract structures rather than homogeneous product offerings.
| Leading Market Players |
|---|
| Calfrac Well Services Ltd. |
| Weatherford International |
| Baker Hughes Company |
| ProFrac Holding Corp. |
| Liberty Oilfield Services LLC |
| Halliburton Company |
| BASF SE |
| National Oilwell Varco |
| Schlumberger Limited |
| Others |
Value Network & Pricing Analysis
Captive additive manufacturing by integrated service providers anchors both supply security and pricing power in North American hydraulic fracturing fluids. Halliburton and Baker Hughes control chemistry costs through in-house polymer production, insulating completions margins from Indian guar gum volatility and rail-constrained Northern White sand spikes.
Pricing Analysis
Capacity additions in Texas and New Mexico are reshaping price floors for water-based fluid systems as fleet expansion outpaces well completion growth. Three-tier pricing structure across premium foam-based, standard crosslinked gel, and economy slickwater formulations differentiates vendors by thermal performance and EPA compliance tier. Cost compression in the mid-tier is intensifying because private-equity-backed drillers negotiate subscription contracts that transfer formulation risk to service providers. Independent producers in the Permian exhibit highest price sensitivity, while integrated majors prioritize technical specification authority over per-barrel economics.
Supply Chain Analysis
Dual-sourcing mandates from Texas Railroad Commission guidelines compel operators to qualify multiple biocide and surfactant suppliers for water-stressed county operations. Supply concentrates in the United States for friction reducer polymers, India for guar gum harvests, and Wisconsin for Northern White proppant. Raw material dependencies include acrylamide monomers, boron crosslinkers, and nitrogen energizing agents. Single-source vulnerability persists for high-temperature zirconium crosslinkers qualified for Delaware Basin thermal conditions. Distribution runs through Halliburton and Baker Hughes integrated service networks, with Calfrac competing on spot-market price in cross-border Canadian operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America hydraulic fracturing fluids market represents a late-cycle quality story as EPA methane standards and state water mandates push demand toward lower-toxicity, certified-compliant formulations that command sustained premium positioning.
For Market Incumbents: Deploy backward integration into captive polymer manufacturing to defend margins against Indian guar harvest volatility and absorb HVFR substitution pressure. Halliburton and Baker Hughes should lock in multi-year performance contracts with Delaware Basin operators before independent producers consolidate procurement. Reinforce technical specification authority through real-time downhole monitoring bundling that raises switching costs for price-sensitive independents. For New Entrants and Emerging Players: Regional service partnerships with Calgary-based cold-weather specialists offer the fastest path to Montney tight-gas penetration where incumbents lack formulation expertise. Target British Columbia LNG-linked projects for foam-based fluid contracts that escape Permian price compression. White space exists in automated chemical injection systems that integrate with electrified fracturing fleets for IRA-aligned methane scoring. For Investors and Strategic Acquirers: Roll-up economics work for specialized fluid technology developers because EPA disclosure requirements extend new chemistry qualification cycles beyond private-equity holding periods. Platform consolidation around subscription-based fluid management models captures recurring revenue visibility that spot-chemical vendors cannot match. Watch for inflection when New Mexico recycled-water mandates spread to Texas Railroad Commission jurisdiction, accelerating treatment infrastructure consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Halliburton's captive polymer production insulates margins from Indian guar price spikes. |
| Subscription-Based Performance Contracts | Multi-year agreements with Permian independents transfer formulation risk to service vendors. |
| Cold-Weather Formulation Development | Montney shale operators require viscosity stability at sub-zero Canadian surface conditions. |
| Real-Time Downhole Monitoring Convergence | Fiber-optic sensing integration enables precision dosing that cuts additive waste per completion. |
| Electrified Fleet Chemistry Alignment | Natural gas-fired fracturing demands reformulated fluids for lower carbon intensity scoring. |
Research Methodology
Coverage spans Texas, New Mexico, Louisiana, Oklahoma, British Columbia, and Alberta, with primary inputs from each production basin weighted by fluid consumption intensity. The research combines structured interviews with completions engineers, fluid chemists, procurement leads at independent producers, and regulatory affairs officers at integrated majors with secondary validation through EPA enforcement data, state oil and gas commission filings, and EIA drilling productivity reports. Bottom-up well count and lateral length estimates triangulate against top-down service company revenue disclosures.
Rate-of-change decomposition separates volume growth from pricing mix effects across the projection horizon. The analytical framework models segmentation by fluid chemistry, end-user procurement sophistication, reservoir application, and additive composition tier. CAGRs derive from basin-level drilling forecasts, stage intensity assumptions, and fluid volume per lateral foot benchmarks. Industry-specific inputs include EPA methane rule implementation timelines and Texas Railroad Commission recycled-water mandate expansion scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Indian monsoon patterns affecting guar harvests and Permian takeaway capacity constraints on drilling economics. Deviation in EPA enforcement intensity or state water-allocation policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
North America Natural Gas Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Hydraulic Workover Units Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Denmark Oil and Gas Midstream Market
Oil & Gas
Slickline Services Market
Oil & Gas
Digital Oilfield Solutions Market