
 Polycrystalline Diamond Compact (PDC) Drill Bit Market | 2026-2036
Polycrystalline Diamond Compact (PDC) Drill Bit Market Size, Share, and Industry Trends Forecast 2026-2036
Polycrystalline Diamond Compact (PDC) Drill Bit Market Analytics
Independent shale producers and national oil companies in unconventional basins are rotating their procurement emphasis toward bits engineered for extended-reach laterals and higher rate-of-penetration economics. Schlumberger Limited leverages its integrated drilling services portfolio to bundle bit selection with real-time downhole analytics. Baker Hughes Company anchors its position through proprietary cutter technology and in-house synthesis of polycrystalline diamond substrates. Halliburton Company competes by dominating North American land market channels and maintaining dense repair-and-rebuild infrastructure close to active rigs.
A polycrystalline diamond compact drill bit is a fixed-cutter drilling tool that bonds synthetic diamond grit to a tungsten carbide substrate under high-pressure high-temperature conditions, producing cutters rated for thermal stability above 750 degrees Celsius in abrasive formations. The primary purpose is to shear rock efficiently in oil, gas, and mining applications where roller cone bits experience excessive wear or low penetration rates. High Performance and Heavy Duty product types command the strongest margin pools because operators pay premiums for cutters that maintain edge geometry through thermally stressful intervals. Oil & Gas application demand dwarfs mining and geothermal segments, though geothermal directional drilling is expanding fastest as EGS projects require bits capable of traversing hard crystalline basement formations.
The American Petroleum Institute governs dimensional and performance standards through API Spec 7-1 and API Q2 quality management requirements that manufacturers must satisfy for North American operator acceptance. ISO 10424-1 and ISO 13533 provide international reference frameworks for drill string design validation and bit classification, while China's GB/T standards and NMPA-equivalent quality protocols shape market access for imported cutters serving Sinopec and PetroChina drilling programs. Stakeholders must monitor how EPA methane emissions rules and evolving state-level flaring restrictions alter drilling intensity patterns, since completion timing directly affects bit consumption cycles and replacement intervals.
Market Dynamics
Longer horizontal wellbores in unconventional shale formations are forcing PDC bit manufacturers to prioritize thermal stability grades above 750 degrees Celsius, compressing replacement cycles and concentrating procurement among operators with extended-reach drilling programs.
Growth Catalysts
- API Spec Q2 compliance mandates:North American operators now require quality management certification for all downhole tools, filtering out uncertified suppliers and consolidating demand toward validated manufacturers.
- Extended-reach lateral drilling:Unconventional shale producers in the Permian Basin are pushing laterals beyond 15,000 feet, demanding cutters that maintain edge geometry through thermally stressful intervals.
- Higher rate-of-penetration economics:Drilling contractors prioritize bits that reduce days-on-well, creating pull-through demand for premium cutter substrates in abrasive formations.
Market Restraints
- Synthetic diamond supply concentration:High-pressure high-temperature synthesis capacity clusters among a limited set of substrate producers, creating input bottlenecks during demand surges.
- Tungsten carbide price volatility:Powder metallurgy feedstock costs fluctuate with mining output and export restrictions, compressing margins on standard-grade bits.
- Roller cone substitution in soft formations:Certain sedimentary intervals still favor mechanical crushing over shearing action, limiting PDC penetration in specific geologic windows.
Strategic Opportunities
- Enhanced geothermal systems (EGS) drilling:Hard crystalline basement formations in Nevada and Utah require bits capable of traversing abrasive igneous rock at high temperatures.
- Real-time downhole analytics integration:Sensor-embedded cutters enabling immediate wear detection are creating service-revenue streams beyond hardware sales.
- Repair-and-rebuild infrastructure proximity:Dense service networks near active rig clusters in West Texas allow faster turnaround and recurring revenue capture.
Industry Challenges
- cutter bonding metallurgy expertise:The specialized knowledge required for high-pressure high-temperature diamond-substrate synthesis remains scarce, constraining manufacturing scale-up.
- ISO 10424-1 validation timelines:Extended drill string design certification cycles delay new product introductions and tie up engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycrystalline Diamond Compact (PDC) Drill Bit Market |
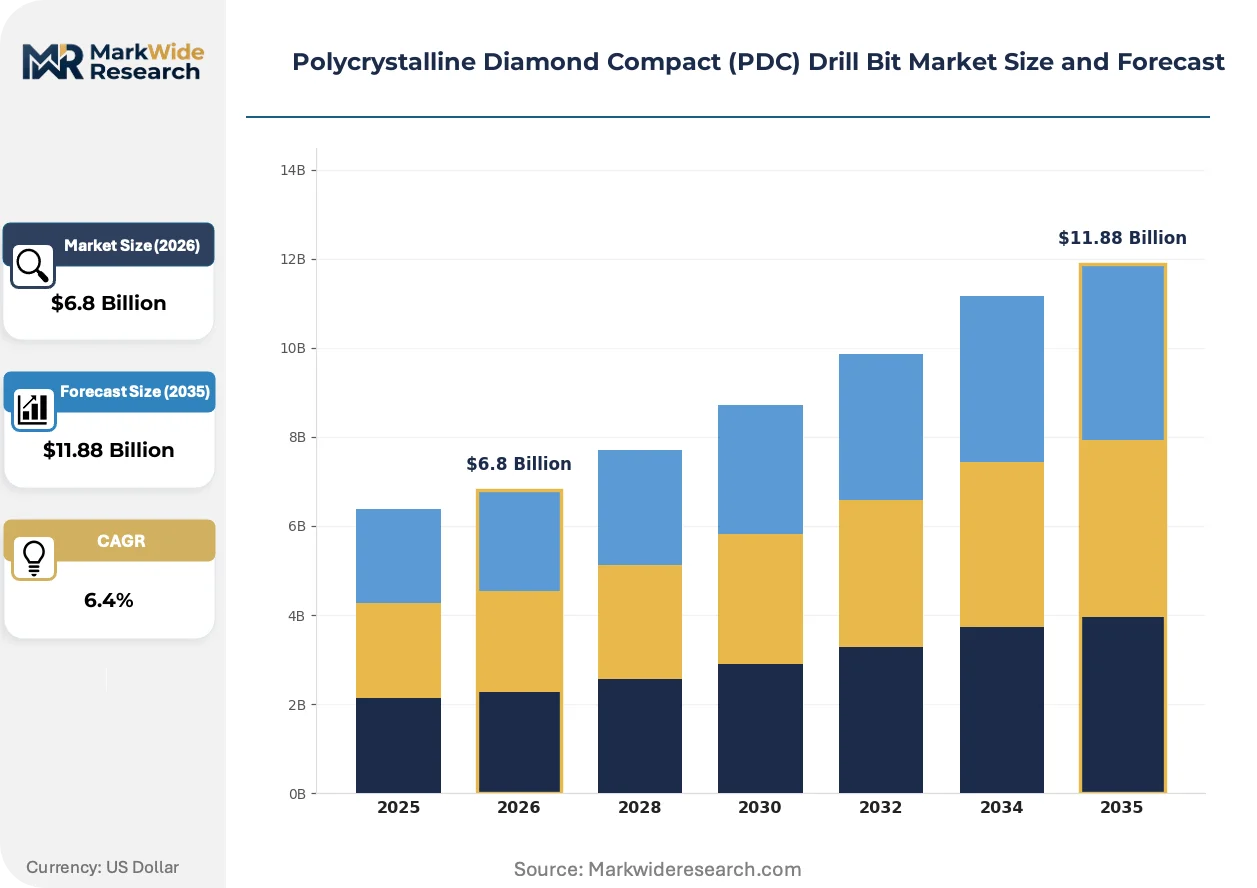
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Performance, Standard, Aggressive, Heavy Duty Application: Oil & Gas, Mining, Geothermal, Water Well Material: Polycrystalline Diamond, Tungsten Carbide, Steel, Composite Size: 8 Inch, 12 Inch, 14 Inch, 20 Inch |
| Companies Covered | National Oilwell Varco, Varel International, Schlumberger Limited, Drill Master International, Ulterra Drilling Technologies, Baker Hughes Company, Sandvik AB, Rockpecker Limited, Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycrystalline Diamond Compact (PDC) Drill Bit Market Evolving Landscape
Cutting structure geometries and substrate compositions are evolving rapidly as operators push drilling parameters into thermally extreme zones, while regulatory pressure on methane emissions intensifies scrutiny of drilling efficiency.
Leached polycrystalline diamond substrates are miniaturizing thermal degradation zones within individual cutters, allowing sharper edge retention at temperatures exceeding 800 degrees Celsius. Operators in the Permian Basin are specifying these grades for the most abrasive Wolfcamp and Bone Spring intervals. The technology is miniaturizing the performance gap between premium and standard cutter tiers, compressing pricing differentiation.
EPA methane emissions rules are tightening completion timelines and flaring restrictions, forcing operators to maximize rate-of-penetration to reduce days-on-well. This regulatory pressure elevates bit selection to a emissions-compliance decision, not merely a cost-center optimization. North American land drilling contractors are responding by standardizing on higher thermal stability grades across their fleets.
Procurement patterns are consolidating around bundled drilling services rather than standalone bit purchases, with operators favoring integrated providers who assume rate-of-penetration risk. This shift disrupts traditional distribution through independent supply stores and redirects volume toward direct manufacturer relationships. The behavioral change is most visible among independent shale producers in the Permian Basin who lack in-house drilling engineering depth.
Polycrystalline Diamond Compact (PDC) Drill Bit Market Segmentation
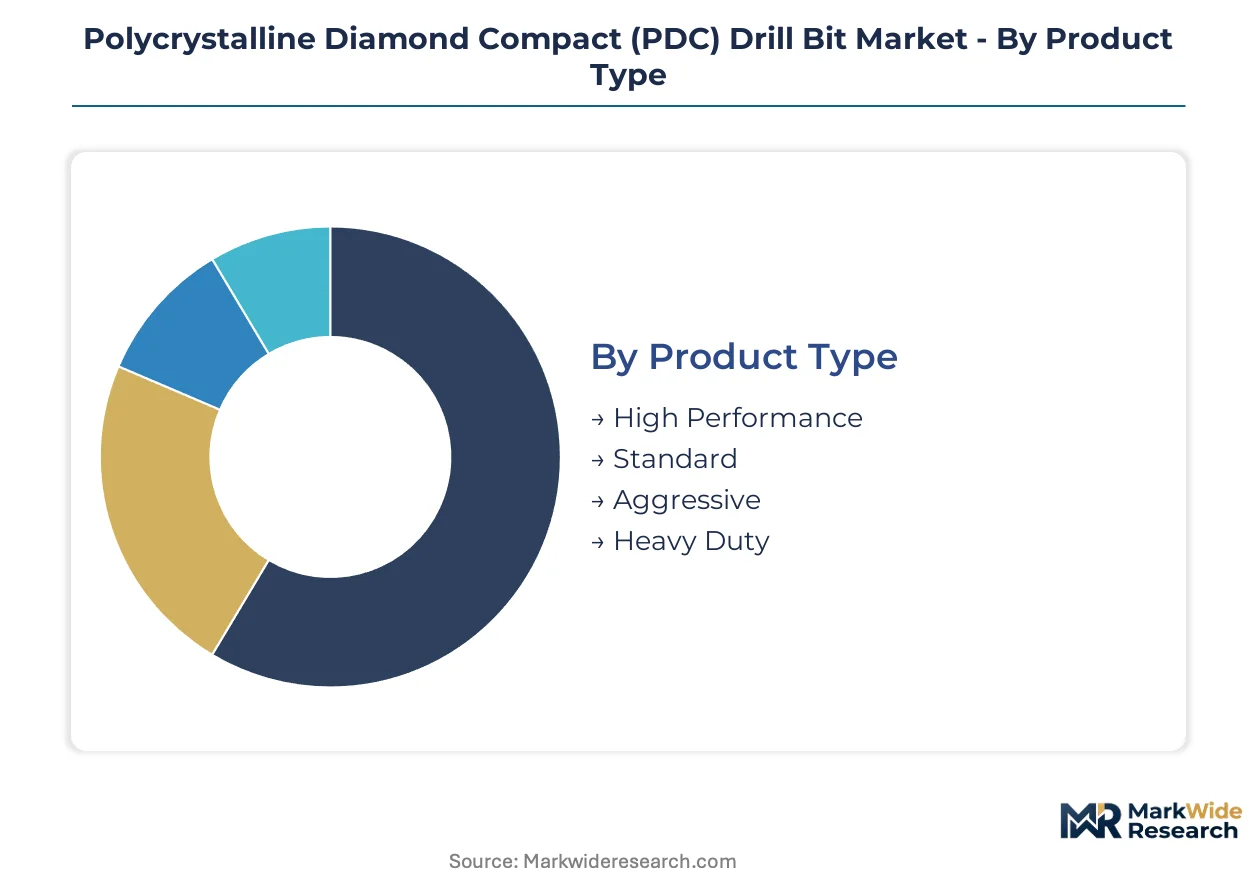
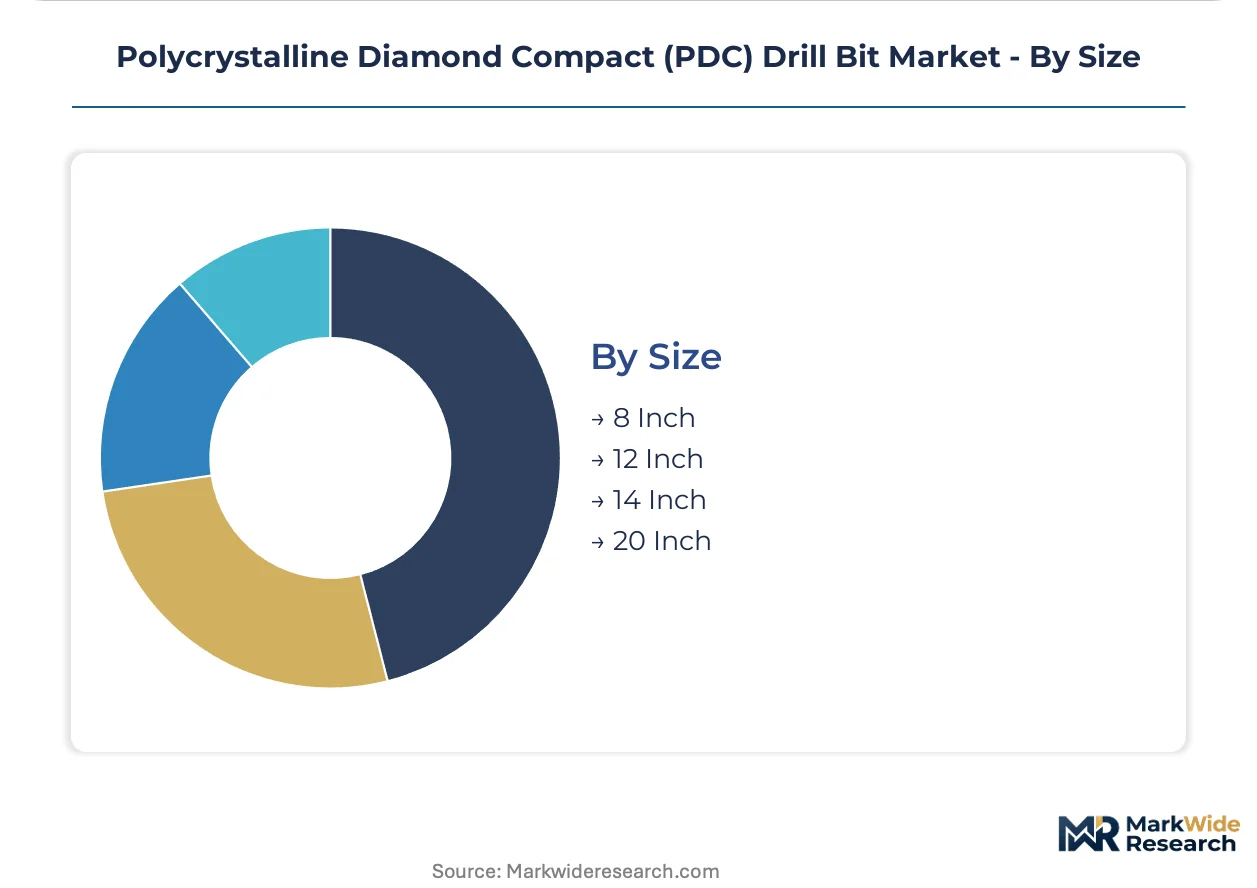
Segmentation in the PDC drill bit market determines procurement channel access, repair infrastructure placement, and thermal stability specification tiers. Operators in the Permian Basin and other unconventional shale plays select product grades based on lateral length requirements and formation abrasiveness, creating distinct margin pools across segment boundaries.
Product Type:
Channel mix varies sharply by performance tier, with High Performance and Heavy Duty bits flowing through direct manufacturer relationships while Standard grades move through independent supply stores and distributor networks.
- High Performance:Leached polycrystalline diamond substrates rated above 750 degrees Celsius thermal stability maintain edge geometry through extended-reach laterals exceeding 15,000 feet in the Wolfcamp and Bone Spring intervals. Operators in West Texas and southeastern New Mexico pay premiums for cutters that compress drilling days and satisfy EPA methane compliance timelines.
- Heavy Duty:Reinforced cutter substrates engineered for abrasive igneous formations in enhanced geothermal systems projects. Demand concentrates in Nevada and Utah where hard crystalline basement formations require bits capable of sustained high-temperature operation.
- Standard:Conventional thermal stability grades serve shorter laterals and less abrasive intervals through distributor channels.
- Aggressive:High rate-of-penetration geometries prioritized by drilling contractors seeking to minimize days-on-well in soft-to-medium formations.
High Performance dominates installed base value. Heavy Duty is where expansion concentrates for geothermal and ultra-deep applications.
Application:
Cost tier separation in this category follows completion intensity, with Oil & Gas commanding premium pricing and Geothermal climbing fastest as project economics improve.
- Oil & Gas:Unconventional shale drilling in the Permian Basin drives procurement volume for extended-reach laterals. API Spec Q2 compliance requirements filter supplier qualification, consolidating demand toward validated manufacturers with integrated drilling services portfolios.
- Geothermal:Enhanced geothermal systems projects in Nevada and Utah require bits capable of traversing hard crystalline basement formations at temperatures exceeding standard cutter ratings. This segment is expanding most quickly as EGS project pipelines mature.
- Mining:Hard rock extraction applications favor PDC bits in specific ore body geometries where roller cone bits experience excessive wear.
- Water Well:Shallow drilling programs in sedimentary basins utilize standard-grade cutters through regional distributor networks.
Oil & Gas anchors manufacturer revenue. Geothermal is where technology differentiation yields the steepest expansion trajectory.
Material:
Supply concentration shapes margin structure, with synthetic diamond substrate synthesis capacity clustering among limited producers and tungsten carbide feedstock subject to powder metallurgy price volatility.
- Polycrystalline Diamond:Synthetic diamond grit bonded to tungsten carbide substrates under high-pressure high-temperature conditions produces cutters with thermal stability ratings determining performance tier classification.
- Tungsten Carbide:Powder metallurgy feedstock costs fluctuate with mining output and export restrictions, compressing margins on standard-grade bit bodies.
- Steel:Conventional bit body material for less thermally stressful applications where weight and cost optimization precede extreme performance.
- Composite:Hybrid material configurations emerging for specific geothermal and mining applications requiring tailored thermal-mechanical properties.
Polycrystalline Diamond commands the highest unit economics. Tungsten Carbide is where supply volatility creates margin pressure.
Size:
Volume distribution correlates with wellbore diameter standardization in North American land drilling, where 8-inch and 12-inch specifications dominate unconventional shale programs.
- 8 Inch:Standard specification for production hole sections in Permian Basin laterals, flowing through dense repair-and-rebuild infrastructure networks close to active rig clusters.
- 12 Inch:Intermediate casing and pilot hole applications in extended-reach programs requiring balanced rate-of-penetration and directional control.
- 14 Inch:Larger diameter surface and intermediate sections in specific basin geometries.
- 20 Inch:Conductor and large-diameter surface hole applications with specialized cutter arrangement requirements.
8 Inch holds the largest installed base. 12 Inch is where procurement volume is concentrating for extended-reach lateral programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States PDC bit exports flow primarily to Canadian oil sands operators and Mexican onshore drilling contractors, establishing a North American trade corridor anchored by Permian Basin manufacturing clusters and West Texas repair infrastructure.
United States
Permian Basin operators in West Texas and southeastern New Mexico drive procurement for extended-reach laterals exceeding 15,000 feet. EPA methane emissions rules compress completion timelines, elevating thermal stability specifications. Dense repair-and-rebuild networks cluster around Midland-Odessa to service active rig counts.
Canada
Oil sands thermal drilling and Montney shale horizontal programs sustain demand for abrasive-formation cutters. Alberta's provincial regulators enforce emissions intensity thresholds that favor rate-of-penetration optimization. Calgary and Edmonton host distributor networks linking to Fort McMurray extraction clusters.
China
Sinopec and PetroChina drilling programs in Sichuan shale basins require NMPA-equivalent quality protocols for imported cutters. GB/T standards shape domestic manufacturing certification. Manufacturing gravity concentrates in Henan and Sichuan provinces where synthetic diamond synthesis capacity has scaled.
Saudi Arabia
Aramco unconventional gas drilling in Jafurah Basin drives specification for high-temperature stable cutters. Domestic content requirements under Vision 2030 incentivize joint ventures with international bit manufacturers. Eastern Province drilling clusters near Dhahran anchor procurement volume.
Brazil
Pre-salt carbonate drilling campaigns require bits capable of traversing hard, abrasive formations at significant depths. ANP regulatory frameworks govern well integrity standards affecting tool qualification. Santos Basin offshore clusters concentrate contractor procurement decisions.
Polycrystalline Diamond Compact (PDC) Drill Bit Market Competitive Landscape
Listed leaders compete with private specialists across integrated service bundling and standalone component supply channels. The vendor base stratifies into three tiers: diversified energy service conglomerates with drilling analytics portfolios, specialized bit manufacturers with captive cutter synthesis, and regional fabricators serving distributor networks. Consolidation pressures favor backward integration into synthetic diamond substrate production and geographic proximity to Permian Basin rig clusters.
Within the integrated services tier, Schlumberger Limited and Baker Hughes Company exemplify archetypes combining real-time downhole analytics with hardware specification. Halliburton Company anchors a position through North American land market channel density. Among specialized manufacturers, Varel International and Ulterra Drilling Technologies occupy positions emphasizing proprietary cutter geometries and repair infrastructure proximity to active drilling programs.
| Leading Market Players |
|---|
| National Oilwell Varco |
| Varel International |
| Schlumberger Limited |
| Drill Master International |
| Ulterra Drilling Technologies |
| Baker Hughes Company |
| Sandvik AB |
| Rockpecker Limited |
| Halliburton Company |
| Others |
Value Network & Pricing Analysis
Leached polycrystalline diamond substrates displacing conventional thermal grades are redrawing procurement geography toward Permian Basin repair clusters while compressing the technology premium that manufacturers command for extended-reach applications.
Pricing Analysis
Current-generation leached substrates rated above 750 degrees Celsius command substantial premiums over prior-generation standard grades, while next-generation sensor-embedded cutters are entering field trials at elevated price points. Three-tier pricing structure across premium, standard, and economy levels separates API Spec Q2-certified manufacturers from uncertified suppliers and distributor-channel commodity bits. Cost compression in standard grades is intensifying because tungsten carbide feedstock volatility and synthetic diamond synthesis bottlenecks squeeze margins. Independent shale producers in the Permian Basin exhibit the highest price sensitivity, prioritizing rate-of-penetration economics over cutter longevity, while national oil companies in Saudi Arabia and China demonstrate lower sensitivity due to integrated service bundling and domestic content requirements.
Supply Chain Analysis
Port congestion at Houston and Long Beach is elevating inbound logistics costs for tungsten carbide powder shipments originating from Chinese mining operations, compressing margin recovery timelines for standard-grade bit manufacturers. Synthetic diamond synthesis capacity clusters in the United States, China, and Ireland, while tungsten carbide powder metallurgy feeds from Chinese and Russian mining output. The supply chain rests on high-pressure high-temperature press availability and specialized cutter bonding metallurgy expertise concentrated among limited producers. Single-source vulnerability in synthetic diamond substrate synthesis creates procurement risk during demand surges. Distribution runs through direct manufacturer relationships for premium grades and independent supply stores for standard tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as enhanced geothermal systems projects in Nevada and Utah accelerate adoption of heavy-duty thermal grades previously confined to oil and gas applications.
For Market Incumbents: Shield premium positioning by deepening backward integration into synthetic diamond substrate synthesis and securing API Spec Q2 certification ahead of regulatory tightening. The threat of bundled drilling services from integrated energy conglomerates compresses standalone hardware margins, making captive cutter production the priority lever for cost control. Capacity addition in Midland-Odessa repair infrastructure defends channel proximity against regional fabricators. For New Entrants and Emerging Players: Anchor in geothermal directional drilling as the most penetrable application segment, where hard crystalline basement formations in Nevada and Utah require specialized heavy-duty grades that established oil and gas suppliers have not optimized. The white space in sensor-embedded cutters for real-time wear detection offers technology differentiation without competing on Permian Basin scale. A go-to-market angle emphasizing EGS project partnerships with independent power producers bypasses entrenched oilfield service relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialized bit manufacturers possessing proprietary cutter geometries but lacking integrated drilling analytics portfolios. Long-term viability hinges on five-to-ten year geothermal expansion trajectories and methane compliance intensity sustaining premium grade procurement. Acquisition target archetypes include regional fabricators with dense Permian repair networks. The signal to watch is EPA methane rule enforcement consistency as a drilling intensity inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Diamond Synthesis | Captive substrate production insulates margins from HPHT press capacity bottlenecks during demand surges. |
| API Spec Q2 Certification Investment | Quality management validation filters supplier pools and consolidates procurement toward certified manufacturers. |
| Repair-and-Rebuild Network Expansion | Proximity to Midland-Odessa rig clusters accelerates turnaround and captures recurring service revenue. |
| Sensor-Embedded Cutter Development | Real-time wear detection creates service-revenue streams beyond hardware sales in extended-reach programs. |
| Geothermal EGS Partnership Formation | Hard crystalline basement drilling in Nevada and Utah opens technology-differentiated expansion outside oil and gas. |
Research Methodology
The analysis maps high-performance, heavy-duty, standard, and aggressive product tiers, each validated through drilling contractors, bit procurement managers at independent shale producers, repair facility operators, and synthetic diamond substrate manufacturers. Primary interviews with these stakeholders combined with secondary validation from API specification documents, EPA methane emissions filings, ISO certification registries, and customs trade data on tungsten carbide powder imports. Bottom-up and top-down triangulation cross-checked unit economics assumptions against rig count trajectories and lateral length expansion patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, application, material composition, and bit size dimensions alongside thermal stability specification tiers and regional regulatory clusters. CAGRs were derived from drilling intensity projections and replacement cycle compression in extended-reach programs. Industry-specific forecast inputs included Permian Basin lateral length trajectories and EGS project pipeline maturation timelines.
Material uncertainties — synthetic diamond synthesis capacity expansion, tungsten carbide export restriction volatility, and EPA methane rule enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions about thermal grade adoption curves and geothermal penetration rates that could revise materially if drilling economics shift. Practitioners should keep alternative scenarios live as regulatory compliance timelines and unconventional shale breakeven thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Libya Oil and Gas Midstream Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
Downhole Tractor Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Global Oil and Chemical Spill Kits Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Ecuador Oil and Gas Midstream Market
Oil & Gas
Asia-Pacific Natural Gas Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
India AI in Oil and Gas Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Managed Pressure Drilling Services Market
Oil & Gas
CO2 EOR Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Global Artificial Lift Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market