
 Global Oil and Chemical Spill Kits Market | 2026-2036
Global Oil and Chemical Spill Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oil and Chemical Spill Kits Market Outlook
Trained hazardous materials response technicians are redrawing competitive boundaries in the Global Oil and Chemical Spill Kits Market as facilities face steeper OSHA compliance thresholds. Clean Harbors leverages its certified workforce network to anchor long-term service contracts with downstream refiners. Oil-Dri Corporation of America dominates absorbent mineral sourcing through captive control over Wyoming bentonite deposits. New Pig Corporation differentiates through channel control of its direct-to-plant distribution model.
Oil and chemical spill kits are engineered response systems comprising polypropylene absorbents, PVC containment booms, nitrile PPE ensembles, and EPA-compliant disposal containers designed to arrest hydrocarbon and corrosive liquid dispersion within regulated timeframes. Absorbents lead product type revenue due to recurring consumption patterns, while containment booms capture premium margins in marine applications where Coast Guard certification requirements elevate technical barriers. Industrial sites anchor application demand through SPCC-mandated stockpiling, though waste management represents the fastest-growing segment as environmental remediation contractors professionalize their field capabilities.
EPA SPCC rules and OSHA Hazardous Waste Operations standards shape domestic product specifications, while REACH compliance in Europe restricts certain synthetic absorbent chemistries and redirects formulation investment. The EU Green Deal's zero-pollution ambition is tightening discharge thresholds for port facilities from Rotterdam to Hamburg. Stakeholders must monitor how regulatory divergence between EPA and ECHA frameworks influences cross-border kit standardization and certification costs.
Market Dynamics
Maritime fleet operators are accelerating chemical-grade containment procurement as MARPOL Annex II discharge amendments force port facilities to upgrade response capabilities ahead of compliance deadlines.
Growth Catalysts
- EPA SPCC enforcement:Refineries along the US Gulf Coast face stepped-up inspection protocols, forcing replacement of aging absorbent inventories and expanding stockpile minimums for above-ground storage tanks.
- EU Green Deal zero-pollution targets:Port authorities from Rotterdam to Hamburg must install certified spill response infrastructure, redirecting capital toward Coast Guard-approved containment systems.
- Bio-based absorbent development:Agricultural waste-derived sorbents are gaining traction in European industrial sites seeking REACH-compliant alternatives to synthetic polypropylene.
Market Restraints
- Wyoming bentonite concentration:Oil-Dri Corporation's captive control over premium absorbent mineral deposits limits second-tier manufacturers' input sourcing flexibility and compresses margin structures.
- REACH formulation restrictions:ECHA's evolving substance restrictions force European kit assemblers to reformulate synthetic absorbent chemistries, extending R&D cycles and certification timelines.
- Silica gel substitution:Desiccant manufacturers are repurposing production lines toward spill-grade absorbents, threatening price stability in industrial maintenance segments.
Strategic Opportunities
- Indian port modernization:Jawaharlal Nehru Port Trust and Mundra Port expansion projects lack mature spill response infrastructure, creating first-mover positioning for certified kit suppliers.
- Waste management contractor professionalization:Environmental remediation firms are building in-house hazardous materials response teams, expanding recurring service contract potential beyond equipment sales.
- Direct-to-plant distribution:Bypassing industrial supply intermediaries allows manufacturers to capture service revenue through on-site inventory management and technician training programs.
Industry Challenges
- HAZWOPER technician scarcity:OSHA-certified hazardous materials responders command premium wages, constraining service providers' ability to scale field operations across multiple client sites simultaneously.
- Cross-border kit standardization:Divergent EPA and ECHA certification requirements force manufacturers to maintain parallel product lines, inflating inventory carrying costs and complicating global account management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oil and Chemical Spill Kits Market |
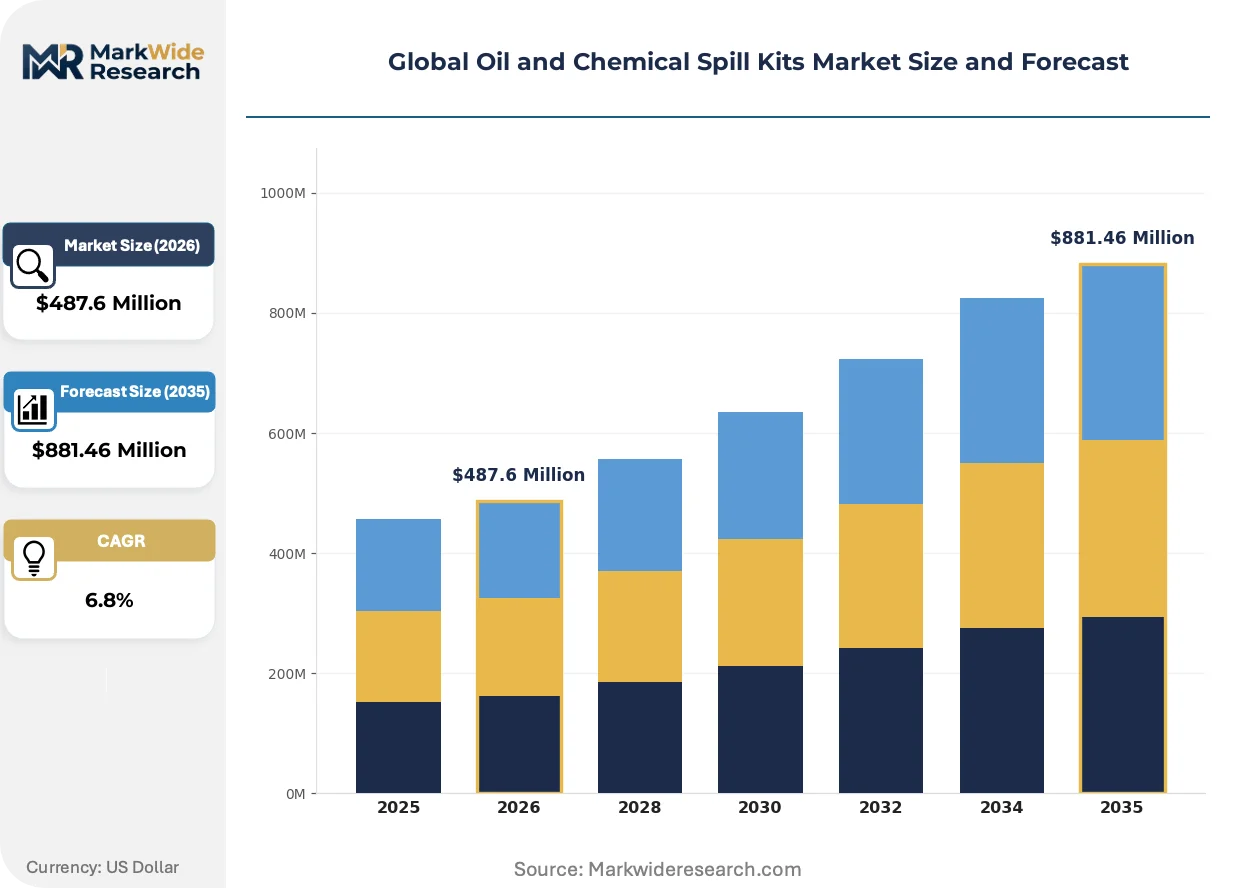
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbents, Containment Booms, PPE, Disposal Bags Application: Industrial Sites, Marine, Transportation, Waste Management End User: Oil & Gas Companies, Shipping Industry, Manufacturing, Government Distribution Channel: Online, Distributors, Direct Sales, Retail |
| Companies Covered | Ecolab, Oil-Dri Corporation of America, New Pig Corporation, UltraTech International, Clean Harbors, 3M Company, Chemtex International, Darcy Spillcare Manufacture, Brady Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oil and Chemical Spill Kits Market Strategic Shifts
Spill response technology is pivoting toward rapid-deployment architectures and bio-based material science, compressing traditional equipment replacement cycles while opening formulation pathways previously blocked by synthetic chemistry regulations.
Cellulose-based absorbents derived from agricultural waste streams are decomposing the polypropylene incumbent position in European industrial applications. Food processing plants in Germany and the Netherlands are piloting these materials to preempt REACH compliance costs. The shift is compressing margins for petroleum-derived sorbent manufacturers while rewarding vertically integrated agricultural processors.
EU Green Deal zero-pollution ambition is tightening discharge thresholds for port facilities from Rotterdam to Hamburg. Terminal operators must now demonstrate Coast Guard-equivalent response readiness within fifteen minutes of incident detection. Marine containment boom specifications are elevating technical barriers, favoring suppliers with integrated manufacturing and certification capabilities.
Refinery procurement departments are consolidating vendor relationships around full-service response providers rather than equipment-only transactions. Downstream operators in Texas and Louisiana are bundling absorbent resupply, technician training, and disposal services under multi-year agreements. This compression of the supplier base is most visible along the US Gulf Coast petrochemical corridor, where integrated service contracts now dominate capital allocation decisions.
Global Oil and Chemical Spill Kits Market Segmentation
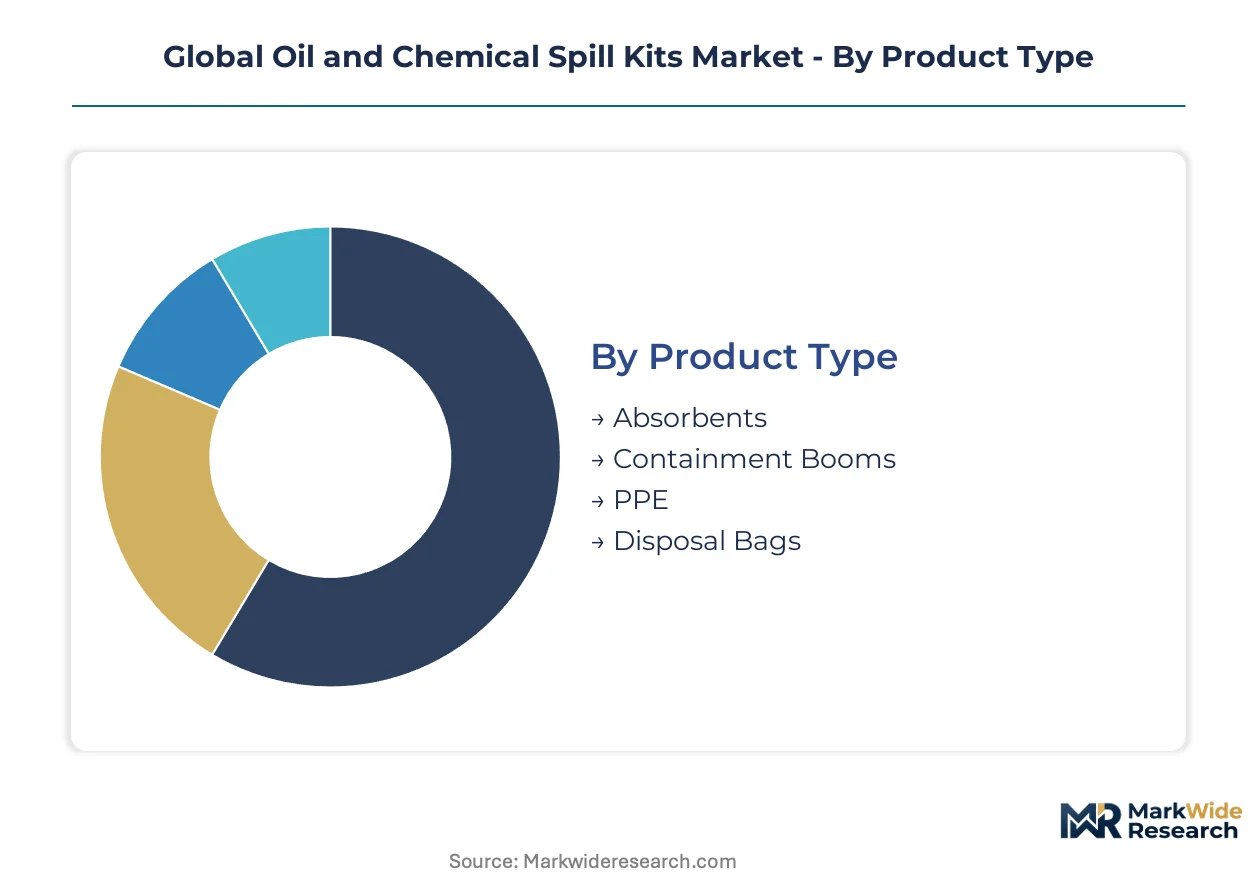
Margin pools in the Global Oil and Chemical Spill Kits Market fragment sharply across product architectures and procurement channels. Regulatory certification tiers and recurring consumption patterns determine where manufacturers capture sustainable returns versus commodity competition.
Product Type:
Margin concentration favors consumables with recurring replacement cycles over durable hardware with extended amortization periods.
- Absorbents:Polypropylene melt-blown pads, cellulose-based loose fill, and bentonite clay granules form the core consumable layer. US Gulf Coast refineries under EPA SPCC inspection mandates drive bulk procurement of oil-selective and universal absorbent configurations.
- Containment Booms:PVC-coated fabric barriers with foam flotation and galvanized steel connector systems command premium pricing in marine certifications. Coast Guard-approved designs for MARPOL Annex II compliance concentrate demand at Rotterdam, Hamburg, and Singapore port authorities.
- PPE:Nitrile glove ensembles, chemical-resistant coveralls, and respiratory protection kits meet OSHA HAZWOPER field requirements.
- Disposal Bags:EPA-compliant LDPE containers with UN certification markings for hazardous waste manifesting.
Absorbents hold installed capacity. Containment booms are rotating up the share rankings.
Application:
Volume concentration sits with mandated stockpiling regimes, while expansion trajectories diverge toward professionalized service segments.
- Industrial Sites:Above-ground storage tank farms, process equipment areas, and loading rack stations require SPCC-mandated spill kit positioning. Texas and Louisiana petrochemical complexes anchor procurement scale through multi-year vendor consolidation.
- Waste Management:Environmental remediation contractors building in-house hazardous materials response teams drive equipment professionalization. Clean Harbors and regional service providers are absorbing kit procurement into integrated response contracts.
- Marine:Tanker fleets, bunkering operations, and port terminal infrastructure require MARPOL-certified containment capabilities.
- Transportation:Railcar loading facilities, trucking terminals, and pipeline maintenance depots maintain mobile response inventories.
Industrial sites anchor volume commitments. Waste management is climbing the fastest.
End User:
Procurement sophistication tiers separate integrated service contract demand from transactional equipment purchasing.
- Oil & Gas Companies:Downstream refiners and upstream production operators bundle absorbent resupply, technician training, and disposal services. Integrated procurement committees at major operators are consolidating vendor relationships around full-service providers.
- Shipping Industry:Maritime fleet operators face accelerated chemical-grade containment procurement deadlines under MARPOL Annex II amendments. Classification society certification requirements elevate technical barriers for kit acceptance.
- Manufacturing:Chemical processors, food production facilities, and metal fabrication plants maintain OSHA-compliant response inventories.
- Government:Coast Guard stations, EPA response teams, and municipal fire departments procure through federal supply schedules.
Oil & gas companies command pricing leverage. Shipping industry requirements are tightening certification standards fastest.
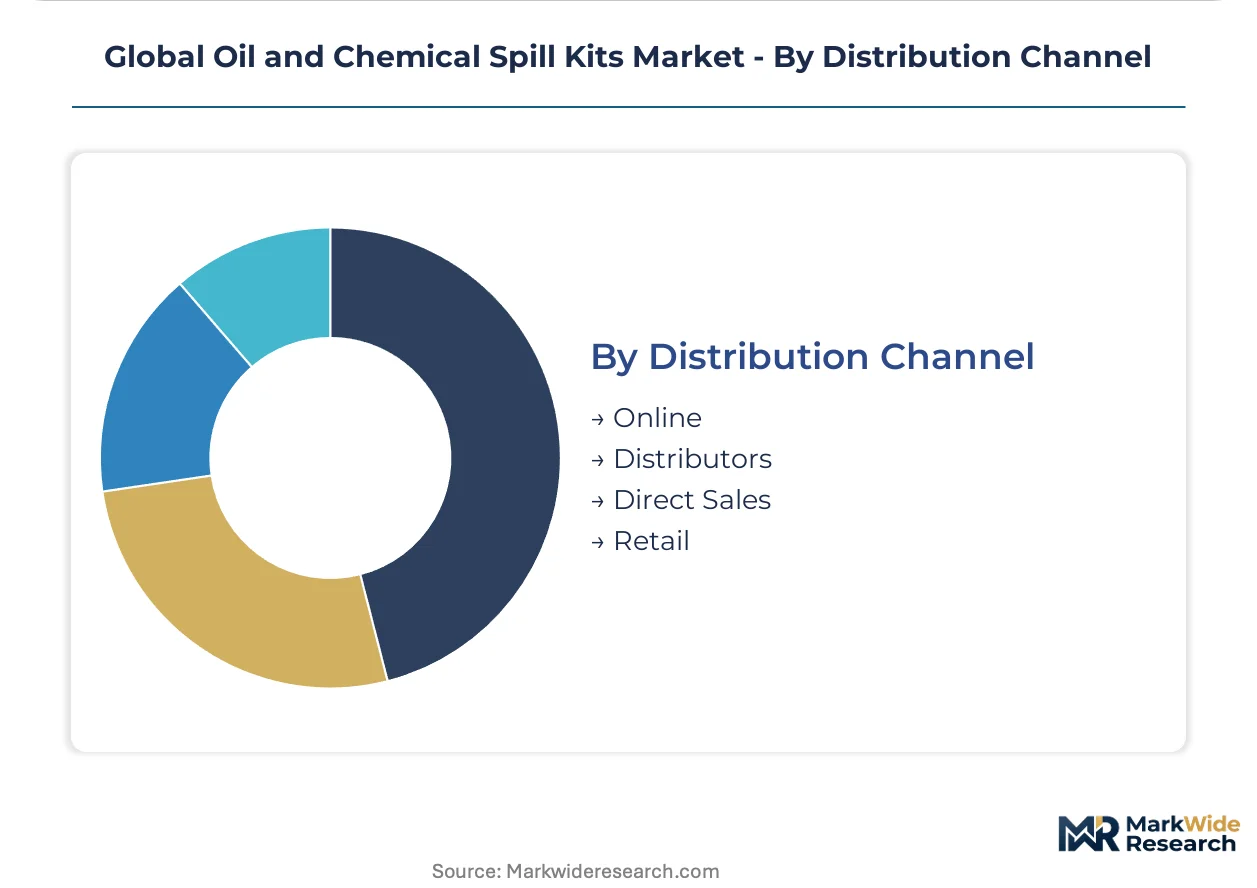
Distribution Channel:
Channel economics favor direct relationships that capture service revenue versus intermediated transactions with margin compression.
- Direct Sales:Manufacturers bypass industrial supply intermediaries through on-site inventory management and technician training programs. New Pig Corporation's plant-embedded service model exemplifies this channel's margin extraction.
- Distributors:Industrial supply houses and safety equipment specialists maintain broad SKU availability for spot purchasing. Regional distributors face pressure from direct manufacturer engagement at major accounts.
- Online:E-commerce platforms serve maintenance procurement for standardized absorbent replenishment.
- Retail:Hardware and safety supply stores address small-scale industrial and commercial maintenance demand.
Direct sales capture service value. Distributor channel share faces compression from manufacturer disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. US Gulf Coast facilities prioritize EPA-mandated absorbent stockpiles for refinery tank farms. European port authorities concentrate procurement on MARPOL-certified containment systems for chemical-grade discharge compliance.
United States
EPA SPCC enforcement drives replacement cycles at Texas and Louisiana petrochemical complexes. The agency's stepped-up inspection protocols force above-ground storage tank operators to expand absorbent inventories beyond historical minimums. Houston Ship Channel terminals anchor procurement scale through multi-year vendor consolidation.
Germany
REACH formulation restrictions redirect investment toward bio-based absorbent alternatives at industrial sites. ECHA's evolving substance limitations force kit assemblers to reformulate synthetic polypropylene chemistries. Port of Hamburg terminal operators must install Coast Guard-equivalent response infrastructure under EU Green Deal zero-pollution targets.
China
Dual carbon goals accelerate demand for environmental remediation equipment at coastal manufacturing zones. MEE discharge standards tighten for chemical processors in Yangtze River Delta clusters. Shanghai port authorities face mounting pressure to upgrade spill response capabilities for bunkering operations.
India
Jawaharlal Nehru Port Trust and Mundra Port expansion projects lack mature spill response infrastructure. DGFT import regulations shape kit specification standards for maritime fleet operators. Gujarat petrochemical corridors generate concentrated demand as domestic refining capacity expands.
Netherlands
Rotterdam port facilities lead European adoption of fifteen-minute response readiness mandates. EU Green Deal discharge thresholds force terminal operators to demonstrate Coast Guard-equivalent certification. Agricultural waste-derived sorbent pilots in food processing plants preempt REACH compliance costs.
Global Oil and Chemical Spill Kits Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in this market. The upper tier captures recurring service revenue through technician training and on-site inventory management. Mid-scale fabricators compete on absorbent mineral sourcing and marine certification speed. Dominant competitive moves include backward integration into bentonite deposits and direct-to-plant distribution disintermediation.
Within the integrated service tier, Clean Harbors leverages its certified HAZWOPER workforce network to anchor long-term refinery contracts. Oil-Dri Corporation of America exemplifies upstream control over Wyoming bentonite deposits. New Pig Corporation occupies a position defined by plant-embedded direct distribution models that bypass industrial supply intermediaries.
| Leading Market Players |
|---|
| Ecolab |
| Oil-Dri Corporation of America |
| New Pig Corporation |
| UltraTech International |
| Clean Harbors |
| 3M Company |
| Chemtex International |
| Darcy Spillcare Manufacture |
| Brady Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Wyoming bentonite miners and absorbent manufacturers lock in supply access while anchoring price visibility across volatile mineral markets. These arrangements insulate Oil-Dri Corporation and its customers from spot-market swings that disrupt second-tier kit assemblers sourcing on shorter cycles.
Pricing Analysis
Contract-based long-term offtake dominates absorbent procurement, with Coast Guard certification tier and volume scale as the primary price differentiation drivers. Cost compression in synthetic polypropylene absorbents is intensifying as silica gel manufacturers repurpose desiccant lines toward spill-grade production. Waste management contractors show the least price sensitivity due to integrated service bundling, while small industrial maintenance buyers face acute margin pressure.
Supply Chain Analysis
Wyoming bentonite deposits anchor raw material sourcing for premium clay absorbents, with polypropylene resin production concentrated in Texas and Louisiana petrochemical corridors. Kit assembly draws from PVC-coated fabric manufacturers in China, nitrile glove producers in Malaysia, and UN-certified container fabricators in Germany. Single-source vulnerability around Wyoming mineral access threatens margin stability for non-integrated competitors. Distribution runs through direct manufacturer-to-plant relationships that bypass industrial supply intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellulose-based agricultural waste absorbents pose a credible substitution threat to petroleum-derived sorbents as REACH restrictions harden, forcing incumbents to defend formulation positions through bio-based R&D or backward integration into compliant chemistries.
For Market Incumbents: Secure captive bentonite supply through long-term mineral leases or exclusive offtake arrangements before second-tier competitors exhaust accessible deposits. Anchor refinery relationships through multi-year technician training contracts that embed switching costs, neutralizing silica gel substitution threats from desiccant manufacturers entering spill-grade markets. For New Entrants and Emerging Players: Technician training and on-site inventory management services represent the most penetrable white-space where incumbent manufacturers under-serve mid-scale industrial accounts. Target Indian port modernization projects at Jawaharlal Nehru Port Trust and Mundra Port, where DGFT import regulations create certification barriers for established Western suppliers. Lead with Coast Guard-equivalent certification speed as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive mineral deposits and certified HAZWOPER workforce networks capable of anchoring recurring service revenue. Long-term viability hinges on regulatory divergence between EPA and ECHA frameworks persisting, which rewards multi-certification capabilities. Watch for MARPOL Annex II compliance deadline acceleration as the inflection signal indicating demand surge for chemical-grade containment systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bentonite Deposits | Oil-Dri Corporation's Wyoming captive supply locks out competitors from premium absorbent mineral sourcing. |
| Coast Guard Certification Investment | Rotterdam and Hamburg port authorities demand fifteen-minute response readiness, elevating technical barriers. |
| Direct-to-Plant Distribution Buildout | New Pig Corporation's embedded service model captures service revenue beyond equipment-only transactions. |
| HAZWOPER Workforce Expansion | Clean Harbors leverages certified technician scarcity to anchor long-term refinery service contracts. |
| Bio-Based Absorbent R&D | German food processors pilot agricultural waste sorbents to preempt REACH synthetic chemistry restrictions. |
Study Parameters
A standing panel of hazardous materials response technicians, refinery procurement directors, port authority environmental compliance officers, and bentonite mining operations managers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against EPA SPCC enforcement records, MARPOL Annex II amendment texts, ECHA substance restriction databases, and USGS mineral commodity summaries. Bottom-up kit shipment estimates triangulated against top-down petrochemical capacity expansion announcements.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for absorbent mineral exports, Coast Guard certification issuance records, and SEC filings from publicly traded environmental services firms. The analytical framework modeled product type, application, end user, and distribution channel dimensions across the projection horizon. CAGRs derived from segment-level demand elasticity analysis incorporating MARPOL compliance deadline schedules and EPA inspection protocol intensification trajectories.
Forecasts assume regulatory continuity in EPA SPCC enforcement and ECHA REACH substance restriction regimes; material policy shifts would require re-modeling absorbent chemistry substitution curves and certification timeline assumptions. Practitioners should keep alternative scenarios live as EU Green Deal zero-pollution ambition and dual carbon goals in China evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Methane Hydrate Extraction Market
Oil & Gas
Vietnam Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Well Test Market
Oil & Gas
Romania Oil and Gas Downstream Market
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Oil and Gas Accumulators Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
Well Testing Services Market
Oil & Gas
Pipeline Pigging Services Market
Oil & Gas
North America Proppants Market