
 Sri Lanka Life and Non-Life Insurance Market | 2026-2036
Sri Lanka Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Sri Lanka Life and Non-Life Insurance Market Analytics
The gap between premium life products with investment-linked features and basic term coverage is broadening as insurers target divergent wealth segments. Ceylinco Life Insurance PLC leverages its extensive agent network to sustain dominance in rural penetration. AIA Insurance Lanka PLC differentiates through digital-first distribution and bancassurance partnerships with commercial banks. Softlogic Life Insurance PLC competes on unit-linked product innovation tied to the Colombo Stock Exchange.
Sri Lanka Life and Non-Life Insurance encompasses risk-pooling contracts where life coverage provides mortality and savings benefits while non-life segments indemnify against property, health, and liability losses, with policies governed by the Insurance Ordinance and prudential rules on capital adequacy. Life Insurance and Health Insurance together anchor the largest premium pools, though Motor Insurance faces margin compression from frequent claims inflation and imported spare part costs. Bancassurance and direct digital channels represent the fastest-growing distribution pathways as smartphone penetration rises among younger policyholders.
The Insurance Regulatory Commission of Sri Lanka enforces risk-based capital standards and consumer protection codes that determine which products reach market and at what pricing. Sri Lanka's central bank coordinates macro-prudential oversight with the regulator to ensure sectoral stability amid currency volatility. Stakeholders must monitor how regulatory capital hikes and mandatory reinsurance cessions reshape competitive viability for mid-tier domestic carriers.
Market Dynamics
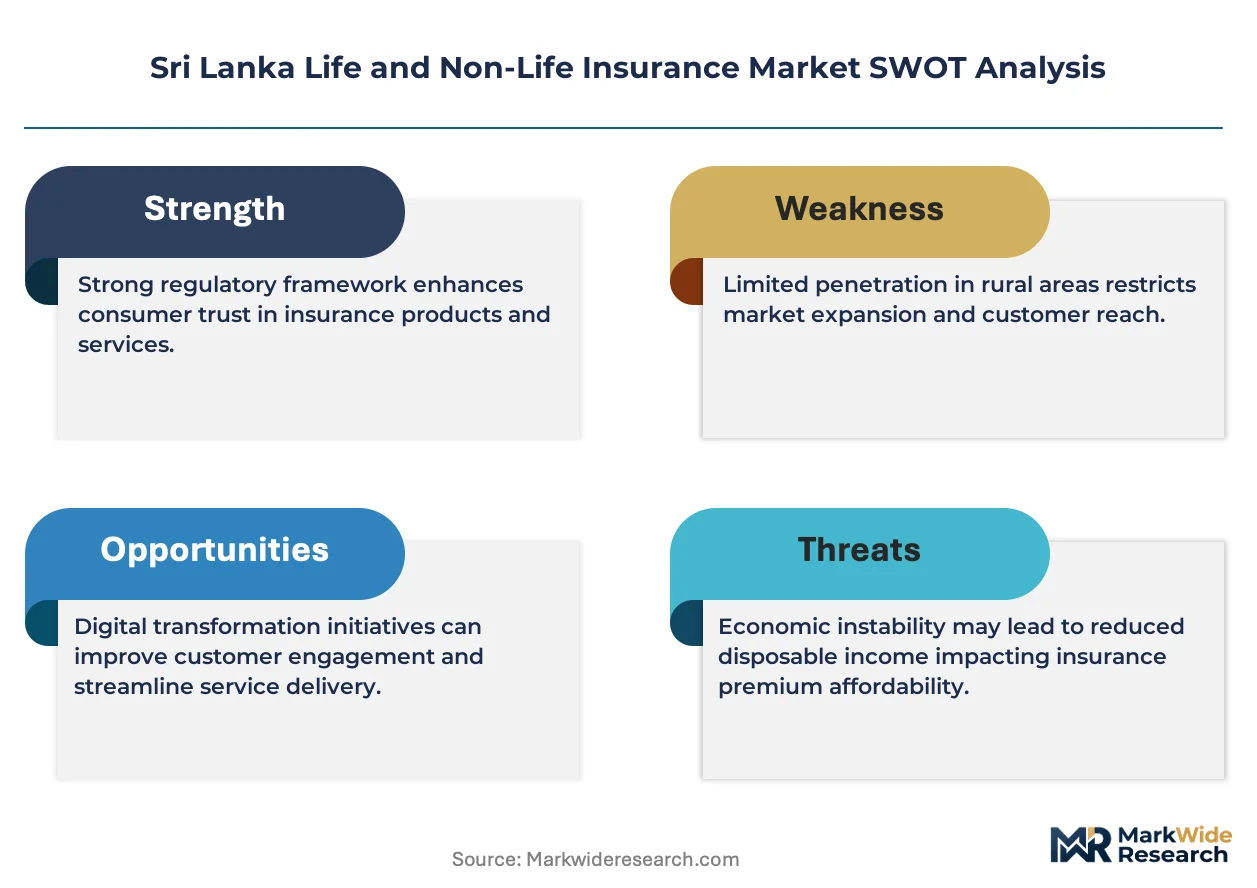
The Insurance Regulatory Commission of Sri Lanka's risk-based capital framework is compressing margins for mid-tier carriers and accelerating consolidation toward bancassurance-heavy distribution models.
Growth Catalysts
- Smartphone penetration:Younger policyholders in Colombo and Gampaha districts are migrating to direct digital channels for policy issuance and premium payments, bypassing traditional agent networks.
- Unit-linked product structures:Insurers tie mortality coverage to Colombo Stock Exchange equity funds, attracting salaried professionals seeking inflation-hedged savings instruments.
- IRCSL solvency requirements:Tighter capital adequacy rules are forcing weaker domestic players toward merger discussions, concentrating premium collection among solvent carriers.
Market Restraints
- Imported spare part costs:Motor insurance claims inflation is eroding underwriting margins as Sri Lanka's currency volatility raises replacement part prices for vehicle repairs.
- Western Province demand concentration:Colombo, Gampaha, and Kalutara districts account for disproportionate premium pools, leaving rural provinces with thin risk-pooling bases.
- Basic term coverage substitution:Low-income households favor informal savings cooperatives over formal insurance, limiting penetration outside the salaried middle class.
Strategic Opportunities
- Southern Province underpenetration:Galle and Matara districts show rising household income without proportional insurance adoption, creating whitespace for micro-premium products.
- Digital health ecosystems:Telemedicine platforms in Colombo are converging with outpatient care riders, enabling insurers to embed coverage into primary healthcare delivery.
- Central Bank coordination:Macro-prudential oversight alignment between the regulator and monetary authority is stabilizing currency hedging costs for foreign reinsurance cessions.
Industry Challenges
- Actuarial talent scarcity:Sri Lanka's universities produce insufficient qualified underwriters, forcing carriers to recruit from India and Singapore at premium compensation.
- Legacy core system integration:Mid-tier insurers struggle to connect policy administration platforms to mobile payment gateways, delaying digital channel rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sri Lanka Life and Non-Life Insurance Market |
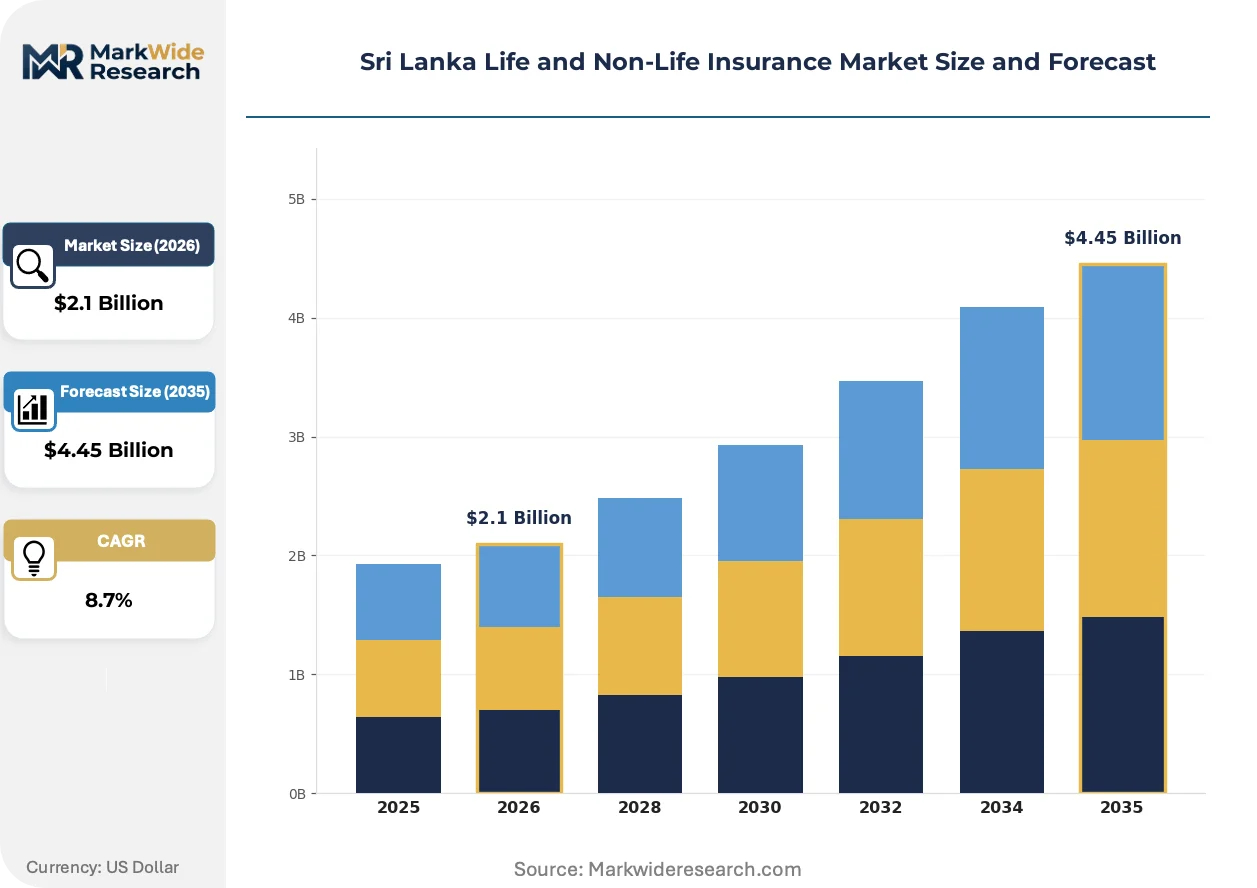
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Life Insurance, Health Insurance, Property Insurance, Motor Insurance Customer Segment: Individuals, Corporates, SMEs, Government Distribution Channel: Agents, Brokers, Direct Sales, Bancassurance Policy Duration: Short-term, Long-term, Renewable, Fixed-term |
| Companies Covered | Ceylinco Life Insurance PLC, Allianz Insurance Lanka Ltd, Softlogic Life Insurance PLC, Sri Lanka Insurance Corporation, AIA Insurance Lanka PLC, MSBL Insurance, Arpico Insurance, Union Assurance PLC, Janashakthi Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sri Lanka Life and Non-Life Insurance Market Evolving Landscape
Distribution architecture is fragmenting as smartphone-enabled policyholders abandon agent-heavy models, while regulatory capital pressure forces product redesign around savings-linked mortality coverage.
Artificial intelligence underwriting engines are converging with mobile-first distribution platforms. Insurers in Colombo deploy algorithmic risk scoring for instant policy issuance. Younger salaried professionals in the Western Province adopt these channels fastest. The technology is converging with traditional agent networks, compressing commission structures and forcing rural-focused carriers to retrain field staff as financial advisors.
The Insurance Regulatory Commission of Sri Lanka's consumer protection codes now mandate plain-language policy documentation and cooling-off period disclosures. This friction raises product development costs for complex unit-linked offerings. Life insurers with investment-heavy portfolios face the steepest compliance burden, responding by simplifying benefit illustrations and pre-sale disclosure workflows.
Households are unbundling mortality coverage from savings vehicles, treating pure protection and wealth accumulation as separate purchase decisions. Bancassurance partnerships at commercial banks are displacing tied-agent distribution for middle-class customers in Colombo and Kandy. This pattern is most visible among dual-income households in the Western Province, where premium collection through salary-deduction schemes now outpaces traditional renewal channels.
Sri Lanka Life and Non-Life Insurance Market Segmentation
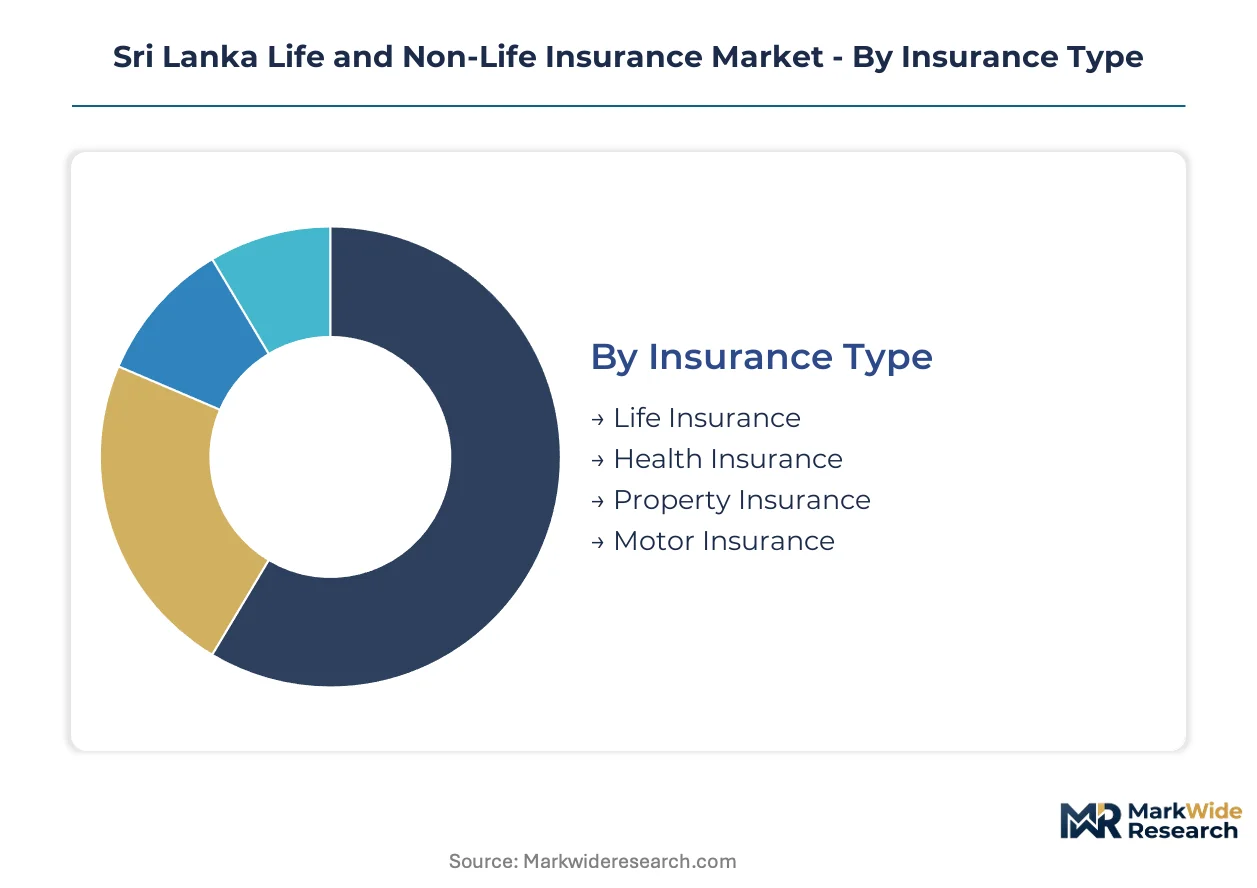
Sri Lanka's insurance market fragments across risk pools, buyer profiles, and distribution architectures that each demand distinct capital deployment. Carriers must align product development and channel investment with segment-specific solvency requirements and commission structures.
Insurance Type:
Capital intensity varies sharply across risk pools, with life and health segments demanding the largest statutory reserves and longest duration asset-liability matching.
- Life Insurance:Long-duration mortality and savings contracts require substantial investment in fixed-income portfolios to match liabilities. Salaried households in Colombo's Western Province dominate premium flows, driven by tax-advantaged retirement accumulation and mandatory group coverage through employers.
- Health Insurance:Outpatient and inpatient reimbursement products face accelerating claims frequency as private hospital networks expand in Gampaha and Kandy districts. Carriers must build dedicated claims administration infrastructure and provider contracting teams to manage cost escalation.
- Property Insurance:Fire and natural peril coverage for commercial assets concentrates among manufacturing and tourism operators in coastal districts. Reinsurance cessions to international markets absorb catastrophe exposure.
- Motor Insurance:Third-party liability and comprehensive vehicle coverage generate high transaction volumes but compressed underwriting margins from imported spare part inflation and currency volatility.
Most installed capacity flows through Life Insurance. Expansion is steepest in Health Insurance.
Customer Segment:
Buyer sophistication and policy complexity diverge across household, enterprise, and institutional purchasers, shaping product design and servicing economics.
- Individuals:Retail policyholders purchase mortality protection, medical reimbursement, and personal accident coverage through agent networks and emerging digital channels. Younger professionals in Colombo's IT and financial services sectors show strongest appetite for unit-linked investment products.
- Corporates:Large employers procure group life, health, and property programs with customized benefit structures and experience-rated pricing. Multinational manufacturing operations in Katunayake and Biyagama investment zones drive demand for comprehensive risk transfer.
- SMEs:Small and medium enterprises access standardized package policies combining property, liability, and business interruption coverage. Brokers serve this segment through simplified underwriting and premium financing arrangements.
- Government:State entities procure coverage for public infrastructure, vehicle fleets, and employee benefit schemes through tender-based procurement with domestic preference requirements.
Premium concentration sits with Individuals. The steepest expansion trajectory belongs to Corporates.
Distribution Channel:
Channel economics determine customer acquisition costs and persistency rates, with technology-enabled pathways displacing traditional commission-heavy structures.
- Agents:Tied and independent representatives dominate rural penetration through relationship-based selling. Ceylinco Life maintains the largest field force, with agents embedded in Galle and Matara districts for decades.
- Brokers:Intermediaries serve commercial and SME segments with market comparisons and placement services. Corporate risk managers in Colombo rely on broker expertise for complex program structuring and claims advocacy.
- Direct Sales:Telephone and online channels capture price-sensitive customers seeking standardized term and motor products. Smartphone penetration among under-35 policyholders in the Western Province accelerates this shift.
- Bancassurance:Commercial bank partnerships distribute investment-linked life products through branch networks and salary-deduction schemes. AIA Insurance Lanka leverages alliances with leading banks to access affluent depositors.
Most premium volume runs through Agents. Digital-enabled pathways are gaining share fastest.
Policy Duration:
Contract tenor shapes capital requirements, renewal economics, and the intensity of policy administration investment.
- Short-term:Annual renewable contracts for motor, property, and travel coverage require frequent re-underwriting and price adjustment. Currency volatility complicates pricing for imported asset coverage.
- Long-term:Multi-decade life and annuity contracts lock in mortality assumptions and investment returns. The Insurance Regulatory Commission of Sri Lanka mandates rigorous asset-liability matching for these liabilities.
- Renewable:Guaranteed renewable health and term life products balance customer retention with periodic repricing. Insurers embed limited rate increase provisions to manage adverse selection.
- Fixed-term:Pure protection products with defined expiration dates, such as mortgage redemption and education funding policies, align coverage with specific liability durations.
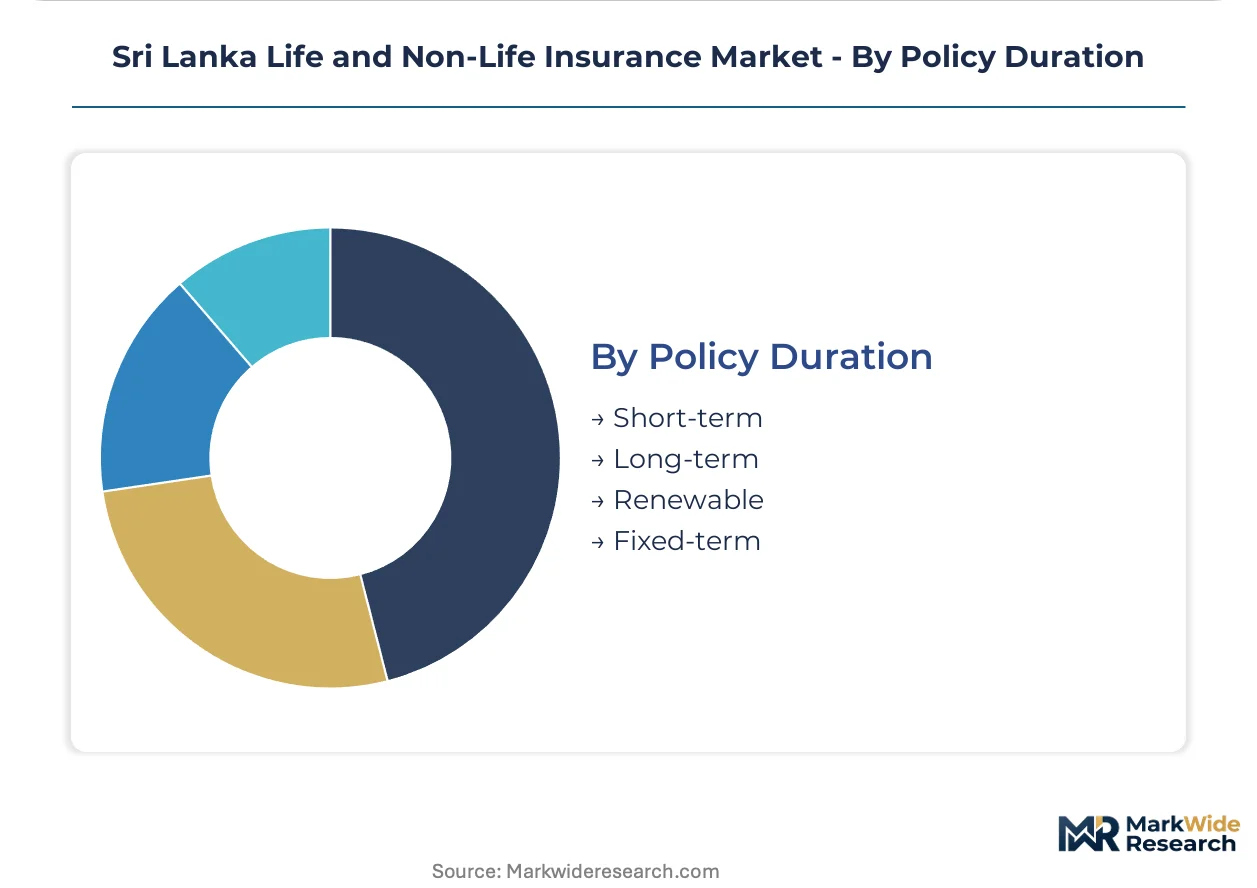
Long-term contracts anchor carrier balance sheets. Renewable structures are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Actuarial talent concentrates in Colombo's Western Province, where university programs and professional institutes anchor the industry's technical workforce. This geographic clustering shapes competitive dynamics across Sri Lanka's insurance landscape.
Western Province
Colombo, Gampaha, and Kalutara districts generate the majority of premium collection through salaried middle-class households and corporate group schemes. The Insurance Regulatory Commission of Sri Lanka's solvency requirements hit mid-tier carriers hardest here, forcing consolidation discussions. Colombo's financial district hosts the largest bancassurance partnerships and digital distribution platforms.
Southern Province
Galle and Matara districts show rising household incomes without proportional insurance penetration, creating whitespace for micro-premium term products. Rural savings cooperatives compete directly with formal carriers for low-income households. Ceylinco Life's agent network maintains decades-long presence in coastal towns, sustaining relationship-based distribution.
Central Province
Kandy district anchors bancassurance growth through commercial bank partnerships targeting dual-income professionals. The Insurance Regulatory Commission of Sri Lanka's consumer protection codes mandate plain-language documentation, raising compliance costs for unit-linked product sales. Private hospital networks in Kandy drive health insurance claims frequency.
Sabaragamuwa Province
Ratnapura district's gem and agricultural economy generates demand for property and personal accident coverage through SME package policies. Currency volatility complicates pricing for imported equipment coverage. Brokers serve this segment through simplified underwriting and premium financing arrangements.
Sri Lanka Life and Non-Life Insurance Market Competitive Landscape
Top-tier vendors anchor the bancassurance and digital distribution segments, while mid-tier domestic carriers face margin compression from regulatory capital requirements. The market structures around three tiers: state-backed incumbents with legacy infrastructure, multinational-affiliated players with technology transfer advantages, and consolidating domestic specialists. Strategic archetypes include agent-network dominant rural penetrators, digital-first urban specialists, and unit-linked product innovators. Competitive moves concentrate on merger discussions for solvency compliance and mobile payment gateway integration for channel expansion.
Within the multinational-affiliated tier, AIA Insurance Lanka PLC and Allianz Insurance Lanka Ltd represent technology-forward distribution models. Ceylinco Life Insurance PLC anchors the agent-network archetype through field force scale. Softlogic Life Insurance PLC occupies a position exemplifying unit-linked product innovation tied to equity market exposure. These three carriers illustrate the strategic divergence between bancassurance-heavy, rural-agent, and investment-linked positioning.
| Leading Market Players |
|---|
| Ceylinco Life Insurance PLC |
| Allianz Insurance Lanka Ltd |
| Softlogic Life Insurance PLC |
| Sri Lanka Insurance Corporation |
| AIA Insurance Lanka PLC |
| MSBL Insurance |
| Arpico Insurance |
| Union Assurance PLC |
| Janashakthi Insurance |
| Others |
Value Network & Pricing Analysis
Actuarial talent clustering in Colombo's Western Province widens pricing-tier spreads between premium investment-linked products and basic term coverage, as labor-cost differentials between qualified underwriters and commission-based agents feed directly into product development economics and distribution overhead structures.
Pricing Analysis
Bundled mortality-savings products command premium pricing through the Colombo Stock Exchange equity linkage, while unbundled pure-protection term coverage competes on minimal commission loads. Price differentiation rests on investment complexity tiers and bancassurance channel access, with salary-deduction schemes showing lowest price sensitivity among Colombo's dual-income households. Cost compression in basic term segments intensifies because informal savings cooperatives undercut formal carrier pricing in rural districts. SME package policy buyers in Ratnapura and Kandy exhibit highest price sensitivity due to currency volatility on imported equipment coverage.
Supply Chain Analysis
Regional distribution centers in Colombo anchor hub-and-spoke patterns for policy issuance and claims processing, with satellite operations in Gampaha and Kandy handling secondary underwriting. Geographic supply concentration draws from India for actuarial talent recruitment, Singapore for reinsurance capacity, and domestic university programs for entry-level underwriting pools. Raw material dependencies center on foreign exchange reserves for international reinsurance cessions, imported medical equipment for health claims valuation, and spare parts for motor repair settlements. Single-source vulnerability sits with Sri Lanka's currency hedging costs for foreign reinsurance. Distribution runs through agent networks for rural penetration and direct digital channels for urban salaried segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sri Lanka's insurance market compounds steadily as regulatory capital requirements force consolidation toward solvent carriers, concentrating premium flows and underwriting capacity among compliant operators across the analysis window.
For Market Incumbents: Acquire digital payment gateway infrastructure to compress policy administration costs and accelerate mobile-first distribution rollout. Consolidate weaker domestic competitors facing Insurance Regulatory Commission of Sri Lanka solvency pressure before bancassurance partnerships lock in exclusive bank distribution. Channel control through proprietary mobile platforms counters agent commission inflation and smartphone-enabled policyholder migration. For New Entrants and Emerging Players: Insurance Regulatory Commission of Sri Lanka consumer protection code mandates in Sri Lanka open a window for compliance-native product design targeting simplified disclosure workflows. Whitespace concentrates in Southern Province micro-premium term products for Galle and Matara's rising-income households underserved by formal carriers. Telemedicine-embedded outpatient riders in Colombo's digital health ecosystem offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier domestic carriers facing forced merger discussions under tightened capital adequacy rules. Long-term viability favors carriers with established bancassurance partnerships and scalable agent networks across provincial penetration. Watch regulatory capital hike announcements as the inflection signal for accelerated consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Payment Gateway Integration | Mobile-first policy issuance captures Colombo's smartphone-enabled salaried professionals fastest. |
| Bancassurance Partnership Expansion | Salary-deduction schemes through commercial banks displace traditional agent renewal channels. |
| Unit-Linked Product Innovation | Colombo Stock Exchange equity linkage attracts inflation-hedging household savings. |
| Micro-Premium Rural Penetration | Southern Province whitespace in Galle and Matara counters Western Province concentration. |
| Telemedicine Rider Embedding | Outpatient care convergence with Colombo digital health platforms creates embedded distribution. |
Research Methodology
Multiple input streams — primary interviews, regulatory filings, and trade data — were reconciled to construct this analysis. Conversations with Insurance Regulatory Commission of Sri Lanka officials, actuarial directors at domestic carriers, bancassurance partnership managers at commercial banks, and claims administrators at private hospital networks informed operational dynamics. Secondary validation drew from central bank macro-prudential reports, Insurance Ordinance amendments, reinsurance market disclosures, and Colombo Stock Exchange equity fund performance data. Bottom-up policy issuance counts and top-down premium pool estimates were triangulated against solvency filing aggregates.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include insurance type, customer segment, distribution channel, and policy duration, with provincial penetration rates as a geography-specific overlay. CAGRs were derived from trend extrapolation of premium collection growth adjusted for regulatory capital impact and consolidation velocity. Forecast inputs incorporated smartphone penetration curves, currency volatility assumptions for imported spare parts, and actuarial talent supply constraints from domestic university output.
Revisions become necessary when regulatory capital thresholds shift, currency hedging costs spike for foreign reinsurance, or informal savings cooperatives gain formal regulatory recognition. Forecasts reflect documented assumptions on consolidation timing and digital adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
Burial Insurance Market
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market
Life and Non Life Insurance
Children Life Insurance Market
Life and Non Life Insurance
Russia Life and Non-Life Insurance Market
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
Austria Life and Non-Life Insurance Market
Life and Non Life Insurance
France Life and Non-Life Insurance Market
Life and Non Life Insurance
Norway Life and Non-Life Insurance Market
Life and Non Life Insurance
Uruguay Life and Non-Life Insurance Market
Life and Non Life Insurance
Poland Life and Non-Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
Peru Life and Non-Life Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market
Life and Non Life Insurance
Group Life Insurance Market
Life and Non Life Insurance
Singapore Life and Non-Life Insurance Market