
 Penoxsulam Market | 2026-2036
Penoxsulam Market Size, Share, and Industry Trends Forecast 2026-2036
Penoxsulam Market Analytics
Glyphosate resistance in rice paddies is broadening the economic case for penoxsulam-based alternatives across Asian agronomy. Dow Chemical Co. leverages its integrated sulfonylurea chemistry platform to control upstream active-ingredient supply. Syngenta AG anchors its position through proprietary formulation technology that enhances rainfastness in tropical conditions. Nufarm Limited specializes in distributing penoxsulam through cooperatives in Australia and Southeast Asia.
Penoxsulam is a triazolopyrimidine sulfonanilide herbicide with a molecular formula of C16H14F3N5O5S, functioning as an acetolactate synthase inhibitor that disrupts branched-chain amino acid synthesis in susceptible weeds. The herbicides segment dominates product-type revenue due to rice-crop specificity, while liquid concentrates command formulation preference among mechanized spraying operations in East Asia. Agricultural applications generate the largest end-user pull from farmer cooperatives, though horticultural demand is gaining traction in protected-cropping systems.
The EPA governs penoxsulam tolerance levels in US food commodities, while China's MEE enforces environmental release standards for triazolopyrimidine manufacturing facilities. REACH compliance in Europe restricts certain co-formulant chemistries, pushing suppliers toward greener adjuvant systems. Stakeholders must monitor regulatory divergence on maximum residue limits, as tightening standards in import markets will determine which formulation portfolios retain commercial viability.
Market Dynamics
Glyphosate resistance proliferation across Southeast Asian rice belts is forcing wholesale substitution toward acetolactate synthase inhibitors. The EU's Sustainable Use of Pesticides Regulation is compressing formulation innovation cycles while tightening residue thresholds for export-bound harvests.
Growth Catalysts
- REACH compliance pressure:Europe's tightening co-formulant restrictions are accelerating green adjuvant R&D. Suppliers reformulating for REACH compatibility capture premium positioning in regulated import markets.
- Vietnam's Mekong Delta intensification:Triple-cropping rice systems in An Giang and Dong Thap provinces generate concentrated procurement volumes. Farmer cooperatives in this cluster negotiate multi-year supply contracts.
- Rainfastness technology:Proprietary formulation advances that bind active ingredients to leaf surfaces during tropical downpours extend application windows. Mechanized spraying operations in East Asia prioritize these performance characteristics.
Market Restraints
- Trifluoromethyl feedstock volatility:Fluorinated intermediate supply concentrates in Chinese specialty chemical clusters. Price swings in this input cascade directly into penoxsulam manufacturing economics.
- EPA residue tolerance compression:Sequential tolerance reductions for rice grain and straw narrow the application-to-harvest interval. Label restrictions limit operational flexibility for US growers.
- Glufosinate substitution threat:Alternative broad-spectrum herbicides with established resistance management protocols compete for the same rice paddy acreage. Some agronomists favor glufosinate's shorter soil persistence profile.
Strategic Opportunities
- Protected-cropping horticulture:Greenhouse vegetable systems in Shandong and Jiangsu provinces represent untrained demand for selective weed control. Penoxsulam's crop safety profile transfers to high-value protected environments.
- Drone application compatibility:Ultra-low volume formulations that integrate with unmanned aerial spraying systems open new service-provider channels. Agricultural drone fleets in Vietnam and Thailand seek herbicide products engineered for aerial dispersion.
- EU Green Deal alignment:Farm-to-Fork pesticide reduction targets create market space for precision application technologies. Formulations enabling 50% rate reduction without efficacy loss qualify for national subsidy programs.
Industry Challenges
- Formulation chemist scarcity:Expertise in sulfonylurea-triazolopyrimidine compatibility and tropical stability testing concentrates among retiring specialists. Recruitment pipelines for this hybrid skill set remain underdeveloped.
- Residue analytical capacity:Third-party testing laboratories capable of detecting sub-ppb penoxsulam metabolites face accreditation backlogs. Export certification delays strand containerized shipments at port.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Penoxsulam Market |
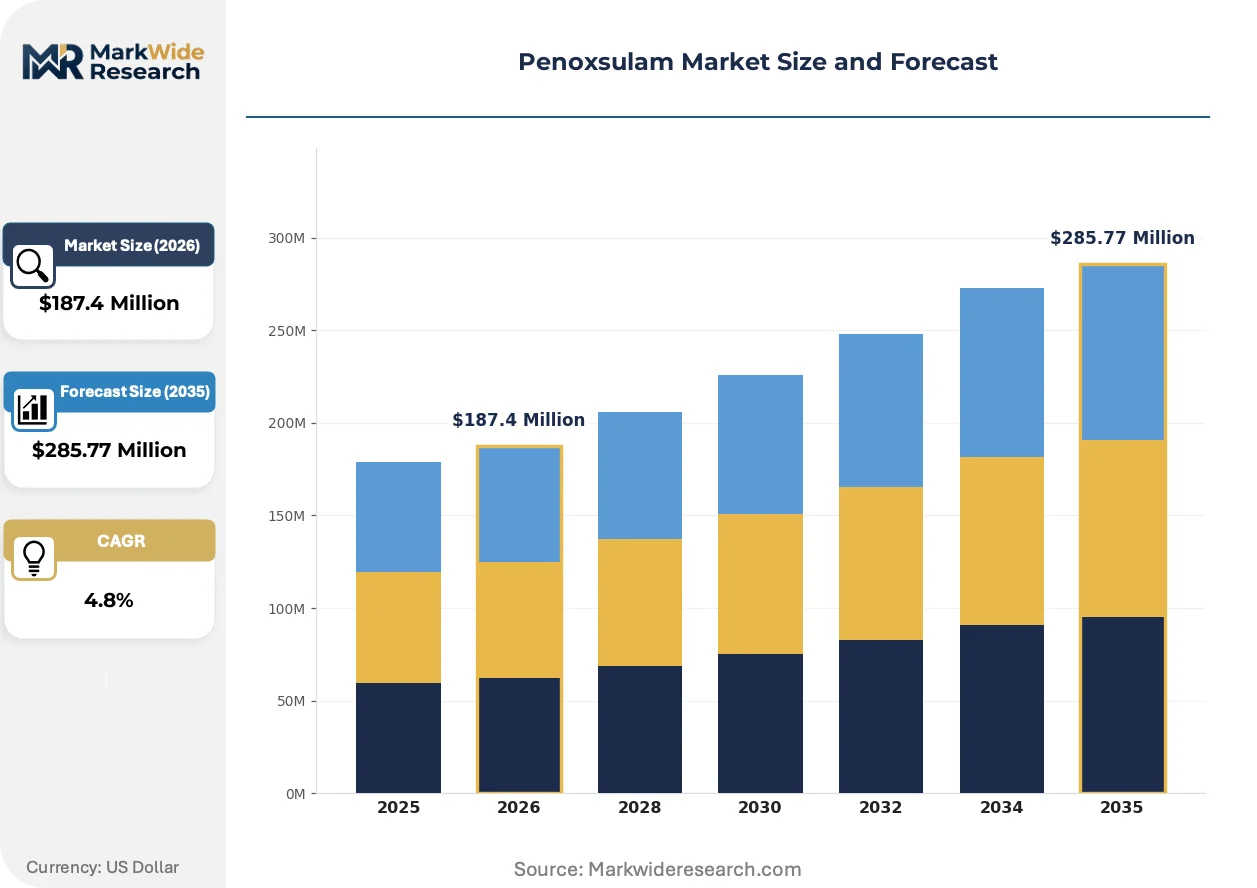
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Acaricides, Fungicides, Insecticides Application: Agricultural, Horticultural, Turf, Forestry End User: Farmers, Agricultural Cooperatives, Landscapers, Garden Centers Formulation: Granules, Liquid Concentrates, Soluble Powders, Emulsifiable Concentrates |
| Companies Covered | Dow Chemical Co., BASF SE, Syngenta AG, Corteva Agriscience, Bayer AG, Nufarm Limited, FMC Corporation, Sumitomo Chemical Co., Ltd., Hangzhou Tianlong Biotechnology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Penoxsulam Market Evolving Landscape
Formulation chemistry and application technology are converging to address tropical climate constraints and regulatory residue compression simultaneously. Three distinct vectors are restructuring competitive positioning.
Micro-encapsulation technology is overtaking conventional emulsifiable concentrate formats in premium segment penetration. This delivery system shields penoxsulam molecules from photodegradation and rainfall washoff. Large-scale rice cooperatives in Vietnam's Mekong Delta specify micro-encapsulated products for their mechanized fleets. The technology is overtaking standard formulations in contract negotiations where rainfastness guarantees determine supplier selection.
China's MEE environmental release standards for triazolopyrimidine manufacturing facilities are forcing capital deployment into closed-loop synthesis systems. Wastewater treatment intensity requirements have doubled since 2020. Active ingredient producers in Jiangsu and Zhejiang provinces are consolidating to amortize compliance infrastructure across larger output volumes. Mid-scale manufacturers without captive treatment capacity face operational license non-renewal.
Farmer cooperative procurement consolidation is compressing distributor margins and reordering channel economics. Volume aggregation through provincial cooperatives in Vietnam and Thailand replaces fragmented retail purchasing. Direct manufacturer-to-cooperative contracting is displacing traditional agrochemical distribution tiers in these procurement clusters. This concentration is most visible in Vietnam's Mekong Delta, where three cooperatives now control over half of regional herbicide procurement.
Penoxsulam Market Segmentation
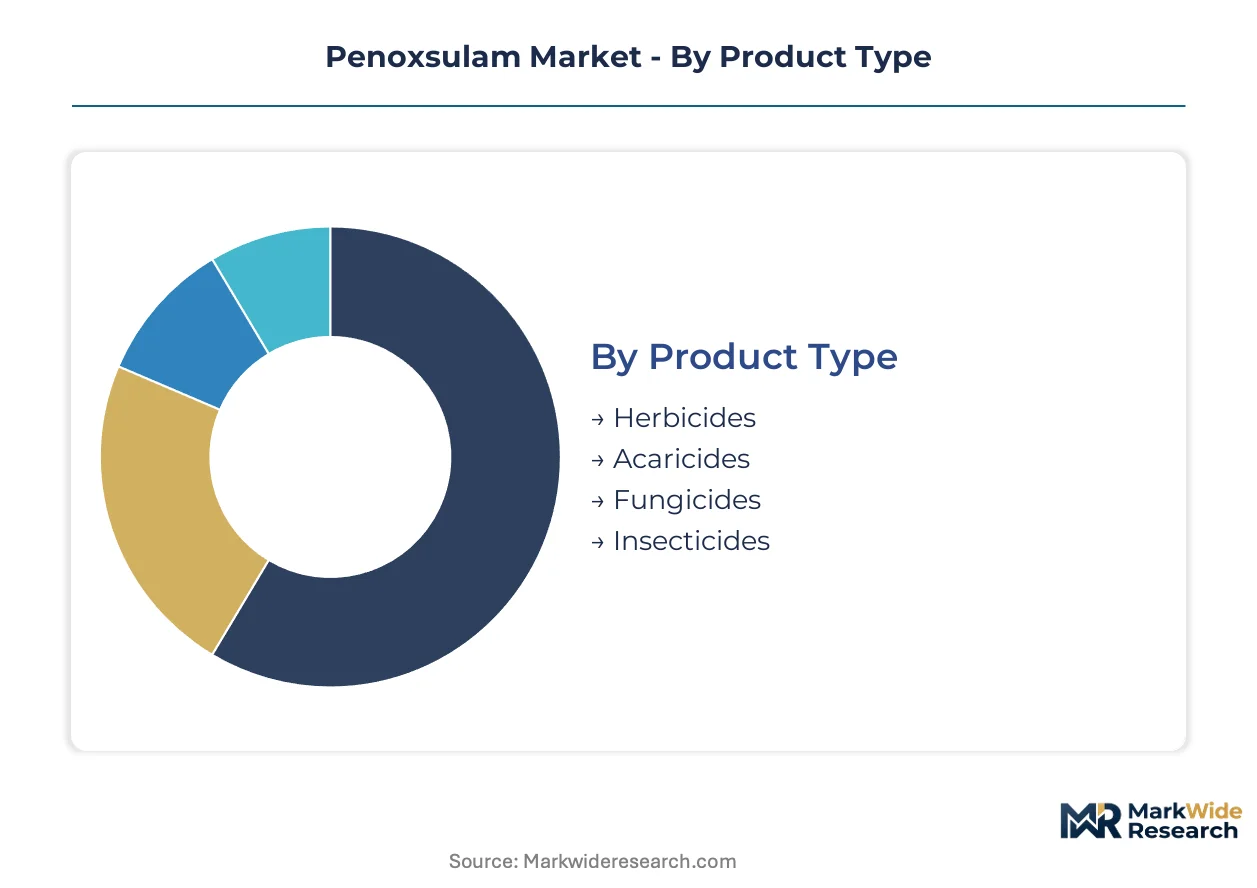
Penoxsulam's market structure reflects divergent regulatory burdens across crop systems and application methods. Segmentation reveals where EPA tolerance compression, REACH co-formulant restrictions, and tropical stability requirements concentrate commercial risk and reward.
Product Type:
EPA residue tolerances and REACH authorization requirements vary sharply across crop protection categories, determining which segments can serve export-bound rice harvests.
- Herbicides:Acetolactate synthase inhibition targets barnyardgrass and sedges in flooded rice paddies. Vietnam's Mekong Delta triple-cropping systems generate concentrated procurement volumes for selective post-emergence weed control.
- Acaricides:Miticidal applications against spider mites in protected vegetable systems require modified formulation chemistry to preserve crop safety margins in greenhouse environments.
- Fungicides:Triazolopyrimidine cores adapted for oomycete control in high-humidity rice belts.
- Insecticides:Cross-licensed neurotoxic modes for rice stem borer management in Southeast Asian intensive cultivation zones.
Herbicides sits at the top of the volume ranking, with acaricides climbing the fastest as protected-cropping horticulture expands in Shandong and Jiangsu provinces.
Application:
Cost tier differentiation separates commodity rice protection from high-value specialty crop systems, with formulation sophistication and service intensity scaling accordingly.
- Agricultural:Mechanized spraying operations across East Asian rice belts demand rainfast formulations that bind to leaf surfaces during tropical downpours. Farmer cooperatives in Vietnam's Mekong Delta negotiate multi-year supply contracts for volume procurement.
- Horticultural:Greenhouse vegetable systems in China's Shandong province apply penoxsulam for selective weed control where crop safety margins are narrow and residue thresholds are stringent.
- Turf:Golf course and sports field maintenance in subtropical climates requires low-rate precision application to avoid phytotoxicity on warm-season grasses.
- Forestry:Plantation weed control in pulpwood operations competes with aerial application economics against established phenoxy herbicide protocols.
Agricultural commands the dominant revenue share, while horticultural gains share fastest through protected-cropping expansion in high-value vegetable zones.
End User:
Customer type determines channel structure, with cooperative consolidation compressing distributor margins and reordering procurement economics toward direct manufacturer contracting.
- Farmers:Individual rice growers in fragmented landholding systems purchase through retail agrochemical networks with limited technical support.
- Agricultural Cooperatives:Provincial cooperatives in Vietnam and Thailand aggregate volume to displace traditional distribution tiers. Three Mekong Delta cooperatives now control over half of regional herbicide procurement.
- Landscapers:Commercial turf maintenance contractors specify rainfast formulations for operational scheduling flexibility in unpredictable tropical weather.
- Garden Centers:Retail packaged goods for consumer lawn and garden use face shelf-space competition from glyphosate-based alternatives with established brand recognition.
Agricultural cooperatives dominate volume procurement, with landscapers expanding most quickly through commercial turf maintenance contract growth.
Formulation:
Supply concentration in Chinese specialty chemical clusters shapes manufacturing economics, with environmental compliance intensity favoring scaled producers with captive wastewater treatment infrastructure.
- Liquid Concentrates:Mechanized spraying fleets in East Asia prioritize these formats for tank-mix compatibility and rapid field preparation. China's MEE environmental release standards for triazolopyrimidine manufacturing have doubled wastewater treatment intensity requirements since 2020.
- Micro-encapsulated variants:Advanced delivery systems shield penoxsulam molecules from photodegradation and rainfall washoff. Large-scale rice cooperatives in Vietnam specify these products for rainfastness guarantees in contract negotiations.
- Granules:Slow-release formulations for pre-emergence application in water-seeded rice systems.
- Soluble Powders:Dry flowable formats for aerial drone application compatibility in Vietnam and Thailand.
- Emulsifiable Concentrates:Conventional oil-in-water systems facing displacement by micro-encapsulation technology in premium contract segments.
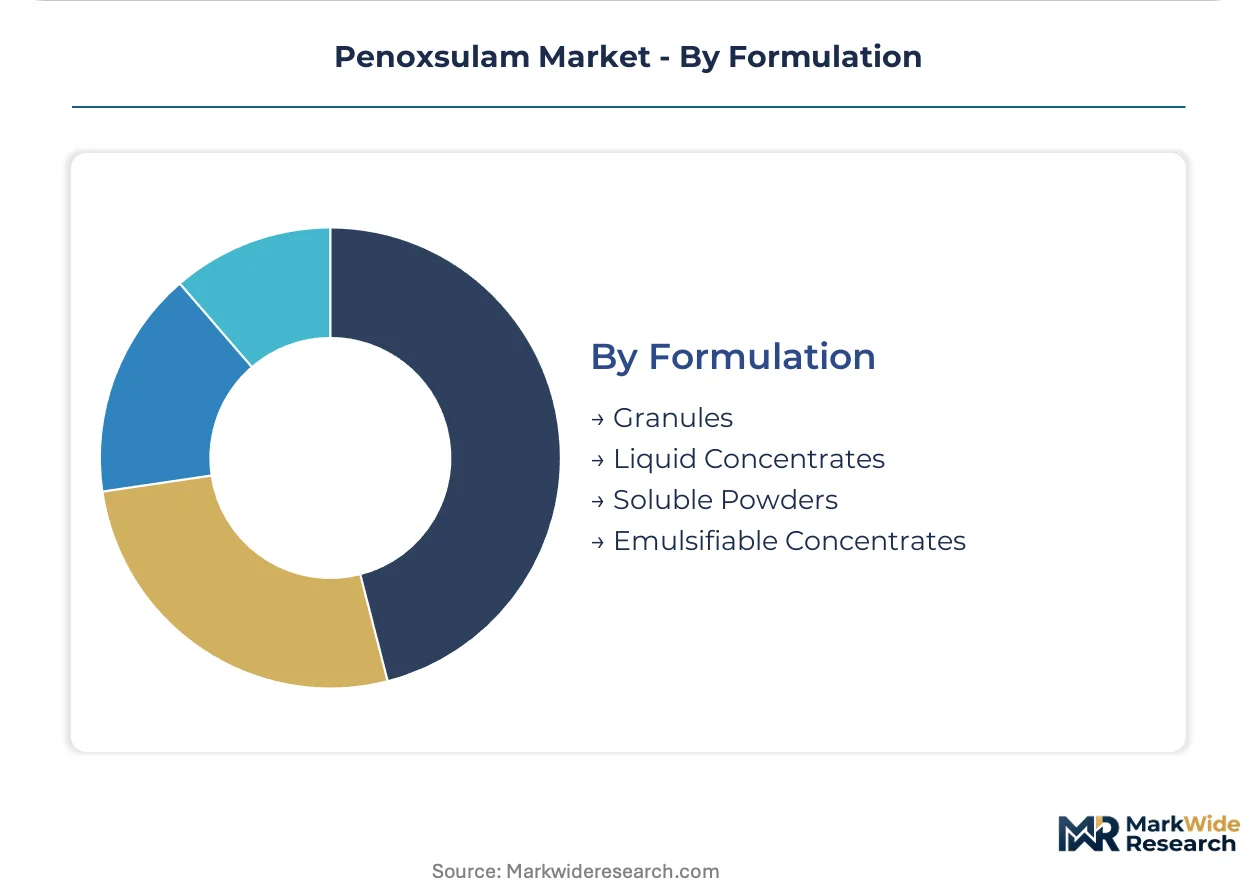
Liquid concentrates holds the volume lead, with micro-encapsulated variants gaining share fastest through cooperative procurement specifications for tropical rainfastness performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Mekong Delta anchors penoxsulam demand through triple-cropping rice intensification, with farmer cooperatives in An Giang and Dong Thap provinces driving concentrated procurement volumes.
Vietnam
Mekong Delta cooperatives aggregate herbicide demand from fragmented smallholders into multi-year supply contracts. The Ministry of Agriculture and Rural Development enforces pesticide residue monitoring for export-bound rice shipments. Can Tho City hosts formulation blending facilities serving the regional cooperative network.
China
Jiangsu and Zhejiang provinces concentrate active ingredient manufacturing for triazolopyrimidine herbicides. MEE environmental release standards have doubled wastewater treatment intensity requirements since 2020. Shandong province's greenhouse vegetable belts generate emerging horticultural demand for selective weed control.
United States
Arkansas and Louisiana rice belts require post-emergence herbicides resistant to tropical storm washoff. EPA tolerance compression for rice grain and straw narrows application-to-harvest intervals. Mississippi Delta milling clusters source formulations compliant with export market residue thresholds.
Thailand
Central Plains rice intensification drives mechanized spraying adoption for water-seeded systems. The Department of Agriculture regulates maximum residue limits for jasmine rice exports to EU markets. Suphan Buri and Ayutthaya provinces consolidate procurement through provincial agricultural cooperatives.
Australia
Murray-Darling Basin rice growers source penoxsulam through Nufarm's cooperative distribution network. APVMA registration requirements govern label claims for rainfastness performance. Riverina district irrigators specify micro-encapsulated formulations for variable weather conditions.
Penoxsulam Market Competitive Landscape
Global majors compete with regional champions across formulation technology and cooperative channel access. The market structures around three tiers: integrated chemistry platforms controlling upstream sulfonylurea supply, proprietary formulation specialists, and distribution-focused regional players. Strategic archetypes include rainfastness technology leaders, environmental compliance consolidators, and cooperative channel specialists. Capacity expansion in Chinese manufacturing clusters and direct manufacturer-to-cooperative contracting represent dominant competitive moves reshaping channel economics.
Within the integrated chemistry tier, Dow Chemical Co. and BASF SE exemplify global majors with captive active ingredient production. Syngenta AG occupies a position among formulation technology specialists emphasizing tropical stability performance. Nufarm Limited represents the cooperative channel archetype, anchoring distribution relationships across Australian and Southeast Asian agricultural collectives.
| Leading Market Players |
|---|
| Dow Chemical Co. |
| BASF SE |
| Syngenta AG |
| Corteva Agriscience |
| Bayer AG |
| Nufarm Limited |
| FMC Corporation |
| Sumitomo Chemical Co., Ltd. |
| Hangzhou Tianlong Biotechnology Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Micro-encapsulation technology migration simultaneously compresses manufacturing yields and consolidates supplier power among scaled producers with captive formulation R&D. The shift from conventional emulsifiable concentrates toward advanced delivery systems in Vietnam's Mekong Delta is reshaping cost economics while concentrating procurement leverage within three dominant cooperatives.
Pricing Analysis
Trifluoromethyl intermediate cost pass-through from Chinese specialty chemical clusters directly governs active ingredient pricing volatility. Three-tier pricing structure across premium micro-encapsulated, standard liquid concentrate, and economy emulsifiable concentrate levels segments buyer tiers by rainfastness specification and cooperative volume scale. Pricing pressure stems from glufosinate substitution in rice paddy applications, compressing margins on conventional formulations. Individual farmers in fragmented landholding systems exhibit highest price sensitivity, while Mekong Delta cooperatives with multi-year contracts absorb premiums for performance guarantees.
Supply Chain Analysis
Dual-sourcing mandates from Vietnam's agricultural cooperatives force manufacturers to qualify secondary active ingredient suppliers beyond Jiangsu and Zhejiang province incumbents. Penoxsulam production draws from fluorinated intermediate feedstocks, sulfonylurea chemistry platforms, and tropical stability adjuvants. Single-source vulnerability concentrates in Chinese environmental compliance consolidation, where MEE wastewater treatment license non-renewal threatens mid-scale manufacturer continuity. Distribution runs through direct manufacturer-to-cooperative contracting, displacing traditional agrochemical distributor tiers in concentrated procurement clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The penoxsulam market represents a late-cycle quality story as glyphosate resistance proliferation across Southeast Asian rice belts redirects demand toward premium ALS-inhibitor specifications with proven rainfastness profiles.
For Market Incumbents: Anticipate glufosinate substitution threats by deepening backward integration into trifluoromethyl intermediate supply and accelerating proprietary micro-encapsulation capacity expansion in Vietnam. Prioritize REACH-compliant green adjuvant R&D to defend premium positioning in EU export-bound rice markets. Lock multi-year supply contracts with Mekong Delta cooperatives before procurement consolidation completes.
For New Entrants and Emerging Players: EU Green Deal pesticide reduction targets in Europe open a window for precision application technologies enabling 50% rate reduction without efficacy loss. Target protected-cropping horticulture in Shandong and Jiangsu provinces where selective weed control demand remains untrained and cooperative procurement concentration is weakest. Pursue drone application compatibility certification as the primary go-to-market angle for aerial spraying service providers in Vietnam and Thailand.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Chinese manufacturers facing MEE environmental license non-renewal pressure. Long-term viability hinges on consolidation into scaled producers with captive wastewater treatment infrastructure and direct cooperative channel access. Monitor EPA tolerance compression trajectory for rice grain and straw as the critical inflection signal determining which formulation portfolios retain commercial viability in US export markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorinated Intermediates | Captive trifluoromethyl supply insulates manufacturing economics from Chinese specialty chemical cluster volatility. |
| Micro-Encapsulation Capacity Expansion | Rainfastness technology deployment captures premium positioning in Mekong Delta cooperative contract negotiations. |
| REACH-Compliant Green Adjuvant Development | Co-formulant reformulation qualifies products for EU Farm-to-Fork subsidy programs and export market access. |
| Drone Application Formulation Engineering | Ultra-low volume compatibility opens agricultural aerial spraying service channels in Vietnam and Thailand. |
| Direct Cooperative Channel Partnerships | Manufacturer-to-cooperative contracting displaces distributor margins in concentrated procurement clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with secondary validation. Conversations with formulation R&D directors, procurement leads at Vietnamese agricultural cooperatives, Chinese specialty chemical plant managers, and EPA regulatory affairs specialists informed demand and supply-side dynamics. Secondary sources included customs trade data for triazolopyrimidine herbicide flows, SEC filings from integrated chemical majors, MEE environmental release standard documentation, and EU REACH authorization databases. Bottom-up volume estimates from cooperative procurement clusters triangulated against top-down market sizing from active ingredient production capacity.
Comparable-period anchoring linked projection assumptions to historical reference intervals spanning regulatory regime transitions and technology substitution cycles. Segmentation modeling incorporated product type, application method, end-user archetype, formulation technology, and regional regulatory cluster dimensions across the analysis window. CAGRs derived from volume-weighted average growth trajectories in cooperative procurement zones, adjusted for EPA tolerance compression impacts and REACH compliance transition timelines. Forecast inputs included rice paddy acreage intensification rates, glyphosate resistance prevalence surveys, and drone spraying fleet expansion data.
Revisions become necessary when EPA tolerance compression accelerates beyond modeled trajectories, MEE enforcement actions trigger unanticipated manufacturing license revocations, or glufosinate resistance management protocols displace ALS-inhibitor market share faster than projected. Deviation in trifluoromethyl feedstock pricing volatility or Mekong Delta cooperative procurement consolidation speed would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
Linear Mercaptans Market
Chemicals
North America Oxo-Alcohol Market
Chemicals
Southeast Asia Construction Chemicals Market
Chemicals
Global Acetic Anhydride Market
Chemicals
Hydrophobing Agents Market
Chemicals
Ethyl Chloride Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
Methanol to Gasoline Market
Chemicals
Morpholine Market
Chemicals
Sodium Fluorosilicate Market
Chemicals
Menadione Market
Chemicals
Phenylethyl Market
Chemicals
Diethyl Sulfate Market
Chemicals
Cumene Hydroperoxide Market