
 Bulk Ingredients Market | 2026-2036
Bulk Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Ingredients Market Intelligence
Digital traceability platforms that verify ingredient origin and sustainability metrics are recalibrating the value proposition beyond mere price per ton. This shift allows major suppliers like Cargill, Incorporated to differentiate its offerings through certified supply chains. Archer Daniels Midland Company leverages its extensive global logistics network to ensure consistent supply for large-scale food manufacturers. Meanwhile, Tate & Lyle PLC specializes in value-added sweeteners and texturants, focusing on clean-label and sugar reduction solutions for the beverage industry.
Bulk ingredients refer to raw or semi-processed materials, such as starches, sugars, and oils, sold in large quantities, typically exceeding 25 kilograms per unit. These materials serve as the primary foundational components in the mass production of food, beverages, and pharmaceuticals. Within the product landscape, sweeteners and thickeners represent mature, high-volume categories driven by the processed food industry. Emulsifiers and stabilizers, however, constitute a higher-margin segment, where technical performance in applications like dairy products and bakery goods commands premium pricing.
Regulatory frameworks from bodies like the U.S. FDA and the European Food Safety Authority (EFSA) impose stringent standards on purity, labeling, and allergen declarations. In developing markets, agencies such as India's FSSAI are harmonizing local rules with international standards, impacting market access and compliance costs. Consequently, suppliers must decide whether to invest in multi-regional certification capabilities or to specialize in markets with lower regulatory hurdles.
Market Dynamics
The primary force shaping the bulk ingredients market is the recalibration of value away from pure commodity pricing towards verifiable sustainability and origin data, driven by digital traceability and consumer demand for transparency in food systems.
Growth Catalysts
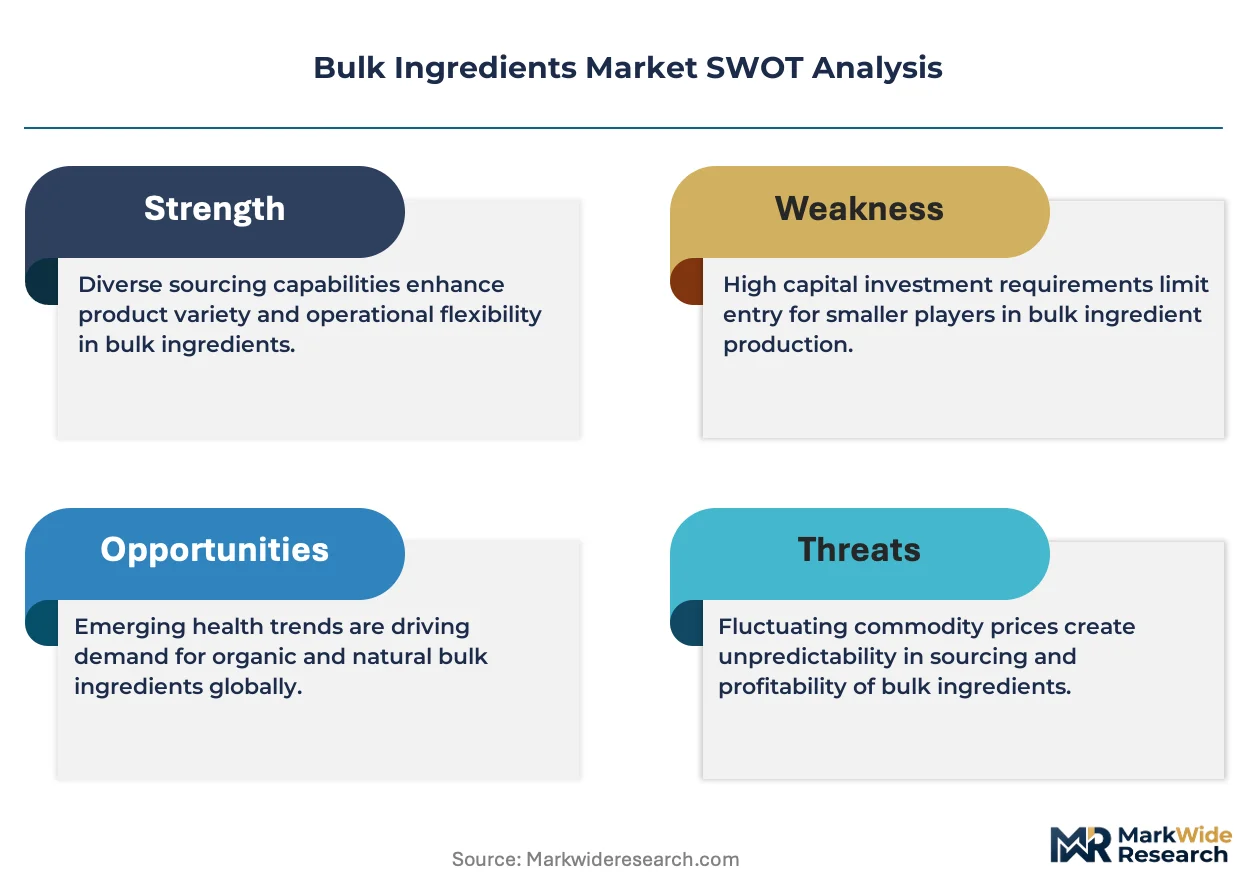
- Nutraceutical Sector Expansion:Rising consumer focus on preventative health is fueling demand for functional foods and dietary supplements, increasing the use of fortified bulk ingredients like specialty fibers and plant-based proteins.
- Clean-Label Formulation Shift:A strong consumer preference for simple, recognizable ingredients is compelling food manufacturers to reformulate products, boosting demand for non-GMO starches, natural sweeteners, and minimally processed oils.
- Food Processing Growth in China:The rapid expansion and modernization of China's food processing industry creates concentrated demand for a wide range of bulk ingredients, from foundational starches and oils to sophisticated texturants.
Market Restraints
- Commodity Price Volatility:The market is exposed to price fluctuations in agricultural raw materials like corn, wheat, and sugar cane, which directly impacts the cost structure and margin stability for producers of starches and sweeteners.
- Divergent Regulatory Standards:Navigating conflicting or overlapping requirements from bodies like the U.S. FDA and Europe's EFSA increases compliance costs, extends time-to-market, and can create significant barriers to trade for suppliers.
- Logistical Network Dependency:Heavy reliance on global shipping lanes for transport makes the supply chain vulnerable to disruptions, port congestion, and rising freight costs, impacting both landed costs and delivery times.
Strategic Opportunities
- Plant-Based Ingredient Innovation:Developing high-functionality plant-based emulsifiers and texturants from sources like pea or chickpea offers a significant opportunity to capture share from traditional animal-derived or synthetic options in bakery and dairy alternative applications.
- Emerging Market Penetration:As agencies like India's FSSAI align with global standards, opportunities are growing for suppliers to enter these large markets with certified, value-added ingredients for the expanding processed food sector.
- Specialized Nutrition Segments:Formulating ingredients for high-margin applications such as infant formula and medical foods, which require exceptional purity and traceability, provides a path away from commodity price competition.
Industry Challenges
- Multi-Regional Certification Burden:Maintaining a portfolio of certifications to meet disparate customer and regulatory demands across multiple geographies requires continuous, costly investment in quality assurance, testing, and documentation systems.
- End-to-End Supply Chain Transparency:Achieving full visibility and verifying sustainability claims across complex agricultural supply chains, which often involve thousands of small farms, presents a major operational and technological hurdle for ingredient suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Ingredients Market |
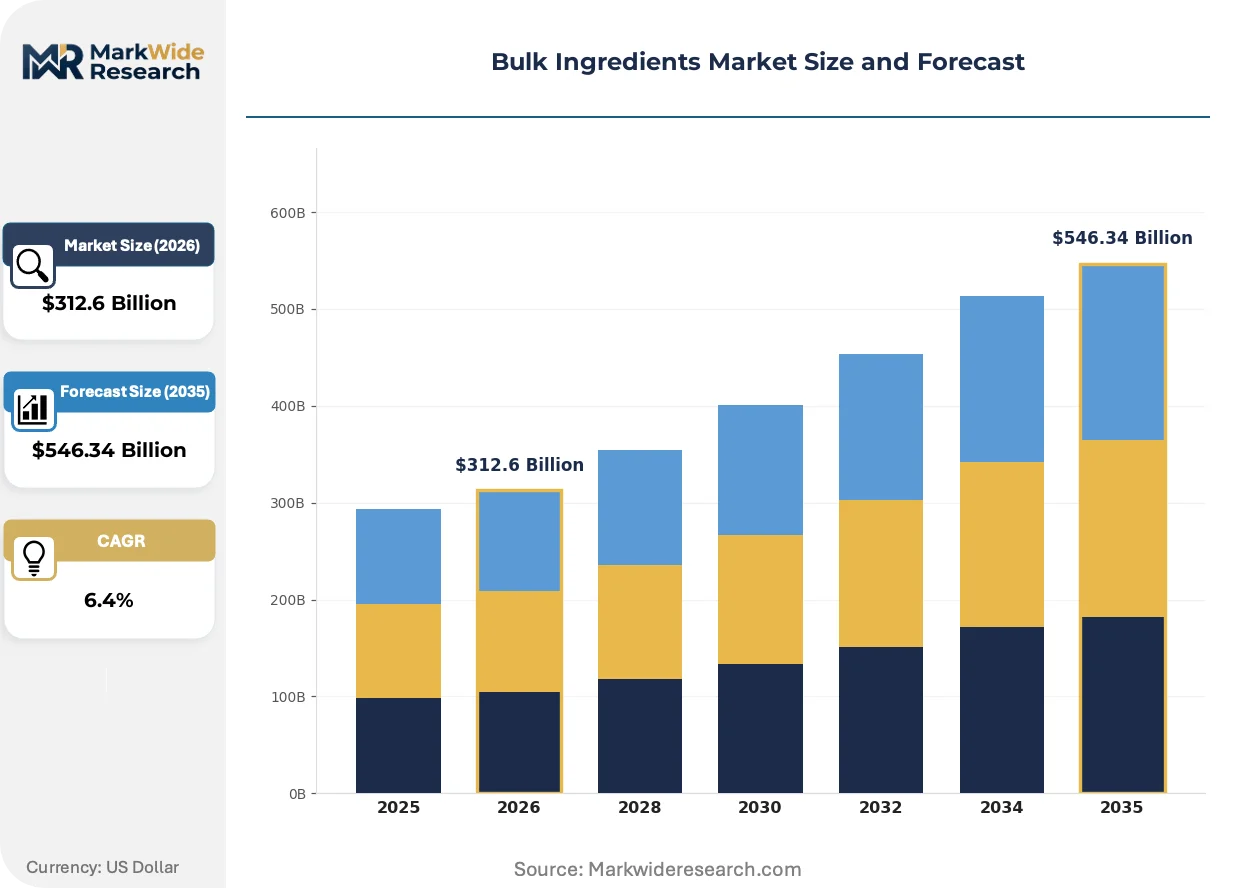
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $546.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweeteners, Stabilizers, Emulsifiers, Thickeners Application: Beverages, Dairy Products, Bakery, Confectionery End User: Food Manufacturers, Beverage Producers, Pharmaceuticals, Nutraceuticals Packaging Type: Bags, Drums, Bulk Containers, Jars |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, Bunge Limited, Ingredion Incorporated, Olam Group, Associated British Foods plc, International Flavours & Fragrances Inc., DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Ingredients Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental pivot from transactional, volume-based supply to integrated partnerships. This change is driven by technological advancements in supply chain verification and a non-negotiable consumer demand for ingredient transparency.
Digital traceability platforms built on blockchain provide an immutable record of an ingredient's journey from farm to factory. Food manufacturers in the organic and premium product spaces are adopting this technology to validate their clean-label claims. This innovation is decentralizing trust from a single supplier's guarantee to a distributed, cryptographically secured ledger accessible by stakeholders.
Europe's Food Safety Authority (EFSA) enforces a stringent pre-market approval framework for novel foods and ingredients with health claims. This regulatory process compels suppliers to conduct extensive clinical studies and compile detailed safety dossiers, elevating the barrier to entry. The functional ingredient segment is most impacted, as marketing health benefits in the EU now requires a high level of scientific evidence.
Purchasing decisions are increasingly influenced by the presence of specific certifications, such as non-GMO, organic, or Fair Trade. This trend is disrupting procurement channels that have historically prioritized cost per unit above all else, forcing suppliers to compete on verified sustainability metrics. This shift is most evident in the North American and European beverage and infant nutrition markets.
Bulk Ingredients Market Segmentation
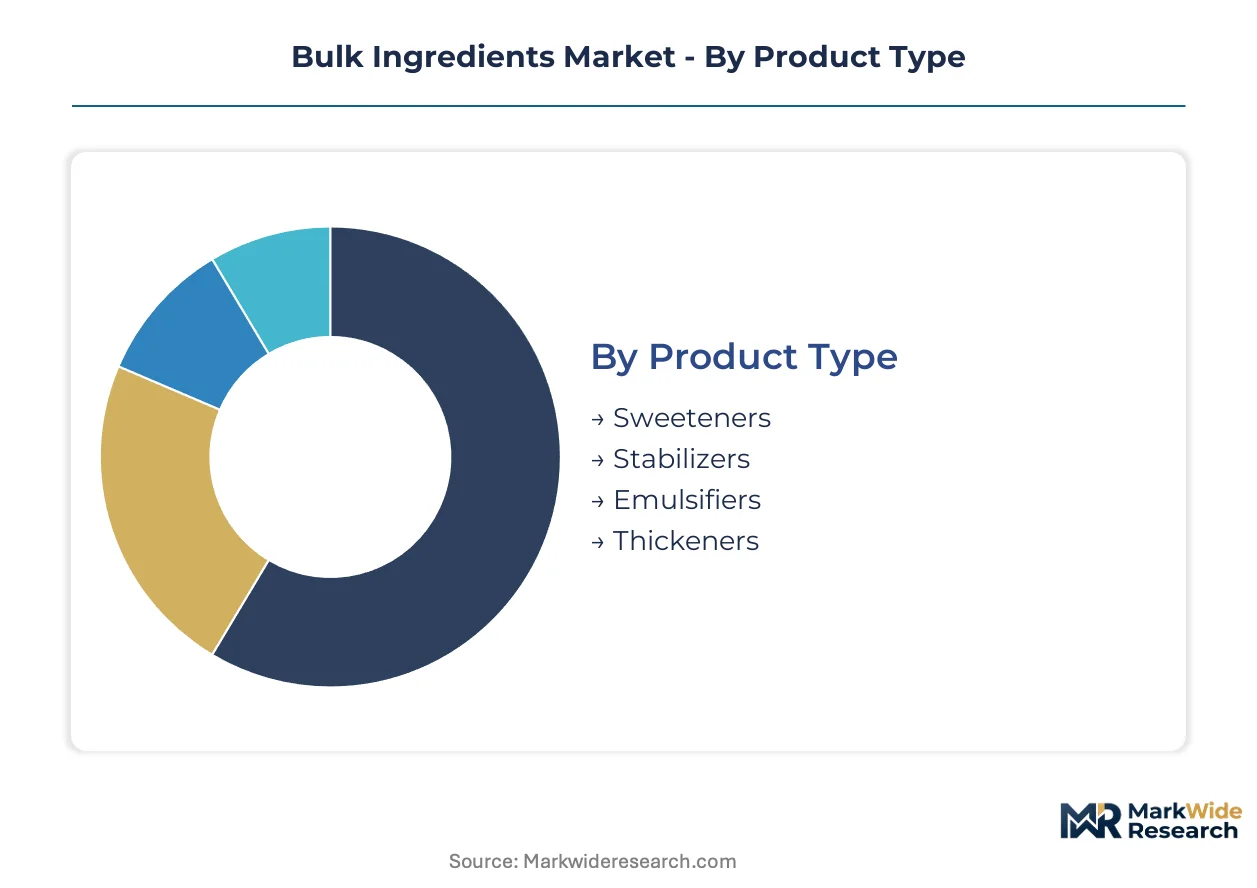
The bulk ingredients market segments across diverse product types, applications, end-users, and packaging formats. Understanding these differentiations allows suppliers to tailor offerings and navigate specific regulatory landscapes. Each segment presents unique challenges and opportunities for product development and market penetration.
Product Type:
Compliance with rigorous standards from bodies like the U.S. FDA and Europe's EFSA dictates the market entry and formulation complexity for different product types.
- Emulsifiers:These complex molecules ensure immiscible liquids blend smoothly, crucial for texture and stability in processed foods. Demand concentrates in dairy products and bakery goods, driven by the need for consistent product quality.
- Stabilizers:Hydrocolloids or proteins prevent phase separation and maintain desired viscosity in liquid and semi-solid formulations. Dairy products and sauces in European markets drive demand, requiring consistent texture over shelf life.
- Sweeteners:These ingredients provide taste and bulk, ranging from high-intensity to nutritive options. Beverages and confectionery in emerging economies utilize large volumes of these ingredients.
- Thickeners:These modify viscosity and texture, often derived from starches or gums. Processed food manufacturers in China use thickeners extensively for sauces and ready meals.
Sweeteners sit at the top of the volume ranking, with Emulsifiers climbing the fastest.
Application:
The specific requirements of different application sectors shape ingredient functionality and procurement patterns.
- Beverages:This sector requires ingredients for sweetness, mouthfeel, and stability, often with a strong emphasis on natural and reduced-sugar solutions. Demand in North America focuses on natural sweeteners and clean-label texturants for functional drinks.
- Dairy Products:This segment needs emulsifiers, stabilizers, and texturants to achieve desired consistency, shelf life, and mouthfeel in items like yogurts and cheese. European dairy producers seek high-performance stabilizers for plant-based milk alternatives.
- Bakery:This segment utilizes ingredients for structure, moisture retention, and leavening. Manufacturers in India integrate bulk starches and flours into bread and biscuit production.
- Confectionery:This sector depends on sweeteners, gelling agents, and colorants for texture and appeal. Asian markets drive demand for specific hydrocolloids in gummy and jelly production.
Each application category presents unique formulation challenges, driving specialized ingredient development across the market.
End User:
Different end-user industries exhibit varying margin profiles, influencing their willingness to invest in premium or specialized bulk ingredients.
- Pharmaceuticals:This sector demands excipients and active pharmaceutical ingredients (APIs) with exceptionally high purity, strict regulatory compliance, and consistent batch-to-batch quality. European pharmaceutical companies require cGMP-certified ingredients for drug formulation.
- Nutraceuticals:This segment utilizes functional ingredients like plant-based proteins, fibers, and vitamins for health-promoting foods and supplements. North American consumers drive demand for certified organic and non-GMO ingredients in dietary supplements.
- Food Manufacturers:This represents the largest volume segment, consuming foundational ingredients like starches, oils, and sugars. China's food processing industry drives substantial demand for basic bulk commodities.
- Beverage Producers:This segment requires ingredients for taste, texture, and preservation in soft drinks, juices, and alcoholic beverages. Brazilian beverage companies source large quantities of sweeteners and acidulants.
The nutraceutical segment, with its focus on health benefits, is pushing innovation in specialized bulk ingredient development.
Packaging Type:
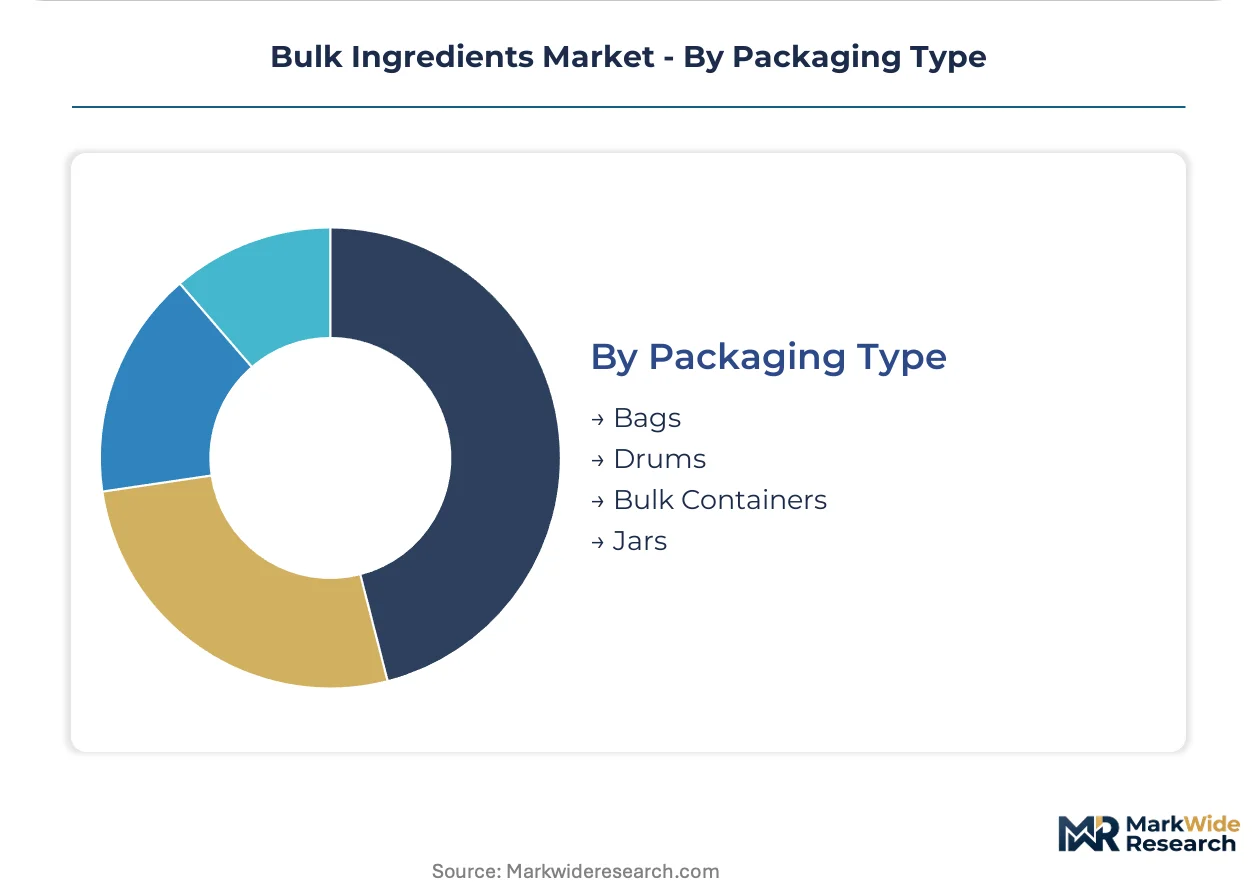
The scale of procurement and logistical infrastructure often dictates the preferred packaging type for bulk ingredient deliveries.
- Bulk Containers:These (e.g., IBCs, tankers, railcars) facilitate the most cost-effective transport of large volumes of liquid or granular ingredients. Large-scale food manufacturers in the United States prefer bulk containers for high-volume oils and sweeteners.
- Drums:These (e.g., 200-liter barrels) provide secure storage and transport for liquid, paste, or solid ingredients, offering protection against contamination and spillage. European chemical and food processors utilize drums for specialty oils and liquid additives.
- Bags:These (e.g., 25kg sacks, FIBCs) are widely used for dry, powdered, or granular ingredients, offering flexibility for various batch sizes. Asian bakeries commonly receive flour and sugar in large bags.
- Jars:These are typically used for smaller quantities of specialized or high-value ingredients, ensuring product integrity and ease of handling. Pharmaceutical companies in Japan package sensitive excipients in jars.
Efficiency gains in logistics are driving a shift towards larger packaging formats for commodity bulk ingredients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global bulk ingredients market experiences production shifts as suppliers seek optimal regulatory environments, balancing stringent compliance costs with market access. This dynamic influences investment decisions and supply chain configurations. Companies often weigh multi-regional certification burdens against specialized market focus.
China
China's food processing industry creates concentrated demand for a wide range of bulk ingredients, from foundational starches to sophisticated texturants. Compliance with China's NMPA regulations and GB standards is essential for market entry and product acceptance. The Yangtze River Delta region, with its extensive food manufacturing hubs, drives substantial procurement volumes.
United States
United States demand for bulk ingredients stems from large-scale food manufacturers and a robust nutraceutical sector. U.S. FDA regulations impose stringent standards on ingredient purity, labeling, and allergen declarations. The Midwest region, a hub for corn and soy processing, is a key source for high-volume starches and sweeteners.
Germany
Germany's bulk ingredient consumption is driven by its advanced dairy and bakery sectors, alongside a growing demand for plant-based alternatives. Europe's EFSA enforces rigorous pre-market approval for novel foods and health claims, impacting ingredient innovation. Industrial clusters in Bavaria and North Rhine-Westphalia consistently seek high-performance stabilizers.
India
India's rapidly expanding processed food sector generates significant demand for bulk starches, flours, and value-added ingredients. India's FSSAI is actively harmonizing local food safety rules with global standards, influencing market access. Manufacturing centers in Maharashtra and Gujarat integrate bulk ingredients into diverse food applications, including bakery and confectionery.
Brazil
Brazil's beverage industry requires substantial volumes of sweeteners and acidulants for soft drinks and juices. ANVISA, Brazil's health surveillance agency, regulates food additives and ingredients, dictating compliance for market entry. The São Paulo region, a major agricultural processing hub, supports local and international beverage companies with foundational commodities.
Bulk Ingredients Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the bulk ingredients market, reflecting varied customer needs. The market exhibits a tiered structure, with large, diversified agricultural processors at one end and niche ingredient innovators at the other. Strategic archetypes include commodity suppliers focused on scale and value-added ingredient providers emphasizing functionality. Dominant competitive moves involve both strategic partnerships for supply chain resilience and capacity expansion to meet regional demand.
Diversified agricultural processors like Cargill, Incorporated and Archer Daniels Midland Company exemplify the large-scale commodity supply archetype, leveraging extensive global logistics networks to serve foundational ingredient needs. Tate & Lyle PLC, conversely, represents a specialized ingredient provider, focusing on value-added sweeteners and texturants for specific applications. These companies occupy distinct positions, from broad-spectrum sourcing and processing to targeted functional ingredient development, influencing pricing and availability. Their market presence anchors various segments, ensuring consistent supply for diverse end-user industries globally.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Bunge Limited |
| Ingredion Incorporated |
| Olam Group |
| Associated British Foods plc |
| International Flavours & Fragrances Inc. |
| DSM |
| Others |
Cost & Logistics Intelligence
Family-owned agricultural processors often prioritize long-term relationships, influencing stable contract pricing for bulk ingredients. This ownership structure underpins consistent supply to major food manufacturers.
Pricing Analysis
Capacity additions in China are reshaping price floors for foundational bulk ingredients like starches and thickeners. The dominant pricing model combines commodity spot rates with long-term contract-based offtake agreements. Price differentiation stems from certification levels, such as non-GMO or organic, and geographic delivery costs. Pricing softness reflects agricultural commodity price volatility, impacting producer margins; food manufacturers are highly price-sensitive for high-volume items, while pharmaceutical companies prioritize purity and consistency.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks optimize last-mile delivery for bulk ingredients. Geographic supply concentrates in China, the United States, and Brazil for foundational starches, sweeteners, and oils. The market relies on agricultural raw materials like corn, wheat, and sugarcane. Commodity price volatility presents a significant structural risk, impacting cost stability, with distribution primarily through specialized ingredient distributors and direct sales to large-scale food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bulk ingredients market functions as a stable compounder, driven by the continuous expansion of the global processed food industry. Consumer demand for convenience foods ensures consistent underlying volume growth.
For Market Incumbents: Deploy digital traceability platforms to verify ingredient origin and sustainability metrics. This differentiates offerings against commodity pricing pressure and addresses consumer demand for transparency. Invest in multi-regional certification capabilities to mitigate divergent regulatory standards and maintain market access. Expand capacity in high-growth economies like China to secure long-term supply contracts.
For New Entrants and Emerging Players: Capture share in the specialized nutrition segments, particularly infant formula and medical foods, which demand exceptional purity. Target the dairy alternative applications with innovative plant-based emulsifiers and texturants. The nutraceutical sector in North America represents a penetrable segment due to high consumer demand for certified organic ingredients. A go-to-market angle emphasizes superior functionality and verifiable sustainability certifications.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized commodity ingredient processors facing margin pressure from larger players. The long-term viability of the bulk ingredients market remains strong over a 5-10 year window, driven by population growth and expanding food consumption. Acquisition targets should be specialized ingredient providers with strong intellectual property in plant-based alternatives or clean-label solutions. Watch for increasing M&A activity within the nutraceutical and functional food ingredient space as an inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Meets concentrated demand from China's rapidly expanding food processing industry. |
| Digital Traceability Platform Adoption | Verifies ingredient origin and sustainability claims for transparency-focused food manufacturers. |
| Plant-Based Ingredient R&D | Captures share in dairy alternative and bakery applications from traditional options. |
| Multi-Regional Certification Investment | Ensures market access and regulatory compliance with U.S. FDA and EFSA standards. |
| Strategic Partnerships for Logistics | Mitigates supply chain vulnerabilities and rising freight costs for global distribution. |
Research Approach
Direct dialogue with procurement leads, R&D directors, and supply chain managers provided primary insights into the bulk ingredients market. This was combined with secondary validation from regulatory body publications like the U.S. FDA and EFSA, industry association reports, and trade data. The analysis integrated bottom-up market sizing with top-down validation through extensive triangulation.
Volume and value projections were developed using a robust analytical framework across the analysis window. The model segmented dimensions by product type, application, end-user, and packaging format, alongside regional consumption patterns. Compound annual growth rates were derived from historical trends and projected demand drivers. Key inputs included population growth rates and per capita food consumption metrics.
Underlying measurement precision varies by segment; foundational ingredients like starches carry tighter precision than specialized emulsifiers. Forecasts reflect assumptions regarding regulatory stability and consumer trends. Geopolitical events or unforeseen agricultural supply shocks could revise these projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Lithium Nitrate Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
Global Isobutanol Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
Europe Barium Carbonate Market
Bulk Chemicals
Acetate Salt Market
Bulk Chemicals
Global Phosphoric Acid Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Middle East Ammonia Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Barium Chloride Market
Bulk Chemicals
Lactic Acid Market
Bulk Chemicals
India Iodine Market
Bulk Chemicals
Sulfamic Acid Market