
 India Fintech Market | 2026-2036
India Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
India Fintech Market Outlook
Buyer concentration among India's small and medium enterprises is shifting from cash-based transactions toward integrated digital payment ecosystems. PhonePe leverages its UPI-first architecture to anchor merchant acquisition in semi-urban markets. Razorpay competes through specialized lending and payroll solutions tailored to emerging business formats. Paytm sustains its position via diversified financial services spanning payments, wealth management, and insurance distribution.
India fintech encompasses technology-enabled financial service delivery through software platforms, mobile applications, and API infrastructure that processes transactions, manages investments, and extends credit without traditional branch networks. Payment processing dominates transaction volumes while lending solutions capture expanding margin pools from underserved credit segments. Artificial Intelligence segments within the technology dimension are maturing fastest as fraud detection and personalized underwriting models deploy at scale across BFSI and E-Commerce verticals.
RBI's regulatory sandbox, SEBI's investment platform guidelines, and the PLI scheme for IT hardware collectively shape product standards and market access thresholds for fintech operators in India. These frameworks mandate data localization, KYC interoperability, and capital adequacy buffers that filter market participants by compliance capability. Stakeholders must monitor evolving central bank digital currency integration timelines and account aggregator framework expansion to anticipate infrastructure-dependent revenue model shifts.
Market Dynamics
India's fintech sector is undergoing a structural transformation driven by RBI's account aggregator framework, which is forcing incumbents to rebuild data architecture around consent-based financial information sharing rather than proprietary silos.
Growth Catalysts
- UPI Infrastructure Expansion:NPCI's real-time payment rails now process merchant settlements below 50 basis points, pulling micro-enterprises in tier-3 cities into formal digital commerce networks.
- Data Localization Mandates:RBI's storage requirements for payment data are compelling foreign cloud providers to establish India-specific infrastructure, creating captive supply of compliant hosting capacity.
- Embedded Finance Proliferation:E-commerce platforms and logistics aggregators are white-labeling lending and insurance products, extending credit access to previously unscored borrower segments.
Market Restraints
- Capital Adequacy Burden:RBI's non-bank lending license requirements demand minimum net owned funds of 200 million rupees, filtering out sub-scale fintech operators from credit markets.
- Cloud Concentration Risk:Over 70% of fintech data infrastructure relies on three hyperscale providers with Mumbai-Availability-Zone dependencies, creating single-point-of-failure exposure during monsoon flooding.
- Feature Phone Limitation:USSD-based transaction interfaces cap monthly volumes at 5,000 rupees per user, excluding rural populations without smartphones from full-service digital banking.
Strategic Opportunities
- Account Aggregator Convergence:Consent-based data sharing between banks, insurers, and wealth managers is enabling cash-flow-based underwriting models for gig economy workers in Bengaluru and Hyderabad.
- CBDC Pilot Expansion:RBI's digital rupee wholesale trials are creating infrastructure for programmable payments in supply chain finance, with programmable escrow applications emerging in commodity trading.
- Telugu-Kannada Language Interfaces:Voice-first UPI applications in regional languages are capturing merchant adoption in Vijayawada, Visakhapatnam, and Mysuru where English literacy barriers persist.
Industry Challenges
- API Talent Scarcity:Fintech product teams in Mumbai and Pune face 40% vacancy rates for engineers with Bharat BillPay and NACH integration experience, delaying platform launches.
- Multi-Regulator Compliance:Operators spanning payments, lending, and wealth management must simultaneously satisfy RBI, SEBI, and IRDAI reporting standards with incompatible data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Fintech Market |
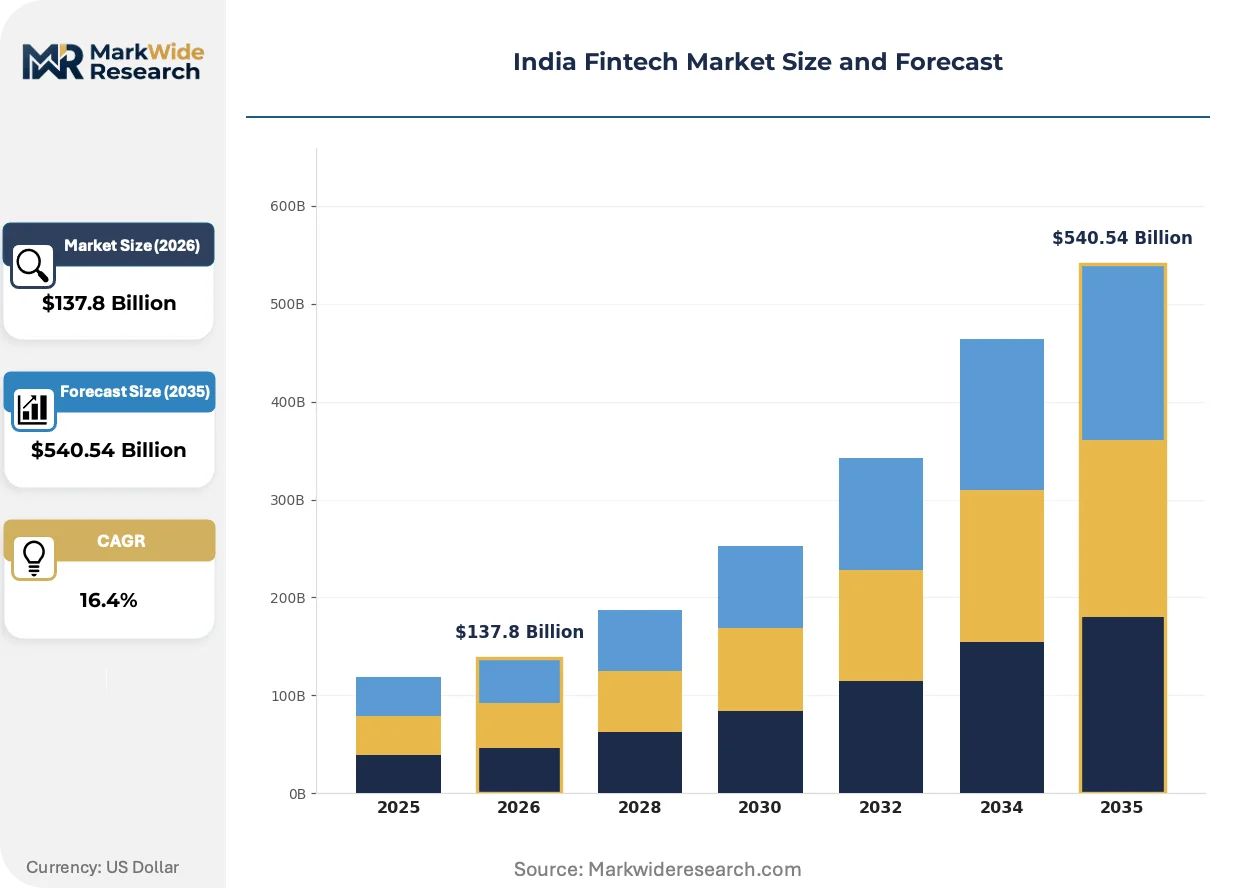
| Market Size in 2026 | $137.8 Billion |
| Market Size in 2035 | $540.54 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Investment Management, Lending Solutions, Insurance Tech Customer Type: Retail Consumers, SMEs, Corporates, Government Entities Technology: Blockchain, Artificial Intelligence, Cloud Computing, Big Data Industry Vertical: BFSI, E-Commerce, Hospitality, Education |
| Companies Covered | BharatPe, PayPal, Paytm, Cashfree Payments, Yubi, PhonePe, Stripe, Jupiter, Razorpay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Fintech Market Strategic Shifts
Three forces are restructuring competitive advantage in India fintech: AI-native fraud detection, consent-based data architectures, and voice-first interfaces for non-English speaking merchant bases.
Machine learning models trained on UPI transaction patterns are electrifying real-time risk scoring capabilities. Payment processors deploy these systems to approve merchant settlements within 30 seconds rather than T+1 cycles. This compression is eliminating working capital gaps for kirana stores in Indore and Coimbatore that previously relied on informal moneylenders.
RBI's account aggregator framework mandates consent-based financial data sharing across banking, insurance, and securities verticals. The regulation compels fintech operators to rebuild customer onboarding flows around explicit permission architectures rather than screen-scraping. Lending platforms in Hyderabad and Chennai are responding by embedding consent capture into vernacular voice interfaces.
Merchant acquisition is rotating from app-based onboarding toward assisted voice-UPI enrollment. Field agents in tier-2 Maharashtra and Gujarat markets now complete KYC through biometric-Aadhaar linkage with verbal confirmation rather than smartphone form-filling. This channel shift is capturing micro-merchant segments previously excluded by digital literacy barriers.
India Fintech Market Segmentation
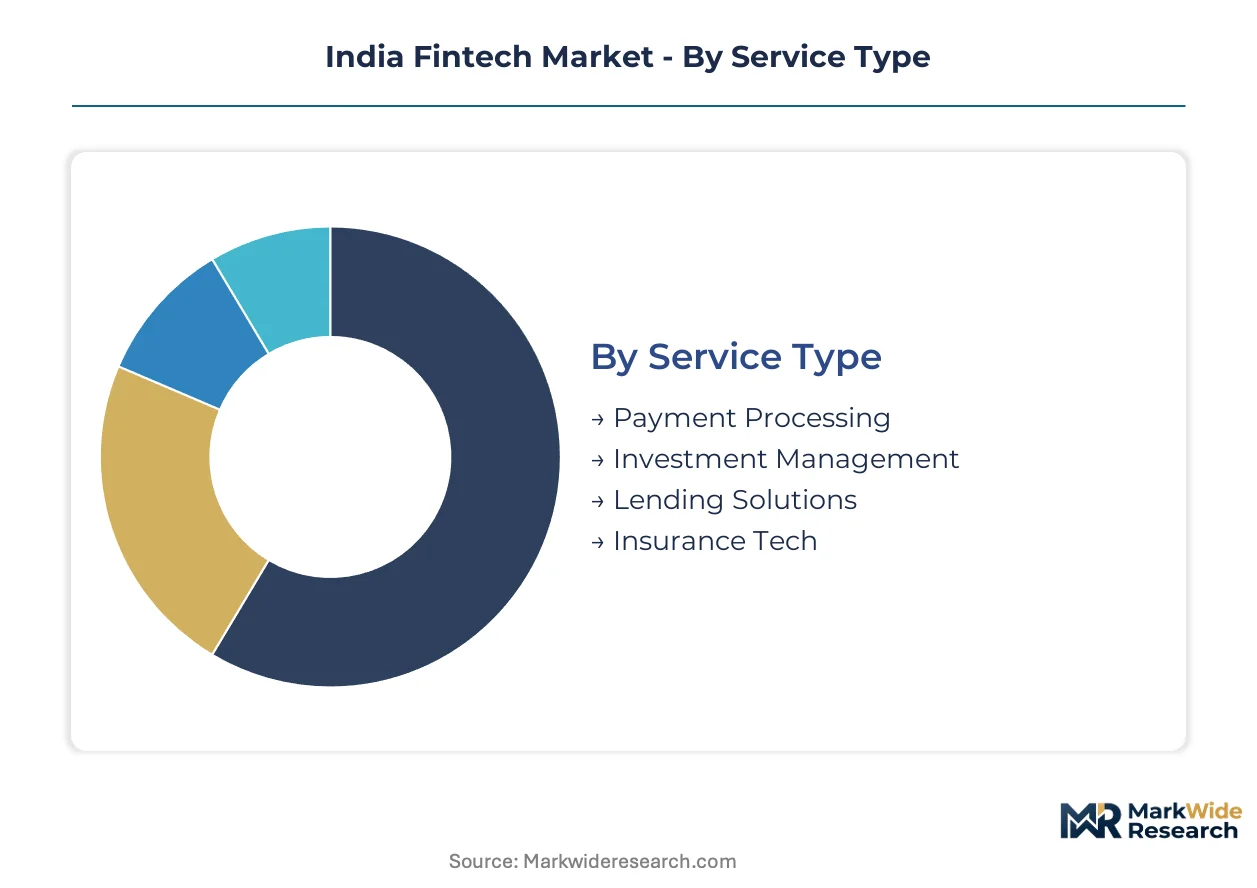
India fintech operators compete across distinct service architectures and customer interfaces, with integration depth determining whether solutions function as standalone platforms or embed within broader ecosystems. The following segmentation maps how technology choices, customer relationships, and vertical applications structure competitive positioning across Maharashtra, Karnataka, and Telangana.
Service Type:
Payment Processing operates as the most embedded layer, with UPI rails and merchant settlement APIs weaving into e-commerce checkouts and logistics platforms. Investment Management and Insurance Tech function more often as standalone applications requiring dedicated customer acquisition.
- Payment Processing:Real-time settlement infrastructure built on NPCI's UPI protocol processes transactions below 50 basis points for merchants. Demand concentrates in tier-2 and tier-3 cities across Gujarat and Rajasthan where kirana stores transition from cash to QR-code acceptance.
- Lending Solutions:Cash-flow-based underwriting models leverage account aggregator data to score gig economy workers and micro-enterprises previously excluded from formal credit. Telangana and Karnataka fintech clusters lead deployment of consent-driven credit decisioning engines.
- Investment Management:Direct mutual fund and equity platforms target salaried professionals in Bengaluru and Mumbai with zero-commission distribution models.
- Insurance Tech:Embedded distribution through travel, e-commerce, and ride-hailing apps dominates premium collection for bite-sized policies.
Payment Processing leads volumes today; Lending Solutions is gaining share fastest.
Customer Type:
Revenue concentration and margin structure diverge sharply across customer tiers, with SMEs delivering the steepest expansion trajectory as digital penetration deepens beyond metro boundaries.
- SMEs:Small and medium enterprises in tier-2 and tier-3 cities drive merchant acquisition costs downward through assisted onboarding models. Maharashtra and Gujarat field agents complete biometric-Aadhaar KYC with voice-verified confirmation, bypassing smartphone dependency.
- Retail Consumers:Individual users access payments, credit, and wealth products through super-app interfaces consolidating multiple financial services. UPI transaction volumes from retail users in Karnataka and Telangana exceed other states due to startup density and banking partnerships.
- Corporates:Treasury management, payroll automation, and vendor payment solutions target mid-market enterprises with API-first integration requirements.
- Government Entities:Public distribution system integration and subsidy disbursement platforms operate through specialized procurement channels with extended implementation cycles.
SMEs anchor revenue growth momentum; Retail Consumers sustain the largest transaction volume base.
Technology:
Deployment maturity varies across technology layers, with Artificial Intelligence and Cloud Computing already at production scale while Blockchain applications remain largely experimental.
- Artificial Intelligence:Machine learning models trained on UPI transaction patterns enable real-time fraud detection and personalized underwriting. Fintech operators in Hyderabad and Pune deploy these systems to compress merchant settlement from T+1 cycles to under 30 seconds.
- Cloud Computing:RBI's data localization mandates compel foreign hyperscale providers to establish India-specific infrastructure, creating compliant hosting capacity captive to domestic fintech demand.
- Big Data:Consent-based financial information aggregation powers cash-flow analysis for alternative credit scoring beyond traditional bureau reports.
- Blockchain:Programmable payment pilots and supply chain finance applications remain confined to RBI's central bank digital currency wholesale trials.
Cloud Computing underpins current infrastructure scale; Artificial Intelligence is expanding most quickly across fraud and underwriting use cases.
Industry Vertical:
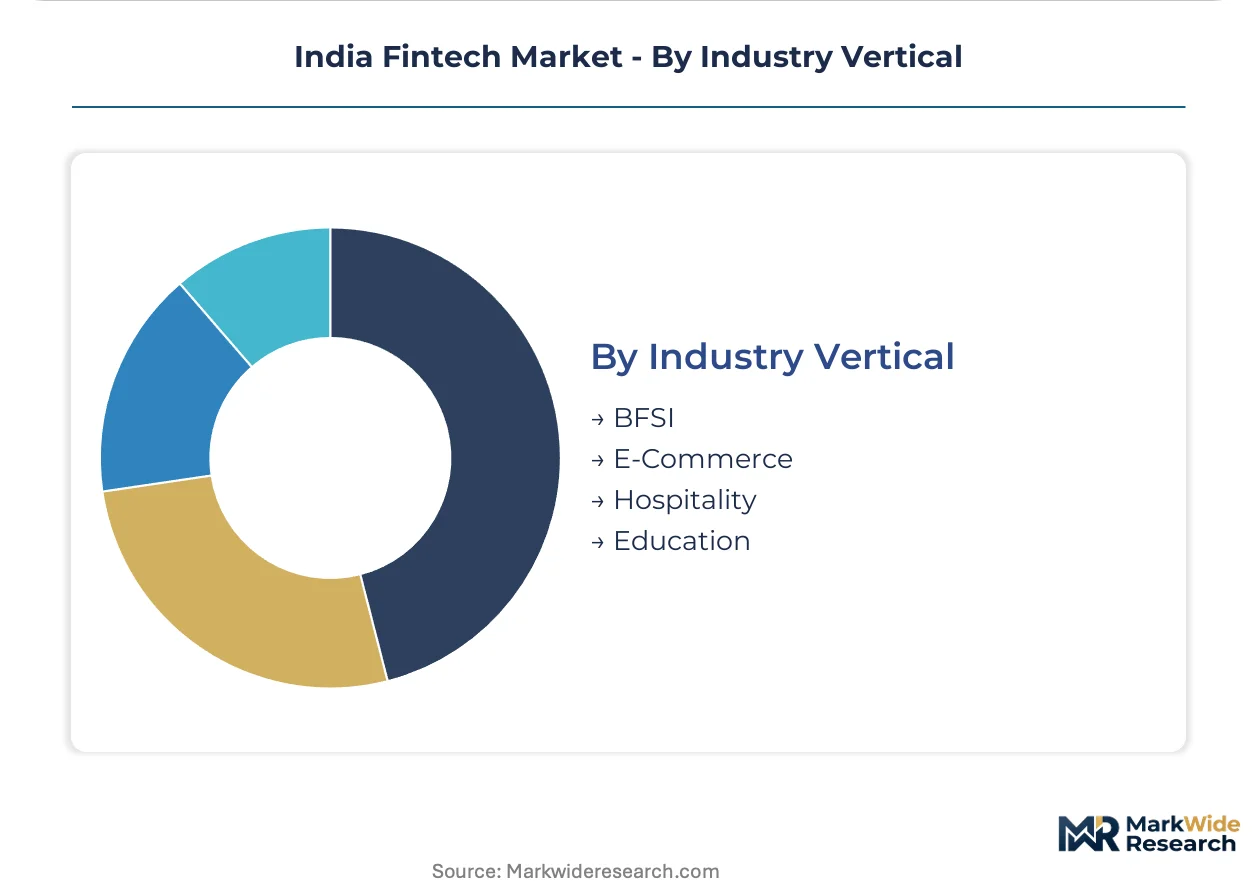
Vertical integration depth determines whether fintech solutions operate as horizontal platforms or sector-specialized offerings with customized compliance and workflow features.
- BFSI:Banks, insurers, and asset managers consume fintech infrastructure for core modernization, with account aggregator integration forcing data architecture rebuilds around consent-based sharing rather than proprietary silos.
- E-Commerce:Marketplaces and direct-to-consumer brands embed lending, insurance, and payment products at checkout, extending credit access to previously unscored borrower segments in tier-2 cities.
- Hospitality:Hotels and restaurants adopt contactless payment terminals and working capital loans tied to seasonal cash flow patterns.
- Education:Fee financing and insurance products target private institutions and test-prep chains with customized collection schedules.
BFSI commands the deepest integration partnerships; E-Commerce is climbing the fastest as embedded finance proliferates across checkout flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Bengaluru, Hyderabad, and Mumbai anchor India's fintech development clusters, with these metros housing the majority of technical workforce specializing in UPI infrastructure, AI underwriting models, and API architecture.
Maharashtra
SME merchant acquisition and banking partnership density drive demand in Mumbai and Pune. RBI's regulatory sandbox framework enables live testing of payment innovations in controlled environments. The Mumbai-Pune corridor concentrates fintech headquarters and venture capital flows, with field agents completing biometric-Aadhaar KYC for tier-2 merchant onboarding.
Karnataka
Startup density and UPI transaction volumes exceed national averages in Bengaluru and Mysuru. SEBI's investment platform guidelines shape wealthtech product standards for direct mutual fund distribution. The Bengaluru cluster leads deployment of AI-native fraud detection systems compressing merchant settlement cycles to under 30 seconds.
Telangana
Consent-based credit underwriting and account aggregator integration accelerate in Hyderabad and Warangal. The PLI scheme for IT hardware creates captive server manufacturing capacity supporting data localization compliance. Hyderabad's fintech operators deploy cash-flow-based scoring models for gig economy workers using aggregated financial data.
Gujarat
QR-code adoption among kirana stores and micro-enterprises expands in Ahmedabad and Surat. RBI's data storage requirements compel cloud infrastructure investment in India-specific hosting zones. Field networks in Surat and Vadodara complete voice-verified merchant enrollment bypassing smartphone dependency barriers.
Delhi-NCR
Corporate treasury solutions and government payment integration concentrate in New Delhi and Gurugram. The account aggregator framework mandates from RBI force enterprise data architecture rebuilds around consent-based sharing. Gurugram hosts embedded finance deployments linking lending products to logistics and e-commerce platforms.
India Fintech Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across India's fintech sector. Market structure tilts toward consolidation at the payments layer while lending and wealth management segments retain fragmentation. Three archetypes dominate: UPI-first payment platforms with merchant network effects, embedded finance providers white-labeling credit and insurance products, and vertical specialists targeting SME payroll and treasury automation. Competitive moves center on strategic partnerships with banking networks and portfolio diversification into adjacent financial services.
Among domestic payment platforms, PhonePe, Razorpay, and Paytm occupy distinct positioning within the competitive architecture. PhonePe exemplifies the UPI-native archetype with deep merchant penetration in semi-urban markets. Razorpay represents embedded finance specialists extending lending and payroll solutions to emerging business formats. Paytm anchors the diversified super-app model spanning payments, wealth management, and insurance distribution through consolidated customer interfaces.
| Leading Market Players |
|---|
| BharatPe |
| PayPal |
| Paytm |
| Cashfree Payments |
| Yubi |
| PhonePe |
| Stripe |
| Jupiter |
| Razorpay |
| Others |
Value Chain & Pricing Dynamics
UPI infrastructure commoditization is compressing transaction economics while concentrating merchant acquisition power among platform operators with captive settlement networks. This dual pressure reshapes how fintech providers structure service bundles and source compliant technology infrastructure.
Pricing Analysis
The bundled-versus-unbundled service split defines competitive pricing architecture across India's fintech sector. Payment processing operates on per-transaction models below 50 basis points for UPI settlements, while lending and wealth management command subscription or revenue-share structures. Price differentiation rests on data integration depth and regulatory compliance certification rather than feature count alone. Pricing pressure stems from NPCI's merchant discount rate caps, which squeeze margin pools for standalone payment processors. SME merchants in tier-2 cities exhibit highest price sensitivity, driving field-assisted onboarding at zero upfront cost; enterprise treasury clients accept premium pricing for API reliability and dedicated support.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure concentrated in Mumbai-Availability-Zone deployments. Technology sourcing draws from domestic data centers in Maharashtra, Karnataka, and Telangana, plus captive server manufacturing under PLI scheme incentives. Raw material dependencies include semiconductor components for POS terminals, biometric sensors for Aadhaar-enabled KYC, and specialized chips for encryption modules. Supply chain risk centers on monsoon-related connectivity disruptions to Mumbai hosting clusters. Distribution runs through API-first integration with banking networks, direct sales to enterprise clients, and assisted field networks for micro-merchant acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's fintech market functions as a regulatory compounder, where RBI's account aggregator framework and CBDC pilot programs continuously expand addressable data infrastructure demand.
For Market Incumbents: Anchor defensible positioning through backward integration into consent-based data architecture and captive cloud capacity in RBI-mandated India zones. Incumbents must consolidate merchant network effects against embedded finance entrants from e-commerce platforms by deepening banking partnership exclusivity. Threat vectors include cash-flow-based underwriting specialists in Hyderabad and voice-first interface providers capturing non-English merchant segments. For New Entrants and Emerging Players: Enter via white-label infrastructure plays targeting tier-3 city cooperative banks lacking in-house technology development. The most penetrable segment sits with regional language voice-UPI applications for Gujarati and Kannada-speaking merchant bases in Surat and Mysuru. Go-to-market execution demands field agent networks completing biometric-Aadhaar KYC without smartphone dependency. For Investors and Strategic Acquirers: Roll-up economics work for vertical specialists with consent-engine technology because account aggregator mandates force incumbent rebuilds around permission-based data sharing. Long-term viability favors platforms with demonstrated compliance across RBI, SEBI, and IRDAI frameworks. The signal to watch is central bank digital currency wholesale trial expansion, which will restructure settlement infrastructure economics.| Strategic Initiative | Industry Significance |
|---|---|
| Account Aggregator Integration | Consent-based data sharing architectures unlock cash-flow underwriting for gig economy workers in Bengaluru and Hyderabad. |
| Regional Language Voice Interface Deployment | Telugu and Kannada UPI applications capture merchant adoption in Vijayawada and Mysuru where English literacy barriers persist. |
| Data Localization Infrastructure Buildout | RBI-mandated storage requirements create captive hosting demand served by India-specific cloud zones in Mumbai and Chennai. |
| Embedded Finance Partnership Expansion | White-label lending and insurance distribution through e-commerce checkouts extends credit access to previously unscored borrower segments. |
| CBDC Infrastructure Preparation | Programmable payment pilot participation positions operators for RBI digital rupee wholesale settlement in supply chain finance. |
Study Parameters
Bottom-up merchant and enterprise modeling reconciled against top-down infrastructure deployment tracking forms the analytical core of this study. Primary interviews with fintech product executives, regulatory compliance officers at non-bank lenders, API integration specialists, and merchant acquisition field managers combined with secondary validation. Secondary sources include RBI circulars and sandbox disclosures, SEBI investment platform guidelines, NPCI transaction volume reports, and PLI scheme beneficiary announcements. Triangulation between demand-side adoption patterns and supply-side capacity buildouts ensures cross-verified estimates.
Historical trendline analysis of UPI transaction growth, merchant acquisition cost trajectories, and regulatory milestone impacts established baseline momentum indicators. Segmentation modeling spans service type, customer tier, technology deployment, and state-level regulatory adoption patterns across the projection horizon. CAGRs derive from fitted growth curves adjusted for infrastructure penetration ceilings and competitive density saturation points. Forecast inputs include account aggregator framework expansion timelines and CBDC pilot scaling assumptions.
Inputs from NPCI, RBI regulatory sandbox disclosures, and state-level startup registry data were available through the study window; gaps in real-time merchant churn rates and precise cloud infrastructure utilization introduce uncertainty bands. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology adoption S-curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Information and Communication Technology
Global Cognitive Automation Market
Information and Communication Technology
Top Robotics Market
Information and Communication Technology
Service Provider Network Infrastructure Market
Information and Communication Technology
Workflow Management Software (WMS) Market
Information and Communication Technology
Global Third-Party Logistics Software Market
Information and Communication Technology
Robotics Technology Market
Information and Communication Technology
Global Blockchain Market
Information and Communication Technology
Body Area Network Market
Information and Communication Technology
IoT Smart Gas Meter Market
Information and Communication Technology
Europe Smart Doorbell Market
Information and Communication Technology
Smart Process Application (SPA) Market
Information and Communication Technology
5G Mmwave Technology Market
Information and Communication Technology
Wireless Smart Home Market
Information and Communication Technology
P2P Rental Apps Market
Information and Communication Technology
Account-Based Advertising Software Market
Information and Communication Technology
Customer Journey Analytics Market