
 Global Virtual Reality in Therapy Market | 2026-2036
Global Virtual Reality in Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Reality in Therapy Market Foresight
Market Context
The divergence between premium and commodity tiers is hardening as clinical-grade immersive systems separate from consumer VR hardware repurposed for therapy. AppliedVR leverages FDA breakthrough device pathways to anchor its position in prescription digital therapeutics for chronic pain. XRHealth sustains geographic dominance through telehealth-integrated platforms deployed across rehabilitation facilities in North America and Europe. MindMaze differentiates via neurorehabilitation specialization combining motion capture with adaptive algorithms for stroke recovery.
Technical Definition and Segments
Virtual reality in therapy encompasses immersive head-mounted displays, spatial audio, and haptic feedback systems engineered to deliver controlled sensory environments for psychological and neurological intervention, operating through real-time biometric adaptation to patient responses. Gesture recognition and eye tracking technologies are concentrating investment as precision metrics for therapeutic efficacy validation. Pain management applications occupy mature margin pools while cognitive rehabilitation segments attract fastest-growing clinical trial activity. Deployment type dynamics favor cloud-based VR architectures enabling remote therapist oversight and session analytics across home care providers and specialized clinics.
Regulatory Frame and Outlook
FDA, EMA, and Japan's PMDA are tightening software-as-medical-device classifications requiring clinical evidence packages for VR therapeutic platforms seeking reimbursement eligibility. ISO 13485 quality management and IEC 62304 software lifecycle standards are becoming baseline requirements for market access across major jurisdictions. Stakeholders must monitor evolving digital therapeutics reimbursement codes as gatekeepers for scalable commercial deployment.
Market Dynamics
Clinical validation requirements under FDA breakthrough device pathways and EU MDR are compressing commercialization timelines while elevating capital barriers for immersive therapeutic platforms seeking reimbursement eligibility.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for VR-based chronic pain and PTSD interventions are reducing time-to-market for prescription digital therapeutics in the United States.
- Telehealth Infrastructure Maturation:Remote therapist oversight capabilities embedded in cloud-based VR architectures are expanding addressable patient populations beyond traditional clinic boundaries.
- Biometric Sensor Convergence:Real-time eye tracking and galvanic skin response integration is enabling adaptive exposure protocols that personalize anxiety treatment intensity dynamically.
Market Restraints
- Clinical Trial Cost Structure:Large-scale randomized controlled studies required for FDA software-as-medical-device classification impose capital demands exceeding typical digital health venture thresholds.
- Hardware Supply Concentration:Dependence on concentrated Asian manufacturing clusters for high-resolution OLED microdisplays creates vulnerability in clinical-grade head-mounted display availability.
- Reimbursement Code Gaps:Absence of dedicated CPT codes for immersive therapeutic sessions in major private payer networks limits provider willingness to adopt VR protocols.
Strategic Opportunities
- German Statutory Health Insurance Integration:Formalized digital health application assessment pathways under BfArM create precedent for VR therapy reimbursement expansion across European social insurance systems.
- Home-Based Cognitive Rehabilitation:Stroke recovery protocols combining motion capture with adaptive algorithms address the gap between hospital discharge and outpatient neurorehabilitation access.
- AI-Driven Exposure Personalization:Machine learning integration with spatial audio environments enables automated phobia hierarchy construction reducing therapist manual configuration burden.
Industry Challenges
- Clinical Workflow Integration:Electronic health record interoperability gaps force dual documentation systems that increase administrative overhead for VR-enabled care delivery.
- Biometric Data Governance:HIPAA compliance complexity for real-time patient physiological streaming creates liability exposure across multi-state telehealth deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Reality in Therapy Market |
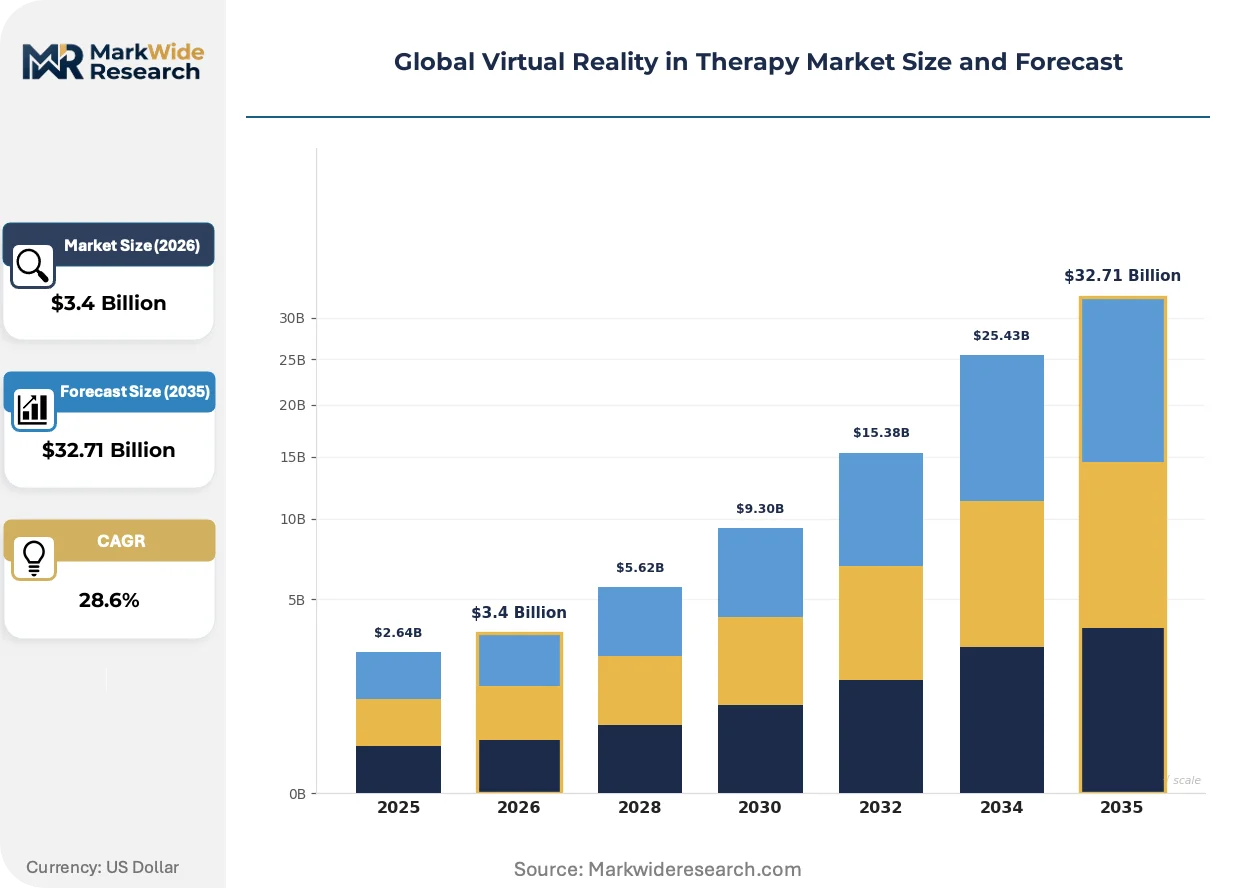
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $32.71 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Anxiety Disorder, PTSD, Phobia Treatment, Pain Management, Cognitive Rehabilitation, Neurorehabilitation Technology: Immersive Head-Mounted Displays, Gesture Recognition, Eye Tracking, Motion Sensors, Spatial Audio, Haptic Feedback End User: Specialized Clinics, Mental Health Centers, Rehabilitation Facilities, Geriatric Care Homes, Pediatric Therapy Units, Home Care Providers Deployment Type: Standalone Systems, Tethered VR, Mobile VR, Cloud-Based VR, Mixed Reality Platforms |
| Companies Covered | Virti, ORamaVR, AppliedVR, MindMaze, Heru, XRHealth, SimX, WAVR, MyndVR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Reality in Therapy Market Shifts & Advancements
Immersive therapeutic platforms are pivoting from hardware sales toward software-as-medical-device recurring revenue models anchored by clinical outcome guarantees and longitudinal patient engagement metrics.
Haptic feedback gloves with force-resistance actuation are electrifying precision rehabilitation protocols for hand dexterity recovery. Occupational therapy departments in post-acute care facilities are deploying these systems at accelerating replacement cycles for traditional mechanical exercise devices. The technology is electrifying competitive differentiation in neurorehabilitation segments where motor learning fidelity determines clinical adoption decisions.
EU MDR Class IIa software classification requirements for VR therapeutic platforms are mandating clinical evidence packages that previously applied only to physical medical devices. Manufacturers must now submit post-market surveillance plans and risk management files to notified bodies before CE marking authorization. German and French notified bodies are experiencing application backlogs that are extending market access timelines by twelve to eighteen months for immersive therapy developers.
Subscription-based platform licensing is displacing perpetual software purchases in hospital procurement departments. Health system value analysis committees are prioritizing total cost-of-ownership models that bundle hardware, software, and remote therapist training across three-year contractual terms. This shift is most pronounced in United States integrated delivery networks where capital expenditure constraints favor operational expenditure recognition for digital therapeutic infrastructure.
Global Virtual Reality in Therapy Market Segmentation
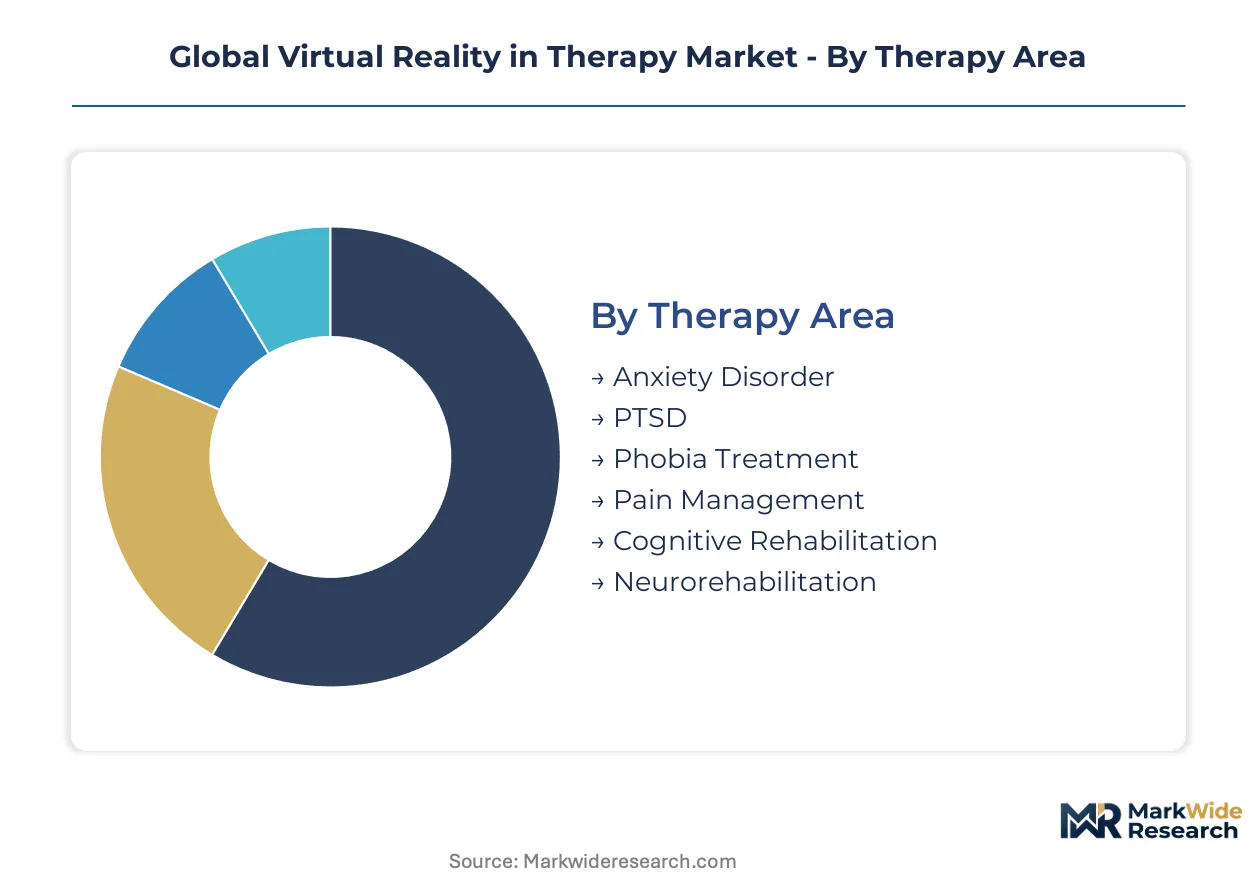
Segmentation in VR therapy markets reveals how capital deployment, regulatory pathways, and reimbursement eligibility concentrate across distinct technical and clinical configurations. Each dimension carries specific hardware requirements, software validation burdens, and end-user procurement behaviors that determine commercial viability.
Therapy Area:
Capital intensity varies sharply across therapy areas, with neurorehabilitation requiring the most substantial upfront investment in motion capture infrastructure and adaptive algorithm development.
- Pain Management:Mature reimbursement codes in United States Medicare and German statutory health insurance reduce commercialization risk for prescription digital therapeutics. Clinical evidence requirements under FDA breakthrough device pathways are compressing time-to-market for chronic pain platforms relative to psychiatric indications.
- Neurorehabilitation:Stroke recovery protocols demand integrated motion sensors and haptic feedback systems with ISO 13485 quality management certification. Demand concentrates in post-acute care facilities across Japan and Germany where aging demographics expand addressable patient populations.
- Anxiety Disorder:Exposure therapy applications leverage lower-cost mobile VR deployments with cloud-based therapist oversight.
- PTSD:Military healthcare systems in the United States and United Kingdom drive procurement through dedicated veteran service budgets.
- Phobia Treatment:Private practice adoption favors standalone systems with minimal IT infrastructure requirements.
- Cognitive Rehabilitation:Geriatric care homes in France and Netherlands pilot subscription-based platforms for dementia care protocols.
Most installed capacity flows through Pain Management. Expansion is steepest in Neurorehabilitation.
Technology:
Hardware specifications determine margin structure, with eye tracking and haptic feedback commanding premium pricing against commoditized head-mounted display components.
- Immersive Head-Mounted Displays:High-resolution OLED microdisplays from concentrated Asian manufacturing clusters create supply vulnerability for clinical-grade systems. FDA software-as-medical-device classification demands IEC 62304 software lifecycle documentation that elevates development costs above consumer VR hardware repurposing.
- Haptic Feedback:Force-resistance actuation gloves enable precision rehabilitation protocols with motor learning fidelity metrics that differentiate neurorehabilitation platforms. Occupational therapy departments in United States post-acute care facilities deploy these systems at accelerating replacement cycles for traditional mechanical devices.
- Gesture Recognition:Camera-based hand tracking reduces hardware cost burden for anxiety exposure protocols.
- Eye Tracking:Biometric precision metrics validate therapeutic efficacy in PTSD treatment trials.
- Motion Sensors:Inertial measurement units support home-based cognitive rehabilitation with remote therapist monitoring.
- Spatial Audio:3D soundscapes enhance presence in phobia hierarchy construction with minimal incremental hardware cost.
Revenue concentration sits with Immersive Head-Mounted Displays. Technology leadership is shifting toward Haptic Feedback.
End User:
Procurement authority and reimbursement access create distinct customer tiers, with specialized clinics holding concentrated purchasing power against fragmented home care demand.
- Specialized Clinics:United States integrated delivery networks favor three-year operational expenditure contracts bundling hardware, software, and remote therapist training. Value analysis committees prioritize total cost-of-ownership models that displace perpetual software purchases.
- Rehabilitation Facilities:German and Japanese stroke recovery centers drive neurorehabilitation platform adoption through formalized digital health application assessment pathways. BfArM precedent creates reimbursement expansion leverage across European social insurance systems.
- Mental Health Centers:Scaling immersive exposure protocols for anxiety and PTSD treatment with FDA breakthrough device designation support.
- Geriatric Care Homes:Pilot programs in Netherlands and Belgium test subscription-based cognitive rehabilitation.
- Pediatric Therapy Units:Developmental disorder applications face heightened safety scrutiny under EU MDR Class IIa software classification.
- Home Care Providers:Cloud-based VR architectures enable remote therapist oversight with HIPAA compliance complexity for multi-state telehealth deployments.
Volume leadership belongs to Specialized Clinics. Fastest penetration gains are occurring in Rehabilitation Facilities.
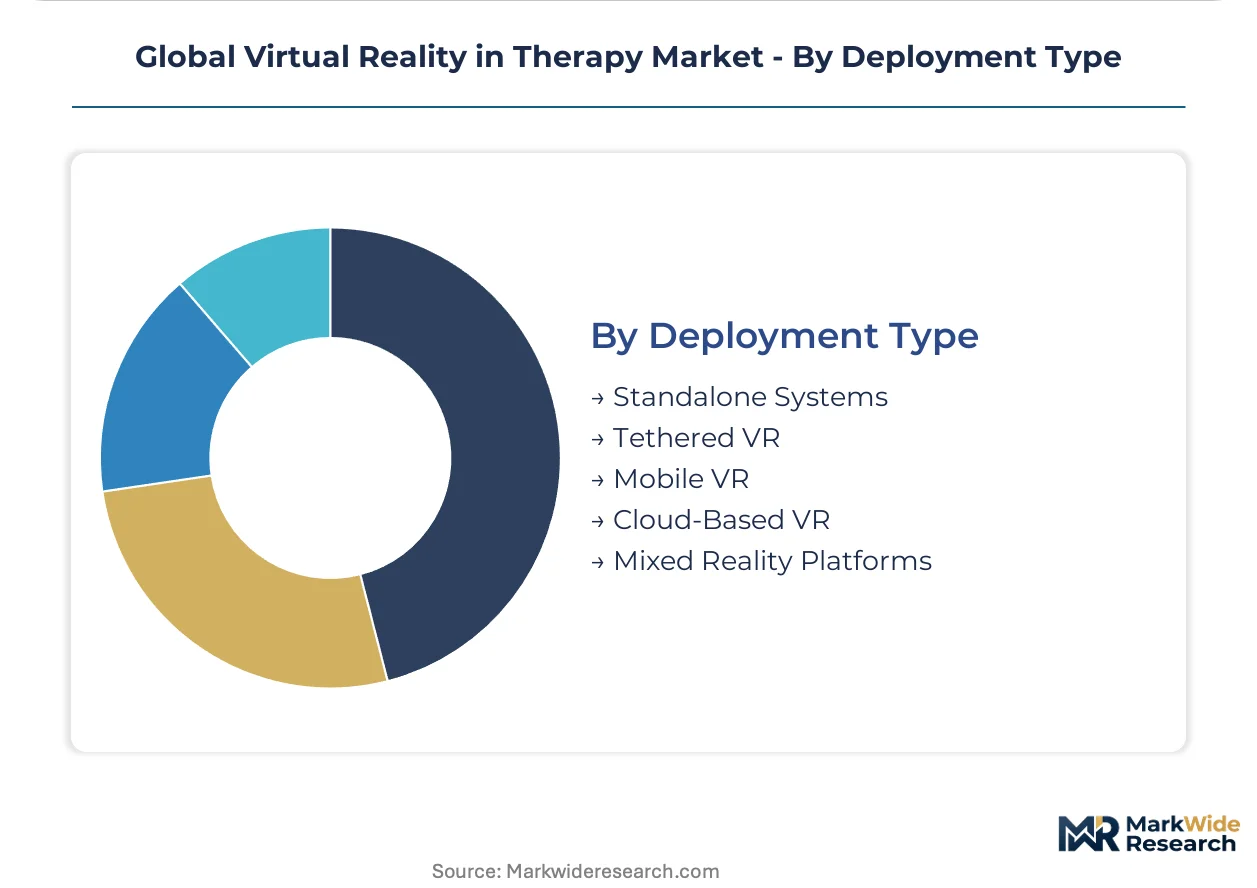
Deployment Type:
Architecture choices determine scalability economics, with cloud-based systems enabling recurring revenue models against capital-intensive tethered installations.
- Cloud-Based VR:Remote session analytics and therapist oversight capabilities expand addressable populations beyond traditional clinic boundaries. EU MDR post-market surveillance requirements mandate real-time performance monitoring that cloud architectures facilitate.
- Tethered VR:High-fidelity graphics processing for neurorehabilitation motion capture demands dedicated computing infrastructure. Hospital IT departments in United States academic medical centers maintain procurement preference for on-premise data governance.
- Standalone Systems:All-in-one headsets reduce IT dependency for mental health center deployments.
- Mobile VR:Smartphone-dependent architectures limit clinical-grade biometric sensor integration.
- Mixed Reality Platforms:Passthrough camera systems enable blended physical-virtual environments for occupational therapy.
Commercial momentum is concentrating in Cloud-Based VR. Tethered VR retains installed base dominance in academic medical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement frameworks mature faster than German statutory pathways, while Japanese stroke recovery demand outpaces European neurorehabilitation deployment rates.
United States
FDA breakthrough device designations accelerate chronic pain and PTSD platform commercialization through expedited review timelines. Medicare Advantage plans in California and Texas pilot dedicated CPT coding for immersive therapeutic sessions. The Boston-Cambridge corridor concentrates venture deployment toward prescription digital therapeutics with clinical outcome guarantees.
Germany
BfArM digital health application assessment pathways establish reimbursement precedent for VR therapy across European social insurance systems. EU MDR Class IIa software classification mandates clinical evidence packages that extend CE marking timelines by twelve to eighteen months. The Munich-Düsseldorf axis hosts post-acute care facility networks deploying motion-capture neurorehabilitation systems.
Japan
PMDA software-as-medical-device frameworks formalize fastest among Asian regulators for immersive therapeutic platforms. Aging demographics in Osaka and Nagoya expand addressable patient populations for stroke recovery protocols combining adaptive algorithms with remote therapist oversight. METI funding programs accelerate domestic haptic feedback glove development for occupational therapy applications.
United Kingdom
NHS digital therapeutics procurement frameworks prioritize total cost-of-ownership models bundling hardware, software, and clinician training across three-year terms. Military healthcare systems in London and Birmingham drive PTSD exposure therapy adoption through dedicated veteran service budgets. MHRA convergence with EU MDR standards simplifies dual-market authorization for immersive therapy developers.
France
ANSM notified body backlogs create regulatory bottlenecks for VR therapeutic platforms seeking CE marking authorization. Pilot programs in Paris and Lyon geriatric care homes test subscription-based cognitive rehabilitation for dementia care protocols. The Île-de-France region concentrates academic medical center procurement preference for cloud-based VR architectures with real-time biometric monitoring.
Global Virtual Reality in Therapy Market Competitive Landscape
Top-tier vendors anchor prescription digital therapeutics, while mid-tier specialists concentrate on telehealth-integrated rehabilitation platforms. The vendor base stratifies across FDA breakthrough device holders, neurorehabilitation motion capture specialists, and cloud-based remote therapy enablers. Three archetypes dominate: clinical-grade hardware-software integrators, adaptive algorithm developers, and telehealth infrastructure providers. Competitive moves concentrate on strategic partnerships with integrated delivery networks and geographic expansion through BfArM reimbursement pathways.
Within the clinical validation tier, AppliedVR and XRHealth occupy positions exemplifying FDA breakthrough pathway navigation and telehealth-integrated deployment respectively. MindMaze anchors the neurorehabilitation specialization vector with motion capture and adaptive algorithm combinations. These three entities represent distinct strategic archetypes: prescription digital therapeutic commercialization, cloud-based platform scaling, and precision motor learning fidelity.
| Leading Market Players |
|---|
| Virti |
| ORamaVR |
| AppliedVR |
| MindMaze |
| Heru |
| XRHealth |
| SimX |
| WAVR |
| MyndVR |
| Others |
Supply & Pricing Matrix
ISO 13485 quality management certification gates qualified supply for clinical-grade VR therapeutic systems, with only manufacturers meeting IEC 62304 software lifecycle standards accessing premium-tier pricing in United States and German procurement channels. This environmental mandate separates prescription digital therapeutic platforms from repurposed consumer hardware, concentrating margin capture among FDA breakthrough device holders and EU MDR Class IIa certified developers.
Pricing Analysis
Capacity additions in South Korean OLED microdisplay fabrication are reshaping price floors for immersive head-mounted displays while maintaining premiums for eye-tracking and haptic feedback configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA software-as-medical-device classification tier and ISO 13485 certification status. Cost compression in standalone mobile VR deployments is intensifying because gesture recognition camera modules commoditize faster than force-resistance actuation systems. Pediatric therapy units and home care providers exhibit highest price sensitivity; academic medical centers with dedicated neurorehabilitation budgets demonstrate lowest.
Supply Chain Analysis
Refurbishment flows for clinical-grade head-mounted displays concentrate in United States and German service depots, extending hardware lifecycles for mental health center deployments. Manufacturing draws from Taiwan and South Korea for high-resolution OLED microdisplays, Japan for inertial measurement units, and China for injection-molded headset chassis. Single-source vulnerability in Sony and Samsung microdisplay allocation creates bottleneck risk for neurorehabilitation platforms requiring sub-20ms motion-to-photon latency. Distribution runs through specialized medical device distributors in North America and direct-to-hospital contracts in European social insurance systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between United States FDA breakthrough pathway acceleration and German BfArM digital health application assessment timelines creates cost and regulatory differential for clinical validation investment deployment.
For Market Incumbents: Deploy post-market surveillance infrastructure to satisfy EU MDR Class IIa software classification requirements before notified body backlogs extend twelve to eighteen months. Consolidate around motion capture algorithm IP as haptic feedback glove specialists emerge from METI-funded Japanese development programs. Channel control through integrated delivery network three-year operational expenditure contracts defends against cloud-based platform entrants. For New Entrants and Emerging Players: Launch via subscription-based platform licensing to bypass capital expenditure constraints in United States academic medical centers. Home-based cognitive rehabilitation for stroke recovery addresses the gap between hospital discharge and outpatient access, with Netherlands and Belgium geriatric care homes showing fastest penetration gains. Target German statutory health insurance integration as the most penetrable reimbursement pathway. For Investors and Strategic Acquirers: Roll-up economics work for adaptive algorithm developers because FDA software-as-medical-device classification concentrates clinical evidence burden on standalone platforms. Five-to-ten year viability hinges on biometric sensor convergence enabling real-time exposure personalization. Watch German BfArM reimbursement code expansion velocity as inflection indicator for European social insurance system adoption.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Expedited review pathways compress time-to-market for chronic pain prescription digital therapeutics. |
| CE Marking Pathway under EU MDR | Class IIa software classification mandates clinical evidence packages extending authorization timelines. |
| Hospital System Partnership | United States integrated delivery networks favor three-year bundled contracts displacing perpetual purchases. |
| Software Companion Development | Cloud-based architectures enable remote therapist oversight expanding addressable populations beyond clinics. |
| Reimbursement Strategy | German BfArM digital health application assessment creates precedent across European social insurance systems. |
Research Methodology
Coverage spans United States, Germany, Japan, United Kingdom, and France, with primary inputs from each combining interviews with FDA regulatory consultants, hospital biomedical engineers, GPO contracts managers, and neurorehabilitation clinicians alongside secondary validation. Bottom-up and top-down triangulation incorporates FDA 510(k) and breakthrough device filings, EMA and PMDA software-as-medical-device submissions, hospital procurement databases, and CMS Medicare reimbursement code tracking.
Granularity-level modeling captures therapy area, technology component, end-user facility type, and deployment architecture dimensions across the analysis window. CAGRs derive from installed base growth curves for immersive head-mounted displays and haptic feedback systems, weighted by reimbursement eligibility velocity in each national market. Forecast inputs include clinical trial pipeline progression for PTSD exposure protocols and motion capture precision benchmarks for stroke recovery applications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA software-as-medical-device reclassification or EU MDR notified body capacity constraints. Practitioners should monitor CPT code pilot program expansion in United States Medicare Advantage plans and BfArM application processing rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
VR in Sports Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Enterprise Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Amusement Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Prototype Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Automotive Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality (XR) Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Visor Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Glasses Market