
 India E-Commerce Market | 2026-2036
India E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
India E-Commerce Market Outlook
Grocery and fast-moving consumer goods purchasing is broadening beyond metro consumers into smaller Indian cities. Flipkart leverages its warehouse network to anchor same-day delivery in dense urban corridors. Amazon India sustains technology leadership through machine learning-driven demand forecasting for its India fulfillment centers. Meesho competes on zero-commission marketplace models that attract millions of small-town resellers.
India E-Commerce denotes the digital exchange of goods and services through internet-connected platforms, utilizing mobile applications, web interfaces, and integrated payment gateways to facilitate transactions between sellers and buyers. The sector operates on cloud-native architecture with real-time inventory synchronization, last-mile logistics orchestration, and AI-powered recommendation engines designed to convert browsing behavior into completed purchases. Electronics and fashion together form the largest product category revenue pool, though groceries represent the fastest-expanding segment as cold-chain infrastructure matures. Digital wallets and UPI-powered payment methods now dominate transaction volumes, displacing cash-on-delivery from its earlier primacy as consumer trust in digital finance deepens across Indian demographics.
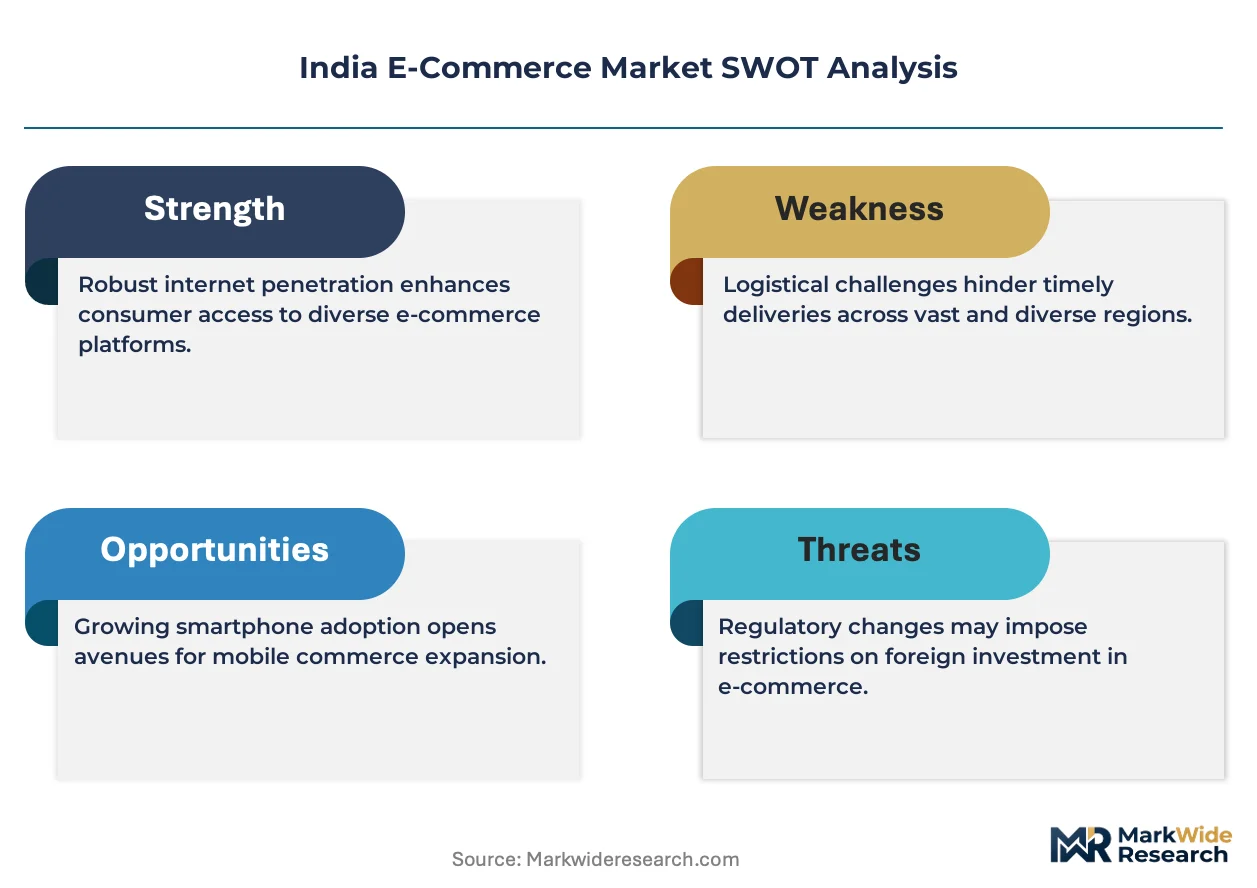
The Reserve Bank of India governs payment system integrity through its Payment and Settlement Systems Act, while the Consumer Protection (E-Commerce) Rules under the Ministry of Consumer Affairs mandate disclosure standards and grievance redressal mechanisms for platforms. The Department for Promotion of Industry and Internal Trade enforces foreign direct investment caps in inventory-based e-commerce models, channeling capital toward marketplace structures. Stakeholders must monitor how proposed amendments to data localization requirements and platform accountability frameworks alter operating cost structures and competitive moats.
Market Dynamics
UPI's dominance in digital payments is compressing checkout friction and accelerating transaction velocity across Indian e-commerce platforms. The RBI's real-time settlement infrastructure has eliminated the cash-on-delivery dependency that once constrained seller cash flows and buyer conversion rates.
Growth Catalysts
- Production-Linked Incentive scheme:Electronics manufacturing subsidies under India's PLI scheme are expanding domestic smartphone and appliance supply, reducing import dependency and enabling faster fulfillment cycles for platform sellers.
- Tier-two and tier-three city demand:Households in smaller Indian cities are accelerating online grocery adoption as cold-chain infrastructure reaches secondary urban centers previously excluded from same-day delivery networks.
- Cloud-native architecture:Real-time inventory synchronization across distributed warehouse networks is enabling platforms to promise accurate delivery windows and reduce stockout-driven cart abandonment.
Market Restraints
- Foreign direct investment caps:The Department for Promotion of Industry and Internal Trade enforces inventory-based e-commerce restrictions that channel capital toward marketplace models and constrain platform-owned inventory strategies.
- Data localization compliance:Proposed amendments to storage requirements for payment and consumer data are elevating server infrastructure costs and complicating cross-border technology partnerships.
- Last-mile logistics fragmentation:Delivery partner density remains uneven across India's northeastern states and Himalayan territories, extending delivery timelines and elevating per-unit shipping costs in these geographies.
Strategic Opportunities
- Vernacular interface expansion:Platform localization into Hindi, Tamil, Telugu, and Marathi interfaces is unlocking first-time e-commerce users in non-English-speaking households across Bihar, Uttar Pradesh, and rural Maharashtra.
- Quick commerce integration:Dark store networks for 10-15 minute grocery delivery are creating new real estate categories and attracting dedicated capital pools separate from traditional warehouse infrastructure.
- FSSAI-compliant private labels:Food safety certification is enabling platforms to launch house-brand staples with margin structures superior to third-party FMCG listings.
Industry Challenges
- AI/ML talent scarcity:Demand forecasting and recommendation engine development require specialized data science capabilities that command premium compensation and experience high attrition in Bengaluru and Hyderabad talent markets.
- Multi-platform seller integration:Inventory management systems must synchronize across Flipkart, Amazon India, and Meesho interfaces simultaneously, creating API complexity and order-routing errors.
- Grievance redressal automation:The Consumer Protection (E-Commerce) Rules mandate response timelines that strain manual customer service operations and require capital-intensive chatbot and escalation system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India E-Commerce Market |
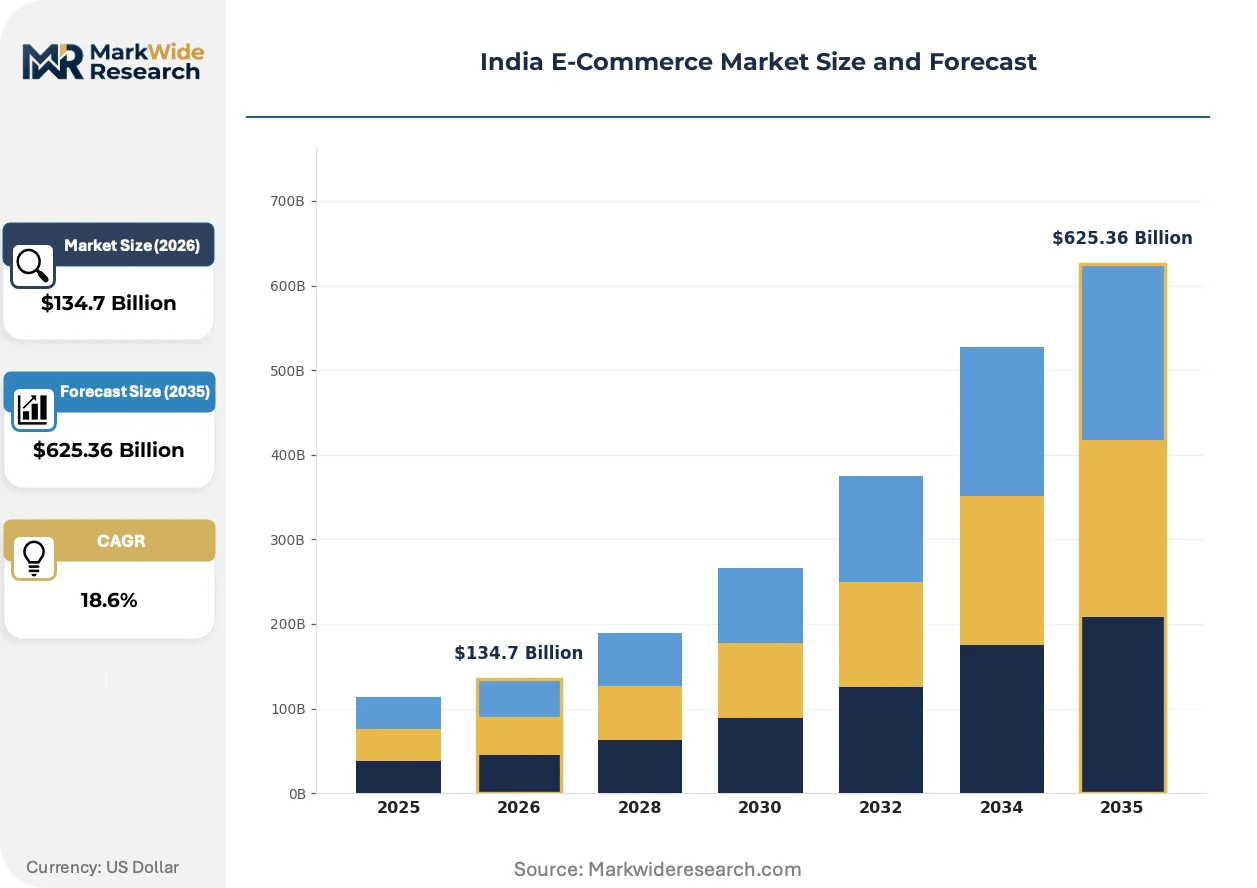
| Market Size in 2026 | $134.7 Billion |
| Market Size in 2035 | $625.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Fashion, Home Appliances, Groceries Service Type: Online Retail, Subscription Services, Resale Platforms, Direct-to-Consumer Customer Demographic: Millennials, Gen Z, Working Professionals, Families Payment Method: Credit Card, Digital Wallets, Bank Transfer, Cash on Delivery |
| Companies Covered | Flipkart, Amazon India, Reliance Industries, Tata Group, Meesho, Nykaa E-Retail, Myntra, BigBasket, Snapdeal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India E-Commerce Market Strategic Shifts
Artificial intelligence is embedding into every layer of Indian e-commerce operations, from warehouse robotics to personalized recommendation engines. Three interconnected developments are compressing fulfillment timelines and elevating platform switching costs simultaneously.
Machine learning-driven demand forecasting is rewriting inventory positioning strategies for electronics and fashion categories. Tier-one city fulfillment centers now stock products based on predictive models trained on search behavior, weather patterns, and festival calendars. This compression of safety stock requirements is freeing working capital for platform expansion into quick commerce.
The RBI's Payment and Settlement Systems Act enforcement is tightening compliance requirements for wallet providers and buy-now-pay-later operators. Non-bank payment entities must now maintain stricter net worth thresholds and transaction audit trails. Marketplace sellers in high-ticket categories are responding by diversifying across UPI, credit cards, and EMI options to minimize dependency on any single payment rail.
Reseller network models are displacing traditional inventory-holding merchant structures in small-town India. Individual entrepreneurs source products through platform interfaces and distribute via WhatsApp and Instagram, earning commissions without warehousing risk. This behavioral shift is most visible in Gujarat and Rajasthan textile clusters, where home-based resellers now account for substantial order volume originating outside metropolitan postal codes.
India E-Commerce Market Segmentation
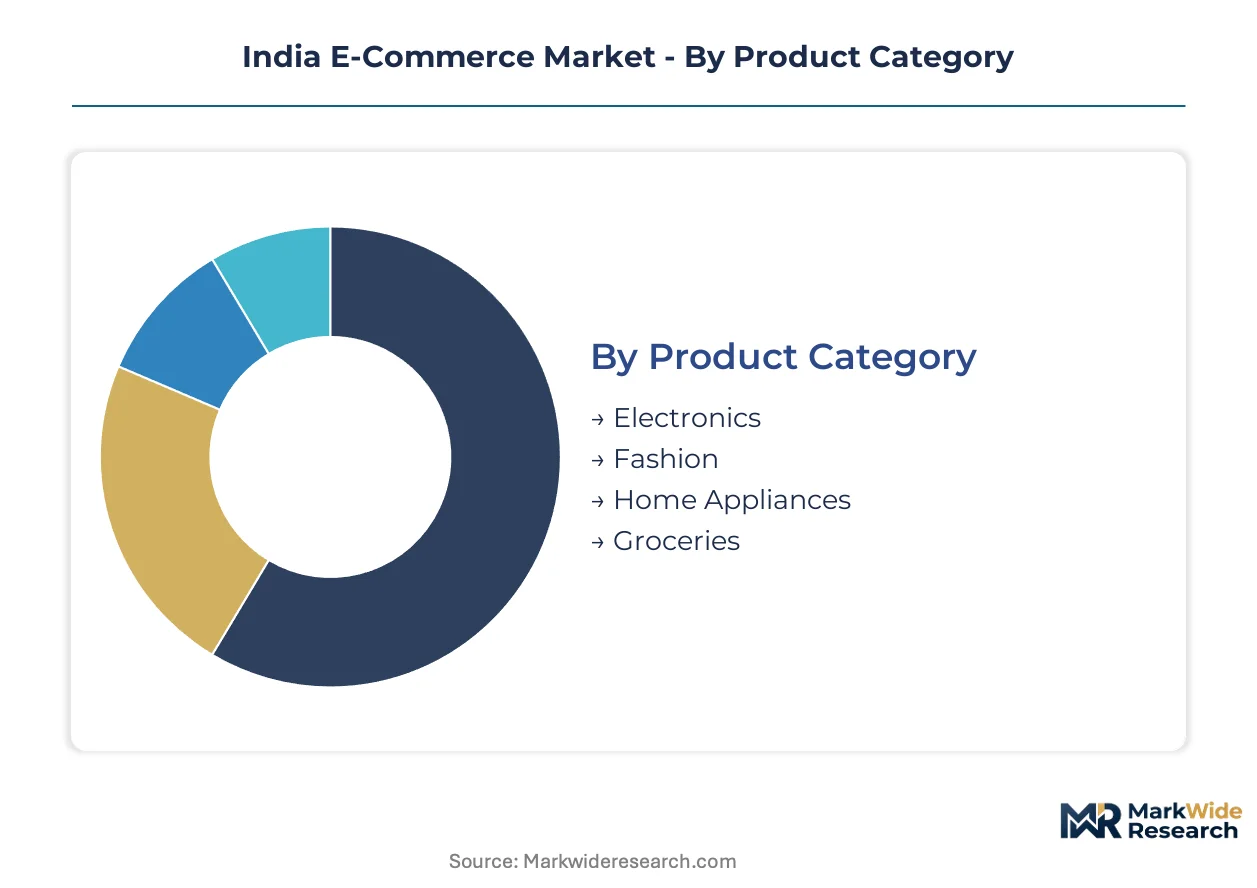
India's e-commerce market fragments across four distinct dimensions that determine platform strategy, logistics investment, and payment infrastructure priorities. Product category concentration shapes warehouse network design, while demographic shifts dictate interface localization and marketing spend allocation.
Product Category:
Purchase frequency and fulfillment velocity separate electronics buyers from grocery shoppers, driving fundamentally different supply chain economics across Indian platforms.
- Electronics:High-ticket items with extended replacement cycles dominate warehouse capacity in Maharashtra and Karnataka fulfillment clusters. Smartphone and laptop demand concentrates in Delhi-NCR and Bengaluru, where consumers prioritize warranty coverage and EMI availability over immediate delivery speed.
- Fashion:Seasonal inventory turnover and high return rates compress margin structures for apparel marketplaces. Tier-two city consumers in Uttar Pradesh and Rajasthan now drive volume growth, shifting sizing standardization requirements away from metro-centric fits.
- Home Appliances:Installation-dependent purchases require coordinated logistics networks combining delivery with technician dispatch across Indian states.
- Groceries:Cold-chain infrastructure maturity in tier-one cities enables same-day delivery promises, while tier-three expansion depends on dark store density.
Electronics leads volumes today; groceries is gaining share fastest.
Service Type:
Platform business models diverge based on inventory risk allocation and seller relationship structures, determining capital intensity and regulatory exposure under Indian FDI rules.
- Online Retail:Marketplace aggregators connect third-party sellers to buyers without holding inventory, complying with DPIIT foreign investment restrictions on inventory-based models. Flipkart and Amazon India operate predominantly through this structure.
- Subscription Services:Recurring delivery commitments for personal care and household staples generate predictable demand patterns that optimize procurement cycles. Urban working professionals in Mumbai and Pune show highest adoption for curated beauty and wellness boxes.
- Resale Platforms:Meesho's zero-commission model attracts millions of small-town resellers distributing through WhatsApp networks in Gujarat and Tamil Nadu.
- Direct-to-Consumer:Brand-owned storefronts bypass marketplace fees but absorb customer acquisition costs and logistics complexity independently.
Online retail commands current revenue concentration; resale platforms are expanding most quickly into non-metro Indian markets.
Customer Demographic:
Age and household composition determine device preference, payment method adoption, and category penetration depth across Indian e-commerce.
- Millennials:First-generation digital buyers now entering peak earning years drive premium electronics and international fashion brand demand. This cohort's comfort with UPI and credit-based EMI options reduces cash-on-delivery dependency in tier-one cities.
- Gen Z:Mobile-native shoppers prioritize short-form video discovery and vernacular interface engagement. Bihar and Uttar Pradesh youth populations represent the largest untapped conversion opportunity for Hindi-language platform localization.
- Working Professionals:Time-constrained buyers in Bengaluru and Hyderabad generate disproportionate quick commerce adoption for prepared meals and convenience groceries.
- Families:Bulk purchasing patterns and price sensitivity characterize household decision-making, favoring subscription models and festival-season discounting.
Millennials anchor current spending power; Gen Z shows the steepest expansion trajectory as first-income earners.
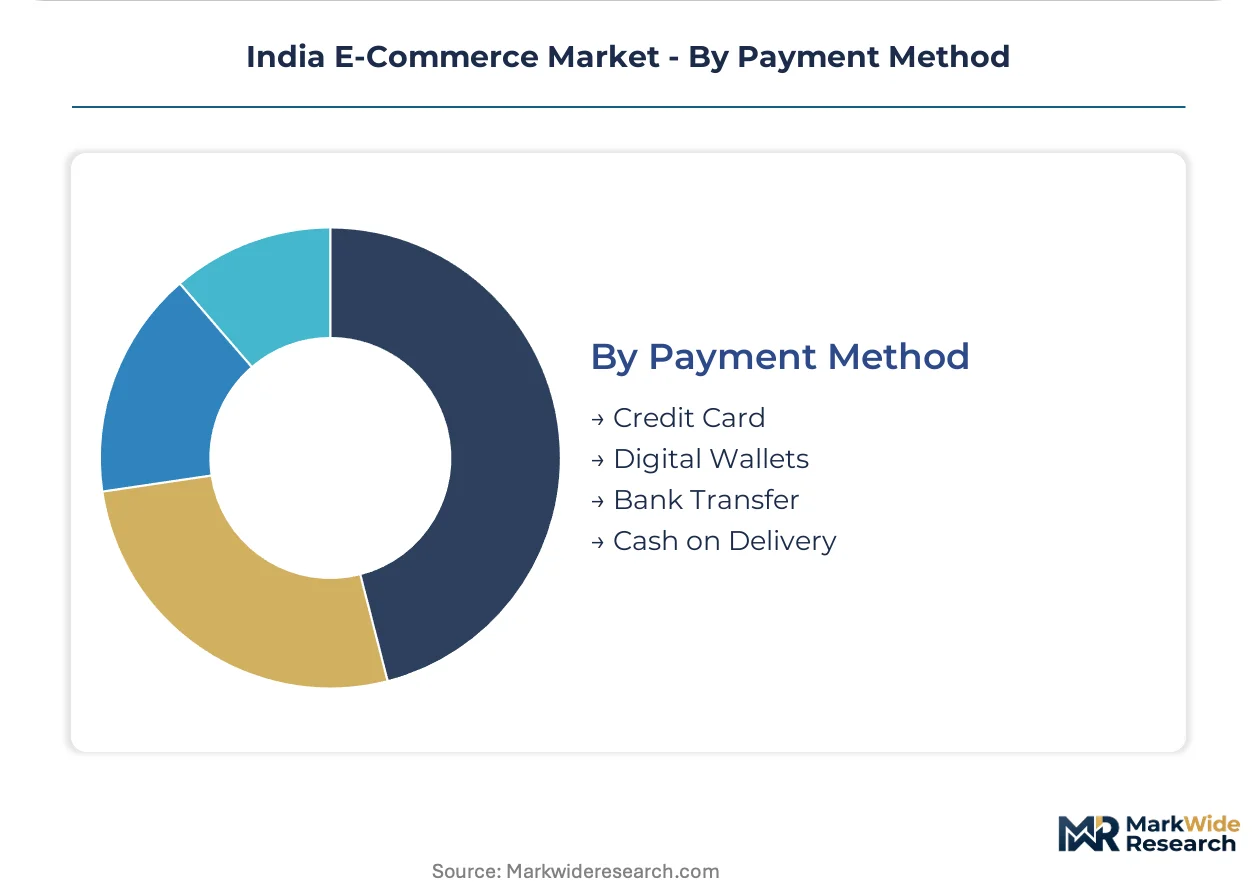
Payment Method:
Settlement infrastructure maturity and consumer trust levels segment Indian e-commerce transactions across four rails with distinct cost structures and fraud risk profiles.
- Digital Wallets:UPI-powered real-time settlement now dominates transaction volumes, displacing cash-on-delivery from primacy. RBI's Payment and Settlement Systems Act enforcement tightens compliance requirements for wallet providers.
- Credit Card:High-ticket electronics and international travel bookings concentrate in this channel, with EMI conversion options driving affordability for premium purchases in Delhi-NCR and Mumbai.
- Bank Transfer:Net banking and NEFT settlements persist for B2B procurement and high-value transactions requiring documentary trail.
- Cash on Delivery:Remaining relevance in tier-three cities and first-time buyer segments constrains seller cash flow and elevates logistics costs through return-to-origin risks.
Digital wallets lead transaction volumes today; credit card penetration is climbing the fastest among aspirational tier-two consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra anchors fulfillment center investment across Indian e-commerce, with Mumbai-Pune corridor warehousing absorbing the highest capital deployment. State-level industrial policies and GST registration clusters concentrate seller ecosystems in specific geographies.
Maharashtra
Mumbai's dense postal code network enables same-day delivery promises for premium electronics and fashion categories. The state's warehousing policy under MIDC offers subsidized land allocations for cold-chain infrastructure near Bhiwandi. Thane district hosts India's largest consolidated fulfillment cluster, processing cross-category inventory for platforms serving western India.
Karnataka
Bengaluru's tech workforce generates disproportionate demand for quick commerce and subscription services. The Karnataka Industrial Areas Development Board fast-tracks warehouse approvals for e-commerce operators in Hoskote and Dabaspet. Whitefield and Electronic City sub-markets concentrate dark store networks targeting IT corridor professionals.
Delhi-NCR
High-ticket electronics demand concentrates in Gurugram and Noida, where EMI penetration exceeds national averages. The Delhi government's electric vehicle policy mandates last-mile fleet electrification timelines affecting delivery economics. Okhla and Bawal industrial zones anchor cross-border fulfillment for northern hinterland states.
Tamil Nadu
Chennai's manufacturing base supplies consumer durables to marketplace sellers across southern markets. The Tamil Nadu Industrial Policy offers capital subsidies for automated warehousing investments in Sriperumbudur. Coimbatore's textile clusters feed reseller networks distributing through platform interfaces into Kerala and Karnataka.
Telangana
Hyderabad's pharmaceutical and nutraceutical manufacturing base expands platform private-label sourcing for wellness categories. The Telangana State Industrial Infrastructure Corporation designates e-commerce logistics parks in Shamshabad with single-window clearance mechanisms. Miyapur and Kondapur sub-markets show highest quick commerce adoption rates among Indian tier-one cities.
India E-Commerce Market Competitive Environment
Strategic partnerships dominate the current landscape as conglomerates and pure-play platforms negotiate supply agreements and technology sharing. The market structures around three tiers: diversified industrial groups with captive retail arms, venture-capital-backed horizontal marketplaces, and vertical specialists in beauty or grocery. Two archetypes anchor competitive positioning — conglomerate-affiliated platforms leveraging existing distribution infrastructure, and asset-light marketplaces prioritizing seller network scale over inventory ownership. Competitive moves center on exclusive brand launches and quick commerce dark store expansion.
Within the conglomerate-affiliated tier, Reliance Industries and Tata Group exemplify backward integration strategies, controlling supply chains from manufacturing through last-mile delivery. Flipkart and Amazon India occupy positions as horizontal marketplaces with established fulfillment networks, while Meesho represents the zero-commission reseller archetype penetrating non-metro markets through social distribution channels.
| Leading Market Players |
|---|
| Flipkart |
| Amazon India |
| Reliance Industries |
| Tata Group |
| Meesho |
| Nykaa E-Retail |
| Myntra |
| BigBasket |
| Snapdeal |
| Others |
Value Chain & Pricing Dynamics
FSSAI food-safety certification gates access to premium-tier private-label margins and qualified cold-chain suppliers for Indian e-commerce platforms. The RBI's digital payment infrastructure mandates compress transaction costs for UPI-enabled sellers while elevating compliance expenses for non-compliant warehouse operators.
Pricing Analysis
Retailer markup structures stratify across three tiers: premium same-day delivery commands 15-20% logistics premiums, standard 2-3 day fulfillment captures volume share, and economy 5-7 day options penetrate price-sensitive tier-three markets. Price differentiation rests on cold-chain certification grade and vernacular interface localization investment. Cost compression in standard-tier electronics is intensifying because PLI-subsidized domestic manufacturing expands supplier pools. Tier-three city households show highest price sensitivity; working professionals in Bengaluru and Hyderabad demonstrate lowest elasticity for quick commerce premiums.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing is reshaping sourcing patterns away from China-dependent smartphone assembly toward domestic Karnataka and Tamil Nadu production hubs. Raw material dependencies center on semiconductor chips from Taiwan, lithium-ion cells from China, and cold-chain equipment from Germany. Single-source vulnerability concentrates in UPI payment gateway infrastructure controlled by NPCI-regulated entities. Distribution runs through Bhiwandi-Thane fulfillment clusters for western India, Hoskote-Dabaspet for southern corridors, and Okhla-Bawal for northern hinterland states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's e-commerce market offers margin-expansion pathways through quick commerce dark-store density and PLI-subsidized captive manufacturing. Cost compression in logistics technology and payment infrastructure widens the operating leverage available to scaled operators.
For Market Incumbents: Acquire dark-store real estate in Hyderabad's Miyapur-Kondapur corridor and Bengaluru's Whitefield sub-market to anchor 10-15 minute delivery promises. Consolidate reseller network relationships in Gujarat and Rajasthan textile clusters before Meesho-exclusive arrangements harden. Threat from zero-commission marketplace models demands backward integration into FSSAI-certified private-label food production to defend margin structures.
For New Entrants and Emerging Players: Vernacular-language mobile interfaces unlock first-time e-commerce users in Bihar and Uttar Pradesh Gen Z populations. Target quick commerce in tier-two pharmaceutical manufacturing hubs like Hyderabad's Shamshabad logistics parks where working professional density exceeds current dark-store coverage. Go-to-market leverage rests on WhatsApp-integrated social selling tools that replicate Meesho's reseller acquisition model without platform fee burdens.
For Investors and Strategic Acquirers: Roll-up economics work for regional logistics specialists with cold-chain certification because fragmented last-mile operator density in northeastern states prevents national platform self-build. Long-term viability favors warehouse automation technology providers and vernacular AI interface developers over undifferentiated marketplace plays. Watch RBI data-localization amendment passage as inflection signal for infrastructure cost structure resets.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark Store Network Expansion | 10-15 minute grocery delivery promises lock in urban working professional loyalty in Bengaluru and Hyderabad. |
| Vernacular Interface Localization | Hindi, Tamil, and Telugu platform versions unlock first-time e-commerce conversion in Bihar and Uttar Pradesh. |
| FSSAI Private-Label Launch | House-brand staples capture margin premiums unavailable to third-party FMCG marketplace listings. |
| Reseller Network Acquisition | WhatsApp-distributed seller relationships in Gujarat and Rajasthan textile clusters deflect Meesho expansion. |
| UPI Infrastructure Compliance | RBI Payment and Settlement Systems Act adherence preserves transaction volume access as regulatory thresholds tighten. |
Study Parameters
Multiple input streams — primary interviews with fulfillment center operations heads, marketplace seller network managers, and RBI regulatory affairs specialists, alongside secondary validation through DPIIT FDI circulars, FSSAI compliance databases, and state industrial policy filings — were reconciled through bottom-up warehouse capacity modeling and top-down payment volume triangulation. Stakeholder consultations included logistics technology vendors, cold-chain equipment suppliers, and vernacular AI localization developers. Secondary sources encompassed UPI transaction data from NPCI disclosures, PLI scheme beneficiary lists from the Ministry of Electronics and Information Technology, and state-level warehousing policy documents from Maharashtra MIDC and Karnataka Industrial Areas Development Board.
Historical fulfillment center investment patterns were cross-referenced against panel input from platform supply chain strategists to anchor capacity expansion assumptions across the projection horizon. Segmentation dimensions modeled include product category velocity, service type inventory risk allocation, customer demographic payment behavior, and state-level logistics infrastructure maturity. CAGRs were derived from reconciling top-down macro consumption forecasts with bottom-up warehouse square footage and delivery partner density buildouts. Industry-specific inputs incorporated UPI penetration curves and cold-chain certification compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for AI-driven demand forecasting and warehouse robotics deployment would alter the outlook for labor cost structures and inventory accuracy targets. Forecasts reflect assumptions regarding PLI scheme continuation and UPI infrastructure stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Commerce Software Market
E-Commerce Solutions
Asia Pacific E-Commerce Market
E-Commerce Solutions
Social Commerce Market
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
Courier Express and Parcel (CEP) Market
E-Commerce Solutions
Global Subscription E Commerce Market
E-Commerce Solutions
E-Commerce Buy Now Pay Later Market
E-Commerce Solutions
Albania E-Commerce Market
E-Commerce Solutions
Global B2B E-Commerce Market
E-Commerce Solutions
Global Online Book Services Market
E-Commerce Solutions
Oman E-Commerce Market
E-Commerce Solutions
FMCG B2B E-Commerce Market
E-Commerce Solutions
Europe Food Platform-To-Consumer Delivery Market
E-Commerce Solutions
Denmark E-Commerce Market
E-Commerce Solutions
UK Ecommerce Market
E-Commerce Solutions
Bedding E-Commerce Platform Market