
 Global Internal Communications Software Market | 2026-2036
Global Internal Communications Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Internal Communications Software Market Foresight
Platform bundling is restructuring buyer choice across the internal communications software landscape. Microsoft Teams leverages its Office 365 integration to dominate enterprise procurement cycles. Staffbase anchors its position through specialized employee-experience layers for distributed workforces. Slack competes by sustaining developer-friendly customization ecosystems that reduce IT dependency.
Internal communications software encompasses digital platforms that enable structured information exchange, real-time messaging, and content distribution within organizational boundaries, typically operating across web and mobile endpoints with API-driven interoperability. The primary commercial purpose centers on reducing email volume, accelerating decision velocity, and preserving institutional knowledge across hybrid work configurations. Cloud-based deployment leads in new customer acquisition while on-premise installations retain favor among financial services and defense contractors with data-sovereignty requirements. Employee engagement use cases command the widest deployment footprint, though crisis management functionality is expanding fastest as organizations harden operational resilience protocols.
The EU AI Act and GDPR shape product architecture requirements for vendors serving European enterprises, mandating automated decision transparency and cross-border data governance controls. The US HIPAA framework and SEC disclosure rules extend compliance obligations for healthcare and publicly traded adopters, respectively. ISO 27001 certification has become a baseline procurement filter rather than a differentiator. Stakeholders must evaluate vendor roadmaps against emerging interoperability standards and AI governance frameworks before committing to multi-year contracts.
Market Dynamics
Platform bundling by Microsoft, Salesforce, and SAP is compressing procurement cycles and marginalizing standalone vendors across the internal communications software landscape. Buyers now evaluate communications tools within broader enterprise suites rather than as discrete purchases.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must deploy auditable messaging systems with automated decision transparency, accelerating replacement of legacy email infrastructure.
- Healthcare workforce mobility:HIPAA-covered entities require secure clinical communication platforms that preserve patient data sovereignty across shift-based nursing and remote physician consultations.
- API-first architecture adoption:Developer teams embed communications modules directly into operational software, reducing IT ticket backlogs and accelerating deployment timelines.
Market Restraints
- Cloud concentration risk:Three hyperscalers control over 70% of underlying infrastructure, creating single-point-of-failure exposure for multi-tenant SaaS deployments.
- GDPR cross-border friction:Data localization requirements in Germany, France, and Austria fragment vendor architectures and inflate compliance engineering costs.
- Email persistence:Regulatory archiving requirements in financial services perpetuate parallel email systems, preventing full platform consolidation.
Strategic Opportunities
- India manufacturing corridors:PLI scheme beneficiaries require multilingual workforce coordination platforms for plant-floor to headquarters information flow.
- Frontline worker activation:Retail, logistics, and hospitality sectors seek mobile-first engagement tools for deskless employee populations historically excluded from digital workplace investments.
- CSRD disclosure alignment:European sustainability reporting mandates create demand for internal communication platforms that track and disseminate workforce diversity metrics.
Industry Challenges
- ISO 27001 certification timelines:Vendor security audits extend 9-14 months, delaying enterprise contract signatures and compressing implementation windows.
- Legacy ERP integration complexity:SAP and Oracle on-premise installations resist API connectivity, forcing costly middleware development for unified employee directories.
- AI governance skill scarcity:European buyers lack internal expertise to evaluate algorithmic transparency claims under the EU AI Act risk classification framework.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Internal Communications Software Market |
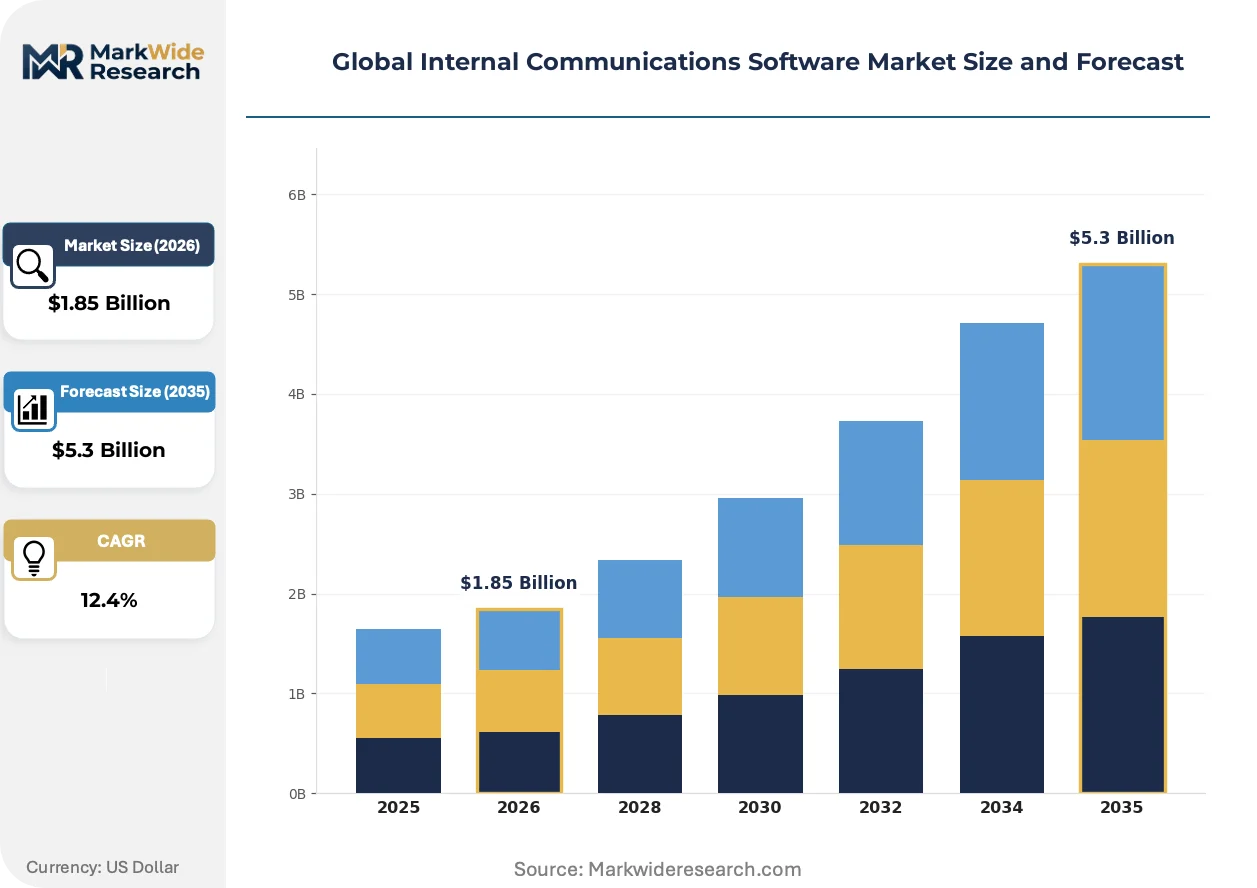
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.3 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Virtual Private Cloud Solution Type: Messaging, Video Conferencing, Document Sharing, Employee Surveys, Task Management Use Case: Employee Engagement, Crisis Management, Internal Marketing, Knowledge Sharing, Remote Collaboration Customer Type: Small Enterprises, Medium Businesses, Large Corporations, Non-Profit Organizations |
| Companies Covered | Monday.com, Staffbase, Slack, ContactMonkey, Connecteam, Microsoft Teams, Zoom, eXo Platform, Google Workspace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Internal Communications Software Market Shifts & Advancements
Artificial intelligence is embedding into core messaging workflows, shifting competitive differentiation from channel breadth to predictive content delivery and automated sentiment analysis.
Microservices-based backend architecture is modularizing vendor development roadmaps, allowing healthcare systems in Germany and the United States to deploy only crisis-alert, shift-scheduling, or clinical-handoff modules rather than full-suite implementations. Hospital procurement teams accelerate vendor selection by 40% when evaluating componentized offerings against monolithic alternatives. This structural decomposition is compressing implementation cycles and lowering switching costs for specialized use cases.
The EU AI Act's high-risk system classification is forcing vendors serving European enterprises to document training data provenance and establish human-in-the-loop override protocols for automated message routing. Product teams must redesign natural-language processing pipelines to satisfy French CNIL and German BSI audit requirements. Healthcare and financial services adopters now require algorithmic impact assessments as standard procurement documentation.
Frontline workforce segments are commanding dedicated product roadmaps after decades of enterprise software neglect. Manufacturing conglomerates in Japan and retail chains in Brazil now specify mobile-optimized interfaces, offline message caching, and biometric authentication for shared device environments. Vendor sales cycles increasingly separate desk-worker from deskless-worker pricing and feature tiers, reflecting divergent technical requirements and deployment constraints.
Global Internal Communications Software Market Segmentation
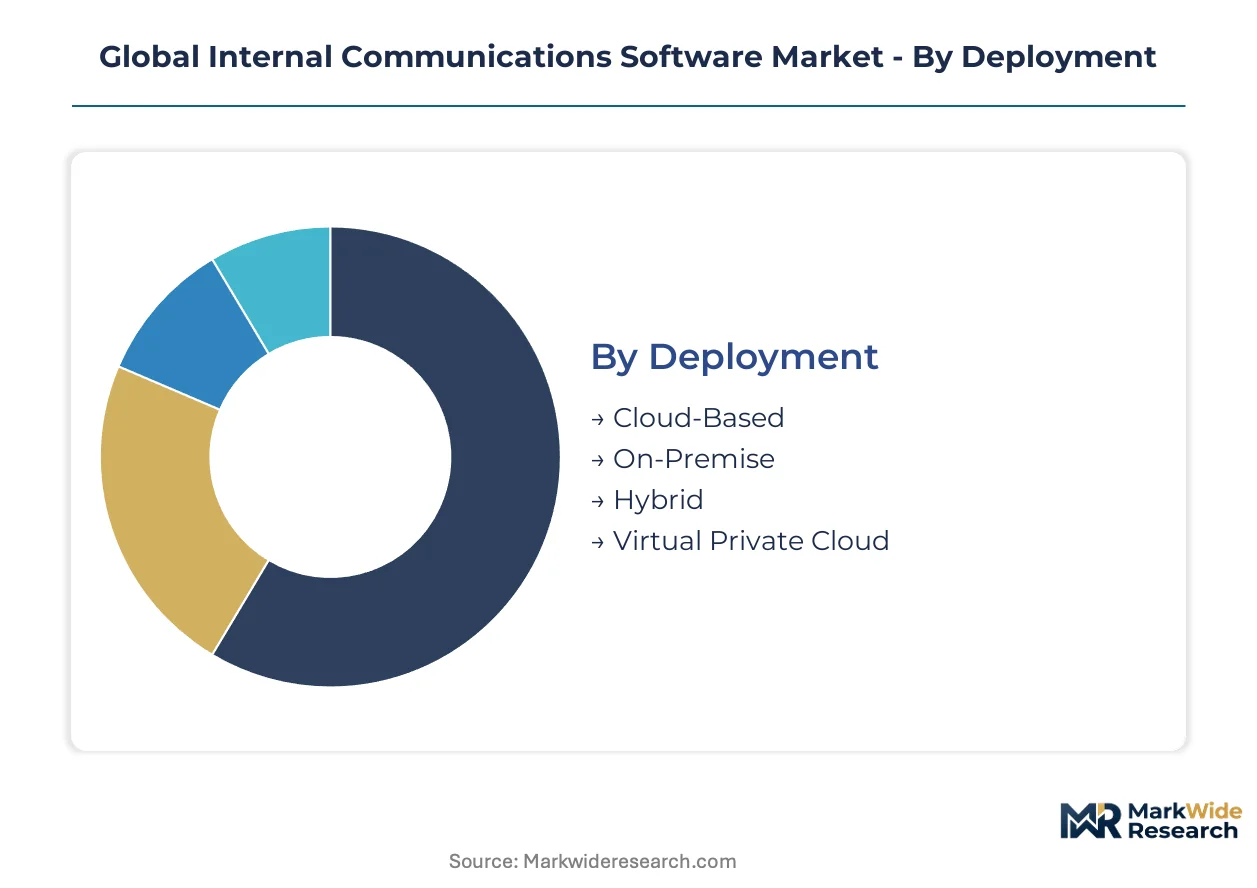
Deployment architecture determines compliance posture and total cost of ownership for internal communications platforms. Solution specialization and use case intensity further differentiate procurement priorities across regulated industries and workforce configurations.
Deployment:
Cost tier separates buyers seeking operational agility from those prioritizing data sovereignty and audit control.
- Cloud-Based:Multi-tenant SaaS architectures deliver automatic updates and elastic scaling without capital expenditure. Healthcare systems in Germany favor these deployments for rapid clinical staff onboarding, though GDPR cross-border data governance adds contractual complexity.
- On-Premise:Self-hosted infrastructure maintains complete data custody within organizational firewalls. Defense contractors and financial services institutions in the United States mandate these installations to satisfy SEC archiving requirements and HIPAA technical safeguards.
- Hybrid:Split configurations route sensitive communications through private infrastructure while leveraging public cloud for general workforce messaging. Industrial conglomerates adopt this model to isolate R&D intellectual property from operational collaboration tools.
- Virtual Private Cloud:Dedicated cloud instances combine single-tenant isolation with managed service economics. Mid-market enterprises in France select this path to satisfy CNIL audit expectations without building internal platform expertise.
Cloud-based deployments lead volumes today; virtual private cloud configurations are gaining share fastest among compliance-conscious mid-market buyers.
Solution Type:
Application intensity varies by workforce mobility and synchronous collaboration requirements.
- Messaging:Real-time text, voice, and threaded conversation platforms form the functional core of modern internal communications. Shift-based nursing teams in United States hospitals depend on these tools for HIPAA-compliant handoffs, driving integration with electronic health record systems.
- Video Conferencing:High-definition synchronous meeting infrastructure supports distributed decision-making and executive broadcasts. Manufacturing headquarters in Japan deploy these solutions for multilingual plant-floor coordination across PLI scheme beneficiary facilities.
- Document Sharing:Centralized repositories with version control and access logging preserve institutional knowledge. These systems serve as compliance archives under EU CSRD disclosure mandates for workforce policy documentation.
- Employee Surveys:Pulse measurement and feedback collection modules enable data-driven engagement strategies. Retail chains in Brazil utilize these tools to capture frontline worker sentiment without dedicated IT support.
- Task Management:Workstream visualization and assignment tracking bridge communication with operational execution. Logistics providers integrate these capabilities directly into warehouse management systems through API-first architectures.
Messaging dominates current procurement volumes; employee survey modules are expanding most quickly as CSRD alignment pressures intensify.
Use Case:
Customer maturity and organizational resilience priorities shape investment concentration across functional applications.
- Employee Engagement:Culture-building and recognition platforms target retention in competitive labor markets. These deployments command the widest footprint across desk and deskless worker populations in hospitality and retail sectors.
- Crisis Management:Emergency alert and business continuity systems harden operational resilience against supply chain disruptions and natural disasters. German industrial conglomerates prioritize these capabilities following recent regulatory emphasis on critical infrastructure protection.
- Internal Marketing:Brand alignment and change communication tools support merger integration and strategic transformation. Large corporations deploy these solutions to maintain cultural coherence across acquired subsidiaries.
- Knowledge Sharing:Expert location and documentation platforms accelerate onboarding and reduce repeat inquiry volume. Professional services firms in the United States leverage these systems to capture retiring partner expertise.
- Remote Collaboration:Virtual workspace and asynchronous coordination tools sustain productivity across distributed teams. Technology sector adoption remains highest, though manufacturing and healthcare are accelerating deployment.
Employee engagement retains the largest installed base; crisis management functionality shows the steepest expansion trajectory as resilience protocols harden.
Customer Type:
Organizational scale dictates feature depth, integration complexity, and pricing sensitivity in vendor selection processes.
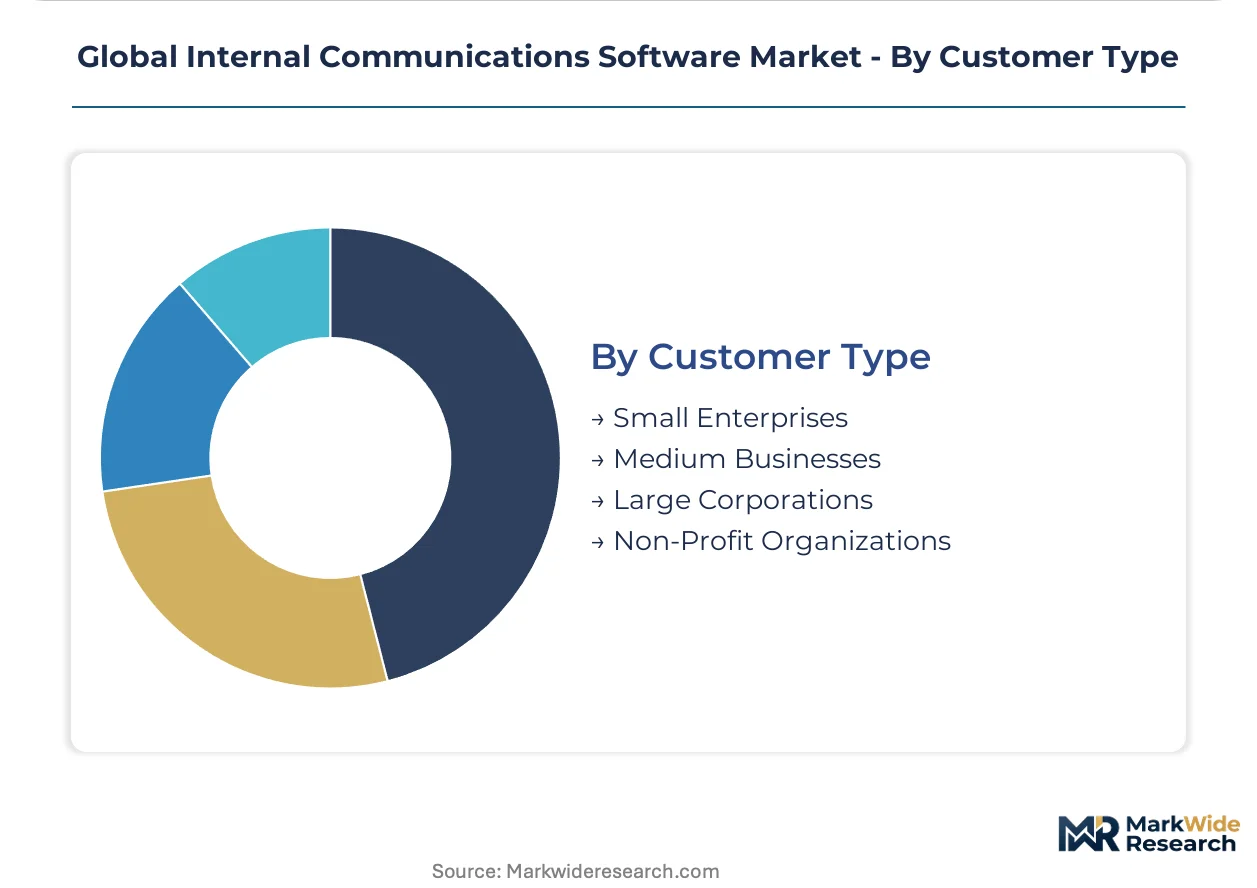
- Small Enterprises:Organizations under 100 employees prioritize out-of-box functionality and minimal IT overhead. These buyers favor bundled suites from major cloud providers over specialized point solutions.
- Medium Businesses:Mid-market companies require configurability without enterprise-grade implementation timelines. Manufacturing SMEs in India select modular microservices architectures to scale communications alongside PLI scheme production expansion.
- Large Corporations:Multinational enterprises demand global data residency options and extensive API ecosystems. These organizations negotiate custom security attestations and dedicated customer success resources.
- Non-Profit Organizations:Mission-driven entities seek donated or discounted licensing with volunteer coordination features. Grant compliance reporting and donor communication integration differentiate vendor suitability.
Large corporations account for the greatest revenue concentration today; medium businesses are expanding procurement most rapidly as modular pricing reduces entry barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Internal communications software emerged from Silicon Valley's enterprise technology corridor before diffusing through European industrial centers and Asia-Pacific manufacturing hubs. Germany's automotive and machinery conglomerates pioneered workforce connectivity mandates that shaped vendor product roadmaps. India's services economy and Japan's precision manufacturing sectors now drive modular deployment architectures.
United States
HIPAA-covered health systems and SEC-regulated financial institutions demand auditable messaging with automated archiving. The FDA's digital health guidance pushes clinical communication vendors toward interoperability with electronic health record systems. Boston's hospital consortiums and New York's banking headquarters concentrate procurement authority for North American enterprise deployments.
Germany
Industrial conglomerates prioritize workforce connectivity across distributed engineering and production sites. The BSI's IT security catalog and GDPR's cross-border data governance fragment vendor architectures with strict localization requirements. Bavaria's automotive clusters and North Rhine-Westphalia's machinery headquarters drive demand for crisis management and shift-coordination modules.
United Kingdom
Professional services firms and fintech operators require knowledge-sharing platforms with retiring partner expertise capture. The Financial Conduct Authority's operational resilience rules mandate business continuity communication systems. London's insurance district and Edinburgh's asset management centers anchor financial services adoption patterns.
India
PLI scheme beneficiaries across electronics and pharmaceutical manufacturing need multilingual plant-floor to headquarters coordination. The RBI's data localization directives and TRAI's cloud security frameworks shape vendor compliance engineering. Gujarat's chemical corridors and Karnataka's technology parks concentrate medium-business procurement for modular microservices architectures.
Japan
Manufacturing headquarters deploy video infrastructure for multilingual coordination across PLI-linked Southeast Asian facilities. METI's cybersecurity supply chain guidelines and PMDA's digital health governance extend procurement documentation requirements. Nagoya's automotive engineering centers and Osaka's precision equipment clusters drive mobile-first engagement tool specifications.
Global Internal Communications Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integration depth and compliance certification vectors. The market structures around hyperscale suite bundlers, specialized employee experience platforms, and API-first developer tools. Three archetypes dominate: enterprise suite anchors, vertical specialists, and modular component vendors. Consolidation proceeds through strategic partnerships with legacy ERP providers and geographic expansion into underpenetrated manufacturing corridors.
Within the enterprise suite tier, Microsoft Teams and Google Workspace exemplify platform bundling strategies that compress standalone vendor margins. Slack occupies a position among developer-centric tools that reduce IT dependency through customization ecosystems. Staffbase represents the vertical specialist archetype with dedicated employee-experience layers for distributed and deskless workforces.
| Leading Market Players |
|---|
| Monday.com |
| Staffbase |
| Slack |
| ContactMonkey |
| Connecteam |
| Microsoft Teams |
| Zoom |
| eXo Platform |
| Google Workspace |
| Others |
Supply & Pricing Matrix
Large enterprise procurement committees concentrate buying power across North America and Western Europe, forcing vendors toward subscription-based SaaS tiers with volume-scaled discounts. Microsoft Teams and Google Workspace bundle communications into productivity suites, compressing standalone pricing power and reshaping how specialized vendors structure their go-to-market economics.
Pricing Analysis
Seat-based subscription tiers with enterprise volume discounts dominate vendor revenue models. Price differentiation rests on API ecosystem breadth and ISO 27001 certification status. Cost compression in the mid-market tier is intensifying because hyperscaler bundling erodes standalone value propositions. Small enterprises exhibit highest price sensitivity, while defense contractors and HIPAA-covered health systems accept premium pricing for data sovereignty guarantees.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure now mandate multi-hyperscaler qualification across enterprise procurement teams. Vendor platforms draw from data center capacity concentrated in the United States, Ireland, and Singapore. Dependencies on NVIDIA GPU clusters for AI inference, TLS certificate authorities for encryption, and identity federation services create layered supply exposure. Single-source vulnerability in GPU allocation for generative AI features threatens product roadmap execution. Distribution runs through direct enterprise sales with systems integrator overlay for complex ERP integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The internal communications software market functions as a stable compounder, with regulatory compliance mandates and hybrid work permanence generating predictable replacement cycles. Vendor consolidation and platform bundling create defensive moats for established players while constraining pricing power for challengers.
For Market Incumbents: Anchor market position through vertical integration into identity management and security certification stacks. Deepen API ecosystem investment to reduce customer switching costs. Defend against hyperscaler bundling by emphasizing sector-specific compliance expertise—particularly EU AI Act documentation and HIPAA technical safeguards—that suite vendors cannot replicate at equivalent depth. For New Entrants and Emerging Players: AI-native workflow automation serves as the most penetrable technology-first wedge. Target frontline workforce segments in India's PLI scheme manufacturing corridors and Brazil's retail chains, where mobile-first engagement tools remain underserved. Pursue land-and-expand tactics through departmental pilot programs rather than enterprise-wide procurement contests. For Investors and Strategic Acquirers: Enterprise software conglomerates represent the most active acquirer category in this space, seeking employee-experience platform fill-ins. The market supports long-duration holding periods given recurring revenue visibility and embedded switching costs. Monitor CSRD disclosure mandate enforcement intensity as the critical inflection signal—accelerated sustainability reporting requirements will drive replacement demand for workforce analytics capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architecture enables embedding into SAP and Oracle ERP environments without middleware. |
| Acquisition of Specialist Firm | Vertical compliance expertise in HIPAA or EU AI Act documentation accelerates enterprise sales cycles. |
| Geographic Expansion | Local data residency in Germany and India satisfies BSI and RBI localization mandates. |
| Product Launch | Microservices-based crisis management modules address German critical infrastructure protection requirements. |
| Strategic Partnership | Systems integrator alliances reduce implementation friction for legacy ERP connectivity projects. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists. Secondary validation draws from SEC filings, hyperscaler capex disclosures, App Annie mobile engagement data, and EU regulatory filings. Bottom-up deployment estimates triangulate against top-down enterprise software spending benchmarks.
Rate-of-change decomposition separates baseline SaaS replacement velocity from incremental AI feature adoption and regulatory-driven upgrade cycles. Segmentation dimensions include deployment architecture, organization size, vertical industry, integration complexity, and regional compliance intensity. CAGRs derive from fitted growth curves adjusted for saturation effects in mature markets. Forecast inputs incorporate EU AI Act implementation timelines and PLI scheme manufacturing expansion trajectories.
The model holds under stable regulatory enforcement and sustained hybrid work patterns; deviation in hyperscaler bundling intensity or cross-border data governance fragmentation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Data Compression Software Market
Software & Services
Intelligent Enterprise Data Capture Software Market
Software & Services
Hypervisor Market
Software & Services
API Testing Market
Software & Services
Global Quoting Software Market
Software & Services
Online Lottery Software Market
Software & Services
Global Testing Software Market
Software & Services
ID Photo Software Market
Software & Services
Global Sales Engagement Platform Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Audio Editing Software Market
Software & Services
Saas-Based SCM Market
Software & Services
Global Business Software Market
Software & Services
Newsroom Software Market
Software & Services
Web Scraping Software Market
Software & Services
Japan Qualitative Data Analysis Software Market