
 India Cloud Computing Market | 2026-2036
India Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
India Cloud Computing Market Insights
The gap between premium managed cloud services and bare-metal commodity infrastructure is rebalancing as Indian enterprises demand outcome-based contracts over raw compute pricing. Amazon Web Services leverages its Mumbai and Hyderabad regions to anchor enterprise workloads requiring low-latency data sovereignty. Microsoft Azure competes through deep integration with Office 365 and Dynamics deployments already entrenched in large Indian corporations. Tata Consultancy Services differentiates by wrapping managed services around hyperscaler infrastructure, capturing margin pools that pure-play providers cannot access.
India cloud computing encompasses the delivery of on-demand computing resources—including servers, storage, databases, networking, software, and analytics—over the internet with metered service models, multi-tenancy architectures, and API-driven orchestration layers that abstract physical infrastructure from end-user applications. Its primary purpose is to replace capital-intensive on-premise IT estates with elastic, operationally efficient alternatives that scale with transaction volumes and seasonal demand patterns. Public cloud deployments lead in absolute spend as startups and SMEs prioritize speed-to-market over control, while hybrid cloud architectures capture the fastest expansion as legacy enterprises in banking and manufacturing pursue phased migration strategies. SaaS within the service model dimension sustains the largest revenue base due to horizontal applications like CRM and ERP, though IaaS generates superior growth rates from AI/ML training workloads and containerized microservices architectures.
India's cloud market operates under layered regulatory oversight from RBI for financial sector cloud usage, BIS for data center standards and encryption protocols, and the Digital Personal Data Protection Act for cross-border data flows and localization mandates. RBI's master direction on IT outsourcing compels banks to maintain audit trails and business continuity plans that favor domestic cloud regions and certified service providers. Stakeholders must monitor how the Data Protection Board's forthcoming localization rules reshape multi-cloud routing decisions and vendor qualification criteria.

Market Dynamics
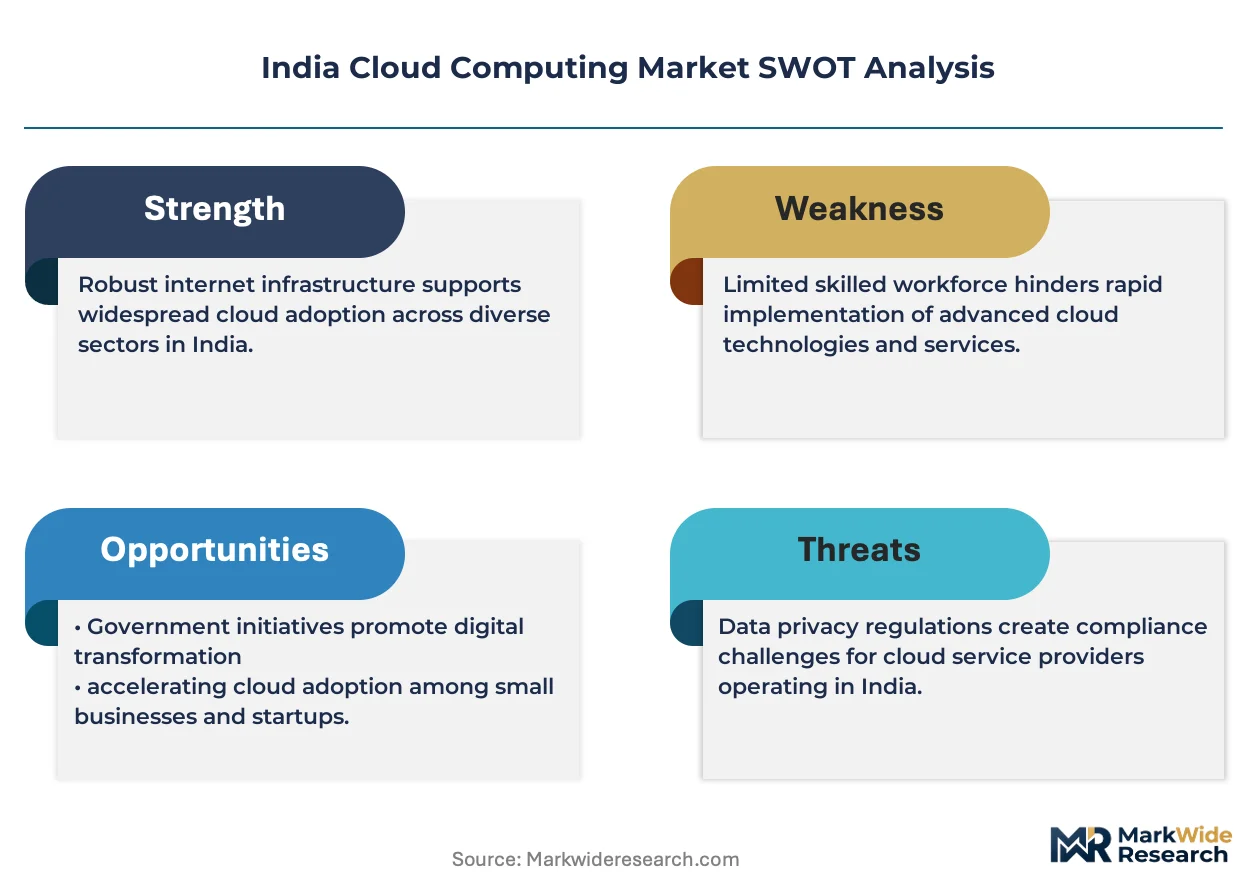
RBI's 2023 IT outsourcing guidelines are compressing vendor qualification timelines and forcing banks into domestic cloud region commitments, reshaping procurement patterns across Mumbai's financial district.
Growth Catalysts
- Data Localization Mandates:The Digital Personal Data Protection Act compels enterprises to route sensitive workloads through domestic data centers, accelerating demand for Mumbai and Hyderabad cloud regions.
- AI/ML Training Workloads:Containerized microservices architectures and GPU-intensive model training are pulling hyperscaler infrastructure spend from traditional on-premise HPC clusters.
- PLI Scheme Incentives:The government's production-linked incentive scheme for IT hardware manufacturing is reducing server equipment costs for domestic cloud providers.
Market Restraints
- Cross-Border Data Friction:Uncertainty around the Data Protection Board's forthcoming localization rules is freezing multi-cloud routing decisions for multinational corporations.
- Power Infrastructure Bottlenecks:Tamil Nadu and Karnataka grid instability is constraining data center expansion timelines beyond Mumbai and NCR clusters.
- Encryption Standard Fragmentation:BIS-mandated cipher suites diverge from global ISO protocols, forcing vendors to maintain dual compliance stacks.
Strategic Opportunities
- Tier-2 City Penetration:Pune, Chennai, and Ahmedabad enterprise hubs remain underserved by managed service providers relative to Mumbai and Bengaluru saturation.
- Edge-Cloud Convergence:5G network slicing and micro data centers are enabling latency-sensitive manufacturing IoT applications in Gujarat industrial corridors.
- Regulatory Sandbox Participation:RBI's cloud sandbox framework allows fintechs to test sovereign cloud architectures with relaxed compliance timelines.
Industry Challenges
- Multi-Cloud Orchestration Expertise:Shortage of Kubernetes-certified engineers and FinOps practitioners is throttling enterprise migration velocity.
- Legacy Mainframe Integration:Core banking systems running on COBOL architectures require expensive middleware layers to interface with API-driven cloud workloads.
- Audit Trail Standardization:RBI-mandated transaction logging formats conflict with hyperscaler native tooling, forcing custom SIEM development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cloud Computing Market |
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $152.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multicloud Service Model: IaaS, PaaS, SaaS, BaaS End User: SMEs, Large Enterprises, Government, Startups Solution: Data Storage, Disaster Recovery, Cloud Security, Analytics |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Tata Consultancy Services, Infosys, Wipro, HCLTech, Tech Mahindra, Bharti Airtel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cloud Computing Market Trends and Innovations
Container orchestration and sovereign infrastructure requirements are bifurcating vendor strategies between global hyperscaler partnerships and domestic captive cloud builds.
Serverless computing architectures are eliminating infrastructure management overhead for event-driven applications. Indian fintech startups and insurtech platforms are adopting function-as-a-service models at three times the pace of traditional lift-and-shift migrations. This consumption pattern is expanding into retail and logistics verticals previously locked into reserved instance contracts.
RBI's master direction on IT outsourcing now mandates annual penetration testing and incident reporting thresholds for all cloud-hosted banking workloads. The regulation has spawned a cottage industry of certified cloud auditors and domestic security operations centers. Tier-1 banks are responding by consolidating vendor relationships to reduce compliance surface area.
Enterprise buyers are unbundling managed services from infrastructure contracts, directly procuring compute and storage while sourcing operations separately. Systems integrators and niche DevOps consultancies are capturing margin pools that hyperscalers previously monopolized. This disaggregation is most pronounced among NBFCs and mid-market manufacturing firms in the NCR industrial belt.
India Cloud Computing Market Segmentation
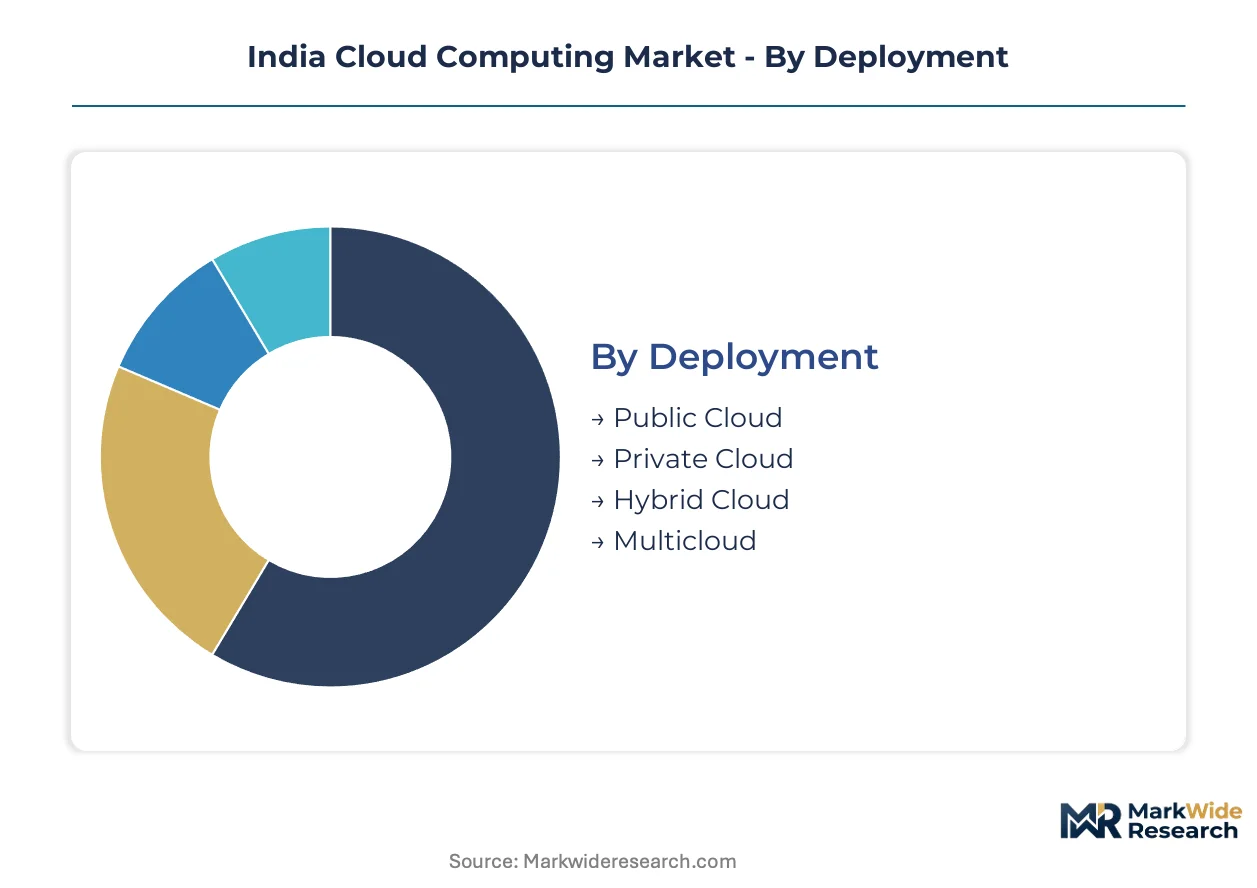
Cloud infrastructure procurement in India fragments across four intersecting dimensions. Deployment architecture determines sovereignty compliance and latency profiles. Service model selection reflects internal engineering maturity and capital constraints.
Deployment:
Customization intensity spans from fully managed public environments to sovereign private builds, with hybrid architectures occupying the middle ground where legacy integration demands flexibility.
- Public Cloud:Shared infrastructure pools deliver elastic compute and storage through metered consumption models. Mumbai's financial district and Bengaluru's technology corridor concentrate procurement as startups and digital-native enterprises prioritize speed over control.
- Private Cloud:Dedicated single-tenant environments run on-premises or in colocation facilities with full administrative isolation. Large banks and NBFCs mandate these deployments under RBI audit trail requirements, driving captive data center builds in Hyderabad and Chennai.
- Hybrid Cloud:Orchestrated workload portability between private infrastructure and public hyperscaler regions. Manufacturing enterprises in Gujarat and Maharashtra adopt this architecture to keep sensitive ERP data on-premise while bursting analytics workloads to cloud.
- Multicloud:Deliberate distribution across two or more hyperscaler platforms to mitigate vendor lock-in and optimize price-performance by workload type. Sophisticated enterprises with mature FinOps functions deploy this strategy, though Kubernetes orchestration expertise shortages constrain adoption velocity.
Most installed capacity flows through Public Cloud deployments. Expansion is steepest in Hybrid Cloud as legacy enterprises pursue phased migration strategies.
Service Model:
Margin structure descends from infrastructure abstraction layers toward application-level subscriptions, with platform services capturing developer productivity premiums.
- IaaS:Raw compute, storage, and networking resources provisioned through APIs and orchestration layers. GPU-intensive AI/ML training workloads in Bengaluru's insurtech cluster and Mumbai's quantitative trading desks pull spend from traditional on-premise HPC infrastructure.
- PaaS:Managed runtime environments, databases, and middleware abstracting infrastructure management from application deployment. Developer teams in Pune's automotive software hubs and Chennai's SaaS factories adopt container platforms and serverless functions to accelerate release cycles.
- SaaS:Fully managed application software delivered through web browsers and mobile clients with subscription pricing. Horizontal CRM and ERP systems dominate procurement in NCR's professional services corridor, while vertical solutions penetrate specialty retail and logistics.
- BaaS:Backend services including authentication, push notifications, and database synchronization exposed through SDKs. Mobile-first fintech startups in Mumbai and gaming studios in Hyderabad leverage these capabilities to compress time-to-market for consumer applications.
Revenue concentration sits with SaaS subscriptions across horizontal business applications. IaaS generates the steepest expansion trajectory from AI/ML training and containerized microservices adoption.
End User:
Procurement sophistication correlates with organizational scale, from consumption-based experimentation at small entities through compliance-governed enterprise frameworks.
- SMEs:Mid-market firms with limited IT staff favor managed services and SaaS bundles over infrastructure complexity. Ahmedabad's diamond trading houses and Coimbatore's textile exporters prioritize operational expenditure predictability.
- Large Enterprises:Conglomerates and multinational subsidiaries operate multi-year cloud transformation programs with dedicated centers of excellence. Mumbai-headquartered conglomerates in metals, cement, and pharmaceuticals maintain hybrid architectures bridging decades-old ERP investments.
- Government:Central and state ministries procure through MeitY-empaneled cloud service providers with mandatory data localization. Smart city projects in Surat and Indore and digital health records initiatives drive sovereign cloud demand.
- Startups:Venture-backed technology companies consume cloud-native architectures from inception, eschewing capital expenditure entirely. Bengaluru's SaaS unicorns and Mumbai's fintech scale-ups represent the most intensive per-employee cloud spend cohort.
Transaction volume concentrates in Large Enterprise procurement cycles. Startups deliver the fastest customer acquisition velocity for hyperscaler marketplaces.
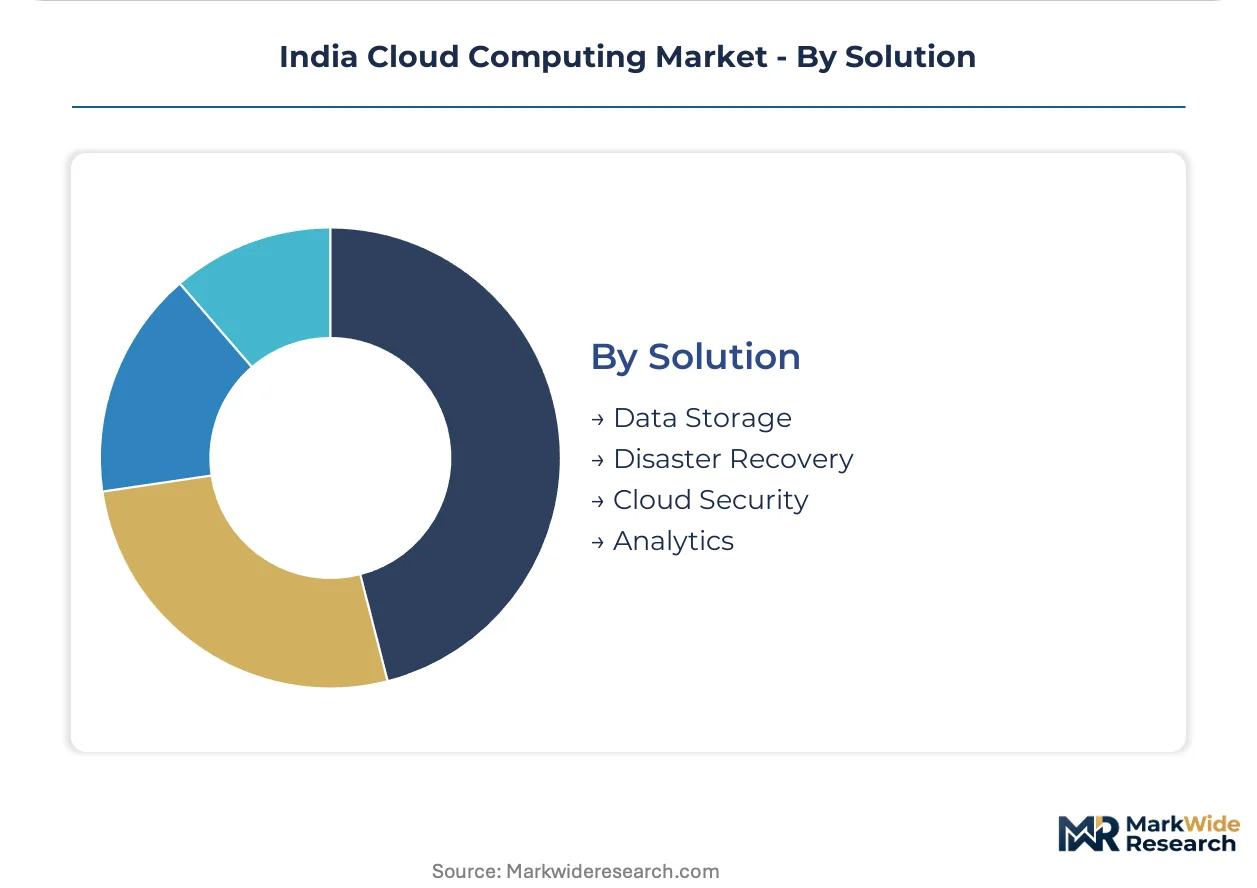
Solution:
Functional specialization ranges from foundational storage primitives toward integrated security and intelligence layers commanding premium pricing.
- Data Storage:Object, block, and file storage services with tiered durability and retrieval latency guarantees. Media production houses in Mumbai and genomics research institutes in Hyderabad drive petabyte-scale object storage consumption.
- Disaster Recovery:Automated backup, replication, and failover orchestration ensuring business continuity against infrastructure failures. RBI-mandated recovery time objectives for systemically important banks mandate these deployments across domestic availability zones.
- Cloud Security:Identity management, encryption key services, threat detection, and compliance monitoring delivered as native platform capabilities. BIS-mandated cipher suite divergence from global standards forces vendors to maintain dual compliance stacks for Indian deployments.
- Analytics:Data warehouses, lakehouse architectures, and business intelligence platforms processing structured and unstructured datasets. Retail chains in Delhi NCR and FMCG distributors deploy these solutions for demand forecasting and supply chain optimization.
Most provisioned capacity serves Data Storage workloads. Analytics solutions demonstrate the steepest growth curve as enterprises operationalize machine learning pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure talent concentrates in Mumbai's financial district and Bengaluru's technology corridor, where certified engineers and FinOps practitioners anchor procurement decisions for domestic enterprises.
Maharashtra
Mumbai's banking sector drives sovereign cloud demand under RBI's 2023 IT outsourcing guidelines. The state's data center clusters in Navi Mumbai and Pune host hyperscaler availability zones serving NBFCs and insurance conglomerates. Thane's emerging fintech hub attracts edge computing deployments for low-latency trading applications.
Karnataka
Bengaluru's SaaS unicorns and insurtech scale-ups consume GPU-intensive AI training workloads through containerized microservices. The state's software engineering density supports multi-cloud orchestration expertise scarce elsewhere. Mysuru's secondary campus corridors are absorbing overflow data center capacity as Bengaluru land costs escalate.
Telangana
Hyderabad's pharmaceutical and genomics research institutes pull petabyte-scale object storage consumption. The state's Electronics Policy incentivizes domestic cloud hardware manufacturing under PLI scheme frameworks. Cyberabad's IT corridor hosts Microsoft Azure and Amazon Web Services regions serving central government digital initiatives.
Gujarat
Ahmedabad's diamond trading houses and Surat's textile exporters prioritize operational expenditure predictability through managed SaaS bundles. The state's industrial corridors in Vadodara and Rajkot deploy edge-cloud convergence for manufacturing IoT applications. GIFT City's international financial services center mandates domestic cloud residency for regulatory compliance.
Tamil Nadu
Chennai's automotive software hubs adopt platform-as-a-service models to accelerate release cycles for connected vehicle programs. The state's SaaS factories serve Southeast Asian markets through API-driven cloud architectures. Grid instability in rural districts constrains data center expansion beyond Chennai's enterprise zones.
India Cloud Computing Market Competitive Landscape
Top-tier vendors anchor hyperscale infrastructure provision, while systems integrators capture margin pools through managed service wrappers. The market exhibits tiered concentration with global cloud providers commanding compute pricing power and domestic IT services firms differentiating through compliance expertise. Three archetypes dominate: hyperscalers with sovereign region investments, national champions with captive data center builds, and specialist DevOps consultancies. Competitive moves center on multi-cloud certification programs and strategic partnerships with BIS-empaneled security auditors.
Within the hyperscaler tier, Amazon Web Services, Microsoft Azure, and Google Cloud exemplify infrastructure-first positioning with Mumbai and Hyderabad region anchoring. These entities represent the capital-intensive end of competitive dynamics, while Tata Consultancy Services and Infosys occupy the systems integrator archetype wrapping managed services around third-party infrastructure. Wipro and HCLTech sit within the same tier, consolidating vendor relationships to reduce compliance surface area for banking clients.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Tata Consultancy Services |
| Infosys |
| Wipro |
| HCLTech |
| Tech Mahindra |
| Bharti Airtel |
| Others |
Pricing and Supply Chain Analysis
Containerization and serverless computing adoption across Indian enterprises simultaneously compresses infrastructure unit economics and concentrates procurement leverage among hyperscalers with domestic region investments. This technology shift rewards vendors achieving scale in Mumbai and Hyderabad data center clusters while squeezing margins for undifferentiated managed service providers.
Pricing Analysis
Bundled managed services versus unbundled raw infrastructure splits procurement patterns across buyer archetypes. Three-tier pricing structure across premium compliance-certified, standard enterprise-grade, and economy developer tiers reflects RBI audit trail requirements and BIS encryption mandates. Cost compression in the economy tier intensifies as hyperscalers absorb commodity compute pricing through reserved instance commitments. NBFCs and mid-market manufacturers exhibit highest price sensitivity, while systemically important banks prioritize sovereign certification over unit cost.
Supply Chain Analysis
BIS and RBI certification gating restricts qualified server equipment sourcing to Taiwan, China, and South Korea manufacturing bases. Domestic cloud providers draw from NVIDIA GPU accelerators, Intel Xeon processors, and Samsung NAND storage components. Single-source vulnerability concentrates in advanced semiconductor lithography equipment. Distribution runs through Mumbai and Chennai port-of-entry logistics corridors into Navi Mumbai and Hyderabad data center buildouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where RBI's 2023 IT outsourcing guidelines and the Digital Personal Data Protection Act continuously expand compliant-addressable demand.
For Market Incumbents: Extend sovereign cloud region footprints into underserved Tier-2 industrial corridors before domestic challengers achieve BIS certification. Consolidate vendor relationships to reduce compliance audit surface area. Anchor capacity additions in Gujarat and Tamil Nadu manufacturing belts where edge-cloud convergence accelerates. For New Entrants and Emerging Players: Enter via RBI's regulatory sandbox framework to test sovereign architectures with relaxed compliance timelines. Target Pune and Ahmedabad enterprise hubs where managed service provider saturation lags Mumbai and Bengaluru. Pursue DevOps consultancy positioning to capture margin pools from unbundling infrastructure and operations contracts. For Investors and Strategic Acquirers: Roll-up economics work for certified cloud auditors and domestic security operations centers because RBI-mandated penetration testing requirements fragment the compliance services landscape. Long-term viability hinges on Data Protection Board localization rule finalization. Monitor multi-cloud orchestration talent scarcity as inflection indicator for managed services acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deepens Microsoft Azure and Office 365 entrenchment across Mumbai-headquartered conglomerates. |
| Strategic Partnership | Links hyperscaler infrastructure with TCS managed services to capture RBI-compliant banking workloads. |
| Geographic Expansion | Extends AWS Mumbai and Hyderabad regions into Chennai and Pune enterprise zones. |
| Acquisition of Specialist Firm | Consolidates Kubernetes-certified DevOps consultancies scarce across the analysis window. |
| Product Launch | Introduces sovereign cloud instances meeting BIS-mandated cipher suite divergence requirements. |
Research Methodology
Coverage spans Maharashtra, Karnataka, Telangana, Gujarat, and Tamil Nadu, with primary inputs from each regional cluster combining interviews with cloud architects, IT procurement officers at banks and NBFCs, platform engineers at hyperscaler regions, DevOps consultants, and data center operations managers. Secondary validation draws from RBI master direction filings, BIS standards publications, hyperscaler capex disclosures, and MeitY empanelment records. Bottom-up and top-down triangulation cross-checks regional capacity buildouts against enterprise procurement survey data.
Rate-of-change decomposition separates infrastructure spend growth from service model mix shifts across the projection horizon. Segmentation dimensions modeled include deployment architecture, service model abstraction layer, organization scale tier, vertical regulatory intensity, and regional data center proximity. CAGRs derive from capacity utilization trajectories at hyperscaler availability zones and enterprise migration velocity surveys. AI/ML training workload intensity and containerized microservices adoption serve as cloud-native demand proxies.
Inputs from RBI compliance filing databases and hyperscaler regional expansion announcements were available through the study window; gaps in Data Protection Board draft rule finalization introduce uncertainty bands around multi-cloud routing forecasts. Forecasts reflect assumptions on localization mandate enforcement timing and grid infrastructure stability in Tamil Nadu and Karnataka. A model refresh is warranted upon material change in Data Protection Board cross-border data flow rulings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Healthcare Cloud Infrastructure Market
Cloud Computing
Global Server Virtualization Market
Cloud Computing
Cloud Services Brokerage (CSB) Market
Cloud Computing
North America Professional Cloud Services Market
Cloud Computing
Brazil Cloud Computing Market
Cloud Computing
Saudi Arabia Cloud Computing Market
Cloud Computing
Public Cloud Application Infrastructure Services Market
Cloud Computing
Cloud ELN Service Market
Cloud Computing
Web Scale IT Market
Cloud Computing
Global Cloud Collaboration Market
Cloud Computing
Italy Cloud Computing Market
Cloud Computing
Philippines ICT Market
Cloud Computing
Israel Cloud Computing Market
Cloud Computing
Global Cloud Based ITSM Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Cloud Services Market