
 United States Customer Technical Support Services Market | 2026-2036
United States Customer Technical Support Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Customer Technical Support Services Market Analytics
Enterprise-grade SLA specifications is unwinding legacy break-fix models into proactive, outcome-contracted support relationships. Cognizant leverages its healthcare and financial services vertical depth to anchor premium technical support engagements for regulated industries. TTEC sustains a distributed agent model that competes on cost arbitrage while maintaining domestic compliance footprints. TaskUs specializes in high-velocity, digitally native brand support, occupying a distinct tier between boutique agencies and legacy BPO giants.
Customer technical support services encompass the remote diagnosis, resolution, and escalation of hardware and software failures through voice, digital, and automated channels, typically governed by response-time thresholds measured in minutes for critical infrastructure downtime. The primary commercial purpose is to minimize customer churn and lifetime value erosion by restoring productive use of technology products. Cloud-based delivery models now lead segment growth as enterprises migrate from on-premise call centers to elastic, API-integrated support platforms; outsourced arrangements capture the deepest margin pools through multi-year, volume-committed contracts. Phone support retains the largest revenue base among service types, though live chat and social media support are expanding fastest among millennial and Gen Z consumer segments.
FCC net neutrality rulings and state-level biometric privacy laws, particularly Illinois BIPA and California CCPA amendments, are reshaping how providers record, store, and analyze customer interactions. HIPAA compliance requirements extend into technical support workflows for healthcare IT vendors, constraining vendor selection to HITRUST-certified operators. Stakeholders must weigh the capital requirements of AI agent deployment against the regulatory exposure of automated decision-making in regulated verticals.
Market Dynamics
AI-assisted ticketing platforms are decomposing legacy break-fix support models into predictive, outcome-governed relationships across enterprise SaaS and cloud infrastructure verticals.
Growth Catalysts
- HIPAA compliance mandates:Healthcare IT vendors require HITRUST-certified support operators, expanding contract values for specialized providers serving medical device and EHR software segments.
- California CCPA amendments:Biometric data handling restrictions force providers to rebuild recording and analytics infrastructure, creating upgrade cycles for compliant interaction platforms.
- Texas Austin-Dallas corridor:Enterprise software vendor clustering concentrates demand for technical success operations, anchoring regional service center expansion and specialized talent pools.
Market Restraints
- Agent wage compression:Domestic labor costs for US-based technical support agents constrain margin expansion against offshore alternatives, pressuring hybrid delivery models.
- FCC net neutrality uncertainty:Connectivity prioritization rulings create operational risk for cloud-delivered support platforms dependent on consistent bandwidth allocation.
- AI decision-making liability:Automated escalation protocols in regulated verticals expose providers to compliance violations when algorithmic routing bypasses required human oversight.
Strategic Opportunities
- Illinois BIPA enforcement:Biometric privacy litigation creates demand for voice authentication alternatives, opening markets for behavioral analytics and tokenized identity verification tools.
- API-integrated support platforms:Elastic cloud architectures enable consumption-based pricing models that align vendor revenue with actual customer issue resolution throughput.
- Federal cloud security mandates:FedRAMP and StateRAMP certification requirements filter competition, rewarding providers with pre-certified infrastructure for government and defense contractor segments.
Industry Challenges
- HITRUST certification timelines:Healthcare support operators face 12-18 month assessment cycles that delay market entry and strain working capital during compliance preparation.
- Legacy CRM integration:Enterprise clients demand seamless API connections to decades-old ticketing systems, requiring costly custom middleware development for each major deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Customer Technical Support Services Market |
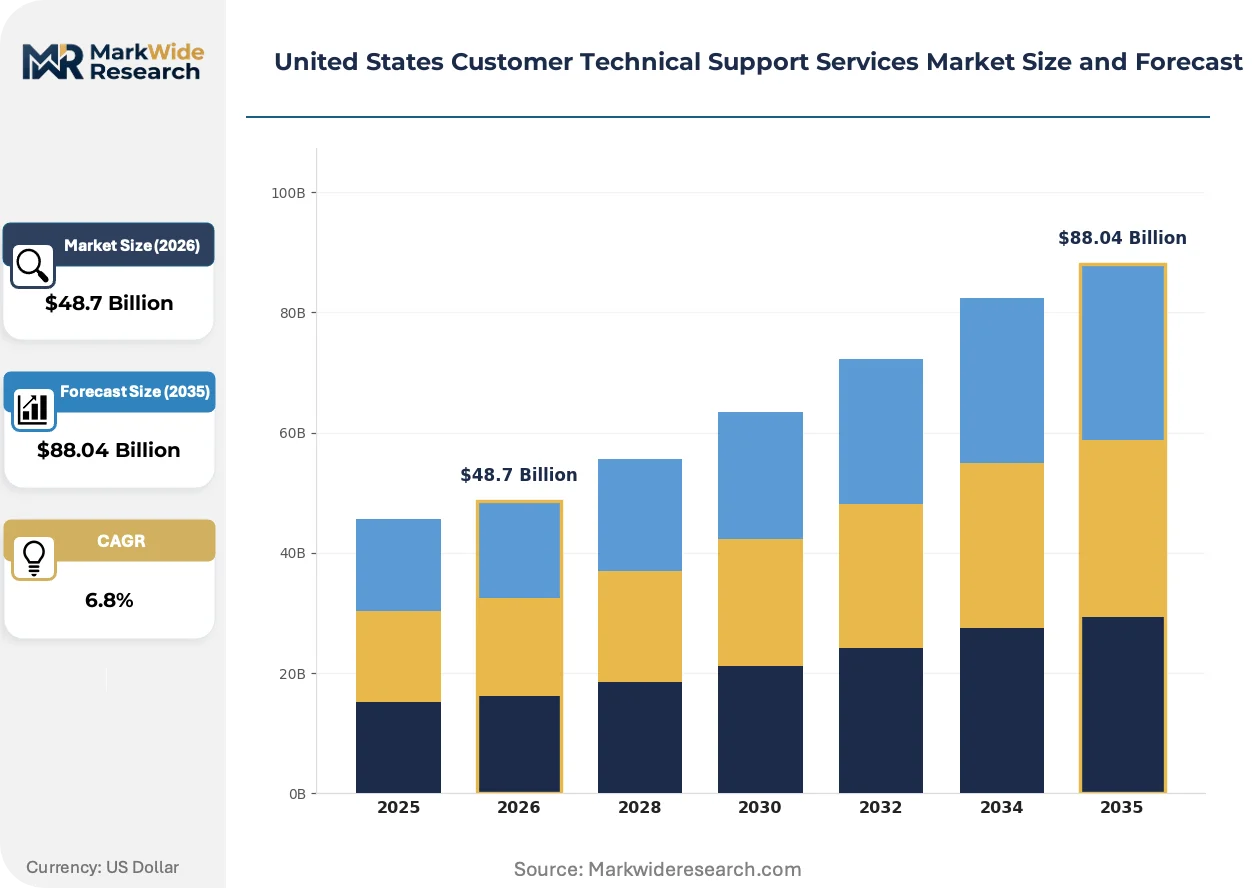
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Phone Support, Email Support, Live Chat, Social Media Support Industry Vertical: Information Technology, Telecommunications, Consumer Electronics, E-Commerce Delivery Model: On-Premise, Cloud-Based, Hybrid, Outsourced Customer Segment: Small Businesses, Enterprises, Startups, Government Agencies |
| Companies Covered | TaskUs, WOW24-7, Teleperformance, Cognizant, Foundever, Concentrix, Helpware CX, Genpact, TTEC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Customer Technical Support Services Market Evolving Landscape
Service delivery economics are compressing as automated channels capture routine incidents while human agents migrate toward complex escalation and customer success functions.
Generative AI copilots are decomposing tier-1 support workflows by surfacing knowledge base articles, drafting response templates, and pre-populating case notes before human agent handoff. Mid-market SaaS vendors deploy these tools fastest, cutting average handle times by enabling agents to resolve common authentication and configuration issues without scripted searches. The structural consequence is collapsing entry-level headcount requirements while raising technical proficiency thresholds for remaining human roles.
Illinois BIPA and California CCPA amendments are reshaping interaction recording practices by requiring explicit biometric consent, encrypted storage, and deletion protocols for voiceprints and facial recognition data. Support providers serving national accounts must architect state-specific data routing to isolate Illinois and California interactions from standard processing pipelines. Healthcare and financial services verticals face the steepest compliance burdens, driving consolidation toward operators with pre-built privacy infrastructure.
Enterprise procurement of technical support is fragmenting from monolithic multi-year contracts toward modular, outcome-measured engagements with embedded SLA penalties. Buyers unbundle phone, chat, and automated channels to optimize cost-to-resolution by incident type, pressuring providers to price each channel independently. This pattern concentrates among digitally native brands in California and Texas, where finance and operations teams demand granular visibility into support spend efficiency.
United States Customer Technical Support Services Market Segmentation
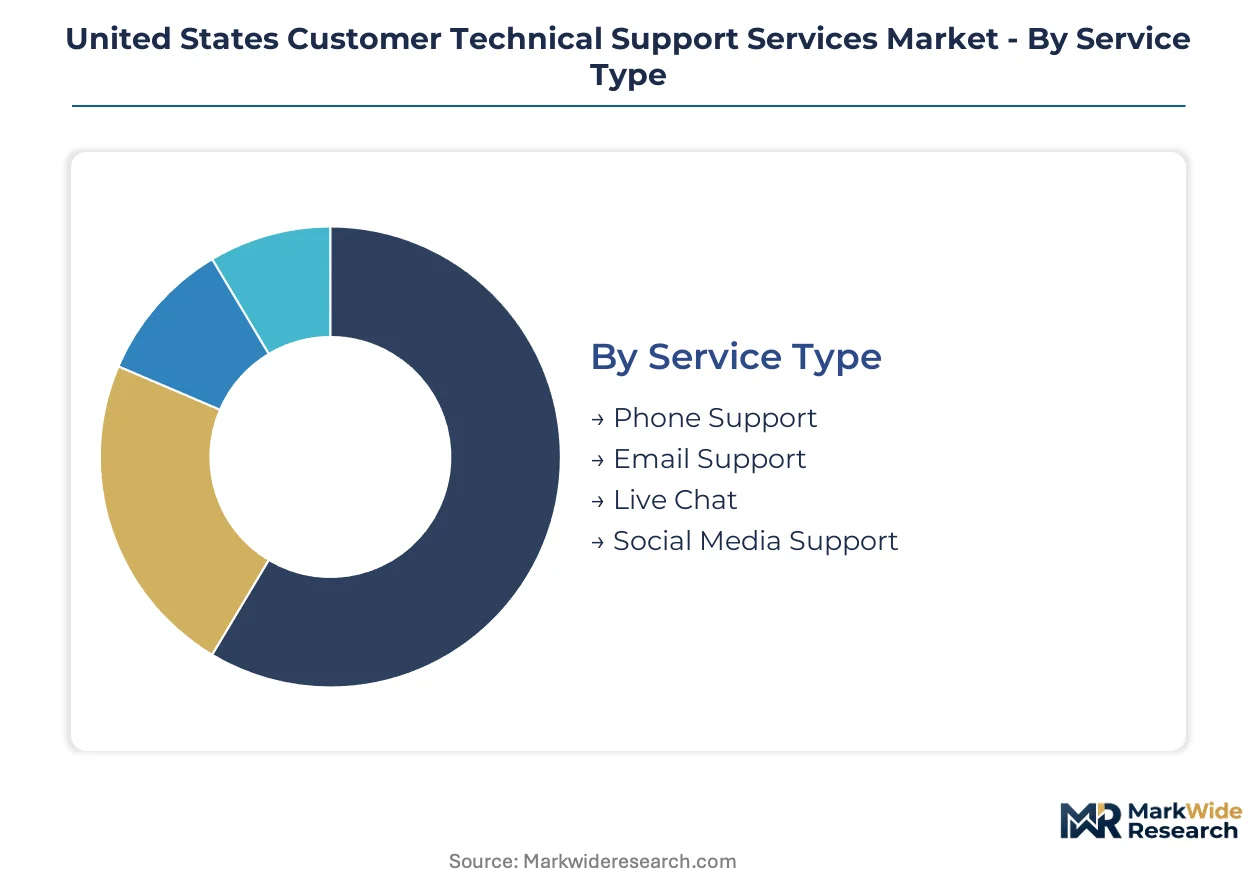
Technical support providers structure their service portfolios around channel economics and compliance requirements. Segment boundaries determine pricing architecture, talent deployment, and infrastructure investment priorities across the US market.
Service Type:
Channel mix determines cost-to-resolution profiles and dictates how providers allocate agent training and automation capital.
- Phone Support:Voice-based resolution retains the largest revenue base. Complex enterprise SaaS and healthcare IT workflows in California and Texas cluster here due to HIPAA-mandated human oversight requirements and high-stakes downtime scenarios.
- Live Chat:Asynchronous text interfaces enable concurrent session handling. Millennial and Gen Z consumer segments in Austin-Dallas and Silicon Valley drive fastest expansion, with authentication and configuration queries dominating volume.
- Email Support:Ticket-based asynchronous resolution handles non-urgent documentation and billing disputes. Lower cost structure attracts mid-market SaaS vendors optimizing support spend efficiency.
- Social Media Support:Public-facing response channels manage brand reputation incidents. Digitally native retailers and consumer electronics brands deploy this for high-velocity issue deflection.
Phone Support dominates installed base. Live Chat is where expansion concentrates.
Industry Vertical:
Vertical specialization determines compliance certification requirements and pricing tier access.
- Information Technology:Enterprise software and infrastructure vendors generate premium contract values. HITRUST and FedRAMP certification requirements filter vendor pools, concentrating demand among pre-certified operators serving regulated sub-segments.
- Telecommunications:Network operators and ISPs require 24/7 coverage for service outage response. FCC regulatory exposure shapes recording and escalation protocols.
- Consumer Electronics:Hardware manufacturers leverage warranty-integrated support to control return rates. Seasonal launch cycles create demand spikes requiring elastic capacity.
- E-Commerce:Transactional support focuses on payment failures and fulfillment tracking. Illinois BIPA and California CCPA compliance burdens elevate infrastructure costs for national account coverage.
Information Technology commands premium pricing. E-Commerce is climbing the fastest.
Delivery Model:
Infrastructure ownership structure determines margin profiles and capital intensity.
- Cloud-Based:API-integrated elastic platforms enable consumption-based pricing. Multi-tenant architectures reduce per-seat infrastructure costs while accelerating deployment timelines.
- Outsourced:Third-party operators capture volume-committed multi-year contracts. Domestic compliance footprints compete against offshore cost arbitrage through specialized vertical expertise.
- Hybrid:Mixed ownership combines captive control over sensitive workflows with outsourced scale for routine volume. Government contractors favor this for FedRAMP boundary management.
- On-Premise:Dedicated physical infrastructure serves defense and intelligence community segments. Capital intensity limits this to classified or air-gapped environments.
Cloud-Based platforms are gaining share fastest. Outsource maintains the deepest contract backlog.
Customer Segment:
Account size and procurement sophistication shape contract structure and retention economics.
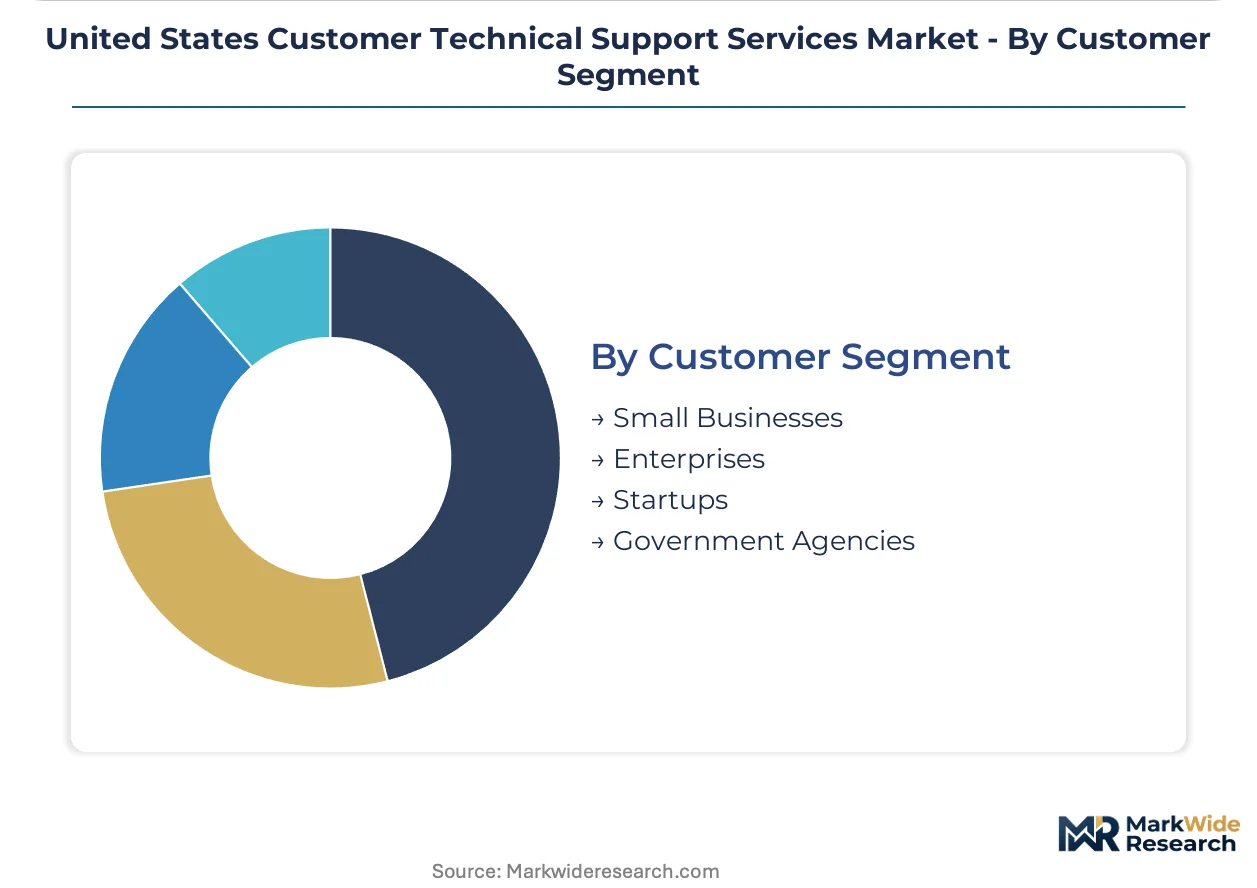
- Enterprises:Fortune 500 and major SaaS vendors demand outcome-governed SLAs with embedded penalty clauses. Procurement teams unbundle channels to optimize cost-to-resolution by incident type.
- Government Agencies:Federal and state entities require StateRAMP and FedRAMP pre-certification. Pre-certified infrastructure filters competition to a narrow vendor pool.
- Small Businesses:Cost-constrained buyers favor standardized packages with limited customization. Volume discounts and self-service portals reduce per-interaction costs.
- Startups:High-growth technology companies prioritize speed-to-deploy over feature depth. API-first platforms and month-to-month terms accommodate rapid scaling.
Enterprises anchor contract values. Government Agencies represent the steepest compliance barrier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Texas and California demonstrate the lowest price elasticity, absorbing premium rates for HIPAA-certified and FedRAMP-compliant operations, while small business segments in the Southeast and Midwest drive commoditization pressures on standardized support packages.
California
Silicon Valley enterprise software vendors anchor the nation's highest contract values for technical success operations. CCPA biometric data amendments force providers to rebuild recording infrastructure with encrypted storage and explicit consent protocols. San Francisco and San Jose clusters concentrate AI-assisted ticketing platform deployments among mid-market SaaS vendors.
Texas
Austin-Dallas corridor enterprise software clustering generates concentrated demand for specialized technical support talent pools. State data privacy frameworks prompt recertification of compliance infrastructure for providers serving national accounts. Dallas-Fort Worth metroplex anchors regional service center expansion for cloud infrastructure vendors.
Illinois
BIPA enforcement creates demand for voice authentication alternatives and behavioral analytics tools among healthcare IT support operators. HIPAA compliance mandates extend technical support workflows into HITRUST-certified vendor selection criteria. Chicago metropolitan area concentrates medical device and EHR software vendor customer success operations.
New York
Financial services verticals in Manhattan demand premium technical support engagements with embedded SLA penalty structures. State cybersecurity regulations intersect with federal cloud security mandates for providers serving banking and insurance technology vendors. New York City metro anchors specialized compliance-focused support operations for regulated industries.
Washington
Pacific Northwest cloud infrastructure vendors drive elastic, API-integrated support platform adoption across enterprise segments. State biometric privacy legislation aligns with California frameworks, requiring multi-jurisdictional compliance architecture. Seattle metropolitan area concentrates technical support operations for hyperscale cloud providers and enterprise SaaS vendors.
United States Customer Technical Support Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the US customer technical support services landscape. The market structure reflects a tiered consolidation pattern where legacy BPO giants, specialized vertical operators, and digitally native challengers occupy distinct competitive positions. Three strategic archetypes dominate: compliance-certified specialists serving regulated healthcare and financial verticals, distributed agent models competing on domestic cost arbitrage, and high-velocity operators optimized for millennial and Gen Z consumer segments. Dominant competitive moves include vertical specialization through HITRUST and FedRAMP certification acquisition, and hybrid delivery model expansion balancing offshore scale with domestic compliance footprints.
Within the compliance-specialist tier, Cognizant and TTEC occupy positions reflecting divergent strategic approaches to regulated industry penetration. Cognizant exemplifies vertical depth through healthcare and financial services certification anchoring, while TTEC represents distributed agent architecture competing on cost positioning. TaskUs sits within the digitally native tier, occupying a distinct market position between boutique agencies and legacy BPO scale operators. These three companies collectively illustrate how certification infrastructure, delivery model economics, and generational consumer targeting segment competitive positioning across the US market.
| Leading Market Players |
|---|
| TaskUs |
| WOW24-7 |
| Teleperformance |
| Cognizant |
| Foundever |
| Concentrix |
| Helpware CX |
| Genpact |
| TTEC |
| Others |
Value Network & Pricing Analysis
Capacity utilization at HITRUST-certified service centers in Texas and California establishes price floors that offshore operators cannot match, compressing margin structures for domestic hybrid delivery models while anchoring premium tiers to compliance infrastructure investments.
Pricing Analysis
HIPAA and FedRAMP certification requirements dictate the pricing tier structure across the US customer technical support services landscape. Three-tier pricing structure across premium, standard, and economy levels separates HITRUST-certified healthcare operators from StateRAMP-verified government contractors and uncertified generalist providers. Price differentiation rests on compliance grade and vertical specialization depth. Cost compression in the standard tier is intensifying because mid-market SaaS vendors deploy AI-assisted platforms to reduce agent headcount. Small business segments in the Southeast and Midwest exhibit highest price sensitivity, while Fortune 500 enterprises in California and Texas absorb premium rates for specialized compliance operations.
Supply Chain Analysis
Just-in-time talent deployment dominates technical support supply chains, with elastic cloud platforms enabling rapid agent scaling against seasonal demand spikes from consumer electronics launches and enterprise software release cycles. Geographic supply concentration centers on India, the Philippines, and the United States for agent capacity, with domestic footprints concentrated in Texas, California, and Arizona. Raw material dependencies include cloud infrastructure subscriptions, CRM software licenses, and biometric authentication tools. Single-source vulnerability in AI model providers creates concentration risk for automated ticketing platforms. Distribution runs through direct enterprise sales teams and channel partners serving mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-assisted ticketing platform adoption represents an early-cycle expansion story, with enterprise SaaS vendors accelerating outsourced technical support procurement as predictive service models displace legacy break-fix relationships.
For Market Incumbents: Consolidate vertical certification moats by accelerating HITRUST and FedRAMP acquisition timelines before compliance backlogs lengthen assessment cycles. Acquire specialized healthcare IT support operators in Illinois and Texas to anchor regional talent pools. AI decision-making liability in regulated verticals threatens margin structures if algorithmic routing bypasses mandated human oversight.
For New Entrants and Emerging Players: Behavioral analytics and tokenized identity verification tools address Illinois BIPA enforcement gaps where incumbents under-serve healthcare IT operators seeking voice authentication alternatives. Target the Austin-Dallas corridor for cloud infrastructure vendor technical success operations, where enterprise software clustering concentrates demand. Deploy API-first platforms with consumption-based pricing to penetrate startup segments prioritizing speed-to-deploy over feature depth.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compliance-certified specialists with pre-built privacy infrastructure serving healthcare and financial services verticals. Long-term viability hinges on defensible certification backlogs and vertical talent pool control. Acquisition target archetype: HITRUST-certified operators with 12-18 month assessment cycle completion and established Illinois BIPA-compliant interaction routing. Signal to watch: Illinois biometric privacy litigation volume crossing thresholds that trigger national account infrastructure rebuilds.
| Strategic Initiative | Industry Significance |
|---|---|
| HITRUST Certification Acquisition | Expands addressable market into HIPAA-mandated healthcare IT support workflows with premium contract values. |
| API-Integrated Platform Deployment | Enables consumption-based pricing alignment with mid-market SaaS vendor cost-to-resolution optimization demands. |
| Biometric Privacy Infrastructure Build | Isolates Illinois and California interactions from standard pipelines to satisfy BIPA and CCPA amendment requirements. |
| Hybrid Delivery Model Expansion | Balances offshore cost arbitrage with domestic compliance footprints for government contractor segment access. |
| AI Copilot Integration | Compresses average handle times for authentication and configuration queries in millennial and Gen Z consumer segments. |
Research Methodology
A spread of perspectives from technical support operations directors, healthcare IT vendor procurement leads, compliance officers at HITRUST-certified operators, and enterprise SaaS customer success executives converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, state biometric privacy enforcement records, FedRAMP authorization databases, and healthcare IT vendor contract disclosures. Bottom-up agent capacity modeling and top-down enterprise spend estimation were triangulated against cloud infrastructure vendor support operation disclosures.
Segmentation dimensions modeled include service type, industry vertical, delivery model, and customer segment across the analysis window. CAGRs were derived from regression analysis of historical outsourcing contract values and projected AI-assisted platform adoption curves. Forecast inputs incorporated HIPAA compliance mandate expansion timelines and FCC net neutrality ruling uncertainty scenarios.
Forecasts assume regulatory continuity in HIPAA, Illinois BIPA, and California CCPA enforcement regimes; material policy shifts would require re-modeling of healthcare and e-commerce vertical demand assumptions. Revision becomes warranted when AI decision-making liability litigation volume crosses thresholds that alter automated escalation protocol deployment economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Global Enterprise Content Collaboration Market
Enterprise Services
Global Supply Chain As a Service (Scaas) Market
Enterprise Services
Workforce Management Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market
Enterprise Services
Global Managed Infrastructure Service Market
Enterprise Services
Human Capital Management (HCM) Market
Enterprise Services
Electronics Contract Manufacturing Services (EMS) Market
Enterprise Services
North America Warehouse Management Systems Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Shared Services Center Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Supplier Management Market