
 Electronic Alarms Market | 2026-2036
Electronic Alarms Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Alarms Market Analytics
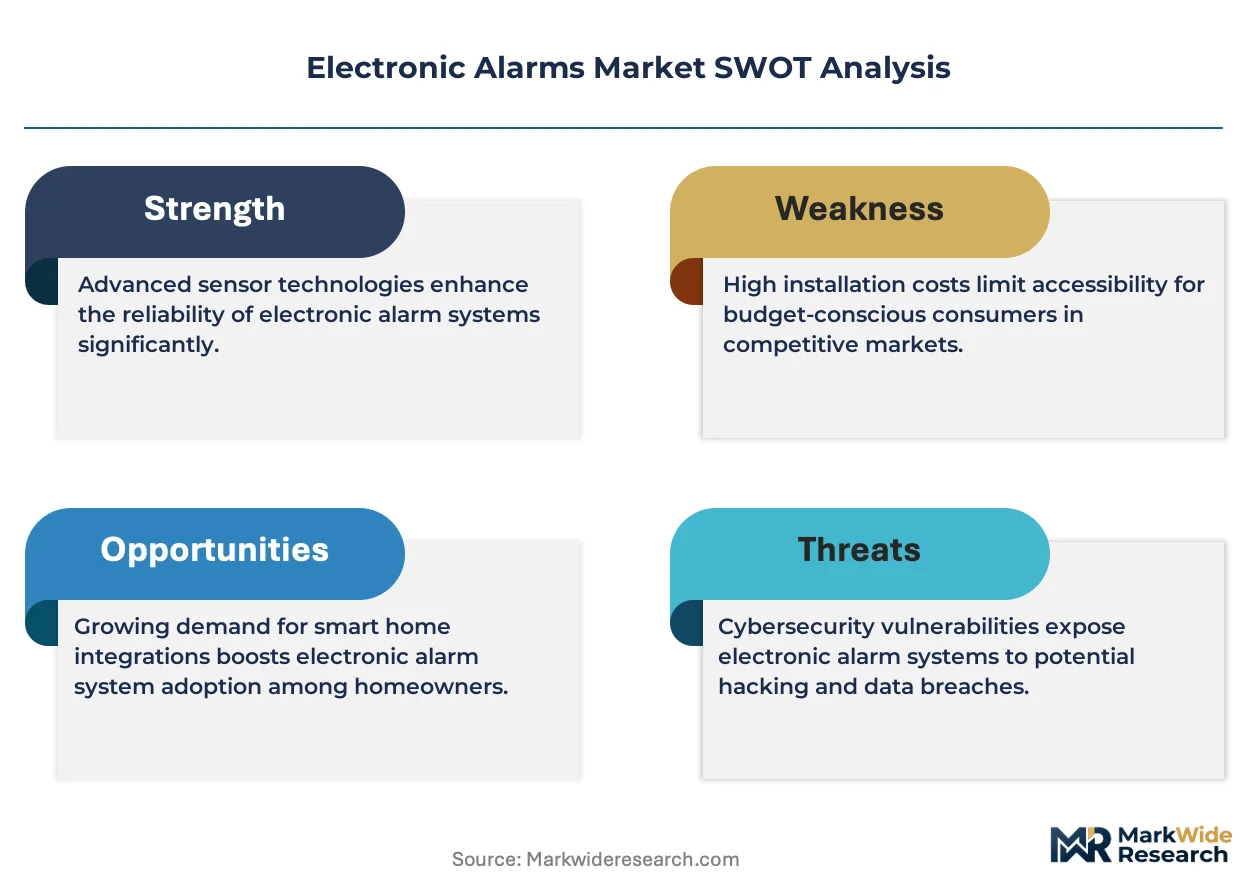
Silicon-based microcontrollers are expanding into piezoelectric sensor arrays across fire and smoke detection units, cutting unit costs while improving false-alarm rejection. Honeywell International leverages backward integration into semiconductor sourcing to protect margin pools on commercial-grade panels. Johnson Controls anchors its position through deep channel control over integrator networks in North American infrastructure projects. Siemens AG competes on R&D intensity in industrial-grade alarm protocols.
Electronic alarms are electromechanical or solid-state devices that detect anomalous conditions—intrusion, combustion, toxic gas accumulation—and emit audible, visual, or networked alerts to initiate protective response. Contemporary units integrate MEMS sensors, RF transceivers, and edge-processing chipsets to achieve sub-100-millisecond trigger-to-notification latency. Smart Technology within the technology dimension leads growth as cloud-connected diagnostics and mobile-app management displace legacy hardwired panels. The residential end-user segment shows the fastest expansion as single-family homeowners adopt DIY-installable wireless kits. Burglar Alarms remain the largest product-type revenue pool though margin compression is accelerating in basic standalone units.
The FCC governs RF spectrum allocation for wireless alarm transmissions in the United States while the EU AI Act imposes transparency requirements on smart systems with automated decision logic. ETSI standards in Europe and UL certification in North America shape interoperability and liability frameworks that determine market access for new entrants. Stakeholders must monitor evolving cybersecurity mandates for IoT-connected alarm infrastructure as regulatory bodies on both continents tighten firmware-update and encryption protocols.
Market Dynamics
Wireless connectivity standards and IoT integration are compressing product development cycles while fragmenting value capture between hardware manufacturers and cloud-platform operators across the electronic alarms ecosystem.
Growth Catalysts
- EU AI Act transparency mandates:Automated decision logic requirements for smart alarm systems are accelerating firmware investment in European markets, pulling demand toward certified intelligent panels.
- Silicon-based microcontroller expansion:Piezoelectric sensor arrays in fire and smoke detection units are cutting unit costs while improving false-alarm rejection rates in residential installations.
- DIY-installable wireless kit adoption:Single-family homeowners in the United States are bypassing professional integrators, expanding addressable market reach beyond traditional commercial channels.
Market Restraints
- Semiconductor supply concentration:Backward integration into chip sourcing remains limited to top-tier manufacturers, leaving mid-scale panel producers exposed to foundry allocation volatility.
- RF spectrum congestion:FCC allocation constraints for unlicensed wireless alarm bands in dense urban deployments are triggering interference-related warranty claims and installation delays.
- Hardwired legacy infrastructure:Commercial building stock with embedded copper cabling creates switching cost barriers against full wireless retrofit adoption in institutional end-uses.
Strategic Opportunities
- Industrial-grade protocol R&D intensity:Siemens AG's positioning demonstrates margin pools available in manufacturing facility applications requiring SIL-certified alarm logic and redundant signaling paths.
- Integrator network channel control:Deep relationships with North American infrastructure project contractors offer defensive moats against direct-to-manufacturer procurement trends in commercial segments.
- Cybersecurity firmware mandates:Emerging encryption and update-protocol requirements from ETSI and UL certification bodies are creating compliance-service revenue streams adjacent to hardware sales.
Industry Challenges
- MEMS sensor calibration expertise:Edge-processing chipset integration demands rare combinations of RF engineering and acoustic physics knowledge, constraining product development velocity at smaller manufacturers.
- Multi-standard certification timelines:Simultaneous pursuit of UL, ETSI, and emerging cybersecurity marks extends time-to-revenue for new product introductions by twelve to eighteen months.
- Cloud-platform dependency:Sub-100-millisecond latency requirements force reliance on third-party infrastructure operators, creating service-level vulnerability in mission-critical installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Alarms Market |
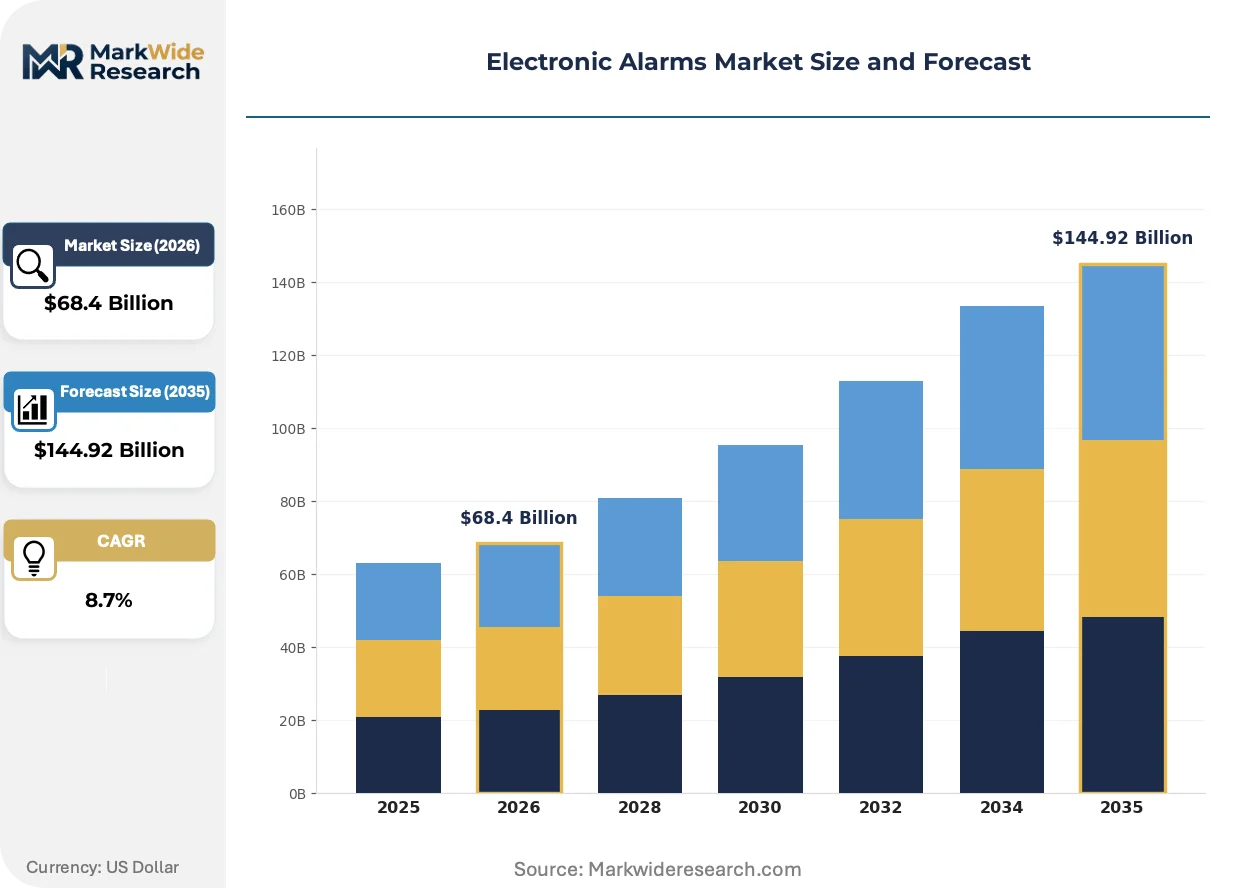
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Burglar Alarms, Fire Alarms, Smoke Alarms, Carbon Monoxide Alarms Technology: Wireless, Hardwired, Hybrid, Smart Technology End User: Residential, Commercial, Industrial, Government Installation Type: DIY, Professional, Integrated Systems, Standalone |
| Companies Covered | Honeywell International, Johnson Controls, ADT Inc., Robert Bosch GmbH, Hangzhou Hikvision Digital Technology Co., Ltd., Vivint Smart Home, Assa Abloy, Schneider Electric SE, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Alarms Market Evolving Landscape
Cloud-connected diagnostics and mobile-app management interfaces are displacing legacy hardwired panels while compressing maintenance revenue models toward subscription-based monitoring services.
Edge-processing chipsets with integrated machine-learning inference engines are electrifying alarm system architectures by enabling local anomaly classification without cloud round-trips. Multi-tenant residential developers in Germany and China are specifying these units for bandwidth-constrained basement equipment rooms. The technology is electrifying competitive positioning by shifting differentiation from hardware durability toward software update frequency and algorithmic accuracy.
The EU AI Act's transparency requirements for automated decision systems are forcing firmware architecture changes across smart alarm portfolios sold in European markets. Manufacturers must now implement explainable-logic modules that document trigger rationale for insurance and liability purposes. Industrial-grade installations in chemical processing and energy infrastructure face the steepest compliance costs, accelerating consolidation among vendors with dedicated European regulatory affairs teams.
Homeowner purchasing patterns are fragmenting across generational lines, with younger buyers in the United States prioritizing app ecosystem integration over panel hardware specifications. Professional security integrators are losing share to direct-to-consumer wireless kit vendors in single-family residential construction. This behavioral split is most visible in new suburban developments across Texas and Florida, where builder-preferred brands diverge sharply from retrofit replacement preferences in legacy housing stock.
Electronic Alarms Market Segmentation
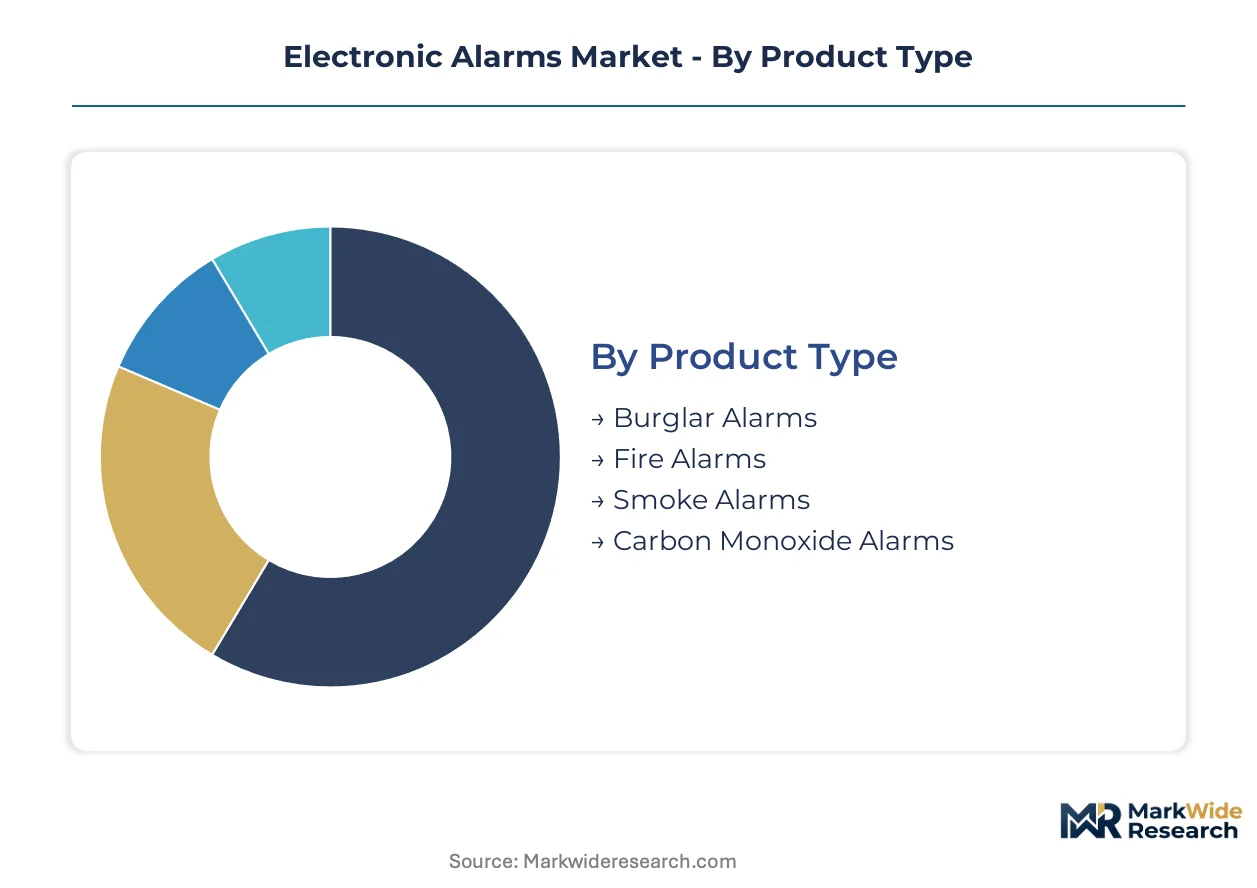
Electronic alarms manufacturers configure product portfolios around distinct technical architectures and buyer procurement patterns. Segment boundaries determine margin capture, certification requirements, and channel strategy for component suppliers and system integrators alike.
Product Type:
Replacement cycles vary dramatically across hazard-detection categories, with smoke and carbon monoxide units facing mandatory retirement timelines that drive recurring revenue.
- Burglar Alarms:Perimeter sensors, motion detectors, and control panels form integrated intrusion-detection networks. Demand clusters in United States suburban residential developments and German commercial retail parks where insurance underwriters mandate certified installations.
- Fire Alarms:Addressable loop architectures and multi-sensor heads detect thermal and optical signatures. Industrial facilities in China's Yangtze River Delta specify these for warehouse complexes under tightened MEE enforcement of facility safety codes.
- Smoke Alarms:Photoelectric and ionization chamber designs dominate residential ceiling-mount applications.
- Carbon Monoxide Alarms:Electrochemical sensor cells with 5-7 year replacement horizons generate recurring hardware pull-through in North American and European markets.
Volume placements concentrate in Burglar Alarms; the faster expansion belongs to Carbon Monoxide Alarms.
Technology:
Cost tiers separate legacy copper-wired installations from silicon-intensive connected platforms, with hybrid architectures capturing transitional upgrade budgets.
- Wireless:RF transceiver modules operating in unlicensed spectrum bands eliminate conduit installation labor. United States single-family homeowners favor these for retrofit projects where drywall penetration costs exceed hardware premiums.
- Smart Technology:Edge-processing chipsets with machine-learning inference enable local anomaly classification without cloud dependency. Multi-tenant developers in Germany specify these for bandwidth-constrained basement equipment rooms.
- Hardwired:Copper-cable signaling paths persist in institutional buildings with embedded infrastructure.
- Hybrid:Dual-path architectures combine wireless sensor flexibility with hardwired backbone reliability.
Customer procurement concentrates in Wireless; Smart Technology gains share fastest among new construction specifications.
End User:
Application maturity determines specification complexity, with industrial buyers demanding SIL-certified logic while residential purchasers prioritize app ecosystem integration.
- Residential:Single-family and multi-tenant housing units drive volume through DIY-installable wireless kits. Younger buyers in United States new suburban developments prioritize smartphone management interfaces over panel hardware specifications.
- Commercial:Office complexes, retail chains, and hospitality properties require networked monitoring with central station dispatch. Johnson Controls maintains channel control through integrator relationships in North American infrastructure projects.
- Industrial:Manufacturing facilities and energy infrastructure demand redundant signaling paths and protocol certification.
- Government:Municipal buildings, military installations, and correctional facilities specify tamper-resistant architectures with encrypted communications.
Procurement volume concentrates in Residential; Commercial applications show the steepest margin expansion trajectory.
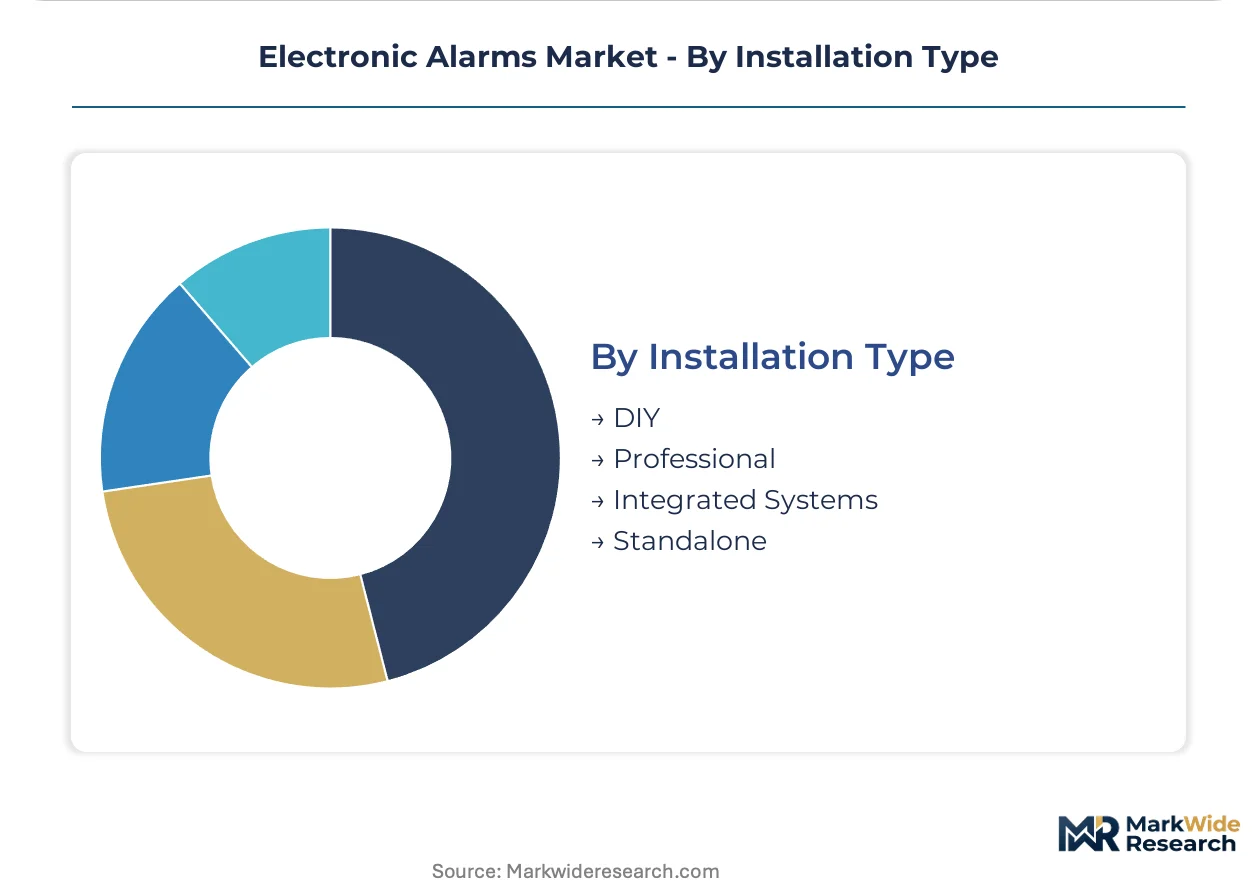
Installation Type:
Service revenue models diverge sharply between self-configured consumer purchases and contracted integration with ongoing maintenance agreements.
- DIY:Pre-paired sensor kits with adhesive mounting and smartphone-guided configuration bypass professional labor. Direct-to-consumer vendors in United States home improvement retail channels capture this expanding segment.
- Professional:Certified technician deployment with commissioning documentation satisfies insurance and regulatory requirements. Commercial end-users in Germany mandate this for liability protection under EU AI Act transparency provisions.
- Integrated Systems:Building management system convergence with HVAC, access control, and lighting networks.
- Standalone:Single-function units without network connectivity persist in cost-sensitive replacement markets.
Shipment volume concentrates in DIY; Professional installations retain premium pricing power in commercial and industrial specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for electronic alarms concentrates in the United States, China, and Germany, where distinct regulatory frameworks and construction cycles shape procurement patterns across residential, commercial, and industrial installations.
United States
Single-family homeowners in Texas and Florida drive DIY-installable wireless kit adoption, bypassing traditional integrator channels. The FCC governs RF spectrum allocation for unlicensed alarm transmissions, creating deployment constraints in dense urban corridors. Suburban developments across the Sun Belt specify cloud-connected panels with mobile-app management interfaces.
China
Industrial facilities in the Yangtze River Delta specify addressable fire alarm loops under tightened MEE enforcement of warehouse safety codes. GB standards and MIIT regulations shape product certification timelines for both domestic consumption and export manufacturing. Multi-tenant residential towers in Shenzhen and Shanghai integrate smart alarm protocols with building management systems.
Germany
Commercial retail parks mandate certified burglar alarm installations where insurance underwriters require professional commissioning documentation. The EU AI Act imposes transparency requirements on automated decision logic in smart systems, accelerating firmware investment. Bavarian industrial zones specify SIL-certified alarm logic for chemical processing and energy infrastructure applications.
Japan
Multi-tenant developers in Tokyo and Osaka prioritize edge-processing chipsets with machine-learning inference for bandwidth-constrained basement equipment rooms. METI efficiency standards and JIS certification requirements shape interoperability frameworks. Aging building stock in Kansai drives hybrid retrofit installations combining wireless sensor flexibility with hardwired backbone reliability.
United Kingdom
London commercial property managers demand networked monitoring with central station dispatch for office complexes and hospitality chains. GDPR and emerging ETSI cybersecurity mandates tighten firmware-update and encryption protocols for IoT-connected infrastructure. Southeast England new-build residential specifications favor smart technology integration over legacy hardwired panels.
Electronic Alarms Market Competitive Landscape
Backward integration into semiconductor sourcing dominates the current landscape as top-tier manufacturers seek protection against foundry allocation volatility. The vendor base stratifies across three tiers: diversified industrial conglomerates with captive chip supply, pure-play security specialists with deep integrator channel control, and direct-to-consumer wireless kit vendors expanding through home improvement retail. Strategic archetypes include scale-driven platform operators, compliance-focused European regulatory affairs teams, and app-centric DIY disruptors. M&A activity and geographic expansion through integrator network acquisitions represent the dominant competitive moves reshaping market structure.
Among diversified industrial conglomerates, Honeywell International and Siemens AG exemplify archetypes built on upstream control over critical component supply and R&D intensity in industrial-grade protocols. Johnson Controls occupies a position within the integrator-dependent tier, anchoring its competitive stance through relationships with North American infrastructure project contractors. These three entities represent distinct strategic postures: captive semiconductor sourcing, protocol certification depth, and channel control moats respectively.
| Leading Market Players |
|---|
| Honeywell International |
| Johnson Controls |
| ADT Inc. |
| Robert Bosch GmbH |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Vivint Smart Home |
| Assa Abloy |
| Schneider Electric SE |
| Siemens AG |
| Others |
Value Network & Pricing Analysis
RF engineering and acoustic physics specialists concentrated in Shenzhen and Taipei drive labor-cost differentials that separate premium smart-alarm engineering from economy-tier panel assembly, with certification-grade firmware architects commanding multiples over basic hardware technicians.
Pricing Analysis
Volume placements cluster in economy-tier standalone burglar alarms while margin capture concentrates in premium smart-technology panels with edge-processing chipsets. Three-tier pricing structure across premium, standard, and economy levels reflects UL certification grade and after-sales service bundling. Cost compression in basic wireless kits stems from MEMS sensor commoditization. Residential DIY buyers exhibit highest price sensitivity; industrial SIL-certified purchasers show lowest.
Supply Chain Analysis
Domestic-content mandates in China's GB standards and India's PLI scheme are reshaping sourcing toward local microcontroller packaging and sensor calibration facilities. Semiconductor fabrication draws from Taiwan, South Korea, and China; piezoelectric sensor elements rest on Japanese and German ceramic substrate suppliers. Single-source vulnerability in foundry allocation for edge-processing chipsets creates bottleneck exposure. Distribution runs through integrator networks in commercial segments and home improvement retail in residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive semiconductor sourcing and firmware development capability determine margin defense against cloud-platform operators.
For Market Incumbents: Extend backward integration into MEMS sensor design and foundry partnerships to protect margin pools from fabless competitors. Deepen channel control over North American infrastructure integrators before direct-to-consumer wireless vendors capture commercial retrofit demand. Prioritize EU AI Act compliance investment as a certification moat against mid-scale European entrants lacking regulatory affairs scale. For New Entrants and Emerging Players: Begin with DIY-installable wireless kits in United States Sun Belt suburban developments where builder-preferred brand relationships remain unformed. Target bandwidth-constrained multi-tenant basement installations in Germany and Japan where edge-processing latency requirements favor specialized hardware over generic cloud-dependent panels. Pursue app ecosystem partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with firmware-architecture specialists holding EU AI Act transparency-module capabilities given accelerating consolidation among vendors with dedicated European regulatory teams. Long-term viability favors acquirers of edge-processing chipset design houses with machine-learning inference IP. Watch for FCC spectrum reallocation decisions as the inflection signal for wireless alarm bandwidth economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Honeywell's captive chip supply protects margins against foundry allocation volatility. |
| EU AI Act Compliance Certification | Siemens' firmware transparency modules create liability protection for industrial buyers. |
| Integrator Network Acquisition | Johnson Controls' contractor relationships defend commercial segments from direct procurement. |
| Edge-Processing Chipset Development | Smart-technology differentiation shifts toward algorithmic accuracy and update frequency. |
| DIY Wireless Kit Platform Launch | Vivint's retail channel expansion captures residential buyers bypassing professional installation. |
Research Methodology
Multi-period observation of MEMS sensor cost curves, RF module pricing, and certification timeline extensions anchored the trend analysis, supplemented by interviews with alarm system R&D directors, UL certification engineers, commercial security integrators, and residential channel buyers at home improvement retailers. Secondary validation drew from FCC spectrum allocation filings, ETSI standard update records, SEC 10-K disclosures by listed manufacturers, and MIIT regulatory bulletins. Bottom-up shipment estimates by product category triangulated against top-down construction spending and insurance mandate penetration data.
Segment-weighting across product type, technology architecture, end-user application, and installation mode determined value distribution throughout the projection horizon. CAGRs derived from fitted growth curves incorporating smart-home adoption elasticities, semiconductor supply constraints, and regulatory compliance cost trajectories. Forecast inputs included wireless protocol migration rates and cloud-platform subscription attach rates by buyer demographic.
Semiconductor supply disruption, FCC spectrum reallocation decisions, and EU AI Act enforcement intensity are the dominant revision risks to modeled outcomes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Adaptive Security Market
Security and Surveillance
Situational Awareness System Market
Security and Surveillance
Signal Jamming Systems Market
Security and Surveillance
Explosive Vapour Detector Market
Security and Surveillance
Global Police and Law Enforcement Equipment Market
Security and Surveillance
Stadium Security Market
Security and Surveillance
Global Security Orchestration Market
Security and Surveillance
Explosive Detection Kit Market
Security and Surveillance
Security Operations Center Market
Security and Surveillance
Middle East Manned Security Services Market
Security and Surveillance
Forensic Technologies Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
Burglar Alarm Systems Market
Security and Surveillance
Cargo and Vehicle Screening Market
Security and Surveillance
Air Cargo Screening Systems Market
Security and Surveillance
Global Security As a Service Market