
 EV Charging Networks Market | 2026-2036
EV Charging Networks Market Size, Share, and Industry Trends Forecast 2026-2036
EV Charging Networks Market Insights
Asset-light leasing and project finance structures are fragmenting capital requirements across the EV charging value chain, enabling non-utility entrants to scale without balance-sheet intensity. ChargePoint leverages its software-agnostic platform to sustain hardware-agnostic network growth across retail and workplace installations. Tesla anchors vertical integration from vehicle to charger, controlling proprietary connector standards and destination charging placement. ABB competes on industrial-grade power electronics, differentiating through grid-stabilizing bidirectional charging capabilities.
EV charging networks comprise interconnected hardware, software, and grid-integration systems that deliver electrical energy to battery-electric vehicles, typically operating at power levels from 7 kW AC residential units to 350 kW+ DC fast chargers with liquid-cooled cables. These networks manage real-time load balancing, authentication protocols, and energy metering to enable reliable commercial vehicle refueling at scale. DC fast charging commands the dominant share of public infrastructure investment due to throughput economics, while fleet charging represents the fastest-expanding station type as logistics operators electrify depots. Wireless charging remains nascent but occupies strategic testing corridors for autonomous taxi and transit applications where connector wear presents operational risk.
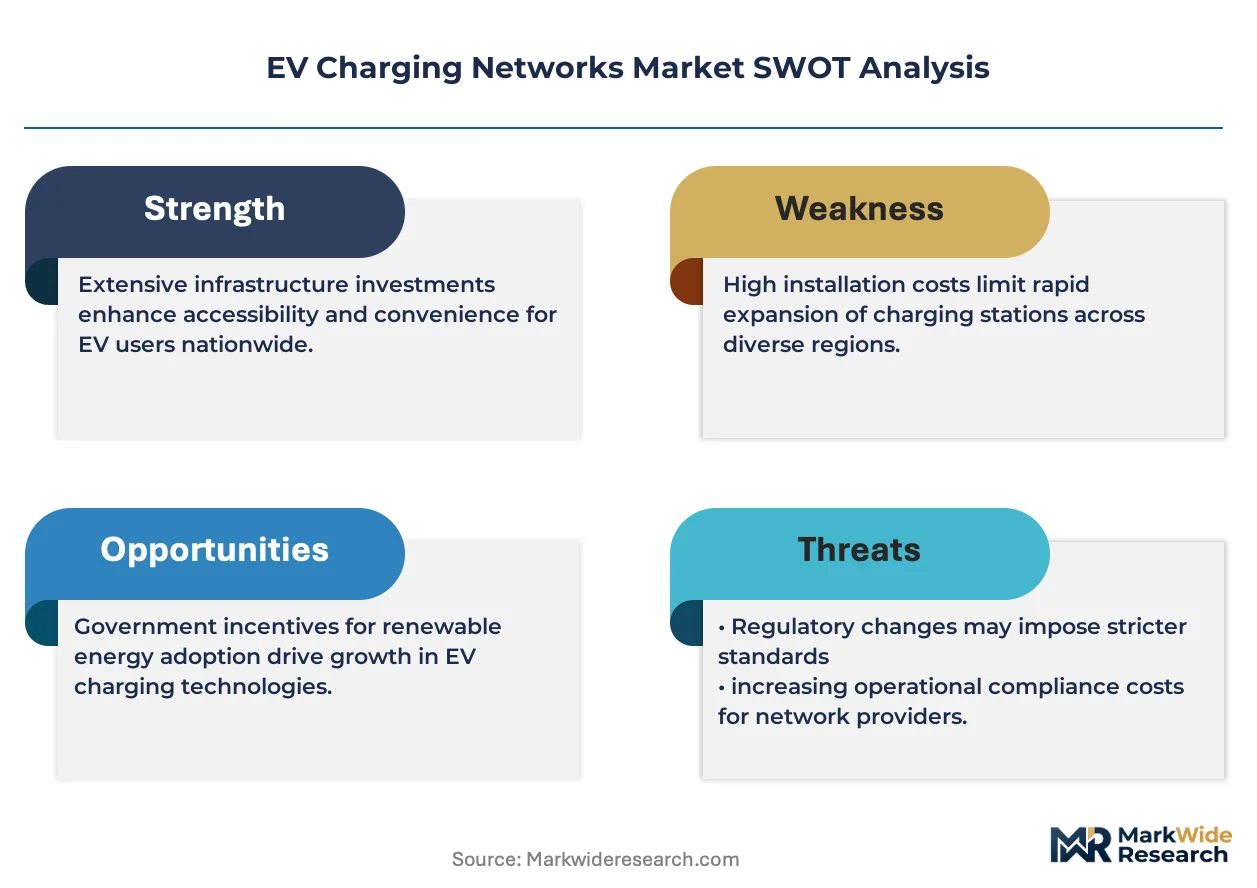
The US Department of Transportation's National Electric Vehicle Infrastructure Formula Program and the Federal Energy Regulatory Commission's interconnection rules are standardizing highway corridor deployment and grid access timelines. In Europe, the EU Alternative Fuels Infrastructure Regulation mandates minimum charging coverage along trans-European transport networks, while ECHA's REACH compliance affects cable and housing material selection. China's MIIT and NMPA coordinate GB/T connector standards with grid codes that prioritize domestic equipment procurement. Stakeholders must monitor how interoperability mandates and carbon-accounting requirements for construction materials reshape procurement criteria and vendor qualification timelines.
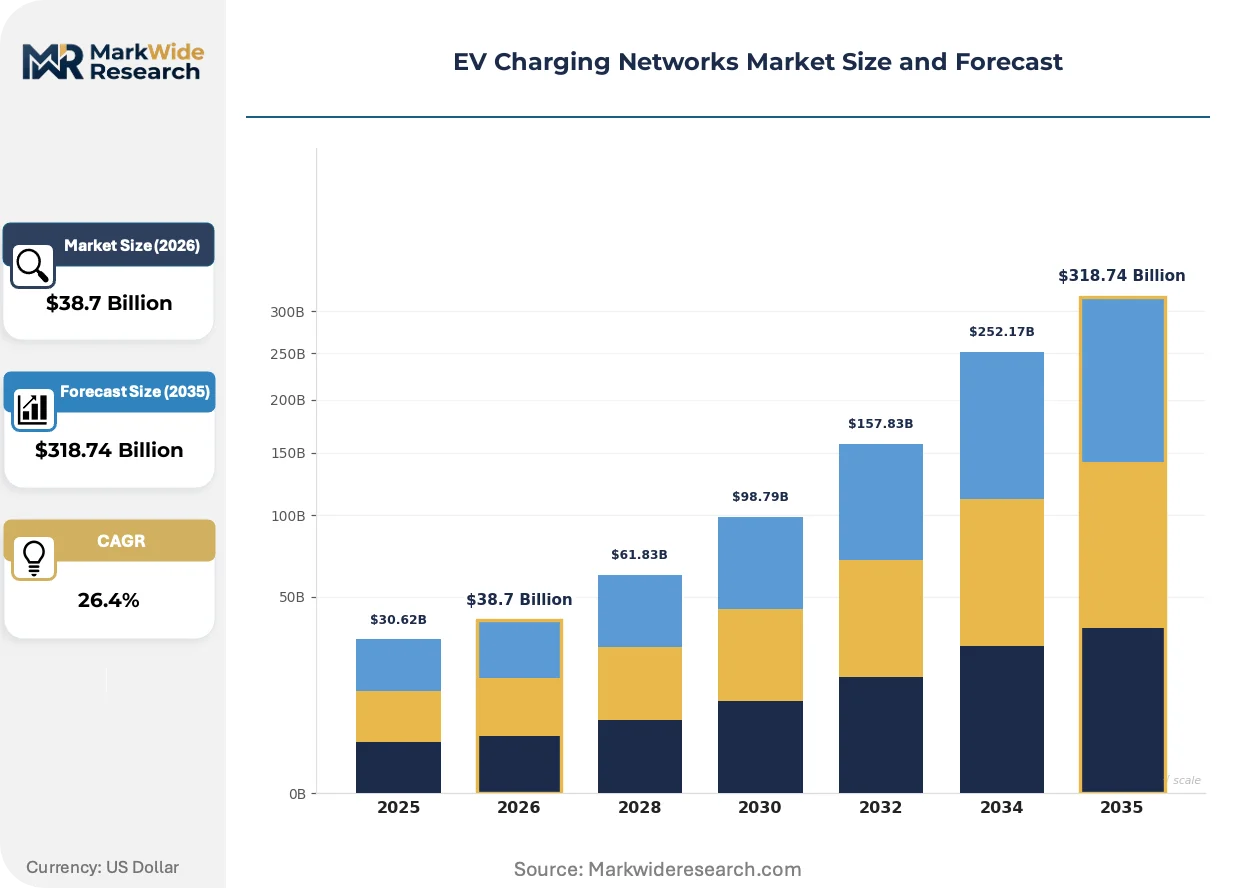
Market Dynamics
DC fast charging infrastructure buildouts are fragmenting capital deployment across asset-light leasing structures, enabling non-utility entrants to scale without balance-sheet intensity while grid interconnection queues create deployment bottlenecks.
Growth Catalysts
- US Inflation Reduction Act Alternative Fuel Vehicle Refueling Property Credit:Federal tax incentives channel public capital into highway corridor charging stations, accelerating deployment timelines for fast-charging networks.
- Fleet electrification commitments:Logistics operators across North America and Europe are electrifying depots, creating dedicated charging demand that anchors station utilization economics.
- EU Green Deal Fit for 55 package:Binding emissions targets mandate charging coverage along trans-European transport networks, forcing infrastructure buildouts ahead of vehicle adoption curves.
Market Restraints
- Copper and silicon carbide supply concentration:Power electronics manufacturing depends on concentrated raw material suppliers, exposing hardware costs to commodity volatility and geopolitical disruption.
- Grid interconnection queue delays:Federal Energy Regulatory Commission standardization has not eliminated regional utility backlogs, extending project commissioning timelines by 12-24 months in high-demand corridors.
- Proprietary connector lock-in:Tesla's North American Charging Standard creates interoperability friction for non-Tesla vehicles, fragmenting network access and requiring dual-hardware installations.
Strategic Opportunities
- Wireless charging corridors:Autonomous taxi and transit operators are piloting inductive charging pads where connector wear presents operational risk, opening depot and roadway-embedded installation demand.
- Bidirectional vehicle-to-grid integration:Aggregated fleet batteries offer grid stabilization services, creating new revenue streams beyond energy sales for charging network operators.
- Workplace and retail destination charging:Underpenetrated commercial real estate segments in Germany and California represent captive dwell-time charging opportunities with superior utilization profiles.
Industry Challenges
- Power electronics engineering talent scarcity:Specialized skill requirements for high-voltage DC systems and thermal management exceed available workforce supply, compressing project execution capacity.
- Multi-standard certification complexity:GB/T, CCS, and NACS connector variants require parallel testing protocols, extending hardware qualification timelines for equipment vendors serving multiple geographies.
- Legacy electrical infrastructure retrofit costs:Aging distribution networks in dense urban cores require costly upgrades to support 350 kW+ charging clusters, inflating site development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Charging Networks Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $318.74 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charging Technology: AC Charging, DC Fast Charging, Wireless Charging, Ultra-Fast Charging Charging Station Type: Public Charging, Private Charging, Fleet Charging, Home Charging End User: Municipalities, Commercial Operators, Residential Users, Fleet Managers Platform: Mobile App, Subscription Service, Network Management, Payment Gateway |
| Companies Covered | Tesla, ChargePoint, ABB, EVgo, Shell Recharge, Wallbox, EVBox, BP Pulse, Blink Charging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Charging Networks Market Trends and Innovations
Software-defined charging platforms are displacing hardware-centric network architectures, enabling dynamic load management and interoperability layers that decouple infrastructure ownership from service delivery.
Artificial intelligence-based predictive maintenance is digitizing charging station operations. Fleet operators and network managers deploy machine learning models to forecast component failures before downtime occurs. Predictive algorithms compress maintenance costs and station availability metrics, shifting competitive advantage toward data-rich operators.
The EU Alternative Fuels Infrastructure Regulation mandates minimum charging power outputs and payment accessibility standards across member states. Equipment vendors must redesign housing interfaces and terminal software to comply with unified accessibility requirements. Germany and France are accelerating tender processes to meet corridor coverage deadlines, favoring vendors with pre-certified hardware platforms.
Energy-as-a-service contracting is displacing capital-intensive station ownership for commercial fleet operators. Logistics providers prefer operational expenditure models where charging infrastructure vendors retain asset ownership and guarantee uptime performance. California and the Netherlands show the fastest contract velocity, with municipal transit agencies leading adoption of performance-guaranteed service agreements.
EV Charging Networks Market Segmentation
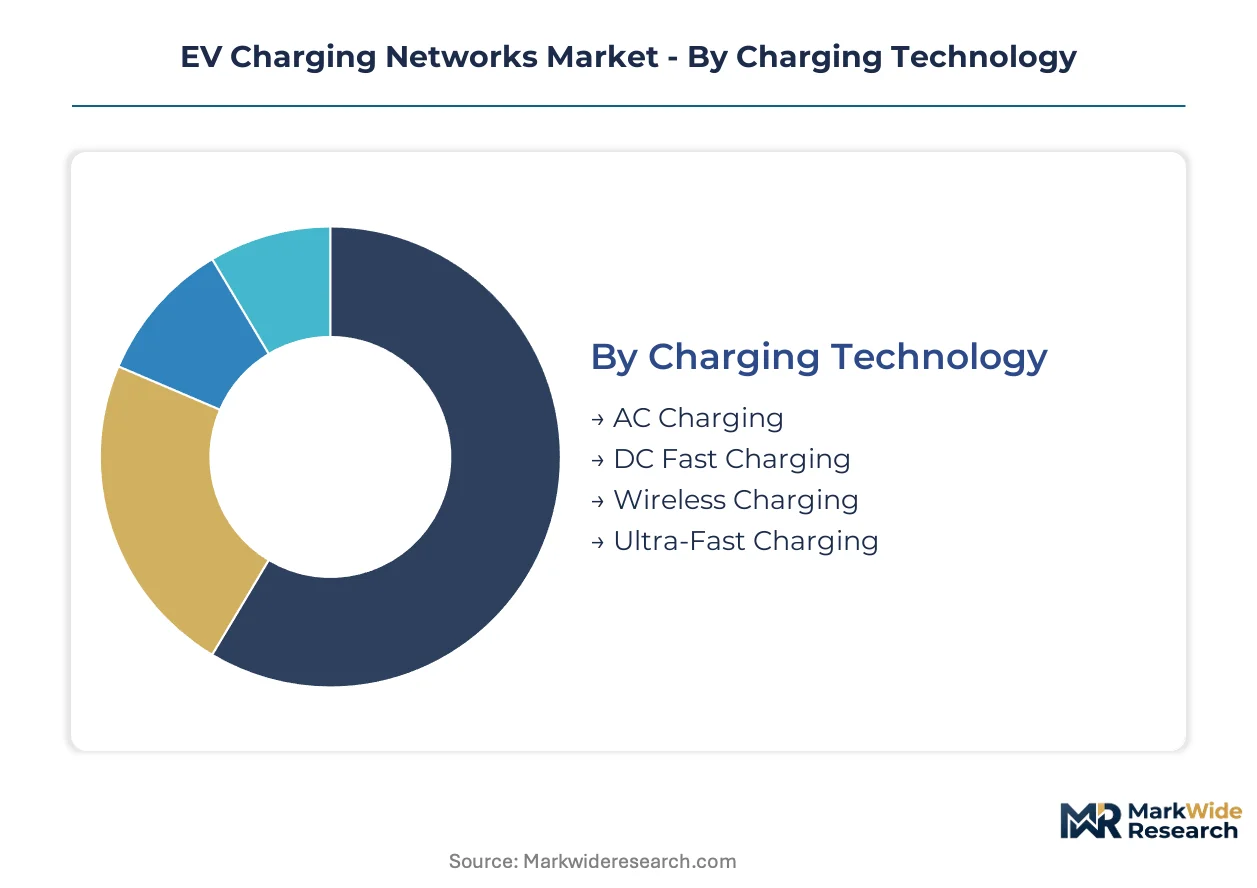
Segmentation in EV charging networks reveals how capital flows, technology cycles, and regulatory pressures concentrate across distinct operational models. Understanding these divisions exposes where infrastructure economics break favorably and where deployment bottlenecks persist.
Charging Technology:
Technology segments diverge sharply in replacement cycles, with power electronics refreshing every 3-5 years while connector standards persist for decades.
- AC Charging:Level 1 and Level 2 units deliver 3-19 kW through onboard vehicle rectifiers, dominating workplace and residential installations where dwell times exceed 4 hours. Demand clusters in Germany and California commercial real estate as building codes mandate EV-ready parking ratios.
- DC Fast Charging:Direct current systems bypass onboard converters to deliver 50-350 kW, commanding premium hardware costs and grid interconnection complexity. Highway corridor deployment in the US and EU absorbs the bulk of public infrastructure subsidies as fleet operators prioritize route coverage over depot density.
- Wireless Charging:Inductive pads transfer power across air gaps using resonant magnetic coupling, eliminating connector wear for autonomous vehicle fleets. Pilot installations concentrate in Singapore and Dubai transit corridors where robotic taxi services test hands-free operation.
- Ultra-Fast Charging:Liquid-cooled 350 kW+ systems enable sub-15 minute refueling for heavy-duty electric trucks. Thermal management engineering and utility demand charges constrain site economics to high-volume freight corridors.
AC Charging dominates installed base. DC Fast Charging is where expansion concentrates.
Charging Station Type:
Station ownership models split capital intensity between utility balance sheets, third-party operators, and captive fleet infrastructure.
- Public Charging:Open-access highway and urban curbside stations serve mixed vehicle populations with roaming interoperability protocols. US NEVI Formula Program and EU AFIR mandates accelerate deployment along designated transport corridors.
- Private Charging:Restricted-access installations at workplaces, retail destinations, and multi-unit dwellings serve known user populations with simplified authentication. California and the Netherlands lead contract velocity for commercial real estate integrations.
- Fleet Charging:Dedicated depot infrastructure serves captive electric truck and bus populations with predictable load profiles. Logistics operators in Germany and the US Midwest electrify distribution hubs ahead of vehicle delivery timelines.
- Home Charging:Residential Level 2 units represent the lowest-cost installation per port but face split-incentive problems in rental housing markets. Utility time-of-use rate designs in Texas and Italy shape charging behavior optimization.
Fleet Charging climbs the fastest as logistics electrification accelerates. Home Charging retains volume leadership in port count.
End User:
Customer procurement authority determines contract structure, from municipal RFP processes to fleet operational expenditure models.
- Municipalities:City and regional governments deploy curbside and transit charging with public funding mandates and accessibility requirements. EU procurement rules favor pre-certified equipment vendors with established maintenance networks.
- Commercial Operators:Retail, hospitality, and workplace property managers install charging as amenity infrastructure with utilization-agnostic business cases. Germany's commercial real estate segment shows underpenetrated expansion opportunity.
- Residential Users:Individual homeowners and renters purchase equipment through electrical contractor channels with limited standardization. Split-incentive barriers in multi-family housing suppress adoption velocity relative to single-family markets.
- Fleet Managers:Logistics and transit operators negotiate energy-as-a-service contracts guaranteeing uptime and per-mile energy costs. California municipal transit agencies lead performance-guaranteed service agreement adoption.
Commercial Operators anchor current revenue concentration. Fleet Managers drive contract innovation toward outcome-based structures.
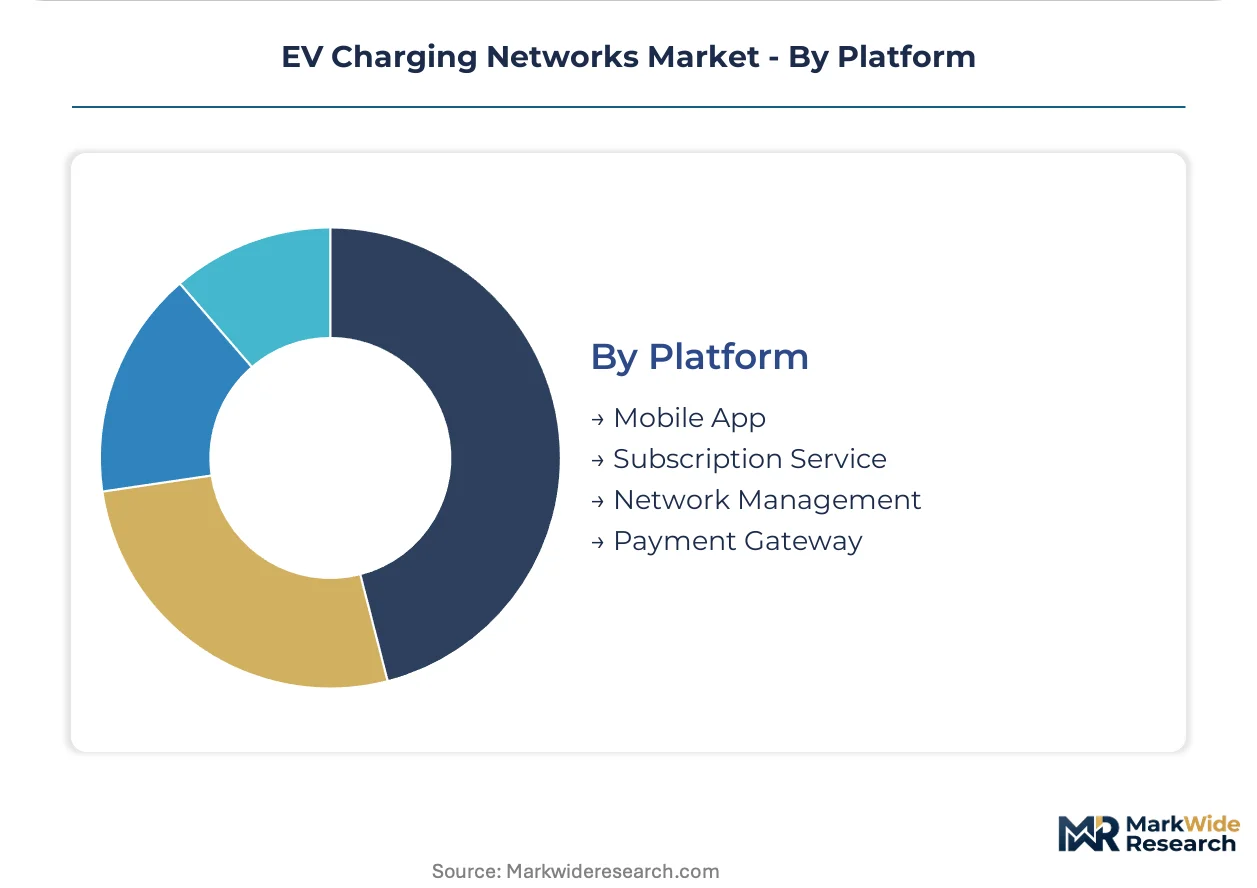
Platform:
Software layers decouple infrastructure ownership from service delivery, enabling asset-light network expansion.
- Mobile App:Consumer-facing discovery and session control applications aggregate roaming access across fragmented hardware networks. Payment tokenization and route planning features differentiate competitive offerings.
- Subscription Service:Flat-rate charging plans reduce price uncertainty for high-frequency users, common among fleet operators with predictable depot utilization. Dutch and California markets show fastest subscription plan uptake.
- Network Management:Back-office platforms coordinate load balancing, fault detection, and energy optimization across distributed charging assets. Grid-stabilizing bidirectional capabilities command premium software licensing fees.
- Payment Gateway:Interoperable transaction processing enables ad-hoc charging without proprietary memberships, mandated by EU AFIR accessibility requirements. Contactless payment terminal integration extends hardware qualification timelines.
Network Management commands highest software margins. Mobile App penetration expands most rapidly among consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital equipment trade flows for EV charging infrastructure show China dominating DC fast charger exports while Germany and the United States absorb premium hardware imports for highway corridor deployment.
United States
Fleet electrification commitments from logistics operators and the NEVI Formula Program are accelerating charging infrastructure deployment. The Federal Energy Regulatory Commission's interconnection rules standardize grid access timelines while California and Texas municipal transit agencies lead performance-guaranteed service agreement adoption for depot charging.
Germany
Commercial real estate charging penetration lags vehicle adoption curves, creating underexploited workplace installation opportunities. The EU Alternative Fuels Infrastructure Regulation mandates trans-European corridor coverage, compelling accelerated tender processes in Bavaria and North Rhine-Westphalia where distribution hub electrification concentrates.
China
Domestic equipment procurement preferences under MIIT and NMPA coordination anchor GB/T standard deployment. The Yangtze River Delta and Pearl River Delta manufacturing clusters supply power electronics globally while absorbing liquid-cooled ultra-fast charging systems for heavy-duty electric truck corridors.
Netherlands
Energy-as-a-service contracting velocity exceeds European peers as logistics providers prefer operational expenditure models. Randstad municipal transit agencies and Rotterdam port operators pioneer performance-guaranteed uptime agreements, shifting vendor selection criteria toward service reliability metrics.
Japan
Workplace and retail destination charging installations cluster in Kanto and Kansai metropolitan corridors. METI standardization efforts coordinate CHAdeMO connector continuity with bidirectional vehicle-to-grid pilot programs in Nagoya and Osaka industrial zones.
EV Charging Networks Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in power electronics and thermal management. The vendor base concentrates around three strategic archetypes: vertically integrated vehicle-to-charger ecosystems, software-agnostic hardware platforms, and industrial-grade power electronics fabricators. Competitive positioning sharpens through M&A activity targeting grid-integration capabilities and strategic partnerships securing semiconductor supply for silicon carbide modules.
Among North American platform operators, Tesla and ChargePoint exemplify divergent architectural approaches to network scale. Tesla anchors proprietary connector standardization and destination charging placement, while ChargePoint occupies the hardware-agnostic integration tier. ABB represents European industrial-grade power electronics specialization, competing on grid-stabilizing bidirectional capabilities. These three anchors illustrate how vertical integration, platform openness, and component depth define competitive boundaries.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| EVgo |
| Shell Recharge |
| Wallbox |
| EVBox |
| BP Pulse |
| Blink Charging |
| Others |
Pricing and Supply Chain Analysis
Chinese silicon carbide wafer fabrication concentrates upstream power electronics supply, anchoring hardware cost structures while downstream margin pools accrue to software-integrated network operators who decouple service delivery from asset ownership. This upstream concentration forces equipment vendors into long-term offtake negotiations while fleet operators capture pricing leverage through energy-as-a-service aggregation.
Pricing Analysis
Fleet operators anchor subscription-based pricing structures across charging infrastructure, with three-tier pricing stratification across premium liquid-cooled systems, standard DC fast charging, and economy AC depot installations. Price differentiation hinges on certification tier—UL 2594 versus IEC 61851 compliance—and after-sales uptime guarantees. Cost compression in economy tiers intensifies as Chinese power module imports expand, though premium segments retain pricing power through grid-stabilizing bidirectional capabilities. Municipal transit agencies show highest price sensitivity due to public procurement constraints, while logistics providers prioritize total-cost-of-ownership over capital expenditure minimization.
Supply Chain Analysis
Hon Hai Precision Industry and Jabil Circuit hold contract manufacturing capacity for power conversion modules, with production gravity centering on China, Taiwan, and Mexico facilities. Silicon carbide substrates and copper busbars draw from concentrated raw material suppliers, exposing lead times to commodity volatility. Single-source vulnerability runs through liquid-cooled cable assemblies qualified to OEM specifications. Distribution runs through electrical contractor channels for commercial installations and direct utility procurement for highway corridor deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across North American and European logistics markets concentrates procurement leverage, shifting vendor selection criteria toward outcome-based uptime guarantees and away from hardware-centric specifications.
For Market Incumbents: Insulate proprietary connector ecosystems through accelerated NACS certification programs while deepening backward integration into silicon carbide module supply. Grid interconnection queue management capabilities represent the priority defensive lever as regional utility backlogs extend project timelines. Software-defined load balancing platforms must absorb hardware commoditization pressure from Chinese equipment imports. For New Entrants and Emerging Players: German commercial real estate charging penetration lags vehicle adoption curves, presenting white-space opportunity in workplace and retail destination installations. California multi-unit dwelling infrastructure faces split-incentive barriers that asset-light leasing structures can circumvent. Target municipal transit agencies with performance-guaranteed service agreements that shift capital burden to operational expenditure models. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed charging network operators pursuing platform rollup strategies. Long-term viability across the analysis window favors vendors with grid-integration software capabilities over pure hardware fabricators. Monitor FERC interconnection queue clearance rates as inflection indicator for deployment velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captive silicon carbide supply secures margin control against Chinese import volatility. |
| Software-Defined Charging Platform Launch | Dynamic load management layers decouple infrastructure ownership from recurring service revenue. |
| Grid Stabilization Service Contracting | Bidirectional V2G capabilities unlock utility revenue streams beyond energy sales. |
| Wireless Charging Corridor Pilot | Inductive pad deployment targets autonomous taxi operational risk in Singapore transit zones. |
| Multi-Standard Certification Investment | Parallel GB/T, CCS, and NACS qualification compresses hardware vendor geographic expansion timelines. |
Research Methodology
A standing panel of fleet electrification directors, utility interconnection planners, power electronics procurement leads, and municipal transit agency contract managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FERC interconnection filings, NEVI Formula Program disbursement records, EU AFIR regulatory texts, and SEC 10-K disclosures from listed charging network operators. Bottom-up station deployment counts triangulated against top-down infrastructure investment flow estimates.
Scenario-bracketing framed projections across the analysis window, modeling charging technology segments, station ownership archetypes, end-user procurement authority, and platform service tiers. CAGRs derived from installed base expansion curves, fleet electrification commitment timelines, and subsidy program authorization trajectories. Forecast inputs incorporated grid interconnection queue clearance assumptions and raw material supply elasticity parameters.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by automotive OEMs into captive charging infrastructure would shift outcomes substantially. Quarterly review of FERC queue clearance rates, EU AFIR tender award velocity, and silicon carbide spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Wireless Electric Vehicle Charger Market
Electric Vehicle Charging
Belgium Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Home Charger Market
Electric Vehicle Charging
Western Europe Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Charger Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Quick Charging Station Market
Electric Vehicle Charging
Electric Vehicle Grid Integration Solutions Market
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Global Electric Vehicle Charging As a Service Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market