
 Electric Vehicle (EV) Charging Station and Pile Operation and Management Market | 2026-2036
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market Insights
The split between premium smart-charging networks and basic commodity plug-in hardware is repositioning capital allocation across the value chain. Tesla sustains vertical integration from vehicle to charger, controlling end-to-end user experience. ABB specializes in high-power DC hardware for commercial and highway deployments. Blink Charging navigates a capital-light model focused on site-host partnerships.
Electric Vehicle Charging Station and Pile Operation and Management encompasses the deployment, maintenance, and software orchestration of conductive charging equipment ranging from 3.7 kW Level 1 residential units to 350 kW DC fast chargers with liquid-cooled cables. Its primary purpose is to deliver reliable, metered energy transfer to electric drivetrains while maximizing asset utilization through networked intelligence. DC Fast Charging commands the steepest infrastructure investment and tightest margin pools due to grid interconnection complexity and thermal management requirements. Network Management software captures recurring revenue streams as operators prioritize uptime guarantees and dynamic load balancing across sites. Wireless Charging remains nascent but occupies strategic R&D budgets among premium OEMs seeking seamless parking-lane integration.
The US Department of Transportation and EPA shape deployment through National Electric Vehicle Infrastructure formula funding and emissions standards that tighten fleet electrification timelines. China's MIIT and State Grid enforce GB/T connector standards and grid integration protocols that determine equipment certification and interconnection access. Stakeholders must weigh regulatory compliance costs against software monetization potential as charging transitions from hardware sale to service-platform economics.
Market Dynamics
Grid interconnection bottlenecks and 800V vehicle architectures are forcing charging infrastructure providers to re-engineer thermal management and power electronics for sustained 350kW+ output without utility-scale demand charges.
Growth Catalysts
- EPA fleet emissions standards:Corporate fleet operators face binding electrification timelines that accelerate depot and highway charging procurement cycles.
- Bi-directional V2G integration:Vehicle-to-grid protocols transform parked EVs into grid stabilization assets, creating new revenue streams for charging network operators.
- Copper-intensive cable assemblies:Liquid-cooled conductor technology enables sustained high-power delivery without the diameter penalties of conventional copper runs.
Market Restraints
- Transformer lead times:North American utility equipment backlogs extend site energization timelines to 18-24 months, freezing capital deployment.
- Silicon carbide wafer concentration:Power semiconductor substrate supply concentrates among Japanese and German substrate growers, constraining module availability.
- Permitting fragmentation:Municipal electrical code variations across US jurisdictions create compliance overhead that slows multi-site rollouts.
Strategic Opportunities
- India's FAME-II subsidy extension:The country's transport electrification push opens demand for 50kW DC urban hubs and intercity corridor networks.
- Autonomous vehicle charging:Self-parking EV fleets require robotic conductive arms and precision positioning infrastructure at fleet depots.
- ISO 15118-20 Plug and Charge:The communication standard enables automatic authentication and billing, removing friction from public charging sessions.
Industry Challenges
- High-voltage technician scarcity:Qualified electricians certified for 1000V DC systems command premium wages that inflate O&M costs.
- Multi-vendor interoperability testing:Charging management software must validate against dozens of vehicle OBC protocols, extending certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle (EV) Charging Station and Pile Operation and Management Market |
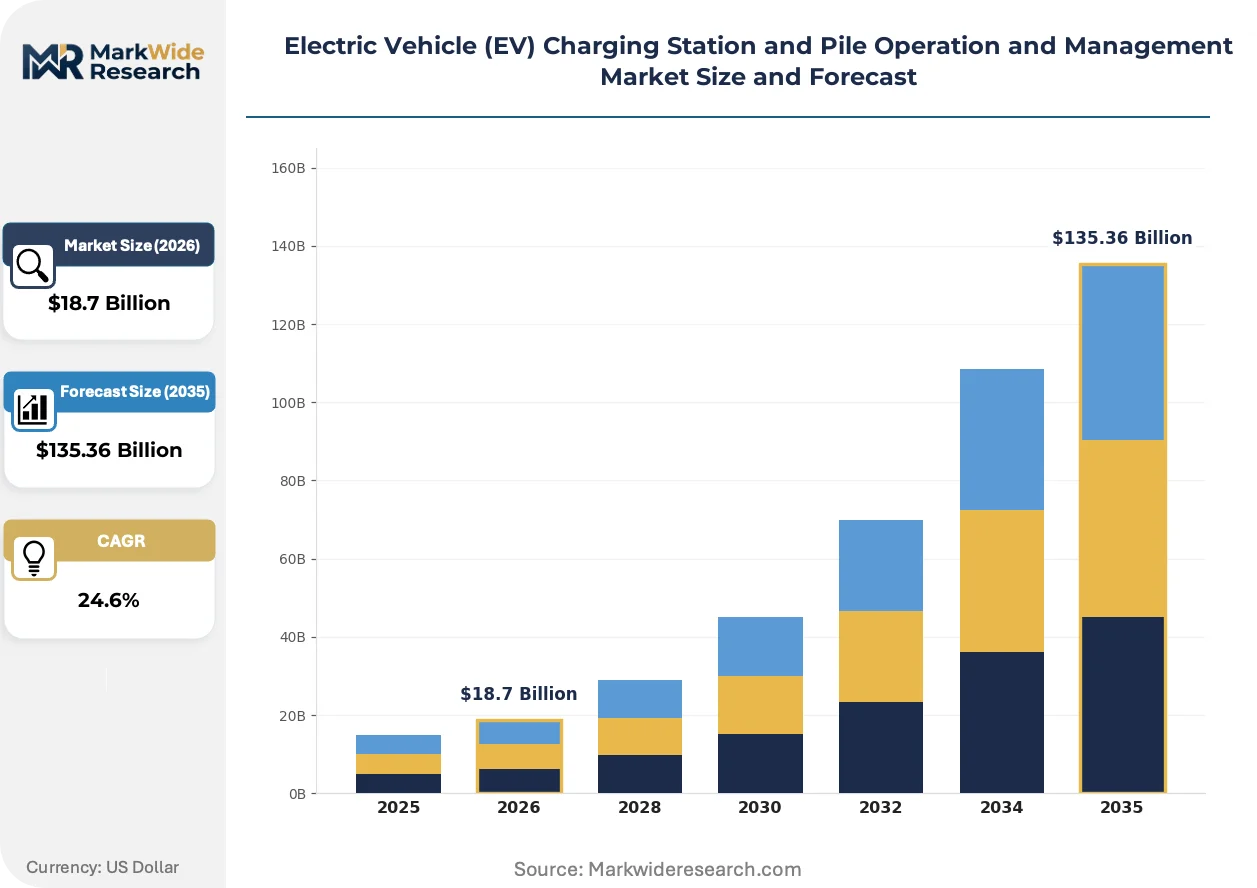
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charging Infrastructure Type: Level 1, Level 2, DC Fast Charging, Wireless Charging Installation Site: Public Locations, Residential Areas, Commercial Properties, Highway Stations Management Solution: Network Management, Billing Software, User Authentication, Remote Monitoring Charging Mode: AC Charge, DC Charge, Bidirectional Charging, Smart Charging |
| Companies Covered | ChargePoint Holdings, Tesla, Blink Charging, ABB, Shell Recharge, BP Pulse, State Grid, Star Charge, Tgood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market Trends and Innovations
Hardware commoditization and software monetization are diverging investment returns across the charging value chain, with capital rotating toward network orchestration platforms and away from pure equipment manufacturing.
Silicon carbide MOSFETs are absorbing switching losses that previously limited power density in DC fast chargers. Tier-1 suppliers are integrating these devices into 400kW rectifier modules for highway corridor deployment. The technology is absorbing market share from legacy IGBT architectures by enabling smaller footprints and reduced cooling overhead.
China's MIIT GB/T connector mandates and State Grid interconnection protocols are consolidating domestic equipment certification around unified standards. Foreign manufacturers must redesign power electronics and communication stacks to access the world's largest deployment market. European and North American suppliers are responding by establishing localized production and joint ventures with domestic license holders.
Fleet operators are consolidating charging procurement under single-network contracts that bundle hardware, installation, energy management, and uptime guarantees. Traditional equipment vendors face displacement by integrated service providers offering per-mile charging economics. This concentration is most visible in US and European last-mile delivery electrification programs where operators prioritize operational simplicity over capital ownership.
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market Segmentation
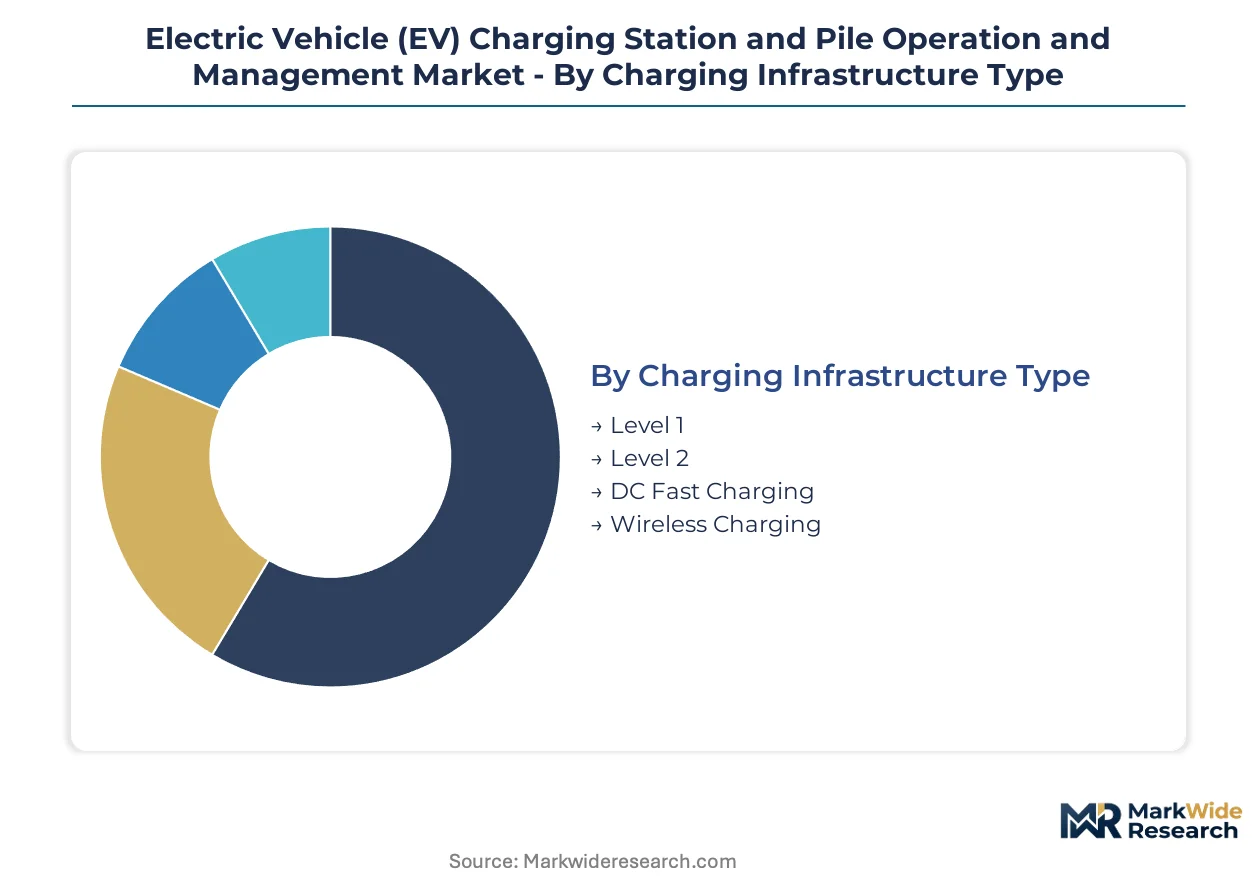
Segmentation in EV charging infrastructure separates hardware commoditization paths from software monetization opportunities. Understanding these divisions reveals where capital allocation concentrates across power electronics, site deployment, and network orchestration layers.
Charging Infrastructure Type:
Power delivery specifications determine thermal engineering requirements, grid interconnection complexity, and margin structure across the hardware stack.
- Level 1:3.7 kW residential units using standard household outlets require minimal installation but deliver slow replenishment cycles. Demand concentrates in apartment complexes and urban rental stock where panel upgrades prove cost-prohibitive, constrained by utility demand charge thresholds that discourage daytime charging.
- Level 2:7-22 kW AC equipment dominates workplace and retail destination installations with balanced capital cost and dwell-time compatibility. Fleet depot procurement in California and Germany drives volume, supported by IRA tax credits and EU Green Deal building mandates that mandate pre-wiring for new construction.
- DC Fast Charging:50-350 kW rectifier systems with liquid-cooled cables enable highway corridor and commercial fleet turnaround. Grid interconnection backlogs in Texas and Ontario constrain site energization timelines despite OEM pre-order commitments for 800V vehicle architectures.
- Wireless Charging:Inductive pad systems operating at 11-300 kW eliminate connector wear but suffer efficiency penalties and foreign object detection complexity. Premium OEM R&D budgets in South Korea and Germany pilot automated parking-lane integration for luxury vehicle segments.
Level 2 leads on scale; DC Fast Charging leads on momentum.
Installation Site:
Site economics vary dramatically across ownership structures, utilization patterns, and regulatory jurisdiction layers.
- Public Locations:Municipal parking structures and curbside installations serve transient users with high fragmentation across payment systems. European cities including Amsterdam and Copenhagen mandate public charging ratios per parking space, accelerating procurement cycles.
- Residential Areas:Single-family home garages and multi-unit dwelling parking stalls constitute the lowest-cost deployment channel. California Title 24 building codes and Germany's Building Energy Act mandate EV-ready infrastructure in new residential construction.
- Commercial Properties:Retail anchors, office campuses, and hospitality venues deploy charging as amenity and dwell-time extension. Singapore's Land Transport Authority grants commercial developers density bonuses for charging-ready parking provisions.
- Highway Stations:Corridors between metropolitan clusters require 350 kW+ capacity and battery buffering to manage grid demand charges. US NEVI formula funding prioritizes interstate-adjacent sites with 150-mile spacing requirements.
Commercial Properties lead on scale; Highway Stations lead on momentum.
Management Solution:
Software layers extract recurring revenue from hardware deployments through subscription and transaction-based monetization models.
- Network Management:Centralized platforms orchestrate load balancing, fault detection, and firmware updates across distributed assets. Operators in Norway and the Netherlands prioritize uptime guarantees exceeding 99 percent to maintain fleet contracts.
- Billing Software:Tariff engines process complex time-of-use rates, demand charge allocation, and roaming settlement between networks. ISO 15118-20 Plug and Charge protocols automate payment clearing without mobile application intermediation.
- User Authentication:RFID, mobile credentials, and vehicle-integrated identifiers manage session authorization and access control. China's State Grid mandates unified authentication stacks for interoperability across domestic charging networks.
- Remote Monitoring:Predictive maintenance algorithms reduce technician dispatch frequency through thermal sensor telemetry and power electronics degradation modeling. Indian operators deploy remote diagnostics to offset high-voltage technician scarcity in tier-2 cities.
Billing Software leads on scale; Remote Monitoring leads on momentum.
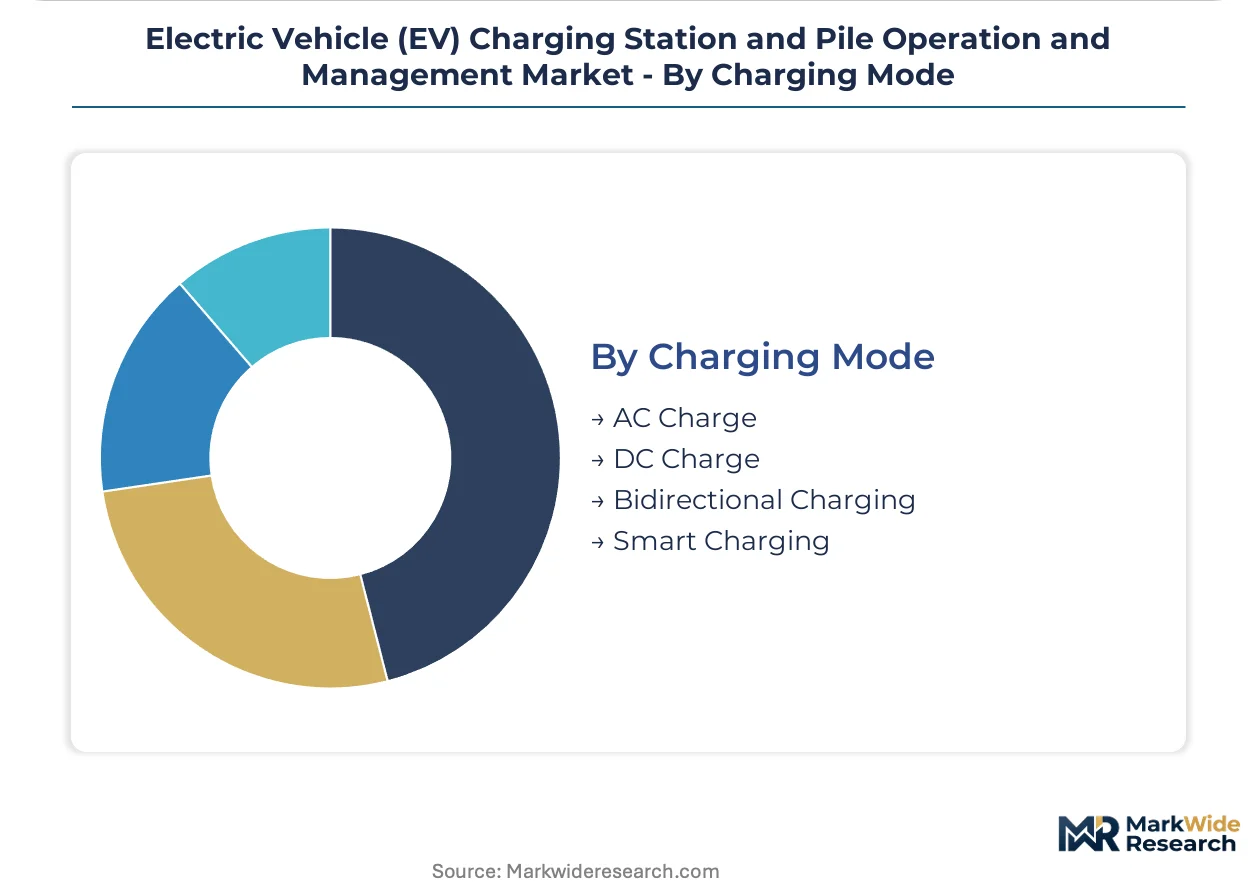
Charging Mode:
Power flow directionality and intelligence integration differentiate basic energy transfer from grid-interactive asset optimization.
- AC Charge:Onboard rectifier conversion from alternating current dominates residential and workplace applications with lowest capital intensity. Japanese CHAdeMO and European Type 2 standards maintain incompatible connector geometries despite IEC harmonization efforts.
- DC Charge:Offboard rectification delivers direct current at elevated voltages, bypassing vehicle onboard charger limitations. Silicon carbide MOSFET adoption in German and Japanese power modules enables 400 kW sustained output with reduced cooling overhead.
- Bidirectional Charging:Vehicle-to-grid and vehicle-to-home protocols transform parked EVs into distributed storage assets. Denmark's Energinet and California's CAISO pilot frequency regulation markets that compensate EV fleet operators for grid stabilization services.
- Smart Charging:Dynamic load management responds to real-time price signals, renewable generation availability, and building demand constraints. UK's OZEV mandates smart functionality for subsidy eligibility, accelerating software stack standardization.
AC Charge leads on scale; Bidirectional Charging leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's electrical engineering workforce anchors the world's densest charging infrastructure deployment. Germany's precision manufacturing talent sustains high-power hardware innovation. California's software engineering concentration drives network management platform development.
China
Fleet electrification mandates and urban air quality targets accelerate charging procurement across 30 provincial-level divisions. MIIT enforces GB/T connector standards and grid interconnection protocols that determine equipment certification access. Shenzhen and Shanghai concentrate deployment density through State Grid and Star Charge networks serving the world's largest EV parc.
United States
Corporate fleet commitments and IRA tax credits reshape capital allocation toward highway corridor and depot installations. NHTSA and EPA emissions standards tighten binding electrification timelines for commercial operators. Texas and California face transformer lead times extending site energization to 18-24 months despite NEVI formula funding allocations.
Germany
Industrial automotive supply chains and autobahn freight electrification drive 350kW+ hardware demand. EU Green Deal building mandates and KBA vehicle-type approvals synchronize charging infrastructure with fleet turnover cycles. Bavaria and Baden-Württemberg host ABB and Siemens production clusters supplying liquid-cooled cable assemblies across European highway networks.
India
FAME-II subsidy extension and commercial fleet electrification targets open demand for 50kW DC urban hubs. CEA grid codes and BIS equipment standards determine interconnection access and certification pathways. Maharashtra and Karnataka concentrate early deployment through Tata Power and Adani TotalEnergies networks in Mumbai and Bangalore metropolitan corridors.
United Kingdom
ULEZ expansion and corporate fleet decarbonization commitments accelerate workplace and destination charging procurement. OZEV mandates smart functionality eligibility for subsidy programs, standardizing software stack requirements. London and the Southeast concentrate network management platform development through BP Pulse and Shell Recharge operations.
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market Competitive Landscape
Top-tier vendors anchor integrated service platforms, while equipment specialists occupy component supply tiers. The vendor base stratifies across three structural layers: automotive OEMs with captive charging networks, pure-play charging network operators, and power electronics hardware fabricators. Dominant competitive moves include strategic site-host partnerships that transfer capital ownership to property operators, and silicon carbide supply agreements that secure power semiconductor access for 400kW+ rectifier development.
Within the integrated platform tier, Tesla and ChargePoint Holdings exemplify divergent capital intensity models. Tesla's closed-loop ecosystem extends from vehicle manufacturing through charging infrastructure ownership, while ChargePoint Holdings operates a capital-light network anchored by site-host partnership structures. Among power electronics specialists, ABB occupies a position representing European precision manufacturing concentration in high-power DC hardware. Chinese market density is reflected through State Grid and Star Charge, which anchor deployment scale within the world's largest EV market through standardized GB/T infrastructure rollouts.
| Leading Market Players |
|---|
| ChargePoint Holdings |
| Tesla |
| Blink Charging |
| ABB |
| Shell Recharge |
| BP Pulse |
| State Grid |
| Star Charge |
| Tgood |
| Others |
Pricing and Supply Chain Analysis
Backward integration into silicon carbide power modules anchors both supply security and pricing power for DC fast charger manufacturers competing on 350kW+ output specifications. Tesla's captive semiconductor sourcing and ABB's substrate supply agreements with Japanese wafer growers illustrate how upstream control over switching devices determines margin retention against commodity hardware competitors.
Pricing Analysis
Bundled service contracts separating hardware from energy management subscriptions now dominate fleet procurement, with per-mile charging economics displacing capital purchase models. Pricing stratifies across premium smart-charging networks with 99 percent uptime guarantees, standard DC hardware with basic network access, and economy Level 2 units for residential pre-wiring mandates. Cost compression in liquid-cooled cable assemblies is intensifying because copper-intensive conductor technology commoditizes faster than power electronics differentiation. Fleet operators show least price sensitivity for highway corridor sites with grid buffering, while workplace destination charging faces acute margin pressure from IRA tax credit arbitrage.
Supply Chain Analysis
China's MIIT domestic-content mandates for GB/T connector certification are reshaping sourcing patterns, forcing European and North American suppliers into joint ventures with domestic license holders. Manufacturing concentrates in China, Germany, and Japan for power modules and liquid-cooled assemblies. Silicon carbide substrates, copper conductors, and high-voltage capacitors constitute critical input dependencies. Single-source vulnerability in Japanese and German wafer growers constrains 400kW rectifier module availability. Distribution runs through tier-1 automotive suppliers and direct utility partnerships for highway corridor deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications now dominate procurement criteria as 800V vehicle architectures and fleet uptime guarantees filter out subscale operators. This late-cycle dynamic favors incumbents with certified technician networks and proven grid interconnection track records over capital-light hardware vendors.
For Market Incumbents: Hedge silicon carbide supply exposure through long-term substrate offtakes with Japanese and German wafer growers before capacity constraints harden. Consolidate technician certification programs to offset high-voltage electrician scarcity inflating O&M costs. Defensive positioning against Chinese equipment vendors requires GB/T licensing partnerships rather than pure export strategies. For New Entrants and Emerging Players: India's FAME-II subsidy extension opens a window for 50kW DC urban hub deployment in tier-2 metropolitan corridors where Tata Power and Adani TotalEnergies networks remain underpenetrated. Target autonomous vehicle fleet depots requiring robotic conductive arm infrastructure as the most penetrable white space. Lead with ISO 15118-20 Plug and Charge integration to bypass mobile application friction in public charging sessions. For Investors and Strategic Acquirers: Roll-up economics work for regional network operators with site-host lease portfolios because fragmented municipal permitting creates localization moats against national platform expansion. Five-to-ten year viability hinges on recurring revenue share from energy management software rather than hardware margin capture. Watch NEVI formula funding disbursement velocity as the signal indicating whether transformer lead times or capital availability constrains deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures Japanese wafer substrate access for 400kW rectifier development against module shortages. |
| GB/T Certification Partnership | Unlocks China's MIIT equipment approval for world's largest EV deployment market access. |
| Fleet Service Contract Consolidation | Bundles hardware, installation, and uptime guarantees into per-mile economics for delivery operators. |
| High-Voltage Technician Network | Builds certified 1000V DC labor pools to offset wage inflation and reduce dispatch frequency. |
| Bi-Directional V2G Integration | Positions parked EVs as CAISO frequency regulation assets creating new network revenue streams. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with charging network operators, utility interconnection planners, fleet procurement directors, and power electronics engineers against secondary validation. SEC filings from ChargePoint Holdings and Blink Charging, EPA NEVI funding disbursement records, MIIT equipment certification databases, and IEA EV outlook publications anchored volume estimates. Bottom-up site deployment counts triangulated against top-down energy demand projections.
Historical reference periods spanning pre-IRA, IRA implementation, and post-Inflation Reduction Act phases anchored the forecast window to policy discontinuities. The analytical framework modeled charging infrastructure type, installation site economics, management solution revenue models, and regional regulatory clusters across the projection horizon. CAGRs derived from equipment shipment trajectories, fleet electrification timelines, and grid interconnection capacity expansion. Silicon carbide MOSFET adoption curves and 800V vehicle architecture penetration served as technology-specific forecast inputs.
Revisions become necessary when transformer lead times extend beyond utility planning horizons, when GB/T standard updates force hardware redesign cycles, or when V2G protocol commercialization accelerates faster than grid code harmonization. Forecasts reflect documented assumptions about subsidy continuity, semiconductor supply normalization, and technician certification pipeline expansion. A small set of named triggers—NEVI disbursement velocity, MIIT certification queue depth, and CAISO market participation rules—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
Solar-Based Electronic Vehicle Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
Italy Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
United Kingdom Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
North America Electric Vehicle Charging Cable Market
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
EV Charging Management Software Platform Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
Bidirectional Charging Units Market