
 Wireless Charging Market | 2026-2036
Wireless Charging Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Charging Market Intelligence
Qi2 magnetic alignment certification is reorganizing supplier hierarchies as interoperability becomes a baseline procurement requirement. Samsung Electronics leverages its semiconductor foundry scale to captive-produce power management ICs for wireless charging modules. Qualcomm Incorporated anchors premium automotive contracts through its WiPower platform integration with vehicle infotainment systems. Texas Instruments competes on precision analog front-end designs that reduce coil-to-coil positioning sensitivity.
Wireless charging transmits electrical energy across air gaps through resonant inductive coupling, typically operating at frequencies between 110–205 kHz for near-field applications with power transfer efficiency ranging from 70% to 85% depending on coil alignment and distance. The technology eliminates exposed conductive contacts in consumer electronics, medical implants, and sealed automotive assemblies where moisture ingress or mechanical wear would compromise reliability. Inductive technology occupies the dominant revenue position due to its maturity in smartphone and wearable applications, while magnetic resonance extends range and positional tolerance for automotive underbody and furniture-embedded installations. Radio frequency technology represents the fastest-expanding segment for low-power IoT sensors and hearing aids where milliwatt-level trickle charging eliminates battery replacement cycles.
The Federal Communications Commission in the United States governs RF emissions from wireless power transmitters under Part 18 rules, while the European Telecommunications Standards Institute harmonizes cross-border spectrum allocation for resonant charging systems. China's Ministry of Industry and Information Technology mandates GB/T standard compliance for electromagnetic radiation exposure limits in public-access charging infrastructure. India's Telecom Regulatory Authority has opened consultation on unlicensed spectrum bands for wireless power transmission, signaling forthcoming licensing frameworks for commercial deployment. Stakeholders must monitor regulatory divergence between sub-6 GHz and 6–100 GHz spectrum allocations, as this choice will determine which technology architectures achieve multi-region scale without redundant hardware redesigns.
Market Dynamics
Qi2 magnetic alignment certification is reorganizing supplier hierarchies as interoperability becomes a baseline procurement requirement. This standardization pressure is compressing margins for uncertified module producers while rewarding foundry-scale semiconductor integration.
Growth Catalysts
- Automotive OEM Integration:Premium and mid-tier vehicle lines now embed wireless charging pads as standard equipment, creating captive demand for automotive-grade power management ICs.
- EU Radio Equipment Directive:Tightened electromagnetic compatibility requirements for cross-border shipments are filtering out non-compliant suppliers and consolidating procurement toward certified vendors.
- Resonant Inductive Coupling:Operating frequencies between 110–205 kHz now deliver 70% to 85% power transfer efficiency, eliminating exposed conductive contacts in moisture-sensitive applications.
Market Restraints
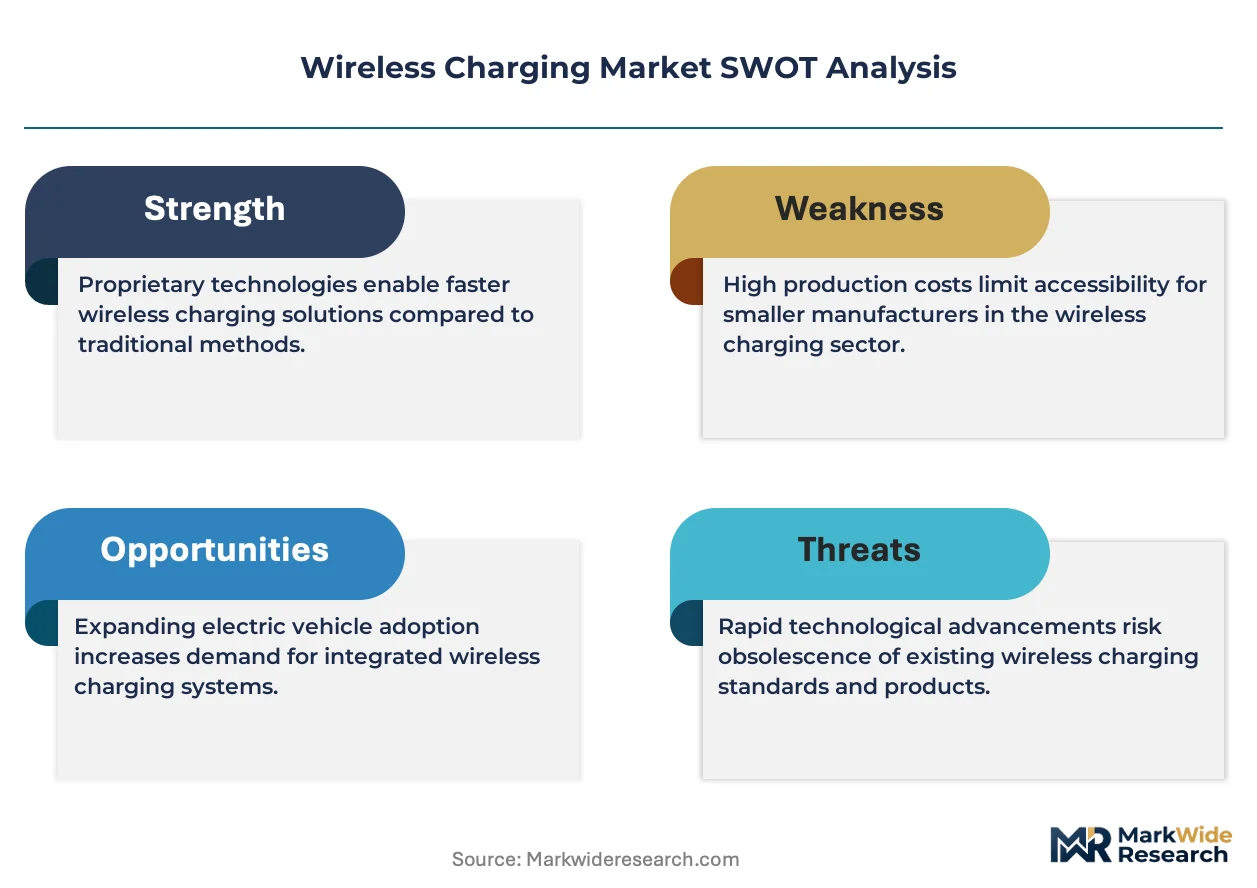
- Copper Coil Input Volatility:Litz wire and ferrite core materials face price swings tied to mining output from Chile and the Democratic Republic of Congo.
- South Korean Supply Concentration:Samsung Electronics and domestic component suppliers anchor a dense supplier ecosystem that creates single-point vulnerability for global module procurement.
- GB Standard Compliance Costs:China's MIIT mandates electromagnetic radiation exposure limits that require redundant testing protocols for public-access infrastructure deployments.
Strategic Opportunities
- India Unlicensed Spectrum Opening:TRAI consultation on wireless power transmission bands signals forthcoming licensing frameworks for commercial deployment in the world's second-largest smartphone market.
- RF Trickle Charging Convergence:Radio frequency technology paired with ultra-low-power IoT sensors eliminates battery replacement cycles in hearing aids and environmental monitors.
- Furniture-Embedded Magnetic Resonance:Extended range and positional tolerance enable under-table installations in hospitality and corporate workspace fit-outs.
Industry Challenges
- Qi2 Certification Timeline Compression:Magnetic alignment testing protocols require six-to-nine-month validation cycles that delay product launches and tie up engineering resources.
- Cross-Spectrum Hardware Redesign:Divergence between sub-6 GHz and 6–100 GHz spectrum allocations across the FCC, ETSI, and MIIT forces redundant RF front-end architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Charging Market |
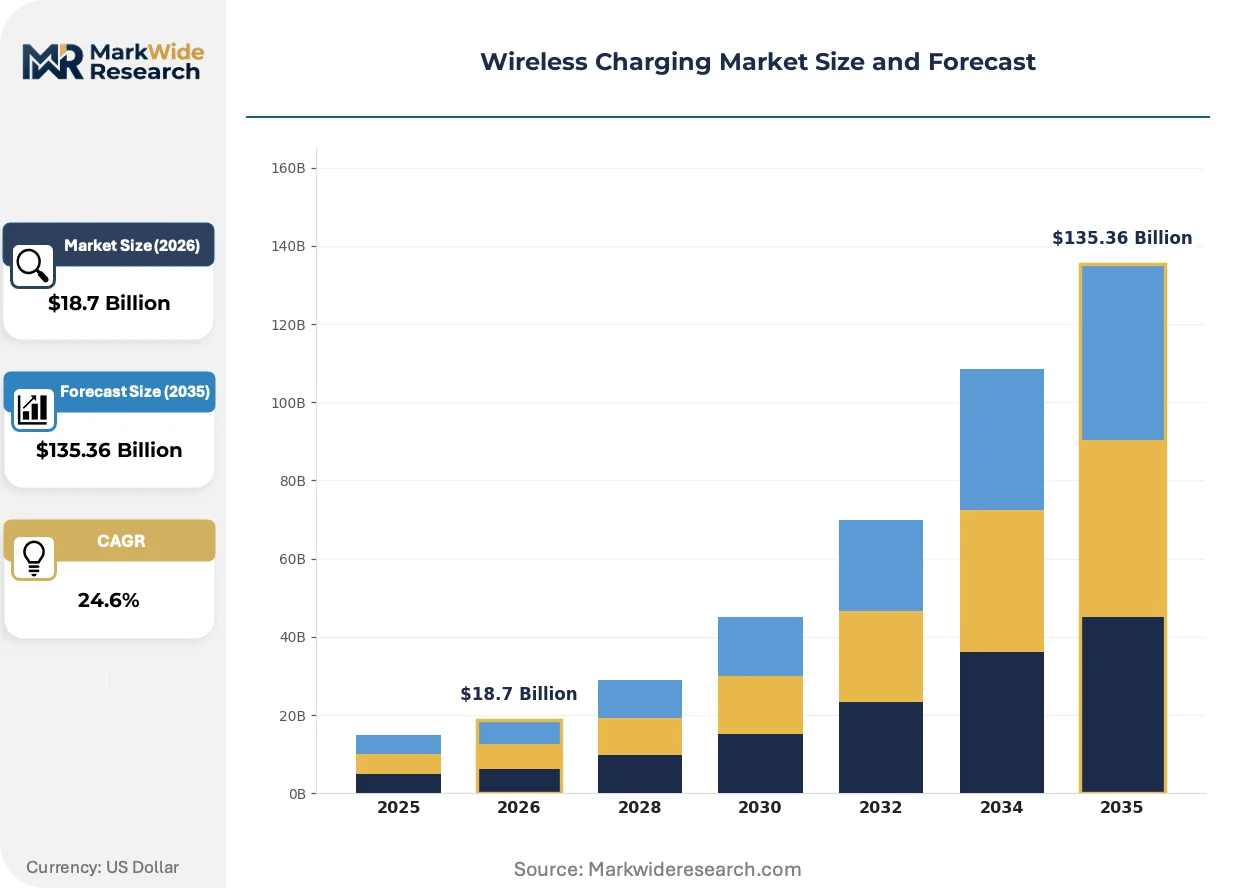
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphone, Wearable, Laptop, Electric Vehicle Technology: Inductive, Magnetic Resonance, Radio Frequency, Capacitive End User: Consumer Electronics, Automotive, Healthcare, Industrial Installation: Freestanding, Embedded, Integrated, Portable |
| Companies Covered | Samsung Electronics, Qualcomm Incorporated, Texas Instruments, WiTricity Corporation, Powermat Technologies, Belkin International, Apple, Energous Corporation, Ossia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Charging Market Strategic Shifts & Innovations
Wireless power architectures are fragmenting across frequency bands and power classes, forcing suppliers to place parallel bets on inductive, resonant, and RF technologies rather than consolidating behind a single standard.
Modular coil array designs are decomposing the traditional single-transmitter architecture into distributed pad configurations. Automotive Tier 1 suppliers are adopting these arrays for vehicle cabin integration, enabling simultaneous multi-device charging without precise user positioning. This decomposition is compressing the addressable market for fixed-position smartphone pads while expanding the specification range for adaptive systems.
ETSI harmonization of cross-border spectrum allocation for resonant charging systems is standardizing frequency bands across EU member states. This regulatory convergence reduces hardware SKU complexity for manufacturers serving multiple European markets. Medical device manufacturers are responding fastest, redesigning implantable charging interfaces around the harmonized bands to streamline CE marking pathways.
Buyer preference is hardening around interoperability certification as a non-negotiable procurement filter. Enterprise IT managers and fleet vehicle purchasers are disqualifying non-Qi2 modules from vendor shortlists, displacing proprietary fast-charge protocols that locked users into single-brand ecosystems. South Korean consumer electronics retailers report the strongest certification-driven preference compression, with uncertified products losing shelf placement regardless of price positioning.
Wireless Charging Market Segmentation
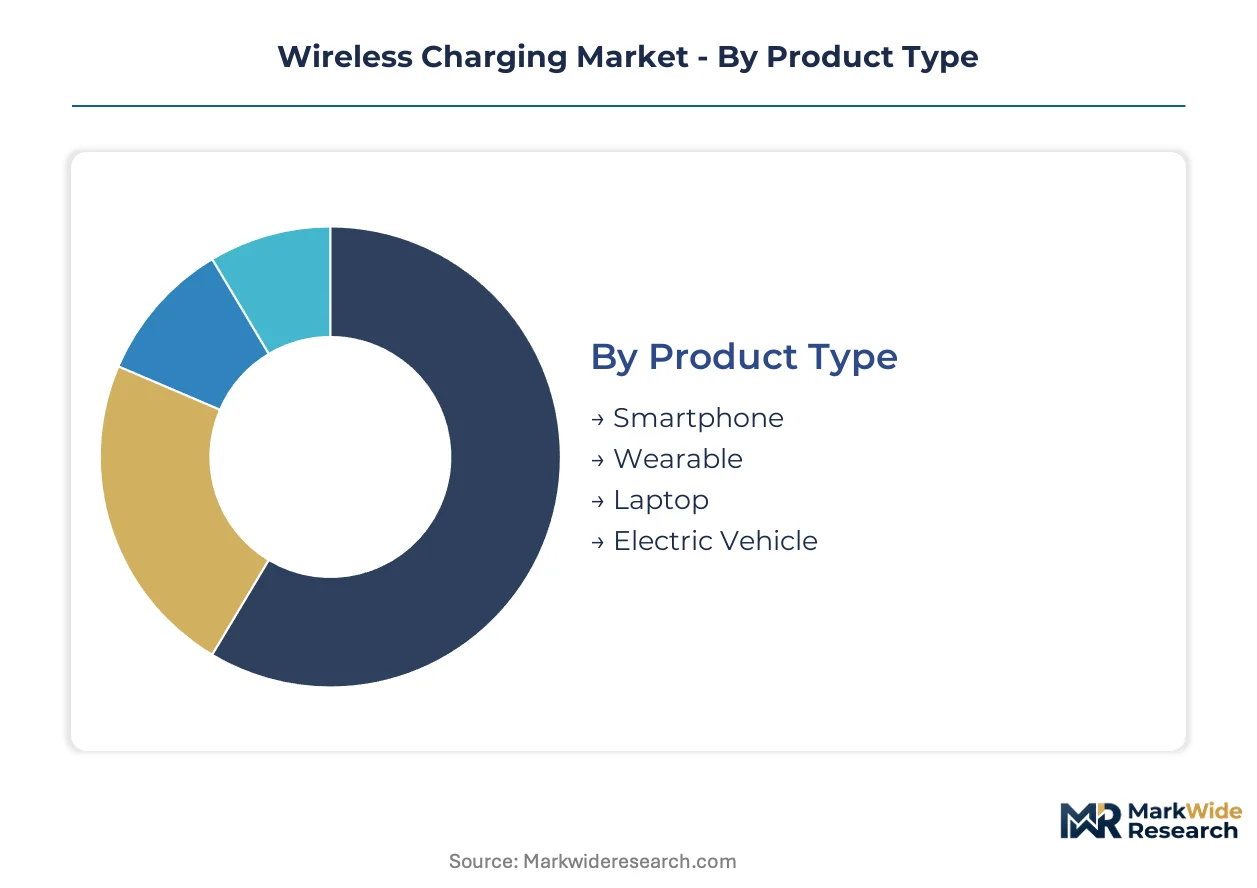
Wireless charging architectures fragment across power classes, frequency bands, and physical form factors. Each segmentation dimension carries distinct procurement channels, certification requirements, and margin structures that determine supplier positioning.
Product Type:
Smartphone pads dominate retail and e-commerce channels, while automotive and laptop modules flow through direct OEM procurement. Wearable charging docks concentrate in consumer electronics specialty retail.
- Smartphone:Qi2-certified pads operate at 110–205 kHz with coil-to-coil efficiency between 70% and 85%. Demand concentrates in South Korea and China where Samsung Electronics and domestic suppliers anchor dense manufacturing ecosystems, constrained by six-to-nine-month magnetic alignment certification cycles.
- Wearable:Compact coil designs accommodate smartwatches and earbuds with reduced power budgets. Healthcare procurement channels in Germany and Japan are driving medical-grade waterproofing specifications for continuous glucose monitors and hearing aids.
- Laptop:Higher-wattage implementations require active cooling and multi-coil arrays. Corporate IT refresh cycles in the United States are standardizing 65W wireless docking stations for hybrid workspace deployments.
- Electric Vehicle:Underbody and cabin-embedded systems leverage magnetic resonance for extended positional tolerance. Automotive Tier 1 suppliers in Germany and Japan are integrating these modules with vehicle infotainment architectures.
Smartphone dominates installed base. Electric Vehicle is where expansion concentrates.
Technology:
Inductive architectures command the highest production volumes and lowest unit costs. Magnetic resonance and RF technologies occupy premium positioning with elongated development cycles.
- Inductive:Mature near-field coupling at standardized frequencies enables mass manufacturing with established ferrite core supply chains. Consumer electronics OEMs in China and South Korea source these modules through captive semiconductor foundries.
- Magnetic Resonance:Extended air-gap tolerance enables furniture-embedded and automotive underbody installations without precise user positioning. Hospitality fit-out contractors in the United States and United Arab Emirates are specifying these systems for premium workspace and hotel deployments.
- Radio Frequency:Harvests ambient RF energy for milliwatt-level trickle charging of IoT sensors and medical implants. India's TRAI consultation on unlicensed spectrum bands is creating licensing pathways for commercial deployment in environmental monitoring networks.
- Capacitive:Electric field coupling eliminates magnetic components for ultra-thin form factors. Japanese component suppliers are developing these for card-style wearables and smart card applications.
Inductive captures volume leadership. Radio Frequency is climbing the fastest as ultra-low-power IoT deployments scale.
End User:
Consumer electronics channels emphasize retail certification and brand interoperability. Automotive and healthcare procurement prioritizes electromagnetic compliance and reliability testing.
- Consumer Electronics:Qi2 interoperability certification functions as a non-negotiable filter for enterprise IT and fleet vehicle procurement. South Korean retailers report uncertified products losing shelf placement regardless of price positioning.
- Automotive:OEMs embed charging pads as standard equipment across premium and mid-tier vehicle lines, creating captive demand for automotive-grade power management ICs. Germany's KBA and Japan's METI govern electromagnetic compatibility for cabin installations.
- Healthcare:Implantable devices require sealed assemblies where moisture ingress would compromise reliability. ETSI harmonization of resonant charging bands is streamlining CE marking pathways for EU medical device manufacturers.
- Industrial:Sealed charging interfaces eliminate exposed contacts in food processing and chemical manufacturing environments. The United States OSHA guidelines influence ingress protection specifications for factory-floor deployments.
Consumer Electronics holds the largest addressable base. Healthcare is gaining share fastest as implantable device charging interfaces proliferate.
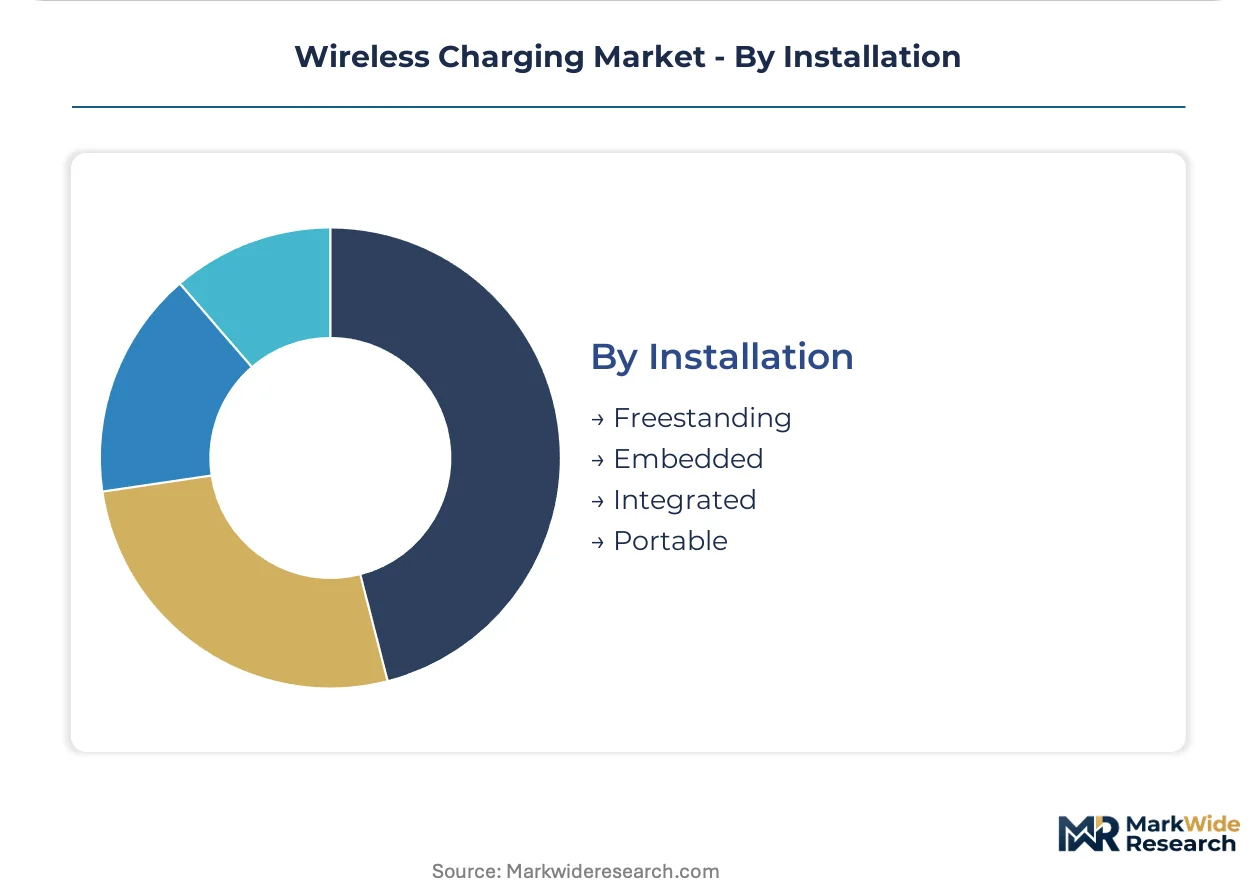
Installation:
Freestanding and portable units move through retail and e-commerce with minimal installation complexity. Embedded and integrated systems require construction-phase coordination and electrical contractor certification.
- Freestanding:Desktop and countertop pads require no electrical modification, enabling rapid consumer adoption. Mass-market retailers in the United States and United Kingdom dominate distribution.
- Embedded:Furniture and architectural integration demands coordination with millwork contractors and electrical inspectors. Corporate workspace fit-out specialists in Germany and the Netherlands are standardizing under-table coil arrays.
- Integrated:Vehicle cabin and appliance-embedded modules ship as factory-installed components. Automotive OEMs in Japan and Germany specify these through Tier 1 supplier contracts with multi-year lock-in periods.
- Portable:Battery-backed charging pads address travel and outdoor use cases with reduced power output. Airport retail and travel goods channels in the United Arab Emirates and Singapore concentrate distribution.
Freestanding dominates unit shipments. Embedded is where specification value is concentrating as hospitality and corporate workspace fit-outs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement in Germany tolerates 15-20% cost premiums for automotive-grade certification, while Indian smartphone accessory buyers squeeze margins below 8% through unorganized retail channels. South Korean consumers demand Qi2 interoperability as a baseline, rejecting proprietary protocols regardless of price positioning.
United States
FCC Part 18 rules govern RF emissions from wireless power transmitters, creating compliance thresholds that filter out uncertified module producers. Corporate IT refresh cycles in Austin and Seattle are standardizing 65W wireless docking stations for hybrid workspace deployments. The hospitality sector in New York and Los Angeles is specifying furniture-embedded magnetic resonance systems for premium hotel fit-outs.
Germany
KBA electromagnetic compatibility mandates for vehicle cabin installations are consolidating procurement toward Tier 1 suppliers with multi-year OEM lock-in contracts. ETSI harmonization of resonant charging bands is streamlining CE marking pathways for medical device manufacturers in Munich and Stuttgart. Corporate workspace specialists in Berlin and Frankfurt are adopting under-table coil arrays as standard specification.
South Korea
MFDS radiation exposure limits for medical implant charging interfaces are accelerating healthcare-grade module development in Seoul. Samsung Electronics and domestic component suppliers anchor a dense supplier ecosystem in Suwon and Pyeongtaek that creates single-point vulnerability for global procurement. Consumer electronics retailers in Seoul report uncertified products losing shelf placement regardless of price positioning.
China
MIIT GB/T standard compliance for electromagnetic radiation exposure limits requires redundant testing protocols for public-access infrastructure deployments. Yangtze River Delta manufacturing clusters in Shanghai and Suzhou are captive-producing power management ICs through semiconductor foundry scale. Domestic OEMs in Shenzhen are embedding Qi2-certified pads as standard equipment across mid-tier smartphone lines.
India
TRAI consultation on unlicensed spectrum bands for wireless power transmission is signaling forthcoming licensing frameworks for commercial deployment. Unorganized retail channels in Mumbai and Delhi squeeze smartphone accessory margins below 8% through price-first procurement. Environmental monitoring network pilots in Bangalore and Hyderabad are testing RF trickle charging for ultra-low-power IoT sensors.
Wireless Charging Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure where premium automotive contracts flow to semiconductor-integrated suppliers while commodity smartphone pads concentrate in foundry-scale fabricators. The vendor base spans three strategic tiers: captive-integrated electronics conglomerates, precision analog specialists, and resonant technology pure-plays. Dominant competitive moves include Qi2 certification acceleration and automotive Tier 1 supplier contract lock-in.
Within the captive-integrated tier, Samsung Electronics exemplifies foundry-scale semiconductor control over power management IC supply chains. Texas Instruments occupies a position among precision analog specialists competing on coil-to-coil positioning sensitivity reduction. WiTricity Corporation anchors the resonant technology pure-play segment focused on extended air-gap tolerance applications.
| Leading Market Players |
|---|
| Samsung Electronics |
| Qualcomm Incorporated |
| Texas Instruments |
| WiTricity Corporation |
| Powermat Technologies |
| Belkin International |
| Apple |
| Energous Corporation |
| Ossia |
| Others |
Cost & Logistics Intelligence
Qi2 magnetic alignment certification gates supplier qualification and price differentiation simultaneously, compressing margins for uncertified module producers while rewarding foundry-scale semiconductor integration with premium positioning in automotive and enterprise procurement channels.
Pricing Analysis
After-sales service contracts and extended warranty tiers drive lifetime value in automotive and medical implant applications. Three-tier pricing structure across premium Qi2-certified automotive modules, standard consumer pads, and economy unbranded accessories dominates procurement. Price differentiation hinges on certification grade and coil-to-coil positioning sensitivity. Cost compression in economy smartphone accessories is intensifying because unorganized retail channels in India and Southeast Asia squeeze margins below sustainable levels. Fleet vehicle purchasers and hospital procurement committees demonstrate lowest price sensitivity, while mass-market smartphone accessory buyers exhibit extreme elasticity.
Supply Chain Analysis
South Korea and China anchor power management IC fabrication and coil module assembly. The supply chain draws from Chilean copper for Litz wire, Congolese ferrite cores, and Taiwanese semiconductor foundry capacity. Single-source vulnerability concentrates in Samsung Electronics' captive production ecosystem around Suwon and Pyeongtaek. Distribution runs through direct OEM contracts for automotive and laptop modules, with retail and e-commerce channels handling smartphone and wearable accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless charging represents a high-growth disruption propelled by Qi2 standardization collapsing proprietary ecosystem lock-ins and forcing interoperability as a baseline procurement filter across automotive, healthcare, and enterprise IT verticals.
For Market Incumbents: Fortify automotive Tier 1 supplier relationships through multi-year power management IC supply agreements with embedded minimum volume commitments. Accelerate Qi2 certification pipelines to six-month validation cycles before competitor modules achieve qualification. Deepen backward integration into ferrite core sourcing to offset copper and rare earth price volatility from Chilean and Congolese mining output.
For New Entrants and Emerging Players: Lead with RF trickle charging modules for ultra-low-power IoT sensors in India's forthcoming unlicensed spectrum regime. Target environmental monitoring networks and hearing aid manufacturers in Bangalore and Hyderabad pilot programs. Pursue white-label partnerships with hospitality fit-out contractors specifying furniture-embedded magnetic resonance systems.
For Investors and Strategic Acquirers: India's TRAI spectrum consultation reshapes the acquisition landscape by creating first-mover licensing pathways for RF charging pure-plays. Long-term viability centers on resonant technology architectures spanning sub-6 GHz and 6–100 GHz bands without redundant hardware redesigns. Monitor ETSI-FCC-MIIT spectrum allocation convergence as the critical inflection signal for multi-region scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Qi2 Certification Acceleration | Compresses validation cycles to capture automotive OEM pad integration windows. |
| Automotive Tier 1 Contract Lock-In | Secures multi-year power management IC supply agreements with infotainment integrators. |
| Resonant Technology Platform Expansion | Extends air-gap tolerance for furniture-embedded and underbody vehicle installations. |
| RF Spectrum Licensing Positioning | Establishes first-mover advantage in India's unlicensed wireless power transmission bands. |
| Foundry-Scale Semiconductor Integration | Captive power management IC production reduces coil-to-coil positioning sensitivity costs. |
Research Approach
A standing panel of automotive Tier 1 supplier procurement officers, semiconductor foundry operations managers, medical device regulatory affairs leads, and hospitality fit-out specification consultants provided ongoing calibration. Primary interviews combined with secondary validation from FCC Part 18 filings, ETSI harmonization documents, MIIT GB/T standard publications, and customs trade data for ferrite core and Litz wire shipments. Bottom-up module shipment estimates triangulated against top-down automotive production and smartphone assembly forecasts.
Consistency checks validated volume and value outputs against external benchmarks including vehicle infotainment system integration rates, Qi2 certification database entries, and resonant charging patent filings. The analytical framework modeled product type, technology architecture, end-user vertical, and installation complexity across the projection horizon. CAGRs derived from segmented growth rate synthesis incorporating automotive OEM pad standardization timelines, healthcare implant charging interface proliferation, and RF IoT sensor deployment curves.
Forecasts assume regulatory continuity in FCC Part 18, ETSI resonant band harmonization, and MIIT GB/T exposure limits; material policy shifts in spectrum allocation or electromagnetic compatibility thresholds would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Copper in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Electric Vehicle 800-Volt Charging Pile Market
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
E-Bike Charging Station Market
Electric Vehicle Charging
Europe Electric Vehicle Chargers Market
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Global EV Charging Piles Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market