
 Electric Vehicle (EV) Charging Connector Market | 2026-2036
Electric Vehicle (EV) Charging Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle (EV) Charging Connector Market Foresight
IEC 62196-2 certification for AC charging interfaces is collapsing the supplier base eligible for European public tenders. Siemens AG anchors its position through captive testing laboratories that accelerate qualification timelines. Mennekes Elektrotechnik GmbH & Co. KG dominates type 2 connector supply across German OEM platforms. Bosch GmbH leverages automotive heritage to extend into integrated charging module production.
An electric vehicle charging connector is an electromechanical coupling device engineered to transmit electrical energy between a charging station and a vehicle battery, typically rated for currents between 16A and 500A depending on charging mode, with contact materials plated in silver or nickel alloys to resist arcing degradation. Its primary commercial purpose is to establish safe, standardized power transfer across diverse grid-to-vehicle interfaces. CCS connectors lead deployment in European and North American public networks due to regulatory harmonization, while DC fast charging connectors capture expanding margin pools as fleet operators prioritize throughput over residential convenience. Smart charging technology segments are gaining structural traction as utilities deploy load-balancing protocols that require bidirectional communication hardware embedded in connector assemblies.
The US EPA and NHTSA coordinate fuel economy credits that indirectly mandate charging infrastructure density, while the EU F-Gas Regulation and CE marking framework constrain thermal management materials used in high-amperage connector housings. China's GB/T standard and NMPA certification requirements create a parallel qualification track that fragments interoperability for connectors serving the domestic market. Stakeholders must monitor which certification regimes achieve bilateral recognition before committing tooling investments for next-generation connector architectures.
Market Dynamics
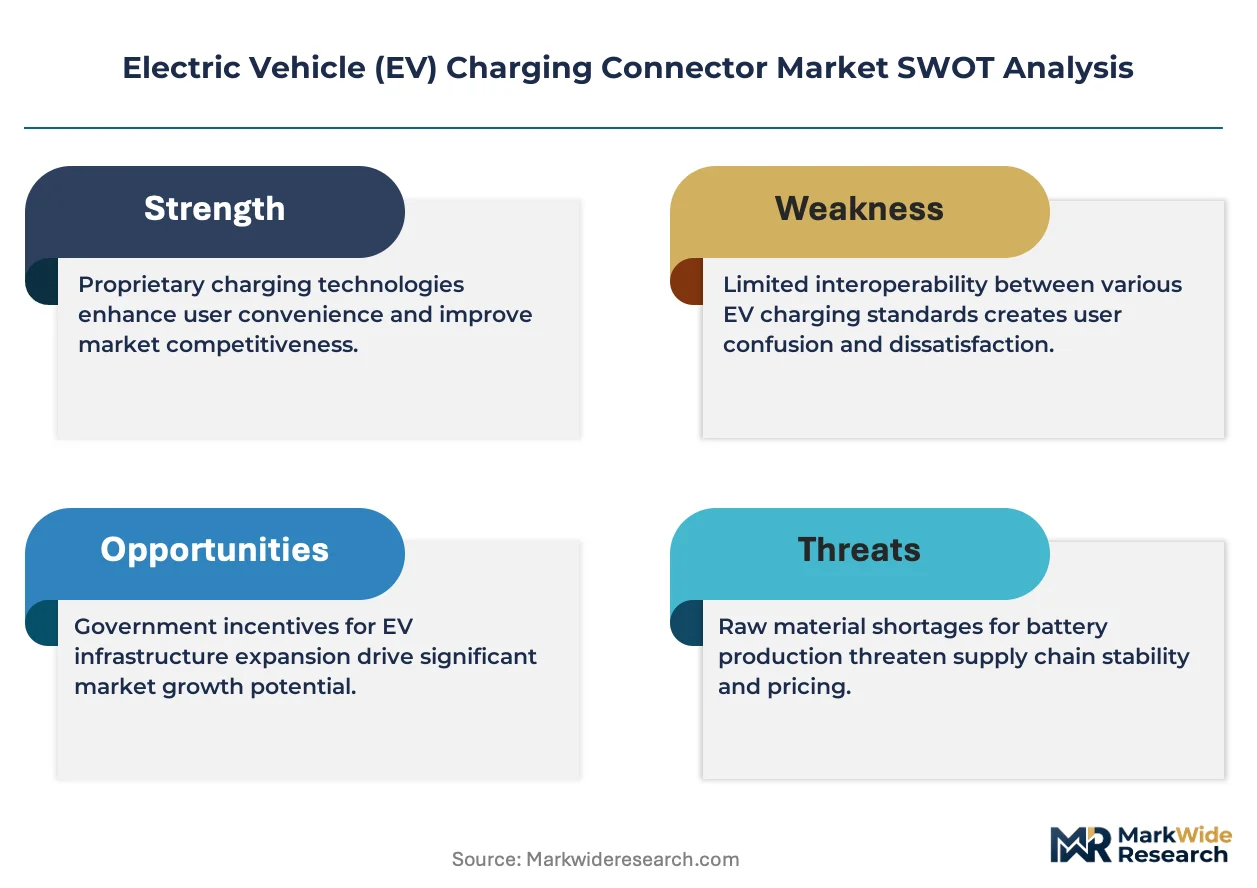
Connector standardization wars between CCS, NACS, and GB/T architectures are forcing suppliers to maintain redundant tooling lines while awaiting regulatory clarity on interoperability mandates.
Growth Catalysts
- US EPA fuel economy credits:The coordinated credit system with NHTSA indirectly mandates charging infrastructure density, compelling OEMs to pre-install CCS-compatible inlets on new vehicle platforms.
- Fleet electrification protocols:Depot operators for electric buses and delivery vans are specifying 350A+ DC fast charging connectors to maximize vehicle utilization during narrow overnight windows.
- Silver-nickel plating advances:Improved contact metallurgy extends cycle life beyond 10,000 mating operations, reducing replacement frequency for high-turnover public charging stations.
Market Restraints
- Copper price volatility:Contact pins and cable conductors represent 35-40% of bill-of-materials cost, exposing margins to commodity swings on the London Metal Exchange.
- Chinese supply concentration:GB/T connector housings and cable assemblies originate predominantly from Shenzhen and Dongguan manufacturing clusters, creating single-source vulnerability.
- IEC 62196-2 certification backlog:European testing laboratory capacity constraints extend qualification timelines to 14-18 months, freezing new entrants from public tender eligibility.
Strategic Opportunities
- India's BIS certification pathway:The Bureau of Indian Standards is developing IS 17017 harmonization with IEC protocols, opening procurement channels for AC and DC connector suppliers ahead of 2030 EV adoption targets.
- Bidirectional V2G integration:ISO 15118-20 standardization enables connectors with embedded power-line communication chips to serve grid stabilization contracts for utilities.
- Integrated charging modules:Connector-cable-inverter assemblies reduce installation labor by 60% for commercial depot operators seeking turnkey hardware procurement.
Industry Challenges
- High-voltage safety engineering scarcity:Qualified designers capable of 1000V DC arc suppression and thermal runaway containment command premium compensation, constraining R&D throughput.
- Legacy vehicle retrofit incompatibility:Early-model EVs with proprietary connector geometries require adapter hardware that complicates warranty coverage and liability allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle (EV) Charging Connector Market |
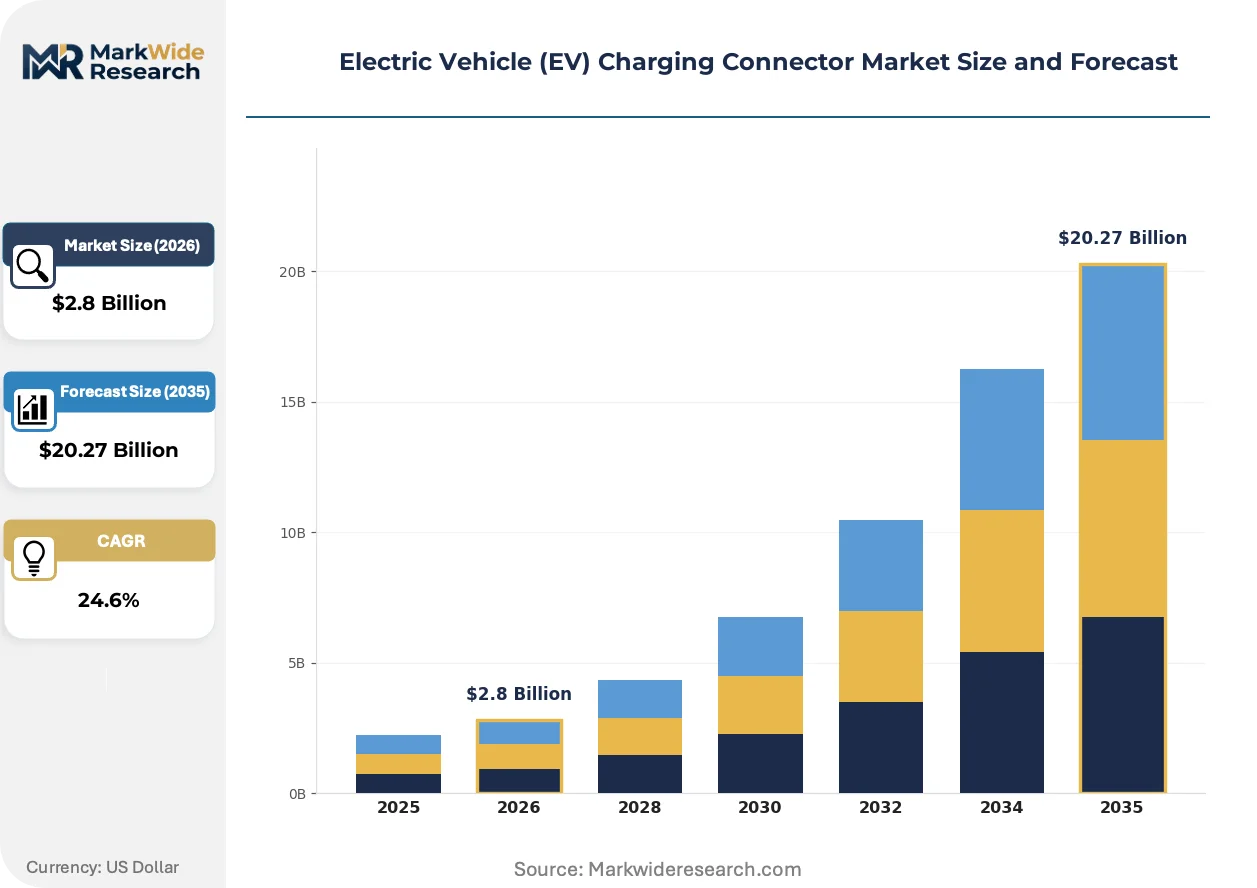
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: AC Connector, DC Connector, Tesla Connector, CCS Connector Application: Residential, Commercial, Fleet, Public Technology: Wired Charging, Wireless Charging, Fast Charging, Smart Charging End User: OEMs, Utility Providers, Charging Networks, Vehicle Owners |
| Companies Covered | Delta Electronics, Inc., EVBox Group, Siemens AG, Mennekes Elektrotechnik GmbH & Co. KG, Hubbell Incorporated, Bosch GmbH, ChargePoint Holdings, Inc., Webasto SE, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle (EV) Charging Connector Market Shifts & Advancements
Cooling-integrated connector architectures are displacing passive thermal designs as operators push beyond 350kW power levels, forcing suppliers to embed liquid-cooled cable systems directly into connector assemblies.
Liquid-cooled charging cables enable sustained 500A current delivery without exceeding 90°C surface temperatures. Fleet operators in Germany and California are specifying these systems for 24/7 commercial depot operations. The technology is fragmenting procurement specifications across utilities, with some requiring closed-loop glycol systems while others mandate dielectric fluid alternatives.
The EU F-Gas Regulation constrains hydrofluorocarbon-based cooling media in high-amperage connector housings, compelling manufacturers to adopt CO2 or hydrocarbon refrigerant loops. Thermal management suppliers must recertify designs under revised safety protocols. German OEM platforms are absorbing these compliance costs fastest, integrating F-Gas-compliant modules into 2026 model-year charging hardware.
Direct procurement from connector manufacturers is displacing tiered distribution for large fleet operators managing 500+ vehicle deployments. These buyers are negotiating volume frameworks that bundle connector supply with installation supervision and predictive maintenance analytics. The pattern concentrates in California's electric bus procurement programs, where transit agencies specify single-source accountability for charging infrastructure performance.
Electric Vehicle (EV) Charging Connector Market Segmentation
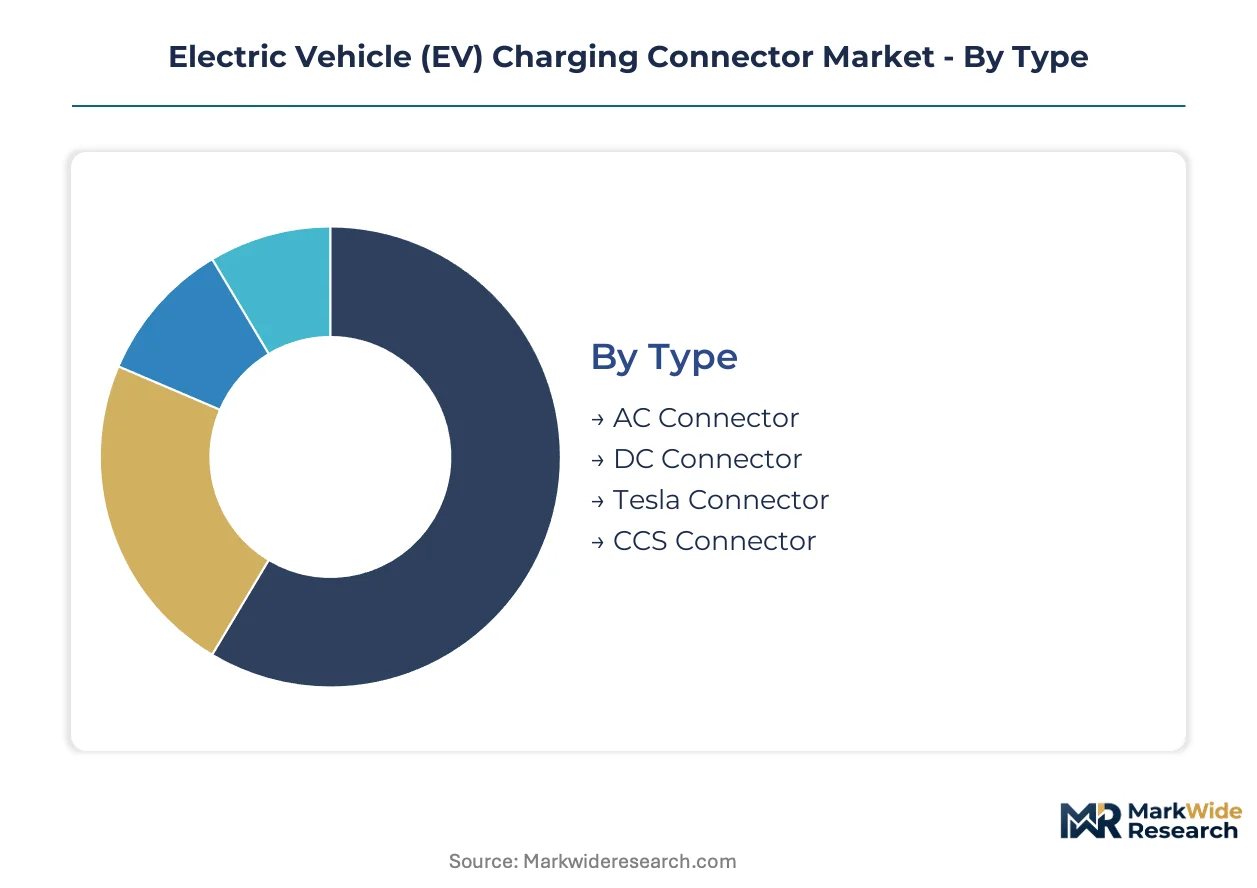
Connector architecture choices determine certification pathways, thermal engineering requirements, and margin structures across the value chain. Procurement patterns diverge sharply between depot operators optimizing for throughput and residential installers prioritizing cost minimization.
Type:
DC Connector faces the most acute substitution pressure as liquid-cooled architectures displace passive designs above 350kW power levels.
- AC Connector:IEC 62196-2 type 2 interfaces dominate European residential and workplace installations with standardized 16A to 63A current ratings. German OEM platforms specify these connectors for overnight charging scenarios where extended dwell times offset lower power delivery.
- DC Connector:CCS Combo configurations anchor public fast-charging networks across North America and Europe with integrated power-line communication for ISO 15118-20 bidirectional protocols. Fleet operators in California specify 350A+ variants to compress electric bus charging windows.
- Tesla Connector:NACS geometry is displacing CCS inlets on new vehicle platforms as US OEMs adopt the slimmer form factor for cost and packaging advantages.
- CCS Connector:Combined Charging System hardware maintains regulatory preference for subsidy eligibility under EPA-coordinated credit frameworks.
AC Connector anchors the volume base while DC Connector gains share at the steepest rate.
Application:
Cost tier stratification separates turnkey depot installations from fragmented residential contractor channels.
- Residential:Level 2 wall-mounted units with SAE J1772 inlets dominate single-family installations. California's Title 24 building codes mandate pre-wiring for EV readiness in new construction.
- Commercial:Workplace and retail locations specify dual-port pedestal configurations to maximize parking asset utilization. German property developers bundle charging infrastructure into green building certification schemes.
- Fleet:Electric bus and delivery van depots drive demand for 500A liquid-cooled systems with predictive thermal monitoring. Transit agencies in Los Angeles and Berlin negotiate performance-guaranteed procurement frameworks.
- Public:Highway corridor installations prioritize interoperability certification to qualify for federal infrastructure subsidies under NEVI program requirements.
Fleet applications concentrate the highest per-site spending while Public infrastructure expands most quickly.
Technology:
Volume concentration favors established conductive architectures over emerging inductive alternatives.
- Wired Charging:Copper conductor assemblies with silver-nickel plated contacts constitute the dominant technical platform. Shenzhen and Dongguan manufacturing clusters supply cable-connector integrated systems.
- Wireless Charging:Inductive pad systems target premium autonomous vehicle applications with automated alignment requirements. Qi-based protocols face efficiency penalties that limit commercial deployment.
- Fast Charging:DC architectures above 150kW require active thermal management with glycol or dielectric fluid cooling loops. EU F-Gas Regulation constrains refrigerant selection for high-amperage housings.
- Smart Charging:ISO 15118-20 embedded communication chips enable utility load-balancing and vehicle-to-grid revenue streams. German grid operators pilot dynamic tariff integration with connector-integrated power electronics.
Wired Charging retains the installed base while Smart Charging climbs the fastest on utility contract monetization.
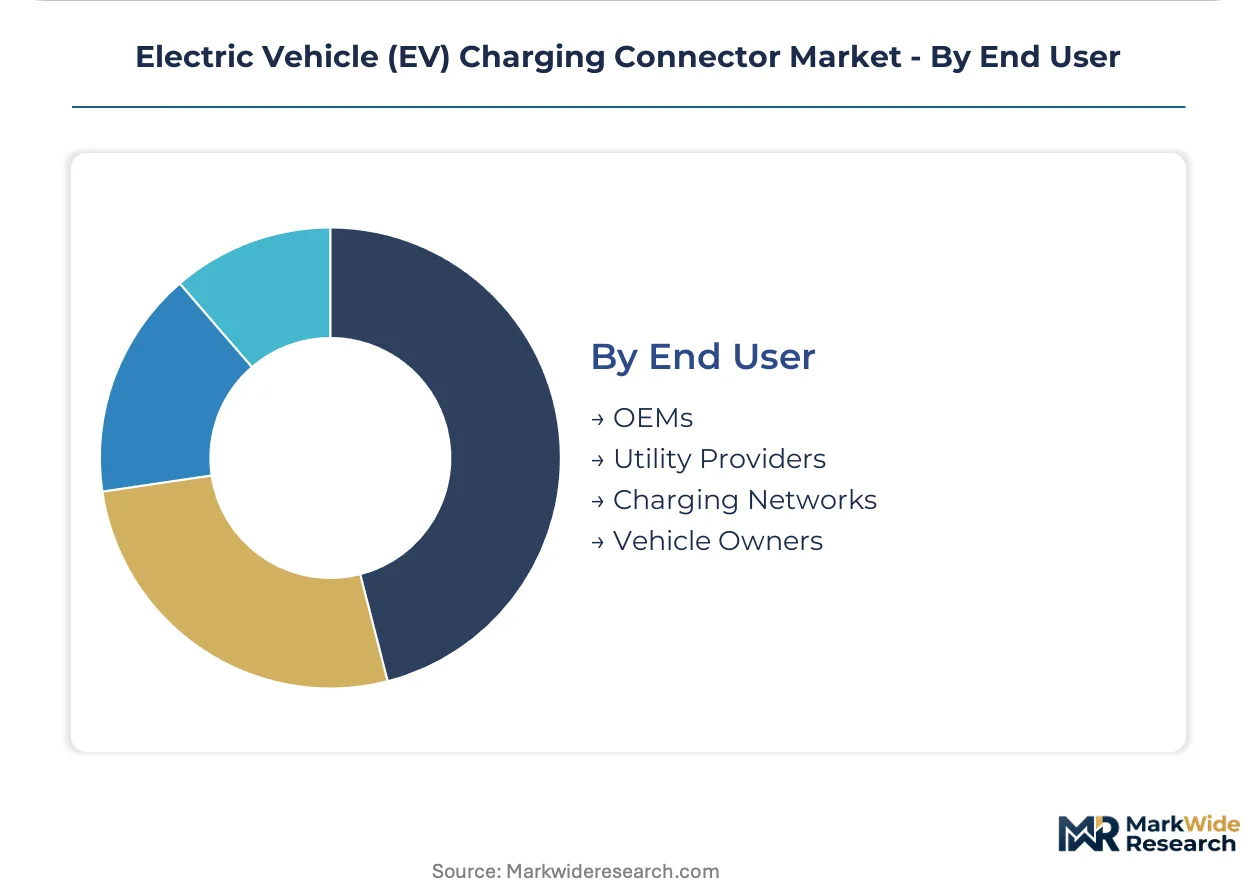
End User:
Customer type determines specification authority and procurement complexity across the value chain.
- OEMs:Vehicle manufacturers specify inlet geometries and communication protocols during platform development. German automakers maintain captive testing laboratories to accelerate IEC 62196 certification timelines.
- Utility Providers:Grid operators procure smart charging infrastructure to manage distributed energy resource integration. California investor-owned utilities bundle connector supply with demand response program enrollment.
- Charging Networks:Infrastructure operators negotiate volume frameworks for connector-cable-inverter assemblies to reduce installation labor. Electrify America and Ionity specify interchangeable hardware across European and North American sites.
- Vehicle Owners:Retail purchasers prioritize adapter compatibility and warranty coverage for aftermarket installations. Early-model EV owners face proprietary connector obsolescence requiring hardware bridge solutions.
Charging Networks concentrate procurement volume while Utility Providers drive the steepest specification evolution on grid integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US EPA coordinates fuel economy credits with NHTSA to indirectly mandate charging infrastructure density, compelling OEMs to pre-install CCS-compatible inlets on new vehicle platforms. This regulatory mechanism concentrates procurement authority with fleet operators and charging network developers across specific national markets.
United States
California's Title 24 building codes mandate EV-ready pre-wiring in new residential construction, while transit agencies in Los Angeles specify performance-guaranteed procurement frameworks for electric bus depots. The NHTSA coordinates safety standards for high-voltage connector assemblies. Manufacturing clusters in the Detroit metro area supply CCS-compatible inlet systems to domestic OEM platforms.
Germany
German OEM platforms absorb EU F-Gas Regulation compliance costs fastest, integrating compliant thermal management modules into 2026 model-year charging hardware. The KBA enforces type approval for vehicle inlet geometries. Industrial concentration in Baden-Württemberg and Bavaria hosts captive testing laboratories that accelerate IEC 62196 certification timelines for connector suppliers.
China
NMPA certification requirements and GB/T standards create a parallel qualification track that fragments interoperability for connectors serving the domestic market. The MIIT oversees charging infrastructure deployment mandates in major metropolitan zones. Manufacturing clusters in Shenzhen and Dongguan dominate GB/T connector housing and cable assembly production.
India
The Bureau of Indian Standards is developing IS 17017 harmonization with IEC protocols, opening procurement channels for AC and DC connector suppliers ahead of 2030 EV adoption targets. The CEA regulates grid integration standards for smart charging infrastructure. Industrial activity concentrates in Maharashtra and Gujarat, where state-level EV policies accelerate depot electrification for commercial fleets.
Electric Vehicle (EV) Charging Connector Market Competitive Landscape
Player mix skews toward diversified electrical equipment conglomerates with automotive heritage. Market structure consolidates around vertically integrated suppliers controlling certification timelines through captive testing infrastructure. Three archetypes dominate: diversified industrial conglomerates with automotive supply relationships, specialized electrotechnical component manufacturers, and charging network operators backward-integrating into hardware procurement. Competitive dynamics center on certification acceleration and integrated module bundling to reduce installation labor.
Among diversified industrial conglomerates, Siemens AG and Bosch GmbH occupy positions that leverage automotive supply chain relationships into charging infrastructure. Siemens anchors qualification velocity through captive testing laboratories. Bosch exemplifies the archetype extending component manufacturing into integrated charging module production. Specialized electrotechnical manufacturers include Mennekes Elektrotektrotechnik GmbH & Co. KG, which represents the dedicated connector engineering tier focused on type 2 interface dominance across German OEM platforms.
| Leading Market Players |
|---|
| Delta Electronics, Inc. |
| EVBox Group |
| Siemens AG |
| Mennekes Elektrotechnik GmbH & Co. KG |
| Hubbell Incorporated |
| Bosch GmbH |
| ChargePoint Holdings, Inc. |
| Webasto SE |
| Schneider Electric SE |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between fleet operators and connector manufacturers lock in multi-year supply access while flattening price volatility for copper-intensive cable assemblies. California transit agencies and German depot operators leverage these contracts to secure IEC 62196-2 certified hardware ahead of laboratory qualification backlogs.
Pricing Analysis
Certification level (IEC 62196-2/SAE J1772 versus uncertified aftermarket) creates the primary spread between public-tender-eligible and gray-market pricing. Volume-tiered contracting dominates procurement, with 500+ unit frameworks commanding 15-25% discounts over spot purchases. Cost compression in residential AC connectors is intensifying because Shenzhen manufacturers are absorbing copper volatility to maintain market share. Fleet operators exhibit the lowest price sensitivity, prioritizing thermal reliability and warranty coverage over per-unit savings.
Supply Chain Analysis
China and Germany anchor connector manufacturing, with Shenzhen and Dongguan clusters producing GB/T housings and cable assemblies while Baden-Württemberg hosts captive testing laboratories for IEC certification. Silver-nickel plating feedstock draws from South African and Russian mining operations, creating geopolitical exposure. Single-source vulnerability concentrates in liquid-cooled cable systems where two German suppliers control glycol-compatible sealing technology. Distribution runs through charging network operators and tier-1 automotive suppliers, bypassing traditional electrical distribution channels for large fleet deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connector standardization fragmentation across CCS, NACS, and GB/T architectures creates specialized supply niches for certification-accelerated suppliers and regional compliance specialists.
For Market Incumbents: Shield market position by deepening captive laboratory capacity to compress IEC 62196-2 qualification timelines below 12 months, countering the 14-18 month backlog freezing new entrants. Acquire liquid-cooled thermal management specialists to defend margin pools above 350kW power levels where passive designs face substitution.
For New Entrants and Emerging Players: Lead with India's BIS certification pathway for IS 17017-harmonized connectors, exploiting the 2026-2030 procurement window before domestic manufacturing scales. Target bidirectional V2G-integrated connector assemblies for German utility pilot programs, leveraging ISO 15118-20 communication chip partnerships as the go-to-market anchor.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated suppliers with captive testing infrastructure and automotive OEM relationships, positioned to capture fleet electrification procurement cycles. The inflection signal to monitor is bilateral recognition between China's GB/T and European IEC certification regimes, which would collapse redundant tooling requirements and reshape competitive economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Laboratory Expansion | Captive IEC 62196-2 testing capacity accelerates public tender eligibility timelines for European depot deployments. |
| Liquid-Cooled Cable Integration | Embedded thermal management enables sustained 500A delivery for California electric bus operators. |
| Smart Charging Communication Module Development | ISO 15118-20 power-line chips unlock utility load-balancing contracts with German grid operators. |
| Regional Certification Harmonization Partnership | IS 17017 alignment with IEC protocols opens procurement channels ahead of India's 2030 EV targets. |
| Integrated Charging Module Bundling | Connector-cable-inverter assemblies reduce installation labor by 60% for commercial fleet operators. |
Research Methodology
Desk research of regulatory filings, customs trade databases, and OEM technical specifications preceded structured interviews with charging network procurement officers, fleet depot managers, thermal engineering directors, and certification laboratory technicians. Primary fieldwork across Shenzhen manufacturing clusters, German automotive supply corridors, and California transit agencies was cross-validated against EPA fuel economy credit frameworks and EU F-Gas Regulation compliance disclosures. Bottom-up connector shipment data and top-down infrastructure investment flows were triangulated to anchor volume estimates.
Variance decomposition across connector architecture types, application segments, and power rating tiers structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro EV adoption curves and infrastructure deployment mandates. Modeled inputs included fleet operator charging window compression requirements, laboratory certification capacity constraints, and copper price trajectory assumptions.
Forecasts assume regulatory continuity in EPA-NHTSA coordinated credit systems and EU CE marking frameworks; material policy shifts would require re-modeling. Specific risks include GB/T-IEC bilateral recognition delays, F-Gas Regulation refrigerant constraint tightening, and NACS standard adoption velocity exceeding base-case assumptions. Recalibration cycles align with material shifts in certification regime interoperability and fleet electrification procurement award patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Airport Charging Stations Market
Electric Vehicle Charging
Bidirectional Charging Units Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
EV Charging Cables Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
North America EV Charging Stations Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market
Electric Vehicle Charging
Denmark Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
PV BESS EV Charging Systems Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
Electric Vehicle Charging System Market
Electric Vehicle Charging
Battery Swapping Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market