
 Heavy-Duty Electric Vehicle Charging Infrastructure Market | 2026-2036
Heavy-Duty Electric Vehicle Charging Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy-Duty Electric Vehicle Charging Infrastructure Market Foresight
ISO 15118-20 certification for plug-and-charge interoperability is redrawing competitive boundaries in heavy-duty charging. ABB leverages its integrated power electronics portfolio to dominate high-megawatt bus and truck applications. Siemens anchors European depot installations through its Sicharge portfolio, while Tesla controls proprietary network density for its Semi program.
Heavy-duty electric vehicle charging infrastructure comprises fixed and mobile systems engineered to deliver sustained power outputs exceeding 150 kW to commercial battery-electric trucks, buses, and vocational vehicles, utilizing liquid-cooled cable assemblies and dynamic load management to prevent thermal degradation during extended charging sessions. Fast chargers occupy the largest installed base among product types, though ultra-fast chargers above 350 kW capture disproportionate capital allocation as fleet operators prioritize route-minimizing turnaround times. Depot charging leads installation-type deployment because logistics companies and public transport services require predictable overnight replenishment at centralized facilities rather than opportunistic on-street access.
The US Federal Energy Regulatory Commission and the European Union's Alternative Fuels Infrastructure Regulation jointly mandate minimum corridor coverage and standardized connector availability, compelling network providers to overbuild capacity ahead of vehicle deployment. California's Air Resources Board accelerates this dynamic through fleet-specific zero-emission mandates that force compliance timelines. Stakeholders must weigh interoperability commitments against proprietary ecosystem lock-in as charging standard consolidation remains unresolved.
Market Dynamics
Fleet electrification mandates are compressing deployment timelines faster than grid interconnection permits can be secured, creating a structural bottleneck where charger hardware availability outpaces site energization capacity across major logistics corridors.
Growth Catalysts
- Alternative Fuels Infrastructure Regulation:The EU mandate for corridor coverage compels member states to pre-position high-capacity charging before vehicle fleets arrive, accelerating capital commitment cycles.
- Depot electrification by logistics operators:Centralized fleet facilities in Germany and the United States are converting diesel yards to megawatt-scale charging campuses, locking in multi-year hardware procurement contracts.
- Liquid-cooled cable assemblies:Thermal management advances now sustain 500+ kW continuous output without conductor degradation, enabling sub-45-minute turnaround for Class 8 tractors.
Market Restraints
- Copper and silicon carbide supply concentration:Processing capacity for high-purity copper rod and SiC wafres clusters in China, exposing non-Chinese charger manufacturers to input cost volatility and export restriction risk.
- Utility interconnection queues:Distribution system operators in California, Texas, and the Netherlands face 18-36 month backlogs for multi-megawatt service upgrades, delaying revenue recognition for installed hardware.
- CCS-MCS connector fragmentation:Competing physical interface standards between CharIN's Megawatt Charging System and legacy CCS Combo create procurement paralysis for fleet operators fearing stranded asset risk.
Strategic Opportunities
- India's freight corridor electrification:The Delhi-Mumbai Industrial Corridor and dedicated freight routes present greenfield deployment potential before domestic battery-electric truck production scales.
- Battery-buffered charging stations:Integration of second-life battery storage with grid-constrained sites allows 350+ kW peak delivery without full utility infrastructure buildout, opening rural highway locations.
- Inflation Reduction Act tax credits:Section 30C provisions for alternative fuel infrastructure reduce effective capital cost for depot installations, improving project IRRs for fleet operators in qualifying census tracts.
Industry Challenges
- High-voltage electrical technician scarcity:Installation and maintenance of 1000V DC systems requires specialized certification that union training programs and technical colleges have not yet scaled to match deployment velocity.
- ISO 15118-20 certification timelines:Plug-and-charge interoperability testing creates 6-12 month product launch delays as hardware vendors sequence firmware validation through multiple certification bodies.
- Legacy fleet management system integration:Telematics platforms from incumbent diesel-era suppliers require custom API development to synchronize charging schedules with route optimization algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy-Duty Electric Vehicle Charging Infrastructure Market |
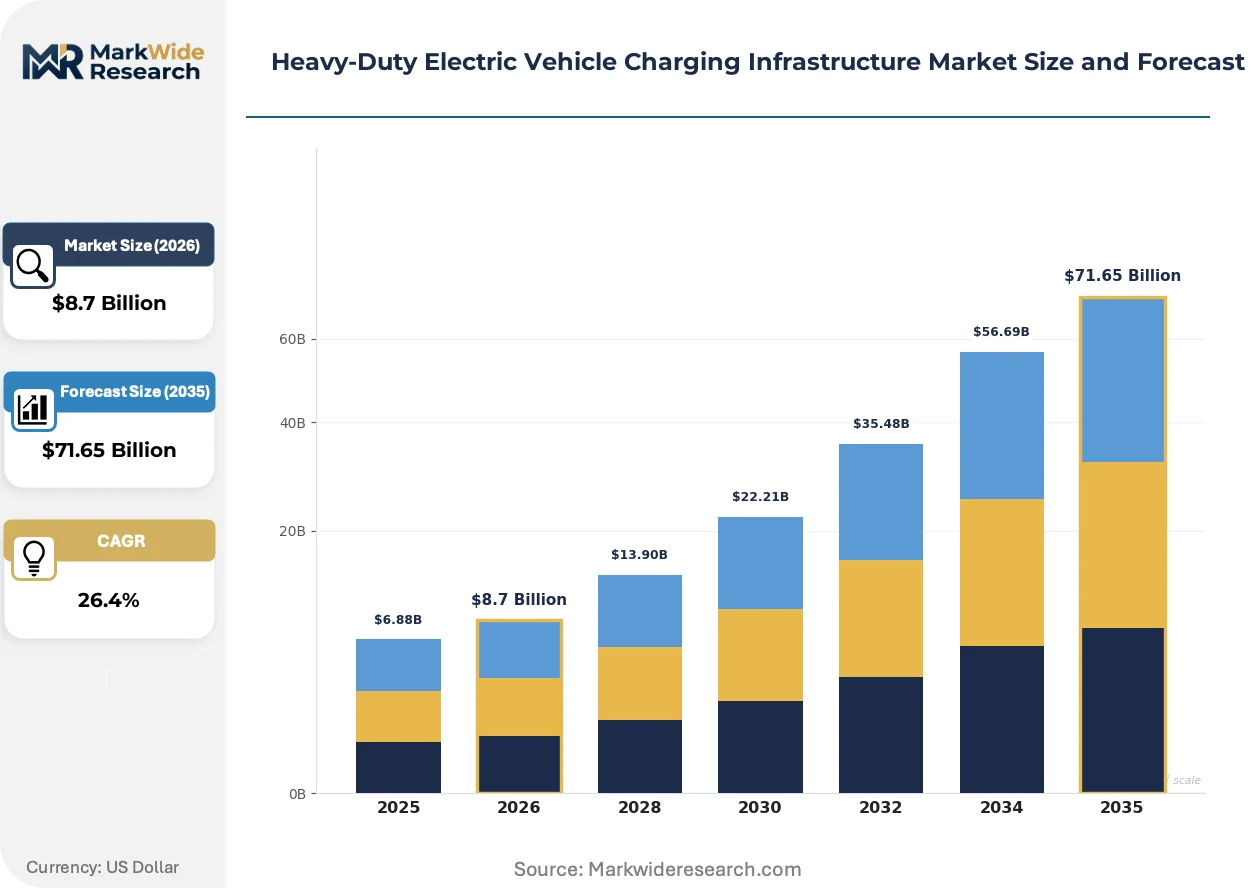
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $71.65 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fast Chargers, Ultra-Fast Chargers, Level 2 Chargers, Mobile Charging Units End User: Fleet Operators, Public Transport Services, Logistics Companies, Charging Network Providers Installation Type: On-Street, Off-Street, Commercial Facilities, Depot Charging Charging Standard: CCS, CHAdeMO, Tesla Supercharger, IEC 61851 |
| Companies Covered | ABB, Siemens, ChargePoint, Tesla, Electrify America, Blink Charging, EVBox, Schneider Electric, Heliox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy-Duty Electric Vehicle Charging Infrastructure Market Shifts & Advancements
Power electronics architecture is undergoing fundamental redesign as silicon carbide MOSFETs displace IGBT modules, enabling higher switching frequencies that reduce transformer size and cooling system mass in containerized charging stations.
Silicon carbide-based power conversion modules now handle 1200V bus voltages with sub-50 nanosecond switching losses. Heavy-duty fleet operators in the United States and Germany are specifying SiC-equipped chargers for new depot builds, accepting 15-20% hardware premiums for footprint reduction. This semiconductor transition is miniaturizing the physical envelope of megawatt-scale charging systems, allowing installation in existing truck yards without structural reinforcement.
The US Inflation Reduction Act's domestic content bonuses for clean energy hardware are redirecting supply chain geography. Charger manufacturers must now source 40% of manufactured product value from North American facilities to qualify for maximum tax credit stacking, forcing component suppliers to establish US-based winding, assembly, and testing operations by 2026.
Fleet procurement departments are unbundling hardware acquisition from energy management services, treating charging infrastructure as distinct capital expenditure from software subscriptions and maintenance agreements. This purchasing pattern is most pronounced among US-based private trucking fleets with 100-500 vehicle counts, where internal sustainability teams negotiate directly with charger OEMs while outsourcing operational software to specialized platform providers.
Heavy-Duty Electric Vehicle Charging Infrastructure Market Segmentation
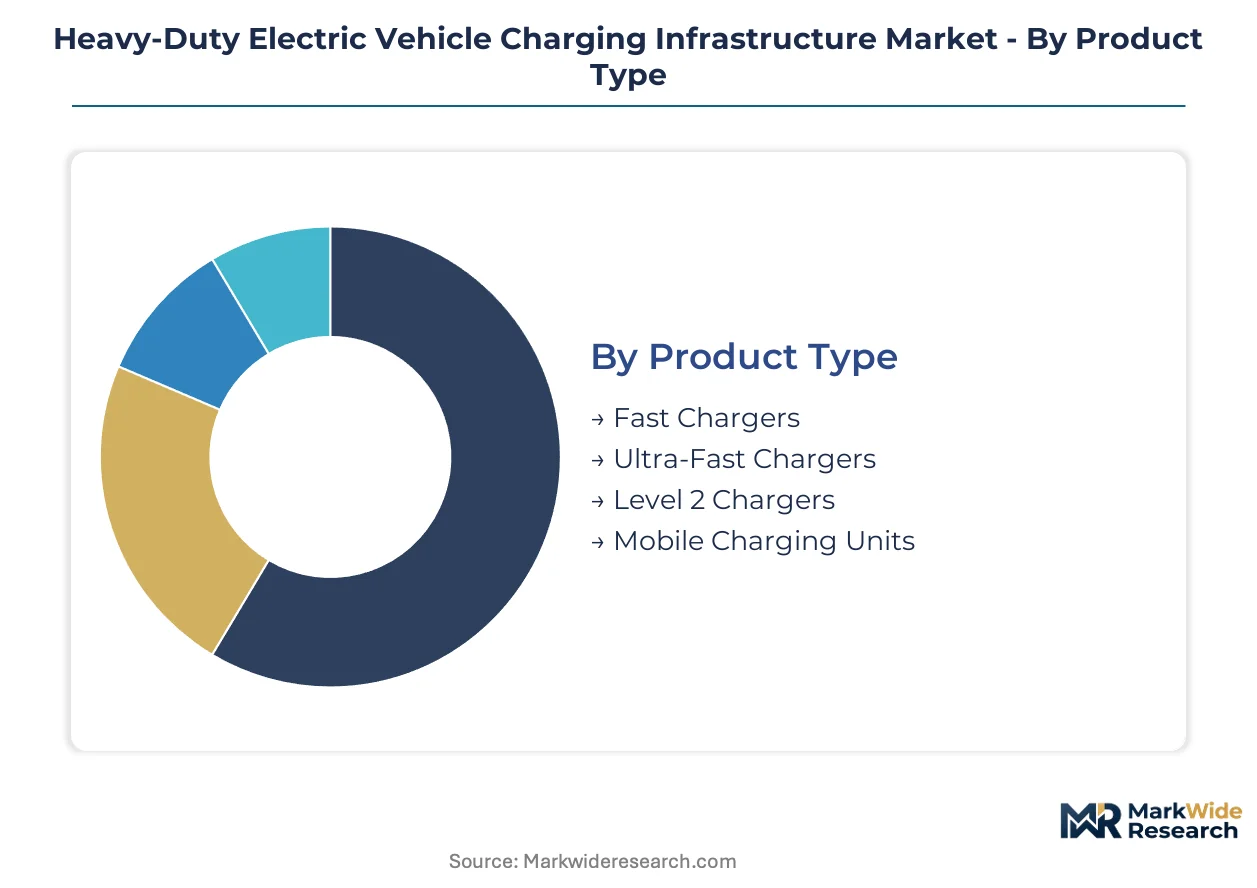
Heavy-duty charging infrastructure segments diverge sharply across regulatory jurisdictions. Fleet procurement patterns in Germany, China, and the United States create distinct demand profiles that reshape equipment specifications and installation priorities.
Product Type:
FERC in the United States and the EU's Alternative Fuels Infrastructure Regulation impose divergent power output mandates that reshape equipment procurement across fast and ultra-fast categories.
- Fast Chargers:Sustained 150-350 kW output through liquid-cooled cable assemblies serves overnight depot replenishment for Class 6-8 trucks. German logistics operators specify these units for fleet yards in the Rhine-Ruhr corridor, accepting longer dwell times to minimize capital expenditure per installation bay.
- Ultra-Fast Chargers:Above-350 kW systems utilizing silicon carbide power electronics enable sub-45-minute turnaround for long-haul tractors. Chinese highway corridor deployments along the Beijing-Shanghai axis prioritize these units to maximize asset utilization rates for state-owned freight fleets.
- Level 2 Chargers:Lower-power AC systems serve auxiliary vehicle classes and maintenance yard support equipment in California compliance zones.
- Mobile Charging Units:Containerized trailer-mounted systems address grid-constrained sites and emergency roadside assistance across Texas logistics corridors.
Fast chargers handle the majority of throughput; ultra-fast chargers are expanding most quickly on share.
End User:
Cost tier differentiation separates enterprise fleet capital budgets from municipal procurement constraints.
- Fleet Operators:Private trucking companies with 100-500 vehicle counts negotiate direct hardware procurement while outsourcing software management. These operators concentrate in the US Midwest and German industrial regions, driving depot-scale megawatt installations.
- Logistics Companies:Third-party freight providers face compressed payback requirements that favor battery-buffered charging stations over full grid upgrades. Dutch distribution hubs near Rotterdam specify these configurations to circumvent 24-month utility interconnection delays.
- Public Transport Services:Municipal bus operators in California and Germany mandate overnight depot charging with predictable route scheduling.
- Charging Network Providers:Independent infrastructure developers build corridor coverage ahead of vehicle deployment to capture IRA Section 30C tax credits.
Fleet operators commit the largest capital volumes; logistics companies are gaining share fastest on deployment velocity.
Installation Type:
Application context determines electrical infrastructure requirements and permitting complexity.
- Depot Charging:Centralized fleet facilities with dedicated utility service upgrades enable megawatt-scale campus configurations. US private trucking fleets in Ohio and Pennsylvania convert diesel yards to electrified terminals, locking in multi-year hardware contracts with integrated energy management systems.
- Commercial Facilities:Retail and industrial property owners install destination charging to capture freight traffic. German autobahn service areas prioritize these installations to meet AFIR corridor coverage mandates.
- On-Street:Urban curb-side installations serve last-mile delivery vans in California compliance zones with constrained real estate.
- Off-Street:Dedicated parking structures accommodate intermittent charging needs for vocational vehicles in municipal fleets.
Depot charging dominates installed capacity; commercial facilities are climbing the fastest on new project announcements.
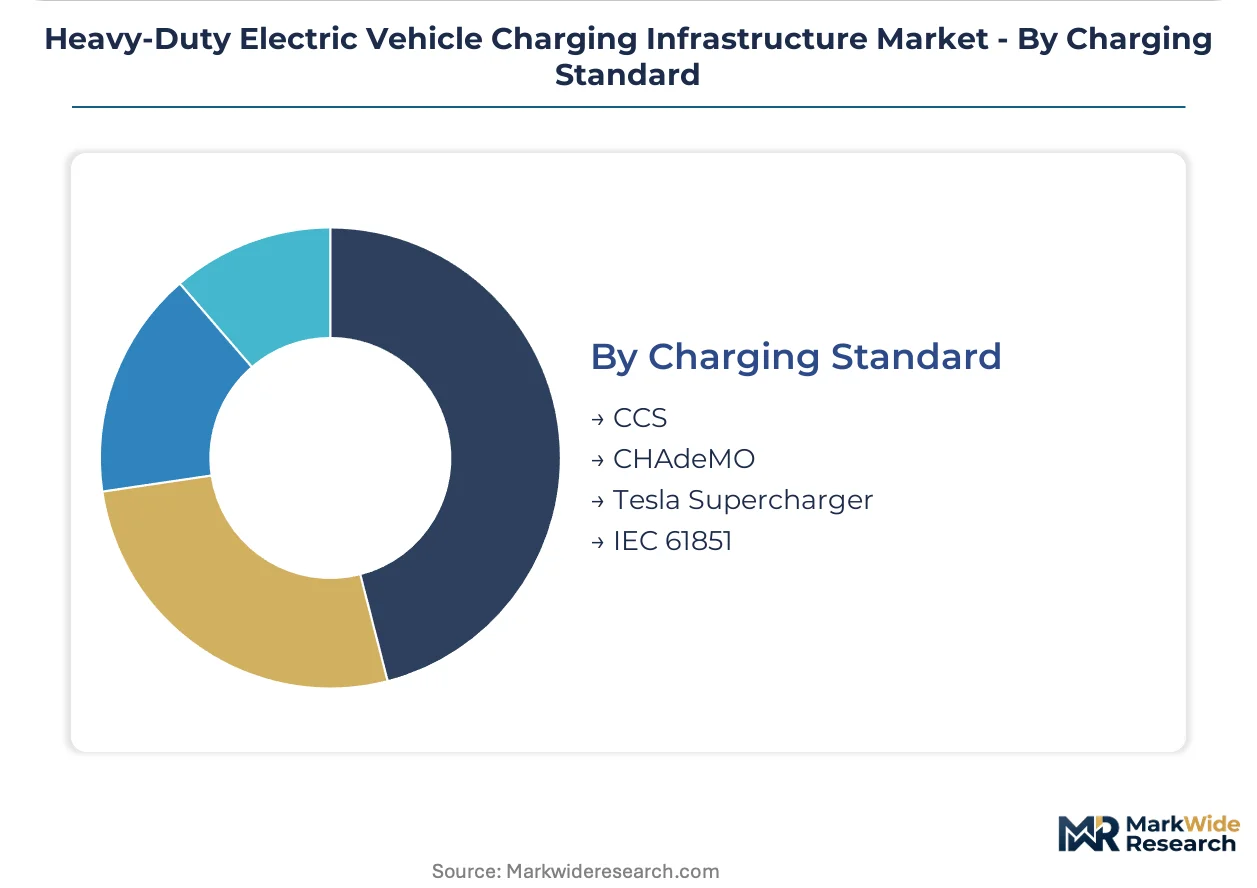
Charging Standard:
Connector fragmentation creates procurement paralysis as fleet operators weigh interoperability against stranded asset risk.
- CCS:Combined Charging System with Combo connectors serves as the prevailing European standard under AFIR harmonization requirements. German and Dutch infrastructure deployments specify CCS exclusively for public access stations to ensure multi-manufacturer vehicle compatibility.
- IEC 61851:The foundational international standard governs conductive charging system communication protocols. Chinese domestic manufacturers align with IEC-derived GB/T standards for heavy-duty applications along the Yangtze River freight corridor.
- CHAdeMO:Japanese-origin DC fast charging protocol retains niche presence in legacy bus fleet retrofits.
- Tesla Supercharger:Proprietary network density supports the Semi program with dedicated megawatt hardware at private terminals.
CCS carries the bulk of public infrastructure investment; IEC 61851-aligned systems are advancing fastest on standardization momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act compresses payback periods for high-capacity installations, while the EU's Alternative Fuels Infrastructure Regulation mandates minimum corridor coverage ahead of vehicle deployment. These policy frameworks concentrate procurement activity in specific national markets where grid interconnection capacity and fleet electrification timelines align.
United States
Private trucking fleets with 100-500 vehicle counts negotiate direct hardware procurement for depot-scale megawatt installations. FERC mandates standardized connector availability along major logistics corridors, compelling network providers to overbuild capacity. California's Air Resources Board enforces fleet-specific zero-emission mandates that force compliance timelines in the Los Angeles Basin and Central Valley freight corridors.
Germany
Logistics operators in the Rhine-Ruhr corridor specify 150-350 kW fast chargers for overnight depot replenishment, accepting longer dwell times to minimize capital expenditure. The EU AFIR compels member states to pre-position high-capacity charging before vehicle fleets arrive. German autobahn service areas prioritize commercial facility installations to meet corridor coverage mandates.
China
State-owned freight fleets prioritize above-350 kW ultra-fast systems along the Beijing-Shanghai highway axis to maximize asset utilization rates. Domestic manufacturers align with IEC-derived GB/T standards for heavy-duty applications. Processing capacity for high-purity copper rod and silicon carbide wafers clusters in Chinese facilities, exposing non-Chinese charger manufacturers to input cost volatility.
Netherlands
Distribution hubs near Rotterdam specify battery-buffered charging stations to circumvent 24-36 month utility interconnection delays for multi-megawatt service upgrades. Dutch logistics companies face compressed payback requirements that favor peak delivery without full grid infrastructure buildout. The Port of Rotterdam electrification program anchors depot charging deployment for drayage and regional freight operations.
India
The Delhi-Mumbai Industrial Corridor presents greenfield deployment potential before domestic battery-electric truck production scales. The country's national freight regulator has not yet mandated corridor coverage, creating first-mover advantage for infrastructure developers. Dedicated freight routes in Gujarat and Maharashtra attract early capital commitment from international charger OEMs seeking manufacturing localization under the PLI scheme.
Heavy-Duty Electric Vehicle Charging Infrastructure Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with integrated power electronics portfolios, creating a tiered structure where electrical infrastructure specialists compete against automotive-captive networks. Two strategic archetypes dominate: European engineering conglomerates leveraging century-old utility relationships, and North American network operators capturing IRA tax credit flows. Competitive moves center on silicon carbide supply chain anchoring and firmware certification sequencing through ISO 15118-20 validation bodies.
Within the European engineering tier, ABB and Siemens occupy positions as archetypal integrated power electronics providers. ABB represents the high-megawatt bus and truck application specialist, while Siemens anchors European depot installations through its Sicharge portfolio. Tesla sits within the automotive-captive network archetype, controlling proprietary megawatt hardware density for its dedicated terminal program. These three companies exemplify the competitive tension between interoperability commitments and proprietary ecosystem lock-in as charging standard consolidation remains unresolved.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| ChargePoint |
| Tesla |
| Electrify America |
| Blink Charging |
| EVBox |
| Schneider Electric |
| Heliox |
| Others |
Supply & Pricing Matrix
Eighteen-to-thirty-six-month utility interconnection queues in California, Texas, and the Netherlands compress hardware procurement cycles and amplify pricing power for charger OEMs with certified inventory. This lead-time environment forces fleet operators to accept 15-20% hardware premiums for silicon carbide-equipped systems while concentrating procurement leverage among integrated power electronics providers with captive component pipelines.
Pricing Analysis
Certification level creates the primary spread across charger hardware tiers, with ISO 15118-20 plug-and-charge validation commanding substantial premiums over basic CCS interoperability units. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels reflects firmware maturity and testing investment depth. Cost compression in the economy tier intensifies because Chinese manufacturers flood depot segments with unvalidated hardware. Fleet operators with 100-500 vehicle counts exhibit highest price sensitivity, while state-owned freight fleets in China accept premium positioning for asset utilization guarantees.
Supply Chain Analysis
Strait of Malacca transit underwrites silicon carbide wafer delivery schedules from Chinese processing facilities to European and North American assembly plants. High-purity copper rod, silicon carbide substrates, and liquid-cooled cable assemblies draw from concentrated Chinese, German, and South Korean supplier bases. Single-source vulnerability in SiC wafer fabrication exposes non-Chinese charger manufacturers to export restriction risk. Distribution runs through direct OEM-fleet procurement channels rather than distributor networks, with logistics companies and charging network providers representing distinct downstream archetypes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heavy-duty charging infrastructure is approaching a platform-economics inflection where ISO 15118-20 interoperability certification determines ecosystem membership and revenue capture. The shift from proprietary connector lock-in toward standardized plug-and-charge protocols restructures competitive moats around firmware validation velocity rather than hardware scale alone.
For Market Incumbents: Consolidate silicon carbide supply relationships through backward integration into wafer sourcing or long-term offtake agreements with Chinese and South Korean substrate providers. Anchor certification sequencing capacity by expanding ISO 15118-20 validation laboratory partnerships ahead of competitor firmware launches, neutralizing emerging entrant threats from automotive-captive networks with proprietary connector ecosystems. For New Entrants and Emerging Players: Lead with battery-buffered charging station architectures targeting grid-constrained rural highway locations in India and Texas where utility interconnection delays block incumbent depot-focused deployments. The Delhi-Mumbai Industrial Corridor presents the most penetrable geography, with dedicated freight routes in Gujarat offering first-mover positioning before domestic battery-electric truck production scales. Pursue joint development agreements with logistics operators seeking peak delivery without full infrastructure buildout. For Investors and Strategic Acquirers: Long-term, this sits as a grid-interconnection arbitrage play because utility queue compression creates persistent hardware scarcity premiums and favors asset-light battery-buffered configurations over capital-intensive full-grid upgrades. Acquisition targets should display demonstrated firmware certification velocity through multiple validation bodies and established relationships with distribution system operators in California, Texas, and the Netherlands. Watch FERC and EU AFIR corridor coverage mandate acceleration as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15118-20 Certification Acceleration | Plug-and-charge interoperability validation compresses product launch timelines and locks in fleet procurement preference. |
| Silicon Carbide Supply Anchoring | Captive wafer sourcing from Chinese and South Korean facilities insulates against export restriction volatility. |
| Battery-Buffered Station Deployment | Second-life storage integration opens grid-constrained rural highway locations without utility interconnection delays. |
| Depot-Scale Energy Management Integration | Megawatt-scale campus configurations with dynamic load management secure multi-year logistics operator contracts. |
| Domestic Content Localization | North American assembly and testing operations qualify charger hardware for maximum IRA Section 30C tax credit stacking. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement directors, utility interconnection planners, charger OEM product managers, and silicon carbide substrate suppliers; and secondary validation against FERC filings, EU AFIR implementation reports, California Air Resources Board compliance databases, and customs records for copper rod and power electronics trade flows. Bottom-up equipment shipment tallies by charger power class and installation type triangulated against top-down fleet electrification commitment announcements across the analysis window.
Across the projection horizon, the analytical framework modeled demand segmentation by product type, end user archetype, installation context, and charging standard alignment. CAGRs derived from equipment procurement pipeline analysis and fleet operator capital expenditure disclosure patterns. Key forecast inputs included utility interconnection queue duration by ISO region, IRA Section 30C tax credit eligibility mapping by census tract, and silicon carbide wafer fabrication capacity expansion announcements.
Forecasts assume regulatory continuity in FERC corridor mandates, EU AFIR coverage requirements, and California Air Resources Board fleet electrification timelines; material policy shifts would require re-modeling interconnection priority structures and subsidy availability. Practitioners should keep alternative scenarios live as CCS-MCS connector standard consolidation and Chinese export control evolution reshape hardware procurement economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Germany EV Charging Infrastructure Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
Europe Electric Vehicle Chargers Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
Wireless Electric Vehicle Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Copper in Electric Vehicle Market
Electric Vehicle Charging
Global EV Charging Adapter Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
Asia-Pacific Brushless DC Motors Market