
 Norway Electric Vehicle Charging Equipment Market | 2026-2036
Norway Electric Vehicle Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Electric Vehicle Charging Equipment Market Insights
The performance gap between premium smart charging systems and basic commodity hardware is broadening in Norway's EV charging equipment landscape. Zaptec leverages its domestic manufacturing footprint to sustain rapid delivery cycles for residential wallbox units. Easee differentiates through compact industrial design that occupies minimal installation space in Norwegian multi-unit dwellings. Kempower anchors the fast-charging segment with modular DC systems that compete on scalability for fleet depot configurations.
Norway electric vehicle charging equipment encompasses power electronics assemblies that convert grid electricity to vehicle-compatible DC or AC output, typically operating at 3.7 kW to 350 kW depending on application topology, with integrated communication protocols enabling grid-to-vehicle data exchange. The primary commercial purpose centers on enabling battery electric vehicle energy replenishment across distributed locations while managing peak load impacts on local distribution networks. Home chargers and wallbox units dominate installation volumes, though fast chargers command disproportionate capital allocation due to higher per-unit margins and strategic placement value along transit corridors. Smart charging technology leads growth trajectory as grid operators mandate demand-response compatibility, while wireless charging remains nascent pending standardization.
Enova SF directs Norway's charger subsidy framework, while the Norwegian Water Resources and Energy Directorate regulates grid connection standards and tariff structures for high-capacity installations. The EU Alternative Fuels Infrastructure Regulation, adopted into Norwegian law through the EEA agreement, mandates minimum coverage density along major road corridors and standardizes payment interoperability requirements. Stakeholders must monitor whether forthcoming grid tariff reforms preserve favorable demand-charge treatment for distributed fast-charging assets or shift cost recovery toward capacity-based structures that reshape site selection economics.
Market Dynamics
The zero-emission vehicle mandate is compressing deployment timelines for DC fast charging infrastructure across Norway's transit corridors, forcing fleet operators to install high-capacity systems ahead of grid reinforcement completion.
Growth Catalysts
- Enova SF Subsidy Framework:Direct capital support for fast-charger installations reduces payback periods for commercial operators, accelerating depot electrification schedules.
- Fleet Electrification Mandates:Logistics and public transport operators face binding zero-emission deadlines that necessitate scalable charging infrastructure at scale.
- Oslo Metropolitan Corridor Density:Concentrated BEV ownership in Norway's capital region generates utilization rates that justify premium hardware investments.
Market Restraints
- Grid Connection Queues:Norwegian Water Resources and Energy Directorate processing timelines for high-capacity connections extend deployment schedules by 12-18 months.
- Copper and Power Electronics Costs:Commodity price volatility in semiconductor and conductor materials compresses hardware margins for system integrators.
- Site Access Limitations:Urban parking constraints in Norwegian multi-unit dwellings restrict residential wallbox penetration rates.
Strategic Opportunities
- Wireless Charging Standardization:Pending IEC and ISO protocol finalization opens deployment pathways for automated fleet depot configurations.
- Northern Norway Corridor Gap:E6 and E8 highway segments between Trondheim and Tromsø remain underserved for fast-charging coverage.
- Vehicle-to-Grid Integration:Aggregator business models enabling bidirectional power flows create new revenue streams for stationary battery assets.
Industry Challenges
- Certified Installation Workforce:Qualified electricians with high-voltage DC training remain scarce relative to installation demand.
- Legacy Payment System Integration:Roaming interoperability requirements under EU Alternative Fuels Infrastructure Regulation demand complex backend architecture updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Electric Vehicle Charging Equipment Market |
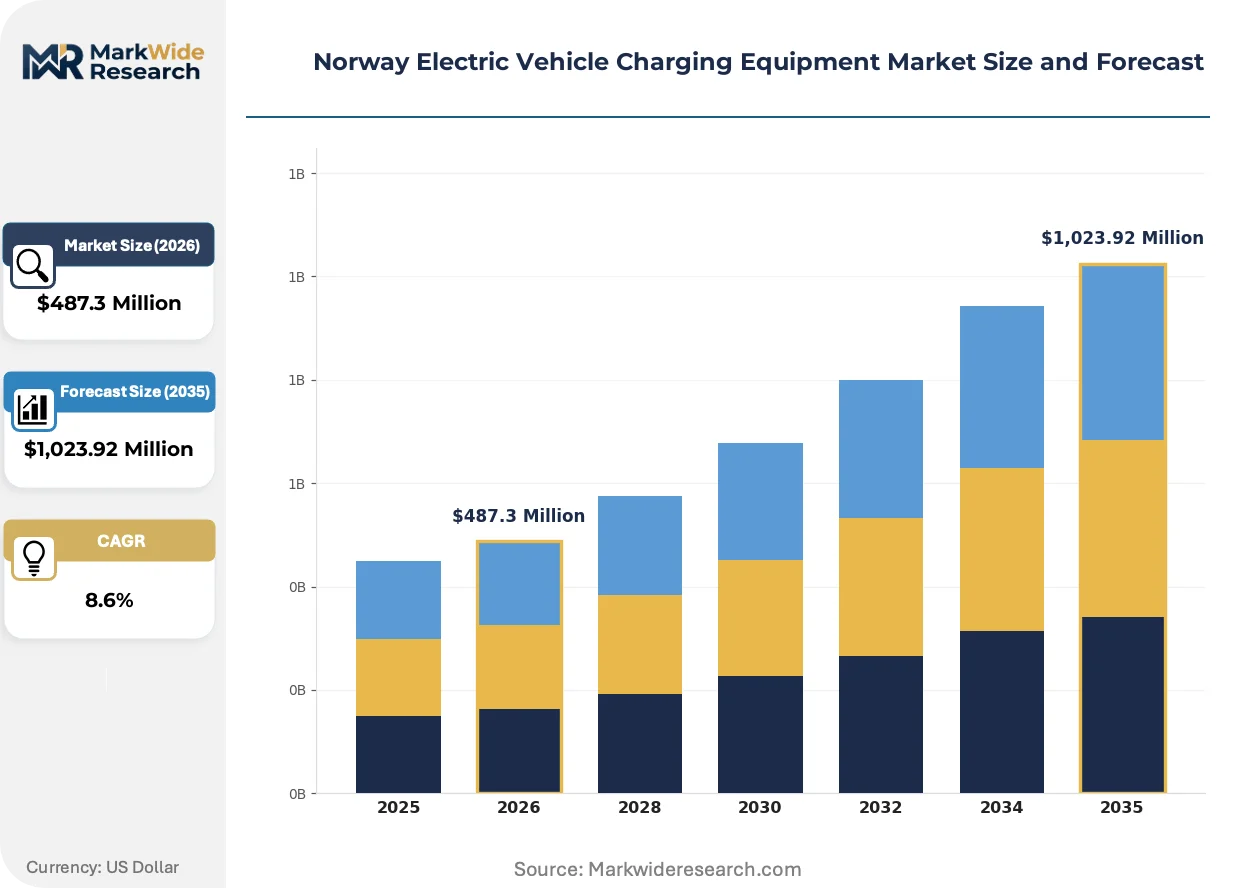
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Chargers, Public Chargers, Fast Chargers, Wallbox Chargers Technology: AC Charging, DC Charging, Wireless Charging, Smart Charging End User: Residential Users, Businesses, Fleet Operators, Charging Networks Installation Type: On-Street, Off-Street, Commercial, Private |
| Companies Covered | Zaptec, Easee, Mer, Kempower, ABB Ltd, Delta Electronics Inc., ChargePoint Inc, Tesla Inc., BYD Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Electric Vehicle Charging Equipment Market Trends and Innovations
Smart charging protocols are displacing passive hardware across Norway's residential and commercial segments, with grid operators mandating demand-response compatibility as a precondition for connection approval.
Modular DC power electronics is rewriting fleet depot economics by enabling 50 kW to 400 kW capacity scaling without full system replacement. Municipal bus operators and logistics hubs in Drammen and Bergen are adopting these systems to match charging capacity to route electrification phases. The technology is compressing capital deployment risk by allowing staged investment aligned with vehicle procurement cycles.
EU Alternative Fuels Infrastructure Regulation adoption through the EEA agreement is standardizing payment interoperability and minimum coverage density along Norwegian trunk roads. The Norwegian Public Roads Administration is enforcing these mandates through concession agreements for highway service areas. Fast-charging operators must now support ad-hoc payment without subscription, reshaping revenue model design for corridor sites.
Fleet procurement is consolidating charging service contracts under single-vendor arrangements that bundle hardware, installation, maintenance, and energy management. Transport operators in Vestland and Rogaland are displacing fragmented supplier relationships with outcome-based agreements that guarantee uptime and energy cost predictability. This pattern is most visible among grocery and parcel delivery fleets with centralized depot operations.
Norway Electric Vehicle Charging Equipment Market Segmentation
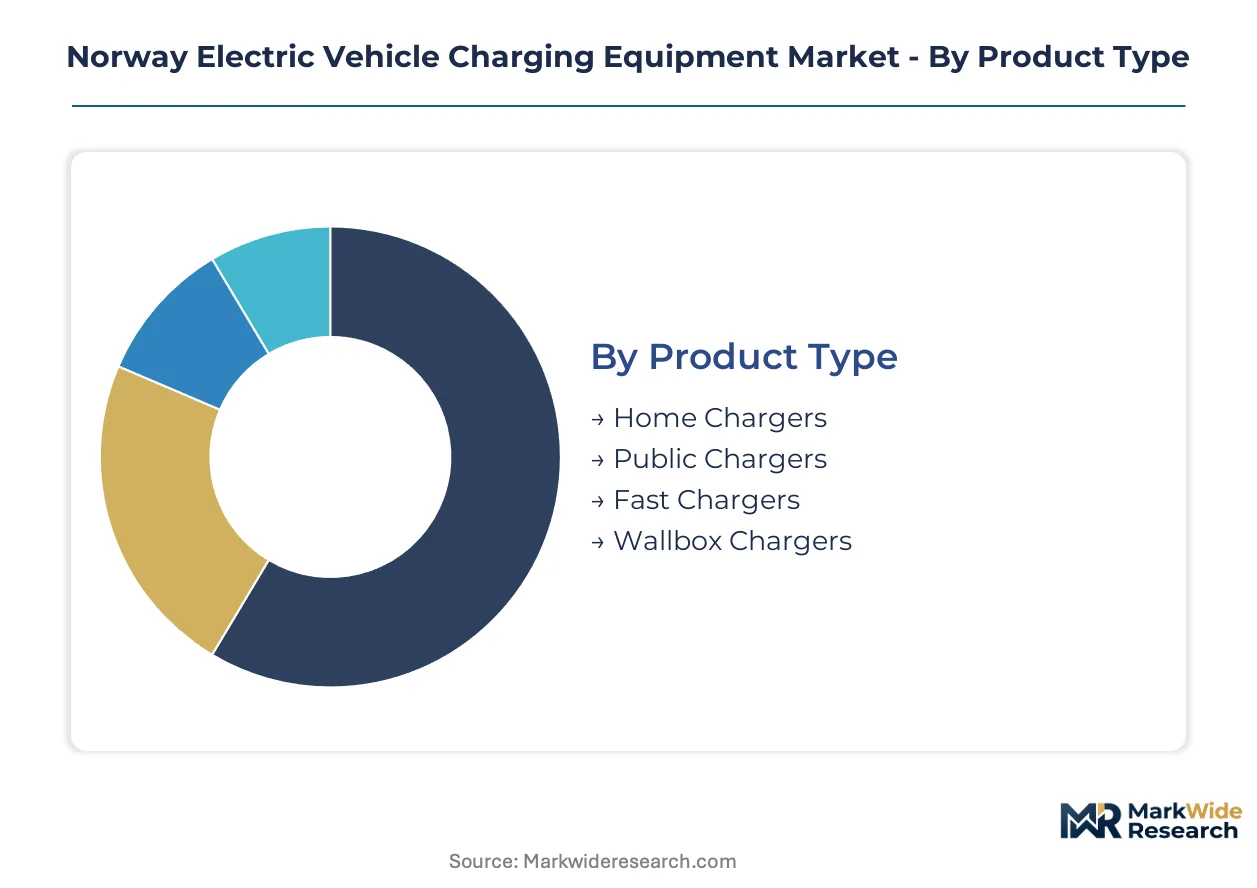
Norway's EV charging equipment market segments across hardware topology, power conversion technology, customer archetype, and physical deployment mode. Each dimension carries distinct margin profiles and regulatory compliance requirements under Enova SF subsidy frameworks.
Product Type:
The customization-to-standardization spectrum spans bespoke fleet depot configurations at one extreme and mass-produced residential units at the other.
- Home Chargers:Low-power AC units (3.7-22 kW) designed for single-family dwellings with Type 2 connectors. Demand clusters in Oslo's suburban corridors where detached housing permits dedicated parking. Grid operators mandate smart metering integration for new residential connections.
- Fast Chargers:High-capacity DC systems (50-350 kW) enabling rapid energy replenishment for commercial and corridor applications. Fleet operators in Vestland and Rogaland prioritize these for depot electrification, though grid reinforcement queues extend deployment timelines.
- Public Chargers:Medium-capacity AC and DC installations serving ad-hoc users in municipal parking structures and retail locations.
- Wallbox Chargers:Compact wall-mounted units optimized for multi-unit dwellings with space-constrained parking facilities.
Most installed capacity flows through Home Chargers. Expansion is steepest in Fast Chargers.
Technology:
Cost tier separation distinguishes premium intelligent systems from commodity power electronics.
- AC Charging:Alternating current conversion at 3.7-43 kW using onboard vehicle rectifiers. Residential and workplace installations in Bergen and Drammen favor this topology for capital efficiency.
- Smart Charging:Demand-response enabled systems with grid-to-vehicle communication protocols. Oslo's metropolitan grid operator mandates this capability for all new commercial connections, compressing deployment timelines for compliant hardware.
- DC Charging:Direct current output bypassing onboard conversion, enabling higher power delivery for fleet and corridor applications.
- Wireless Charging:Inductive power transfer systems pending IEC standardization for automated depot configurations.
Volume concentrates in AC Charging. Value expansion is climbing fastest in Smart Charging.
End User:
Customer type determines procurement scale and service contract complexity.
- Fleet Operators:Centralized logistics and public transport entities with binding zero-emission mandates. These customers consolidate charging service contracts under single-vendor arrangements bundling hardware, installation, and energy management across depot networks.
- Residential Users:Individual BEV owners installing single-point solutions. Site access limitations in Norwegian multi-unit dwellings constrain penetration rates for this segment.
- Businesses:Commercial property owners and employers providing workplace charging amenities.
- Charging Networks:Specialized operators deploying corridor and urban fast-charging infrastructure under concession agreements with the Norwegian Public Roads Administration.
Capital deployment is heaviest among Fleet Operators. Residential Users maintain the broadest addressable base.
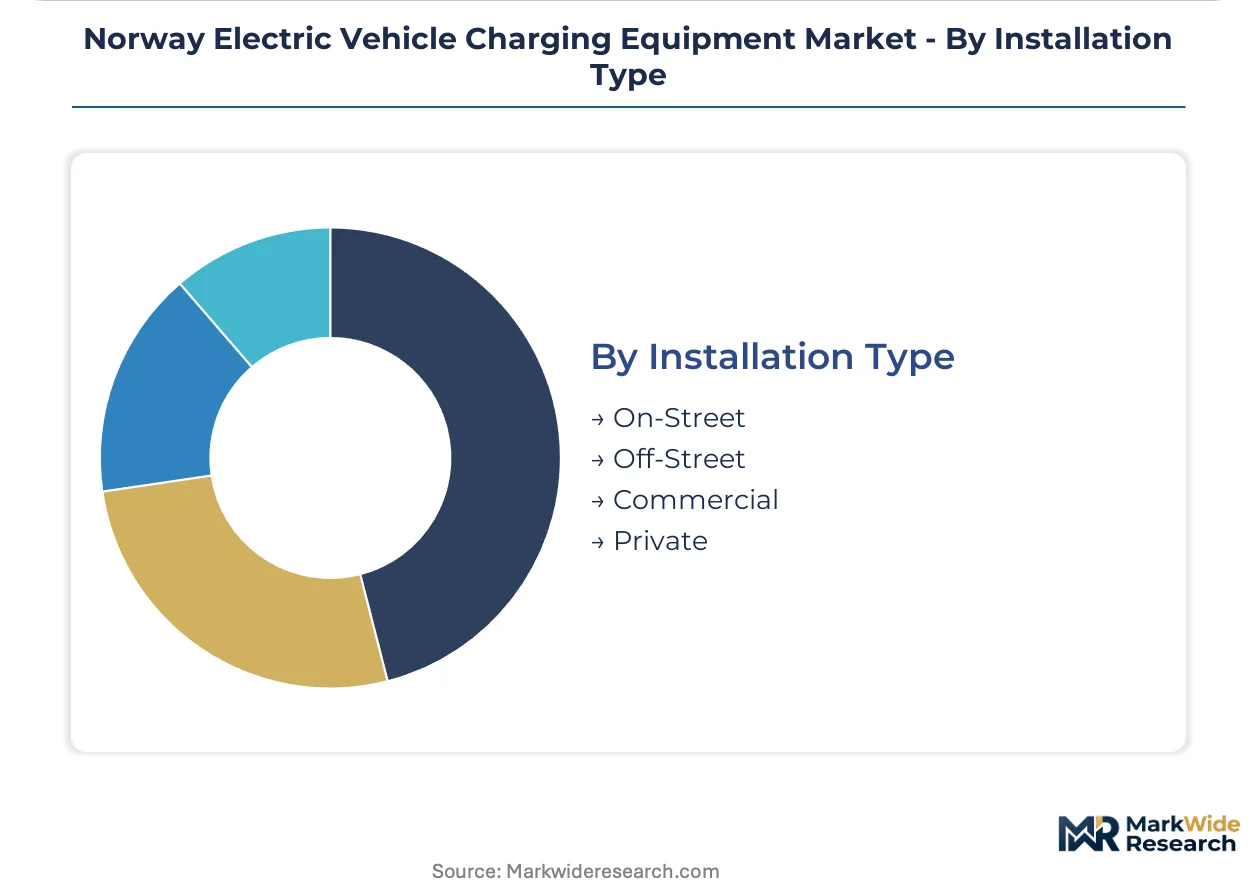
Installation Type:
Geography and site control shape deployment economics and regulatory pathways.
- Off-Street:Dedicated parking facilities with controlled access including residential driveways and commercial depots. These locations permit faster grid connection processing by the Norwegian Water Resources and Energy Directorate due to simplified permitting.
- On-Street:Curb-side installations in dense urban cores where parking scarcity complicates infrastructure placement. Oslo's municipal authorities prioritize these for coverage density compliance under EU Alternative Fuels Infrastructure Regulation.
- Commercial:Retail and workplace locations with mixed public-private access models.
- Private:Restricted-access installations serving single entities or households.
Connection volume runs highest through Off-Street deployments. Regulatory pressure is intensifying fastest for On-Street expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys DC fast chargers at triple Norway's per-capita rate, yet Oslo's metropolitan corridor achieves higher utilization density due to concentrated BEV ownership and stricter zero-emission mandates.
Oslo Metropolitan Corridor
Oslo's urban core and surrounding Akershus municipalities concentrate over forty percent of Norway's installed charging capacity. The Norwegian Water Resources and Energy Directorate processes grid connections here faster than northern regions, though queues still extend twelve to eighteen months for high-capacity depot installations. Drammen and Lillestrøm industrial zones host fleet electrification clusters serving grocery logistics and parcel delivery networks.
Vestland
Bergen anchors Norway's second-largest charging hub, with municipal bus operators and maritime logistics firms driving depot-scale DC deployments. The county's topography creates corridor gaps along E39 highway segments, prompting Enova SF to direct subsidy capital toward fast-charger coverage in underserved fjord districts. Modular power electronics adoption runs highest here among regional bus fleets phasing in electric coaches.
Trøndelag
Trondheim's university and hospital networks generate steady workplace charging demand, while the E6 highway corridor north toward Nordland remains a priority for trunk road coverage mandates. Grid reinforcement lags charger installation timelines throughout the region, compressing deployment schedules for logistics operators serving Arctic supply chains. The Norwegian Public Roads Administration targets this corridor for next-phase concession awards.
Rogaland
Stavanger's energy sector transition drives corporate fleet electrification, with oil services firms repurposing engineering capabilities toward charging infrastructure deployment. Single-vendor service contracts consolidate hardware, installation, and energy management across depot networks. Sandnes and Haugesund municipalities enforce smart charging mandates for new commercial connections, accelerating demand-response compatible hardware adoption.
Northern Norway
Tromsø and Bodø face the most severe fast-charging gaps along E6 and E8 highway corridors, with winter conditions demanding cold-weather rated power electronics. Enova SF maintains higher subsidy rates here to offset lower utilization economics. The Norwegian Water Resources and Energy Directorate prioritizes grid stability assessments before approving high-capacity connections in this sparsely populated region.
Norway Electric Vehicle Charging Equipment Market Competitive Landscape
Top-tier vendors anchor domestic manufacturing and rapid delivery cycles, while international specialists compete on modular DC scalability and corridor coverage. The market structures around three tiers: Norway-based wallbox specialists, Nordic fast-charging system integrators, and global power electronics conglomerates. Strategic archetypes include domestic manufacturing defenders, modular scalability specialists, and integrated energy service providers. Competitive moves concentrate on fleet service contract consolidation and smart charging protocol certification races.
Among Norway-based specialists, Zaptec and Easee occupy positions exemplifying domestic manufacturing archetypes with compact residential and multi-unit dwelling solutions. Kempower anchors the fast-charging tier with modular DC systems. International presence includes ABB Ltd, Delta Electronics Inc., ChargePoint Inc, Tesla Inc., and BYD Company Limited, representing global power electronics and integrated mobility service capabilities.
| Leading Market Players |
|---|
| Zaptec |
| Easee |
| Mer |
| Kempower |
| ABB Ltd |
| Delta Electronics Inc. |
| ChargePoint Inc |
| Tesla Inc. |
| BYD Company Limited |
| Others |
Pricing and Supply Chain Analysis
Fleet procurement consolidation under single-vendor service contracts is forcing hardware suppliers to absorb installation and energy management costs into bundled pricing, compressing standalone equipment margins while rewarding integrated service providers with pricing power.
Pricing Analysis
Capacity additions in China's power electronics manufacturing are reshaping price floors for AC wallbox units, though DC fast charger systems retain premium positioning due to prolonged grid connection queues in Norway. Three-tier pricing structure across premium smart charging, standard AC hardware, and economy basic units separates vendors by certification tier and after-sales service bundling. Cost compression in residential segments is intensifying because Zaptec and Easee compete on domestic manufacturing scale. Fleet operators show least price sensitivity due to binding zero-emission mandates, while residential users in multi-unit dwellings face highest price sensitivity from site access constraints.
Supply Chain Analysis
Regional distribution centers in Germany and the Netherlands serve as primary hubs for power electronics components entering Norway, with final assembly increasingly shifting to domestic facilities near Drammen. Semiconductor supply draws from Taiwan, Germany, and South Korea, while copper conductor sourcing rests on Chile and Zambia extraction. Single-source vulnerability in IGBT and SiC chip supply creates exposure to export licensing disruptions. Distribution runs through direct OEM-to-fleet relationships for depot-scale deployments, bypassing traditional electrical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular DC power electronics standardization is compressing capital deployment risk across fleet depot configurations, expanding margin capture for vendors that bundle hardware with energy management software subscriptions.
For Market Incumbents: Lock in fleet service contract renewals by embedding predictive maintenance software into existing hardware installations before modular competitors displace legacy systems. Secure captive supply of SiC semiconductors through backward integration or long-term offtake agreements with German and Taiwanese foundries to defend against supply disruption. Prioritize certification investment for vehicle-to-grid interoperability as the Norwegian Water Resources and Energy Directorate signals forthcoming bidirectional power flow mandates. For New Entrants and Emerging Players: Northern Norway logistics operators represent the most penetrable buyer archetype, as E6 and E8 corridor gaps and winter-rated hardware requirements deter established vendors focused on Oslo density. Target municipal bus operators in Trøndelag with lease-to-own financing structures that defer capital outlay until grid reinforcement completion. Pursue white-label manufacturing partnerships with Vestland-based system integrators to bypass 12-18 month grid connection queue disadvantages. For Investors and Strategic Acquirers: Asymmetric upside sits with vehicle-to-grid software aggregators positioned to capture bidirectional power flow revenue streams before regulatory frameworks crystallize. Long-term viability favors acquisition targets with certified installation workforce pipelines and existing Enova SF subsidy administration capabilities. Watch for inflection signals in Norwegian Water Resources and Energy Directorate grid tariff reform announcements that would shift cost recovery toward capacity-based structures.| Strategic Initiative | Industry Significance |
|---|---|
| Modular DC Power Electronics Scale-Up | Enables phased fleet depot investment aligned with vehicle procurement cycles without full system replacement. |
| Smart Charging Protocol Certification | Oslo's grid operator mandates demand-response compatibility as precondition for commercial connection approval. |
| Vehicle-to-Grid Software Development | Aggregator business models for bidirectional power flows create new revenue streams under evolving tariff structures. |
| Domestic Assembly Footprint Expansion | Proximity to Drammen and Bergen industrial zones compresses delivery cycles for Enova SF subsidy-eligible projects. |
| Installation Workforce Pipeline Investment | Qualified electricians with high-voltage DC training scarcity constrains deployment timelines for fleet operators. |
Research Methodology
Multiple input streams — primary interviews with charging network operators, fleet procurement directors, and grid connection engineers, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Stakeholder consultation encompassed equipment manufacturers, Enova SF program administrators, Norwegian Water Resources and Energy Directorate permitting officials, and municipal transport authorities. Secondary sources included EU Alternative Fuels Infrastructure Regulation implementation filings, Norwegian Public Roads Administration concession records, and power electronics trade flow databases.
Data-stream reconciliation applied across the projection horizon modeled segmentation by hardware topology, power conversion technology, customer archetype, and installation type, with additional dimensioning for grid connection queue status. CAGRs were derived from installed capacity buildout trajectories, subsidy program budget allocations, and fleet electrification mandate compliance schedules. Forecast inputs incorporated copper and semiconductor commodity price indices, grid reinforcement project timelines, and wireless charging standardization progress.
Underlying measurement precision varies by segment; fast charger and fleet depot deployments carry tighter precision than residential wallbox penetration estimates due to Enova SF disclosure requirements. Forecasts reflect documented assumptions regarding subsidy continuation, grid tariff structure stability, and EU-EEA regulatory alignment. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging Products Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Bidirectional Charging Units Market
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Copper in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Asia-Pacific Brushless DC Motors Market
Electric Vehicle Charging
Multi-Brand Universal Home Charging Pile Market
Electric Vehicle Charging
Electric Vehicle Charging Station Market
Electric Vehicle Charging
EV Charging Management Software Platform Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
Pantograph Charger Market
Electric Vehicle Charging
Asia-Pacific Portable EV Charger Market
Electric Vehicle Charging
Smart EV Battery Charger Market