
 Solid-State Batteries for Electric Vehicles Market | 2026-2036
Solid-State Batteries for Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Solid-State Batteries for Electric Vehicles Market Insights
OEM supply pipelines for solid-state EV cells is narrowing as pre-qualification requirements harden. Toyota anchors Japan's solid-state roadmap through in-house sulfide-electrolyte development. Samsung SDI competes from South Korea's Gyeonggi cluster, leveraging polymer-ceramic hybrid architectures. QuantumScape dominates oxide-electrolyte licensing in the US-German corridor, positioning its separator platform for European OEM integration.
Solid-state batteries for electric vehicles replace flammable liquid electrolytes with ion-conducting solids—typically sulfide, oxide, or polymer-ceramic composites—enabling energy densities above 400 Wh/kg and operating ranges extending past 1,000 charge cycles. Their primary purpose is eliminating thermal runaway risk while compressing pack volume for extended-range EV architectures. Pouch cell formats lead prototyping investment due to flexible stacking geometry, yet prismatic designs are capturing structural attention as automakers seek cell-to-pack integration. High-capacity segments concentrate margin pools where sulfide electrolyte manufacturing yields remain the binding constraint.
NHTSA's updated battery safety protocols and the EU's F-Gas Regulation are accelerating solid-state qualification timelines by mandating non-flammable chemistries in premium vehicle classes. Japan's METI funds sulfide-electrolyte pilot lines through national technology roadmaps, while South Korea's MFDS aligns medical-grade purity standards with battery-grade ceramic processing. Stakeholders must monitor electrolyte yield rates at pilot scale, as these determine which manufacturing process—sintering, vapor deposition, or slurry casting—achieves commercial viability first.
Market Dynamics
Sulfide electrolyte manufacturing yields remain the binding constraint on commercial rollout, with pilot-line defect rates dictating which solid-state architectures reach automotive qualification first.
Growth Catalysts
- NHTSA thermal-runaway mandates:Updated battery safety protocols in the US now mandate non-flammable chemistries for premium vehicle classes, forcing OEMs to accelerate solid-state qualification timelines.
- South Korea's Gyeonggi cluster concentration:Dense supplier networks around Samsung SDI and Hyundai Motor Group enable rapid iteration between cell prototyping and vehicle integration testing.
- Sulfide electrolyte energy density:The material pathway delivers theoretical capacities above 400 Wh/kg, compressing pack volume requirements for extended-range EV architectures.
Market Restraints
- Ceramic precursor cost volatility:High-purity lithium sulfide and rare-earth dopants face concentrated mining supply from limited geographies, inflating raw material exposure.
- Japan METI funding concentration:National technology roadmaps channel public capital toward domestic sulfide-electrolyte champions, creating asymmetric access for foreign competitors.
- Dendrite penetration mechanics:Lithium metal anodes in solid-state configurations remain vulnerable to filament growth during fast-charge cycles, capping power density targets.
Strategic Opportunities
- EU F-Gas Regulation alignment:The phasedown of fluorinated greenhouse gases in thermal management systems creates regulatory tailwinds for solid-state's reduced cooling requirements.
- Structural battery integration:Cell-to-pack architectures that use prismatic solid-state cells as load-bearing chassis elements open new value capture in vehicle engineering.
- Medical-grade ceramic processing:South Korea's MFDS purity standards for implantable devices transfer directly to battery-grade sulfide manufacturing, attracting cross-industry talent.
Industry Challenges
- Dry-room capex intensity:Sulfide-electrolyte production requires sub-10 ppm humidity environments, multiplying facility construction costs versus conventional lithium-ion lines.
- Automotive qualification timelines:OEMs demand 1,000+ charge-cycle validation before platform integration, stretching development cycles beyond typical venture capital horizons.
- IP thickets around oxide separators:QuantumScape's patent estate and licensing terms complicate entry for competitors pursuing ceramic-electrolyte pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid-State Batteries for Electric Vehicles Market |
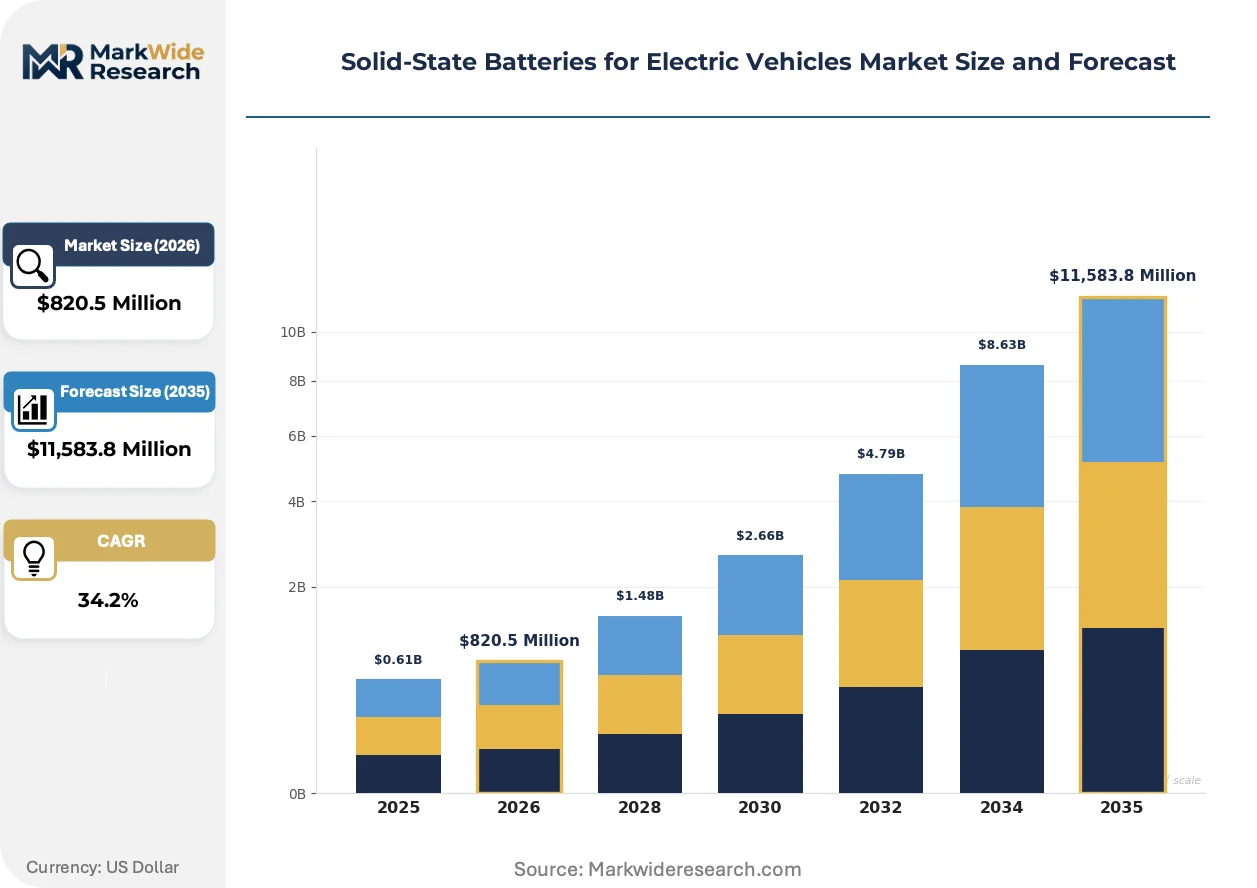
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $11,583.8 Million |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-Film, Prismatic, Coin Cell, Pouch Cell Technology: Electrolyte Materials, Separator Technology, Manufacturing Process, Recharging Mechanism End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Vehicles Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | Solid Power, QuantumScape, Toyota, ProLogium Technology, Factorial Energy, Blue Solutions, Samsung SDI, BYD, Ilika, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid-State Batteries for Electric Vehicles Market Trends and Innovations
Solid-state manufacturing is bifurcating between vapor-deposition precision and slurry-casting scale, with equipment suppliers retooling for whichever process achieves yield parity first.
Polymer-ceramic hybrid electrolytes are virtualizing the traditional liquid-electrolyte supply chain by enabling room-temperature ionic conductivity without flammable solvents. Korean tier-one suppliers are piloting these architectures for mid-range EV platforms where cost sensitivity exceeds performance extremes. The technology is virtualizing incumbent separator and electrolyte filling equipment, forcing equipment vendors to reposition toward solid-state deposition tools.
The EU's F-Gas Regulation is compressing thermal management system choices by restricting fluorinated refrigerants in vehicle climate control. Solid-state cells' reduced cooling requirements now align with compliance pathways that liquid-electrolyte batteries cannot satisfy without costly redesign. Premium German OEMs are restructuring platform thermal architectures around this regulatory constraint, prioritizing cell suppliers with verified low-heat-generation chemistries.
Fleet procurement is consolidating around cell-to-pack specifications that embed solid-state cells as structural elements rather than modular replacements. Logistics operators and ride-hail platforms are rewriting RFP language to prioritize volumetric energy density over upfront cell cost, reflecting total-cost-of-ownership models that favor extended cycle life. This specification shift is most visible in California's commercial EV incentive programs, where range and durability thresholds now exclude conventional lithium-ion from premium credit tiers.
Solid-State Batteries for Electric Vehicles Market Segmentation
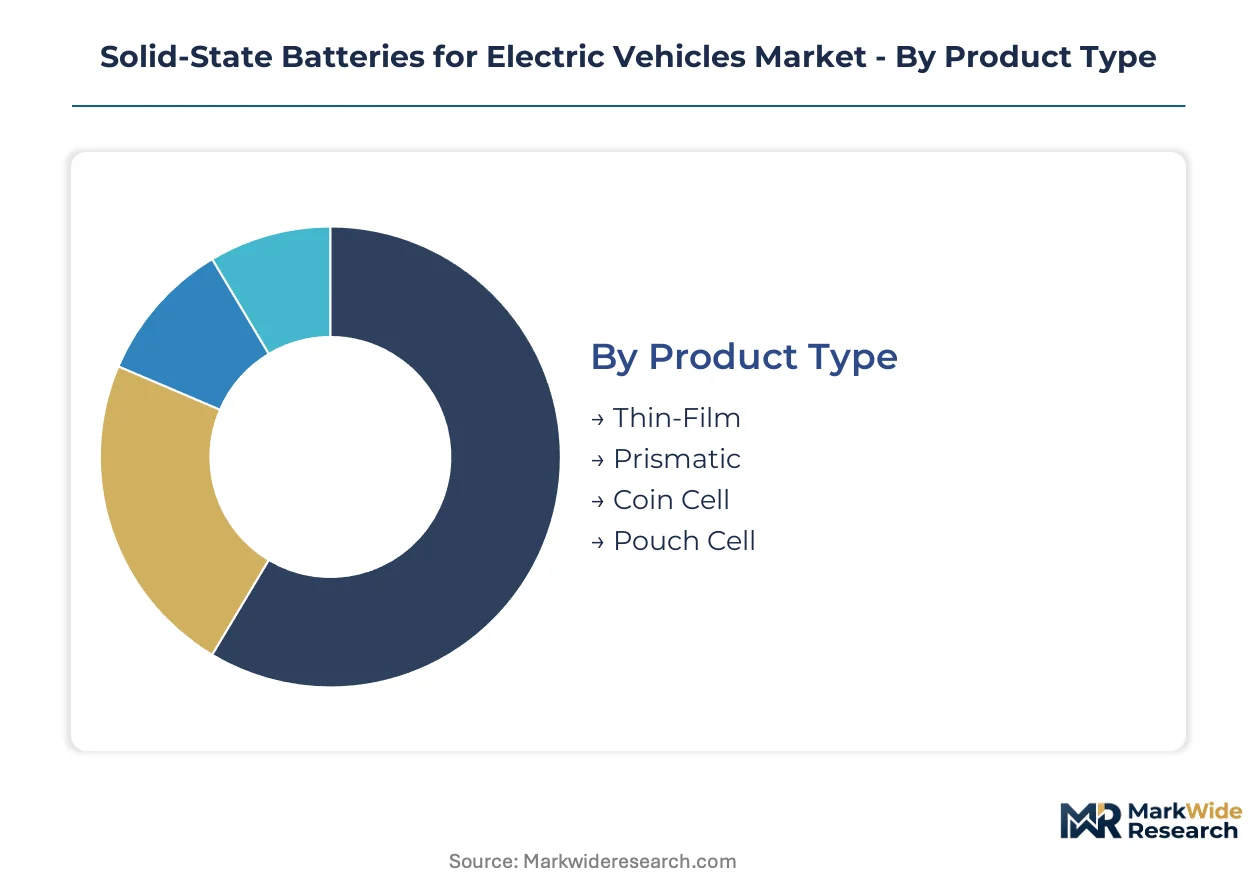
Solid-state battery architectures diverge sharply across form factors and electrolyte pathways, with each segment demanding distinct manufacturing investments and qualification timelines. OEM procurement teams segment supplier evaluations by thermal management requirements, structural integration potential, and cycle-life validation thresholds.
Product Type:
Pouch cells turn over fastest in pilot programs as automakers iterate stacking geometries, while prismatic formats face extended validation cycles for structural battery integration.
- Thin-Film:Micro-scale solid-state layers fabricated via vapor deposition achieve sub-millimeter profiles ideal for sensor-integrated vehicle electronics. Demand concentrates in German premium OEM cockpit systems where space constraints override energy density targets, though manufacturing throughput remains limited by chamber-based batch processing.
- Prismatic:Rigid rectangular housings enable direct cell-to-pack mounting as chassis load-bearing elements. South Korean automakers anchor qualification programs around prismatic sulfide cells for extended-range SUVs, driven by NHTSA structural integrity mandates for battery enclosures in premium vehicle classes.
- Coin Cell:Compact cylindrical formats serve diagnostic and backup power functions within EV electrical architectures.
- Pouch Cell:Flexible laminated enclosures dominate prototyping investment due to rapid geometry adaptation and minimal tooling changeover costs.
Prismatic formats anchor the volume base while pouch cells gain share at the steepest rate.
Technology:
Cost tiers separate precision deposition equipment from slurry-casting scale infrastructure, with electrolyte material purity driving the widest margin spreads.
- Electrolyte Materials:Sulfide compounds deliver ionic conductivity exceeding liquid electrolytes at room temperature, but lithium sulfide precursor costs fluctuate with concentrated mining supply from select geographies. Japanese METI-funded pilot lines prioritize sulfide pathways for domestic OEM integration, leveraging national technology roadmaps to compress yield learning curves.
- Separator Technology:Ceramic-oxide laminates manufactured through thin-film sputtering prevent dendrite penetration during fast-charge cycles. US-German licensing corridors concentrate around oxide separator IP, with European automakers demanding verified thermal stability above 300°C for premium platform qualification.
- Manufacturing Process:Vapor deposition achieves precision layer control at limited throughput; slurry casting promises scale but struggles with defect rates.
- Recharging Mechanism:Lithium metal anode interfaces require modified current collector architectures to manage volume expansion.
Electrolyte materials capture the dominant cost position while separator technology expands most quickly through cross-licensing arrangements.
End User:
Application requirements stratify by duty cycle intensity, with commercial fleet operators rewriting procurement specifications around total-cost-of-ownership models.
- Passenger Vehicles:Premium OEM platforms in Germany and Japan drive pre-production orders as thermal-runaway safety mandates harden. Cell suppliers compete on volumetric energy density above 400 Wh/kg for extended-range sedan architectures, with qualification timelines stretching across multiple charge-cycle validation protocols.
- Commercial Vehicles:Logistics operators prioritize cycle life over upfront cell cost, reflecting utilization rates that exhaust conventional lithium-ion within 3-4 years. California commercial EV incentive programs now exclude liquid-electrolyte batteries from premium credit tiers, redirecting fleet procurement toward solid-state specifications.
- Two-Wheelers:Compact pack requirements favor polymer-ceramic hybrids with reduced cooling infrastructure.
- Heavy-Duty Vehicles:Mining and construction applications demand abuse-tolerant cell architectures for uncontrolled temperature environments.
Passenger vehicles anchor the volume base while commercial vehicles gain share at the steepest rate.
Capacity:
Supply concentration tightens at the ultra-high threshold, where sulfide electrolyte manufacturing yields remain the binding constraint on commercial rollout.
- Low Capacity:Sub-20 kWh packs serve auxiliary power and range-extender functions in hybrid architectures.
- Medium Capacity:20-50 kWh configurations target urban commuter segments with moderate range requirements.
- High Capacity:50-100 kWh packs dominate premium SUV and sedan platforms where energy density directly enables competitive range positioning. South Korea's Gyeonggi cluster concentrates high-capacity prototyping investment, with Samsung SDI and Hyundai Motor Group co-locating cell validation and vehicle integration testing.
- Ultra High Capacity:Exceeding 100 kWh, these architectures require breakthroughs in sulfide electrolyte layer uniformity to prevent localized heating. German OEMs anchor development partnerships around ultra-high capacity targets for luxury electric flagships, driven by EU F-Gas Regulation constraints on thermal management system complexity.
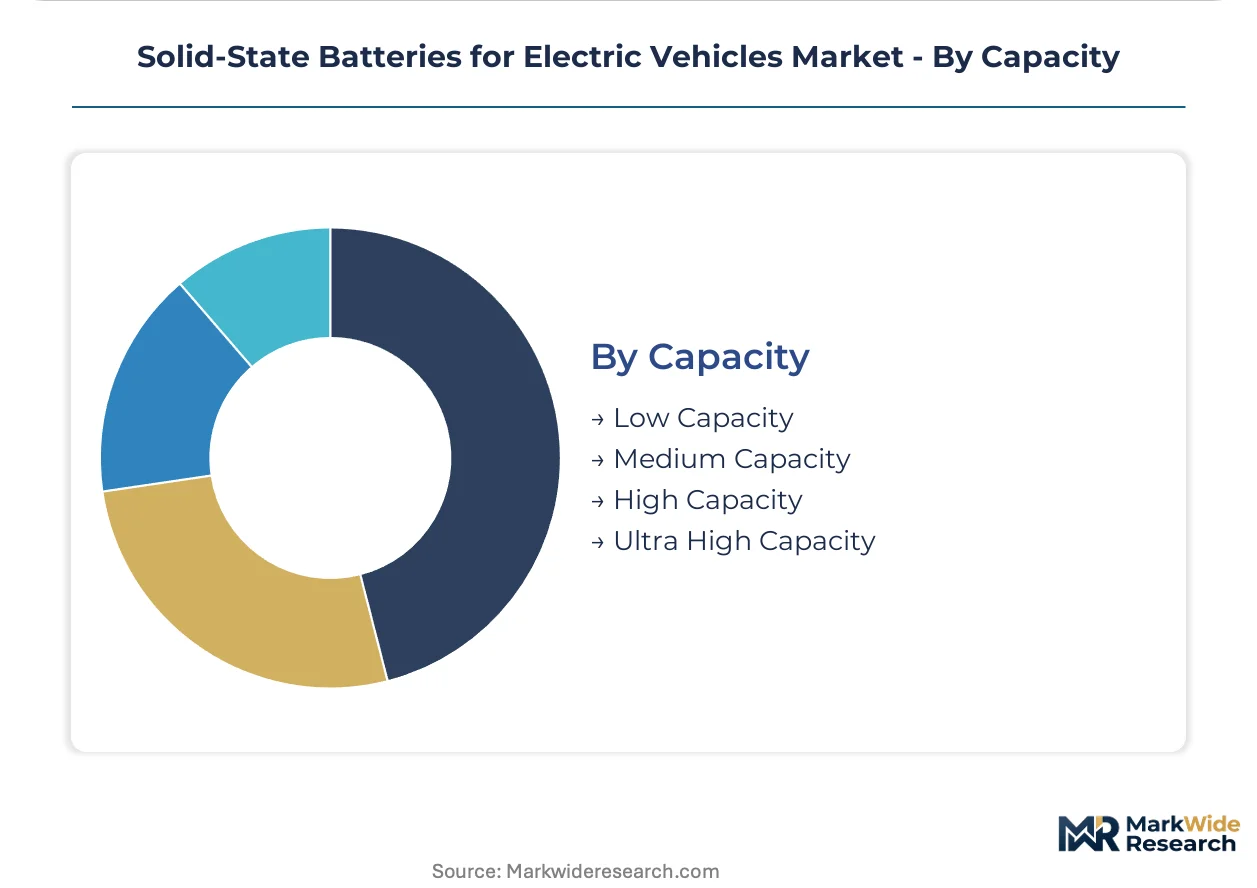
High capacity segments anchor the volume base while ultra high capacity gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korea's Gyeonggi cluster where Samsung SDI and Hyundai Motor Group co-locate validation facilities, while German premium OEMs absorb cost premiums for sulfide-electrolyte qualification. Japan's METI-funded pilot lines extract technology access concessions from foreign partners. Regulatory fragmentation across NHTSA, EU F-Gas, and Japan's safety mandates forces multi-jurisdictional compliance architectures.
United States
NHTSA thermal-runaway mandates accelerate solid-state qualification timelines for premium vehicle classes. The Inflation Reduction Act domestic content provisions reshape supplier selection criteria for battery tax credits. QuantumScape anchors oxide-electrolyte development in the San Jose corridor, licensing separator platforms to European OEMs seeking US market access.
Germany
Premium OEM platforms drive pre-production orders as EU F-Gas Regulation restricts fluorinated refrigerants in thermal management systems. KBA structural integrity mandates for battery enclosures favor prismatic cell-to-pack architectures. Bavaria's automotive engineering cluster concentrates around Munich-based validation partnerships for extended-range SUV platforms.
Japan
Toyota's in-house sulfide-electrolyte development anchors national technology roadmaps through METI-funded pilot lines. JIS standards for medical-grade ceramic processing transfer to battery-grade manufacturing requirements. Nagoya's Chubu region hosts concentrated prototyping investment between domestic OEMs and precursor chemical suppliers.
South Korea
MFDS medical-grade purity standards align with battery-grade sulfide manufacturing specifications. The Gyeonggi cluster enables rapid iteration between Samsung SDI cell prototyping and Hyundai Motor Group vehicle integration testing. Seoul Capital Area suppliers dominate polymer-ceramic hybrid architecture development for mid-range EV platforms.
China
Dual carbon goals accelerate non-flammable chemistry adoption in premium EV segments. MIIT battery safety protocols tighten parallel to NHTSA and EU regulatory trajectories. BYD anchors domestic solid-state development in Shenzhen's Pearl River Delta manufacturing corridor, leveraging captive vertical integration into precursor supply chains.
Solid-State Batteries for Electric Vehicles Market Competitive Landscape
Automotive OEMs and pure-play battery specialists split the market between captive technology development and open supplier licensing. The structure concentrates around three strategic archetypes: integrated automakers with in-house electrolyte programs, independent cell manufacturers pursuing hybrid architectures, and materials-focused licensors of separator platforms. Competitive moves center on pilot-line capacity expansion and cross-border technology partnerships to secure automotive qualification slots.
Within the integrated automaker tier, Toyota and BYD occupy positions defined by backward integration into sulfide-electrolyte precursor supply. Samsung SDI exemplifies the independent cell manufacturer archetype, leveraging South Korea's Gyeonggi cluster concentration for rapid validation cycles. QuantumScape represents the materials-licensing model, with its oxide-separator platform positioned for European OEM integration through US-German technology corridors.
| Leading Market Players |
|---|
| Solid Power |
| QuantumScape |
| Toyota |
| ProLogium Technology |
| Factorial Energy |
| Blue Solutions |
| Samsung SDI |
| BYD |
| Ilika |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor carries lithium sulfide precursors and ceramic dopants from concentrated mining geographies to European and Asian manufacturing clusters, with freight cost volatility feeding directly into sulfide-electrolyte pricing spreads and downstream cell cost differentiation between configured-to-order and standard specifications.
Pricing Analysis
The customization-premium spread separates configured-to-order sulfide-electrolyte cells from standard polymer-ceramic hybrid architectures, with pricing stratifying across premium, standard, and economy tiers based on electrolyte purity grades and NHTSA thermal-runaway certification status. Price differentiation rests on volume scale and vertical integration depth, with fully integrated OEMs capturing margin compression unavailable to merchant cell suppliers. Cost compression in standard-tier pouch cells is intensifying because Korean tier-one suppliers are scaling slurry-casting capacity. Fleet procurement teams show lowest price sensitivity, while mid-range passenger vehicle platforms exhibit highest cost elasticity.
Supply Chain Analysis
Extended payment terms from South Korean cell manufacturers to Australian and Chilean lithium sulfide miners are stabilizing precursor procurement against commodity price swings, though supply-chain finance facilities remain concentrated in Seoul Capital Area banking networks. Geographic supply concentration draws from Japan, South Korea, and China for sulfide-electrolyte precursor refining and ceramic-oxide separator fabrication. Raw material dependencies hinge on high-purity lithium sulfide, rare-earth dopants, and medical-grade alumina substrates. Single-source vulnerability persists in vapor-deposition equipment, where German and Japanese toolmakers control chamber-based batch processing. Distribution runs through co-located validation partnerships between Gyeonggi cluster cell prototyping and Hyundai Motor Group vehicle integration testing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
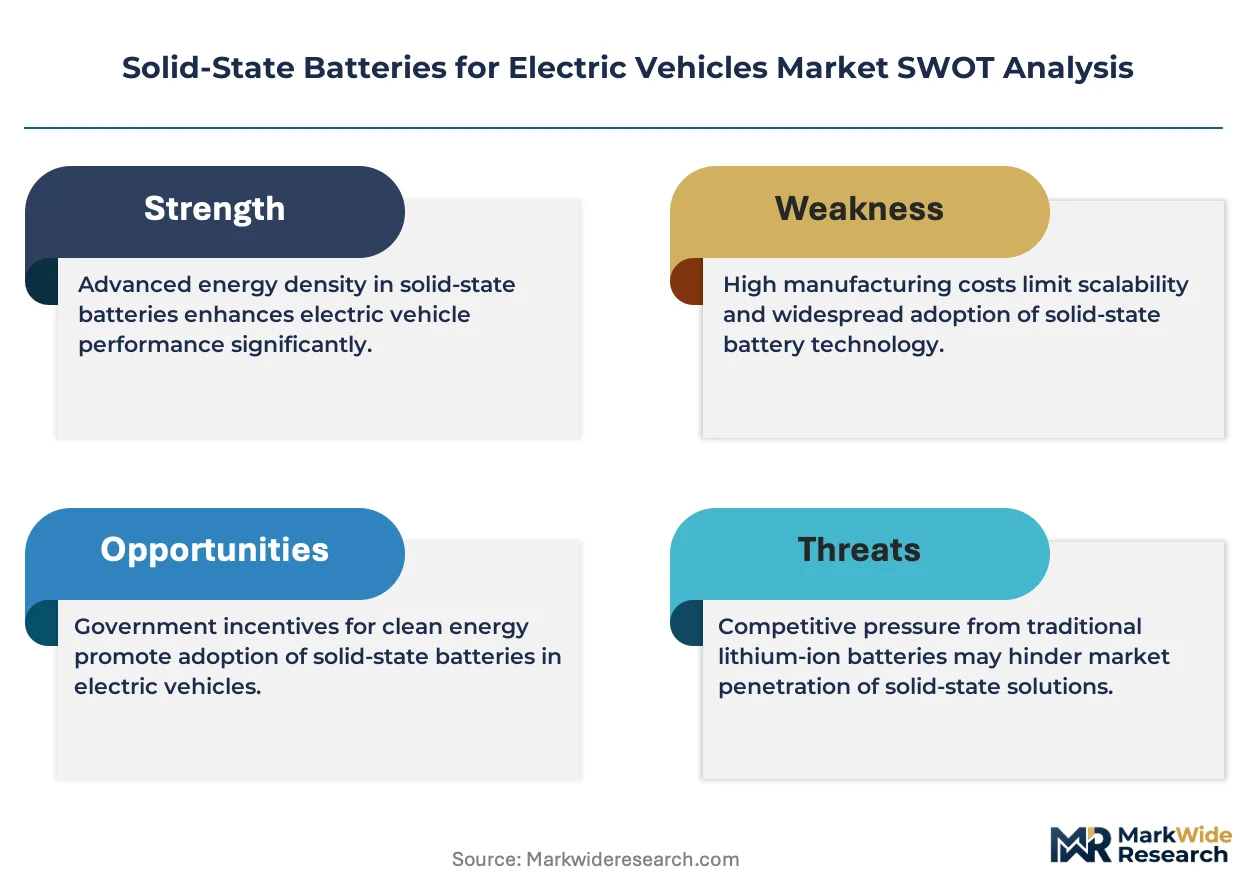
Solid-state battery procurement is fragmenting across electrolyte pathways and form factors, with NHTSA and EU F-Gas regulatory divergence creating distinct qualification niches that favor specialized suppliers over generalist incumbents.
For Market Incumbents: Insulate qualification slots by accelerating sulfide-electrolyte yield improvements at pilot scale before Korean competitors achieve slurry-casting parity. Deepen backward integration into Australian lithium sulfide offtake contracts to offset precursor cost volatility. Secure NHTSA pre-certification status for prismatic cell-to-pack architectures to defend against oxide-separator licensing entrants.
For New Entrants and Emerging Players: Establish a beachhead in polymer-ceramic hybrid architectures for California commercial fleet operators, where state incentive programs now exclude liquid-electrolyte competitors from premium credit tiers. Target medical-grade ceramic processing talent pools in South Korea's MFDS-regulated device sector for cross-industry recruitment. Lead with thermal management system simplification as the go-to-market angle, leveraging solid-state's reduced cooling requirements against incumbent redesign costs.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with captive sulfide-electrolyte precursor operations but no automotive qualification traction. Long-term viability favors materials licensors with oxide-separator patent estates and validated OEM partnerships over capital-intensive cell manufacturers. Watch sulfide-electrolyte pilot-line defect rates as the inflection indicator for which manufacturing process achieves commercial scale first.
| Strategic Initiative | Industry Significance |
|---|---|
| Sulfide-Electrolyte Pilot Line Expansion | Yield learning curves at METI-funded Japanese facilities determine qualification timelines for Toyota and domestic OEM integration. |
| Oxide-Separator Licensing Agreement | QuantumScape's platform access enables European automakers to bypass NHTSA thermal-runaway redesign costs for US market entry. |
| Cell-to-Pack Structural Integration | Prismatic solid-state formats as chassis load-bearing elements capture value from KBA enclosure mandates in German premium SUVs. |
| Medical-Grade Ceramic Processing Transfer | MFDS purity standards from South Korean implantable device manufacturing reduce sulfide-electrolyte contamination rates below 10 ppm. |
| Long-Term Precursor Supply Agreement | Australian lithium sulfide offtake contracts insulate Samsung SDI and Hyundai from concentrated mining supply price spikes. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with battery cell prototyping engineers, OEM platform integration managers, sulfide-electrolyte precursor procurement leads, thermal management system architects, and NHTSA regulatory affairs specialists. Secondary validation drew from MIIT battery safety protocol filings, EU F-Gas Regulation implementation guidance, METI technology roadmap disclosures, and SEC 10-K supply chain risk disclosures from listed automotive and materials companies. Bottom-up cell cost modeling and top-down market sizing triangulated volume estimates across the projection horizon.
Calibration against historical lithium-ion adoption curves and solid-state pilot-line yield disclosures anchored the analytical framework. Segmentation dimensions modeled include electrolyte material pathway, cell form factor, vehicle class integration, manufacturing process equipment type, and regional regulatory cluster. CAGRs were derived from slope analysis of technology readiness level transitions and automotive qualification timeline compression. Industry-specific forecast inputs incorporated vapor-deposition chamber throughput constraints and slurry-casting defect rate learning curves.
Sensitivities concentrate around sulfide-electrolyte manufacturing yield breakthroughs, NHTSA thermal-runaway mandate enforcement timing, and EU F-Gas Regulation phasedown acceleration. Forecasts reflect documented assumptions about pilot-line scale-up trajectories and OEM platform integration commitments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
South America Consumer Battery Market
Batteries
West Africa Battery Market
Batteries
Wood-Based Batteries Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Asia Power Tool Batteries Market
Batteries
US Solar Battery Market
Batteries
Japan Battery Market
Batteries
Lithium Marine Battery Market
Batteries
N-Type Battery Market
Batteries
Medical Batteries Market
Batteries
Global Solar Battery Charger Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
West Europe Battery Market
Batteries
United States SLI Battery Market
Batteries
Secondary Battery Market
Batteries
Absorbent Glass Mat (AGM) Battery Market