
 Battery Maintainer Market | 2026-2036
Battery Maintainer Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Maintainer Market Insights
Fleet operators is bifurcating from residential hobbyists as the dominant demand archetype in the battery maintainer landscape. CTEK Sweden AB dominates the European commercial channel with OEM-grade charging protocols for heavy-duty applications. The NOCO Co. competes aggressively in North American retail through compact lithium-compatible designs. Robert Bosch GmbH anchors the industrial segment with integrated diagnostic capabilities embedded into workshop equipment lines.
A battery maintainer is an electronic device that supplies a low-amperage trickle charge—typically 0.75 to 5 amps—while monitoring voltage thresholds, temperature coefficients, and sulfation states to preserve lead-acid or lithium-ion cells during storage cycles. Smart charger units incorporate microprocessor-controlled multi-stage algorithms that adjust float voltage based on ambient thermal conditions, preventing electrolyte stratification in flooded batteries. Solar maintainer configurations represent the fastest-expanding product category as off-grid marine and RV installations proliferate, though automatic charger variants still capture the largest margin pool due to their integration into dealership service bays. Fleet operators drive premiumization toward units with LCD diagnostics and temperature compensation, while residential buyers gravitate toward overcharge-protected entry models sold through automotive parts stores.
The EPA enforces battery recycling mandates under RCRA standards that shape disposal protocols for maintainer-equipped fleets, while the EU F-Gas Regulation and CE marking requirements constrain charger electronics sold into European marine harbors. California Air Resources Board zero-emission fleet rules indirectly stimulate maintainer demand by extending battery replacement intervals for hybrid commercial vehicles. Stakeholders must monitor how NHTSA evolving guidelines on vehicle auxiliary power systems reshape charger interface standards before committing to next-generation platform designs.

Market Dynamics
Fleet electrification mandates are compressing replacement cycles for commercial vehicle batteries while forcing maintainer manufacturers to engineer multi-chemistry platforms that handle both legacy lead-acid and emerging lithium-ion architectures without manual reconfiguration.
Growth Catalysts
- California ZEV fleet rules:Commercial operators in California face accelerating battery replacement schedules for hybrid work trucks, driving maintainer procurement to extend cell longevity and defer capital outlays.
- Marine harbor infrastructure:Port authorities from Long Beach to Rotterdam are installing shore-power systems with integrated battery conditioning for electric tugboats and harbor craft, creating sustained demand for industrial-grade maintainers.
- Microprocessor-controlled multi-stage charging:Advanced algorithms now automatically adjust float voltage based on ambient thermal conditions, eliminating manual intervention and reducing electrolyte stratification failures in flooded batteries.
Market Restraints
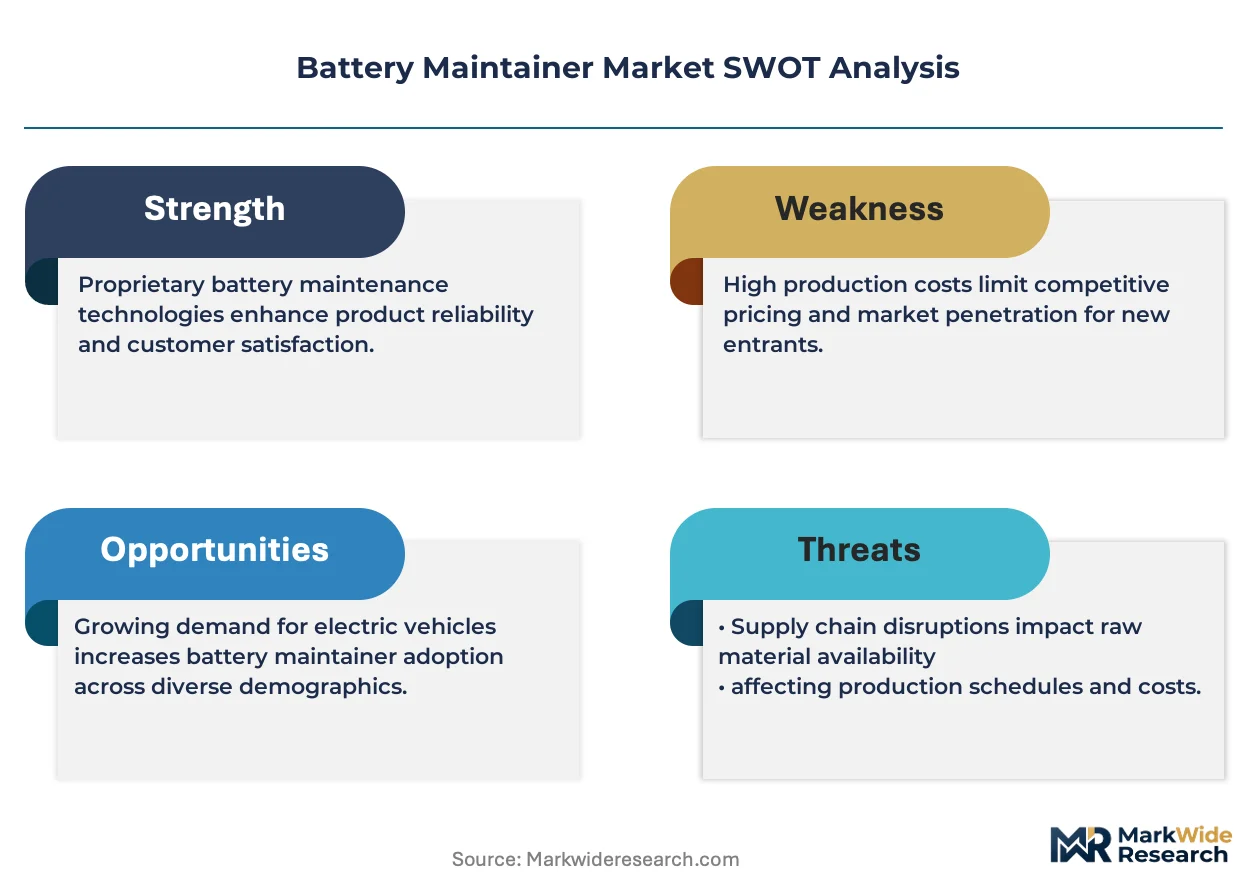
- Semiconductor supply concentration:Microcontroller fabrication for smart charger logic concentrates in Taiwanese foundries, exposing OEMs to allocation delays and forcing extended lead times for temperature-compensated units.
- Raw material volatility:Copper windings and rare-earth magnets in transformer cores face price swings that compress margins on entry-level automatic charger variants sold through automotive retail channels.
- Technical interoperability gaps:Absence of unified communication protocols between maintainer units and fleet telematics systems forces redundant hardware layers and inflates total cost of ownership for multi-vendor deployments.
Strategic Opportunities
- Off-grid marine and RV solar installations:Solar maintainer configurations represent underpenetrated white space as boaters and recreational vehicle owners seek autonomous charging without shore power dependency.
- EU F-Gas Regulation alignment:Charger electronics sold into European marine harbors must meet CE marking and F-Gas compliance, creating a regulatory moat for suppliers who pre-certify integrated diagnostic capabilities.
- Telematics convergence with battery management:Fleet operators are demanding LCD-enabled maintainers that stream voltage and sulfation data directly into cloud-based asset tracking platforms, opening software-subscription revenue streams.
Industry Challenges
- Embedded systems firmware expertise:Shortage of engineers fluent in both power electronics and automotive-grade software stacks delays product launches for multi-chemistry platforms with over-the-air update capability.
- NHTSA auxiliary power interface standards:Evolving guidelines on vehicle charger connection protocols force design teams to maintain multiple hardware variants pending final rulemaking, inflating engineering overhead.
- RCRA battery recycling compliance:Fleet operators equipped with maintainers face complex disposal documentation for desulfated cells, requiring supplier investment in reverse-logistics programs and recycling partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Maintainer Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Charger, Solar Maintainer, Automatic Charger, Manual Charger End User: Residential Users, Automotive Enthusiasts, Fleet Operators, Marine Operators Features: Overcharge Protection, Temperature Compensation, LCD Display, Multiple Charging Modes Distribution Channel: Online Retailers, Automotive Parts Stores, Home Improvement Stores, Specialty Shops |
| Companies Covered | CTEK Sweden AB, The NOCO Co., Battery Tender, Schumacher Electric Corp., Robert Bosch GmbH, Stanley Black and Decker Inc., Exide Technologies, EnerSys, Deltran Battery Tender, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Maintainer Market Trends and Innovations
Smart charging architectures are fragmenting the competitive landscape as OEM-grade protocols diverge from retail-compatible designs, forcing suppliers to choose between fleet service bay integration and consumer automotive channel penetration.
Multi-chemistry charging hardware is bifurcating the product roadmap as commercial fleet buyers demand unified lead-acid and lithium-ion support while residential hobbyists prioritize compact single-chemistry units. Heavy-duty applications in municipal bus depots and airport ground support fleets are adopting switch-mode power supplies with adaptive current limiting. This capability compression is eliminating standalone charger categories and collapsing maintainer functionality into broader vehicle power management systems.
EPA enforcement of RCRA battery recycling mandates is reshaping aftermarket service economics by requiring documented disposal chains for cells conditioned through maintainer cycles. Fleet maintenance divisions must now integrate recycling logistics into procurement decisions. California Air Resources Board zero-emission commercial vehicle rules indirectly amplify this pressure by extending battery replacement intervals and increasing the volume of regulated waste per vehicle lifecycle.
Direct procurement from maintainer manufacturers is displacing traditional automotive parts distributor intermediation as large fleet operators centralize charging equipment standardization. Procurement teams at national logistics companies now negotiate master service agreements with OEMs rather than sourcing through regional jobbers. This channel compression is most visible in the United States, where commercial fleet electrification concentrates purchasing power among fewer buyers with dedicated energy management divisions.
Battery Maintainer Market Segmentation
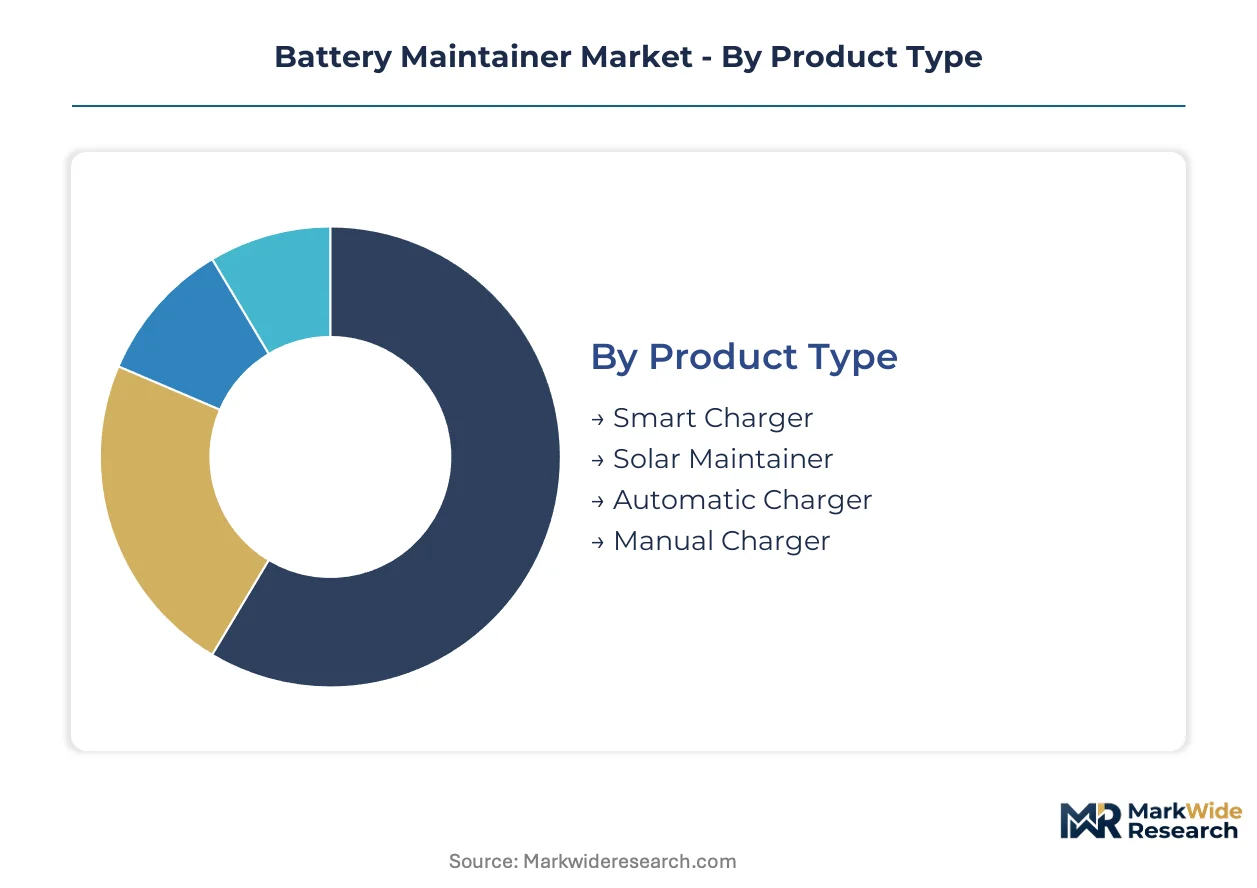
Segmentation in the battery maintainer market reveals divergent technology requirements across customer archetypes. Fleet procurement teams prioritize diagnostic integration and multi-chemistry compatibility, while residential buyers favor compact units with simplified safety features.
Product Type:
Domestic demand concentrates in smart charger and automatic charger variants, whereas solar maintainer exports are accelerating toward European marine harbors and off-grid installations.
- Smart Charger:Microprocessor-controlled units execute multi-stage charging algorithms that adjust float voltage based on ambient thermal sensors. Fleet operators in California municipal depots are standardizing these for hybrid work truck fleets facing compressed replacement cycles under CARB zero-emission mandates.
- Solar Maintainer:Photovoltaic-powered configurations eliminate shore-power dependency for marine and RV applications. Boat owners in the Netherlands and Germany are driving procurement as EU F-Gas Regulation compliance tightens harbor infrastructure requirements.
- Automatic Charger:Entry-level units with fixed voltage thresholds dominate automotive retail channels. Copper winding costs in transformer cores are pressuring margins on these variants.
- Manual Charger:Basic trickle-charge units without thermal compensation persist in hobbyist segments. Demand is fragmenting toward developing markets with limited smart grid penetration.
Automatic charger holds the largest share; momentum sits with solar maintainer.
End User:
Cost tier stratification separates premium fleet-grade procurement from price-sensitive residential channels.
- Fleet Operators:National logistics companies negotiate master service agreements directly with OEMs, bypassing traditional automotive distributors. These buyers demand LCD-enabled units streaming voltage data into cloud-based asset tracking platforms.
- Marine Operators:Port authorities from Long Beach to Rotterdam install shore-power systems with integrated battery conditioning for electric tugboats. EU CE marking and F-Gas compliance create regulatory moats for certified suppliers.
- Automotive Enthusiasts:Hobbyists prioritize compact lithium-compatible designs sold through specialty retailers. Overcharge protection features command modest premiums in this segment.
- Residential Users:Price-conscious buyers gravitate toward entry models with basic sulfation monitoring. Online retailers and home improvement stores capture the majority of this volume.
Fleet operators command the highest unit economics; marine operators are expanding most quickly.
Features:
Application severity determines feature bundling, with commercial deployments requiring full diagnostic suites.
- Temperature Compensation:Ambient thermal sensors adjust charging voltage to prevent electrolyte stratification in flooded lead-acid batteries. Municipal bus depots are mandating this capability for outdoor charging infrastructure.
- LCD Display:Real-time voltage and sulfation readouts enable predictive maintenance workflows. Fleet telematics convergence is driving software-subscription revenue streams around this feature.
- Overcharge Protection:Voltage cutoff circuits prevent cell damage during extended storage cycles. Residential buyers treat this as a baseline safety requirement rather than a differentiator.
- Multiple Charging Modes:Toggle between lead-acid and lithium-ion protocols without hardware reconfiguration. Semiconductor supply constraints from Taiwanese foundries are delaying multi-chemistry platform launches.
Temperature compensation anchors commercial specifications; LCD display is gaining share fastest.
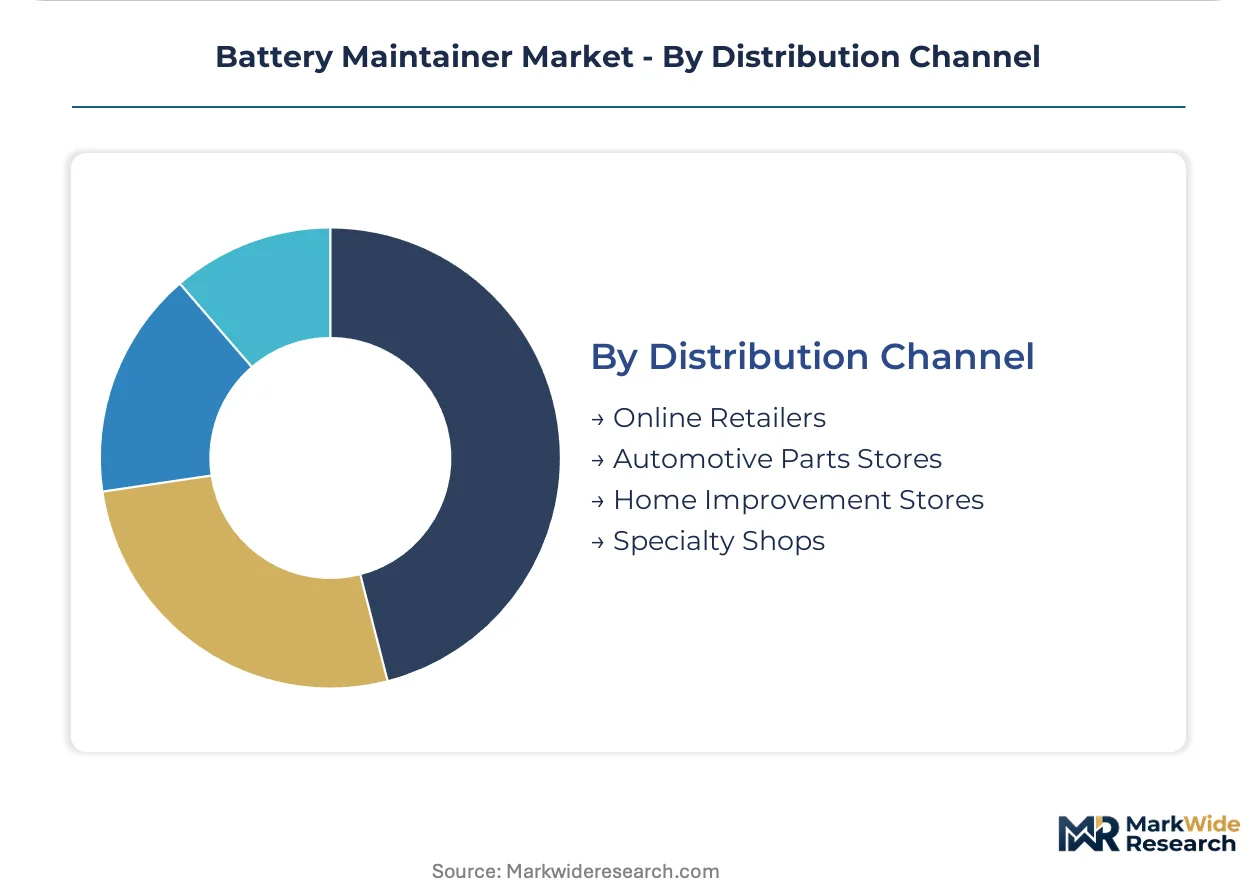
Distribution Channel:
Supply concentration in direct OEM procurement is compressing traditional distributor margins.
- Online Retailers:E-commerce platforms capture residential and enthusiast volume through comparison shopping and review aggregation. Return logistics complexity rises with misconfigured chemistry settings.
- Automotive Parts Stores:Regional jobbers retain hobbyist traffic but are losing fleet accounts to manufacturer-direct contracts. NAPA and O'Reilly are expanding private-label maintainer SKUs to defend position.
- Home Improvement Stores:Big-box retailers target DIY vehicle owners with entry-level automatic chargers. Seasonal promotional cycles align with winter battery storage preparation.
- Specialty Shops:Marine and RV dealers provide installation support for solar maintainer configurations. Technical expertise justifies premium pricing in this channel.
Automotive parts stores retain volume leadership; online retailers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish OEM-grade charging protocol manufacturers export heavily to German commercial fleet depots and Dutch marine harbors, establishing a North Sea-Baltic trade corridor for industrial battery conditioning equipment.
United States
California municipal depots and Long Beach port authorities drive procurement of multi-chemistry maintainers for hybrid work truck fleets. EPA RCRA battery recycling mandates force documented disposal chains for conditioned cells. The Pacific Northwest corridor concentrates solar maintainer installations for off-grid marine applications.
Germany
Industrial workshop equipment lines integrate diagnostic-capable maintainers for commercial vehicle service bays. EU F-Gas Regulation and CE marking requirements constrain charger electronics sold into Hamburg and Rotterdam harbor networks. Bavaria-based automotive suppliers anchor OEM-grade protocol development for heavy-duty applications.
Netherlands
Rotterdam port authority shore-power systems create sustained demand for battery conditioning units in electric tugboat operations. EU Green Deal harbor electrification timelines accelerate maintainer deployment timelines. The Randstad logistics cluster concentrates fleet operator procurement of telematics-integrated charging hardware.
Sweden
Marine and RV off-grid installations proliferate solar maintainer configurations along the Baltic coastline. CE marking alignment creates regulatory moats for pre-certified suppliers entering European harbor infrastructure. Stockholm-based energy management divisions negotiate direct OEM procurement contracts bypassing traditional distributors.
United Kingdom
Automotive enthusiast channels sustain demand for compact lithium-compatible designs through specialty retailers. REACH compliance shapes electronics sourcing for charger logic assemblies. The Midlands manufacturing belt hosts assembly operations for temperature-compensated units targeting municipal bus depot specifications.
Battery Maintainer Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with automotive heritage alongside specialized charging equipment fabricators. The competitive terrain separates into three tiers: OEM-grade protocol specialists serving commercial fleets, retail-channel compact designers targeting hobbyists, and integrated diagnostic platform providers anchoring workshop equipment lines. Strategic moves concentrate on multi-chemistry platform engineering and direct fleet procurement relationship cultivation.
Among Sweden-based OEM-grade protocol specialists, CTEK Sweden AB exemplifies the commercial-channel archetype with heavy-duty application focus. The NOCO Co. and Robert Bosch GmbH occupy distinct positioning vectors—compact retail-oriented design versus integrated industrial diagnostic capability. These three anchors represent the spectrum from consumer automotive penetration to fleet service bay integration, with each archetype demanding divergent firmware expertise and distribution infrastructure commitments.
| Leading Market Players |
|---|
| CTEK Sweden AB |
| The NOCO Co. |
| Battery Tender |
| Schumacher Electric Corp. |
| Robert Bosch GmbH |
| Stanley Black and Decker Inc. |
| Exide Technologies |
| EnerSys |
| Deltran Battery Tender |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide MOSFET substitution for legacy silicon IGBTs in switch-mode power supplies is redrawing procurement geography toward Taiwanese foundries while compressing margins on temperature-compensated smart charger units. This materials transition simultaneously elevates performance thresholds for multi-chemistry platforms and forces OEMs to absorb upfront engineering costs that resist immediate price pass-through to fleet buyers.
Pricing Analysis
Next-generation multi-chemistry platforms command substantial premiums over legacy lead-acid-only units and entry-level automatic chargers still stocked in automotive retail channels. Three-tier pricing structure across premium smart chargers, mid-grade automatic units, and economy manual maintainers reflects certification depth and diagnostic integration rather than raw amperage output. Pricing pressure stems from copper winding volatility in transformer cores and semiconductor allocation delays from Taiwanese microcontroller fabrication. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership framing, while residential hobbyists driving online retail volume treat overcharge protection as a baseline expectation rather than a premium feature.
Supply Chain Analysis
Strategic stockpiling of rare-earth magnets and copper windings is displacing just-in-time preferences as lead-time uncertainty from Asian component sources forces inventory buffers at North American assembly facilities. Microcontroller logic draws from Taiwanese foundries, transformer cores rest on Chinese and Mexican metalworking capacity, and final assembly clusters in the United States and Germany. Single-source vulnerability concentrates in semiconductor fabrication for temperature-sensing algorithms. Distribution runs through direct OEM procurement for fleet accounts and automotive parts retailers for residential channels, with specialty marine dealers capturing solar maintainer installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation into national logistics companies with centralized energy management divisions has inverted traditional channel power, compressing distributor margins and forcing manufacturers toward direct procurement relationships.
For Market Incumbents: Secure multi-chemistry firmware platforms with over-the-air update capability before NHTSA finalizes auxiliary power interface standards, locking in fleet service bay integration. Anchor backward integration into Taiwanese semiconductor sourcing partnerships to mitigate allocation risk from foundry concentration. Defend against compact lithium-compatible entrants by embedding diagnostic telemetry into cloud-based asset tracking workflows that resist disintermediation. For New Entrants and Emerging Players: Lead with solar maintainer configurations targeting Netherlands and German marine harbors where EU F-Gas Regulation compliance creates certification barriers for established suppliers. The off-grid RV installation segment presents the most penetrable white space, with boaters seeking shore-power autonomy driving fastest procurement velocity. Pursue specialty marine dealer channel partnerships that justify premium positioning through installation expertise rather than price competition. For Investors and Strategic Acquirers: The market sits at a fleet-electrification acceleration phase that favors OEM-grade protocol specialists with embedded diagnostic capabilities over retail-channel commodity assemblers. Long-term viability over the coming decade hinges on telematics convergence and software-subscription revenue attachment. Acquisition targets should demonstrate CE marking pre-certification for European harbor infrastructure and active fleet pilot programs with documented voltage data integration. Watch NHTSA rulemaking timelines as the inflection signal that will determine which hardware variants achieve standardization lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Chemistry Platform Development | Unified lead-acid and lithium-ion support captures California municipal fleet procurement under CARB mandates. |
| Telematics Integration Partnership | LCD-enabled voltage streaming into cloud asset platforms opens recurring software revenue from logistics operators. |
| CE Marking Pre-Certification | EU F-Gas Regulation alignment creates regulatory moats for Rotterdam and Hamburg harbor infrastructure tenders. |
| Direct Fleet Procurement Agreements | Master service contracts with national logistics companies bypass automotive distributor margin compression. |
| Solar Maintainer Configuration Launch | Photovoltaic-powered units address Netherlands and Baltic coastline off-grid marine demand without shore-power dependency. |
Research Methodology
A spread of perspectives from fleet maintenance directors, automotive aftermarket procurement managers, marine harbor operations engineers, and power electronics R&D leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA RCRA enforcement documentation, NHTSA regulatory filings, EU F-Gas Regulation implementation guidance, and customs trade data for copper winding and semiconductor imports. Bottom-up unit economics from fleet operator procurement patterns were triangulated against top-down market sizing from automotive parts retail channel audits.
Segmentation dimensions modeled include product type architecture, end-user procurement tier, feature bundling severity, and distribution channel structure across the projection horizon. CAGRs were derived from weighted scenario analysis of fleet electrification mandate timelines and marine harbor infrastructure investment cycles. Forecast inputs incorporated semiconductor allocation lead times from Taiwanese foundry disclosures and California CARB zero-emission commercial vehicle rule implementation pacing.
The analysis sits within stated boundaries; outcomes outside sustained fleet electrification investment or stable rare-earth magnet supply flows would require recalibration. Forecasts reflect documented assumptions regarding NHTSA rulemaking progression and EU harbor electrification subsidy continuity. Revision becomes warranted when microcontroller fabrication capacity constraints or copper price volatility cross thresholds that invalidate current procurement cycle assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Japan Battery Market
Batteries
Europe SLI Battery Market
Batteries
Micro Battery Market
Batteries
Rear Rack Battery Market
Batteries
Proton Battery Market
Batteries
West Europe Battery Market
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
Global Battery Market
Batteries
Floor Scrubber Battery Market
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market
Batteries
India Rechargeable Battery Market
Batteries
Dry Cell Battery Market
Batteries
Echelon Utilization of Power Battery Market
Batteries
Southeast Asia Battery Market
Batteries
Power Battery Sealant Market
Batteries
Portable Battery Powered Products Market