
 Japan Logistics Market | 2026-2036
Japan Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Logistics Market Insights
Last-mile delivery revenue is tilting toward technology-enabled platforms as shippers prioritize speed and traceability. Yamato Holdings leverages its nationwide Kuroneko network to sustain parcel density advantages in residential zones. Nippon Express anchors industrial freight flows through integrated rail-truck corridors linking the Pacific Belt manufacturing zone. Sagawa competes aggressively on same-day delivery slots, while Kintetsu World Express specializes in cross-border e-commerce customs clearance.
Logistics encompasses the planning, execution, and control of goods movement and storage across supply chains, typically measured by ton-kilometer throughput, warehouse utilization rates, and order-cycle time performance. Its primary purpose is to synchronize inventory positioning with demand signals across manufacturing, distribution, and retail endpoints. Transportation services dominate value capture in Japan's logistics structure, though e-commerce fulfillment represents the fastest-expanding margin pool as direct-to-consumer volumes reshape warehouse automation requirements. Warehousing operations increasingly integrate IoT-enabled inventory tracking and AI-driven demand forecasting to reduce safety stock buffers.
METI enforces fuel-efficiency standards under the Energy Saving Act, while the Ministry of Land, Infrastructure, Transport and Tourism regulates commercial vehicle weight limits and driver hours through the Motor Truck Transportation Business Act. These frameworks elevate compliance costs for fleet operators but simultaneously accelerate investment in electric vehicles and automated sorting infrastructure. Stakeholders must monitor how JIS standards for autonomous delivery systems evolve alongside labor shortage pressures in rural distribution corridors.
Market Dynamics
Japan's logistics sector faces a structural compression between METI's Green Logistics mandates and acute driver shortages, forcing capital reallocation toward automation and alternative powertrains.
Growth Catalysts
- Omnichannel fulfillment:Japanese retailers are rebuilding warehouse networks around same-day delivery promises, pulling investment into automated sortation and micro-fulfillment nodes.
- METI Green Logistics initiatives:Emissions reduction mandates across freight corridors are accelerating fleet electrification and intermodal rail adoption.
- Greater Tokyo Area density:Port congestion and last-mile saturation create premium pricing power for operators with localized capacity.
Market Restraints
- Diesel price volatility:Fuel cost swings compress margins for truckload operators unable to pass through surcharges.
- Driver labor scarcity:Japan's aging workforce and strict Motor Truck Transportation Business Act hour limits constrain fleet expansion.
- Suburban warehouse land costs:Industrial zoned plots near consumption centers command multiples of regional alternatives.
Strategic Opportunities
- Rural corridor automation:Autonomous delivery pilots under evolving JIS standards could unlock cost coverage in low-density prefectures.
- Cross-border e-commerce customs:Simplified clearance protocols for China and Southeast Asia-bound parcels offer margin expansion.
- Battery-swapping infrastructure:Standardized exchange networks for electric commercial vehicles reduce downtime versus charging.
Industry Challenges
- Warehouse management system integration:Legacy WMS platforms resist API connectivity with IoT inventory tracking and AI forecasting modules.
- Autonomous vehicle certification timelines:Unclear JIS approval pathways delay deployment schedules and capital recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Logistics Market |
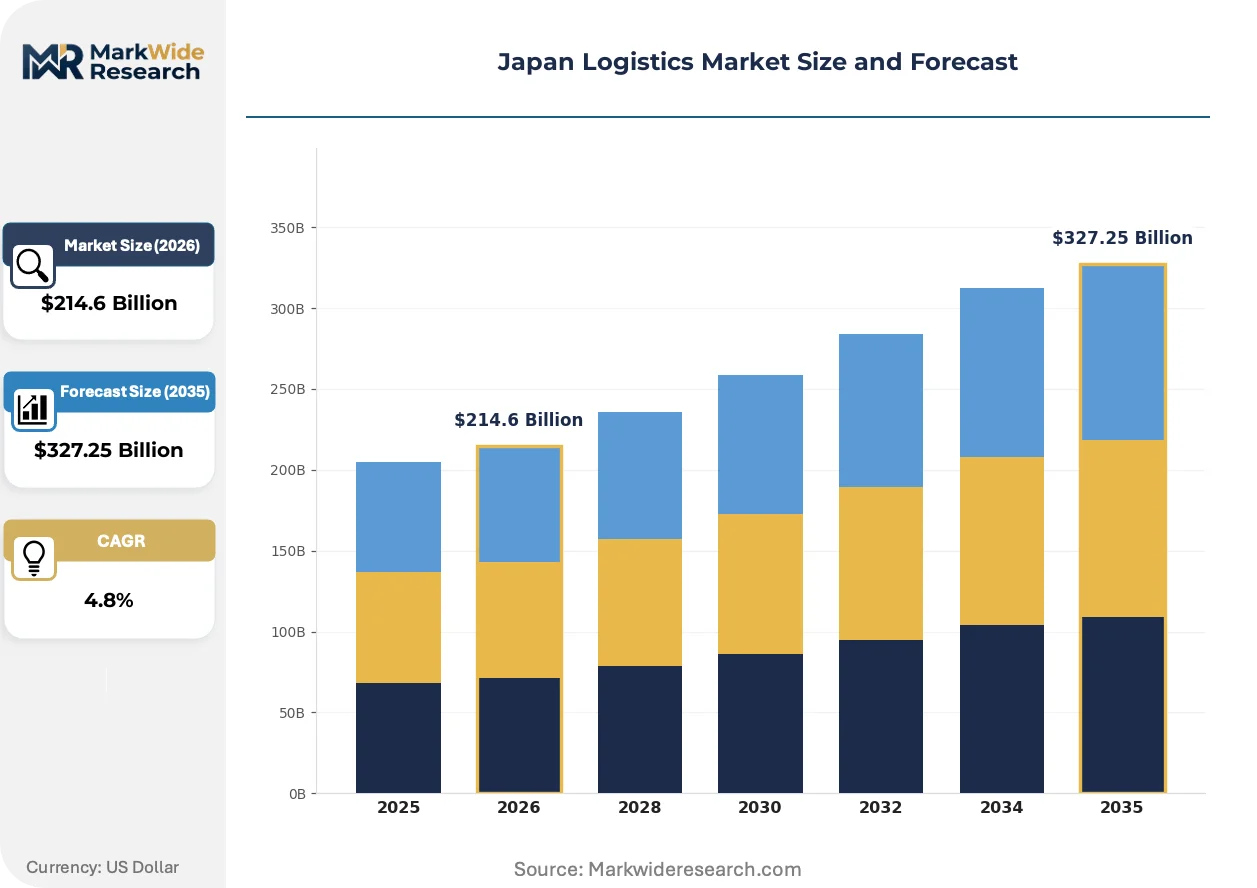
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $327.25 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Transportation, Freight Forwarding, Last Mile Delivery Delivery Model: Direct Shipping, Drop Shipping, Third-Party Logistics, E-commerce Fulfillment End User: Retail, Automotive, Healthcare, Electronics Technology: IoT, Automation, AI, Blockchain |
| Companies Covered | Sagawa, MOL Logistics, Nippon Express, Kuehne+Nagel, Kintetsu World Express, Yusen Logistics, Japan Post, Isewan Terminal Service, Yamato Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Logistics Market Trends and Innovations
Digital freight matching and predictive routing are compressing traditional brokerage margins while elevating asset-light platform operators.
Autonomous mobile robots in fulfillment centers coordinate pick paths through machine vision and warehouse mapping, with major apparel and electronics retailers deploying at scale. The hardware-software stack is rendering obsolete fixed conveyor infrastructure and manual zone-picking workflows.
METI's Energy Saving Act enforces escalating fuel-efficiency standards for commercial fleets, compelling operators to accelerate electric vehicle procurement or face operational penalties. Heavy-duty truck segments face the steepest compliance curves, with manufacturers prioritizing battery-electric and hydrogen fuel cell platforms.
Shippers now contract for guaranteed capacity blocks rather than spot-market flexibility, reversing decades of just-in-time logistics practice. Pharmaceutical and cold-chain food distributors lead this shift, locking in refrigerated transport capacity across the Pacific Belt manufacturing zone to secure temperature integrity.
Japan Logistics Market Segmentation
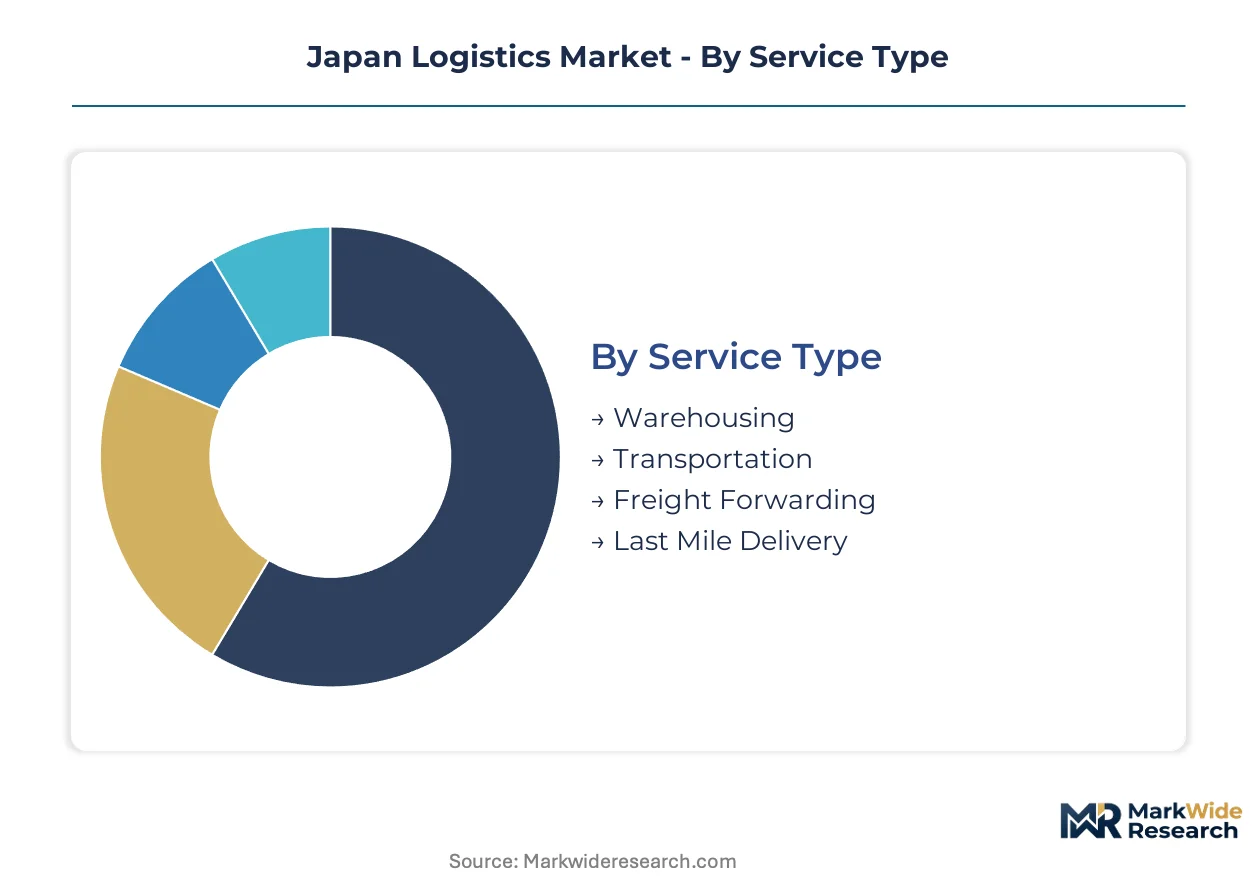
Segmentation in Japan's logistics market reveals how service velocity, delivery architecture, and end-use specialization determine capital allocation and margin capture. Cycle-time disparities across service types and delivery models create distinct competitive arenas requiring tailored infrastructure investments.
Service Type:
Cycle times compress from months in warehousing contracts to hours in last-mile operations, with transportation and freight forwarding occupying intermediate velocity bands where asset utilization drives profitability.
- Warehousing:Long-dwell inventory storage with automated sortation systems and climate-controlled zones for pharmaceuticals. Demand concentrates in Greater Tokyo's Chiba and Saitama prefectures where METI's Green Logistics mandates accelerate solar-powered facility retrofits and electric forklift fleets.
- Transportation:Truck-rail intermodal corridors linking Pacific Belt manufacturing clusters to port gateways. Fukuoka-Osaka-Tokyo freight lanes absorb the heaviest tonnage as automotive and electronics shippers prioritize scheduled reliability over spot-market flexibility.
- Freight Forwarding:Customs brokerage and documentation coordination for containerized exports through Yokohama and Kobe ports. Cross-border e-commerce volumes into China and Southeast Asia expand margin pools for temperature-controlled and time-definite services.
- Last Mile Delivery:Parcel finalization through Kuroneko-style residential networks and convenience store pickup points. Tokyo's 23 wards generate the densest stop-per-route economics, while rural Hokkaido and Tohoku regions strain cost coverage under driver hour limits imposed by the Motor Truck Transportation Business Act.
Transportation anchors the volume base while last-mile delivery gains share at the steepest rate.
Delivery Model:
Cost tiers separate capital-heavy asset ownership from variable-cost platform intermediation, with third-party logistics and e-commerce fulfillment commanding premium pricing for outcome-based service guarantees.
- Direct Shipping:Shipper-controlled fleet operations with dedicated routes and captive warehousing. Automotive assemblers in Aichi prefecture maintain this model for production-line sequencing where schedule adherence outweighs third-party cost efficiency.
- Drop Shipping:Inventory-free fulfillment where suppliers ship directly to end consumers, minimizing working capital for apparel and electronics retailers. Platform operators extract fees for order-routing algorithms and payment processing rather than physical handling.
- Third-Party Logistics:Outsourced warehouse management and transportation procurement with multi-client facility sharing. Pharmaceutical distributors favor this model for JIS-compliant temperature validation without captive infrastructure investment.
- E-commerce Fulfillment:Same-day and next-day promise architectures with micro-fulfillment nodes positioned within 50 kilometers of consumption centers. Automated sortation and machine-vision picking displace fixed conveyor systems as order velocities accelerate.
Third-party logistics anchors the volume base while e-commerce fulfillment climbs the fastest.
End User:
Application-specific requirements fragment service specifications, with healthcare and electronics imposing the most stringent handling protocols while retail and automotive drive throughput scale.
- Retail:Omnichannel inventory synchronization across brick-and-mortar and digital storefronts, with reverse logistics for returns processing. Seasonal volume spikes around New Year and Golden Week strain capacity planning.
- Automotive:Just-in-sequence parts delivery to assembly plants with zero-defect packaging standards. Toyota Production System principles propagate through tiered supplier networks, elevating delivery precision over cost minimization.
- Healthcare:Cold-chain integrity for vaccines and biologics with PMDA-compliant temperature logging. Metropolitan hospital clusters in Tokyo and Osaka consolidate procurement to secure dedicated refrigerated capacity.
- Electronics:High-velocity handling of semiconductors and consumer devices with electrostatic discharge protection. Kyushu and Tohoku fabrication plants require specialized clean-room transport for wafer shipments.
Retail anchors the volume base while healthcare expands most quickly on regulatory compliance premiums.
Technology:
Maturity gradients separate proven deployments from pilot-phase innovations, with IoT and automation already scaling while AI and blockchain remain concentrated in proof-of-concept implementations.
- IoT:Sensor networks for real-time location tracking and environmental monitoring across refrigerated trailers and warehouse zones. METI's Energy Saving Act mandates fuel-efficiency data collection that IoT platforms satisfy.
- Automation:Autonomous mobile robots in fulfillment centers and automated guided vehicles in manufacturing-adjacent warehouses. Major apparel retailers deploy at scale in Greater Tokyo distribution parks.
- AI:Demand forecasting and dynamic route optimization with machine learning models trained on historical traffic and consumption patterns. Deployment concentrates in last-mile dispatch systems where driver scarcity elevates algorithmic efficiency premiums.
- Blockchain:Distributed ledger pilots for pharmaceutical provenance and cross-border customs documentation. Regulatory clarity from METI and customs authorities remains pending before commercial scaling.
Automation anchors the volume base while AI shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freight corridors concentrate around the Pacific Belt manufacturing zone, with port throughput and last-mile density determining service economics. METI's regional infrastructure investments channel automation capital toward consumption clusters facing acute labor scarcity.
Kanto/Tokyo
E-commerce fulfillment demand saturates the 23 wards, pulling investment into micro-fulfillment nodes within 50 kilometers of consumption centers. MLIT's port congestion mitigation programs prioritize Yokohama and Tokyo container terminal efficiency upgrades. Chiba and Saitama prefectures warehouse solar retrofits and electric forklift fleets under METI Green Logistics mandates.
Kansai/Osaka
Pharmaceutical and electronics distributors anchor cold-chain and clean-room logistics requirements. PMDA temperature validation standards elevate compliance costs for vaccine and biologics handling. Osaka Bay port clusters consolidate cross-border e-commerce customs clearance for China-bound parcels.
Chubu/Nagoya
Automotive just-in-sequence parts delivery dominates freight flows, with Toyota Production System principles propagating through tiered supplier networks. Motor Truck Transportation Business Act hour limits constrain fleet expansion across Aichi prefecture assembly corridors. Manufacturing-adjacent warehouses deploy automated guided vehicles for production-line sequencing.
Kyushu
Semiconductor fabrication plants in Fukuoka and Kumamoto generate specialized clean-room transport demand for wafer shipments. JIS standards for autonomous delivery systems pilot in low-density rural prefectures to address driver shortages. Intermodal rail-truck corridors link island manufacturing to Osaka-Tokyo freight lanes.
Hokkaido and Tohoku
Agricultural and seafood cold-chain exports strain cost coverage under driver hour regulations and sparse population density. Battery-swapping infrastructure pilots for electric commercial vehicles target reduced downtime versus charging in remote corridors. Sapporo and Sendai metropolitan zones concentrate limited fulfillment automation deployment.
Japan Logistics Market Competitive Landscape
Integrated network operators and specialized platform providers split the market along asset-intensity lines. Consolidation pressures favor players with captive rail-truck intermodal capacity and established last-mile residential density. Three archetypes dominate: nationwide parcel networks with convenience store integration, freight forwarders anchoring customs brokerage and documentation, and industrial logistics specialists serving manufacturing sequencing requirements. Competitive moves center on warehouse automation partnerships and electric fleet procurement commitments under METI emissions mandates.
Within the integrated network tier, Yamato Holdings and Nippon Express exemplify contrasting scale strategies. Sagawa occupies a position emphasizing same-day velocity in metropolitan zones. Kintetsu World Express anchors cross-border e-commerce customs specialization. These three represent the spectrum from domestic parcel density to international freight forwarding integration.
| Leading Market Players |
|---|
| Sagawa |
| MOL Logistics |
| Nippon Express |
| Kuehne+Nagel |
| Kintetsu World Express |
| Yusen Logistics |
| Japan Post |
| Isewan Terminal Service |
| Yamato Holdings |
| Others |
Pricing and Supply Chain Analysis
Diesel procurement concentration in Middle Eastern and Southeast Asian refining clusters feeds directly into margin compression for Japan's truckload operators, while METI's Green Logistics mandates reallocate value capture toward electrified fleet operators and intermodal rail providers.
Pricing Analysis
METI's Energy Saving Act dictates the pricing tier structure across Japan's logistics sector. Three-tier pricing separates premium guaranteed-capacity contracts from standard scheduled services and economy spot-market brokerage. Price differentiation rests on fuel-efficiency certification tiers and after-sales service bundling. Cost compression in economy truckload segments is intensifying because diesel price volatility outpaces surcharge pass-through mechanisms. Small and mid-sized shippers exhibit highest price sensitivity, while pharmaceutical and automotive assemblers prioritize schedule adherence over rate minimization.
Supply Chain Analysis
Contract manufacturing concentration in China's Pearl River Delta and Yangtze River Delta anchors component sourcing for Japan's electronics and automotive logistics corridors. Battery cell production draws from South Korean and Chinese suppliers, while semiconductor fabrication equipment sources from Dutch and American vendors. Single-source vulnerability in rare earth magnet supply chains for electric drivetrains creates exposure to export restriction shocks. Distribution runs through Pacific Belt rail-truck intermodal terminals linking Greater Tokyo, Nagoya, and Osaka manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's logistics sector is undergoing high-growth disruption as METI's emissions mandates and driver hour regulations force capital reallocation toward automation and alternative powertrains.
For Market Incumbents: Harden network density advantages through captive rail-truck intermodal capacity expansion along Pacific Belt corridors. Deepen warehouse automation partnerships to offset Motor Truck Transportation Business Act hour constraints. Prioritize JIS-compliant autonomous vehicle certification investment to secure first-mover positioning in rural delivery pilots. For New Entrants and Emerging Players: Build out micro-fulfillment node networks within 50 kilometers of Greater Tokyo consumption centers where same-day delivery premiums support greenfield automation investment. Target cross-border e-commerce customs clearance specialization for China and Southeast Asia-bound parcels. Pursue battery-swapping infrastructure partnerships with electric commercial vehicle OEMs as a service-layer entry point. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional truckload operators facing succession and electrification capital needs. Long-term viability favors platforms with established last-mile residential density and API-connected warehouse management systems. Watch JIS autonomous delivery approval timelines as the critical regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Procurement Commitment | METI's Green Logistics mandates accelerate zero-emission vehicle deployment across freight corridors. |
| Automated Sortation Infrastructure | Machine-vision picking displaces fixed conveyor systems in Greater Tokyo fulfillment centers. |
| Intermodal Rail-Truck Partnership | Pacific Belt manufacturing clusters require scheduled reliability for just-in-sequence parts delivery. |
| Micro-Fulfillment Node Expansion | Same-day delivery promises pull investment within 50 kilometers of consumption centers. |
| Cross-Border Customs Specialization | Simplified clearance protocols for China-bound parcels expand margin pools for temperature-controlled services. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of METI regulatory filings, MLIT transport statistics, and customs trade data. Interviews with fleet operations directors, warehouse automation vendors, pharmaceutical distribution managers, and rail-truck intermodal planners informed demand segmentation. Bottom-up ton-kilometer throughput modeling and top-down GDP elasticity approaches triangulated market sizing.
Forecast inputs span service type velocity bands, delivery model capital intensity tiers, and end-use compliance requirements across the projection horizon. Segmentation dimensions include warehousing dwell-time categories, transportation mode splits, and technology adoption maturity curves. CAGRs derive from historical freight volume elasticities applied to e-commerce penetration scenarios and METI emissions compliance timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-based freight matchers or battery-swapping consortiums would shift outcomes. Quarterly review of JIS autonomous vehicle certification progress and electric commercial vehicle subsidy uptake is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Georgia Freight and Logistics Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
US Dangerous-Hazardous Goods Logistics Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market
Logistics and Shipping
China Local Courier Market
Logistics and Shipping
Tanker Cargo Ship Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Less-Than-Truckload Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
Vietnam Logistics Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
North America Freight Brokerage Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market