
 United States Automotive Logistics Market | 2026-2036
United States Automotive Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Automotive Logistics Market Analytics
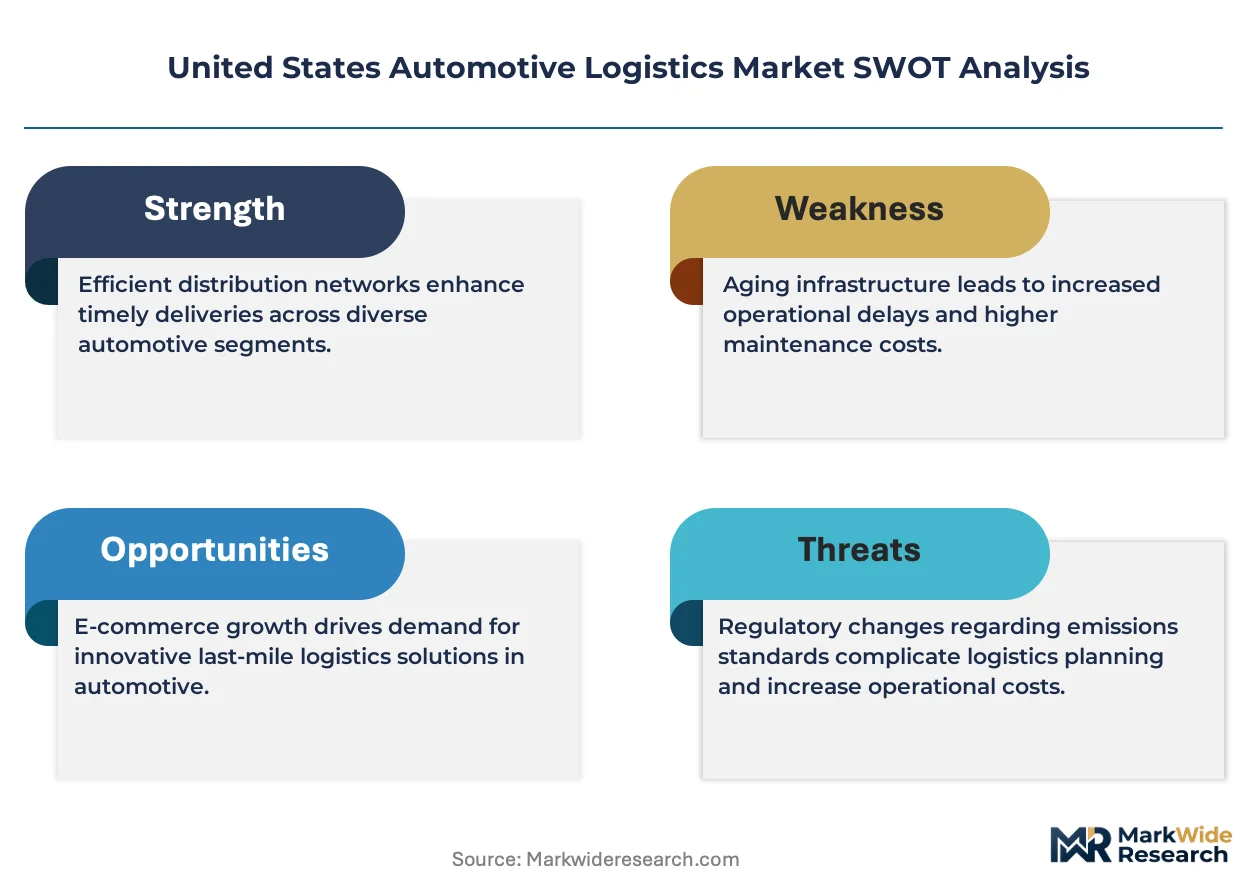
Asset-light leasing and third-party fleet financing is rewriting competitive entry barriers for mid-size logistics providers in the United States. XPO Logistics leverages its dedicated contract carriage model to sustain density across the Southeast automotive corridor. C.H. Robinson competes through digital freight-matching platforms that anchor spot-market liquidity for OEM outbound distribution. Penske Logistics differentiates via integrated maintenance and fleet management services that dominate just-in-time delivery contracts with Detroit-area manufacturers.
United States automotive logistics encompasses the coordinated movement, storage, and information management of vehicles, parts, and components across assembly, distribution, and aftermarket channels, typically operating within temperature-controlled and vibration-monitored parameters to preserve component integrity. The sector manages finished vehicle transport via specialized rail carriers and multi-level auto haulers, plus inbound parts flows sequenced to hourly assembly line takt times. Transportation services lead revenue contribution due to fuel and driver cost exposure, while warehousing commands margin concentration through value-added sequencing and kitting operations for Tier-1 suppliers. IoT Tracking adoption is accelerating fastest among delivery models requiring real-time visibility, though Cloud-Based Management platforms now underpin cross-docking coordination for OEMs seeking inventory minimization.
The Federal Motor Carrier Safety Administration governs driver hours-of-service rules that directly constrain fleet utilization rates and capacity planning across automotive freight networks. EPA Phase 3 greenhouse gas standards for heavy-duty vehicles are forcing carrier investment in alternative-fuel tractors, reshaping procurement economics for long-haul OEM routes. NHTSA electronic logging device mandates enforce compliance transparency that favors large carriers with integrated telematics infrastructure. Stakeholders must monitor how California's Advanced Clean Trucks regulation spreads to other states, as this will determine whether zero-emission fleet conversion becomes a competitive requirement or a geographic niche strategy.
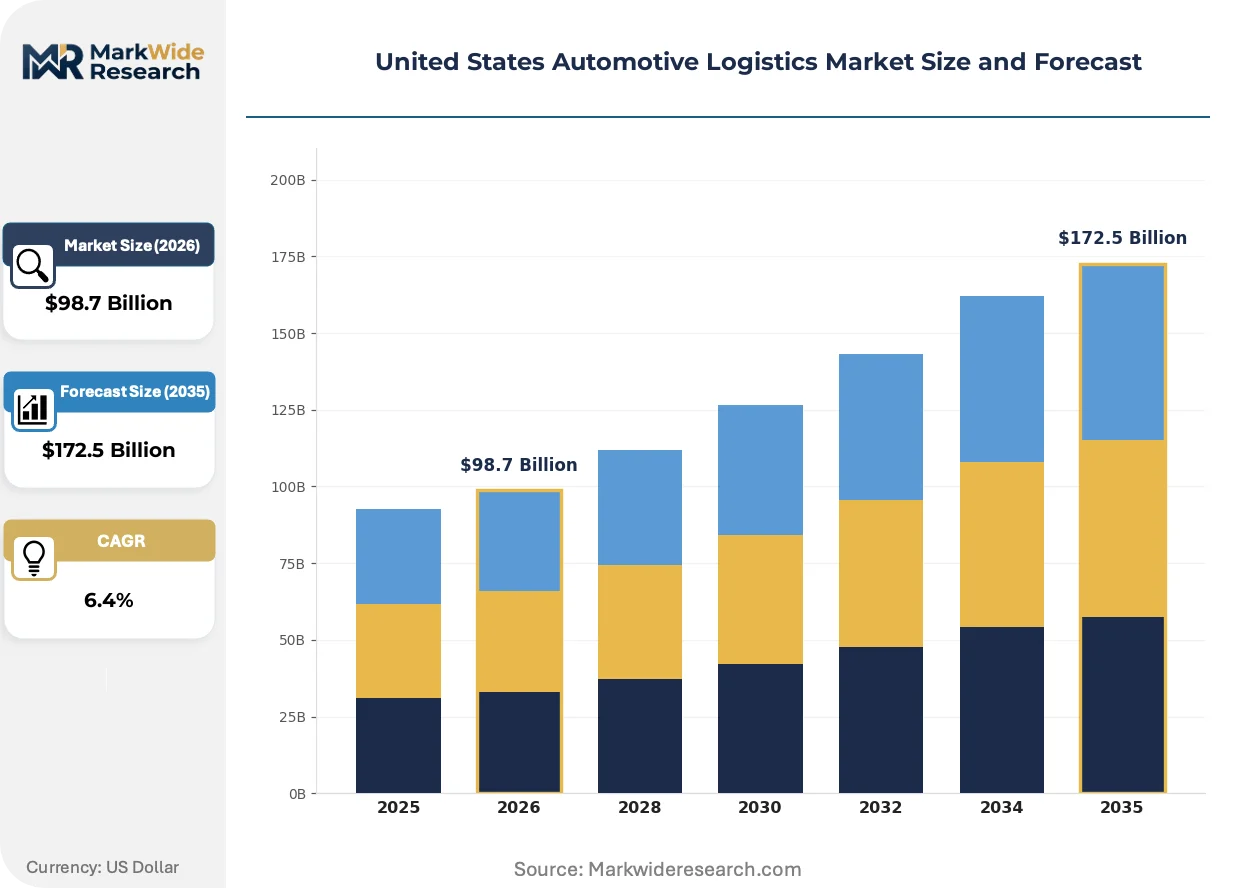
Market Dynamics
EPA Phase 3 greenhouse gas standards are compressing carrier fleet replacement cycles while electric vehicle production expansion across the Midwest and Southeast is reconfiguring inbound parts networks away from traditional engine-component corridors toward battery and electric drivetrain supply chains.
Growth Catalysts
- EPA Heavy-Duty Emissions Standards:Tightened Phase 3 regulations are accelerating fleet modernization investments, creating sustained demand for compliant transport capacity across OEM outbound distribution networks.
- EV Manufacturing Clustering:Battery and electric drivetrain suppliers are concentrating new facilities in Tennessee, Kentucky, and South Carolina, generating greenfield logistics infrastructure requirements.
- IoT Telematics Integration:Real-time visibility platforms are enabling just-in-time sequencing precision that reduces inventory carrying costs for Tier-1 suppliers serving hourly takt-time assembly lines.
Market Restraints
- Diesel Fuel Cost Volatility:Long-haul carrier economics remain exposed to petroleum price swings that compress margins on fixed-rate OEM contracts.
- Driver Availability Constraints:FMCSA hours-of-service rules limit fleet utilization rates, constraining capacity expansion without proportional headcount increases.
- Specialized Equipment Concentration:Multi-level auto hauler manufacturing concentrates among limited North American suppliers, creating procurement bottlenecks during demand surges.
Strategic Opportunities
- Texas-Mexico Cross-Border Expansion:Nearshoring of automotive component manufacturing is generating demand for integrated US-Mexico customs brokerage and bonded warehousing services.
- Cloud-Based Yard Management:Digital coordination platforms are penetrating vehicle processing centers and rail ramps, replacing manual gate control and inspection workflows.
- California Advanced Clean Trucks Spillover:Zero-emission fleet conversion requirements spreading to Oregon, Washington, and New York are creating geographic differentiation opportunities for early electrifying carriers.
Industry Challenges
- Telematics Technician Scarcity:Fleet maintenance operations face acute shortages of technicians trained on integrated sensor diagnostics and predictive maintenance software.
- ELD Compliance Integration:NHTSA electronic logging device mandates require legacy dispatch systems to interface with certified hardware, generating IT modernization costs for mid-size carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Automotive Logistics Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $172.5 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Inventory Management, Freight Forwarding Client Type: OEMs, Tier-1 Suppliers, Dealerships, Aftermarket Providers Delivery Model: Direct Shipment, Cross-Docking, Just-In-Time, Drop Shipping Technology: IoT Tracking, Cloud-Based Management, RFID Systems, Automation |
| Companies Covered | XPO Logistics, Ryder System Inc., DHL Supply Chain, C.H. Robinson, DB Schenker, DSV, Penske Logistics, UPS Supply Chain Solutions, Kuehne + Nagel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Automotive Logistics Market Evolving Landscape
Digital freight-matching platforms and predictive analytics are compressing tender-to-delivery cycle times while autonomous yard tractors and battery-electric last-mile vehicles are entering pilot deployment across high-volume automotive distribution nodes.
Blockchain-enabled bill-of-lading verification is rendering obsolete paper-based documentation workflows that previously delayed cross-docking operations at vehicle processing centers. Tier-1 suppliers serving Detroit-area OEMs are piloting distributed ledger systems for component provenance tracking. This compression of documentation friction is accelerating same-day sequencing turnaround requirements.
The EPA's Phase 3 greenhouse gas standards are mandating alternative-fuel tractor procurement across heavy-duty fleets serving long-haul OEM routes. Carrier capital allocation is shifting toward electric and hydrogen fuel cell vehicle orders with extended delivery lead times. Southeast corridor operators are prioritizing depot charging infrastructure to maintain density on dedicated contract carriage lanes.
Automotive procurement departments are consolidating spot-market freight brokerage relationships toward platform-based managed transportation services with guaranteed capacity commitments. Digital freight-matching liquidity pools are displacing traditional phone-based broker networks for outbound vehicle distribution. Michigan OEMs are most advanced in this transition, with Tier-1 suppliers following to secure outbound parts capacity during peak production windows.
United States Automotive Logistics Market Segmentation
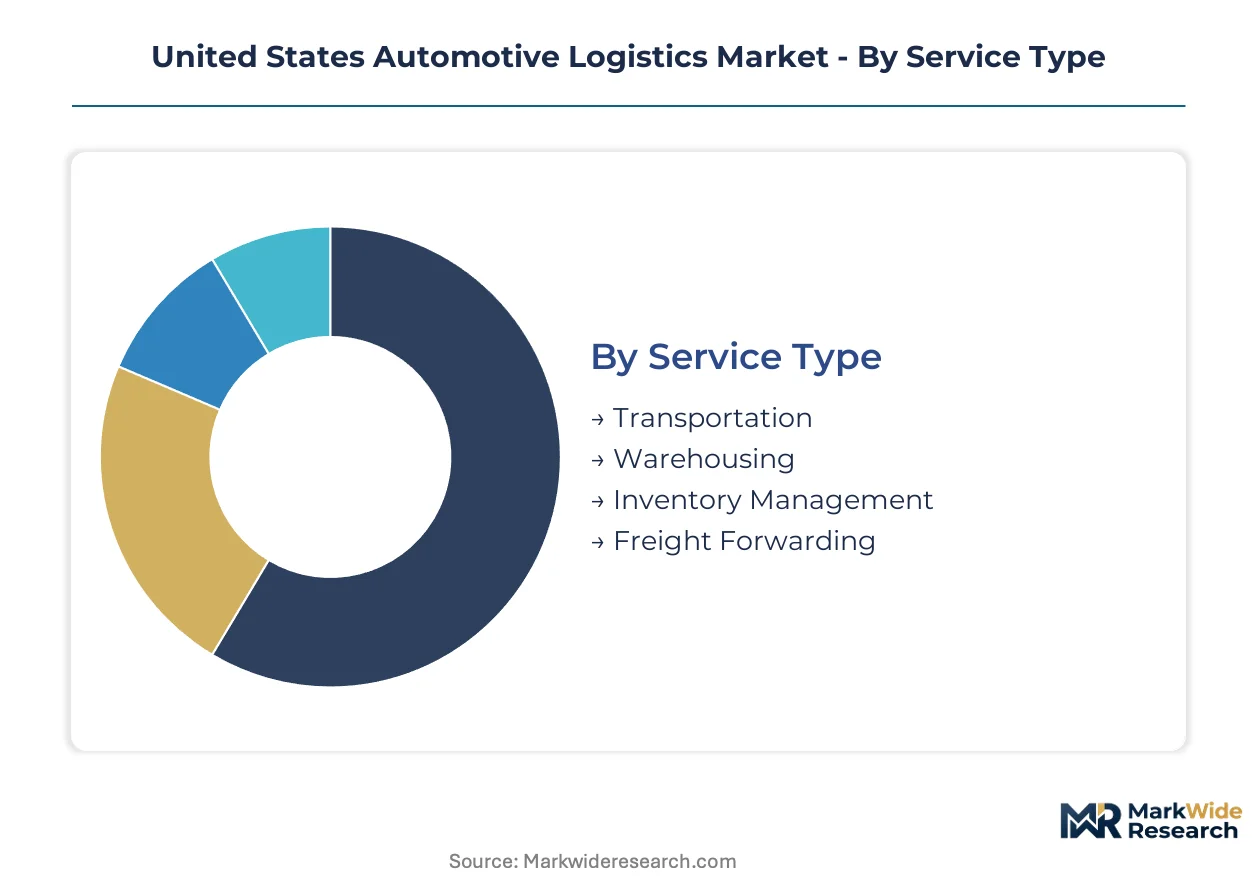
Automotive logistics segmentation reveals how service velocity, client procurement cycles, and technology refresh rates create divergent margin profiles across the value chain. Cycle-time variance between same-day JIT sequencing and multi-day finished vehicle transport dictates working capital intensity and carrier equipment specialization requirements.
Service Type:
Transportation commands the shortest capital recovery cycles with daily fleet utilization pressure, while inventory management extends longest due to multi-year WMS implementation timelines and embedded software dependencies.
- Transportation:Encompasses finished vehicle haulage via multi-level auto carriers and inbound parts movement by dedicated contract carriage. Demand concentrates in Michigan's Detroit-Lansing corridor where OEM assembly plants require hourly takt-time parts delivery synchronized to production schedules.
- Warehousing:Covers sequencing centers, kitting operations, and temperature-controlled storage for sensitive components. Kentucky and Tennessee battery supplier clusters are driving greenfield construction of cross-dock facilities with vibration-monitoring infrastructure.
- Inventory Management:Deploys WMS platforms and demand forecasting tools to minimize carrying costs across Tier-1 supplier networks. Cloud-native deployments are accelerating among Southeast EV manufacturing greenfields seeking rapid system standup.
- Freight Forwarding:Manages customs brokerage and bonded warehousing for Mexico-sourced components. Texas border zones exhibit fastest adoption of integrated US-Mexico documentation platforms.
Transportation anchors the volume base while inventory management gains share at the steepest rate.
Client Type:
Procurement sophistication stratifies sharply, with OEMs demanding outcome-based contracts and aftermarket providers operating on spot-market volatility exposure.
- OEMs:Original equipment manufacturers negotiate dedicated capacity agreements with penalty clauses for line-stoppage incidents. Ford, General Motors, and Stellantis facilities in Michigan and Ohio represent the densest contract concentration.
- Tier-1 Suppliers:Bosch, Denso, and Magna operations require sequenced delivery precision to multiple OEM customers from common distribution points. Their logistics procurement is consolidating toward platform-based managed transportation services.
- Dealerships:Franchise networks rely on regional vehicle processing centers for rail-to-lot distribution. California and Texas dealer groups are piloting autonomous yard tractor programs at high-volume rail ramps.
- Aftermarket Providers:NAPA, AutoZone, and O'Reilly distribution networks operate on less predictable demand patterns with higher spot-market freight exposure. Their logistics spend concentrates in last-mile parcel and LTL segments.
OEMs anchor the volume base while Tier-1 suppliers are expanding most quickly.
Delivery Model:
Inventory velocity requirements separate synchronous production-linked flows from asynchronous distribution patterns with divergent infrastructure needs.
- Direct Shipment:Point-to-point truckload movement for finished vehicles and bulk parts shipments. Long-haul routes from Midwest assembly plants to coastal ports maintain highest equipment utilization rates.
- Cross-Docking:Rapid freight consolidation at vehicle processing centers and rail terminals. Southeast corridor operators are deploying cloud-based yard management platforms to replace manual gate control workflows.
- Just-In-Time:Hourly sequenced parts delivery synchronized to assembly line takt times. Michigan OEM plants enforce strict delivery windows with line-down penalties exceeding carrier margins.
- Drop Shipping:Direct-to-dealer or direct-to-consumer parts fulfillment bypassing intermediate storage. EV manufacturers are expanding this model for battery and drivetrain component warranty replacement.
Just-in-time anchors the volume base while cross-docking is climbing the fastest.
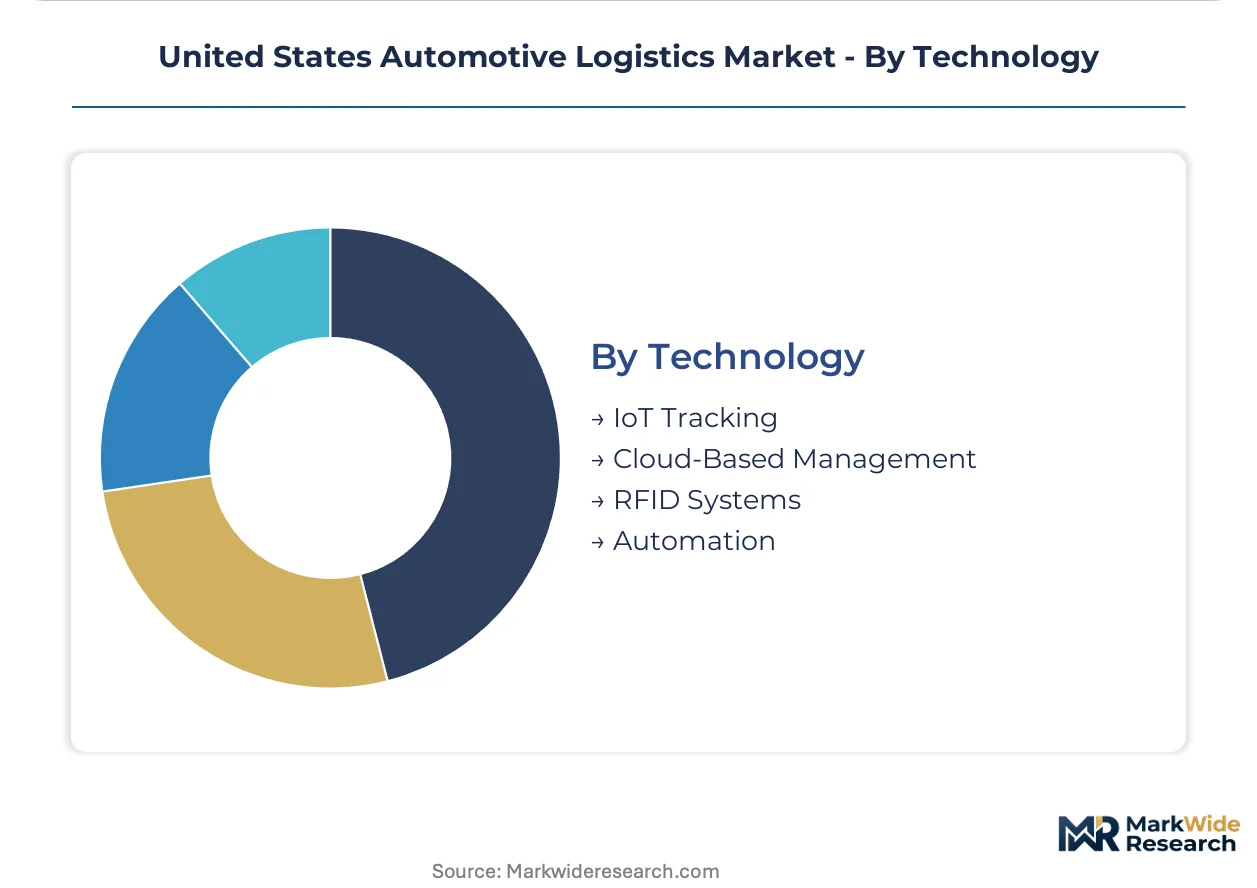
Technology:
Deployment maturity spans decades-old RFID installations to emerging autonomous systems with replacement cycle implications for carrier capital planning.
- IoT Tracking:Real-time telematics platforms monitor vehicle location, temperature, and shock exposure across transport modes. EPA Phase 3 compliance is accelerating integrated sensor deployment for fuel consumption optimization.
- Cloud-Based Management:SaaS platforms coordinate multi-party visibility across OEM, carrier, and supplier systems. Southeast battery manufacturing clusters favor cloud-native TMS implementations for rapid network scaling.
- RFID Systems:Legacy automatic identification for yard inventory and gate processing. Rail ramps and vehicle processing centers maintain installed bases with selective upgrade paths to passive UHF standards.
- Automation:Autonomous yard tractors and robotic sortation systems entering pilot deployment. High-volume distribution nodes in California and Texas are testing battery-electric autonomous shuttles for repetitive drayage loops.
RFID systems anchor the volume base while cloud-based management is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure incentives and state-level clean truck mandates are redistributing automotive logistics investment across American manufacturing corridors, with battery supply chain clustering now rivaling traditional engine-component networks for carrier density.
Michigan
Detroit-Lansing corridor OEMs enforce hourly takt-time delivery windows with line-down penalty clauses exceeding carrier margins. EPA Phase 3 standards accelerate fleet turnover among dedicated contract carriage providers serving Ford, General Motors, and Stellantis assembly plants. Tier-1 supplier sequencing centers concentrate in Warren and Sterling Heights, with cloud-native WMS deployments expanding fastest among battery component inbound flows.
Southeast
Tennessee, Kentucky, and South Carolina battery manufacturing greenfields generate greenfield logistics infrastructure requirements for vibration-monitored cross-dock facilities. State economic development authorities compete for EV supplier investments through targeted infrastructure bonds. Chattanooga and Spartanburg anchor dedicated contract carriage density for BMW and Volkswagen Group operations, with depot charging infrastructure prioritized on Southeast corridor lanes.
Texas
Nearshoring of automotive component manufacturing from Mexico drives integrated customs brokerage demand across Laredo and El Paso border zones. Texas Department of Transportation freight corridor investments reduce cross-border dwell times for just-in-time parts networks. Dallas-Fort Worth vehicle processing centers pilot autonomous yard tractors for high-volume rail-to-lot distribution.
California
Advanced Clean Trucks regulation mandates zero-emission fleet conversion for drayage and last-mile operations serving Port of Los Angeles and Port of Long Beach automotive imports. California Air Resources Board enforcement creates geographic differentiation for early-electrifying carriers. Ontario and Fontana vehicle processing centers test battery-electric autonomous shuttles for repetitive distribution loops.
Ohio
Honda and Stellantis operations in Marysville and Toledo sustain dedicated contract carriage demand for inbound powertrain and stamping components. Ohio EPA diesel emission reduction grants accelerate alternative-fuel tractor procurement among regional carriers. Columbus anchors digital freight-matching platform adoption for spot-market outbound vehicle distribution during peak production windows.
United States Automotive Logistics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across contract structures ranging from dedicated capacity agreements to spot-market liquidity provision. Large integrated carriers dominate OEM procurement through outcome-based contracts with line-stoppage penalties, while asset-light brokers capture volatility exposure in aftermarket and dealer distribution segments. Strategic archetypes separate into fleet-heavy dedicated contract specialists, digital platform intermediaries, and integrated maintenance-service bundlers. Competitive moves concentrate on M&A for regional density and technology licensing for telematics integration.
Within the integrated maintenance-service tier, Penske Logistics and Ryder System Inc. exemplify carriers bundling fleet management with just-in-time delivery contracts. Among digital platform intermediaries, C.H. Robinson occupies a position anchoring spot-market liquidity pools that displace traditional phone-based brokerage for outbound vehicle distribution. These three companies represent divergent strategic bets on asset intensity versus technology leverage across Michigan and Southeast corridor operations.
| Leading Market Players |
|---|
| XPO Logistics |
| Ryder System Inc. |
| DHL Supply Chain |
| C.H. Robinson |
| DB Schenker |
| DSV |
| Penske Logistics |
| UPS Supply Chain Solutions |
| Kuehne + Nagel |
| Others |
Value Network & Pricing Analysis
Undercapacity across specialized multi-level auto hauler manufacturing is forcing OEM procurement teams toward longer-term dedicated capacity agreements with embedded price escalation clauses. Michigan assembly plants facing hourly takt-time delivery windows accept premium pricing for guaranteed sequencing precision, while Southeast battery supplier clusters negotiate volume-scaled contracts for vibration-monitored cross-dock services.
Pricing Analysis
Equipment utilization tiers create the primary spread between dedicated contract carriage and spot-market brokerage rates. Three-tier pricing structure across premium guaranteed capacity, standard scheduled lanes, and economy spot-fill segments governs OEM outbound distribution. Cost compression in economy brokerage runs through diesel fuel cost exposure and driver wage inflation. Aftermarket parts distributors exhibit highest price sensitivity due to unpredictable demand patterns, while Detroit-area OEMs prioritize line-stoppage penalty avoidance over rate minimization.
Supply Chain Analysis
Extended payment terms from Tier-1 suppliers to domestic multi-level auto hauler manufacturers strain working capital across equipment procurement cycles. Manufacturing concentrates in the United States, Mexico, and Germany for specialized auto carriers and battery component enclosures. Raw material dependencies span high-strength steel alloys, lithium-ion cell chemistries, and semiconductor-grade sensors. Single-source vulnerability concentrates in automated gate control systems for vehicle processing centers. Distribution runs through rail ramps at Port of Los Angeles, Port of Long Beach, and Laredo border crossings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of telematics technicians trained on integrated sensor diagnostics and predictive maintenance software constrains carrier fleet modernization timelines. EPA Phase 3 compliance deadlines and EV production ramp-ups intensify competition for qualified maintenance personnel.
For Market Incumbents: Harden dedicated contract carriage density across Michigan and Southeast corridors through exclusive sequencing center partnerships with Bosch, Denso, and Magna operations. Secure captive maintenance technician pipelines via community college apprenticeship programs in Warren and Sterling Heights. Battery supplier procurement consolidation toward platform-based managed transportation services threatens spot-market brokerage margins. For New Entrants and Emerging Players: Ohio aftermarket parts distribution exhibits underpenetration by integrated maintenance-service bundlers, with NAPA and AutoZone networks relying on fragmented regional carriers. Target Columbus and Toledo for cloud-native yard management platform deployment, leveraging Ohio EPA diesel emission reduction grant eligibility to offset alternative-fuel tractor capital requirements. Go-to-market angle emphasizes guaranteed capacity commitments during peak production windows. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery-electric last-mile vehicle and depot charging infrastructure segments. Long-term viability favors carriers with integrated telematics infrastructure and cross-border customs brokerage capabilities. Acquisition target archetype combines Texas-Mexico bonded warehousing operations with cloud-based TMS deployments. Signal to watch: California Advanced Clean Trucks regulation adoption velocity in Oregon, Washington, and New York.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Charging Infrastructure Buildout | Southeast corridor operators prioritize charging networks to maintain density on BMW and Volkswagen Group dedicated lanes. |
| Cloud-Based Yard Management Deployment | Digital coordination platforms replace manual gate control at Dallas-Fort Worth and Ontario vehicle processing centers. |
| Cross-Border Customs Brokerage Integration | Nearshoring from Mexico drives demand for bonded warehousing services across Laredo and El Paso zones. |
| Telematics Technician Apprenticeship Programs | Community college partnerships address acute shortages of sensor diagnostics and predictive maintenance specialists. |
| Battery Supplier Sequencing Center Partnerships | Tennessee and Kentucky greenfields require vibration-monitored cross-dock facilities for hourly takt-time delivery. |
Research Methodology
A standing panel of OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distribution operations managers, and FMCSA compliance officers provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA regulatory filings, NHTSA electronic logging device mandate documentation, vehicle production databases, and IHS Markit registration data. Bottom-up carrier capacity assessments and top-down OEM logistics spend estimates underwent cross-triangulation.
Scenario-bracketing framed low, base, and high cases across the projection horizon. Segmentation dimensions modeled encompass service type, client procurement sophistication, delivery velocity requirements, and technology deployment maturity. CAGRs were derived from regression analysis against vehicle production forecasts and regulatory compliance timelines. Industry-specific inputs included EPA Phase 3 fleet turnover assumptions and EV manufacturing facility announcement pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive electrification moves by early-adopting carriers or accelerated California Advanced Clean Trucks spillover would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
Europe Logistics Automation Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
Air Cargo Market
Logistics and Shipping
Straddle Carrier Market
Logistics and Shipping
Asia Pacific Automotive Logistics Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
Europe Courier Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
Mexico Containerized Shipping Market
Logistics and Shipping
Australia 3PL Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market