
 France Freight and Logistics Market | 2026-2036
France Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
France Freight and Logistics Market Foresight
Buyer concentration among French retail chains is rebalancing toward fragmented e-commerce fulfillment networks. GEODIS leverages its multimodal infrastructure to serve expanding omnichannel distribution needs. CMA CGM Group anchors maritime connectivity through Mediterranean and Atlantic port gateways. DHL Group competes on cross-border express capacity linking France to Benelux and German industrial corridors.
France freight and logistics encompasses the physical movement of goods via road, rail, air, maritime, and pipeline networks, coordinated through warehousing, forwarding, and customs services, typically operating within EU-standardized weight and dimension protocols for cross-border interoperability. Its primary purpose is synchronizing supply chains for manufacturing, retail, and agricultural output across metropolitan and peripheral zones. Road freight dominates tonnage moved domestically, though rail freight captures structural share on bulk and containerized corridors where EU infrastructure subsidies apply. Contract logistics and warehousing concentrate margin pools around temperature-controlled pharmaceutical storage and automated fulfillment centers near Paris and Lyon.
France's logistics sector operates under EU Green Deal emission targets, national implementation of CSRD disclosure rules, and F-Gas Regulation constraints on refrigerated transport fleets. ANSM pharmaceutical transport guidelines and CNIL data governance standards further shape cold-chain and digital tracking compliance requirements. Stakeholders must monitor how EU AI Act provisions on automated warehouse systems will redefine liability and workforce certification frameworks.
Market Dynamics
France's freight and logistics sector is undergoing a fundamental reconfiguration as the EU Green Deal's emission mandates force fleet electrification and multimodal infrastructure investment across the Île-de-France and Auvergne-Rhône-Alpes corridors. The regulatory pressure is compressing diesel asset lifecycles while accelerating warehouse automation deployment near Paris and Lyon.
Growth Catalysts
- E-commerce Fulfillment Networks:Retail chains are fragmenting distribution nodes across metropolitan France to meet same-day delivery expectations. Automated micro-fulfillment centers are proliferating in suburban Paris zones.
- EU Green Deal Implementation:France's national low-emission mobility frameworks are channeling subsidies toward electric truck procurement and rail freight modal shift on subsidized corridors.
- Pharmaceutical Cold-Chain Expansion:ANSM guidelines are mandating temperature-validated storage capacity expansion near Lyon-Saint-Étienne and Paris pharmaceutical clusters.
Market Restraints
- Driver Shortage Concentration:Road freight operators face acute recruitment gaps for certified hazardous materials and refrigerated transport operators across French regions.
- Grid Infrastructure Lag:Heavy-duty electric vehicle charging networks remain underdeveloped on Atlantic and Mediterranean corridor routes, constraining fleet conversion timelines.
- Rail Freight Cost Disadvantage:Last-mile trucking requirements and terminal handling fees erode rail's competitiveness against road on sub-500 kilometer French domestic lanes.
Strategic Opportunities
- Île-de-France Last-Mile Density:Urban consolidation centers and cargo bike networks can capture regulatory exemptions from Paris congestion charging schemes.
- EU AI Act Warehouse Deployment:Automated picking and predictive inventory systems qualify for accelerated permitting under France's digital transformation incentives.
- Cross-Border Benelux Integration:Multimodal platforms linking Lille and Strasbourg to Belgian and Dutch port networks can capture EU TEN-T corridor funding.
Industry Challenges
- CSRD Disclosure Complexity:Logistics operators must implement Scope 3 emissions tracking across subcontractor networks with limited standardized data protocols.
- Workforce Reskilling Urgency:Warehouse automation and electric vehicle maintenance require technician certifications that French vocational training centers are struggling to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Freight and Logistics Market |
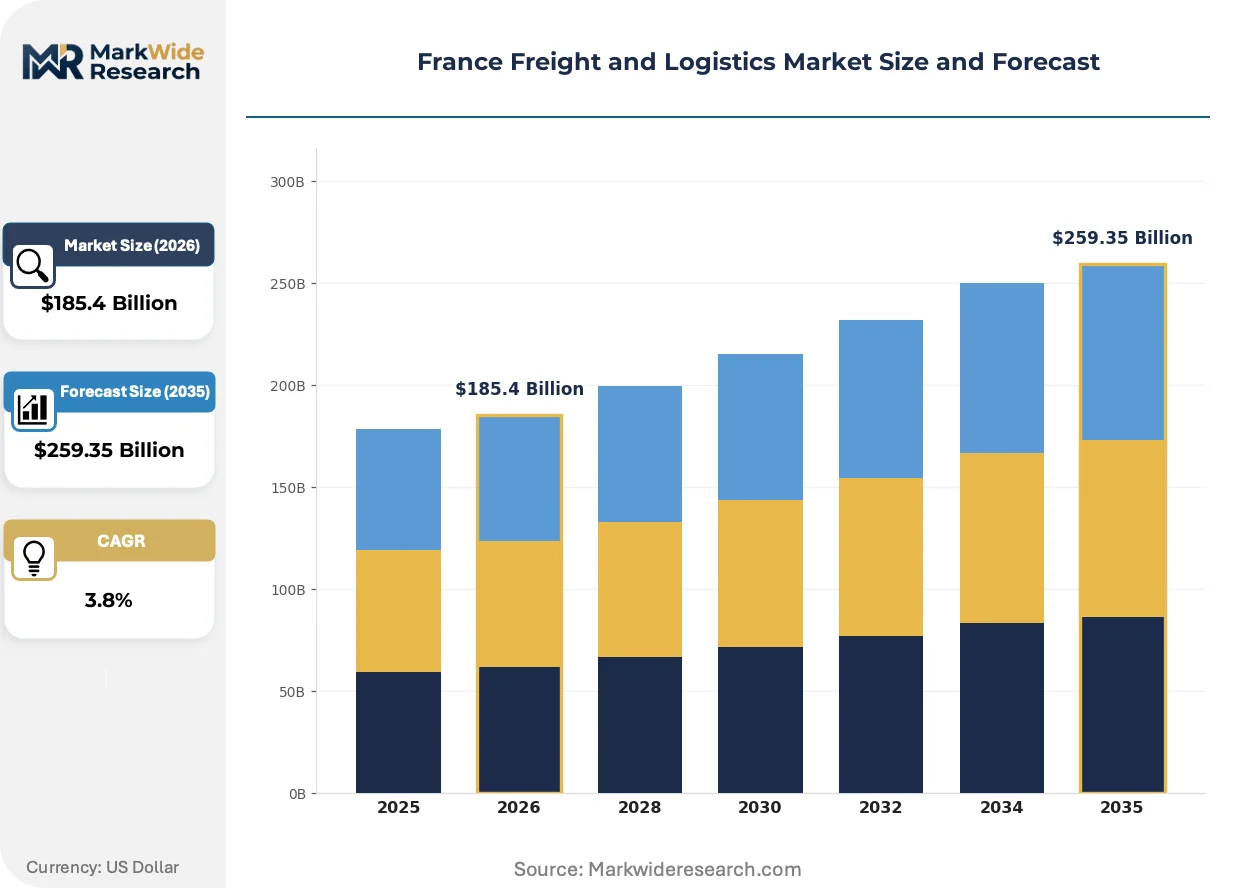
| Market Size in 2026 | $185.4 Billion |
| Market Size in 2035 | $259.35 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Mode: Road Freight, Rail Freight, Air Cargo, Maritime Shipping, Pipeline Transport Service Type: Parcel Delivery, Contract Logistics, Warehousing, Freight Forwarding, Customs Brokerage Customer Type: Manufacturers, Retail Chains, E-commerce Companies, Agricultural Producers, Construction Firms Technology Integration: GPS Tracking, Warehouse Automation, Electronic Data Interchange, Blockchain, Internet of Things |
| Companies Covered | La Poste Group, CEVA Logistics, GEODIS, Alstom, Hapag-Lloyd, CMA CGM Group, Kuehne+Nagel, FM Logistic, DHL Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Freight and Logistics Market Shifts & Advancements
Digital infrastructure and emission compliance are converging to reshape asset deployment patterns across French logistics networks. Technology adoption is accelerating most visibly in warehouse automation and fleet telematics.
Autonomous mobile robots and goods-to-person systems are automating order fulfillment in French distribution centers serving omnichannel retail. Third-party logistics providers in the Paris basin are deploying these systems to compress labor dependency and increase throughput density per square meter. The technology is automating inventory handling tasks previously requiring manual picker movement across warehouse zones.
France's transposition of the EU AI Act is imposing conformity assessment requirements on automated warehouse management systems. Logistics operators must document algorithmic decision transparency and human oversight protocols for AI-driven inventory allocation. Cold-chain pharmaceutical storage facilities in Lyon face the steepest compliance timelines given ANSM's overlapping quality system mandates.
Retail procurement patterns are fragmenting toward micro-fulfillment networks with shorter contract durations and performance-based service level agreements. Traditional long-term dedicated warehouse contracts are giving way to flexible capacity arrangements indexed to seasonal e-commerce volatility. This shift concentrates margin pressure on 3PL operators in the Île-de-France corridor where land scarcity elevates facility costs.
France Freight and Logistics Market Segmentation
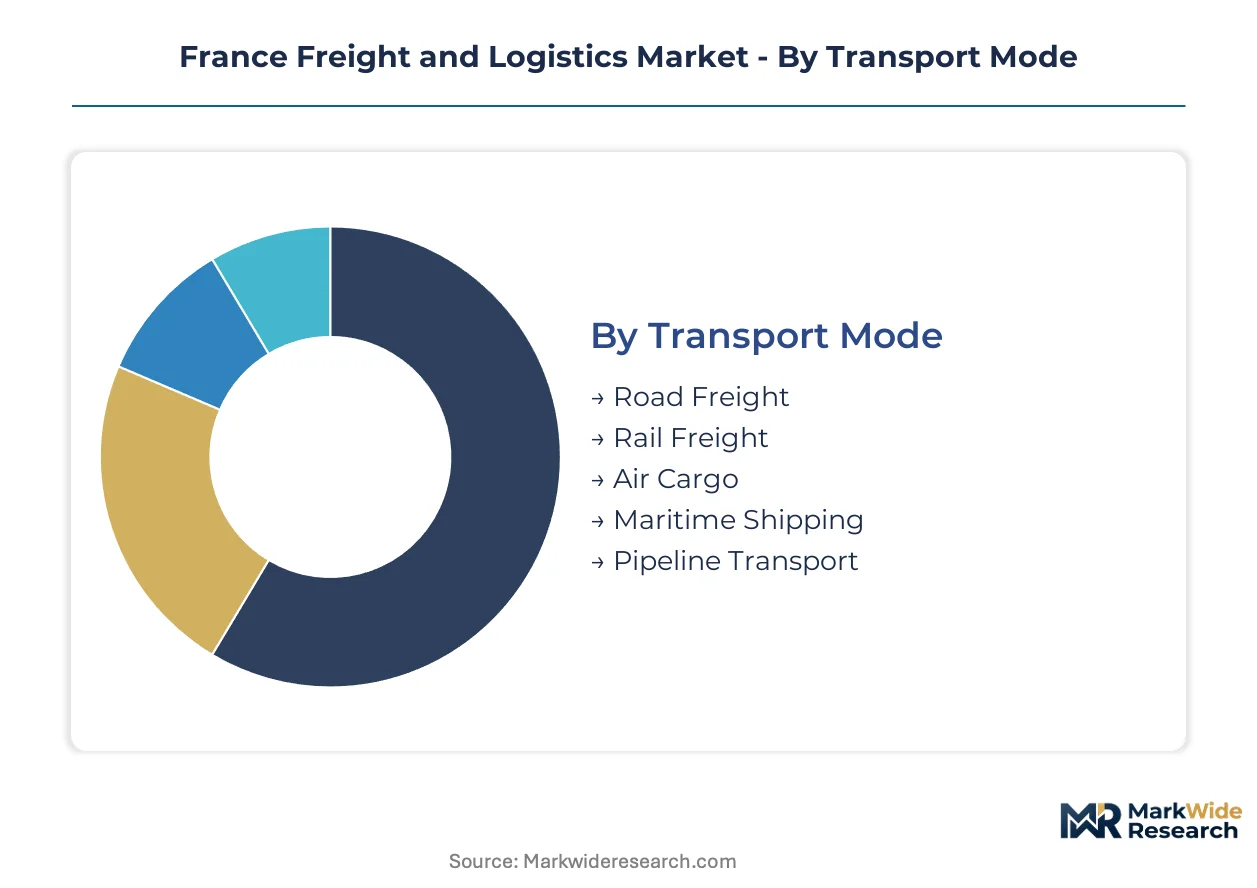
Segmentation in the France freight and logistics market reveals how regulatory burdens and infrastructure requirements concentrate margin pools across distinct operational profiles. Understanding these divisions exposes where EU Green Deal compliance costs and ANSM certification requirements reshape competitive positioning.
Transport Mode:
Road freight and rail freight carry the heaviest EU Green Deal certification obligations, while air cargo and maritime shipping face distinct ETS emission trading compliance tiers.
- Road Freight:Diesel and electric heavy-duty vehicles moving palletized and containerized cargo across French national routes. Demand concentrates around the Île-de-France corridor where e-commerce fulfillment networks require flexible last-mile capacity, though driver shortages constrain fleet expansion.
- Rail Freight:Bulk commodities and intermodal containers on electrified corridors linking Lyon-Saint-Étienne to Atlantic and Mediterranean ports. The Auvergne-Rhône-Alpes cluster drives volume as pharmaceutical and chemical shippers seek lower-carbon alternatives to road transport.
- Air Cargo:Time-critical shipments through Paris-Charles de Gaulle and Lyon-Saint-Exupéry hubs serving aerospace and pharmaceutical exporters.
- Maritime Shipping:Container and bulk vessel operations through Marseille-Fos, Le Havre, and Dunkirk port gateways connecting to EU TEN-T corridors.
- Pipeline Transport:Refined petroleum products and natural gas through the Trapil and other operator networks serving French industrial zones.
Road freight sits at the top of the volume ranking, with rail freight climbing the fastest on subsidized modal shift corridors.
Service Type:
Margin structures diverge sharply between asset-heavy warehousing operations and asset-light forwarding services, with contract logistics capturing the steepest automation investment cycles.
- Contract Logistics:Dedicated warehousing, inventory management, and value-added services under multi-year agreements with manufacturers and retailers. Pharmaceutical cold-chain facilities near Lyon command premium pricing due to ANSM validation requirements and land scarcity constraints.
- Parcel Delivery:B2C and B2B small-package networks with dense last-mile coverage in metropolitan France. Suburban Paris zones see the most intense competition as e-commerce volumes fragment distribution node requirements.
- Warehousing:Public and shared storage facilities with temperature-controlled and ambient capacity serving seasonal demand fluctuations.
- Freight Forwarding:Intermediary coordination of multimodal international shipments, customs documentation, and carrier selection.
- Customs Brokerage:Post-Brexit customs clearance and EU import-export compliance services at Channel and Atlantic port entry points.
Contract logistics commands the highest margin per square meter, while parcel delivery is gaining share fastest on e-commerce penetration.
Customer Type:
Procurement sophistication varies dramatically across customer segments, with e-commerce companies driving the most demanding service-level specifications and shortest contract durations.
- E-commerce Companies:Omnichannel retailers and pure-play digital merchants requiring same-day and next-day fulfillment across metropolitan France. These buyers impose automated inventory visibility and returns processing capabilities that reshape 3PL technology requirements.
- Manufacturers:Automotive, aerospace, and industrial goods producers with just-in-sequence supply chain synchronization needs concentrated around Toulouse, Nantes, and Saint-Étienne production clusters.
- Retail Chains:Hypermarket and specialty store networks with regional distribution center replenishment schedules.
- Agricultural Producers:Grain, wine, and fresh produce shippers dependent on seasonal harvest timing and temperature-controlled export logistics.
- Construction Firms:Heavy building materials and equipment logistics with project-based scheduling and site delivery coordination.
Manufacturers represent the largest contract value concentration, with e-commerce companies expanding their logistics spend most aggressively.
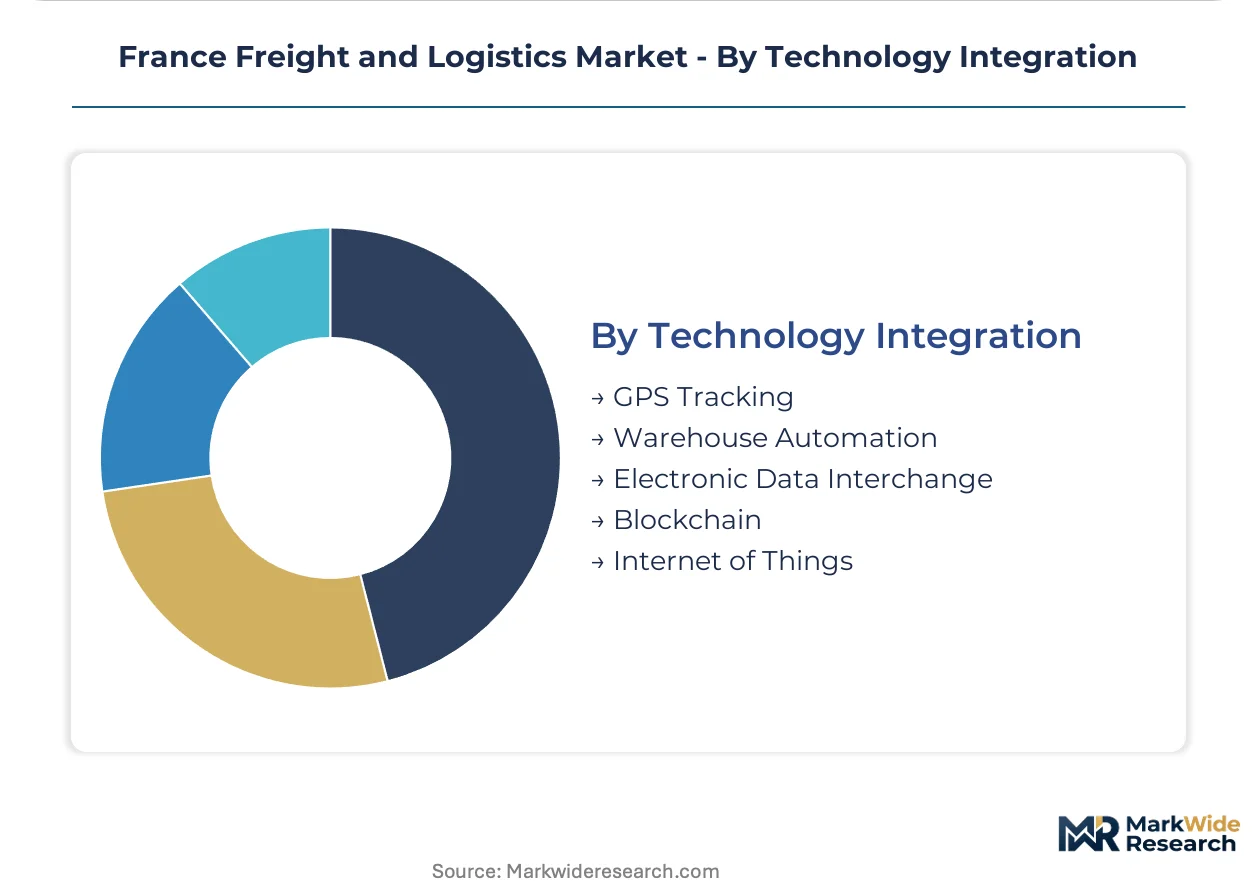
Technology Integration:
EU AI Act conformity assessment requirements are segmenting technology adoption between established systems with clear compliance pathways and emerging platforms facing regulatory uncertainty.
- Warehouse Automation:Autonomous mobile robots, goods-to-person systems, and automated storage and retrieval equipment in French distribution centers. The Île-de-France corridor leads deployment as labor costs and land scarcity compress fulfillment economics.
- GPS Tracking:Real-time fleet telematics and route optimization platforms mandated by CSRD emissions disclosure requirements across road transport fleets.
- Electronic Data Interchange:Standardized customs and shipping documentation protocols linking French operators to EU Single Window systems.
- Internet of Things:Sensor networks for cold-chain monitoring and predictive maintenance on refrigerated transport assets.
- Blockchain:Pilot implementations for pharmaceutical provenance tracking and cross-border trade finance documentation.
GPS tracking holds the widest installed base, with warehouse automation posting the steepest investment growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's rail freight modal share exceeds France's, yet French logistics operators face steeper EU Green Deal compliance timelines due to earlier national implementation deadlines. Both markets concentrate contract logistics margin pools around automotive and pharmaceutical clusters, though regulatory fragmentation creates divergent investment patterns.
Germany
Automotive just-in-sequence supply chains and chemical bulk distribution drive logistics demand across Baden-Württemberg and Bavaria. KBA vehicle certification requirements and national low-emission zone frameworks accelerate electric truck procurement timelines. The Rhine-Ruhr corridor anchors intermodal container flows, with Duisburg inland port handling sustained volume growth on subsidized rail corridors.
Netherlands
Rotterdam port throughput and Schiphol air cargo volumes sustain freight forwarding density unmatched in continental Europe. National implementation of EU ETS maritime provisions and CSRD disclosure mandates reshape carrier procurement specifications. The Randstad logistics ring concentrates automated warehousing investment as e-commerce fulfillment networks fragment distribution nodes.
Spain
Perishable agricultural exports from Andalusia and automotive component flows from Catalonia generate temperature-controlled and just-in-time logistics demand. National transposition of EU F-Gas Regulation constrains refrigerated transport fleet renewal economics. The Madrid-Barcelona-Valencia triangle anchors contract logistics capacity expansion as retailers build omnichannel distribution redundancy.
Italy
Luxury fashion exports from Milan-Turin corridors and pharmaceutical production around Bologna sustain high-value air freight and specialized warehousing demand. ANVISA-equivalent pharmaceutical transport guidelines and national sustainability reporting frameworks elevate cold-chain compliance costs. Lombardy's logistics real estate scarcity compresses fulfillment economics faster than national averages.
Belgium
Antwerp port connectivity and Brussels air cargo handling sustain multimodal forwarding density serving French and German hinterlands. National implementation of EU customs union protocols and CSRD supply chain disclosure requirements reshape 3PL contractual frameworks. The Flanders logistics corridor captures EU TEN-T corridor funding for rail electrification and terminal automation.
France Freight and Logistics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across French freight and logistics, creating a tiered market structure where scale advantages clash with niche regulatory expertise. Asset-heavy operators control warehousing and fleet capacity while asset-light forwarders capture margin on customs complexity and multimodal coordination. Three archetypes dominate: integrated postal-courier networks with last-mile density, maritime carriers with inland logistics extensions, and third-party logistics operators with sector-specific certification depth. Competitive moves concentrate on warehouse automation deployment and electric fleet conversion timelines.
Among France-based operators, La Poste Group and GEODIS occupy positions spanning postal, parcel, and contract logistics archetypes, with La Poste representing the integrated postal-courier model and GEODIS exemplifying multimodal forwarding scale. CMA CGM Group anchors the maritime carrier archetype with inland logistics extensions. These three entities represent distinct strategic postures within a market where EU Green Deal compliance and ANSM pharmaceutical certification requirements increasingly segment competitive positioning.
| Leading Market Players |
|---|
| La Poste Group |
| CEVA Logistics |
| GEODIS |
| Alstom |
| Hapag-Lloyd |
| CMA CGM Group |
| Kuehne+Nagel |
| FM Logistic |
| DHL Group |
| Others |
Supply & Pricing Matrix
Certified hazardous materials drivers concentrated in the Île-de-France corridor command wage premiums that compress pricing-tier spreads between standard and premium logistics services. Labor-cost differentials between Paris basin operators and peripheral regional carriers translate directly into three-tier pricing stratification across contract logistics, parcel delivery, and freight forwarding segments.
Pricing Analysis
Capacity additions in the Auvergne-Rhône-Alpes logistics cluster are reshaping price floors for pharmaceutical cold-chain services as ANSM-certified warehousing expands near Lyon-Saint-Étienne. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and geographic delivery cost differentials. Cost compression in economy-tier road freight is intensifying because electric fleet conversion subsidies favor large-scale operators over regional carriers. E-commerce companies exhibit the highest price sensitivity, while pharmaceutical manufacturers accept premium pricing for validated temperature control.
Supply Chain Analysis
Returns processing flows from omnichannel retail networks are creating reverse-logistics infrastructure demands that reshape warehouse layout economics in suburban Paris zones. German, Belgian, and Dutch port gateways anchor inbound container flows, while French domestic production draws from Spanish automotive components and Italian pharmaceutical inputs. Single-source vulnerability concentrates in electric truck battery supply tethered to Asian manufacturing. Distribution runs through multimodal platforms linking Atlantic and Mediterranean corridors to inland rail terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
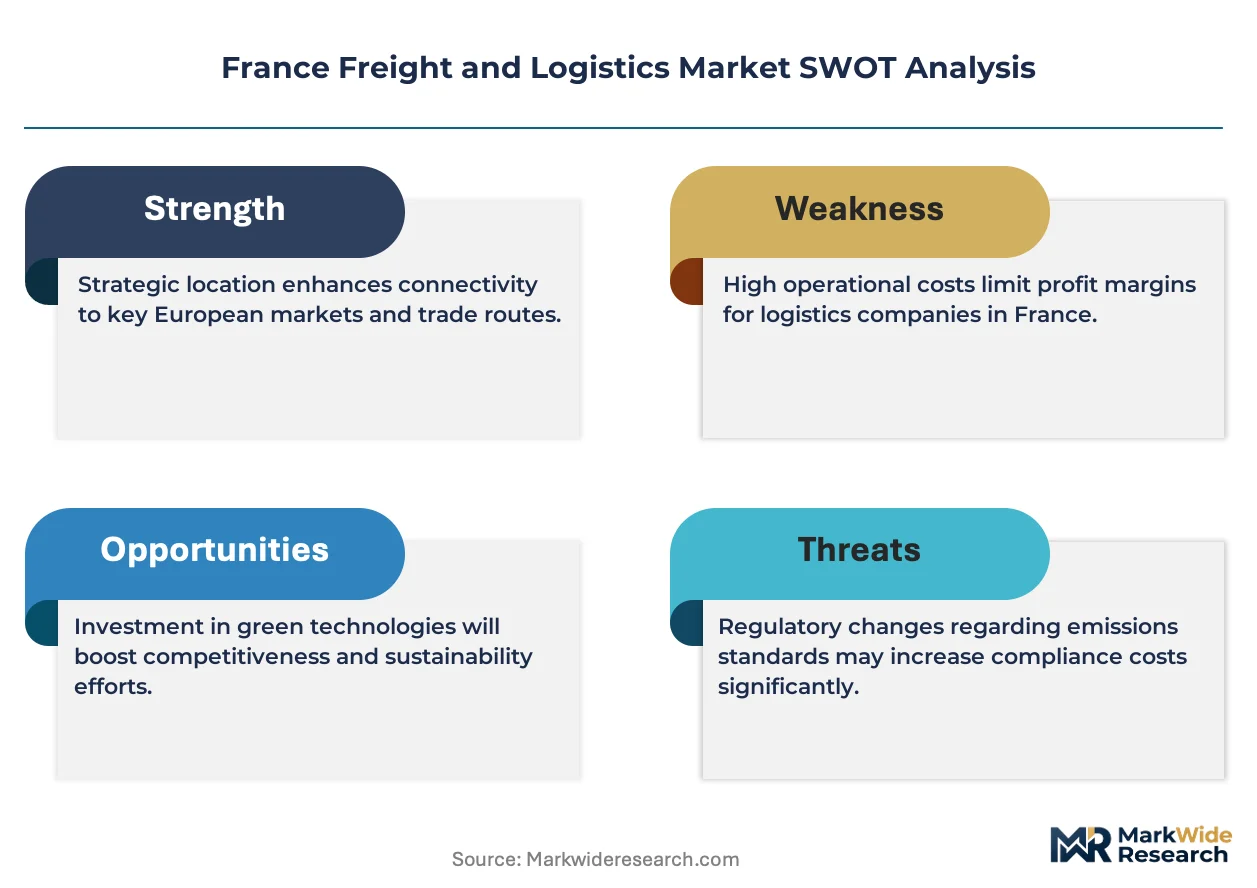
France freight and logistics functions as a stable compounder anchored by EU Green Deal infrastructure spending that guarantees sustained capital deployment across electrification and automation. E-commerce fulfillment density and pharmaceutical cold-chain certification create defensible margin pools for positioned operators.
For Market Incumbents: Anticipate workforce reskilling bottlenecks by partnering with French vocational training centers to secure electric vehicle technician certifications ahead of competitor recruitment. Consolidate ANSM-validated cold-chain capacity around Lyon-Saint-Étienne before land scarcity elevates facility costs further. Defensive positioning against maritime carrier inland extensions requires deepening multimodal forwarding expertise on Benelux corridors.
For New Entrants and Emerging Players: Autonomous mobile robot deployment for micro-fulfillment centers offers the most penetrable wedge into suburban Paris logistics real estate where incumbents face labor cost compression. Target cargo bike last-mile networks in Île-de-France urban consolidation zones that qualify for congestion charge exemptions. Go-to-market positioning should emphasize EU AI Act compliance documentation as a differentiated service layer for automated warehouse implementations.
For Investors and Strategic Acquirers: Maritime carriers with inland logistics extensions represent the most active acquirer category in this space, seeking forwarding networks to capture hinterland container flows. Long-term viability over the coming decade hinges on electric fleet conversion timelines and warehouse automation deployment rates. Acquisition targets should display ANSM pharmaceutical certification depth or established Île-de-France last-mile density. The signal to monitor is EU TEN-T corridor funding allocation shifts that reconfigure intermodal competitive economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | EU Green Deal subsidies favor early movers on Atlantic and Mediterranean corridor routes. |
| ANSM Certification Investment | Validated cold-chain capacity near Lyon commands premium pricing from pharmaceutical clusters. |
| Warehouse Automation Deployment | Goods-to-person systems in Paris basin compress labor dependency and CSRD disclosure burdens. |
| Cross-Border Benelux Integration | Multimodal platforms linking Lille to Rotterdam capture EU TEN-T corridor development funding. |
| Micro-Fulfillment Network Expansion | Suburban Paris automated centers serve fragmented e-commerce same-day delivery requirements. |
Research Methodology
Direct dialogue with fleet operations directors, pharmaceutical logistics managers, 3PL contract executives, and EU regulatory compliance officers grounded qualitative assessments of electrification timelines and automation deployment patterns. Secondary validation drew from EU transport statistics, ANSM pharmaceutical transport guidelines, CSRD disclosure frameworks, and French customs trade flow data. Bottom-up capacity modeling across transport modes and service types was triangulated against top-down macroeconomic indicators.
Bottom-up segment analysis tracked vehicle fleet composition, warehouse square footage, and employment levels across French regions, while top-down approaches calibrated aggregate market sizing against EU logistics sector benchmarks. Segmentation dimensions modeled included transport mode, service type, customer archetype, and technology integration intensity. CAGRs were derived from trend extrapolation of e-commerce penetration rates, EU Green Deal implementation schedules, and pharmaceutical cold-chain capacity expansion plans.
The model holds under sustained EU infrastructure subsidy commitments and stable e-commerce growth trajectories; deviation in battery supply chain disruptions or driver shortage acceleration would shift fleet conversion timelines and pricing dynamics. Forecasts reflect assumptions regarding regulatory compliance cost pass-through and automation technology adoption curves. Periodic stress-testing of base assumptions against EU AI Act implementation progress and TEN-T funding allocation decisions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Latin America Contract Logistics Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
Asia-Pacific less-Than Container Load (LCL) Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
GCC Dangerous Goods Logistics Market
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Saudi Arabia Integrated Cold Chain Logistics Market
Logistics and Shipping
Germany Same Day Delivery Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
ASEAN Chemical Logistics Market